
 Automotive Door Latch Market | 2026-2036
Automotive Door Latch Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Door Latch Market Intelligence
Profitability from standalone mechanical latch hardware is narrowing as value shifts toward integrated electronic and software-defined access systems. Kiekert AG specializes in advanced side-door latch technologies and power closing mechanisms. Magna International leverages its extensive portfolio in mechatronics and body systems to offer complete solutions. AISIN CORPORATION sustains its strong position through established supply chains with major global automakers.
An automotive door latch is a device that secures a vehicle door to the body, preventing unintended opening. These components must meet stringent performance specifications for load resistance and durability, often defined by safety standards. While mechanical latches remain prevalent in economy models, electromechanical latches now dominate new passenger car applications. The adoption of smart access technology represents the fastest-growing segment, commanding higher margins for suppliers.
Federal Motor Vehicle Safety Standards from the US NHTSA set critical performance benchmarks for latch integrity. Similarly, UN Regulation No. 11 and China's GB 15086 dictate anti-burst strength and retention requirements globally. These mandates directly influence material choices and testing protocols for all market participants. Component suppliers must now balance mechanical reliability with the increasing cybersecurity demands of connected vehicle architectures.
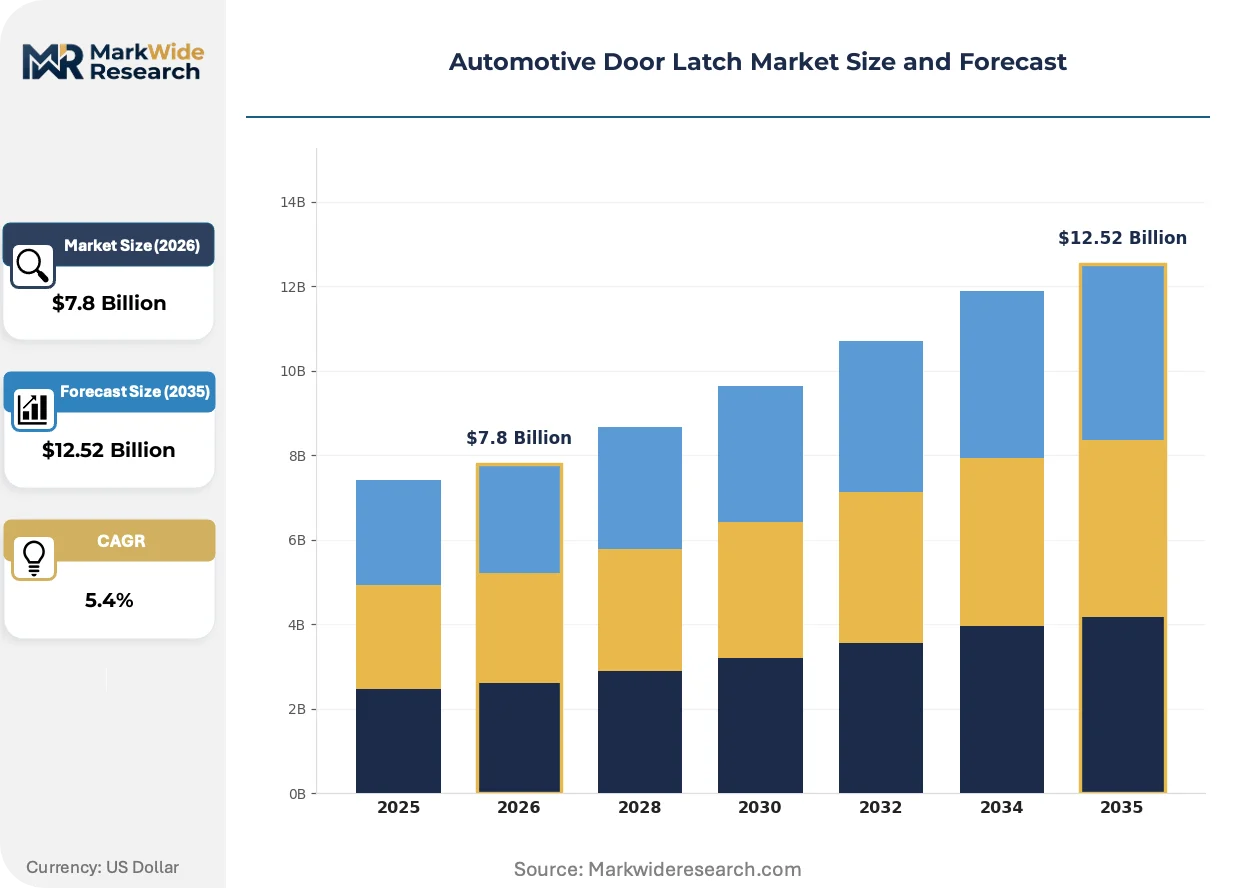
Market Dynamics
The market's central dynamic is the tension between maintaining mechanical anti-burst strength, mandated by safety standards, and integrating complex electronics for smart access features. This convergence forces a re-evaluation of component design, material science, and testing protocols.
Growth Catalysts
- Electrification and SUV Demand:The rapid expansion of the electric vehicle and SUV segments, which prioritize advanced features, accelerates adoption of electromechanical latches.
- Stringent Safety Mandates:Regulations like China's GB 15086 and UN Regulation No. 11 set high anti-burst strength requirements, sustaining demand for high-performance latch systems.
- Consumer Preference for Convenience:Demand for smart access, keyless entry, and remote functionalities pushes automakers to specify more sophisticated latch modules in mass-market vehicles.
Market Restraints
- Mechanical Latch Commoditization:Profitability on traditional, purely mechanical latches is declining due to intense price competition, particularly in the economy vehicle and aftermarket segments.
- Integration Complexity:Integrating advanced electromechanical latches with diverse vehicle electrical architectures and body control modules can cause development delays and compatibility issues.
- Electronic Component Dependency:Production of smart latches depends on a stable supply of microcontrollers and sensors, creating vulnerability to semiconductor shortages and price volatility.
Strategic Opportunities
- Software-Defined Access Systems:Developing integrated software and hardware for features like digital keys and over-the-air updates creates new, recurring revenue streams for suppliers.
- Power Closing Mechanisms:Expanding into adjacent, high-margin products like power cinching or fully automated door closing systems offers a path for value-added differentiation.
- Aftermarket Upgrades:A significant opportunity exists in developing upgrade kits that allow owners of older or lower-trim vehicles to add modern convenience access features.
Industry Challenges
- Cybersecurity Vulnerabilities:Connected latches present a new attack surface for vehicle theft, requiring suppliers to invest heavily in cybersecurity expertise and threat-mitigation technologies.
- Balancing Conflicting Standards:Suppliers must simultaneously meet legacy mechanical safety standards for durability while also complying with emerging electronic and cybersecurity regulations.
- High Capital Expenditure:The transition from manufacturing traditional mechanical latches to complex electromechanical systems requires substantial investment in new tooling, testing equipment, and cleanroom facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Door Latch Market |
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $12.52 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mechanical Latch, Electromechanical Latch, Electronic Latch, Pneumatic Latch Technology: Locking Mechanism, Sensor Integration, Remote Control, Smart Access Application: Passenger Cars, Commercial Vehicles, Specialty Vehicles, Recreational Vehicles End User: OEMs, Tier-1 Suppliers, Vehicle Assemblers, Aftermarket Providers |
| Companies Covered | AISIN CORPORATION, Mitsui Kinzoku ACT Corporation, Kiekert AG, Strattec Security Corporation, Huf Hülsbeck & Fürst GmbH & Co. KG, Magna International, Inteva Products LLC, WITTE Automotive GmbH, Brose Fahrzeugteile GmbH & Co. KG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Door Latch Market Strategic Shifts & Innovations
Component evolution is defined by the integration of latches into the vehicle's broader digital ecosystem. This transition transforms a standalone mechanical part into a connected electronic node, fundamentally altering its function and value proposition within the vehicle architecture.
Digital key technology utilizes Bluetooth Low Energy or NFC protocols to grant vehicle access via a smartphone. Premium and electric vehicle segments are the primary adopters, with rapid integration into new model platforms. This development is virtualizing the access credential itself, shifting value from physical hardware to cloud-based authentication and software management.
UN Regulation No. 155 mandates a certified Cyber Security Management System for new vehicle types. This forces automakers to secure all electronic control units, including those managing smart door latches, against potential cyber threats. Suppliers of connected components are most affected, now bearing the responsibility for demonstrating end-to-end cybersecurity compliance.
Automakers are beginning to unbundle advanced access features from hardware trim levels, offering them as post-sale software upgrades. This model disrupts the traditional one-time component sale, requiring suppliers to design hardware capable of supporting future over-the-air activations. This shift is most visible in the European and North American EV markets.
Automotive Door Latch Market Segmentation
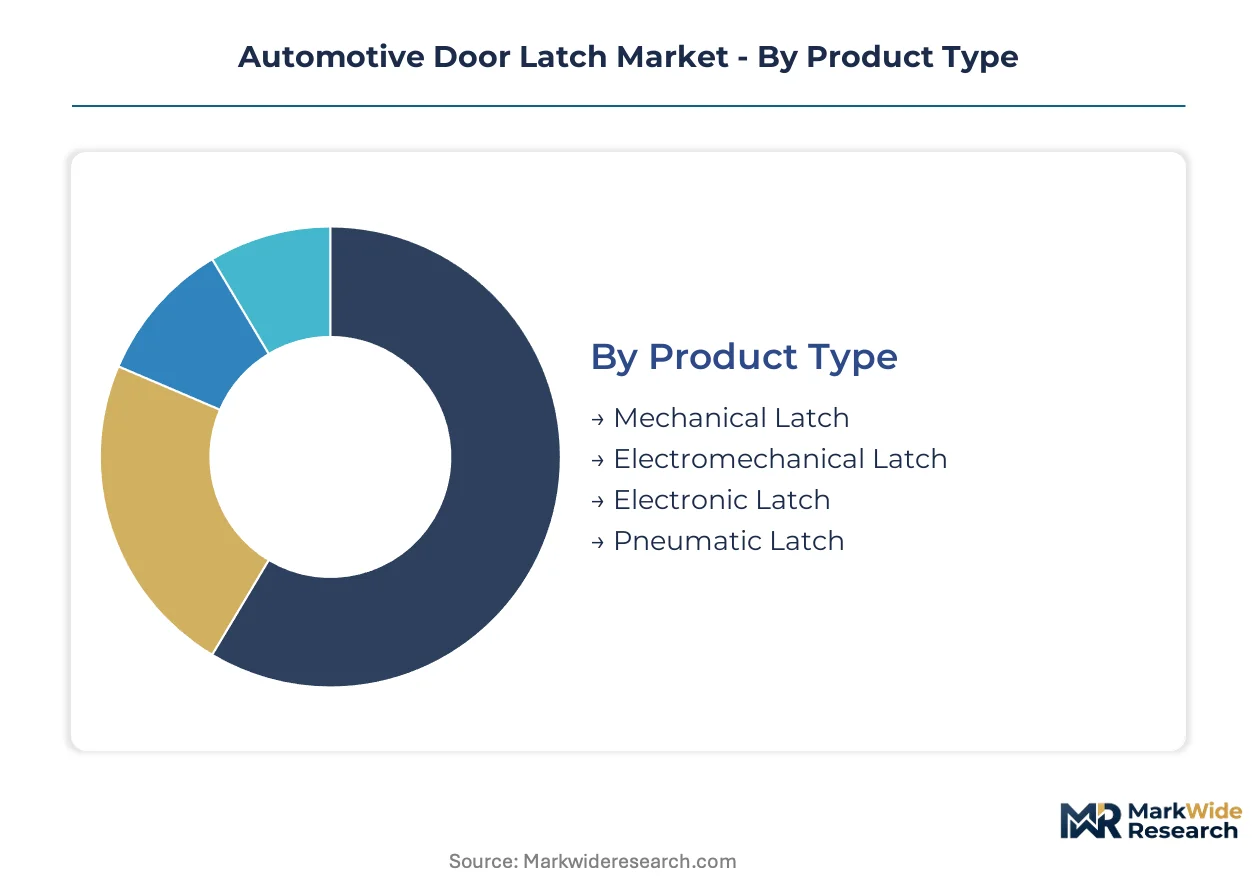
Segmentation of the automotive door latch market reveals distinct value pools and technological trajectories across various product types, technologies, applications, and end users. Understanding these segments is critical for suppliers to tailor product development, investment, and market entry strategies effectively. The market's evolution from mechanical to electromechanical systems drives differentiation across these categories.
Product Type:
Product types for automotive door latches exhibit varying development and replacement cycles, influencing supplier investment strategies.
- Electromechanical Latch:These latches integrate mechanical components with electric motors and sensors, enabling advanced functions like soft-close, anti-theft, and remote operation. Demand concentrates in premium passenger cars and electric vehicles due to their emphasis on advanced convenience and safety features.
- Mechanical Latch:Comprising purely mechanical components, these latches secure the door using springs, levers, and pawls, offering robust and cost-effective solutions. They remain prevalent in economy vehicle segments and commercial vehicles, where simplicity and durability are prioritized over electronic features.
- Electronic Latch:Electronic latches utilize actuators and electronic controls for locking and unlocking, often found in conjunction with keyless entry systems.
- Pneumatic Latch:These systems use air pressure to operate the latching mechanism, typically found in heavy-duty commercial vehicles or specialized applications requiring powerful actuation.
Mechanical latches anchor the volume base while electromechanical latches gain share at the steepest rate.
Technology:
Technologies integrated into automotive door latches directly enhance vehicle functionality and user experience across diverse applications.
- Smart Access:This technology leverages digital keys, Bluetooth Low Energy, or NFC for vehicle access via smartphones, eliminating physical keys. Premium and electric vehicle segments primarily adopt Smart Access, virtualizing access credentials and shifting value to cloud-based authentication.
- Sensor Integration:Incorporating various sensors, such as Hall-effect or micro-switches, enables real-time monitoring of latch status, anti-pinch functionality, and integration with vehicle safety systems. This integration is crucial for meeting stringent safety mandates like UN Regulation No. 11.
- Locking Mechanism:This fundamental technology ensures the door remains securely closed and locked, encompassing various designs from simple pawl-and-ratchet to more complex multi-stage systems.
- Remote Control:Remote control technology allows users to lock and unlock doors from a distance using a key fob or a smartphone application.
Smart Access technology leads innovation, driving premium segment differentiation.
Application:
Automotive door latch applications vary significantly in production volumes and feature requirements.
- Passenger Cars:This segment represents the largest volume market, demanding a wide range of latch types from basic mechanical to sophisticated electromechanical systems with smart access features. Growth is particularly strong in SUV and electric vehicle sub-segments.
- Commercial Vehicles:Latches for commercial vehicles prioritize durability, anti-burst strength, and reliability under heavy usage conditions, often complying with specific load resistance standards. Fleet operators focus on longevity and minimal maintenance requirements.
- Specialty Vehicles:This category includes emergency vehicles, armored vehicles, and custom-built platforms, requiring highly customized and robust latch solutions tailored to unique security or operational demands.
- Recreational Vehicles:Latches for RVs balance security with ease of use, often incorporating lighter materials and sometimes specialized mechanisms for multiple entry points.
Passenger Cars represent the largest application segment, while Specialty Vehicles show specialized feature expansion.
End User:
End users in the automotive door latch market reflect distinct roles within the vehicle manufacturing and maintenance supply chain.
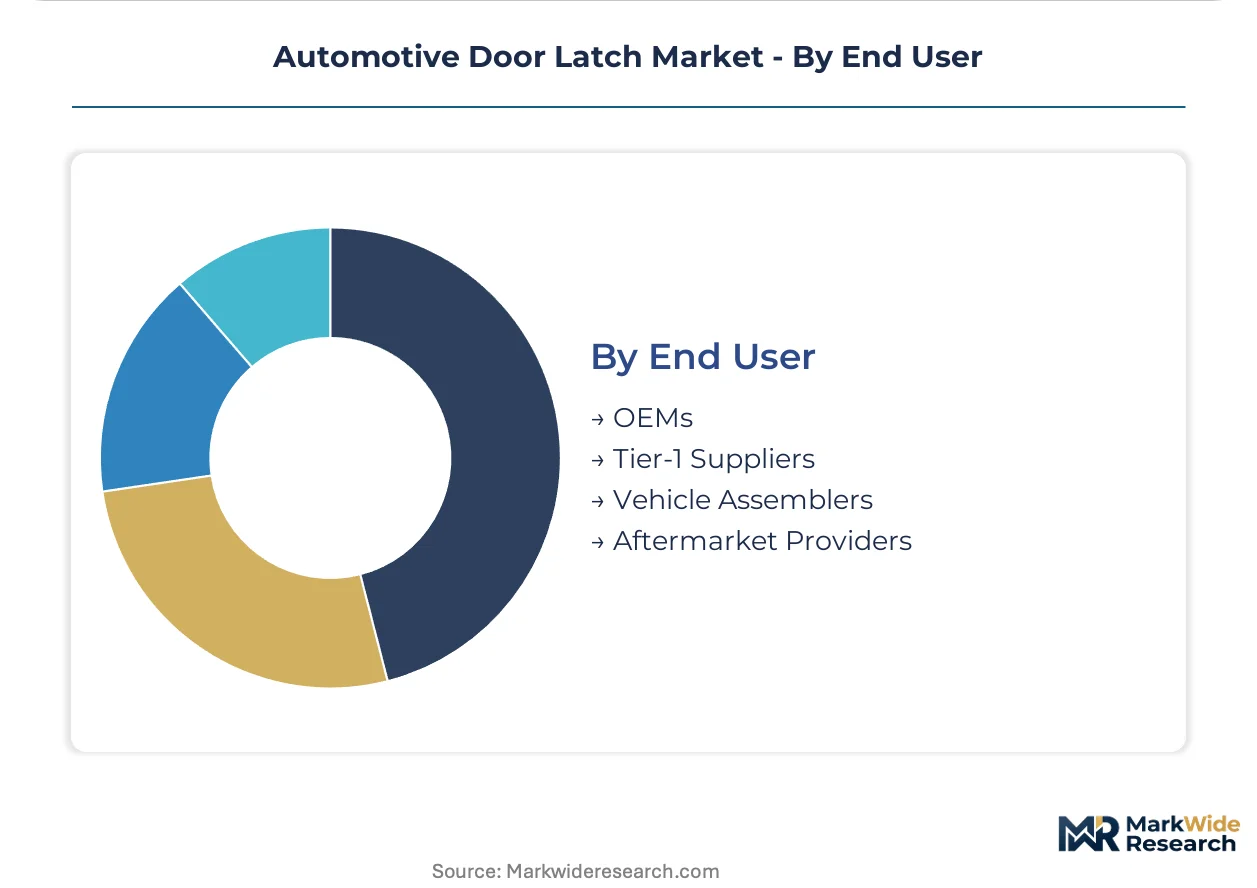
- OEMs:Original Equipment Manufacturers integrate door latches directly into new vehicle production, dictating specifications, performance standards, and supply chain requirements for their platforms. They prioritize seamless integration with vehicle architecture.
- Tier-1 Suppliers:These companies design, manufacture, and supply complete latch modules or systems directly to OEMs, often undertaking significant R&D for advanced technologies like electromechanical and smart access solutions. Kiekert AG and Magna International are prominent Tier-1 players.
- Vehicle Assemblers:These entities are responsible for the final assembly of vehicles, installing latches and ensuring their proper function within the overall vehicle system. Their focus is on efficient installation and quality control.
- Aftermarket Providers:Aftermarket providers supply replacement latches and upgrade kits for vehicles already in operation, catering to repair needs or consumer desires for enhanced features. This segment offers opportunities for modernizing older vehicles.
OEMs dictate primary specifications, with Aftermarket Providers addressing replacement and upgrade demands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's automotive manufacturing clusters drive significant demand for door latches. This concentration influences global supply chain dynamics and technological adoption. Suppliers strategically position production capabilities to serve these high-volume regions.
China
Demand for advanced electromechanical latches is high due to the rapid growth of electric vehicle and SUV segments. GB 15086 standards mandate stringent anti-burst strength, influencing local component design. Shanghai and Guangzhou automotive manufacturing hubs lead innovation in smart access systems.
Germany
Premium passenger car production and strong research and development drive demand for sophisticated latch technologies. KBA regulations and UN Regulation No. 11 shape product development for safety and performance. Stuttgart and Munich host major automotive original equipment manufacturers and Tier-1 suppliers focusing on mechatronic solutions.
Japan
Established automakers prioritize high-quality and durable mechanical and electromechanical latches for global markets. METI initiatives support advanced manufacturing processes and material science research. Nagoya's automotive cluster remains a center for latch system development and supply chain integration.
United States
Consumer preference for convenience features and large SUV sales boost the adoption of smart access systems. NHTSA Federal Motor Vehicle Safety Standards set critical benchmarks for latch integrity. Detroit, Michigan, continues as a key automotive engineering and production hub for new vehicle platforms.
South Korea
Rapid electric vehicle adoption and a focus on integrated digital experiences drive demand for connected latch systems. The country's national automotive safety standards influence design and testing protocols for local manufacturers. Ulsan and Gyeonggi Province are significant automotive production centers integrating advanced latch technologies.
Automotive Door Latch Market Key Industry Players
Integrated systems specialists and traditional mechanical component manufacturers split the market for automotive door latches. The competitive landscape is evolving from fragmented mechanical suppliers to consolidated providers of complex electromechanical modules. Archetypes include advanced technology innovators, full-system integrators, and established volume producers. Key competitive moves involve technology licensing and strategic partnerships to meet complex original equipment manufacturer demands.
Within the advanced technology innovator tier, German-based Kiekert AG exemplifies specialization in sophisticated side-door latch technologies. Canadian-based Magna International, a full-system integrator, occupies a position leveraging its mechatronics and body systems portfolio. AISIN CORPORATION, a Japanese company, anchors the market through its established supply chains with major global automakers. These companies represent different strategic approaches to serving the evolving automotive access systems market. Their presence highlights the industry's shift towards more integrated and electronically controlled solutions.
| Leading Market Players |
|---|
| AISIN CORPORATION |
| Mitsui Kinzoku ACT Corporation |
| Kiekert AG |
| Strattec Security Corporation |
| Huf Hülsbeck & Fürst GmbH & Co. KG |
| Magna International |
| Inteva Products LLC |
| WITTE Automotive GmbH |
| Brose Fahrzeugteile GmbH & Co. KG |
| Others |
Cost & Logistics Intelligence
China's automotive manufacturing clusters and Tier-1 suppliers like Kiekert AG concentrate upstream production, directly influencing where profit margins accumulate downstream within advanced access systems. This concentration shapes component availability and pricing power for sophisticated latch solutions.
Pricing Analysis
NHTSA Federal Motor Vehicle Safety Standards dictate the pricing tier structure for automotive latches, ensuring compliance drives cost. The market primarily operates on a per-unit transactional model, with significant price differentiation based on technology integration and safety certification level. Pricing pressure stems from intense competition in the mechanical latch segment, leading to margin compression. The economy vehicle segment exhibits the highest price sensitivity, while premium and electric vehicle manufacturers are less sensitive to costs for advanced electromechanical solutions.
Supply Chain Analysis
Major Tier-1 suppliers like Magna International and AISIN CORPORATION hold significant manufacturing capacity for automotive latches. Geographic supply concentration includes China, Germany, and Japan, which are key production hubs. The supply chain draws from critical raw materials such as microcontrollers and sensors for electromechanical latches. A structural supply chain risk is vulnerability to semiconductor shortages, which can disrupt smart latch production. Distribution runs through direct channels to Original Equipment Manufacturers for new vehicle assembly.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
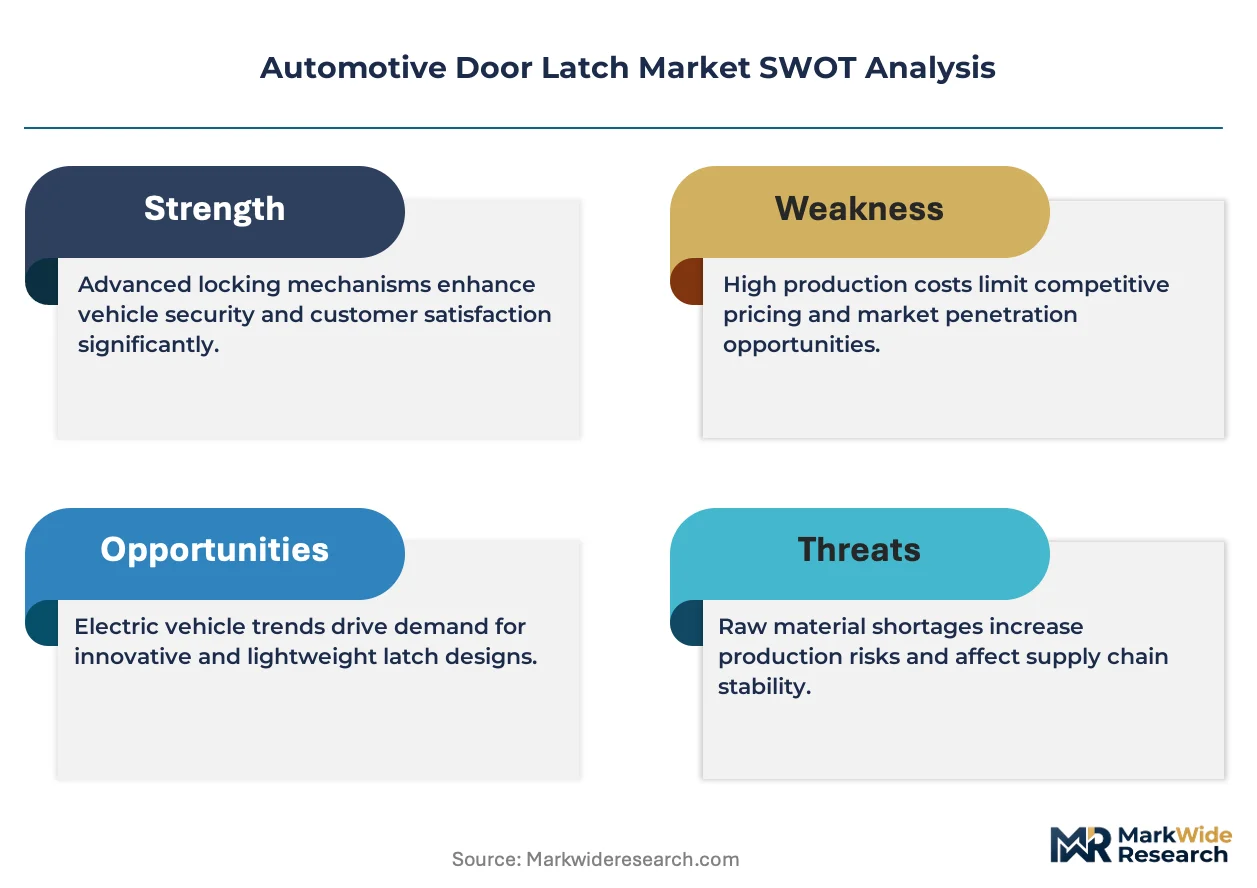
This market presents an early-cycle expansion story, driven by the rapid adoption of electric vehicles that prioritize advanced access features.
For Market Incumbents: Harden core competencies in electromechanical and software integration against the commoditization of basic mechanical latches. Invest heavily in cybersecurity expertise to mitigate emerging vulnerabilities in connected systems. The threat of integration complexity and electronic component dependency demands strategic partnerships. Leverage R&D for next-generation software-defined access platforms.
For New Entrants and Emerging Players: Build out specialized software integration capabilities for digital key solutions. Develop innovative aftermarket upgrade kits that allow older or lower-trim vehicles to add modern convenience features. The aftermarket segment for feature upgrades represents a penetrable white space. A viable go-to-market angle involves offering modular, interoperable solutions for diverse vehicle platforms.
For Investors and Strategic Acquirers: Capital is best deployed toward firms specializing in software-defined access systems and advanced mechatronics. Long-term viability rests on the continued shift to connected and autonomous vehicle architectures. Target acquisition profiles include innovators in automotive cybersecurity solutions. The signal to watch is OEM commitments to digital key standardization and over-the-air update capabilities across their fleets.
| Strategic Initiative | Industry Significance |
|---|---|
| Software-Defined Access Platform Development | Enhances digital key functionalities, creating new revenue streams for vehicle manufacturers. |
| Cybersecurity Protocol Integration | Mitigates risks associated with connected latches, ensuring vehicle security and data integrity. |
| Electromechanical Component R&D | Drives innovation in advanced latch features, supporting premium and electric vehicle market growth. |
| Aftermarket Upgrade Kit Expansion | Captures value from existing vehicle fleets, offering modern convenience features to a broader consumer base. |
| Global Manufacturing Footprint Optimization | Secures supply chain resilience, addressing regional demand shifts and geopolitical risks for components. |
Research Approach
Desk research of vehicle production databases, automotive safety standard documents, and company financial filings preceded structured interviews with Tier-1 supplier executives, OEM procurement specialists, and automotive safety regulators. This approach combined primary insights with secondary validation, employing both bottom-up and top-down triangulation. Industry association reports and regulatory updates also informed the analysis.
Assumptions regarding electric vehicle adoption rates and SUV market share growth were held constant across the analysis window. The analytical framework modeled segmentation dimensions including product type, technology, application, end-user, and regional production clusters. Compound annual growth rates were derived from historical data extrapolation and projected market shifts. Key forecast inputs included regulatory updates on safety and cybersecurity standards.
Practitioners should monitor semiconductor supply stability and evolving cybersecurity threats for early signals of market shifts. Forecasts reflect current assumptions about technological and regulatory trajectories. Quarterly review of OEM digital key adoption rates and new safety mandates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Interior & Exterior
Automotive OEM Interior Coatings Market
Automotive Interior & Exterior
Automotive Exterior Smart Lighting Market
Automotive Interior & Exterior
Automotive Clear Coat Paint Market
Automotive Interior & Exterior
Light Weight Automotive Body Panels Market
Automotive Interior & Exterior
Automotive Air Conditioning Market
Automotive Interior & Exterior
Auto Ventilated Seat Fan Market
Automotive Interior & Exterior
Automotive Films Market
Automotive Interior & Exterior
Automotive Display Market
Automotive Interior & Exterior
Seat Comfort and Lumbar Actuator Systems Market
Automotive Interior & Exterior
Automotive Expanded Polypropylene (EPP) Foam Market
Automotive Interior & Exterior
Exterior Car Accessories Market
Automotive Interior & Exterior
Automotive Active Grille Shutter (AGS) Market
Automotive Interior & Exterior
Automotive Telescopic Mirror Market
Automotive Interior & Exterior
Global Automotive Anti Vibration Mounting Market
Automotive Interior & Exterior
Automotive Fuel Tank Covers Market
Automotive Interior & Exterior
Commercial Vehicle Seats Market