
 Automotive Air Purifier Market | 2026-2036
Automotive Air Purifier Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Air Purifier Market Intelligence
Subscription-based fleet purification services and asset-light leasing models for cabin air systems are reshaping competitive entry barriers. Panasonic Corporation leverages its semiconductor-grade filtration heritage to sustain premium positioning in luxury vehicle programs. DENSO CORPORATION anchors Japanese OEM supply chains through backward integration into filter media manufacturing. Robert Bosch GmbH competes across European and Asian platforms with modular purifier architectures that reduce vehicle integration costs.
An automotive air purifier is an electromechanical cabin system engineered to remove particulate matter, volatile organic compounds, and biological contaminants from enclosed vehicle air volumes, typically achieving HEPA-grade efficiency at airflow rates between 150 and 500 cubic meters per hour depending on cabin class. The device integrates blower motors, multi-stage filter media, and sensor arrays to maintain real-time air quality indices for occupant respiratory protection. HEPA Filters and Activated Carbon Filters dominate value capture due to replacement-cycle recurring revenue and OEM certification requirements, while UV Light Purifiers represent the fastest-expanding technology segment as semiconductor-grade UV-C diode costs decline. Application demand concentrates in Personal Vehicles and Luxury Cars, where cabin wellness features command price premiums and brand differentiation.
EPA cabin air quality advisories and California Air Resources Board low-emission vehicle protocols are mandating finer particulate capture thresholds, forcing filter media suppliers to recertify products against tightened test protocols. China's GB/T automotive air quality standards and SAMR product safety registrations create parallel compliance tracks that fragment certification costs for multinational suppliers. Stakeholders must monitor divergence between regional filtration performance benchmarks and the capital allocation trade-offs between unified global platforms versus region-specific product variants.
Market Dynamics
OEM procurement of cabin air quality systems is intensifying as passenger health becomes a differentiated selling point, tightening filtration performance thresholds across certification regimes and compressing supplier margins through backward integration into filter media manufacturing.
Growth Catalysts
- EPA Indoor Air Quality Guidelines:The EPA's tightening cabin air quality advisories mandate finer particulate capture thresholds, forcing automakers to spec HEPA-grade systems as standard equipment across mid-tier and luxury vehicle classes.
- China's GB/T Automotive Air Quality Standards:Dense urban air pollution in Beijing, Shanghai, and Shenzhen drives consumer willingness to pay for cabin wellness features, outpacing comparable demand formation in other geographies.
- UV-C Diode Cost Decline:Semiconductor-grade UV-C diode manufacturing scale economies are enabling UV light purifier integration into mass-market vehicle platforms previously limited to activated carbon and HEPA filtration.
Market Restraints
- Filter Media Supply Concentration:Japanese and German filter media suppliers control proprietary electrostatic charging technologies for sub-micron capture, creating single-source dependencies for OEMs seeking dual-cabin certification.
- California Air Resources Board Recertification Burden:CARB's low-emission vehicle protocols require filter media suppliers to recertify products against tightened test protocols, extending product development cycles and freezing platform decisions.
- Activated Carbon Input Volatility:Coconut shell and coal-based activated carbon prices fluctuate with agricultural yield cycles and mining permit renewals in Southeast Asian supply basins, compressing gross margins on replacement filter cartridges.
Strategic Opportunities
- Subscription Fleet Purification Services:Asset-light leasing models for cabin air systems allow ride-hail and corporate fleet operators to upgrade purification tiers without capital deployment, opening recurring revenue streams for system integrators.
- India's BIS Automotive Component Certification:India's Bureau of Indian Standards is harmonizing cabin air quality benchmarks with European protocols, creating a regulatory tailwind for suppliers with existing ECE R44 or REACH-compliant product families.
- Sensor-Filtration Convergence:Real-time air quality indices delivered through vehicle infotainment systems are creating data-service bundles that lock in aftermarket filter replacement through predictive maintenance algorithms.
Industry Challenges
- Multi-Protocol Certification Timelines:China's SAMR product safety registrations run parallel to EPA and CARB tracks, fragmenting engineering resources and delaying unified global platform launches by 12-18 months.
- Legacy HVAC Integration Complexity:Cabin air purifier architectures must interface with existing blower motor control systems and climate control modules, requiring software stack rewrites that strain Tier-1 engineering bandwidth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Air Purifier Market |
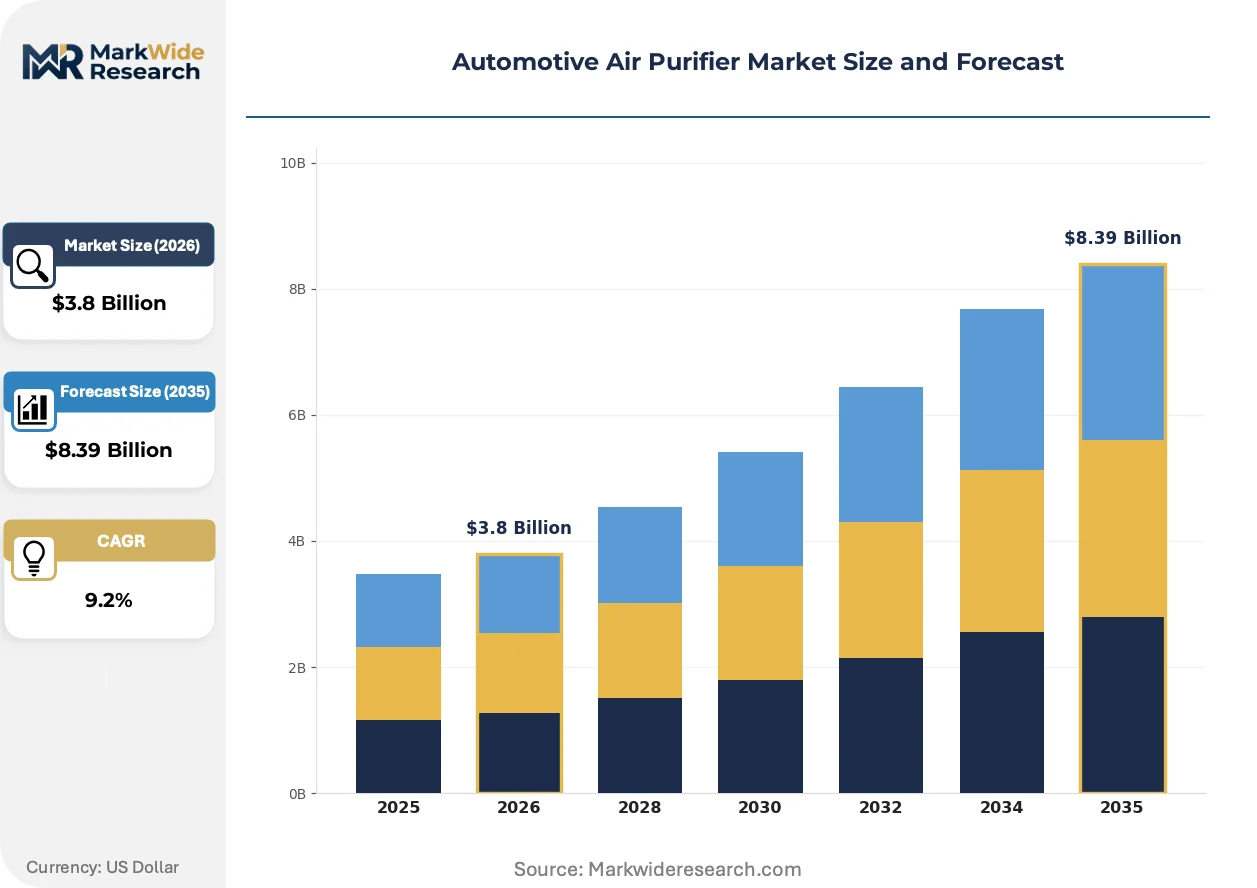
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.39 Billion |
| CAGR (2026 – 2036) | 9.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: HEPA Filters, Activated Carbon Filters, Ionizers, UV Light Purifiers, Photocatalytic Filters Technology: Electrostatic Precipitation, UV Sterilization, Negative Ion Generation, Photocatalytic Oxidation, Ozone Generation Application: Personal Vehicles, Commercial Fleet, Luxury Cars, Off-road Vehicles, Ride-share Services End User Type: OEMs, Aftermarket Suppliers, Vehicle Dealers, Fleet Operators, Rental Services |
| Companies Covered | Honeywell International Inc., Panasonic Corporation, DENSO CORPORATION, 3M, Robert Bosch GmbH, Sharp Corporation, Koninklijke Philips N.V., MAHLE GmbH, MANN+HUMMEL, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Air Purifier Market Strategic Shifts & Innovations
Filtration technology convergence with semiconductor-grade sensing and UV-C diode manufacturing is compressing the performance gap between aftermarket and OEM-integrated systems, while regulatory divergence between regional certification tracks fragments supplier R&D allocation.
Photocatalytic oxidation coatings paired with UV-C LED arrays are achieving VOC decomposition rates previously requiring kilogram-scale activated carbon beds. Luxury vehicle programs in Germany and South Korea are adopting these systems as standard equipment. The technology is rendering obsolete the volume-intensive filter cartridge replacement cycles that sustained aftermarket revenue pools.
China's SAMR product safety registrations and GB/T automotive air quality standards are tightening in parallel with California Air Resources Board protocols, creating a dual-compliance burden for multinational suppliers. Filter media manufacturers must now maintain separate test cell certifications for electrostatic efficiency and formaldehyde capture. European OEMs with China-specific joint ventures are absorbing the highest recertification costs, forcing platform architecture decisions toward region-specific variants rather than unified global designs.
Fleet operators are unbundling cabin air system procurement from vehicle acquisition, contracting purification-as-a-service through monthly per-vehicle fees. This model displaces capital expenditure with operating expenditure accounting, appealing to ride-hail aggregators in São Paulo, Mexico City, and Jakarta. The shift concentrates buyer power with fleet management platforms, compressing supplier margins and privileging integrators with balance sheet capacity to carry asset bases.
Automotive Air Purifier Market Segmentation
Segmentation in automotive air purification reveals divergent margin profiles and replacement-cycle economics across filter media, technology platforms, and procurement channels. Understanding these splits enables suppliers to allocate R&D and manufacturing capacity toward segments with sustainable recurring revenue rather than one-time hardware sales.
Product Type:
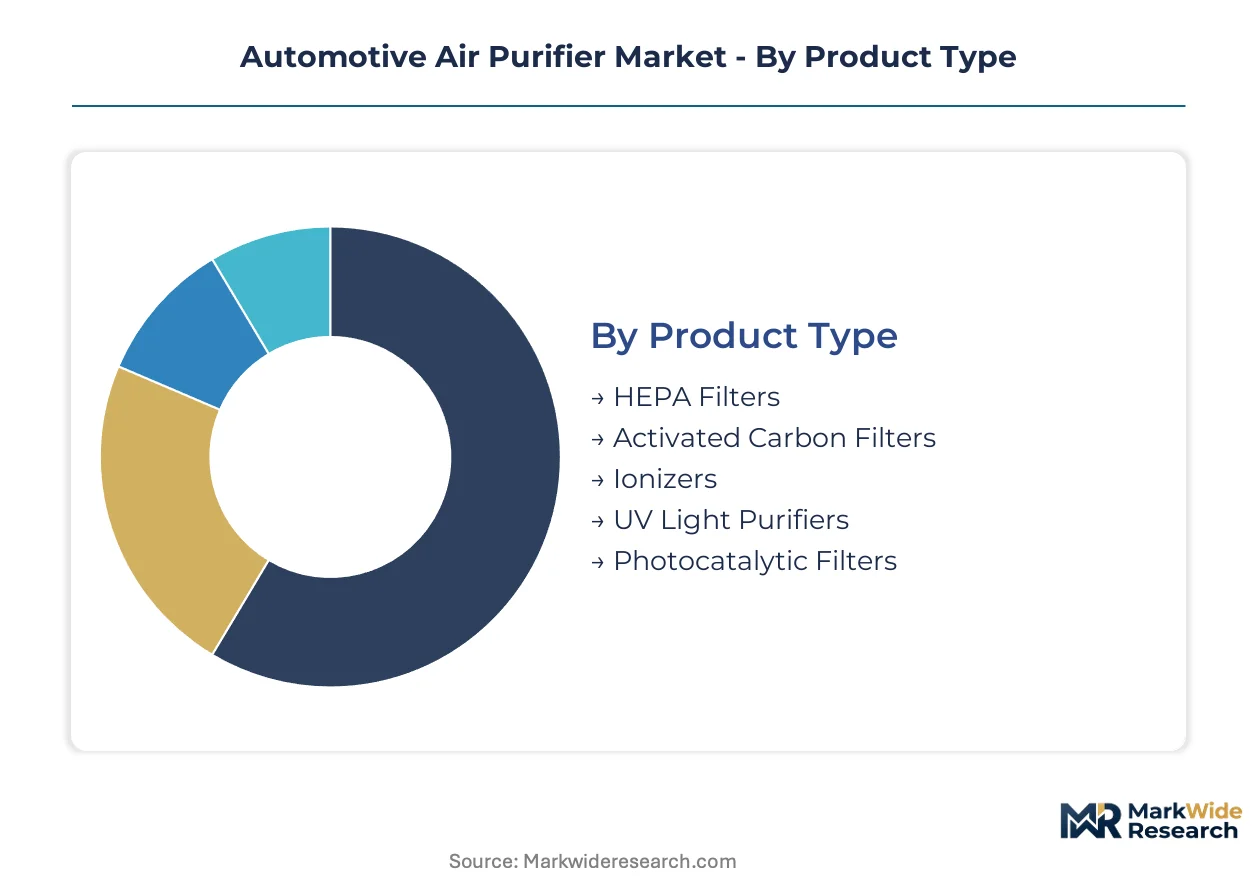
Replacement cycles vary dramatically across filter technologies, from annual cartridge swaps to decade-long UV diode lifespans, creating fundamentally different revenue recognition patterns for suppliers.
- HEPA Filters:Pleated microfiber media achieving 99.97% capture at 0.3 microns, certified to EN 1822 and IEST-RP-CC001 standards. Personal vehicle owners in Shanghai and Beijing replace these at 12-18 month intervals due to extreme ambient particulate loads, generating predictable aftermarket demand.
- Activated Carbon Filters:Impregnated coconut shell or coal-based substrates adsorbing formaldehyde and benzene compounds through physisorption. Luxury car programs in Germany specify dual-layer HEPA-carbon composites as standard equipment, though raw material price volatility from Southeast Asian supply basins compresses gross margins.
- Ionizers:Corona discharge electrodes generating unipolar ions for particulate agglomeration.
- UV Light Purifiers:UV-C LED arrays at 265-280 nanometers disrupting pathogen RNA.
- Photocatalytic Filters:Titanium dioxide coatings activated by UV-A illumination.
HEPA Filters dominate installed base. UV Light Purifiers are where expansion concentrates.
Technology:
Cost tiers separate legacy electrostatic systems from semiconductor-dependent platforms, with pricing stratifying across premium, standard, and economy certification grades.
- Electrostatic Precipitation:High-voltage ionization wires charging particles for collection on grounded plates. Commercial fleet operators in São Paulo favor these for zero filter replacement costs despite higher energy draw.
- UV Sterilization:Mercury-vapor lamps or solid-state diodes delivering germicidal irradiation. South Korean OEMs integrate these into luxury vehicle HVAC modules as wellness differentiators against German competitors.
- Negative Ion Generation:Brush discharge electrodes producing ambient ion concentrations.
- Photocatalytic Oxidation:UV-activated catalysts mineralizing VOCs into water and carbon dioxide.
- Ozone Generation:Silent arc or UV methods producing triatomic oxygen for odor elimination.
Electrostatic Precipitation commands volume leadership. Photocatalytic Oxidation is climbing the fastest on technology substitution.
Application:
Customer type determines performance specifications, with ride-share platforms demanding rapid-cycle durability that personal vehicle owners will not pay for.
- Personal Vehicles:Compact console-mounted or HVAC-integrated units serving single-family ownership patterns. China's dense urban corridors concentrate demand here, where consumers treat cabin air quality as a health necessity rather than luxury feature.
- Commercial Fleet:Heavy-duty architectures with extended service intervals for logistics and delivery vehicles. Fleet operators in Mexico City contract purification-as-a-service to avoid capital deployment on depreciating assets.
- Luxury Cars:Multi-stage systems with real-time air quality displays and fragrance integration.
- Off-road Vehicles:Ruggedized enclosures resisting dust ingress and vibration fatigue.
- Ride-share Services:Rapid-install aftermarket units for driver-owned vehicles.
Personal Vehicles anchor production volumes. Commercial Fleet is gaining share fastest on subscription model adoption.
End User Type:
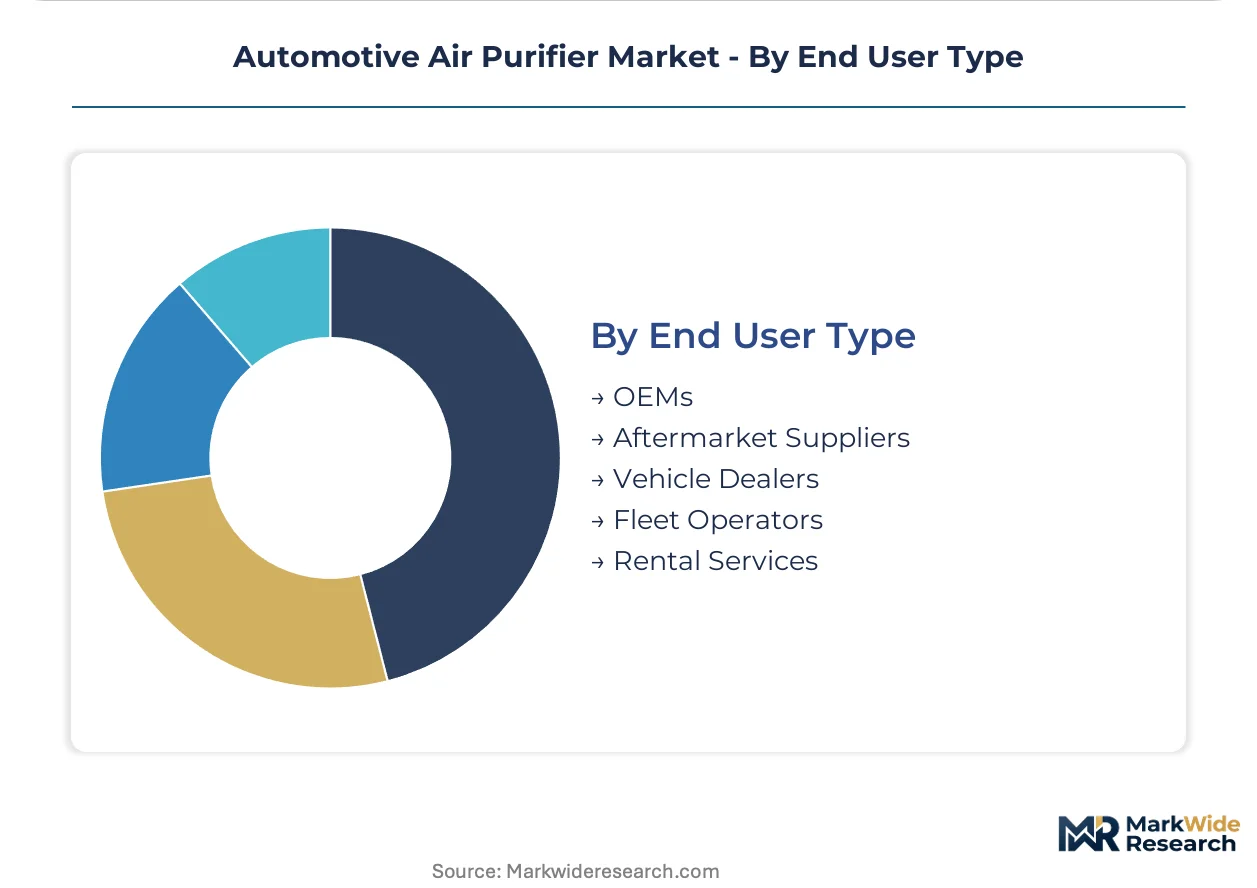
Procurement authority concentrates with OEMs for new vehicle platforms, though aftermarket channels capture higher per-unit margins on replacement cycles.
- OEMs:Direct specification of cabin air systems during vehicle platform development. Japanese OEMs enforce backward integration into filter media manufacturing, squeezing Tier-1 supplier margins through captive supply.
- Aftermarket Suppliers:Replacement cartridge and retrofit kit distribution through retail and e-commerce. India's BIS certification harmonization with European protocols is opening this channel for REACH-compliant product families.
- Vehicle Dealers:Accessory bundling at point of sale.
- Fleet Operators:Centralized procurement for ride-hail and corporate pools.
- Rental Services:Short-term vehicle fleet maintenance programs.
OEMs control platform access. Aftermarket Suppliers capture the steepest expansion trajectory on replacement-cycle economics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fleet operators and luxury vehicle buyers concentrate procurement authority across distinct geographies, with dense urban corridors driving cabin wellness specification and regulatory compliance shaping supplier certification investments.
China
Beijing, Shanghai and Shenzhen generate concentrated demand from consumer willingness to pay for health protection against extreme ambient particulate loads. SAMR product safety registrations and GB/T automotive air quality standards tighten filtration performance thresholds in parallel. Yangtze River Delta manufacturing clusters absorb the highest recertification costs for electrostatic efficiency and formaldehyde capture testing.
United States
EPA indoor air quality guidelines and California Air Resources Board protocols mandate HEPA-grade systems as standard equipment across mid-tier and luxury vehicle classes. CARB's low-emission vehicle recertification requirements extend product development cycles for filter media suppliers. Detroit-area OEM engineering centers drive platform architecture decisions that ripple through North American supply chains.
Germany
Luxury car programs specify multi-stage HEPA-carbon composite systems as wellness differentiators against Asian competitors. ECE R44 compliance and REACH chemical safety protocols create certification overlap with Indian BIS harmonization efforts. Bavaria-based engineering clusters concentrate HVAC integration expertise for climate control module interfacing.
Japan
Japanese OEMs enforce backward integration into filter media manufacturing, squeezing supplier margins through captive electrostatic charging technology for sub-micron capture. METI industrial standards and JIS certification requirements maintain parallel compliance tracks with EPA protocols. Nagoya-area production clusters anchor supply chain control for domestic vehicle platforms.
South Korea
Seoul Capital Area luxury vehicle programs integrate UV sterilization modules as wellness features against German competitors. MFDS medical device manufacturing heritage transfers semiconductor-grade UV-C diode sourcing relationships into automotive applications. Busan-Ulsan industrial corridors concentrate electronics integration capacity for real-time air quality display systems.
Automotive Air Purifier Market Key Industry Players
Channel-controlling players compete with product-specialist players across OEM specification and aftermarket replacement cycles, creating a tiered structure where filtration media ownership determines margin capture. Japanese and German suppliers dominate proprietary electrostatic technologies, forcing dual-source strategies on automakers seeking certification redundancy. Three archetypes anchor positioning: integrated HVAC conglomerates with backward filter media control, semiconductor-grade component specialists leveraging diode cost curves, and aftermarket cartridge distributors capturing replacement-cycle economics. Competitive moves concentrate on M&A for test cell certification assets and strategic partnerships for fleet purification-as-a-service deployment.
Among diversified industrial conglomerates, Panasonic Corporation and DENSO CORPORATION exemplify integrated archetypes with captive supply chain positioning. Robert Bosch GmbH occupies a modular architecture role across European and Asian platform integration. These three anchors represent distinct strategic postures: semiconductor heritage leverage, OEM supply chain anchoring through upstream manufacturing control, and vehicle integration cost reduction through standardized system designs.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| Panasonic Corporation |
| DENSO CORPORATION |
| 3M |
| Robert Bosch GmbH |
| Sharp Corporation |
| Koninklijke Philips N.V. |
| MAHLE GmbH |
| MANN+HUMMEL |
| Others |
Cost & Logistics Intelligence
The Yangtze River Delta freight corridor absorbs elevated logistics costs for electrostatic filter media shipments, compressing margins for German and Japanese suppliers while enabling Chinese manufacturers to price HEPA-carbon composites more aggressively. This cost asymmetry feeds downstream price differentiation between OEM-integrated systems and aftermarket replacement cartridges.
Pricing Analysis
Cost-plus contracts with coconut shell activated carbon indexation dominate procurement agreements between filter media suppliers and automotive OEMs. Pricing stratifies across premium, standard, and economy certification tiers, with EPA and CARB compliance commanding substantial premiums over baseline EN 1822 certification. Cost compression in the standard tier is intensifying due to backward integration by Japanese OEMs into captive electrostatic charging production. Fleet operators exhibit the highest price sensitivity, while luxury vehicle programs demonstrate minimal elasticity for wellness-feature bundling.
Supply Chain Analysis
Supplier-financing facilities extended by Japanese trading houses enable Yangtze River Delta manufacturers to bridge 90-day payment terms demanded by European OEMs. Manufacturing concentrates in China, Germany, and Japan, with filter media production drawing from proprietary electrostatic charging equipment concentrated in Osaka and Stuttgart engineering clusters. Single-source vulnerability persists for sub-micron capture media certified to dual EPA-SAMR protocols. Distribution runs through captive OEM supply chains for new vehicle platforms and independent aftermarket distributors for replacement cycles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in early-cycle expansion as UV-C diode cost curves enable technology substitution previously blocked by semiconductor pricing. Penetration of photocatalytic oxidation systems in luxury vehicle programs signals mainstream adoption trajectory.
For Market Incumbents: Insulate margin position through captive filter media manufacturing and dual-certification test cell ownership. Panasonic and DENSO demonstrate the defensive value of backward integration into electrostatic charging technology. Priority investment targets SAMR-EPA parallel certification capacity to preempt 12-18 month platform launch delays.
For New Entrants and Emerging Players: Establish a beachhead in India's BIS-harmonized aftermarket channel, where European REACH-compliant product families face minimal recertification burden. The ride-hail fleet purification-as-a-service segment offers the most penetrable white space, with São Paulo and Jakarta operators seeking asset-light subscription models over capital deployment.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with underperforming HVAC filtration divisions. Long-term viability hinges on semiconductor-grade sensing convergence and UV-C diode integration capabilities. The signal to watch is fleet operator consolidation into centralized procurement platforms, which would accelerate subscription model adoption and compress supplier margins.
| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Certification Test Cell Investment | Parallel EPA and SAMR certification capacity accelerates unified global platform launches by 12-18 months. |
| UV-C Diode Supply Agreement | Semiconductor-grade sourcing relationships from South Korean MFDS heritage manufacturers enable mass-market integration. |
| Fleet Purification-as-a-Service Platform | Asset-light subscription models displace capital expenditure for São Paulo and Jakarta ride-hail operators. |
| Backward Integration into Filter Media | Captive electrostatic charging production replicates Japanese OEM margin defense against Tier-1 suppliers. |
| Photocatalytic Oxidation R&D Partnership | Titanium dioxide coating expertise from German luxury programs transfers to mid-tier vehicle classes. |
Research Approach
Findings reconcile primary fieldwork against secondary review of EPA regulatory filings, SAMR registration databases, and IHS Markit vehicle production data. Interviews with Tier-1 supplier procurement officers, OEM platform engineers, aftermarket distributors, and fleet operations managers informed demand segmentation. Bottom-up triangulation against top-down macroeconomic indicators validates volume and value outputs.
Forecast inputs incorporate vehicle class, propulsion architecture, content per vehicle, OEM tier, and regional production cluster segmentation. CAGRs derive from installed base growth, replacement cycle frequency, and technology substitution curves across the projection horizon. UV-C diode cost decline trajectories and fleet subscription model adoption rates constitute industry-specific forecast variables.
Sensitivities concentrate around regulatory divergence between EPA and SAMR protocols, activated carbon input volatility from Southeast Asian supply basins, and semiconductor supply constraints affecting UV-C diode availability. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Interior & Exterior
Rear-View Mirror Market
Automotive Interior & Exterior
United Kingdom Automotive Sunroof Market
Automotive Interior & Exterior
Germany Automotive Adaptive Lighting System Market
Automotive Interior & Exterior
Automotive Floor Mats Market
Automotive Interior & Exterior
Automotive Headlamp Reflector Market
Automotive Interior & Exterior
LED-Based Exterior Navigation and Position Lighting Systems Market
Automotive Interior & Exterior
Automotive Tinting Film Market
Automotive Interior & Exterior
Cup Holder Market
Automotive Interior & Exterior
Automotive Exterior Smart Lighting Market
Automotive Interior & Exterior
Sun Visor Market
Automotive Interior & Exterior
Automotive Glove Box Market
Automotive Interior & Exterior
Global Automotive Windscreen Glazing Market
Automotive Interior & Exterior
North America Automotive Interiors Market
Automotive Interior & Exterior
Automotive Lighting Molds Market
Automotive Interior & Exterior
Automotive Bovine Leather Market
Automotive Interior & Exterior
Automotive Automatic Liftgate Market