
 Automotive Headlamp Reflector Market | 2026-2036
Automotive Headlamp Reflector Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Headlamp Reflector Market Intelligence
Optical engineering talent scarcity is redrawing competitive boundaries across the Automotive Headlamp Reflector Market. Koito Manufacturing Co., Ltd. leverages captive injection-molding capacity in Japan to sustain premium reflector supply contracts with Toyota and Lexus. Stanley Electric Co., Ltd. anchors North American production through its Mexico facility, dominating reflector exports to Detroit-based vehicle assemblers. ZKW Group GmbH competes on adaptive-driving-beam integration, specializing in mechatronic reflector modules that pair with camera-based leveling systems.
An automotive headlamp reflector is a precision-contoured optical component, typically vacuum-metallized with aluminum to achieve reflectivity exceeding 85%, that collects and directs light from a source into a regulated beam pattern. The component serves the primary commercial purpose of enabling compliance with photometric intensity standards while minimizing glare to oncoming traffic. LED reflectors now command the fastest expansion within product type segmentation, as thermal management requirements drive substitution of halogen architectures; among materials, glass fiber reinforced polymer variants capture margin pools through weight reduction credentials that support OEM fleet efficiency targets. Passenger vehicle applications lead volume, though commercial vehicle reflector demand stiffens as ECE R48 lighting installation rules tighten for heavy-duty trucks.
ECE R48 and FMVSS 108 shape product geometry and intensity distribution requirements across Europe and the United States, forcing suppliers to maintain dual certification pipelines for cross-regional OEM programs. China's GB 4599 standard and Japan's JIS D 5500 impose additional localized beam-pattern tests that complicate platform standardization. REACH substance restrictions in Europe and EPA chemical reporting in the United States constrain metallization chemistry choices, particularly for chrome-alternative coatings. Stakeholders must monitor divergence between UN-ECE harmonization efforts and national deviation clauses when allocating R&D budgets across reflector platform families.
Market Dynamics
LED thermal management requirements are compressing halogen reflector architectures while polycarbonate-composite molding investments concentrate supply among thermoplastic specialists with vacuum-metallization capabilities.
Growth Catalysts
- Euro NCAP pedestrian safety protocols:Beam-pattern precision mandates are accelerating OEM procurement of adaptive LED reflector modules that minimize upward light spill.
- Glass fiber reinforced polymers:Weight reduction credentials in polycarbonate-composite housings align with fleet efficiency targets set by EPA fuel economy standards.
- Germany:Valeo SE and HELLA GmbH operate advanced thermoplastic molding facilities that anchor European supply for premium reflector modules.
Market Restraints
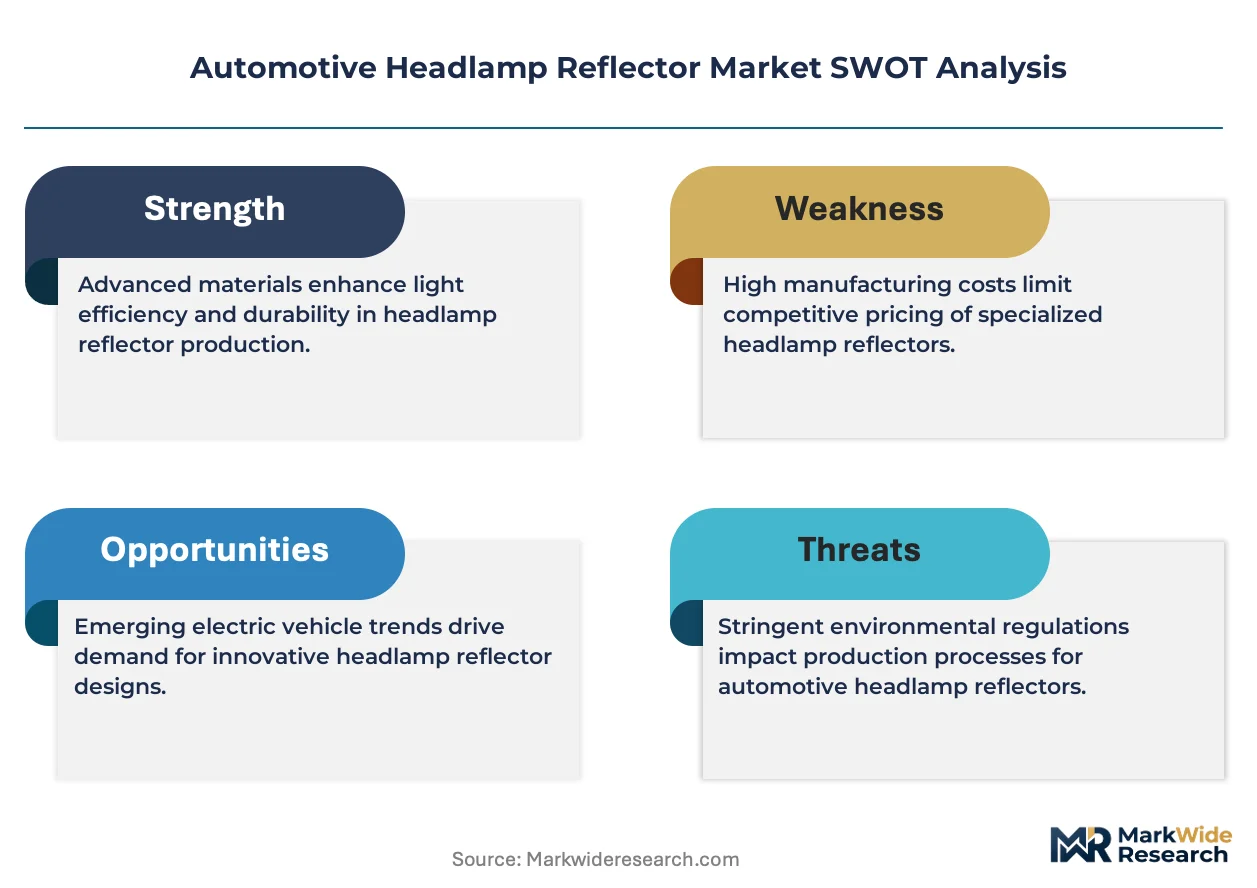
- Aluminum vacuum-metallization chemistry:REACH substance restrictions in Europe and EPA chemical reporting constrain coating formulation choices and raise compliance overhead.
- Optical engineering talent scarcity:Precision contour design capabilities concentrate in Japan and Germany, limiting supplier expansion into mechatronic reflector integration.
- Dual certification pipelines:ECE R48 and FMVSS 108 divergence forces redundant testing for cross-regional OEM programs, inflating platform development costs.
Strategic Opportunities
- Commercial vehicle segments:ECE R48 lighting installation rule tightening for heavy-duty trucks opens margin pools in reflector modules with enhanced durability specifications.
- Camera-based leveling convergence:Mechatronic reflector modules paired with adaptive driving beam systems represent unclaimed territory between lighting and ADAS suppliers.
- Japan's JIS D 5500 localization:Beam-pattern test requirements distinct from UN-ECE standards create captive demand for region-specific reflector geometries.
Industry Challenges
- Photometric intensity certification timelines:GB 4599 standard compliance in China adds localized testing layers that delay platform standardization across OEM global architectures.
- Legacy halogen thermal interface legacy:LED reflector module integration requires redesigned heat-sink geometries that conflict with existing headlamp housing footprints.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Headlamp Reflector Market |
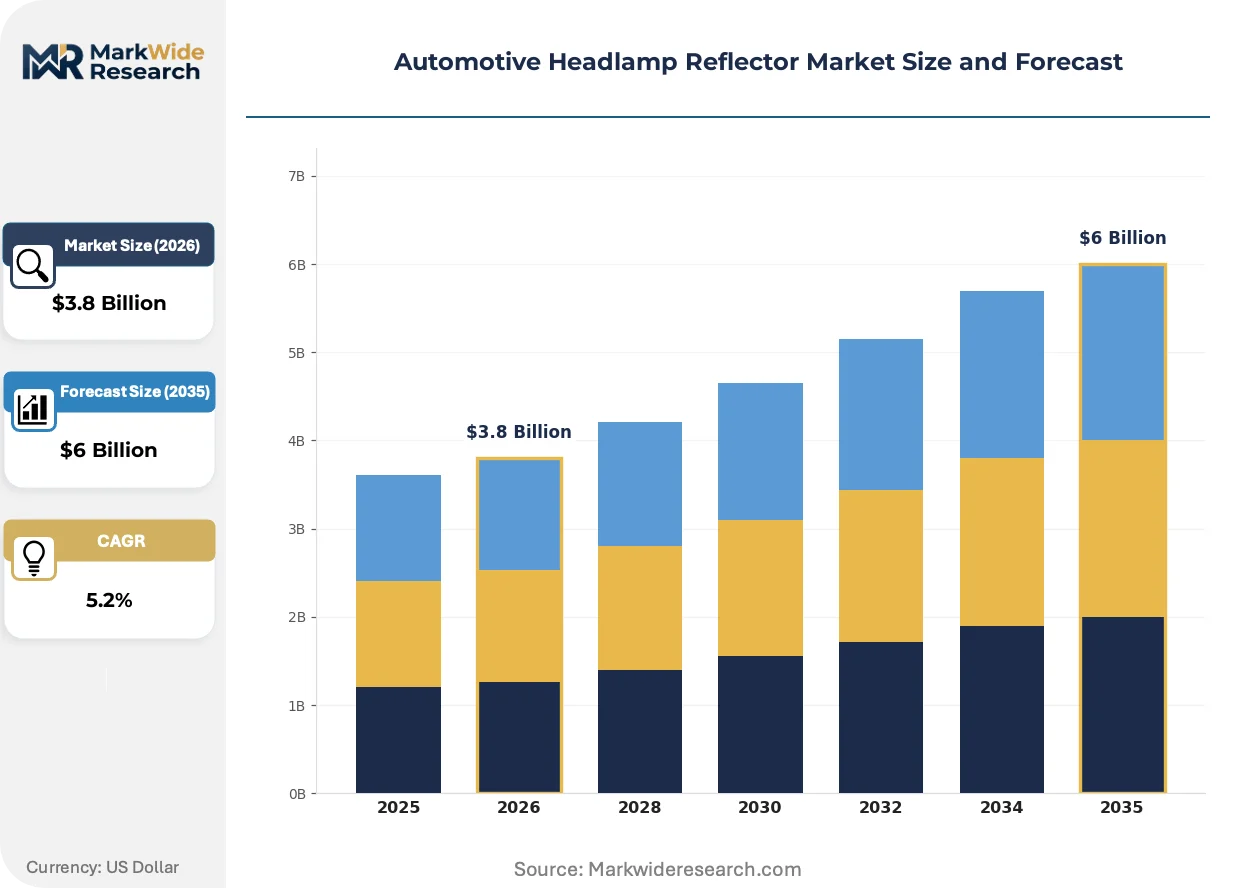
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Halogen Reflectors, LED Reflectors, HID Reflectors, Laser Reflectors Material: Plastic, Aluminum, Composite, Glass Fiber Reinforced Polymer Application: Passenger Vehicles, Commercial Vehicles, Two-wheelers, Off-road Vehicles End User: OEMs, Aftermarket Suppliers, Tier-1 Suppliers, Vehicle Assemblers |
| Companies Covered | Stanley Electric Co., Ltd., ZKW Group GmbH, Koito Manufacturing Co., Ltd., Varroc Engineering Limited, OSRAM GmbH, Valeo SE, Marelli Holdings Co., Ltd., Robert Bosch GmbH, HELLA GmbH & Co. KGaA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Headlamp Reflector Market Strategic Shifts & Innovations
Active beam-pattern modulation is displacing static reflector geometries as pedestrian safety ratings and adaptive driving requirements reshape optical engineering priorities across passenger and commercial vehicle programs.
Free-form reflector surfaces generated through computational optical design are decomposing traditional parabolic and ellipsoidal contour standards. Premium OEM programs in Germany and Japan are adopting these surfaces at accelerating cadence to achieve precise beam cutoff control. The technology is decomposing incumbent tooling investments in fixed-die stamping and conventional injection molding.
REACH substance restrictions on chrome-alternative coatings are tightening metallization chemistry specifications across European supply chains. Industrial consequence includes accelerated qualification of aluminum-silicon oxide vacuum-deposited layers that maintain reflectivity above 85% while eliminating hexavalent chromium processes. Passenger vehicle OEMs with pan-European assembly footprints are most affected, with procurement teams dual-sourcing metallization chemistry to preempt supply interruption.
Long-term service contracts bundling reflector module replacement with headlamp assembly lifecycle management are displacing spot procurement in commercial vehicle fleets. Fleet operators in North America are consolidating vendor relationships around suppliers with captive remanufacturing capabilities. The shift is most visible in heavy-duty trucking segments where uptime guarantees now include optical performance warranties spanning million-mile duty cycles.
Automotive Headlamp Reflector Market Segmentation
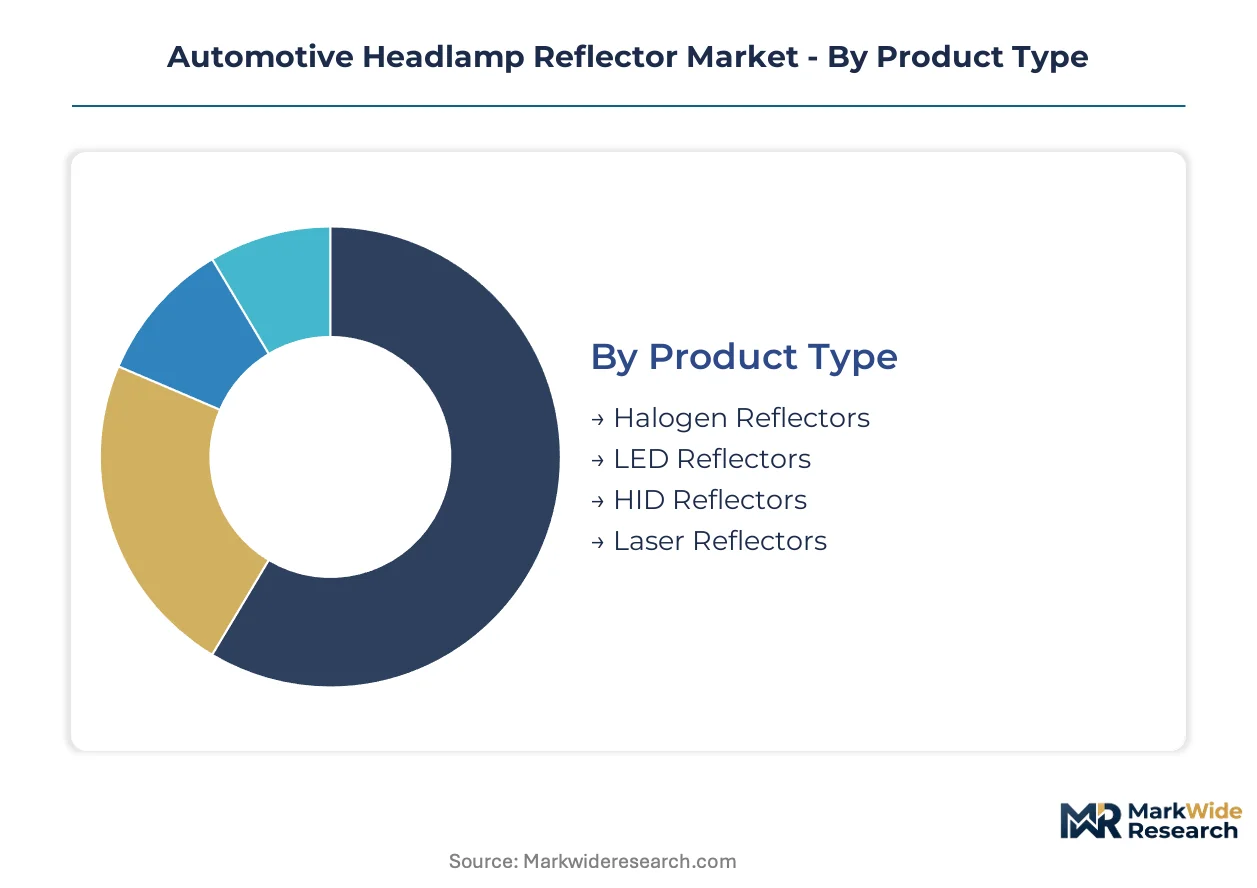
Reflector module procurement patterns diverge sharply across lighting technologies and vehicle architectures. ECE R48 beam-pattern precision mandates and EPA fleet efficiency targets reshape material selection and supplier qualification pathways.
Product Type:
Regulatory frameworks in Europe, the United States, and Japan enforce distinct photometric intensity standards that favor specific light-source architectures.
- LED Reflectors:Polycarbonate-composite housings with aluminum vacuum-metallized surfaces achieve thermal dissipation above 85% reflectivity. Euro NCAP pedestrian safety protocols in Germany and France accelerate OEM procurement for adaptive beam-pattern control.
- Halogen Reflectors:Parabolic aluminum stampings dominate legacy vehicle platforms and aftermarket replacement cycles. Demand concentrates in commercial vehicle segments across the United States where FMVSS 108 grandfathering provisions extend service intervals.
- HID Reflectors:Ellipsoidal projector modules with shielded cutoff mechanisms serve premium passenger vehicle programs in Japan under JIS D 5500 localized testing requirements.
- Laser Reflectors:Micro-lens array integrations enable extended-range high-beam activation. German OEMs lead qualification for ECE-compliant adaptive driving beam convergence.
LED reflectors handle the majority of throughput; laser reflectors are the fastest mover on share.
Material:
Weight reduction imperatives and REACH substance restrictions compress viable material choices across European and North American supply chains.
- Glass Fiber Reinforced Polymer:Polycarbonate-composite variants with 30% glass loading achieve density reductions of 40% versus aluminum stampings. EPA fuel economy standards drive adoption across Detroit-based vehicle assemblers.
- Aluminum:Vacuum-metallized stamped reflectors retain dominance in heavy-duty trucking where thermal cycling durability exceeds polymer limits. ECE R48 installation rules for commercial vehicles preserve demand in German and Polish manufacturing clusters.
- Plastic:Unfilled thermoplastic housings serve economy passenger vehicle segments with simplified beam-pattern requirements. Cost positioning sustains volume in India and Brazil assembly plants.
- Composite:Hybrid aluminum-polymer constructions balance thermal management with mass reduction. Japanese tier-1 suppliers advance these for Lexus and Toyota premium platforms.
Aluminum retains the installed base; glass fiber reinforced polymer is expanding most quickly on new platform share.
Application:
Vehicle duty cycles and regulatory exposure determine reflector durability specifications and replacement economics.
- Passenger Vehicles:Adaptive driving beam integration dominates R&D allocation. German OEMs specify free-form reflector surfaces for precise cutoff control under ECE R48.
- Commercial Vehicles:Heavy-duty trucking segments demand million-mile optical performance warranties. Fleet operators in the United States consolidate procurement around suppliers with captive remanufacturing capabilities.
- Two-wheelers:Compact halogen reflector modules serve cost-sensitive markets. India's BIS certification requirements localize supply chain configuration.
- Off-road Vehicles:Vibration-resistant aluminum housings withstand severe duty cycles. Mining and construction fleets in Australia specify enhanced durability under TGA-equivalent standards.
Passenger vehicles command the volume concentration; commercial vehicles are climbing the fastest on margin contribution.
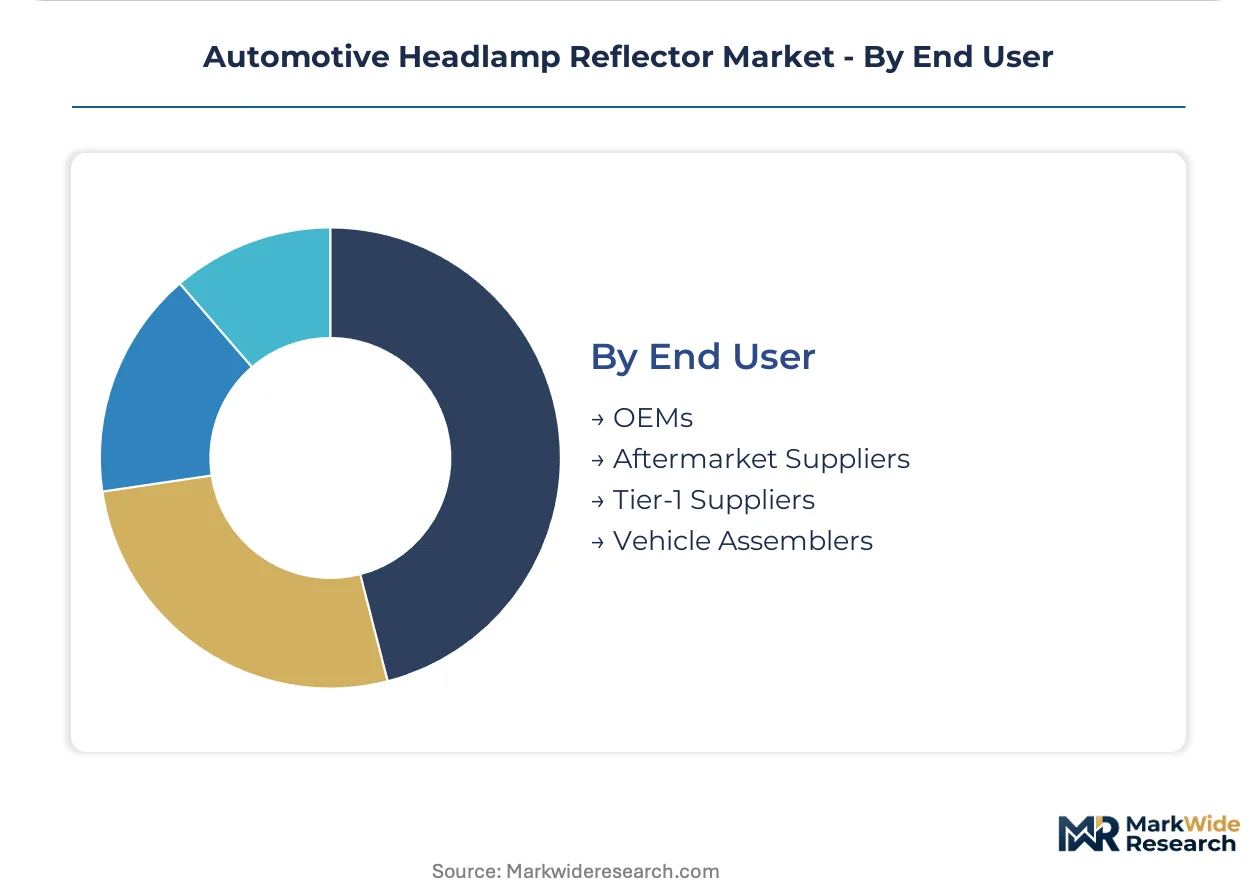
End User:
Procurement authority and technical specification control vary across the tiered automotive supply structure.
- OEMs:Direct reflector module qualification for global platform architectures. Volkswagen Group and Toyota Motor Corporation maintain captive optical engineering centers in Germany and Japan.
- Tier-1 Suppliers:Koito Manufacturing and Stanley Electric integrate reflector production with headlamp assembly. Mexico and Thailand facilities serve regional OEM demand.
- Aftermarket Suppliers:Replacement cycle capture depends on regulatory compliance documentation. EPA chemical reporting requirements constrain metallization chemistry choices for United States distribution.
- Vehicle Assemblers:Contract manufacturing arrangements in Eastern Europe and Southeast Asia source reflector modules from qualified tier-1 pipelines.
Tier-1 suppliers handle the majority of throughput; OEM direct procurement is gaining share fastest on platform consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in Germany commands a premium over Mexico due to ECE R48 certification complexity and captive thermoplastic molding infrastructure. Japan maintains intermediate positioning through JIS D 5500 localization requirements. China and the United States occupy volume-driven segments with divergent regulatory pathways.
Germany
Euro NCAP pedestrian safety protocols and adaptive driving beam mandates drive specification intensity for polycarbonate-composite reflector modules. REACH substance restrictions constrain metallization chemistry choices across Baden-Württemberg supply chains. Stuttgart and Ingolstadt clusters host Valeo SE and HELLA GmbH facilities that vacuum-metallize aluminum-silicon oxide layers for premium OEM platforms.
Japan
Toyota and Lexus platform consolidation sustains demand for precision-contoured optical components with thermal management integration. METI oversees JIS D 5500 beam-pattern testing that diverges from UN-ECE harmonization efforts. Kanto and Chubu manufacturing belts concentrate Koito Manufacturing and Stanley Electric captive injection-molding capacity serving domestic vehicle assemblers.
United States
FMVSS 108 grandfathering provisions extend halogen reflector service intervals in commercial vehicle aftermarket channels. EPA chemical reporting requirements constrain coating formulation choices for Detroit-based procurement teams. Michigan and Ohio assembly corridors source reflector modules from Stanley Electric's Mexico facility for cost-sensitive platform variants.
China
Domestic OEM platform expansion accelerates LED reflector module procurement despite GB 4599 localized testing layers. MIIT administers vehicle lighting certification timelines that delay global architecture standardization. Yangtze River Delta and Pearl River Delta industrial zones concentrate thermoplastic molding investments for glass fiber reinforced polymer housing production.
Mexico
Nearshoring incentives from USMCA provisions attract tier-1 supplier assembly for North American vehicle programs. The country's national automotive regulator enforces NOM standards that align with FMVSS 108 for cross-border component qualification. Nuevo León and Bajío Region manufacturing parks host reflector module integration facilities serving Detroit-based OEM demand.
Automotive Headlamp Reflector Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes across the Automotive Headlamp Reflector Market. The vendor base concentrates among Japanese and German specialists with captive optical engineering capabilities and thermoplastic molding infrastructure. Three archetypes dominate: integrated lighting system suppliers, mechatronic module specialists, and scale-driven polymer processors. Competitive dynamics center on backward integration into vacuum-metallization chemistry and regional certification pipeline duplication.
Among Japanese integrated lighting suppliers, Koito Manufacturing Co., Ltd. and Stanley Electric Co., Ltd. occupy positions defined by captive injection-molding capacity and domestic OEM relationships. German specialists ZKW Group GmbH exemplify the mechatronic integration archetype through adaptive-driving-beam convergence. These three entities represent distinct competitive vectors: volume-scale polymer processing, precision optical engineering, and camera-based leveling system pairing.
| Leading Market Players |
|---|
| Stanley Electric Co., Ltd. |
| ZKW Group GmbH |
| Koito Manufacturing Co., Ltd. |
| Varroc Engineering Limited |
| OSRAM GmbH |
| Valeo SE |
| Marelli Holdings Co., Ltd. |
| Robert Bosch GmbH |
| HELLA GmbH & Co. KGaA |
| Others |
Cost & Logistics Intelligence
Ninety-day aluminum vacuum-metallization lead times in European supply chains concentrate pricing power among Baden-Württemberg thermoplastic specialists with captive coating infrastructure. This inventory compression tightens procurement economics for Detroit-based vehicle assemblers sourcing from Mexico-based tier-1 integration facilities.
Pricing Analysis
Configured-to-order pricing for free-form reflector surfaces commands a 40-60% premium over standard parabolic stampings. Three-tier pricing structure across premium, standard, and economy levels stratifies by ECE R48 certification grade and adaptive driving beam integration depth. Pricing pressure stems from REACH substance restriction compliance overhead in European supply chains. Aftermarket distributors exhibit highest price sensitivity; OEM direct procurement teams prioritize optical performance warranties over unit cost.
Supply Chain Analysis
Inventory compression to 45-60 days of polycarbonate-composite feedstock concentrates supply risk in Germany, Japan, and Mexico manufacturing clusters. Raw material dependencies center on aluminum ingot for vacuum-metallization, glass fiber reinforced polymer pellets, and silicon oxide coating precursors. Single-source vulnerability in aluminum-silicon oxide chemistry qualification creates regulatory exposure under EPA chemical reporting. Distribution runs through tier-1 supplier integration facilities co-located with OEM assembly corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Precision optical engineering talent scarcity constrains supplier expansion into mechatronic reflector integration, concentrating value capture among Japanese and German specialists with captive thermoplastic molding infrastructure.
For Market Incumbents: Compound defensive positioning through backward integration into vacuum-metallization chemistry and dual certification pipeline duplication for ECE R48-FMVSS 108 convergence. Koito Manufacturing and Stanley Electric anchor volume-scale polymer processing against emerging mechatronic specialists. Prioritize captive remanufacturing capabilities for commercial vehicle fleet lifecycle contracts. For New Entrants and Emerging Players: ECE R48 fast-track certification for adaptive driving beam modules opens white-space in camera-based leveling convergence between lighting and ADAS suppliers. Target commercial vehicle segments in North America with million-mile optical performance warranties. Pursue platform standardization partnerships with Detroit-based vehicle assemblers seeking second-source reflector supply. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with underutilized thermoplastic molding assets and dormant optical engineering capabilities. Five-to-ten year viability hinges on LED thermal management integration depth and regional certification pipeline control. Monitor GB 4599 compliance timeline divergence as inflection indicator for China platform standardization economics.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Vacuum-Metallization Chemistry | Eliminates REACH substance restriction exposure for European supply chains serving Stuttgart OEM clusters. |
| Dual Certification Pipeline Investment | Enables single-platform supply to both ECE R48 and FMVSS 108 regulatory jurisdictions without redundant tooling. |
| Free-Form Reflector Surface Capability Buildout | Captures premium procurement from German OEMs specifying computational optical design for beam cutoff precision. |
| Captive Remanufacturing Infrastructure | Secures long-term service contracts with North American heavy-duty trucking fleets demanding uptime guarantees. |
| Camera-Based Leveling System Partnership | Positions reflector modules within ADAS convergence architecture for adaptive driving beam integration. |
Research Approach
The analysis maps LED reflector modules, halogen legacy architectures, and mechatronic adaptive beam systems, each validated through Tier 1 supplier procurement directors, OEM platform engineers, aftermarket distribution channel heads, and optical engineering specialists. Primary interview intelligence triangulates against vehicle production databases, IHS Markit registration data, ECE R48 certification filings, and EPA chemical reporting disclosures. Bottom-up unit economics and top-down market sizing converge through iterative stakeholder cross-checking.
Consistency checks against external automotive lighting industry benchmarks validate volume and value outputs across the projection horizon. Segmentation dimensions include light-source architecture, material grade tier, vehicle duty cycle classification, and regional regulatory cluster. CAGRs derive from installed base turnover modeling and new platform content-per-vehicle assumptions. Forecast inputs incorporate Euro NCAP pedestrian safety protocol adoption curves and commercial vehicle fleet replacement cycle dynamics.
Decision-makers should treat outputs as directional under sustained OEM platform consolidation and REACH substance restriction enforcement; material deviation in aluminum vacuum-metallization chemistry availability would warrant model refresh. Specific risk factors include GB 4599 certification timeline delays, JIS D 5500-UN-ECE harmonization failure, and thermal management interface redesign requirements for LED module integration. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Interior & Exterior
Automotive Structural Steel Market
Automotive Interior & Exterior
Automotive Backlight Moldings Market
Automotive Interior & Exterior
Automotive Expanded Polypropylene (EPP) Foam Market
Automotive Interior & Exterior
Automotive Cabin Insulation Material Market
Automotive Interior & Exterior
Automotive Outside Rearview Mirrors (ORVM) Market
Automotive Interior & Exterior
Automotive Overhead Console Market
Automotive Interior & Exterior
Automotive Airbag Fabric Market
Automotive Interior & Exterior
Automotive Trim Market
Automotive Interior & Exterior
Blind Spot Mirror Market
Automotive Interior & Exterior
Decorative Car Accessories Market
Automotive Interior & Exterior
Automotive Baggage Handling System Market
Automotive Interior & Exterior
Automotive Smart Window Market
Automotive Interior & Exterior
Automotive Heated Seat Market
Automotive Interior & Exterior
North America Automotive Seat Market
Automotive Interior & Exterior
Automotive Plastic Interior Trims Market
Automotive Interior & Exterior
Automotive Films Market