
 LED-Based Exterior Navigation and Position Lighting Systems Market | 2026-2036
LED-Based Exterior Navigation and Position Lighting Systems Market Size, Share, and Industry Trends Forecast 2026-2036
LED-Based Exterior Navigation and Position Lighting Systems Market Insights
OEM-direct procurement channels for marine lighting is reshaping how shipbuilders source navigation systems, bypassing traditional distributor networks. Collins Aerospace leverages its integrated avionics-marine platform to sustain long-term supply agreements with NATO naval programs. Safran dominates European naval retrofit tenders through its certified MIL-STD product lines. Honeywell International anchors North American commercial vessel demand with coast-guard-approved position lighting systems.
LED-based exterior navigation and position lighting systems are solid-state electroluminescent devices engineered to emit specific chromaticity and candela outputs compliant with International Maritime Organization collision regulations, typically operating at color temperatures between 2700K and 6500K depending on vessel classification and operational zone. These systems replace incandescent and halogen marine lanterns to reduce power draw, extend maintenance intervals, and eliminate filament failure modes in salt-air environments. Chip on Board technology leads marine applications where thermal management and lumen density prove critical for masthead and combination light configurations. Surface Mount Device architectures occupy the retrofit segment due to form-factor compatibility with legacy fixture housings. High-Power LED variants represent the fastest-expanding technology category as superyacht builders and naval architects specify extended-range visibility for deep-water operations.
The International Maritime Organization enforces COLREGs Annex I lighting requirements that mandate specific arc and range performance, while the IEC 60945 marine equipment standard governs electromagnetic compatibility and environmental testing for LED navigation fixtures. The US Coast Guard certifies navigation lights under 33 CFR Part 84, creating a compliance gateway for products entering American-flagged commercial service. Stakeholders must monitor divergence between IMO harmonization efforts and emerging national cybersecurity mandates for connected lighting systems as maritime digitization accelerates.
Market Dynamics
Retrofit mandates from aging commercial fleets are compressing replacement cycles for navigation lighting systems, while shipbuilders in South Korea and China specify factory-installed LED configurations for newbuild vessels.
Growth Catalysts
- IMO COLREGs Annex I compliance deadlines:Maritime operators face mandatory upgrades to certified LED fixtures meeting arc and range specifications, eliminating grandfathered incandescent installations.
- Chip on Board thermal performance:Masthead configurations demand superior lumen density and heat dissipation that COB architectures deliver in salt-air environments.
- East Asian shipbuilding clusters:South Korean and Chinese yards constructing new-generation commercial fleets specify LED navigation systems as standard equipment.
Market Restraints
- High-Power LED input cost volatility:Rare earth phosphor and substrate material prices fluctuate with semiconductor foundry capacity constraints.
- US Coast Guard 33 CFR Part 84 certification timelines:Extended testing protocols for electromagnetic compatibility create entry barriers for non-domestic manufacturers.
- Incumbent fixture housing incompatibility:Legacy masthead and combination light enclosures limit form-factor options for Surface Mount Device retrofits.
Strategic Opportunities
- Indian coastal fleet electrification:Domestic shipyards under the country's PLI scheme for manufacturing are specifying LED navigation systems for trawler and cargo vessel newbuilds.
- Cybersecurity-hardened connected lighting:Maritime digitization creates demand for navigation fixtures with encrypted control interfaces and remote diagnostic capability.
- OEM-direct procurement channels:Shipbuilders are bypassing traditional marine distributor networks to secure long-term supply agreements directly with lighting system manufacturers.
Industry Challenges
- IEC 60945 electromagnetic compatibility testing:Navigation fixture manufacturers face extended validation cycles for environmental and interference certification.
- Legacy vessel electrical system integration:Aging fleet retrofits require voltage converter installation and wiring harness modification to accommodate solid-state LED drivers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | LED-Based Exterior Navigation and Position Lighting Systems Market |
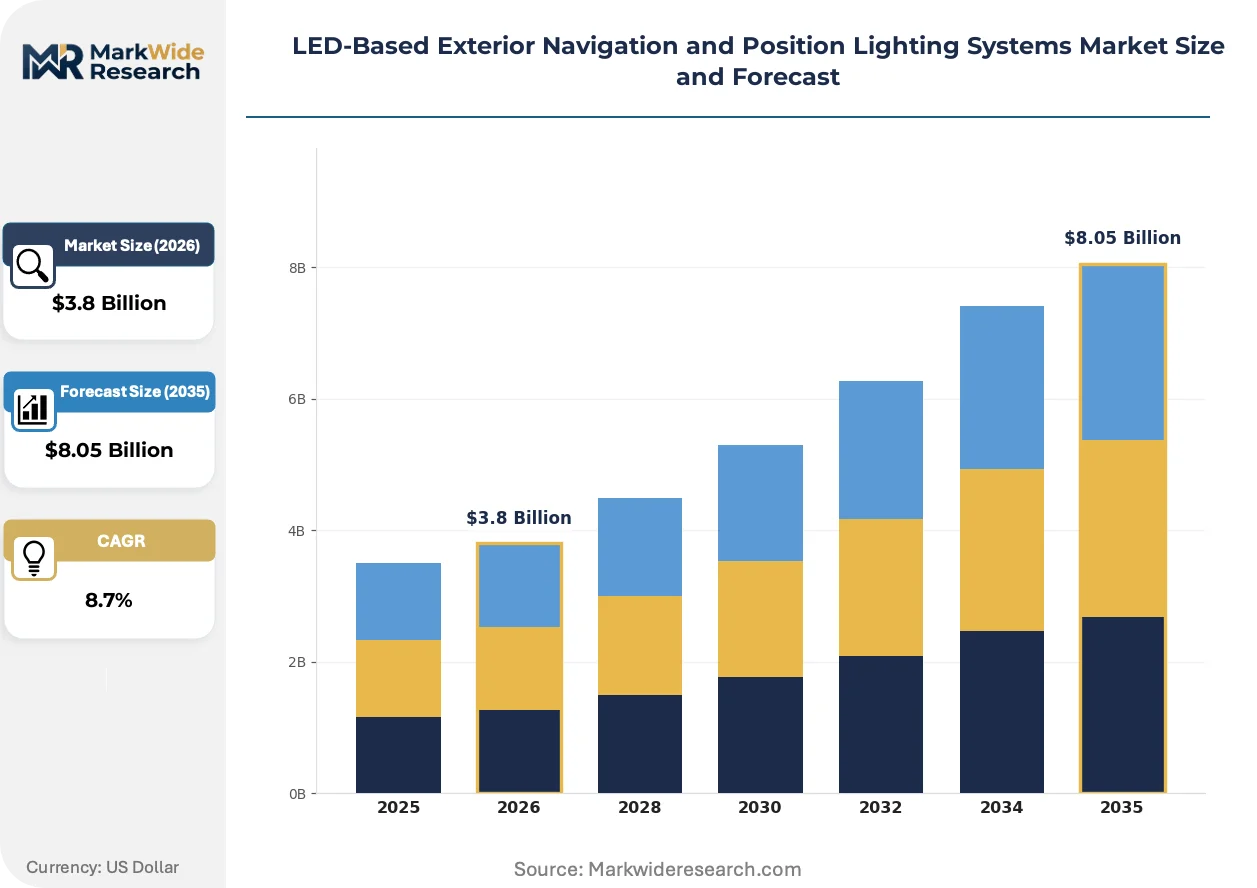
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Anchor Lights, Masthead Lights, Stern Lights, Combination Lights, Floodlights Technology: Surface Mount Device, Chip on Board, High-Power LED, Organic LED, Light Emitting Polymer Application: Commercial Vessels, Naval Ships, Yachts, Fishing Boats, Passenger Ferries End User: Shipbuilders, Marine Retrofitters, Equipment OEMs, Vessel Operators |
| Companies Covered | Astronics Corporation, Collins Aerospace, Safran, Honeywell International, Hella GmbH & Co. KGaA, Diehl Stiftung & Co. KG, Aveo Engineering Group, Oxley Group, Heads Up Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
LED-Based Exterior Navigation and Position Lighting Systems Market Trends and Innovations
Digital twin integration and predictive maintenance protocols are transforming how vessel operators manage navigation lighting assets, compressing fault-response times and extending service intervals.
Chip on Board LED technology is virtualizing thermal management in marine navigation fixtures. Superyacht builders and naval architects specify COB configurations for masthead applications where lumen density and heat dissipation prove critical. The technology is virtualizing traditional discrete LED arrays by consolidating emitters onto single substrates, reducing fixture footprint while improving reliability in corrosive salt-air conditions.
EU F-Gas Regulation restrictions on fluorinated greenhouse gases are accelerating solid-state lighting adoption in European-flagged vessels. Marine equipment suppliers must eliminate gas-discharge lantern technologies from product portfolios to maintain CE marking eligibility. German and Dutch shipyards now specify exclusively LED-based navigation systems to preempt compliance exposure.
Direct procurement from lighting system manufacturers is displacing traditional marine distributor networks. Shipbuilders in South Korea and China negotiate long-term supply agreements that bundle navigation, interior, and emergency lighting into single-source contracts. This channel consolidation concentrates specification authority with naval architects and fleet technical managers rather than aftermarket parts distributors.
LED-Based Exterior Navigation and Position Lighting Systems Market Segmentation
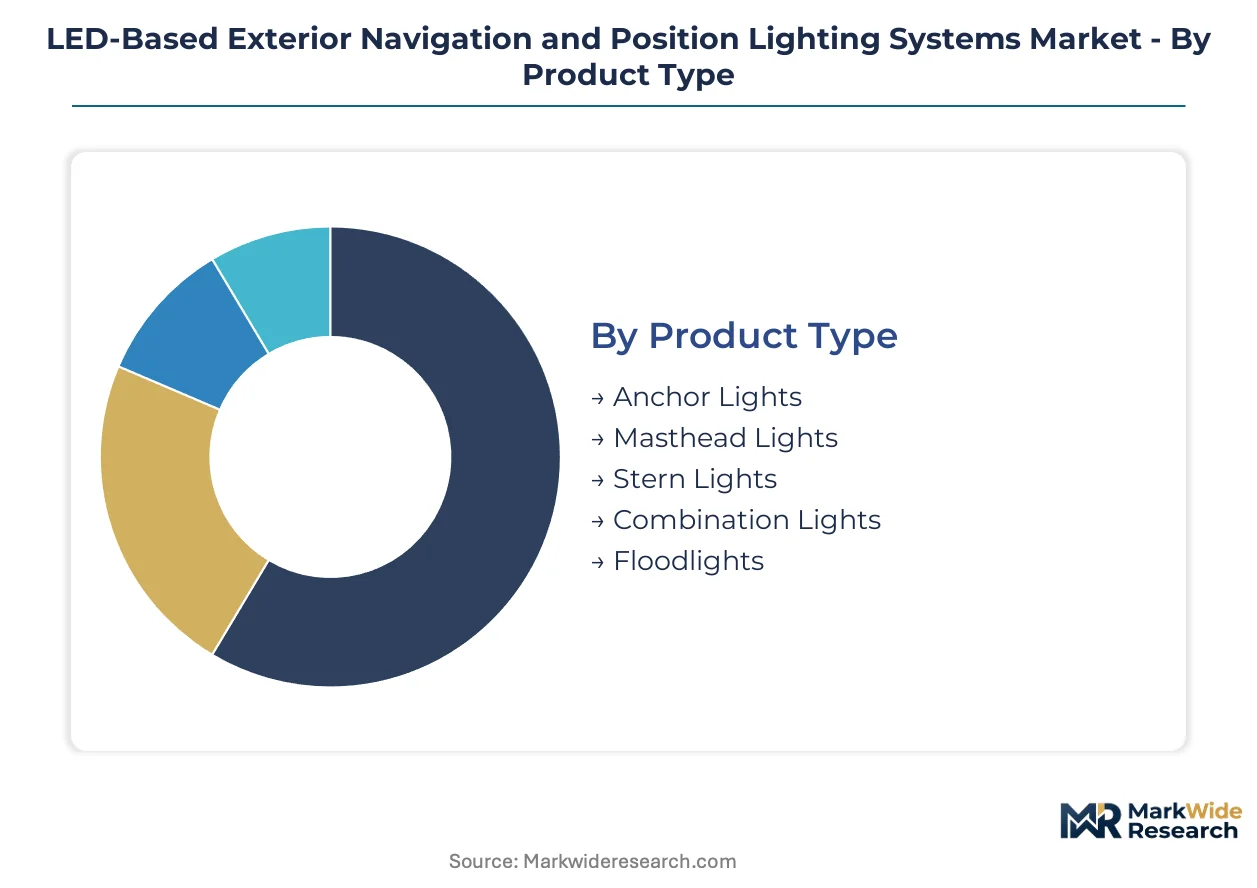
Segmentation in marine navigation lighting reveals how technical specifications, procurement channels, and vessel classifications create distinct commercial territories. Each dimension carries different margin profiles and certification burdens that shape supplier strategy.
Product Type:
Mature masthead configurations dominate fleet retrofit budgets, while emerging combination light designs are compressing installation complexity for newbuild yards.
- Masthead Lights:These fixtures mount at the highest point on a vessel's centerline to display white all-round visibility per COLREGs Rule 21. South Korean shipbuilders specify COB-based masthead arrays for container vessels where thermal management determines service intervals.
- Combination Lights:Integrated units housing multiple lantern functions within single enclosures reduce wiring runs and mast clutter. Chinese yards favor these for bulk carrier newbuilds where crew access for maintenance is limited.
- Anchor Lights:White all-round lanterns with 360-degree arc requirements for vessels at anchor.
- Stern Lights:White fixtures mounted aft showing 135-degree arc visibility astern.
- Floodlights:High-output deck illumination systems for cargo handling and mooring operations.
Masthead lights handle the majority of throughput; combination lights are expanding most quickly on share.
Technology:
Cost tiers separate established packaging formats from emerging emitter architectures with distinct thermal and optical performance tradeoffs.
- Chip on Board:Direct die attachment onto ceramic or metal substrates delivers superior lumen density for masthead applications. Superyacht builders in the Netherlands specify COB modules where fixture miniaturization commands premium positioning.
- Surface Mount Device:Conventional packaged LEDs on printed circuit boards dominate retrofit channels due to legacy fixture compatibility. Marine retrofitters in Germany source SMD arrays to maintain form-factor compliance with existing housings.
- High-Power LED:Discrete emitters exceeding one watt drive deep-water visibility requirements for naval and offshore applications.
- Organic LED:Thin-film electroluminescent technology with limited marine penetration pending humidity sealing validation.
- Light Emitting Polymer:Flexible substrate configurations under evaluation for curved superstructure integration.
Surface Mount Device technology anchors volume shipments; Chip on Board is climbing the fastest on specification authority.
Application:
Customer type stratification separates capital-intensive newbuild programs from maintenance-driven replacement cycles with diverging procurement behaviors.
- Commercial Vessels:Container ships, tankers, and bulk carriers operating under strict flag-state inspection regimes. Vessel operators in Singapore face Port State Control detention risks that accelerate LED upgrade timelines.
- Naval Ships:Military vessels requiring MIL-STD-461 electromagnetic compatibility and shock-hardened construction. NATO procurement offices mandate certified navigation fixtures with encrypted control interfaces.
- Yachts:Superyacht and megayacht segments where aesthetic integration and custom chromaticity drive specification.
- Fishing Boats:Smaller commercial trawlers and longliners with cost-constrained retrofit economics.
- Passenger Ferries:High-occupancy vessels subject to enhanced safety equipment scrutiny by classification societies.
Commercial vessels absorb the dominant share of fixture shipments; naval applications are gaining specification intensity fastest.
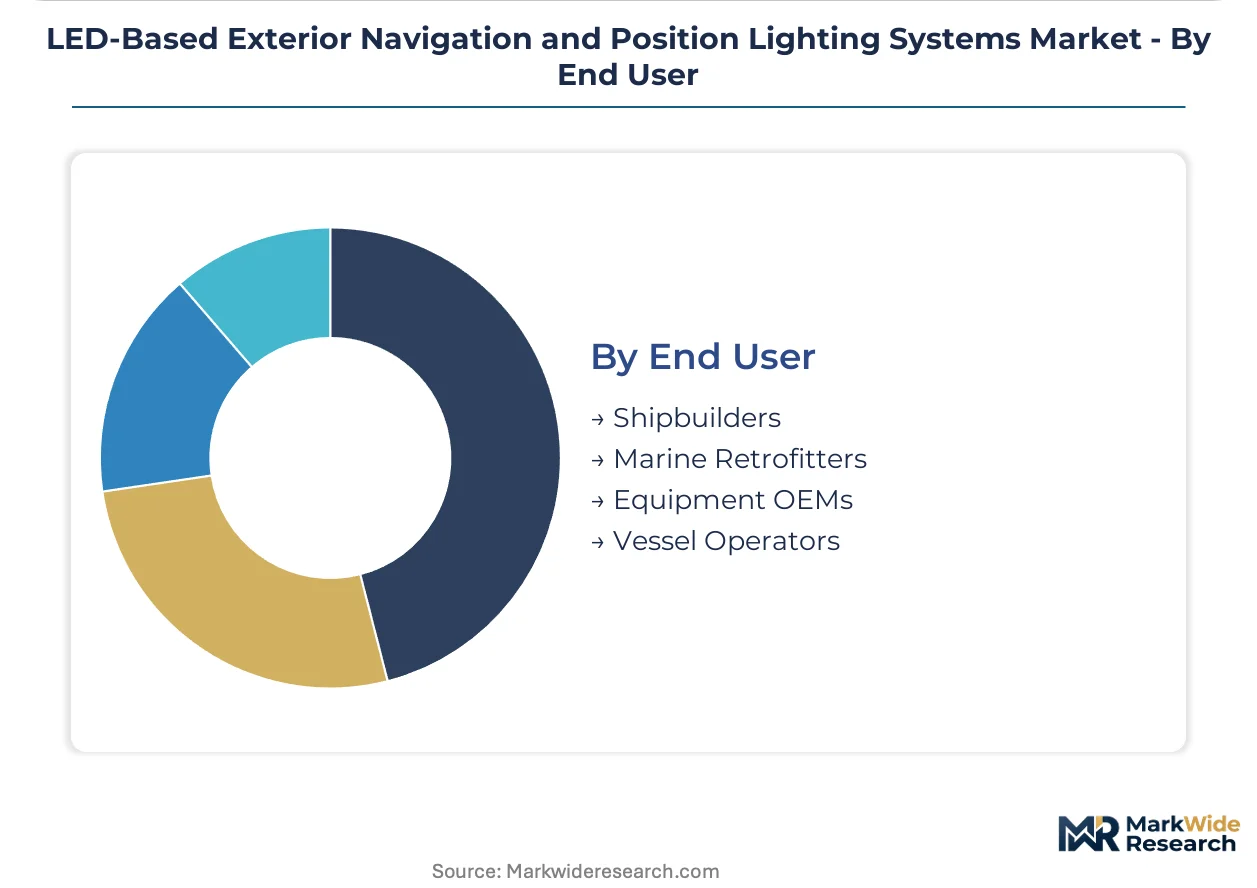
End User:
Supply concentration varies sharply between concentrated OEM-direct channels and fragmented aftermarket distribution.
- Shipbuilders:New construction yards in South Korea and China negotiating multi-year supply agreements that bundle navigation, interior, and emergency lighting.
- Marine Retrofitters:Specialized contractors managing fleet upgrade programs for aging vessels under IMO compliance deadlines.
- Equipment OEMs:Integrated bridge system manufacturers sourcing certified navigation lights as subsystem components.
- Vessel Operators:Fleet technical managers procuring replacement units through distributor networks or direct manufacturer relationships.
Shipbuilders command the largest procurement volumes; marine retrofitters are accelerating fastest on contract velocity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's container throughput underwrites the Netherlands' centrality in European maritime logistics. South Korean shipyards at Busan and Ulsan anchor East Asian newbuild capacity. The US Gulf Coast petrochemical export corridor sustains demand for certified navigation systems on tanker fleets.
United States
Coast Guard detention enforcement at Port State Control inspections accelerates LED retrofit timelines for aging commercial fleets. The US Coast Guard's 33 CFR Part 84 certification framework creates compliance gateways for navigation fixtures entering American-flagged service. Houston-Galveston refineries and export terminals concentrate demand for explosion-proof position lighting on chemical tankers.
South Korea
Hyundai Heavy Industries and Samsung Heavy Industries specify factory-installed COB-based masthead arrays for container vessel newbuilds. The Korean Register of Shipping enforces harmonized IEC 60945 electromagnetic compatibility standards alongside IMO COLREGs mandates. Busan-Ulsan shipbuilding clusters negotiate multi-year supply agreements that bundle navigation, interior, and emergency lighting into consolidated procurement packages.
China
State-owned shipbuilders at Dalian, Shanghai, and Guangzhou drive volume demand for Surface Mount Device retrofits compatible with legacy fixture housings. The China Classification Society implements GB standards for marine electrical equipment that align with IEC environmental testing protocols. Yangtze River Delta yards construct bulk carriers with combination light configurations that reduce wiring runs and mast clutter.
Germany
EU F-Gas Regulation restrictions on fluorinated greenhouse gases eliminate gas-discharge lantern technologies from European-flagged vessel portfolios. Germanischer Lloyd certification requirements preempt compliance exposure for navigation fixture manufacturers. Hamburg and Bremerhaven marine retrofitters source SMD arrays to maintain form-factor compliance with existing masthead enclosures on aging container fleets.
Singapore
Port State Control detention risks at the world's busiest transshipment hub compress replacement cycles for navigation lighting systems. The Maritime and Port Authority of Singapore enforces strict flag-state inspection regimes that penalize non-compliant incandescent installations. Jurong Shipyard and Sembcorp Marine facilities concentrate Southeast Asian retrofit capacity for regional tanker and bulk carrier operators.
LED-Based Exterior Navigation and Position Lighting Systems Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying certified emitters and thermal substrates. The supplier base organizes around three functional layers: avionics-marine platform vendors, dedicated marine lighting manufacturers, and semiconductor packaging houses. Consolidation pressure concentrates at the platform tier where long-term NATO and coast guard supply agreements lock in incumbent positions. Competitive moves center on backward integration into thermal substrate production and geographic expansion through shipbuilder-direct procurement channels.
Among diversified aerospace-platform vendors, Collins Aerospace and Honeywell International occupy positions spanning integrated bridge systems and certified navigation subsystems. Safran anchors European naval retrofit tenders through its MIL-STD product lines. These three represent the platform-integrator archetype that bundles navigation lighting with broader avionics and marine electronics portfolios, securing specification authority through system-level contracts rather than component sales.
| Leading Market Players |
|---|
| Astronics Corporation |
| Collins Aerospace |
| Safran |
| Honeywell International |
| Hella GmbH & Co. KGaA |
| Diehl Stiftung & Co. KG |
| Aveo Engineering Group |
| Oxley Group |
| Heads Up Technologies |
| Others |
Pricing and Supply Chain Analysis
Busan-Ulsan shipbuilding clusters concentrate COB substrate and thermal management component production, translating manufacturing scale into procurement leverage for Korean yards negotiating multi-year navigation lighting bundles. This geographic concentration of emitter packaging capacity feeds downstream pricing power asymmetries between integrated platform vendors and specialized fixture assemblers.
Pricing Analysis
Three-tier pricing structure across MIL-STD certified naval, commercial IEC 60945 compliant, and economy retrofit tiers separates premium thermal substrate specifications from standard SMD configurations. Price differentiation hinges on certification grade—US Coast Guard 33 CFR Part 84 approval commands substantial premiums over uncertified alternatives—and volume scale from OEM-direct shipbuilder contracts. Cost compression in the economy retrofit tier is intensifying because legacy fixture housing compatibility requirements limit supplier switching. Fishing boat operators exhibit highest price sensitivity, while NATO naval procurement offices prioritize electromagnetic compatibility over unit cost.
Supply Chain Analysis
Export control regimes on high-brightness GaN substrates and rare earth phosphor formulations constrain emitter technology flows from US and Japanese suppliers to Chinese fixture assemblers. Manufacturing concentrates in South Korea, China, and Germany, with COB die bonding capacity anchored in Busan and Shenzhen while thermal substrate production draws from Bavarian ceramic foundries. Raw material dependencies span aluminum nitride substrates, silicone encapsulants, and copper heat spreaders. Single-source vulnerability in GaN-on-silicon foundry capacity represents the dominant structural risk. Distribution runs through shipbuilder-direct procurement channels that displace traditional marine distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified thermal engineering talent for salt-air corrosion resistance remains scarce relative to demand from superyacht and naval specification authorities, creating capability bottlenecks that constrain supplier expansion.
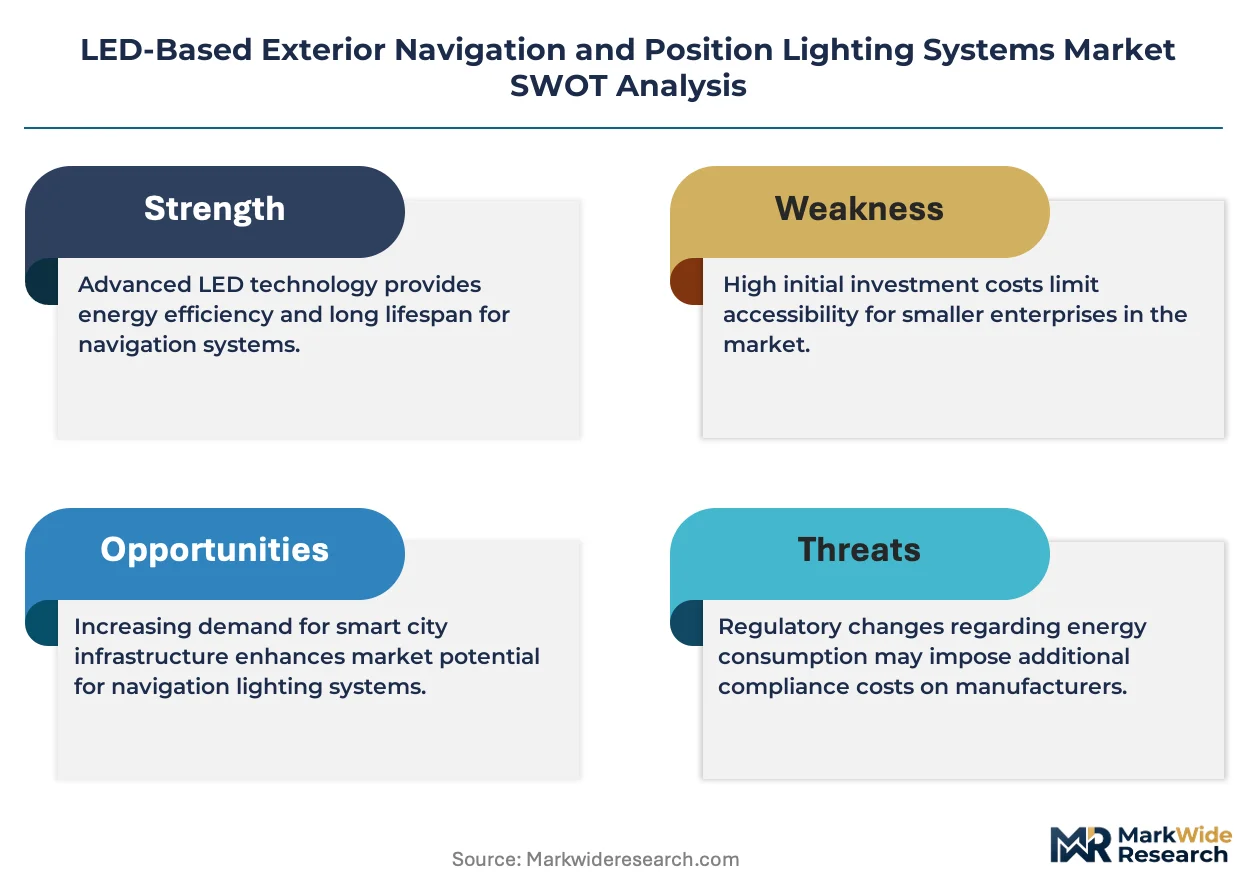
For Market Incumbents: Harden electromagnetic compatibility testing infrastructure against emerging cybersecurity mandates for encrypted navigation fixture control interfaces. Deepen backward integration into ceramic substrate production to defend margin position against GaN foundry cost volatility. Prioritize IEC 60945 pre-certification investments to compress validation cycles for Chinese yard tenders. For New Entrants and Emerging Players: Pursue Indian coastal fleet electrification under the PLI scheme for manufacturing, where domestic trawler and cargo vessel newbuilds lack established supplier relationships. Target marine retrofitters managing IMO COLREGs compliance deadlines for aging European container fleets as the most penetrable channel. Lead with SMD form-factor compatibility and rapid Coast Guard certification turnaround as the go-to-market angle. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among platform-integrator archetypes bundling navigation lighting with integrated bridge systems and long-term NATO supply agreements. Long-term viability over the projection horizon favors suppliers with captive thermal substrate production and MIL-STD product line breadth. Watch for inflection signals in Indian shipyard LED specification rates under PLI scheme acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Thermal Substrates | Captive aluminum nitride ceramic production insulates Collins Aerospace and Safran from GaN foundry pricing volatility. |
| Cybersecurity-Hardened Control Interface Development | Encrypted remote diagnostic capability addresses emerging IMO digitization mandates for connected navigation assets. |
| OEM-Direct Procurement Channel Expansion | Long-term supply agreements with Hyundai Heavy Industries and Samsung Heavy Industries lock out distributor competitors. |
| Indian PLI Scheme Manufacturing Localization | Domestic production eligibility under India's scheme opens state-owned shipyard access for LED navigation system tenders. |
| MIL-STD-461 Electromagnetic Compatibility Pre-Certification | Shock-hardened construction approval accelerates NATO naval retrofit tender participation for European suppliers. |
Research Methodology
A spread of perspectives from naval procurement officers at NATO member defense ministries, fleet technical managers at Singapore and Rotterdam port authorities, shipbuilder specification engineers at Busan and Shanghai yards, and marine retrofit contractors in Hamburg converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation against IEC 60945 test documentation, US Coast Guard 33 CFR Part 84 certification records, and customs trade data for LED marine fixture imports. Bottom-up fixture shipment tallies triangulated against top-down shipyard newbuild orderbook analysis.
Demand-supply balance modeling across the projection horizon segmented by vessel classification, certification tier, technology architecture, and procurement channel shaped volume and value outputs. CAGRs derived from shipbuilder orderbook pipeline analysis and fleet age distribution demographics for retrofit cycle estimation. Specific forecast inputs included IMO COLREGs compliance deadline schedules and East Asian shipbuilding capacity utilization rates.
Macroeconomic conditions sit as an overlay; deviation in semiconductor foundry capex cycles and rare earth material spot prices would shift the trajectory. Forecasts reflect documented assumptions on regulatory harmonization between IMO and emerging national cybersecurity standards. Material shifts in US Coast Guard certification timeline extensions or EU F-Gas Regulation enforcement intensity would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Interior & Exterior
Advanced Vehicle Side Mirror Market
Automotive Interior & Exterior
Global Automotive Interiors Market
Automotive Interior & Exterior
Automotive Structural Steel Market
Automotive Interior & Exterior
Bumper Sticker Market
Automotive Interior & Exterior
Automotive Door Sills Market
Automotive Interior & Exterior
India Automotive Door Seals Market
Automotive Interior & Exterior
Global Smart Tailgate Market
Automotive Interior & Exterior
Japan Automotive Flooring Market
Automotive Interior & Exterior
Automotive Body-In-White Market
Automotive Interior & Exterior
Sun Visor Market
Automotive Interior & Exterior
Automotive Sunroof Market
Automotive Interior & Exterior
Automotive Smart Window Market
Automotive Interior & Exterior
Automotive Electrically Adjustable Outside Rear View Mirror (ORVM) Market
Automotive Interior & Exterior
France Automotive Adaptive Lighting System Market
Automotive Interior & Exterior
Automotive Exterior Trim Parts Market
Automotive Interior & Exterior
Global Light Vehicle (LV) Cabin AC Filters Market