
 Sun Visor Market | 2026-2036
Sun Visor Market Size, Share, and Industry Trends Forecast 2026-2036
Sun Visor Market Analysis
Automotive-grade polycarbonate specification tiers is rotating toward higher impact-resistance and UV-stability thresholds across OEM supply chains. Kasai Kogyo Co., Ltd. leverages its vertical integration into resin compounding to control material consistency for Japanese automakers. Yanfeng Automotive Interior Systems anchors its position through manufacturing scale across fourteen countries. Magna International Inc. differentiates via synchronized engineering with North American and European vehicle platforms.
A sun visor is a cabin-mounted glare-shielding device, typically comprising a rigid substrate core, fabric or vinyl surface layer, and pivoting attachment hardware, engineered to block solar radiation and oncoming headlight beams from the driver's field of vision. Retractable sun visor variants occupy the dominant volume position due to cost-efficient mechanical simplicity and broad vehicle-class compatibility, while electric sun visor segments command concentrated margin pools in premium and luxury vehicle configurations where integrated electrochromic dimming and sensor-activated deployment justify higher price positioning.
NHTSA Federal Motor Vehicle Safety Standard 302 governs flammability resistance for interior materials including visor substrates, while ECE R118 applies to European type approval for burning behavior and melting characteristics. REACH substance restrictions and California Proposition 65 compliance requirements are forcing material substitutions away from certain phthalate plasticizers and heavy-metal pigments in vinyl-coated variants. Stakeholders must monitor evolving cabin-safety sensor integration standards that could mandate redesigned visor geometries to accommodate roof-mounted LiDAR and camera modules without compromising glare-blocking functionality.
Market Dynamics
Automotive interior consolidation is compressing supplier margins while NHTSA glare-reduction standards and ECE R43 safety glass regulations force simultaneous material upgrades across polycarbonate substrate and surface coating tiers.
Growth Catalysts
- NHTSA Federal Motor Vehicle Safety Standard 302:Flammability mandates for interior materials are accelerating substrate material upgrades across North American OEM supply chains.
- Electrochromic dimming integration:Sensor-activated electric sun visor configurations are pulling premium vehicle manufacturers toward higher-margin product portfolios.
- German premium vehicle production clusters:Concentrated OEM demand in Stuttgart and Munich is intensifying specification tightening for cabin comfort components.
Market Restraints
- Polycarbonate resin price volatility:Petrochemical feedstock fluctuations are squeezing margin predictability for rigid substrate manufacturers.
- Japanese supplier concentration:Captive resin compounding capabilities at dominant tier-1 suppliers create barriers for new entrants lacking backward integration.
- REACH substance restrictions:Phthalate plasticizer bans in vinyl-coated variants are forcing costly formulation redesigns without immediate price recovery mechanisms.
Strategic Opportunities
- South Korean EV platform expansion:Hyundai-Kia's dedicated electric architectures present white space for integrated electrochromic visor modules.
- LiDAR accommodation geometries:Redesigned visor form factors enabling roof-mounted sensor integration without glare-blocking compromise represent untapped specification tiers.
- California Proposition 65 compliance:Heavy-metal pigment restrictions are creating first-mover advantage for pigment-substitution specialists serving West Coast OEM final assembly.
Industry Challenges
- Multi-standard certification timelines:Simultaneous NHTSA, ECE R118, and REACH compliance is extending product validation cycles beyond traditional program gates.
- Electro-mechanical integration complexity:Synchronizing electrochromic deployment algorithms with cabin sensor networks requires cross-functional engineering capabilities scarce among legacy mechanical visor suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sun Visor Market |
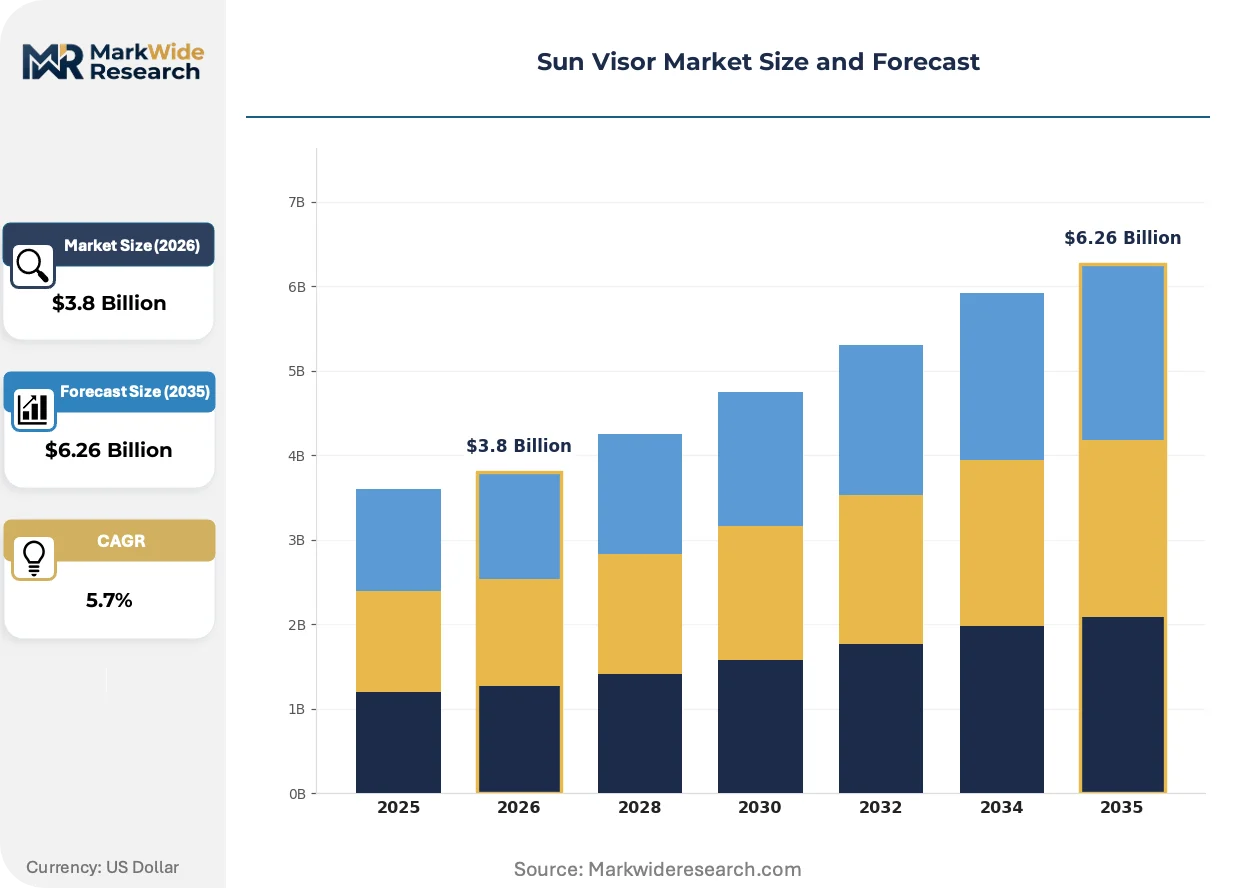
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed Sun Visor, Retractable Sun Visor, Electric Sun Visor, Custom Sun Visor Material: Fabric, Vinyl, Polycarbonate, Leather Vehicle Type: Passenger Cars, SUVs, Trucks, Motorhomes End User: Automakers, Aftermarket Providers, Retailers, Fleet Operators |
| Companies Covered | Kasai Kogyo Co., Ltd., Yanfeng Automotive Interior Systems, Magna International Inc., Atlas Holdings LLC, IAC Group, Grupo Antolin, Continental AG, Hayashi Telempu Corporation, Toyota Boshoku Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sun Visor Market Emerging Trajectories
Material science advances and regulatory chemistry restrictions are actively restructuring competitive positioning across substrate, coating, and attachment hardware tiers. Three developments warrant particular attention.
Electrochromic glass technology is displacing conventional mechanical flip-down configurations in premium vehicle segments. German and Japanese luxury manufacturers are adopting sensor-activated dimming visors at accelerating specification rates. This displacement is compressing addressable volume for pure mechanical suppliers while expanding margin pools for integrated electro-optic system providers.
REACH substance restrictions are forcing material substitutions across European supply chains. ECHA's expanding candidate list for phthalate plasticizers and heavy-metal pigments is compelling vinyl surface layer reformulations. Tier-1 suppliers serving BMW, Mercedes-Benz, and Volkswagen Group platforms are responding with accelerated pigment-substitution R&D programs.
Fleet procurement centralization is consolidating specification authority at OEM group engineering centers. Traditional regional purchasing autonomy for cabin trim components is yielding to global commodity councils. This concentration is most visible at Stellantis and Renault-Nissan-Mitsubishi Alliance headquarters, where visor specifications now harmonize across multiple brand portfolios.
Sun Visor Market Segmentation
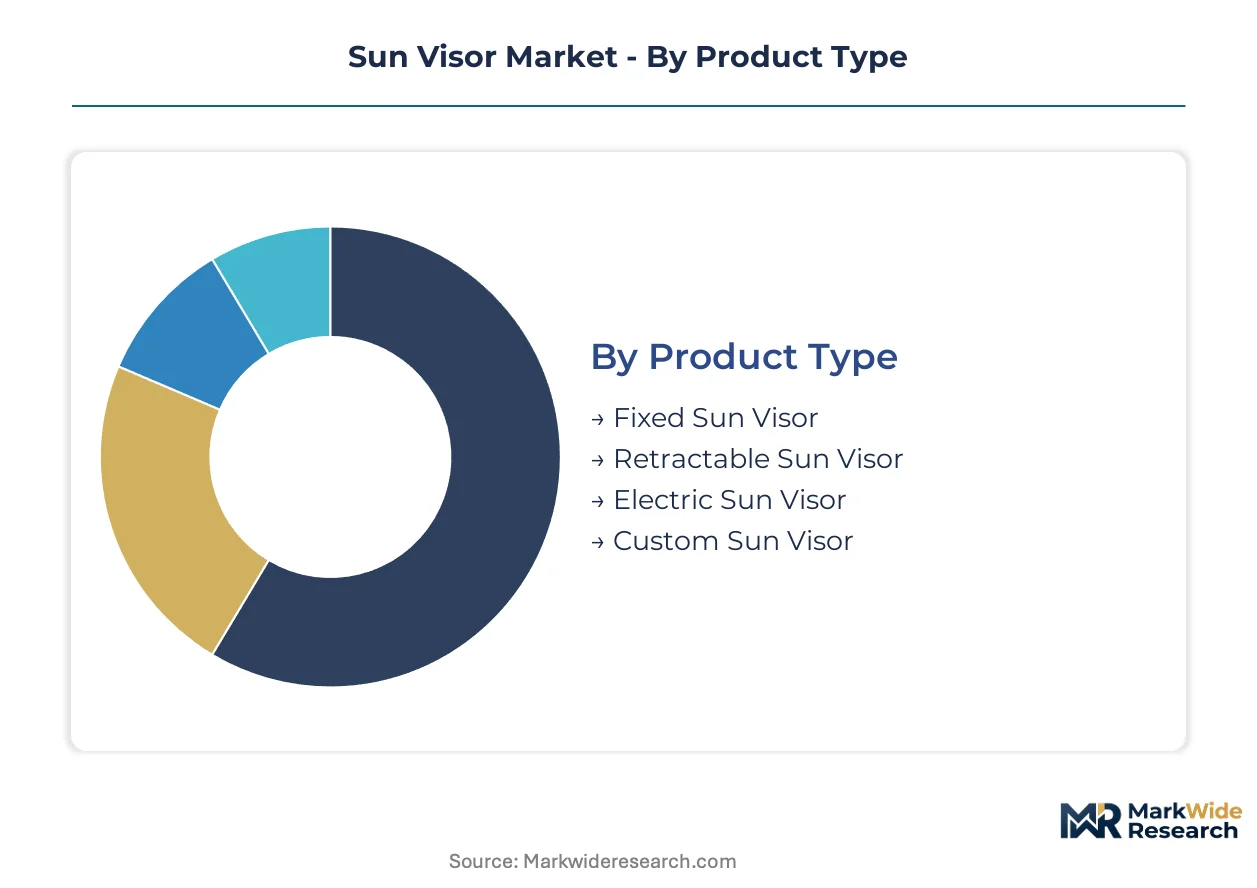
Sun visor segmentation reveals divergent margin structures across mechanical simplicity and electrochromic complexity. Product type and material tiers separate commodity volume from premium value capture, while vehicle and end-user channels dictate specification authority and procurement leverage.
Product Type:
Margin pools concentrate in sensor-activated configurations where electrochromic technology commands price premiums, while mechanical variants compete on manufacturing scale.
- Fixed Sun Visor:Rigid substrate core with permanent mounting geometry offers lowest unit cost and broadest vehicle-class compatibility. Demand concentrates in emerging-market entry vehicle platforms where cabin trim budgets face strict containment.
- Retractable Sun Visor:Pivoting armature with sliding extension mechanism balances functionality against mechanical simplicity. German and Japanese mass-market manufacturers specify this configuration most heavily, prioritizing reliability metrics over feature differentiation.
- Electric Sun Visor:Electrochromic glass with automated dimming algorithms integrates with cabin sensor networks. South Korean EV architectures and German luxury platforms are driving specification rates upward for this highest-margin tier.
- Custom Sun Visor:Bespoke geometries and surface treatments for specialty vehicle builders and aftermarket personalization segments.
The dominant share belongs to Retractable Sun Visor, while Electric Sun Visor is closing the gap fastest.
Material:
Specification authority tilts toward substrates meeting flammability and UV-stability thresholds, with surface coatings facing regulatory chemistry constraints.
- Polycarbonate:Automotive-grade specification tiers demand higher impact-resistance and UV-stability thresholds across OEM supply chains. Japanese and German manufacturers are tightening incoming material certification requirements most aggressively.
- Vinyl:Phthalate plasticizer formulations face REACH substance restrictions and California Proposition 65 compliance pressures, forcing costly reformulation programs without immediate price recovery mechanisms.
- Fabric:Woven textile surface layers with foam-backed substrates serve economy vehicle segments and aftermarket replacement channels.
- Leather:Premium hide or synthetic leather surfaces align with luxury cabin trim specifications at BMW, Mercedes-Benz, and Audi platforms.
Polycarbonate holds the volume lead, though vinyl reformulation costs are compressing its margin advantage.
Vehicle Type:
Platform architecture determines visor geometry constraints and feature integration depth, with premium segments enabling electrochromic adoption.
- Passenger Cars:Sedan and hatchback form factors with standardized windshield angles permit modular visor designs across multiple nameplates. Stuttgart and Munich engineering centers specify the tightest cabin comfort tolerances.
- SUVs:Elevated seating positions and larger glass areas increase glare exposure, driving demand for extended-coverage retractable configurations.
- Trucks:Commercial duty cycles prioritize durability and cost containment over feature sophistication.
- Motorhomes:Specialty vehicle builders require custom geometries for expansive cockpit glass areas.
Passenger Cars generate the highest absolute volume, yet SUVs are expanding most quickly as platform mix shifts.
End User:
Procurement concentration at OEM group engineering centers is compressing supplier margins while consolidating specification authority.
- Automakers:Stellantis and Renault-Nissan-Mitsubishi Alliance headquarters now harmonize visor specifications across multiple brand portfolios, eliminating regional purchasing autonomy.
- Aftermarket Providers:Independent distributors and repair networks serve vehicle aging populations with replacement and upgrade demand.
- Retailers:Consumer-direct channels for accessory and personalization products face price transparency pressures from e-commerce platforms.
- Fleet Operators:Centralized procurement for commercial vehicle pools emphasizes total cost of ownership and warranty coverage terms.
Automakers command the dominant procurement share, while Fleet Operators are gaining specification influence through volume consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German visor component exports supply premium vehicle assembly lines across Stuttgart and Munich, while Japanese manufacturers ship electrochromic modules to South Korean EV platforms.
United States
NHTSA Federal Motor Vehicle Safety Standard 302 mandates flammability resistance for interior substrates, forcing material upgrades across Detroit Three supply chains. Domestic OEMs source polycarbonate cores from compounding facilities in Michigan and Ohio. The Southeast automotive corridor spanning Tennessee, Alabama, and South Carolina attracts foreign-owned assembly plants requiring localized visor supply.
Germany
ECE R118 type approval governs burning behavior and melting characteristics for cabin trim components entering European markets. Stuttgart and Munich engineering centers specify the tightest cabin comfort tolerances for Mercedes-Benz, BMW, and Audi nameplates. Suppliers in Baden-Württemberg and Bavaria concentrate electrochromic R&D investment to serve premium platform demand.
Japan
METI industrial standards coordinate with JIS specifications for automotive interior durability and UV stability. Kasai Kogyo and Toyota Boshoku anchor production clusters in Aichi Prefecture's Nagoya industrial zone. Captive resin compounding capabilities at dominant tier-1 suppliers create barriers for new entrants lacking backward integration into material supply.
South Korea
MFDS chemical safety oversight intersects with Ministry of Trade, Industry and Energy programs supporting EV component localization. Hyundai-Kia's dedicated electric architectures in Gyeonggi Province present specification opportunities for integrated electrochromic visor modules. Busan-Ulsan manufacturing complexes serve export-oriented assembly for North American and European markets.
China
GB standards for automotive interior materials establish baseline flammability and emissions requirements for domestic and export production. Yangtze River Delta and Pearl River Delta clusters concentrate injection molding capacity for retractable visor mechanical components. Yanfeng Automotive Interior Systems leverages fourteen-country manufacturing scale to serve joint-venture OEMs operating within China.
Sun Visor Market Vendor Landscape
Listed leaders compete with private specialists across capital access and strategic flexibility dimensions, creating a tiered structure where scale advantages clash with niche customization capabilities. The vendor base separates into three strategic archetypes: integrated resin compounders controlling material consistency, multi-national fabricators leveraging geographic footprint, and electro-optic specialists capturing premium-tier margins. Dominant competitive moves include synchronized engineering partnerships with vehicle platform teams and backward integration into polycarbonate resin supply.
Within the integrated compounder tier, Kasai Kogyo Co., Ltd. exemplifies captive control over material inputs for Japanese automaker supply chains. Yanfeng Automotive Interior Systems anchors the geographic-scale archetype through its fourteen-country manufacturing presence. Magna International Inc. occupies a position bridging North American and European platform engineering requirements.
| Leading Market Players |
|---|
| Kasai Kogyo Co., Ltd. |
| Yanfeng Automotive Interior Systems |
| Magna International Inc. |
| Atlas Holdings LLC |
| IAC Group |
| Grupo Antolin |
| Continental AG |
| Hayashi Telempu Corporation |
| Toyota Boshoku Corporation |
| Others |
Supply Flow & Price Mechanics
Phthalate plasticizer substitution in vinyl surface coatings is redrawing raw material sourcing maps and compressing margin recovery timelines for European suppliers. REACH substance restrictions are forcing simultaneous reformulation investments across coating tiers while polycarbonate resin volatility from petrochemical feedstock fluctuations constrains pricing predictability for rigid substrate manufacturers serving OEM procurement councils.
Pricing Analysis
Mechanical flip-down configurations, electrochromic glass modules, and sensor-integrated smart visors occupy distinct pricing strata with widening technology-generation gaps. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and volume scale leverage at Stellantis and Renault-Nissan-Mitsubishi Alliance procurement centers. Price erosion runs through mechanical visor tiers as fleet procurement centralization intensifies buyer concentration. Aftermarket distributors exhibit highest price sensitivity, while German luxury OEMs absorb premium positioning for electrochromic integration.
Supply Chain Analysis
Inventory buffers for polycarbonate resin and electrochromic glass substrates have tightened as just-in-time coordination with vehicle platform launch schedules compresses lead-time flexibility. Manufacturing gravity centers on Germany, Japan, and South Korea for premium component assembly, with China anchoring mechanical visor injection molding capacity. Raw material flows draw from Saudi Arabian petrochemical feedstocks, Belgian polycarbonate compounding facilities, and Japanese electrochromic glass specialists. Single-source vulnerability concentrates in captive resin compounding capabilities at Kasai Kogyo and Toyota Boshoku. Distribution runs through Tier 1 supplier direct-to-OEM engineering partnerships rather than spot-market channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cross-functional engineering capabilities spanning mechanical hardware, electro-optic systems, and cabin sensor network integration represent the scarcest asset class in this market, separating consolidators from commodity suppliers.
For Market Incumbents: Compound defensive positioning through backward integration into polycarbonate resin supply and synchronized engineering partnerships with Hyundai-Kia EV platform teams. Electrochromic module specialists threaten margin capture in premium tiers. Certification investment in simultaneous NHTSA, ECE R118, and REACH compliance creates switching-cost barriers against emerging Asian competitors. For New Entrants and Emerging Players: Differentiate on LiDAR-accommodation visor geometries serving roof-mounted sensor integration requirements at German and South Korean OEMs. South Korean EV architectures present the most penetrable white space given localized specification authority at Gyeonggi Province engineering centers. California Proposition 65 compliance specialization offers a regulatory-arbitrage go-to-market angle for West Coast OEM supply. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed automotive interior specialists lacking electrochromic R&D depth. Five-to-ten-year viability hinges on successful technology transition from mechanical to electro-optic product portfolios. Electrochromic patent filing velocity at target firms signals inflection timing for premium-tier margin capture.| Strategic Initiative | Industry Significance |
|---|---|
| Electrochromic R&D Partnership | Aligns Tier 1 suppliers with Mercedes-Benz and BMW sensor-network roadmaps. |
| Backward Integration into Resin Compounding | Mirrors Kasai Kogyo's captive supply model for Japanese OEM consistency requirements. |
| LiDAR-Accommodation Geometry Development | Captures specification authority at Stuttgart engineering centers for next-platform designs. |
| REACH-Compliant Formulation Investment | Secures BMW and Volkswagen Group qualification ahead of phthalate deadline tightening. |
| South Korean EV Platform Localization | Positions suppliers for Hyundai-Kia dedicated architecture volume ramp. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with OEM platform engineers, Tier 1 supplier procurement directors, and aftermarket distribution channel managers; and secondary validation against vehicle production databases, IHS Markit registration data, NHTSA safety standard filings, and ECHA substance restriction updates. Bottom-up modeling of content-per-vehicle metrics triangulated with top-down market sizing across product type, material tier, vehicle class, and end-user channel segmentation.
Across the analysis window, forecasts incorporate vehicle platform launch schedules, propulsion architecture mix shifts, and regulatory compliance timeline acceleration. Segmentation dimensions span product complexity tier, substrate material specification, OEM premium-mass-market positioning, and regional production cluster concentration. CAGRs derive from unit volume trajectory modeling and average selling price evolution assumptions tied to electrochromic penetration rates and mechanical visor commoditization curves.
The analysis sits within stated boundaries; outcomes outside sustained German and South Korean premium vehicle production levels or accelerated REACH substance restriction enforcement would require recalibration. Forecasts reflect documented assumptions regarding polycarbonate resin price stability and electrochromic glass yield-rate improvements. Supply chain disruption from petrochemical feedstock volatility or single-source component concentration represent revision triggers. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Interior & Exterior
Automotive Climate Control Market
Automotive Interior & Exterior
Automotive Steering Wheel Covers Market
Automotive Interior & Exterior
Automotive Outside Rearview Mirrors (ORVM) Market
Automotive Interior & Exterior
Automotive Solar Sunroof Market
Automotive Interior & Exterior
Auto Dimming Mirror Market
Automotive Interior & Exterior
Automotive Ventilated Seats Market
Automotive Interior & Exterior
Automotive Backlight Moldings Market
Automotive Interior & Exterior
Rear-View Mirror Market
Automotive Interior & Exterior
Automotive Door Frame Market
Automotive Interior & Exterior
Automotive Front Windshield Market
Automotive Interior & Exterior
Automotive Flock Market
Automotive Interior & Exterior
Global Smart Tailgate Market
Automotive Interior & Exterior
Automotive Glove Compartment Market
Automotive Interior & Exterior
Automotive Grab Handle Market
Automotive Interior & Exterior
Automotive Glove Box Market
Automotive Interior & Exterior
Global Automotive Anti Vibration Mounting Market