
 Automotive Automatic Liftgate Market | 2026-2036
Automotive Automatic Liftgate Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Automatic Liftgate Market Analysis
Chinese powertrain component manufacturing is broadening its automatic liftgate supply footprint. Johnson Electric leverages its motor expertise to anchor electromechanical actuator production across Asia-Pacific assembly plants. Magna International Inc. sustains North American market presence through integrated module design for Detroit Three OEMs. Bosch competes on smart sensor fusion, combining capacitive foot-activation with radar-based obstacle detection.
An automotive automatic liftgate is a motorized rear cargo access system employing electromechanical actuators, torque rods, and control modules to enable hands-free or button-activated opening and closing, typically operating at 12V with load capacities exceeding 100 kg for utility vehicles. Power liftgate configurations dominate premium vehicle lines, while smart sensor technology represents the fastest-expanding segment as capacitive and radar-based activation replace physical contact switches. OEM channel supply anchors volume, though aftermarket providers occupy a growing niche as vehicle aging populations in developed markets seek retrofit solutions.
NHTSA's Federal Motor Vehicle Safety Standards govern anti-entrapment and pinch-force thresholds in the United States, while ECE R21 and ECE R94 shape European structural integrity and occupant protection requirements for rear closure systems. China's MIIT enforces GB standards for electromagnetic compatibility that constrain control module architecture for domestic and export-bound liftgate assemblies. Stakeholders must monitor evolving cybersecurity mandates for connected vehicle access systems as over-the-air update capabilities become standard.
Market Dynamics
Electromechanical actuator miniaturization is compressing module footprints while stricter pedestrian safety mandates force integration of multi-sensor obstacle detection into every liftgate assembly.
Growth Catalysts
- NHTSA Anti-Entrapment Standards:Federal pinch-force thresholds mandate torque-limiting algorithms and capacitive edge sensors, forcing OEM refresh cycles across Detroit production lines.
- Hands-Free Activation:Capacitive foot-motion recognition eliminates physical contact, driving replacement of button-actuated systems in luxury SUV configurations.
- Shanghai Premium Cluster:Domestic EV manufacturers anchor electromechanical module sourcing within the Yangtze River Delta, reducing logistics costs for export-bound assemblies.
Market Restraints
- Rare Earth Magnet Volatility:Neodymium price swings destabilize permanent magnet motor costs, squeezing margins for mid-tier actuator suppliers.
- Control Module Concentration:Semiconductor fabrication for 12V ECUs concentrates in Taiwan and South Korea, exposing supply chains to single-point disruption.
- Steel Torque Rod Substitution:Carbon fiber-reinforced polymer struts threaten conventional stamped steel architectures in weight-sensitive EV platforms.
Strategic Opportunities
- India Compact SUV Penetration:Sub-4-meter utility vehicle segments remain liftgate-naive, offering first-mover advantage for localized electromechanical kit suppliers.
- EU Cybersecurity Mandates:UN R155 vehicle type approval creates certified-module demand for connected liftgate systems with over-the-air update capability.
- Radar-Capacitive Fusion:Multi-modal sensor convergence enables gesture recognition through winter footwear, differentiating premium tier offerings.
Industry Challenges
- Embedded Software Talent Scarcity:Functional safety engineers versed in ISO 26262 ASIL-B requirements command premium compensation, constraining tier-two supplier scaling.
- Homologation Timeline Compression:Parallel validation across NHTSA, ECE R21, and MIIT GB standards extends development cycles for multi-market liftgate platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Automatic Liftgate Market |
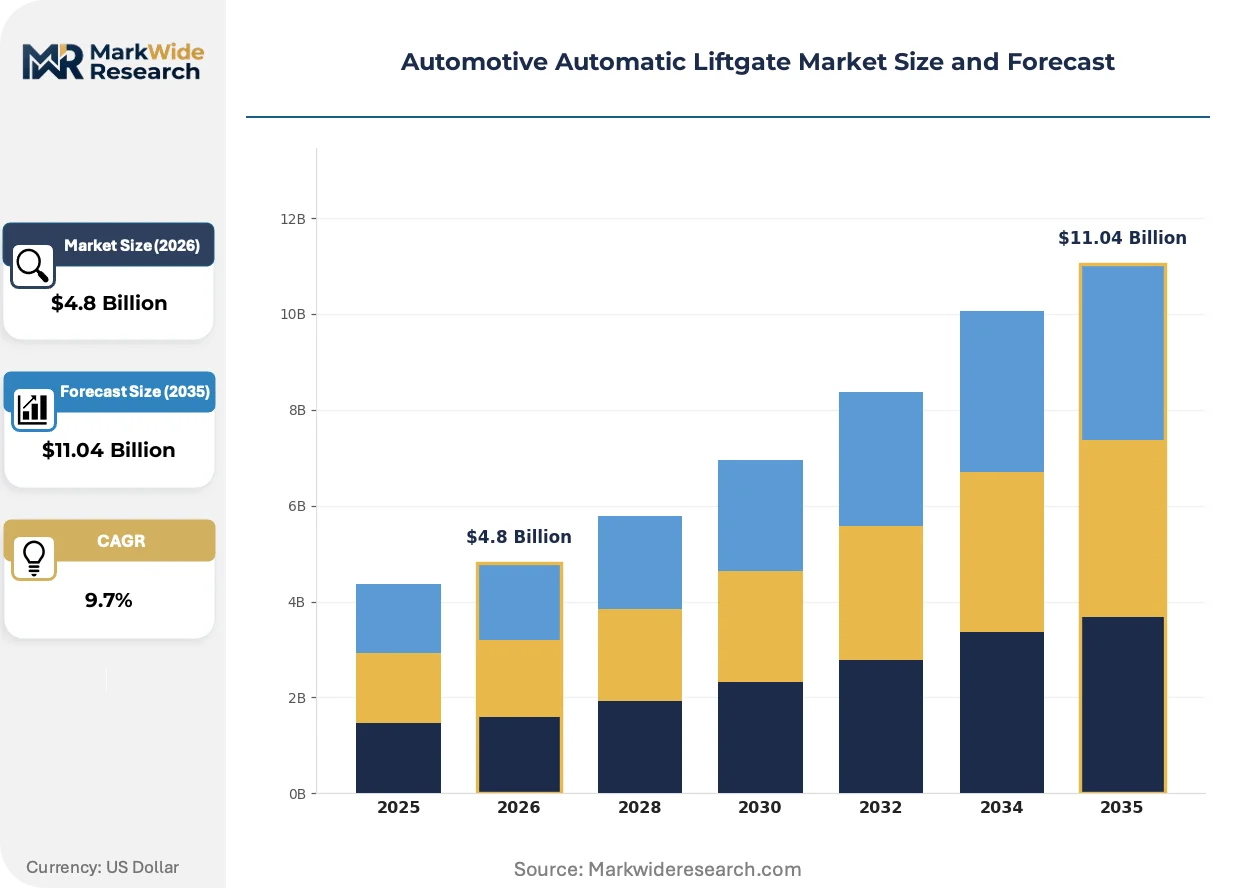
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $11.04 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Traditional Liftgate, Power Liftgate, Tailgate, Hatchback Technology: Electromechanical, Hydraulic, Pneumatic, Smart Sensor End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers Distribution Channel: Online Retail, Dealerships, Specialty Stores, Distributors |
| Companies Covered | Johnson Electric, Aisin Seiki, Magna International Inc., Brose Fahrzeugteile, Huf Hülsbeck & Fürst, Bosch, Valeo, Kiekert AG, Denso Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Automatic Liftgate Market Emerging Trajectories
Smart sensor fusion is replacing discrete mechanical switches, while modular electromechanical architectures enable platform sharing across vehicle segments previously siloed by price tier.
Electromechanical actuation is electrifying rear cargo access by integrating brushless DC motors with planetary gear reduction. Luxury EV manufacturers adopt these compact torque-dense units for hands-free operation. The technology is electrifying supplier margins by collapsing the distinction between premium and mass-market liftgate performance specifications.
REACH substance restrictions on hexavalent chromium plating are forcing conversion to zinc-nickel coating for torque rod corrosion protection. European stamping suppliers absorb capital costs for electrolytic line conversion. Hardware destined for Stuttgart and Wolfsburg assembly plants now carries dual-certified surface treatment documentation.
Fleet procurement of retrofit liftgate kits is fragmenting traditional OEM-captive distribution. Independent installers in Germany and the United States now source electromechanical modules through automotive e-commerce platforms. This channel disintermediation is most pronounced in markets with aging SUV populations seeking hands-free convenience upgrades.
Automotive Automatic Liftgate Market Segmentation
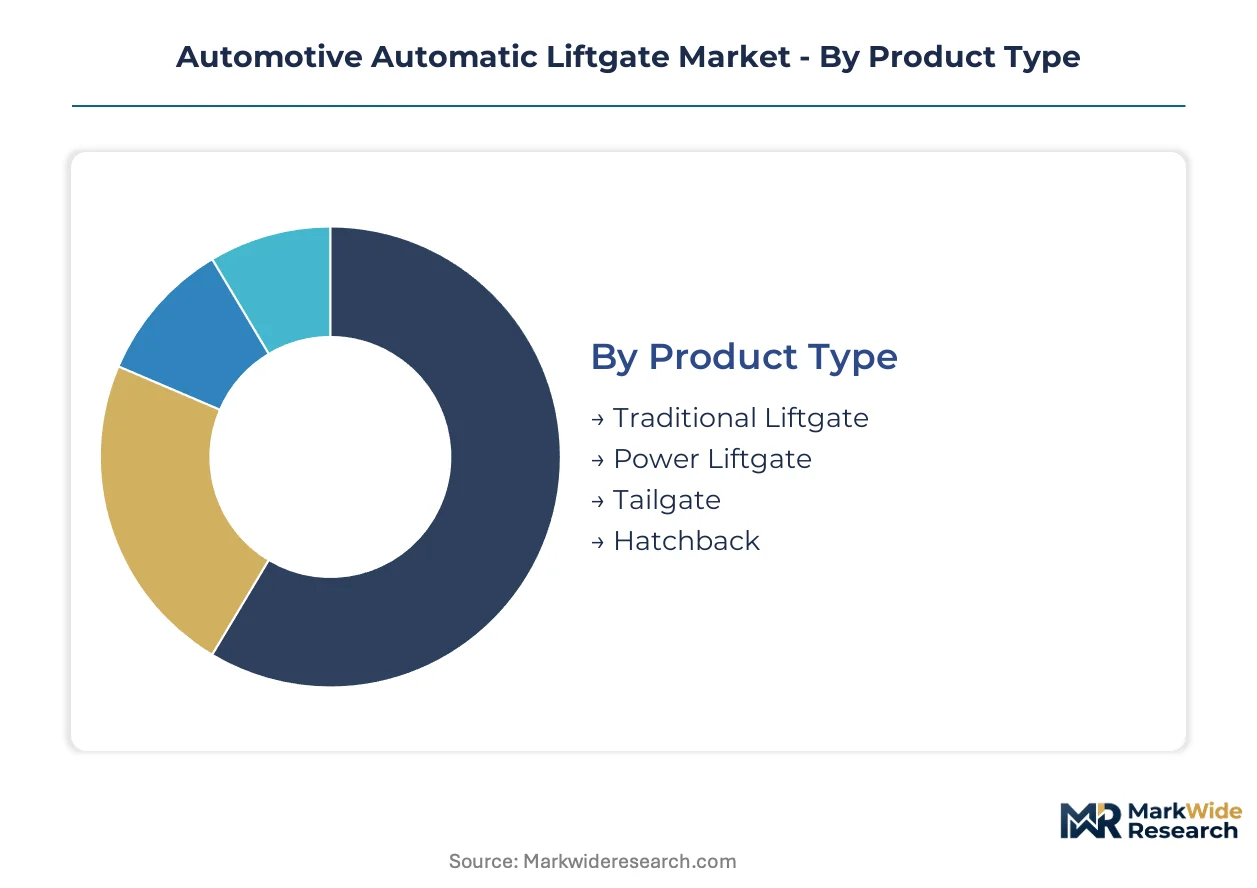
Automatic liftgate purchasing decisions cascade through four distinct lenses: product architecture defines functional capability, technology selection determines activation modality, end-user category dictates integration depth, and channel choice shapes service attachment rates. Understanding how these dimensions intersect reveals where margin pools concentrate and which configurations command price premiums.
Product Type:
Vehicle platform architecture and cargo access requirements drive product selection, with utility-oriented designs commanding higher actuator specifications than passenger-focused configurations.
- Traditional Liftgate:Manually operated rear closures with minimal electromechanical content, typically found in entry-level compact vehicles where cost containment overrides convenience features. Demand concentrates in emerging markets where manual operation remains acceptable and supplier margins compress under intense localization pressure.
- Power Liftgate:Motorized systems employing brushless DC actuators with integrated control modules, now standard equipment in mid-size SUVs and crossover vehicles across premium vehicle assembly plants in Detroit, Stuttgart, and Shanghai. OEMs specify these units for their torque-limiting algorithms and obstacle detection integration.
- Tailgate:Horizontal-swing cargo access systems predominant in pickup trucks and commercial utility vehicles, requiring specialized hinge mechanisms and higher load-bearing electromechanical actuators. North American full-size truck platforms anchor volume for this segment.
- Hatchback:Upward-swinging rear closures with compact actuator footprints suited to smaller vehicle footprints, experiencing technology migration as capacitive foot-activation filters down from luxury configurations.
Volume sits with Power Liftgate; growth tilts toward Smart Sensor-enabled variants across all product architectures.
Technology:
Actuation mechanism selection determines system weight, response latency, and integration complexity with vehicle electrical architectures.
- Electromechanical:Brushless DC motor systems with planetary gear reduction dominate current production, offering compact packaging and precise position control. Shanghai-based EV manufacturers specify these for their 12V electrical compatibility and over-the-air update readiness.
- Hydraulic:Fluid-power actuation persists in heavy-duty commercial applications and legacy platforms where high force output justifies system weight and maintenance burden. European commercial vehicle assemblers in Wolfsburg and Munich retain these for load-rated cargo access.
- Pneumatic:Compressed-air systems occupy niche applications in industrial vehicle conversions and specialty equipment where shop air infrastructure exists. Aftermarket retrofit providers in Germany source these for fleet conversion projects.
- Smart Sensor:Multi-modal activation combining capacitive foot-motion recognition with radar-based obstacle detection, climbing the fastest as NHTSA anti-entrapment mandates and consumer convenience expectations converge. Bosch and Continental compete on fusion algorithm sophistication for this expanding tier.
Electromechanical systems capture current volume leadership; Smart Sensor configurations gain share fastest through premium SUV penetration.
End User:
Integration depth and specification authority vary sharply across the value chain, with captive supply relationships constraining independent supplier access.
- OEMs:Vehicle manufacturers specifying complete liftgate modules for new platform development, controlling design authority and supplier selection through long-term program contracts. Detroit Three automakers maintain dedicated engineering teams for rear closure system integration.
- Tier-1 Suppliers:System integrators like Magna International and Johnson Electric managing electromechanical module assembly and validation against OEM performance specifications. These suppliers absorb homologation burden across NHTSA, ECE R21, and MIIT GB standards.
- Aftermarket Providers:Independent distributors and installers sourcing retrofit kits for aging vehicle populations, with German and United States channels experiencing fastest expansion through automotive e-commerce platforms.
- Vehicle Assemblers:Contract manufacturing operations and joint venture production facilities executing build-to-print liftgate installation under OEM technical direction, prevalent in China domestic brand production.
Tier-1 Suppliers anchor production volume; Aftermarket Providers expand most quickly as vehicle parc ages in developed markets.
Distribution Channel:
Channel selection determines customer acquisition cost, technical support obligation, and warranty exposure for liftgate system providers.
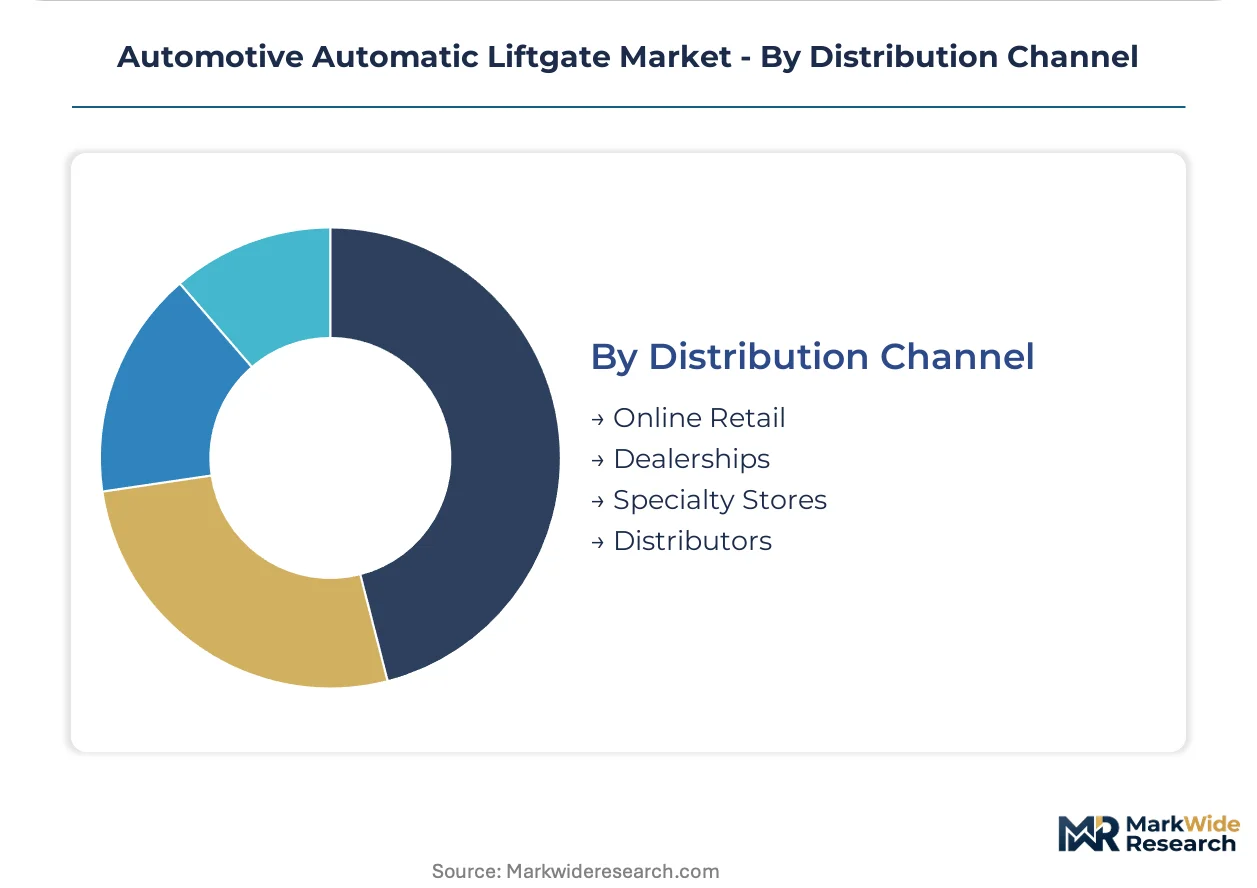
- Online Retail:Direct-to-consumer and B2B platforms capturing growing share of aftermarket kit distribution, with independent installers in Germany and United States sourcing electromechanical modules through specialized automotive e-commerce.
- Dealerships:OEM-authorized service networks handling warranty repairs and factory-option liftgate installation, maintaining proprietary diagnostic equipment and technician certification for integrated vehicle systems.
- Specialty Stores:Independent automotive accessory retailers serving enthusiast and fleet segments with branded retrofit solutions, typically carrying lower price points and reduced technical support.
- Distributors:Regional wholesale operations consolidating inventory for independent repair facilities and smaller aftermarket installers, absorbing working capital requirements for electromechanical module stocking.
Dealerships dominate OEM-captive volume; Online Retail channels climb fastest as fleet procurement patterns fragment traditional distribution.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Neodymium deposits in Inner Mongolia and Jiangxi Province anchor China's permanent magnet motor supply chain for electromechanical actuators. German automotive stamping clusters around Stuttgart and Wolfsburg consume specialized torque rod assemblies. Detroit's integrated module production feeds North American SUV assembly lines with hands-free entry systems.
United States
NHTSA Federal Motor Vehicle Safety Standards mandate anti-entrapment torque-limiting algorithms for all power liftgate assemblies. Detroit Three OEMs operate dedicated rear closure engineering centers in Michigan. The Southeast manufacturing corridor from Tennessee to Alabama attracts electromechanical module suppliers seeking proximity to crossover vehicle assembly plants.
Germany
ECE R21 and ECE R94 regulations govern structural integrity and occupant protection for rear closure systems across European type approval. Stuttgart anchors premium SUV production with integrated hands-free entry specifications. Wolfsburg stamping suppliers absorb capital costs for zinc-nickel coating conversion under REACH substance restrictions.
China
MIIT GB standards enforce electromagnetic compatibility constraints on control module architecture for domestic and export-bound assemblies. Shanghai's Yangtze River Delta cluster concentrates electromechanical module sourcing for domestic EV manufacturers. Shenzhen sensor fusion specialists supply capacitive foot-activation components to tier-one integrators.
Japan
METI industrial policy supports brushless DC motor miniaturization for compact vehicle applications. Nagoya's Chubu region hosts precision gear reduction manufacturing for planetary actuator assemblies. Toyota City suppliers validate obstacle detection algorithms against JIS functional safety benchmarks.
South Korea
MFDS vehicle safety guidelines align with UN ECE regulations for rear closure system homologation. Seoul Capital Area module assemblers supply Hyundai-Kia integrated liftgate platforms. Busan-Ulsan heavy industry corridors fabricate load-rated torque rods for commercial utility vehicle exports.
Automotive Automatic Liftgate Market Vendor Landscape
Global majors compete with regional champions across electromechanical actuator design and sensor fusion integration. The supplier base concentrates around three strategic tiers: integrated module designers, component specialists, and smart sensor technology providers. Market structure rewards backward integration into permanent magnet motor production and forward integration into vehicle-level software validation. Dominant competitive moves include strategic partnerships for multi-market homologation and geographic expansion through Yangtze River Delta manufacturing footprints.
Within the integrated module tier, Magna International Inc. and Johnson Electric exemplify North American and Asia-Pacific supply anchoring respectively. Aisin Seiki occupies a position among Japanese precision actuator specialists. Bosch represents European sensor fusion convergence between capacitive activation and radar-based obstacle detection. Brose Fahrzeugteile and Huf Hülsbeck & Fürst sit within the German automotive component fabricator archetype. Valeo and Denso Corporation exemplify diversified tier-one suppliers with multi-continent production footprints. Kiekert AG anchors specialized latch and closure mechanism expertise.
| Leading Market Players |
|---|
| Johnson Electric |
| Aisin Seiki |
| Magna International Inc. |
| Brose Fahrzeugteile |
| Huf Hülsbeck & Fürst |
| Bosch |
| Valeo |
| Kiekert AG |
| Denso Corporation |
| Others |
Supply Flow & Price Mechanics
Neodymium magnet costs cascade from Jiangxi Province mining operations through three distinct pricing tiers for electromechanical actuators, with warranty bundling separating premium OEM supply from unbundled aftermarket kits.
Pricing Analysis
Warranty and diagnostic service bundling distinguishes OEM-captive supply from aftermarket retrofit offerings. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and volume scale commitments. Pricing pressure stems from rare earth magnet volatility squeezing mid-tier actuator margins. Fleet procurement through automotive e-commerce platforms exhibits highest price sensitivity; integrated module contracts with Detroit Three automakers show lowest.
Supply Chain Analysis
ISO 26262 ASIL-B certification gates access to OEM platform engineering programs for electromechanical module suppliers. Permanent magnet motor fabrication concentrates in China, Taiwan, and South Korea; torque rod stamping clusters in Germany and the United States. The supply chain draws from neodymium deposits, semiconductor foundry capacity, and specialized steel alloys. Single-source vulnerability concentrates in 12V ECU semiconductor fabrication. Distribution runs through tier-one system integrators to OEM assembly plants, with aftermarket channels fragmenting through independent e-commerce platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Capacitive foot-activation systems are displacing button-actuated mechanisms across premium SUV configurations, compressing refresh cycles for legacy electromechanical architectures.
For Market Incumbents: Lock in permanent magnet motor supply through backward integration into Jiangxi Province rare earth processing or long-term offtake agreements with neodymium refiners. Deepen sensor fusion R&D investment to defend against Bosch and Continental algorithm differentiation in radar-capacitive convergence. Certification investment in UN R155 cybersecurity modules creates switching costs for OEM platform engineering teams. For New Entrants and Emerging Players: Capture India's sub-4-meter compact SUV segment where electromechanical liftgate penetration remains minimal and localization pressure favors domestic kit suppliers. Target aftermarket fleet procurement channels in Germany and the United States where aging vehicle populations seek hands-free convenience upgrades through automotive e-commerce platforms. Partner with independent installers to bypass tier-one system integrator gatekeeping. For Investors and Strategic Acquirers: First-mover certification for UN R155 vehicle type approval is the leading indicator that connected liftgate module suppliers will command price premiums in European platform engineering programs. Acquisition focus centers on tier-two electromechanical specialists with ASIL-B functional safety capabilities and Yangtze River Delta manufacturing footprints. Monitor NHTSA rulemaking on cybersecurity mandates for connected vehicle access systems as inflection signal for certified-module demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | Magna International reduces engineering overhead across Detroit Three crossover programs through shared electromechanical module architectures. |
| Sensor Fusion Investment | Bosch combines capacitive foot-activation with radar-based obstacle detection to meet NHTSA anti-entrapment mandates. |
| Geographic Manufacturing Footprint | Johnson Electric anchors actuator production in Yangtze River Delta plants to serve Shanghai-based EV manufacturers. |
| Software-Defined Vehicle Integration | Tier-one suppliers enable over-the-air update capability for connected liftgate control modules under MIIT GB standards. |
| Backward Integration | Specialized suppliers secure neodymium magnet supply chains against price volatility through captive rare earth processing partnerships. |
Methodological Framework
Document review covered vehicle production databases, IHS Markit registration data, and regulatory filings with NHTSA and MIIT, complemented by interviews with Tier 1 supplier procurement managers, OEM platform engineers, aftermarket distributors, and dealership operations heads. Secondary validation drew from ECE R21 homologation records, customs trade data for electromechanical actuator imports, and SEC filings from listed automotive component suppliers. Bottom-up volume modeling triangulated against top-down market sizing across product type, technology, and end-user segmentation dimensions.
Unit shipment and value projections emerged from integrated demand modeling across the projection horizon, with vehicle class, propulsion architecture, content per vehicle, OEM tier, and regional production cluster serving as primary segmentation dimensions. CAGRs derived from regression analysis of historical adoption curves and technology diffusion patterns. Forecast inputs incorporated NHTSA regulatory timeline assumptions, EV platform launch schedules, and rare earth magnet price trajectory scenarios.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to neodymium supply disruptions, semiconductor fabrication capacity constraints, and cybersecurity mandate acceleration. Projections reflect assumptions on regulatory harmonization timelines and OEM platform standardization decisions. A model refresh is warranted upon material change in NHTSA rulemaking or MIIT GB standard revision for connected vehicle access systems.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Interior & Exterior
Global Automotive Windscreen Glazing Market
Automotive Interior & Exterior
Automotive Synthetic Leather Market
Automotive Interior & Exterior
Exterior Car Accessories Market
Automotive Interior & Exterior
Automotive Door Latch Market
Automotive Interior & Exterior
Advanced Vehicle Side Mirror Market
Automotive Interior & Exterior
Automotive Load Floors Market
Automotive Interior & Exterior
Automotive Solar Film Market
Automotive Interior & Exterior
Two Wheeler Backrest Market
Automotive Interior & Exterior
Windscreen Washer System Market
Automotive Interior & Exterior
Smart Automotive Headlight Market
Automotive Interior & Exterior
Automotive Plastic Interior Trims Market
Automotive Interior & Exterior
Global Headliner (OE) Market
Automotive Interior & Exterior
Automotive Decorative Interior Trim Market
Automotive Interior & Exterior
Automotive Smart Seating Systems Market
Automotive Interior & Exterior
Global on Highway Vehicle Lighting Market
Automotive Interior & Exterior
Automotive Cabin Air Filter Market