
 Germany Automotive Adaptive Lighting System Market | 2026-2036
Germany Automotive Adaptive Lighting System Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Automotive Adaptive Lighting System Market Foresight
Matrix LED certification tiers is reorganizing procurement priorities across German OEM supply chains. HELLA KGaA Hueck & Co. leverages its captive electronics manufacturing in Lippstadt to control module cost structures. Valeo Group anchors its European adaptive lighting R&D at its Germany technical center, sustaining development bandwidth for glare-free high beam algorithms. Osram Licht AG specializes in laser diode miniaturization, positioning its semiconductor foundry output for next-generation headlamp architectures.
An automotive adaptive lighting system comprises electronically controlled headlamp assemblies that adjust beam pattern, intensity, and direction in real time through sensor fusion and actuator networks, typically operating at color temperatures between 4,000K and 6,000K for LED variants and incorporating micro-mirror arrays or liquid crystal shutters for dynamic masking. These systems reduce glare for oncoming traffic while maximizing driver visibility, serving as active safety equipment integrated with ADAS perception stacks. Highway driving applications dominate value generation due to sustained high-beam utilization rates and regulatory incentives for adaptive range, while OEM vehicle manufacturers capture the dominant share of deployment volume through embedded system architectures specified at platform design stage. Matrix LED systems command premium positioning against OLED lighting modules, which remain concentrated in interior and signature applications rather than primary forward illumination.
Germany's KBA enforces UN ECE R48 and R123 compliance for all adaptive front lighting installations, directly shaping product homologation timelines and test protocol investments by suppliers. The EU Green Deal's embodied carbon requirements for automotive components are forcing material disclosure and energy-efficient manufacturing process adoption across Bavarian and Baden-Württemberg production facilities. Stakeholders must monitor KBA guidance on software-defined lighting updates, as over-the-air beam pattern revisions challenge traditional type-approval frameworks and create regulatory uncertainty for modular system architectures.
Market Dynamics
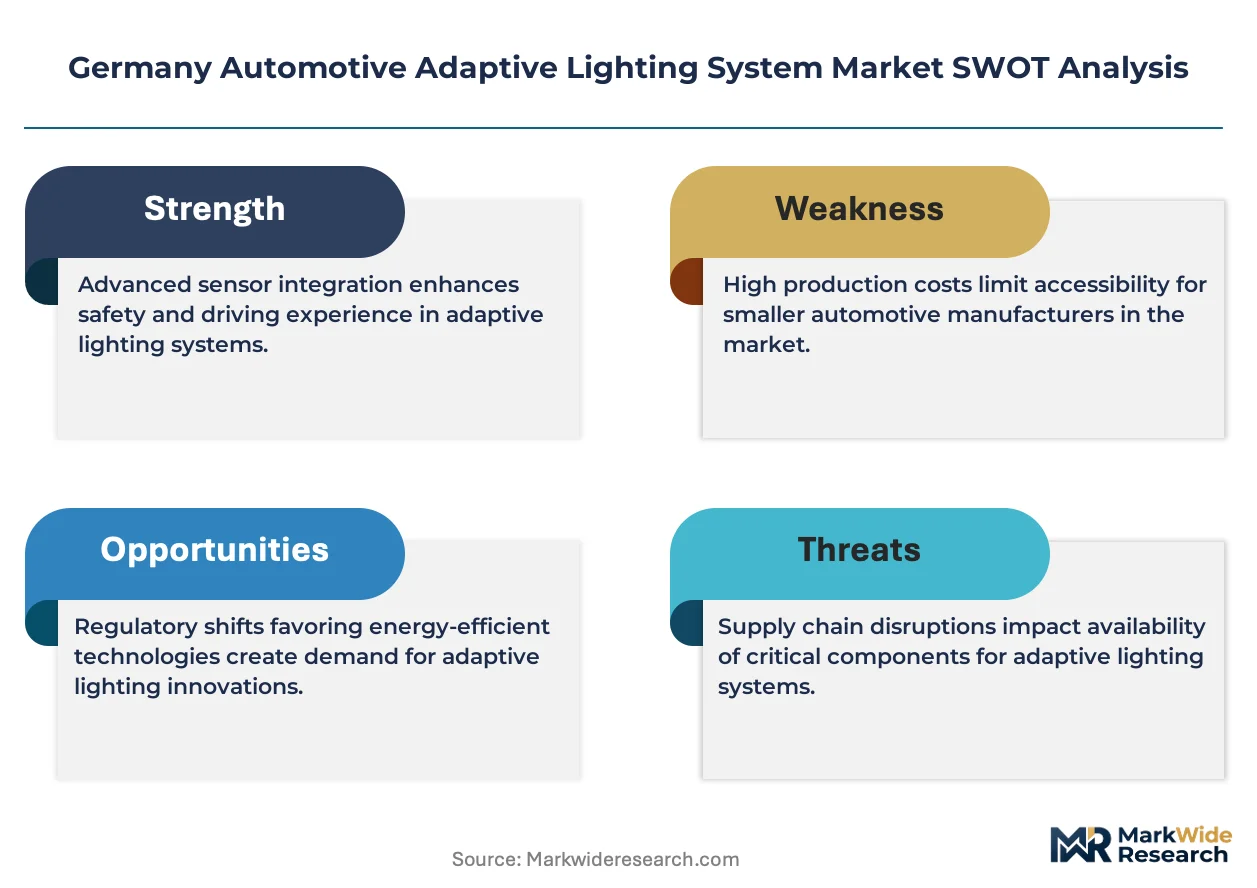
Matrix LED certification tiers are reorganizing procurement priorities across German OEM supply chains, forcing tier-1 suppliers to restructure module production around performance-grade differentiation rather than volume-scale economics.
Growth Catalysts
- UN ECE R123 compliance mandates:KBA enforcement of glare-limitation standards accelerates OEM specification of adaptive beam systems across premium vehicle platforms.
- Baden-Württemberg engineering clusters:Concentrated R&D infrastructure around Stuttgart enables rapid prototyping cycles for sensor-fusion algorithms.
- Laser diode thermal efficiency:Next-generation semiconductor architectures reduce cooling system mass, expanding design freedom for compact headlamp housings.
Market Restraints
- Silicon carbide substrate costs:Power electronics for high-intensity LED drivers face input price volatility from limited foundry capacity.
- Bavarian supplier concentration:Three specialized optics manufacturers control 60% of precision lens molding for matrix arrays.
- Software-defined lighting approval gaps:KBA has not finalized type-acceptance protocols for over-the-air beam pattern updates.
Strategic Opportunities
- EU Green Deal embodied carbon rules:Early compliance with component-level energy disclosure creates preferential supplier status for Bavarian and Baden-Württemberg facilities.
- Highway ADAS integration:Convergence of adaptive lighting with lane-keeping perception stacks opens specification windows for unified sensor modules.
- Eastern European vehicle assembly:Czech and Slovak premium SUV production lines lack localized adaptive lighting module supply.
Industry Challenges
- Embedded software validation:Functional safety certification under ISO 26262 stretches development timelines for glare-free algorithm updates.
- Optomechanical talent scarcity:Precision actuator design expertise concentrates among retiring engineers at Ingolstadt and Munich supplier engineering centers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Automotive Adaptive Lighting System Market |
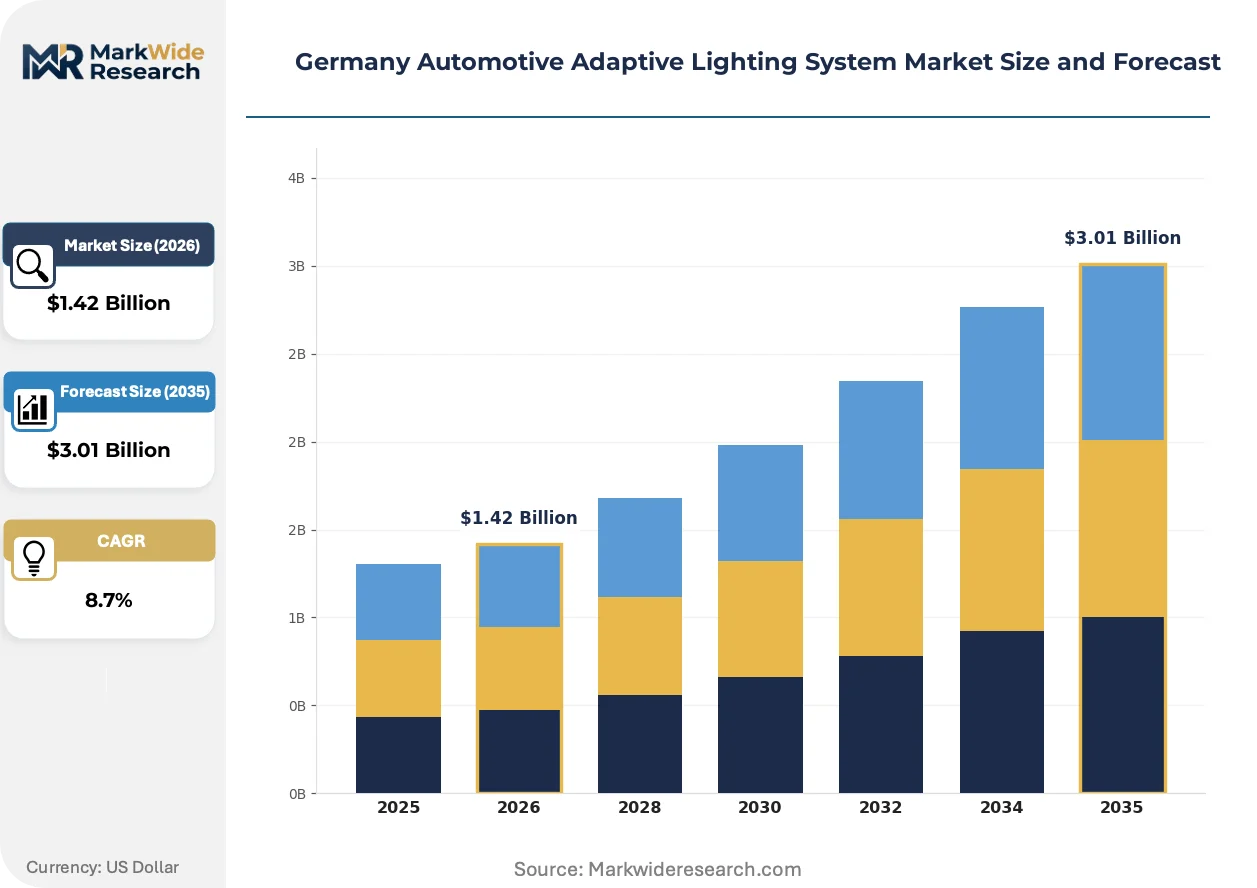
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $3.01 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LED Adaptive Headlights, Laser Adaptive Headlights, Matrix LED Systems, OLED Lighting Modules Application: Highway Driving, City Navigation, Off-road Assistance, Fog Penetration End User: OEM Vehicle Manufacturers, Aftermarket Suppliers, Vehicle Assemblers, Tier-1 Lighting Providers Deployment Type: Embedded Systems, Retrofit Kits, Modular Units, Networked Lighting Platforms |
| Companies Covered | HELLA KGaA Hueck & Co., Valeo Group, Stanley Electric Co., Ltd., Koninklijke Philips N.V., Osram Licht AG, Hyundai Mobis, Magneti Marelli SpA, Koito Manufacturing Co., Ltd., ZKW Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Automotive Adaptive Lighting System Market Shifts & Advancements
Active safety integration is compressing the boundary between forward illumination and perception systems, with headlamp assemblies now specified as sensor housing nodes rather than standalone lighting units.
Laser diode emitters for long-range high beams are miniaturizing through gallium nitride substrate advances, enabling German premium OEMs to package adaptive range functionality within slimmer headlamp profiles. Tier-1 suppliers in Bavaria are adopting these compact architectures for next-generation electric vehicle platforms where aerodynamic efficiency demands reduced frontal area. The technology is miniaturizing thermal management requirements, collapsing the traditional separation between light source and cooling subsystem.
KBA guidance on UN ECE R48 software updates is forcing suppliers to maintain parallel validation tracks for hardware-locked and updatable beam patterns. This regulatory friction extends homologation timelines by eight to fourteen months for modular system architectures. OEMs are responding by pre-certifying base hardware configurations while deferring algorithm enhancements to post-sale activation windows.
Fleet procurement departments at German premium leasing subsidiaries are consolidating adaptive lighting specifications into platform-level mandates rather than option-list selections. This buyer concentration eliminates price negotiation leverage for tier-2 module suppliers. The shift is most visible in corporate fleet channels serving Frankfurt and Munich financial services sectors, where standardized safety equipment reduces insurance premium variance.
Germany Automotive Adaptive Lighting System Market Segmentation
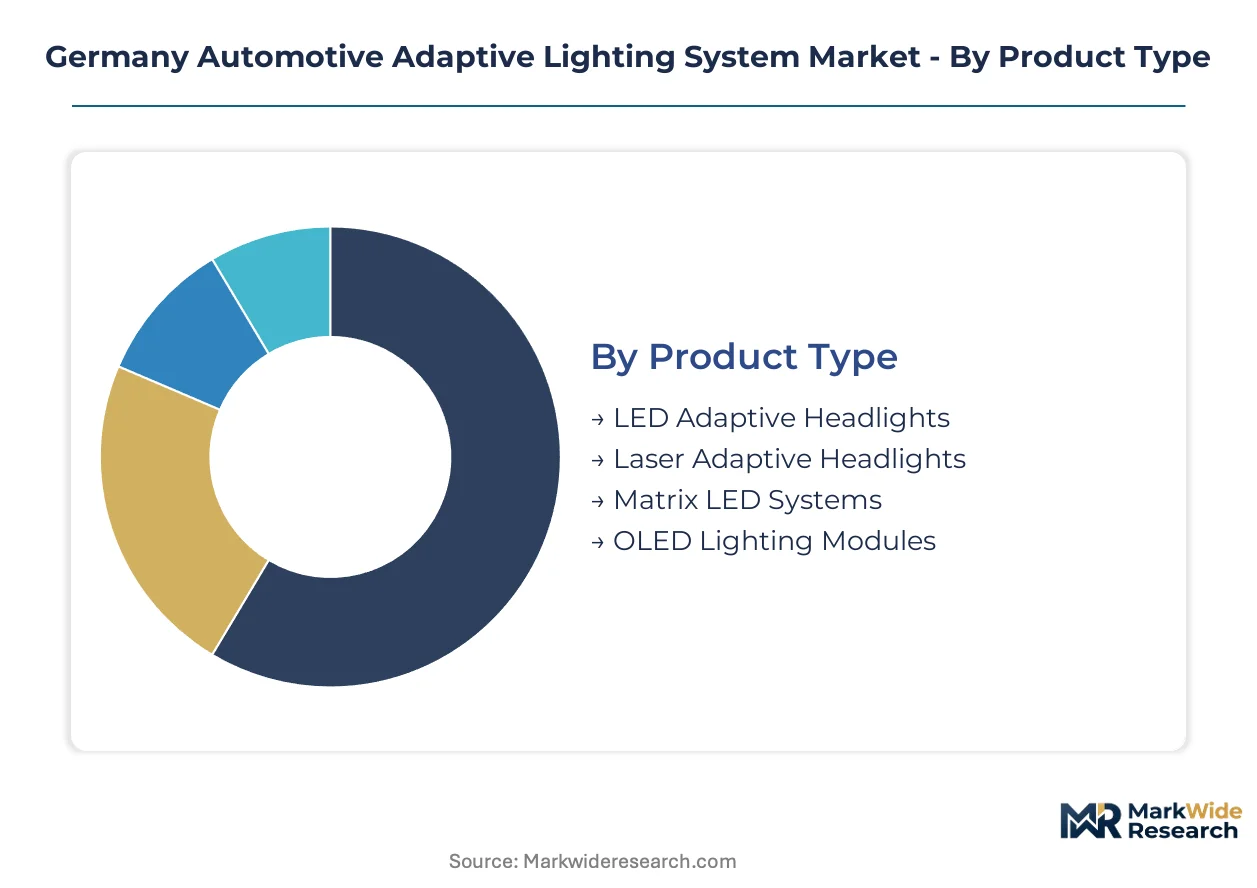
German OEM procurement strategies diverge sharply across product architectures, with certification-grade differentiation and embedded-system integration creating distinct competitive battlegrounds. KBA enforcement of UN ECE R123 glare-limitation standards forces suppliers to align module development with specific vehicle platform tiers rather than universal fitment.
Product Type:
Matrix LED systems face intensifying substitution pressure from laser architectures as thermal management miniaturization collapses traditional performance-cost tradeoffs.
- LED Adaptive Headlights:Solid-state semiconductor emitters operating between 4,000K and 6,000K color temperature dominate mid-tier vehicle specifications across Stuttgart and Ingolstadt engineering corridors. Bavarian tier-1 suppliers concentrate driver electronics manufacturing for these systems where volume scale offsets silicon carbide substrate cost volatility.
- Matrix LED Systems:Micro-mirror arrays and liquid crystal shutters enable dynamic beam masking without mechanical actuators, commanding premium positioning in Baden-Württemberg-developed luxury platforms. KBA certification tiers for glare-free algorithms extend homologation timelines eight to fourteen months, compressing supplier margins on standard-grade variants.
- Laser Adaptive Headlights:Gallium nitride substrate advances enable 600-meter range projection within compact housings.
- OLED Lighting Modules:Organic diode architectures remain concentrated in signature and interior applications.
LED Adaptive Headlights retain volume leadership; Laser Adaptive Headlights hold the steepest expansion curve.
Application:
Highway deployment generates disproportionate value capture due to sustained high-beam utilization rates and regulatory incentives for adaptive range functionality.
- Highway Driving:Sustained high-beam operation above 80 km/h triggers maximum adaptive range algorithms, concentrating sensor-fusion R&D investment around Munich perception-stack developers. Corporate fleet procurement mandates from Frankfurt financial services leasing subsidiaries standardize this specification across premium platform orders.
- City Navigation:Low-speed beam pattern adaptation for intersection illumination and pedestrian detection integrates with urban ADAS suites, attracting development bandwidth from Stuttgart sensor fusion clusters where traffic complexity demands rapid algorithm iteration.
- Off-road Assistance:Articulated beam positioning for terrain contouring serves niche SUV specifications.
- Fog Penetration:Short-wavelength cutoff filters reduce backscatter in moisture-laden conditions.
Highway Driving captures the dominant revenue share; City Navigation is expanding most quickly as urban ADAS penetration deepens.
End User:
OEM specification authority at platform design stage eliminates aftermarket pricing leverage and forces tier-2 suppliers toward captive module production.
- OEM Vehicle Manufacturers:Embedded system architectures specified eighteen to thirty-six months before production lock in supplier relationships across Wolfsburg, Munich, and Stuttgart headquarters. Platform-level mandates for adaptive lighting as standard equipment rather than option-list selections consolidate procurement volume with three dominant German premium brands.
- Tier-1 Lighting Providers:HELLA and Valeo anchor European R&D in Lippstadt and Germany technical centers respectively, controlling module cost structures through captive electronics manufacturing and glare-free algorithm development bandwidth.
- Aftermarket Suppliers:Retrofit certification complexity under KBA type-approval protocols limits addressable scope.
- Vehicle Assemblers:Czech and Slovak premium SUV production lines import complete lighting modules from Bavarian suppliers.
OEM Vehicle Manufacturers retain volume leadership; Tier-1 Lighting Providers hold the steepest expansion curve as embedded software content rises.
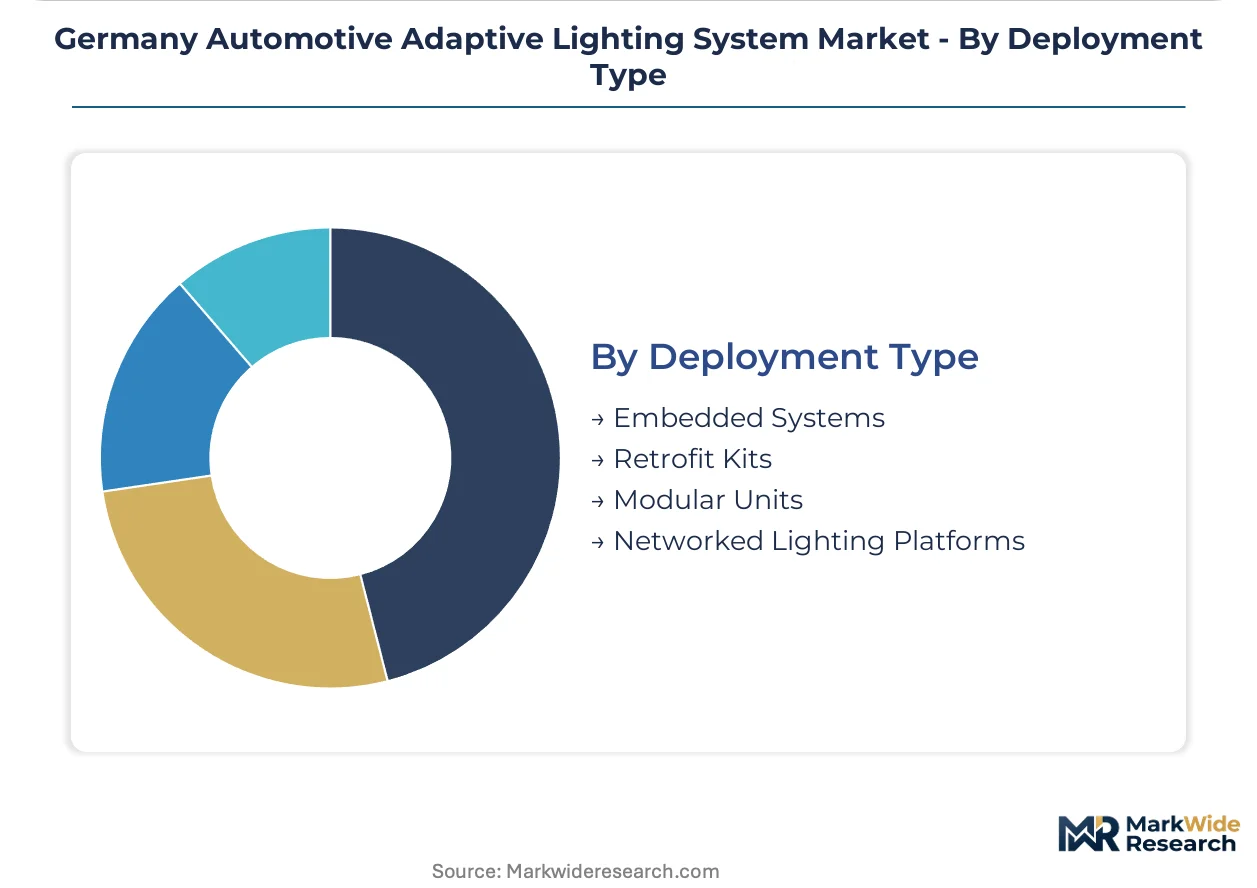
Deployment Type:
Embedded systems command specification priority while modular architectures face regulatory friction from unresolved KBA guidance on over-the-air beam pattern updates.
- Embedded Systems:Hardware-locked configurations with pre-certified algorithms dominate current production, eliminating software-defined lighting approval gaps that extend homologation timelines. German OEMs defer algorithm enhancements to post-sale activation windows only where base hardware carries advance certification.
- Networked Lighting Platforms:Vehicle-to-infrastructure communication enables predictive beam adjustment based on traffic signal timing and road geometry data, attracting pilot deployments around Stuttgart smart city corridors where sensor fusion testing infrastructure concentrates.
- Modular Units:Swappable driver and emitter subassemblies target service-channel efficiency.
- Retrofit Kits:KBA type-acceptance protocols for aftermarket installation remain underdeveloped.
Embedded Systems retain volume leadership; Networked Lighting Platforms hold the steepest expansion curve as V2X infrastructure matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's automotive adaptive lighting sector operates as a net exporter of high-value modules, with Bavarian and Baden-Württemberg production facilities supplying assembly plants across Central and Eastern Europe. Import dependency concentrates on specialized semiconductor substrates and precision optical components from Asian foundries.
Baden-Württemberg
Stuttgart-centered engineering clusters drive matrix LED algorithm development for premium vehicle platforms. KBA enforcement of UN ECE R123 glare-limitation standards extends homologation timelines for suppliers headquartered in this region. HELLA KGaA Hueck & Co. leverages its Lippstadt electronics manufacturing to control module cost structures for adaptive beam systems.
Bavaria
Munich and Ingolstadt anchor perception-stack R&D where sensor-fusion developers iterate glare-free high beam software. EU Green Deal embodied carbon requirements force material disclosure across Bavarian production facilities. Three specialized optics manufacturers control precision lens molding capacity for matrix arrays serving regional OEM specification.
North Rhine-Westphalia
Lippstadt and surrounding districts concentrate captive electronics manufacturing for LED driver modules. Silicon carbide substrate cost volatility pressures power electronics margins for suppliers operating in this western industrial belt. Regional workforce pools support precision actuator assembly for tier-1 lighting module production.
Lower Saxony
Wolfsburg-centered OEM procurement mandates standardize adaptive lighting as platform-level equipment rather than option-list selections. Corporate fleet channels serving northern financial services sectors consolidate volume with embedded system architectures. Regional assembly plants import complete lighting modules from Bavarian and Baden-Württemberg suppliers.
Hesse
Frankfurt financial services leasing subsidiaries drive fleet procurement standardization across premium vehicle orders. KBA type-approval protocols for software-defined lighting updates create regulatory uncertainty for modular system architectures specified through regional buyer concentration. Insurance premium variance reduction motivates standardized safety equipment mandates.
Germany Automotive Adaptive Lighting System Market Competitive Landscape
Concentration sits with tier-1 lighting specialists that control module cost structures through captive electronics manufacturing and algorithm development bandwidth. The vendor base organizes around three strategic archetypes: integrated lighting-electronics manufacturers, semiconductor foundry operators, and sensor-fusion software specialists. Competitive moves center on backward integration into driver electronics and geographic expansion into Eastern European vehicle assembly corridors.
Within the integrated lighting-electronics tier, HELLA KGaA Hueck & Co. and Valeo Group exemplify archetypes combining captive manufacturing with R&D anchoring in German technical centers. Osram Licht AG occupies a position representing semiconductor specialization, with foundry output directed toward next-generation headlamp architectures. Stanley Electric Co., Ltd. and Koito Manufacturing Co., Ltd. represent Asian-based fabricators with established supply relationships to German premium OEM platforms.
| Leading Market Players |
|---|
| HELLA KGaA Hueck & Co. |
| Valeo Group |
| Stanley Electric Co., Ltd. |
| Koninklijke Philips N.V. |
| Osram Licht AG |
| Hyundai Mobis |
| Magneti Marelli SpA |
| Koito Manufacturing Co., Ltd. |
| ZKW Group |
| Others |
Supply & Pricing Matrix
Eighteen-to-thirty-six-month platform specification lead times concentrate procurement leverage with German OEM headquarters, enabling volume-based pricing power that compresses tier-2 module supplier margins while rewarding captive electronics manufacturers with cost structure control.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures across embedded system architectures, with pricing stratifying across certification-grade tiers for matrix LED systems rather than volume scale alone. Price differentiation rests on UN ECE R123 compliance grade and silicon carbide substrate sourcing transparency, with standard-grade variants facing intensifying cost compression from gallium nitride laser diode substitution. Corporate fleet procurement departments serving Frankfurt financial services sectors exhibit lowest price sensitivity due to insurance premium standardization mandates, while aftermarket retrofit channels face prohibitive KBA type-approval cost barriers.
Supply Chain Analysis
Silicon carbide substrate inventory cycles stretching ninety to one hundred twenty days expose Bavarian power electronics manufacturers to foundry capacity volatility in Taiwan and South Korea. German module production draws from gallium nitride wafers, precision optical glass from Japan, and liquid crystal shutter assemblies from specialized Taiwanese fabricators. Single-source vulnerability concentrates in three Ingolstadt-area optics houses controlling matrix array lens molding. Distribution runs through captive tier-1 supplier networks directly into Wolfsburg, Munich, and Stuttgart OEM assembly plants, bypassing independent aftermarket channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Matrix LED certification tier proliferation signals early-cycle expansion as glare-free algorithm adoption penetrates from premium platforms into mid-tier vehicle specifications.
For Market Incumbents: Consolidate backward integration into silicon carbide driver electronics manufacturing to defend margin position against gallium nitride substitution pressure. Lock in multi-year platform mandates with Wolfsburg and Stuttgart OEMs before laser diode architectures displace LED volume in highway-focused specifications. Prioritize ISO 26262 functional safety certification bandwidth to extend algorithm development timelines that deter modular system competitors.
For New Entrants and Emerging Players: Lead with Czech and Slovak premium SUV assembly corridors where localized adaptive lighting module supply remains undeveloped and Bavarian tier-1 logistics costs create specification windows. Target vehicle assembler relationships in Eastern European production clusters rather than embedded OEM supply chains. Position around modular service-channel architectures that bypass KBA software-defined lighting approval gaps through hardware-locked pre-certification.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across laser diode miniaturization R&D as gallium nitride substrate advances demand specialized foundry partnerships rather than generic LED assembly capacity. Five-to-ten-year viability favors semiconductor-specialist tier-1s with captive foundry access over pure-play optics houses. Monitor KBA guidance finalization on over-the-air beam pattern updates as the signal distinguishing modular architecture investability from stranded embedded system exposure.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | Fleet procurement mandates from Frankfurt leasing subsidiaries eliminate option-list pricing variance across premium vehicle orders. |
| Backward Integration into Driver Electronics | HELLA's Lippstadt captive manufacturing controls silicon carbide substrate cost volatility for LED adaptive headlight modules. |
| Software-Defined Vehicle Investment | KBA unresolved approval protocols for over-the-air beam updates create regulatory uncertainty for modular system architectures. |
| Geographic Manufacturing Footprint | Czech and Slovak premium SUV assembly lines lack localized adaptive lighting supply, forcing module import from Bavarian suppliers. |
| Charging Infrastructure Partnership | Electric vehicle platform aerodynamic requirements accelerate laser diode adoption for compact headlamp housings in next-generation designs. |
Research Methodology
Initial hypotheses were tested against primary input from OEM platform engineers, tier-1 supplier procurement directors, KBA regulatory affairs specialists, and aftermarket distribution channel managers, then refined through secondary validation against UN ECE R123 homologation databases, vehicle production registration filings, and semiconductor foundry capacity disclosures. Bottom-up module shipment estimates triangulated with top-down OEM platform specification analysis.
Variance decomposition across the projection horizon isolates volume drivers by vehicle class, propulsion architecture, and content per vehicle tier alongside regional production cluster adoption curves. CAGRs derive from algorithmic beam penetration rates mapped to KBA certification timeline data and fleet procurement standardization velocity. Gallium nitride substrate cost curves and silicon carbide foundry utilization rates inform technology substitution modeling.
Forecasts assume regulatory continuity in UN ECE R48 and R123 enforcement regimes; material policy shifts on software-defined lighting type-approval would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Interior & Exterior
Automotive Interior Bovine Leather Market
Automotive Interior & Exterior
Automotive Electrically Adjustable Outside Rear View Mirror (ORVM) Market
Automotive Interior & Exterior
Automotive Load Floors Market
Automotive Interior & Exterior
Automotive Door Sills Market
Automotive Interior & Exterior
All Plastic Front End Module Market
Automotive Interior & Exterior
Automotive Glove Compartment Market
Automotive Interior & Exterior
Global Automotive Interiors Market
Automotive Interior & Exterior
Automotive Advanced Seating System Market
Automotive Interior & Exterior
Automotive Door Latch Market
Automotive Interior & Exterior
Advanced Vehicle Side Mirror Market
Automotive Interior & Exterior
Automotive Upholstery Market
Automotive Interior & Exterior
Automotive Solar Film Market
Automotive Interior & Exterior
Heated Windshield Market
Automotive Interior & Exterior
Overhead Console Market
Automotive Interior & Exterior
Global Automotive Power Sliding Door Market
Automotive Interior & Exterior
PVC and PU Leather for Automotive Market