
 Composite Bearings Market | 2026-2036
Composite Bearings Market Size, Share, and Industry Trends Forecast 2026-2036
Composite Bearings Market Analysis
A shift from single-source to multi-source procurement for high-performance bearing substrates is realigning supplier relationships across the composite bearings value chain. Schaeffler AG leverages its vertically integrated ceramic matrix composite production to control quality from fiber to finished bushing. SKF competes through geographic proximity, sustaining dense technical service networks in industrial machinery hubs. GGB specializes in polytetrafluoroethylene-based polymeric composites, dominating marine and hydropower applications where corrosion resistance is paramount.
Composite bearings are self-lubricating tribological components engineered from fiber-reinforced matrices—typically PTFE-impregnated woven fabrics bonded to steel or bronze backings—designed to operate without external lubrication under boundary and mixed friction conditions. Their primary purpose is eliminating grease systems in inaccessible or contamination-sensitive machinery while extending maintenance intervals beyond metallic alternatives. Polymeric composites lead unit volume due to cost efficiency in automotive chassis and steering linkages, whereas ceramic matrix composites capture premium margins in aerospace engine mounts and exhaust-adjacent brackets where thermal shock resistance exceeds 800°C. Metal matrix composites occupy a mature position in heavy industrial machinery, with additive manufacturing emerging as a disruptive technology for topology-optimized bearing housings with integrated composite liners.
The EPA regulates perfluorinated compound emissions under TSCA Section 5, compelling U.S. manufacturers to validate alternative self-lubricating chemistries for FDA-contact and environmental applications. REACH restrictions on PFAS substances in Europe are forcing reformulation timelines, with ECHA substance evaluation directly impacting polymeric composite bearing portfolios exported to EU member states. ASTM D3702 and ISO 7148 govern tribological test protocols, creating compliance barriers for suppliers lacking in-house wear-testing infrastructure. Stakeholders must monitor regulatory divergence between U.S. state-level PFAS bans and federal hazard assessment timelines when allocating R&D budgets across material platforms.
Market Dynamics
The REACH regulation on perfluorinated substances is forcing immediate material reformulation across European supply chains while aerospace OEMs simultaneously expand self-lubricating composite bearing specifications for next-generation landing gear assemblies.
Growth Catalysts
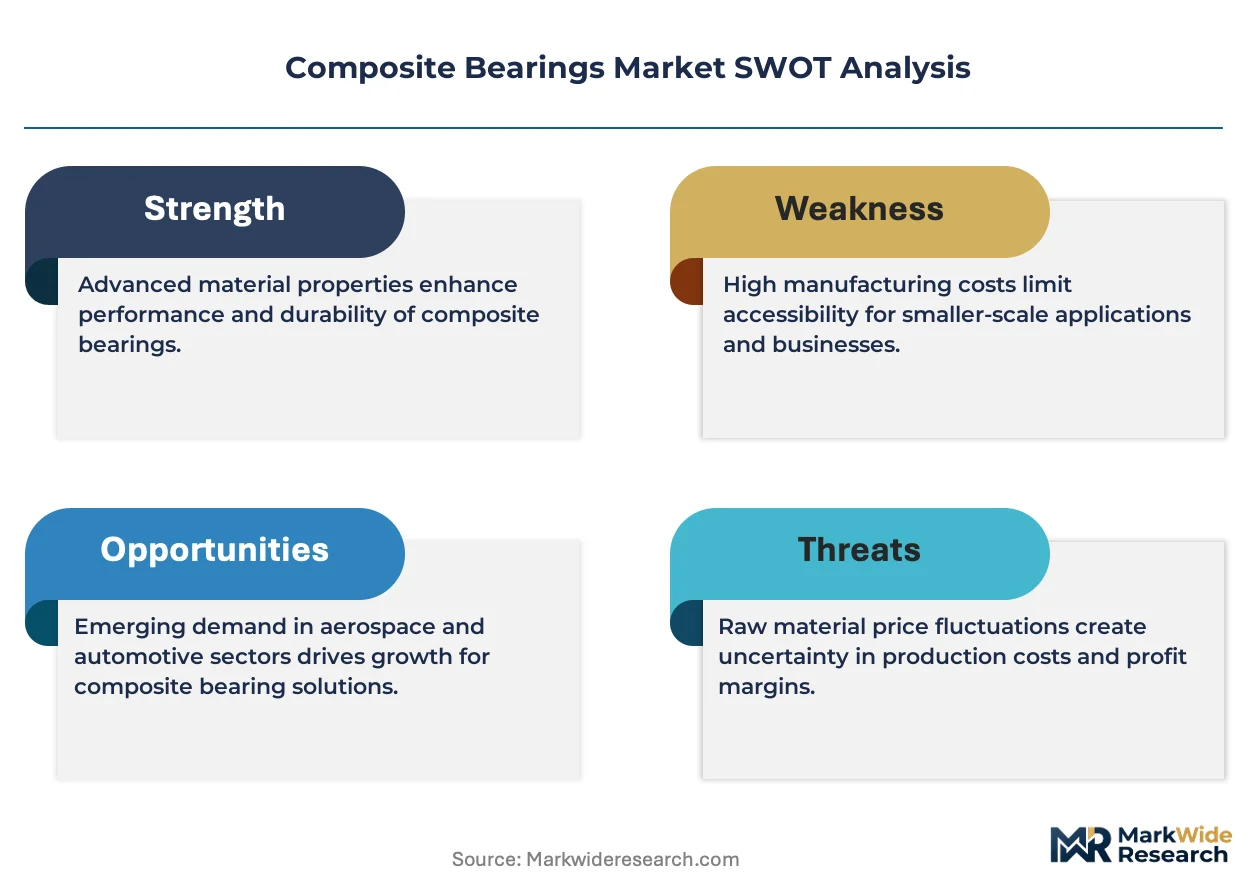
- EU REACH PFAS Restrictions:The ECHA substance evaluation timeline is accelerating PTFE-free polymeric composite development, creating first-mover advantages for suppliers with validated alternative chemistries in marine and food-contact applications.
- Aerospace Landing Gear Modernization:Commercial aircraft programs are specifying fiber-reinforced composite bushings for nose and main landing gear trunnions, eliminating hydraulic grease systems and reducing maintenance intervals by 40% compared to traditional metallic bearings.
- Additive Manufacturing Integration:Topology-optimized bearing housings with integrated composite liners are compressing part counts and assembly steps in industrial machinery, enabling geometric complexity impossible with conventional metal casting.
Market Restraints
- Fluoropolymer Input Cost Volatility:PTFE resin prices fluctuate with fluorspar mining output concentrated in China and Mexico, squeezing margins for polymeric composite bearing manufacturers dependent on conventional self-lubricating formulations.
- Ceramic Fiber Supply Concentration:Silicon carbide and alumina fiber production for ceramic matrix composites concentrates in Japanese and American facilities, creating geographic single-source risk for European and Asian bearing assemblers.
- Metallic Bearing Substitution in Cost-Sensitive Segments:Sintered bronze and steel bushings retain cost advantages below 150°C operating temperatures, limiting composite penetration in automotive chassis applications outside premium electric vehicle platforms.
Strategic Opportunities
- Underpenetrated Hydrogen Infrastructure:Germany's hydrogen pipeline expansion and electrolyzer manufacturing scale-up demand cryogenic-compatible composite bearings for valve actuators and compressor seals operating at -253°C.
- FDA-Contact Food Processing Equipment:The EPA TSCA Section 5 notification pathway for PFAS alternatives creates a regulatory tailwind for validated PTFE-free bearing materials in poultry, dairy, and beverage processing machinery.
- Wind Turbine Pitch Bearing Replacement:Convergence of fiber-reinforced thermoplastic composites with condition monitoring sensors enables predictive maintenance integration in offshore turbine blade pitch systems, displacing grease-dependent roller bearings.
Industry Challenges
- Tribological Testing Infrastructure Scarcity:ASTM D3702 and ISO 7148 compliance requires in-house pin-on-disk and block-on-ring wear rigs costing $500,000-$800,000 per installation, creating certification barriers for mid-tier suppliers.
- Legacy Hydraulic System Integration:Composite bearing retrofit into existing aircraft landing gear and industrial machinery requires redesign of adjacent structural components, extending qualification timelines and engineering resource allocation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Composite Bearings Market |
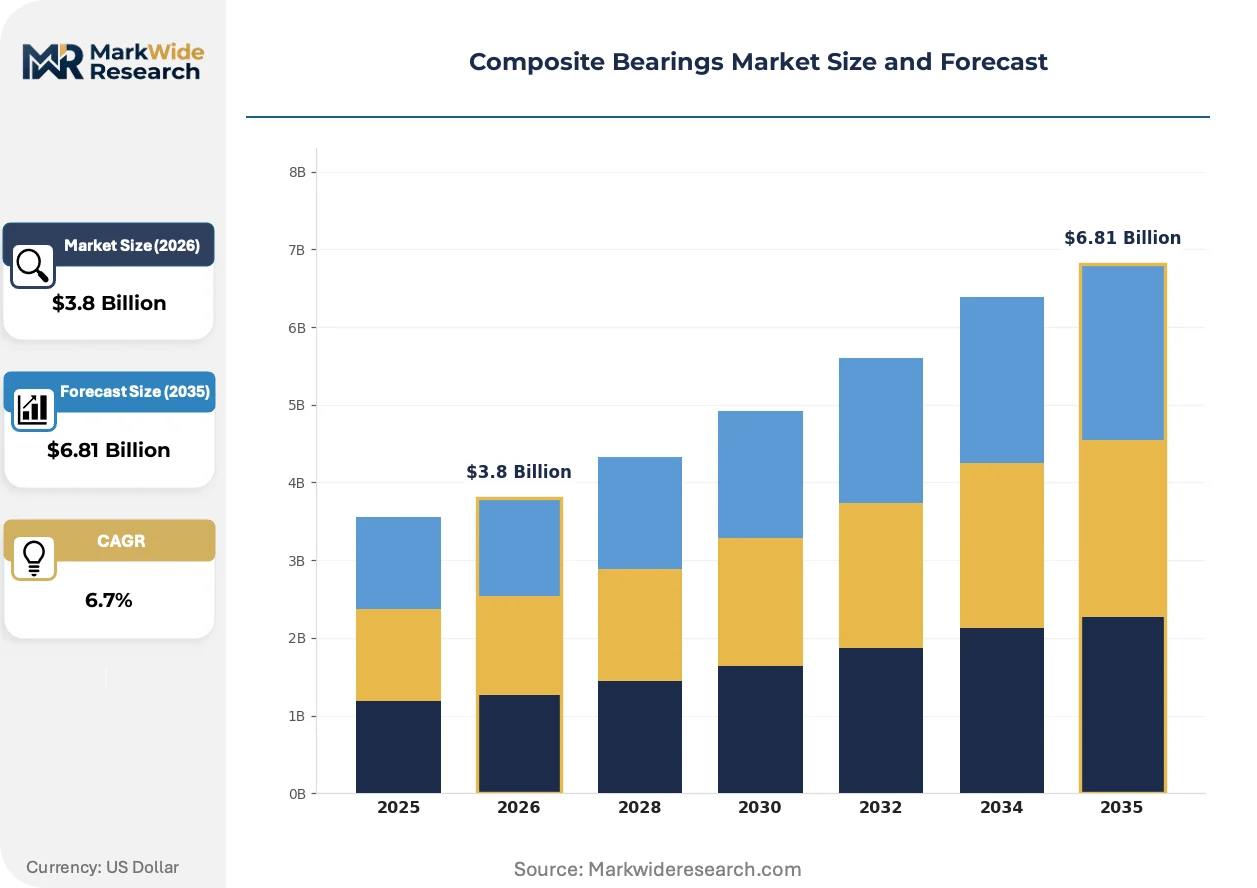
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Metal Matrix Composites, Polymeric Composites, Ceramic Matrix Composites, Hybrid Composites Application: Aerospace, Automotive, Industrial Machinery, Marine End User: Manufacturers, OEMs, Distributors, Aftermarket Technology: Injection Molding, Compression Molding, Casting, Additive Manufacturing |
| Companies Covered | Schaeffler AG, Trelleborg AB, RBC Bearings Incorporated, AST Bearings, Polygon Company, SGL Carbon, SKF, CSB Sliding Bearings, GGB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Composite Bearings Market Emerging Trajectories
Material science convergence with regulatory chemistry constraints is compressing development cycles and reshaping supplier qualification protocols across bearing value chains. Three distinct vectors are redirecting competitive positioning.
Continuous fiber-reinforced thermoplastic composites are unifying structural load-bearing and tribological functions in single-component bearing designs. Automotive steering rack manufacturers in Stuttgart and Wolfsburg are adopting these materials for electric power steering systems, eliminating separate bushing and housing assemblies while reducing part weight by 25%.
REACH Annex XVII PFAS restrictions are compelling reformulation of polymeric bearing matrices toward bio-based polyetheretherketone and polyphenylene sulfide alternatives. The ECHA 2025 restriction proposal timeline is forcing European suppliers to validate new self-lubricating chemistries ahead of U.S. EPA TSCA Section 5 parallel assessments, compressing R&D investment windows.
Multi-year performance guarantees are displacing unit-price procurement in wind energy and hydropower OEM contracts. Vestas and Siemens Gamesa now specify 25-year bearing life warranties backed by predictive sensor data, transferring technical risk upstream to composite bearing suppliers with in-house tribology modeling capabilities.
Composite Bearings Market Segmentation
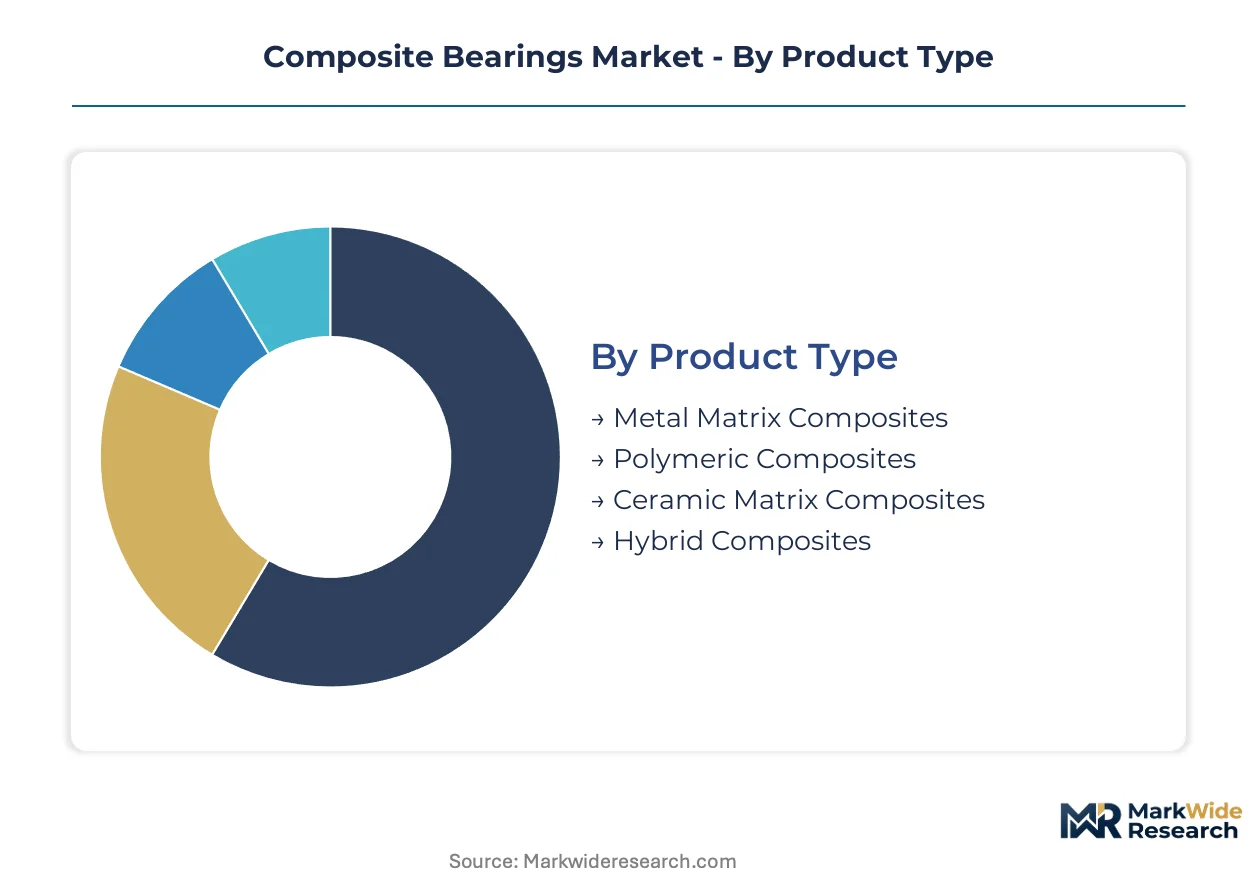
Segmentation in composite bearings reflects divergent material physics and procurement economics. Buyers prioritize thermal envelope and lubrication architecture over unit cost in aerospace and hydrogen applications, while automotive chassis buyers optimize for press-fit compatibility and volume pricing.
Product Type:
Material selection hinges on operating temperature ceiling and structural load requirements, with procurement teams balancing performance specifications against fluoropolymer cost volatility and REACH compliance timelines.
- Metal Matrix Composites:Aluminum or magnesium matrices reinforced with silicon carbide whiskers deliver high specific stiffness for precision spindle bearings in machine tools. Demand concentrates in German and Japanese industrial machinery clusters where dimensional stability under cyclic loading outweighs premium pricing.
- Polymeric Composites:PTFE-impregnated woven fabrics bonded to steel backings dominate unit volume through cost efficiency in automotive steering linkages and chassis bushings. ECHA substance evaluation timelines are accelerating reformulation toward bio-based polyetheretherketone alternatives ahead of U.S. EPA TSCA Section 5 assessments.
- Ceramic Matrix Composites:Silicon carbide fiber-reinforced alumina matrices withstand thermal shock exceeding 800°C in aerospace engine mounts adjacent to exhaust streams.
- Hybrid Composites:Multi-material architectures combining polymeric liners with metallic structural cores optimize weight and tribology in landing gear trunnions.
Volume sits with polymeric composites; growth tilts toward ceramic matrix composites.
Application:
End-use thermal and contamination environments dictate bearing architecture more than procurement scale, with aerospace and marine applications commanding qualification-intensive supply relationships.
- Aerospace:Self-lubricating fiber-reinforced bushings in nose and main landing gear trunnions eliminate hydraulic grease systems and compress maintenance intervals. Commercial aircraft programs in Toulouse and Seattle are expanding specifications for flight control assemblies.
- Automotive:Electric power steering rack manufacturers in Stuttgart specify continuous fiber-reinforced thermoplastic composites that unify structural and tribological functions in single-component designs.
- Industrial Machinery:Topology-optimized bearing housings with integrated composite liners reduce part counts in precision motion systems.
- Marine:Corrosion-resistant polytetrafluoroethylene-based composites dominate propeller shaft bearings and stern tube applications where seawater exposure prohibits metallic alternatives.
Industrial machinery captures volume leadership; aerospace exhibits the steepest expansion trajectory.
End User:
Procurement authority and technical risk allocation vary sharply across the value chain, with OEMs transferring performance guarantees upstream while distributors manage inventory velocity for maintenance-repair-operations demand.
- Manufacturers:Tier-2 bearing fabricators supplying subassemblies to system integrators concentrate in industrial corridors around Stuttgart and Shanghai.
- OEMs:Airbus, Boeing, and Vestas specify multi-year performance warranties backed by predictive sensor data, transferring technical risk to suppliers with in-house tribology modeling.
- Distributors:Technical service networks in machinery hubs stock polymeric composite bushings for expedited replacement in food processing and packaging equipment.
- Aftermarket:Maintenance-repair-operations procurement favors standardized dimensions over application-specific engineering.
OEMs concentrate specification authority; aftermarket channels expand most quickly.
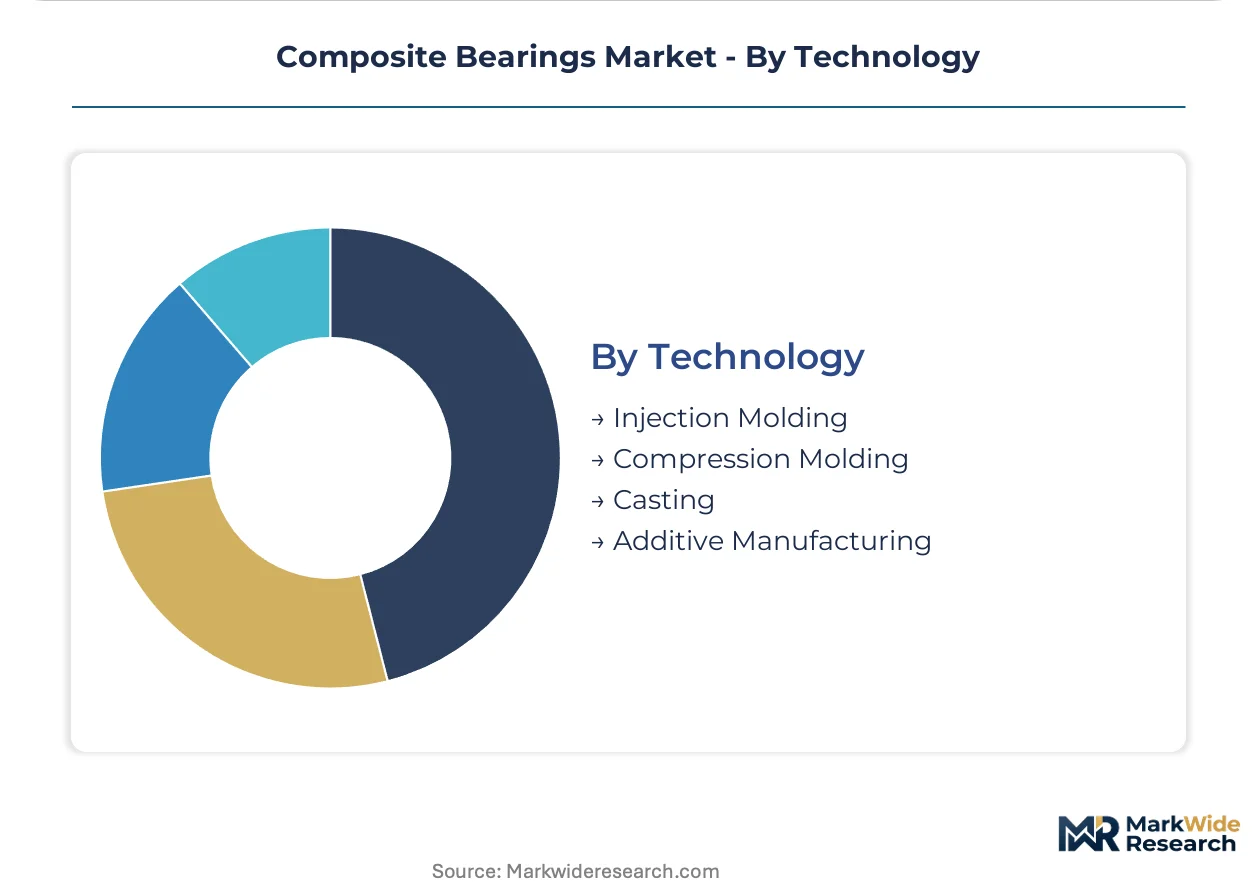
Technology:
Process selection determines geometric complexity, fiber orientation control, and production economics, with additive manufacturing emerging as a disruptive pathway for topology-optimized housings.
- Injection Molding:High-volume production of thermoplastic composite bushings for automotive chassis applications achieves tight dimensional tolerances through precision tool design.
- Compression Molding:Sheet molding compound processes fabricate large-diameter marine bearings with controlled fiber architecture.
- Casting:Molten metal infiltration of preformed ceramic preforms produces metal matrix composite bearing housings for heavy industrial machinery.
- Additive Manufacturing:Selective laser sintering of polymer-matrix composites enables integrated cooling channels and conformal sensor mounting in wind turbine pitch bearing housings.
Injection molding dominates unit volume; additive manufacturing gains share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fluorspar mining districts in Mexico and China anchor raw-material supply chains for PTFE-based polymeric composites, while ceramic fiber production concentrates in Japanese and American facilities serving aerospace demand centers.
Germany
Automotive electric power steering manufacturers in Stuttgart and Wolfsburg specify continuous fiber-reinforced thermoplastic bearings that unify structural and tribological functions. ECHA substance evaluation timelines under REACH are accelerating PTFE-free reformulation toward bio-based polyetheretherketone alternatives. Schaeffler AG maintains vertically integrated ceramic matrix composite production in Herzogenaurach, controlling quality from fiber to finished bushing for industrial OEMs.
United States
Aerospace OEMs in Seattle and Wichita expand self-lubricating composite bearing specifications for next-generation landing gear assemblies, eliminating hydraulic grease systems. EPA regulates perfluorinated compound emissions under TSCA Section 5, compelling manufacturers to validate alternative self-lubricating chemistries for FDA-contact applications. RBC Bearings Incorporated anchors precision bearing fabrication in Connecticut, serving defense and commercial aircraft programs.
Japan
Silicon carbide and alumina fiber production for ceramic matrix composites concentrates in Japanese facilities, creating geographic single-source risk for European and Asian bearing assemblers. METI industrial policy supports advanced materials R&D for thermal shock-resistant engine mount applications exceeding 800°C. Nagoya-area suppliers serve Toyota and Honda electric vehicle platforms with press-fit-compatible polymeric bushings.
China
Fluorspar mining output in Inner Mongolia and Jiangxi provinces influences PTFE resin price volatility, squeezing margins for polymeric composite bearing manufacturers dependent on conventional formulations. MIIT standards govern tribological test protocols for domestic industrial machinery procurement. Shanghai and Suzhou industrial corridors host additive manufacturing specialists developing topology-optimized bearing housings with integrated composite liners.
France
Airbus specifications for flight control assemblies in Toulouse are expanding fiber-reinforced composite bushing adoption, compressing maintenance intervals by 40% compared to metallic alternatives. ANSM maintains pharmaceutical-grade material compliance pathways for food-contact bearing applications in dairy processing equipment. Auvergne-Rhône-Alpes clusters specialize in cryogenic-compatible composites for hydrogen infrastructure valve actuators.
Composite Bearings Market Vendor Landscape
Capacity expansion dominates the current landscape as suppliers build tribological testing infrastructure to meet ASTM D3702 and ISO 7148 compliance requirements. The vendor base organizes around three strategic archetypes: vertically integrated ceramic matrix composite producers, geographic proximity specialists with dense technical service networks, and PTFE-based polymeric composite dominators in corrosion-resistant marine applications. M&A activity and strategic partnerships concentrate among mid-tier fabricators seeking backward integration into fiber preform supply.
Within the vertically integrated tier, Schaeffler AG exemplifies captive supply chain control from ceramic fiber through finished bearing assembly. SKF occupies a position defined by geographic proximity advantages, sustaining technical service density in industrial machinery hubs. GGB represents specialization in polytetrafluoroethylene-based polymeric composites, anchoring marine and hydropower segments where corrosion resistance eliminates metallic alternatives. These three patterns illustrate competitive positioning vectors across material platforms and procurement economics.
| Leading Market Players |
|---|
| Schaeffler AG |
| Trelleborg AB |
| RBC Bearings Incorporated |
| AST Bearings |
| Polygon Company |
| SGL Carbon |
| SKF |
| CSB Sliding Bearings |
| GGB |
| Others |
Supply Flow & Price Mechanics
Family-owned mid-cap specialists in Germany and Japan anchor production of ceramic matrix composite bearings, their conservative balance sheets limiting capacity expansion despite aerospace OEM demand surges. This ownership pattern concentrates supply discipline among a handful of Herzogenaurach and Nagoya producers, insulating pricing from commodity volatility while creating qualification bottlenecks for new entrants seeking ASTM D3702 certification.
Pricing Analysis
Extended warranty bundling separates premium-tier suppliers from transactional competitors, with 25-year performance guarantees now standard in wind energy procurement. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation—REACH-compliant PTFE-free formulations command substantial premia over legacy polymeric composites. Cost compression in standard-tier automotive chassis bushings is intensifying because sintered bronze substitutes retain cost advantages below 150°C. Aftermarket distributors exhibit highest price sensitivity, while aerospace OEMs prioritize qualification speed over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with Japanese silicon carbide fiber producers serving ceramic matrix composite assemblers across Europe and Asia. Raw material flows draw from Chinese fluorspar mining districts, German carbon fiber preform facilities, and American PTFE resin plants. Geographic concentration in Japanese ceramic fiber production creates tariff exposure risk for European bearing fabricators dependent on METI-licensed exports. Distribution runs through technical service networks in Stuttgart, Shanghai, and Connecticut industrial corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Tribological testing infrastructure scarcity props pricing power for incumbents with in-house ASTM D3702 compliance, as mid-tier suppliers face $500,000-$800,000 certification barriers. Capacity constraints in ceramic fiber supply amplify margin protection for qualified producers.
For Market Incumbents: Acquire wear-testing rig installations to fortify certification moats against emerging Asian fabricators. Lock in multi-year offtake agreements with Japanese ceramic fiber producers before METI export licensing tightens. Prioritize backward integration into fiber preform supply to hedge single-source vulnerability in silicon carbide feedstock. For New Entrants and Emerging Players: Hydrogen infrastructure OEMs in Germany represent an underserved buyer archetype with cryogenic-compatible bearing requirements unmet by incumbent portfolios. Target valve actuator and compressor seal applications at -253°C with bio-based polyetheretherketone formulations. Pursue collaborative R&D partnerships with electrolyzer manufacturers to bypass lengthy aerospace qualification cycles. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-tier European fabricators with REACH-compliant reformulation pipelines but underutilized testing infrastructure. Five-to-ten year viability hinges on successful PTFE-free chemistry validation ahead of ECHA restriction enforcement. Monitor ECHA substance evaluation timeline acceleration as inflection indicator for consolidation urgency.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fiber Preform Supply | Captive silicon carbide fiber production insulates Schaeffler AG from Japanese export constraints. |
| REACH-Compliant Reformulation Investment | PTFE-free polyetheretherketone development secures EU market access ahead of ECHA restrictions. |
| Tribological Testing Infrastructure Expansion | In-house ASTM D3702 compliance enables 25-year warranty underwriting for Vestas and Siemens Gamesa. |
| Hydrogen Infrastructure Partnership | Cryogenic bearing qualification with German electrolyzer manufacturers opens -253°C application white space. |
| Additive Manufacturing Capability Buildout | Selective laser sintering of topology-optimized housings reduces part counts in wind turbine pitch systems. |
Methodological Framework
Multi-period observation of REACH regulatory timelines and fluorspar price volatility anchored the trend analysis, supplemented by interviews with aerospace procurement directors, automotive Tier 1 supplier engineers, wind turbine maintenance heads, and tribology laboratory managers. Secondary validation drew from ECHA substance evaluation documents, EPA TSCA Section 5 filings, MIIT standards publications, and SEC 10-K disclosures from bearing manufacturers. Bottom-up demand modeling across application segments triangulated against top-down macroeconomic indicators.
Input-output matrices mapped fiber reinforcement supply through finished bearing fabrication to end-use demand across the projection horizon. Segmentation dimensions modeled include material platform, manufacturing process technology, thermal operating envelope, and regional regulatory cluster. CAGRs derived from elasticity-adjusted volume projections incorporating substitution dynamics between polymeric, ceramic, and metal matrix alternatives. Industry-specific inputs encompassed ECHA restriction proposal timelines and aerospace OEM landing gear modernization schedules.
Revisions become necessary when ECHA accelerates PFAS restriction enforcement or Japanese ceramic fiber export licensing tightens materially. Deviation in fluorspar mining output from Chinese and Mexican districts would shift polymeric composite pricing assumptions and margin outlook substantially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Components
Global Electric Vehicle Parts and Components Market
Vehicle Components
Bicycle Brake Cable Market
Vehicle Components
Global Automotive EGR Valves Market
Vehicle Components
Global Automotive Carbon Monocoque Chassis Market
Vehicle Components
UK Automotive Glass Fiber Composites Market
Vehicle Components
Hooklift Trailer Market
Vehicle Components
Cross Roller Bearings Market
Vehicle Components
United Kingdom Vacuum Truck Market
Vehicle Components
2 Wheeler Fuel Injection System Market
Vehicle Components
HCV Axles Market
Vehicle Components
Steering Knuckle Market
Vehicle Components
Argentina Automotive Carbon Fiber Composites Market
Vehicle Components
Intelligent Rubber Tracks Market
Vehicle Components
Passenger Air Brake Market
Vehicle Components
Vehicle Radiator Market
Vehicle Components
Trailer Axle Market