
 Automotive Floor Mats Market | 2026-2036
Automotive Floor Mats Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Floor Mats Market Intelligence
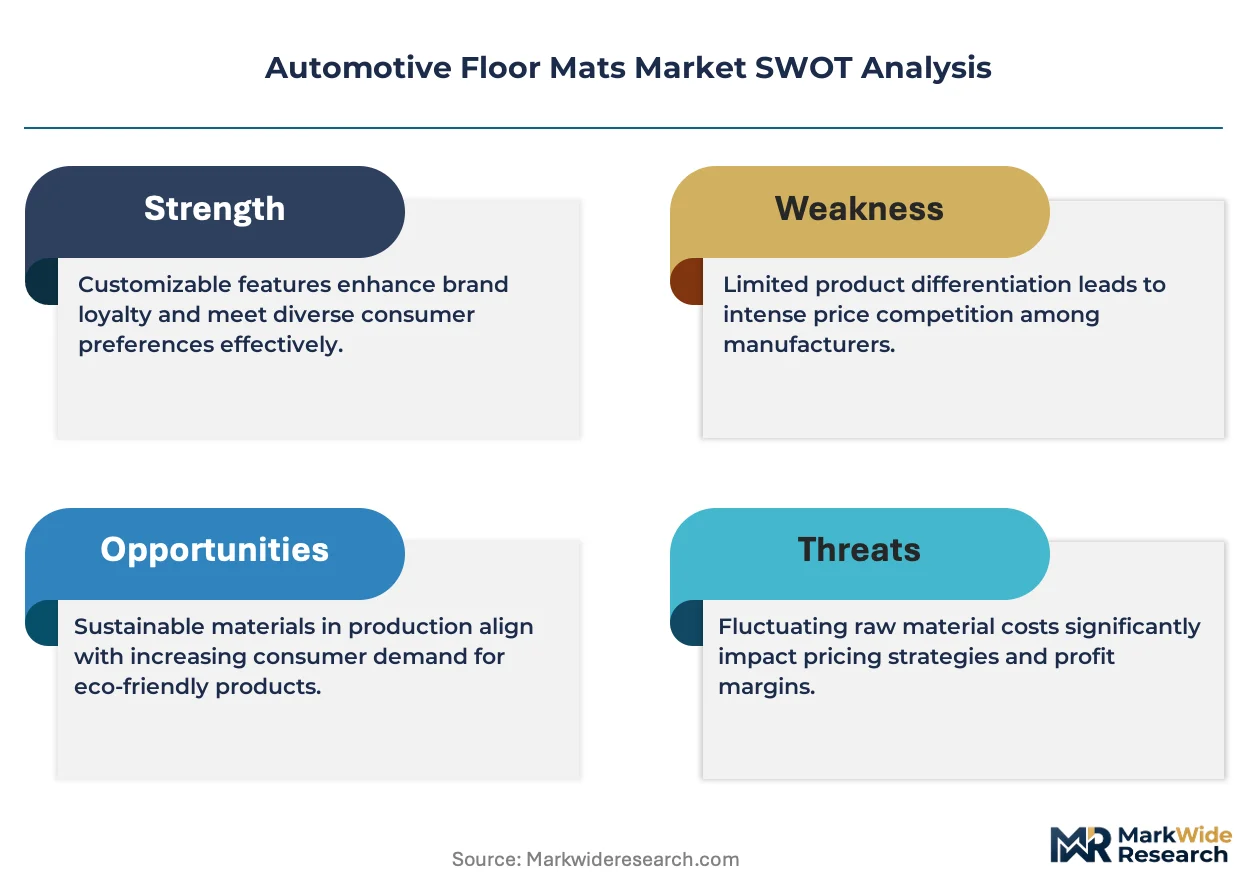
EU REACH regulation is hardening compliance thresholds for phthalates and heavy metals in rubber formulations, pushing manufacturers toward certified thermoplastic elastomers. WeatherTech leverages in-house extrusion capabilities to control compound consistency across its all-weather lines. MacNeil Automotive Products anchors its position through deep OEM relationships with Detroit-based automakers. Husky Liners specializes in laser-measured custom fits that reduce return rates and installation friction.
Automotive floor mats are protective inserts manufactured from rubber compounds, nylon carpeting, vinyl sheeting, or polypropylene mesh, typically featuring anti-slip backing, perimeter containment edges, and wear-resistant surface textures designed to shield vehicle flooring from moisture, abrasion, and debris accumulation. Rubber and all-weather pattern variants dominate commercial fleet procurement due to durability requirements and hose-down maintenance protocols. Custom-fit sizing commands margin premiums over universal configurations because dimensional precision reduces material waste and installation labor for OEM assembly lines. Polypropylene segments compete on cost efficiency in emerging-market aftermarket channels where price sensitivity overrides longevity expectations.
The US EPA oversees volatile organic compound emissions from adhesive bonding processes, while NHTSA maintains flammability standards for interior materials that constrain substrate selection. China's SAMR enforces GB standards for plasticizer content in automotive interior components, creating dual-certification burdens for multinational suppliers. Stakeholders must monitor evolving per- and polyfluoroalkyl substance restrictions across California's Department of Toxic Substances Control and the EU's ECHA candidate list, as these chemicals have historically enabled stain-resistant carpet treatments.
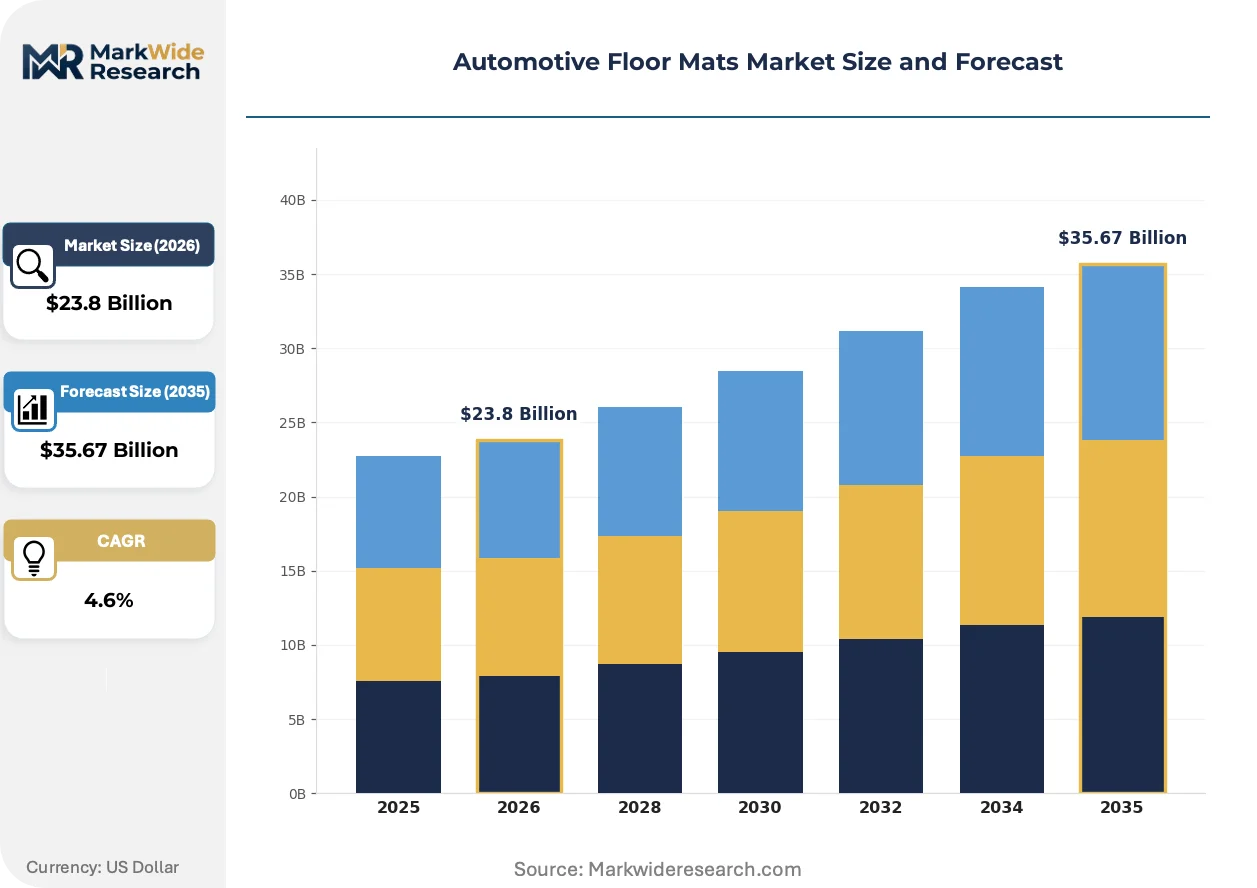
Market Dynamics
Fleet electrification and REACH-mandated material substitutions are compressing traditional rubber supply chains while elevating certified thermoplastic elastomers as the dominant substrate category for commercial vehicle pools.
Growth Catalysts
- EU REACH phthalate restrictions:Hardening compliance thresholds for heavy metals and plasticizers are redirecting formulation R&D toward certified thermoplastic elastomers that meet ECHA candidate list requirements.
- Commercial fleet standardization:Fleet operators across logistics and ride-hailing verticals are mandating all-weather rubber configurations with hose-down maintenance protocols to reduce vehicle downtime.
- Laser measurement adoption:Dimensional capture technology is enabling mass-customization at cost parity with universal mats, reducing return rates and installation labor.
Market Restraints
- Synthetic rubber price volatility:Petrochemical feedstock fluctuations and energy cost spikes in Germany and China are compressing margin structures for compound-dependent manufacturers.
- Dual-certification burdens:China's SAMR GB standards for plasticizer content create parallel compliance tracks for multinational suppliers serving both European and Chinese OEM assembly lines.
- Carpet mat substitution:Nylon carpeting retains cost advantages in price-sensitive emerging-market aftermarket channels where longevity expectations remain secondary to upfront expenditure.
Strategic Opportunities
- India aftermarket penetration:Underdeveloped organized retail infrastructure for vehicle accessories creates first-mover advantages for brands establishing direct-to-consumer digital channels.
- Per- and polyfluoroalkyl substance replacement:California DTSC and EU ECHA restrictions on stain-resistant treatments are opening formulation windows for bio-based surface coatings.
- Subscription fleet services:Vehicle-as-a-service operators require standardized protective flooring programs with consolidated procurement and replacement scheduling.
Industry Challenges
- Compound formulation expertise scarcity:Migration from traditional rubber to thermoplastic elastomers demands polymer science capabilities concentrated among a limited supplier base.
- California Proposition 65 alignment:Warning label requirements for chemical exposure create labeling complexity that slows product launches and expands liability exposure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Floor Mats Market |
| Market Size in 2026 | $23.8 Billion |
| Market Size in 2035 | $35.67 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Rubber, Carpet, Vinyl, Polypropylene Size: Standard, Custom Fit, Universal, Oversized End User: OEMs, Aftermarket Providers, Fleet Operators, Individual Consumers Pattern Type: Textured, Smooth, Branded, All-Weather |
| Companies Covered | Auto Custom Carpets, MacNeil Automotive Products, WeatherTech, Covercraft Industries, BDK Auto, Husky Liners, 3M, ExactMats, Lloyd Mats, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Floor Mats Market Strategic Shifts & Innovations
Digital measurement tools and bio-based material platforms are displacing legacy manufacturing assumptions while regulatory chemistry restrictions accelerate substrate turnover across all major automotive markets.
Digital fitment technology is decentralizing the production economics of custom automotive floor mats. Laser scanning and vehicle-specific CAD databases now enable made-to-order manufacturing at unit costs approaching mass-produced universal configurations. Tier-one suppliers are deploying these systems for OEM assembly line integration, while aftermarket channels leverage mobile measurement applications to reduce dimensional error and return processing.
REACH Annex XVII expansions are hardening enforcement against short-chain chlorinated paraffins and polycyclic aromatic hydrocarbons in rubber compounds. Formulators serving European OEMs must now document supply chain attestation for every batch, increasing testing overhead but creating competitive moats for certified compounders. North American exporters to the EU are restructuring supplier relationships to maintain market access.
Direct-to-fleet contracting is compressing traditional distribution layers for commercial vehicle protective flooring. Large logistics operators now negotiate multi-year supply agreements with manufacturers, bypassing wholesale and retail intermediaries. This pattern concentrates procurement volume among fewer buyers while demanding just-in-time inventory management and consolidated replacement scheduling across dispersed vehicle pools.
Automotive Floor Mats Market Segmentation
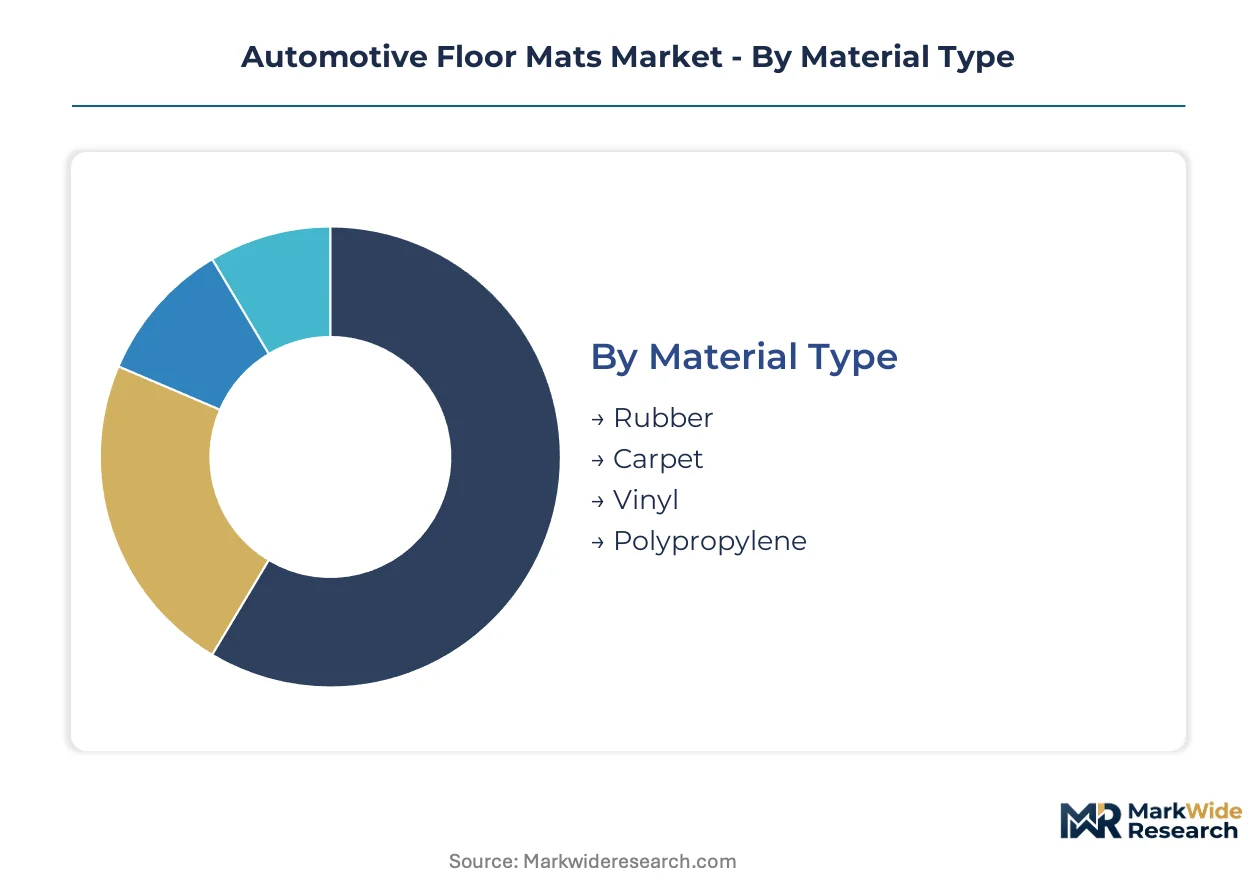
Material composition and dimensional precision determine replacement frequency and margin capture across automotive floor mat channels. Upgrade cycles accelerate where regulatory chemistry restrictions force substrate turnover or where fleet standardization mandates protective flooring refreshes.
Material Type:
Rubber formulations and carpet substrates diverge sharply in replacement economics and regulatory exposure.
- Rubber:Heavy-duty vulcanized compounds with anti-slip backing and containment edges dominate commercial fleet procurement due to hose-down maintenance protocols and extended service life. Demand concentrates among logistics operators in the United States and Germany as these markets enforce rigorous vehicle uptime requirements and worker safety standards.
- Carpet:Nylon-pile constructions with thermoplastic backing offer acoustic dampening and OEM aesthetic matching but face accelerated substitution from all-weather alternatives in high-moisture climates. Cost advantages sustain volume in price-sensitive aftermarket channels where longevity expectations remain secondary to upfront expenditure.
- Vinyl:Calendered PVC sheets with embossed surface textures provide chemical resistance and color stability for service vehicle applications.
- Polypropylene:Injection-molded mesh structures compete on raw material efficiency and recyclability credentials in emerging-market manufacturing.
Volume placements concentrate in rubber configurations; the faster expansion belongs to polypropylene as sustainability mandates reshape material procurement.
Size:
Dimensional strategy separates assembly-line economics from aftermarket convenience premiums.
- Custom Fit:Laser-measured profiles derived from vehicle-specific CAD databases eliminate installation labor and return processing for OEM integration. Precision manufacturing commands margin premiums over universal alternatives as dimensional accuracy reduces material waste and warranty claims.
- Universal:Trim-to-fit dimensions with multi-position anchoring systems maximize inventory turns across fragmented aftermarket retail. Price positioning sustains volume in developing markets where organized service networks remain underdeveloped.
- Standard:Fixed-dimension formats optimized for high-volume vehicle platforms balance tooling efficiency with coverage adequacy.
- Oversized:Extended perimeter dimensions for commercial vans and heavy-duty trucks accommodate cargo-area protection requirements.
Universal formats dominate unit shipments; custom-fit applications climb fastest as digital measurement tools democratize precision manufacturing.
End User:
Procurement authority and replacement scheduling discipline vary sharply across buyer categories.
- Fleet Operators:Multi-year supply agreements with consolidated replacement scheduling across dispersed vehicle pools compress distribution layers and demand just-in-time inventory management. Direct contracting patterns concentrate volume among logistics and ride-hailing operators with standardized protective flooring programs.
- OEMs:Assembly-line integration requires dimensional precision, color matching, and regulatory batch documentation for every production run. Supplier relationships anchor on compound certification and capacity guarantees rather than spot purchasing.
- Aftermarket Providers:Wholesale and retail intermediaries serve fragmented demand through inventory breadth and installation services.
- Individual Consumers:Digital channels and mobile measurement applications reduce search costs and dimensional error for replacement purchases.
Fleet contracting captures the highest procurement volume; individual consumer digital adoption expands most quickly as direct-to-customer platforms displace traditional retail.
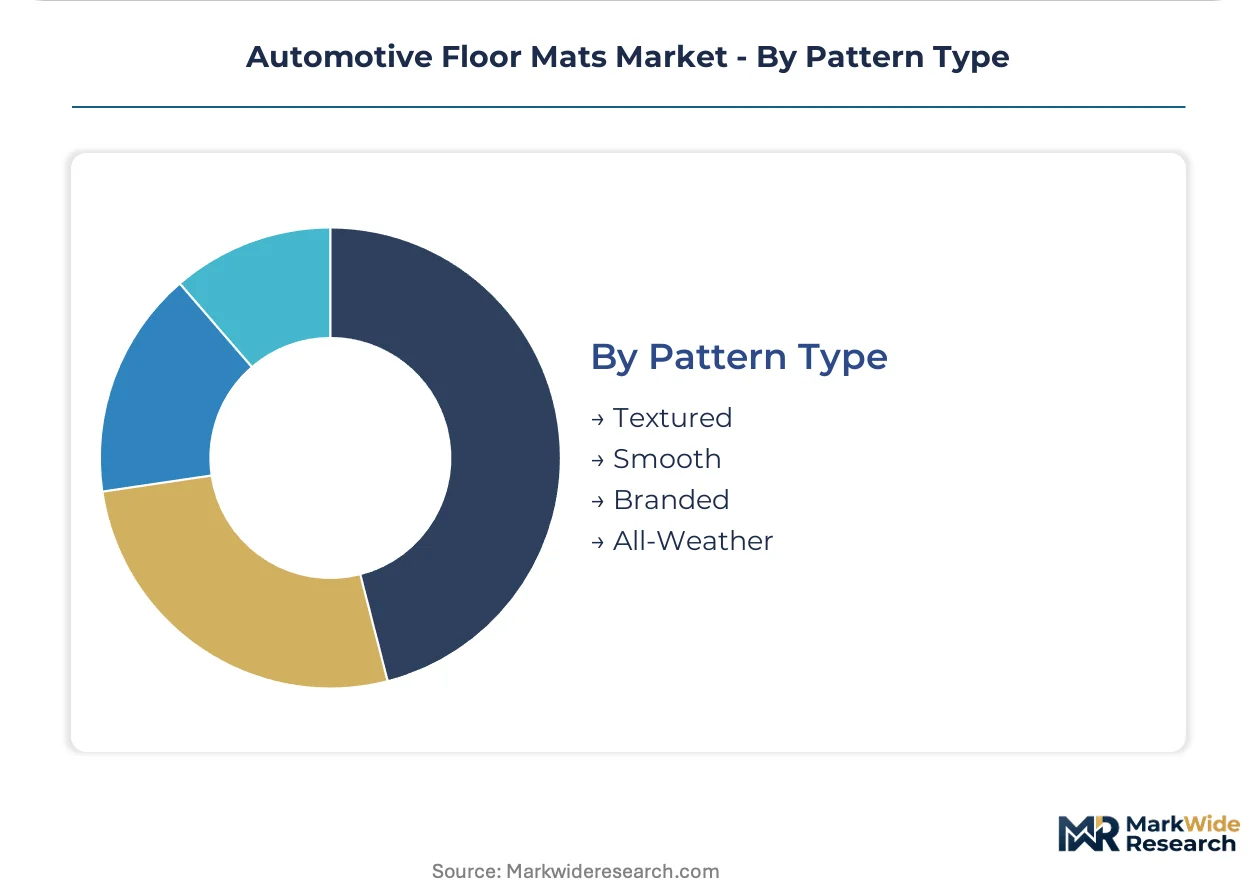
Pattern Type:
Surface engineering balances traction performance, aesthetic differentiation, and manufacturing complexity.
- All-Weather:Deep-channel drainage designs with perimeter containment edges manage snow, slush, and debris accumulation in severe climates. Specifications dominate northern-tier United States and German markets where seasonal weather exposure accelerates replacement cycles.
- Textured:Embossed or molded surface patterns enhance slip resistance and hide wear patterns in high-traffic driver positions. Functional benefits sustain preference among safety-conscious fleet managers and individual owners.
- Smooth:Flat-surface configurations minimize manufacturing complexity and material usage for economy-tier positioning.
- Branded:Licensed designs and manufacturer logos serve accessory personalization demand in premium aftermarket channels.
Textured patterns hold the largest installed base; all-weather configurations gain share fastest as climate volatility intensifies protective flooring requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Detroit anchors North American automotive floor mat manufacturing through its dense concentration of OEM assembly plants and tier-one supplier networks. The metropolitan corridor channels protective flooring demand from legacy automakers and emerging EV manufacturers alike.
United States
Logistics fleet operators in the Midwest and Southeast mandate all-weather rubber configurations with hose-down maintenance protocols to minimize vehicle downtime. NHTSA flammability standards for interior materials constrain substrate selection across domestic OEM assembly lines. The Detroit-Warren-Dearborn corridor concentrates compound formulation expertise and laser-measurement manufacturing capabilities.
Germany
Commercial vehicle pools across Bavaria and North Rhine-Westphalia enforce rigorous worker safety standards that elevate durable rubber specifications. REACH Annex XVII restrictions on short-chain chlorinated paraffins and polycyclic aromatic hydrocarbons force batch-level supply chain attestation. The Stuttgart industrial region hosts precision manufacturing clusters serving premium OEM fitment requirements.
China
Domestic automakers in the Yangtze River Delta and Pearl River Delta drive volume demand for cost-efficient polypropylene mesh configurations. SAMR enforces GB standards for plasticizer content that create dual-certification burdens for multinational suppliers. Shanghai's automotive supplier ecosystem integrates digital measurement tools for mass-customization at scale.
India
Price-sensitive aftermarket channels in Maharashtra and Gujarat sustain nylon carpeting volume despite accelerated all-weather substitution in fleet segments. BIS certification requirements for automotive interior components elevate quality thresholds for organized retail penetration. The Pune-Nashik industrial corridor attracts compound-dependent manufacturers seeking lower energy costs.
Japan
OEM assembly lines in the Toyota City-Nagoya corridor demand dimensional precision and color matching for just-in-time protective flooring integration. METI industrial standards emphasize material traceability and recyclability credentials in supplier qualification. The Kanto region around Tokyo concentrates aftermarket distribution networks serving individual consumer replacement cycles.
Automotive Floor Mats Market Key Industry Players
Premium-margin players sit above commodity-margin players across material certification and dimensional precision capabilities. The vendor base stratifies between compound-certified specialists serving OEM assembly lines and price-positioned fabricators targeting fragmented aftermarket channels. Three archetypes dominate: laser-measurement custom-fit specialists, REACH-certified thermoplastic elastomer compounders, and scale-driven universal mat producers. Consolidation pressure operates through direct-to-fleet contracting that compresses wholesale intermediaries, while backward integration into extrusion capabilities separates quality-tier competitors.
Within the precision-fit tier, WeatherTech and Husky Liners occupy positions defined by in-house manufacturing control and vehicle-specific database depth. MacNeil Automotive Products exemplifies the OEM-anchored archetype through its Detroit-based automaker relationships. Among diversified industrial conglomerates, 3M represents the materials science platform approach that spans adhesive bonding and surface treatment technologies beyond standalone mat production.
| Leading Market Players |
|---|
| Auto Custom Carpets |
| MacNeil Automotive Products |
| WeatherTech |
| Covercraft Industries |
| BDK Auto |
| Husky Liners |
| 3M |
| ExactMats |
| Lloyd Mats |
| Others |
Cost & Logistics Intelligence
Polymer science expertise concentration in the Stuttgart industrial region feeds labor-cost differentials that separate REACH-certified compound premiums from commodity rubber pricing tiers across European and North American markets.
Pricing Analysis
Fleet uptime value anchors pricing power for all-weather rubber configurations that minimize vehicle downtime through hose-down maintenance protocols. Three-tier pricing structure across premium laser-fit, standard OEM-specified, and economy universal levels stratifies by dimensional precision and compound certification grade. Cost compression in commodity polypropylene segments intensifies as Chinese manufacturers scale injection-molded mesh production for price-sensitive aftermarket channels. Individual consumers exhibit highest price sensitivity while fleet operators prioritize total cost of ownership over unit expenditure.
Supply Chain Analysis
Freight cost differentials between Asian manufacturing hubs and European assembly plants compound margin pressure for compound-dependent suppliers serving just-in-time OEM integration. Raw material sourcing concentrates in Germany, China, and the United States for synthetic rubber feedstocks, thermoplastic elastomer resins, and polypropylene pellets. Supply chains draw from petrochemical complexes vulnerable to energy price volatility and ECHA REACH batch-attestation documentation burdens. Distribution runs through direct-to-fleet contracting that compresses wholesale intermediaries for commercial vehicle pools.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where captive control over extrusion capabilities and compound formulation separates margin tiers from commodity positioning.
For Market Incumbents: Lock in supply security by securing certified thermoplastic elastomer compound capacity ahead of REACH-mandated substitution deadlines. Deepen backward integration into laser-measurement manufacturing to defend against digital-fitment specialists eroding custom-fit premiums. Prioritize batch-level documentation systems that satisfy ECHA attestation requirements for European OEM assembly line access. For New Entrants and Emerging Players: Subscription fleet services represent the most penetrable buyer archetype for protective flooring programs with consolidated procurement and replacement scheduling. Target direct-to-consumer digital channels in India's underdeveloped organized retail infrastructure where mobile measurement applications reduce dimensional error. Pursue bio-based surface coating formulations as California DTSC and EU ECHA restrictions eliminate legacy stain-resistant treatments. For Investors and Strategic Acquirers: Re-rating potential sits with REACH-certified compounders given regulatory chemistry restrictions that create supply scarcity and pricing power. Long-term viability favors manufacturers with demonstrated polymer science capabilities and OEM relationship depth rather than pure-play aftermarket fabricators. Monitor fleet electrification adoption curves as inflection indicators for protective flooring refresh cycles across commercial vehicle pools.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Extrusion Capabilities | WeatherTech's in-house compound control demonstrates margin capture through quality consistency. |
| Direct-to-Fleet Contracting | Logistics operators bypass wholesale intermediaries, concentrating volume among fewer buyers. |
| Digital Measurement Platform Deployment | Laser-scanning CAD databases enable mass-customization at universal-mat cost parity. |
| REACH-Certified Compound Investment | ECHA batch attestation creates competitive moats against uncertified rubber formulators. |
| Bio-Based Surface Coating Development | California DTSC and EU restrictions on per- and polyfluoroalkyl substances open formulation windows. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by primary interviews with OEM platform engineers, Tier 1 supplier procurement leads, aftermarket distribution heads, and fleet operations managers. Secondary sources included vehicle production databases, ECHA REACH substance restriction updates, SAMR GB standard documentation, and customs import records for rubber compound classifications. Bottom-up segmentation modeling triangulated against top-down market sizing from automotive production forecasts.
Granularity-level modeling operated at material-type, dimensional-precision, and end-user archetype dimensions across the analysis window. CAGRs derived from regression analysis of historical replacement cycles, fleet expansion patterns, and regulatory substitution timelines. Vehicle class and propulsion architecture splits informed content-per-vehicle assumptions for protective flooring penetration rates.
Revisions become necessary when REACH Annex XVII expands restricted substance lists, fleet electrification accelerates vehicle refresh cycles, or energy price volatility disrupts petrochemical feedstock costs. Forecasts reflect documented assumptions about regulatory enforcement consistency and OEM sourcing stability. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Interior & Exterior
Automotive Grab Handle Market
Automotive Interior & Exterior
Automotive Display Market
Automotive Interior & Exterior
Automotive Roof Liners Market
Automotive Interior & Exterior
All Plastic Front End Module Market
Automotive Interior & Exterior
Automotive Woven Upholstery Market
Automotive Interior & Exterior
Brazil Automotive Flooring Market
Automotive Interior & Exterior
Automotive Climate Control Market
Automotive Interior & Exterior
Global Headliner (OE) Market
Automotive Interior & Exterior
Automotive Grill Guard Market
Automotive Interior & Exterior
Automotive Lighting Market
Automotive Interior & Exterior
Automotive Seat Recliners Market
Automotive Interior & Exterior
Automotive Mirror Dimming Market
Automotive Interior & Exterior
Automotive Films Market
Automotive Interior & Exterior
Automotive Fascia Market
Automotive Interior & Exterior
Automotive Active Spoiler Market
Automotive Interior & Exterior
Asia-Pacific Automotive Flooring Market