
 Rear-View Mirror Market | 2026-2036
Rear-View Mirror Market Size, Share, and Industry Trends Forecast 2026-2036
Rear-View Mirror Market Intelligence
Automotive OEM supply contracts is rewriting how tier-one mirror suppliers secure long-term revenue. Gentex Corporation leverages its electrochromatic expertise to sustain premium pricing in North American light-vehicle programs. Magna International anchors global production through integrated glass and electronics manufacturing across multiple continents. Ficosa International competes on module complexity, supplying folding and dimming mechanisms to European and Asian vehicle platforms.
A rear-view mirror is an optical safety device mounted inside or outside a vehicle, typically comprising glass substrate, reflective coating, polymer housing, and electronic actuators for power adjustment and dimming, designed to provide the driver with a field of view of the rear roadway without head rotation. Camera-based and electrochromatic variants now command the highest engineering investment as automakers integrate display streams and automatic glare suppression into unified cockpit electronics. Passenger vehicle OEM channels dominate volume, while aftermarket providers capture margin in replacement cycles for aging vehicle populations. Fleet operators represent a concentrated demand pocket where camera-based technology reduces blind-spot liability exposure in commercial logistics.
NHTSA rear-visibility standards, ECE R46 mirror regulations, and China's GB 15084 standard collectively dictate field-of-view angles, mounting durability, and electronic reliability thresholds that determine product certification and market access. The EU AI Act and emerging software-type approval frameworks in Germany and France are extending compliance obligations to camera-based mirror systems with embedded object detection algorithms. Stakeholders must monitor how regulatory divergence between camera-permissive and mirror-mandated jurisdictions reshapes product platform strategies and localization decisions.
Market Dynamics
The rear-view mirror market is pivoting on camera-based mirror replacements as automakers dismantle traditional glass-and-housing architectures in favor of unified cockpit electronics streams. This technology shift compresses component counts while expanding field-of-view capabilities beyond physical mirror constraints.
Growth Catalysts
- NHTSA rear-visibility mandates:Expanded field-of-view requirements in the United States are compelling OEMs to adopt camera-based systems that eliminate blind spots inherent in conventional mirror designs.
- China's GB 15084 standard evolution:Regulatory acceptance of camera monitor systems is accelerating domestic EV manufacturer procurement of digital mirror replacements at production scale.
- Electrochromatic dimming integration:Automatic glare suppression technology is migrating from premium segments into mass-market light-vehicle programs as sensor fusion costs decline.
Market Restraints
- Glass substrate cost volatility:Float glass and specialized reflective coating materials expose suppliers to energy-intensive production cost swings in European and Asian manufacturing hubs.
- Regulatory fragmentation:Divergent mirror-mandated versus camera-permissive jurisdictions force parallel product platform maintenance, inflating engineering overhead for global programs.
- Mirrorless system substitution limits:Commercial fleet operators in liability-sensitive logistics segments retain conventional mirrors pending comprehensive insurance framework updates for camera-only configurations.
Strategic Opportunities
- Software-type approval pathways:Germany's KBA and France's CNIL are developing embedded algorithm certification frameworks that create first-mover advantage for camera systems with integrated object detection.
- Fleet aftermarket channel expansion:Aging vehicle populations in North America are extending replacement cycles for power-adjustment and dimming mechanisms through independent service providers.
- EV platform standardization:Dedicated electric vehicle architectures are eliminating traditional mirror mounting points, enabling clean-sheet camera monitor system design without legacy hardware accommodation.
Industry Challenges
- Functional safety engineer scarcity:ISO 26262 compliance for camera-based systems requires specialized automotive electronics expertise concentrated among tier-one suppliers.
- Multi-jurisdiction certification timelines:Simultaneous NHTSA, ECE R46, and GB 15084 approval processes extend product launch windows by 18-24 months.
- Legacy vehicle integration complexity:Retrofit camera monitor systems must interface with aging CAN bus architectures without full electronics platform replacement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rear-View Mirror Market |
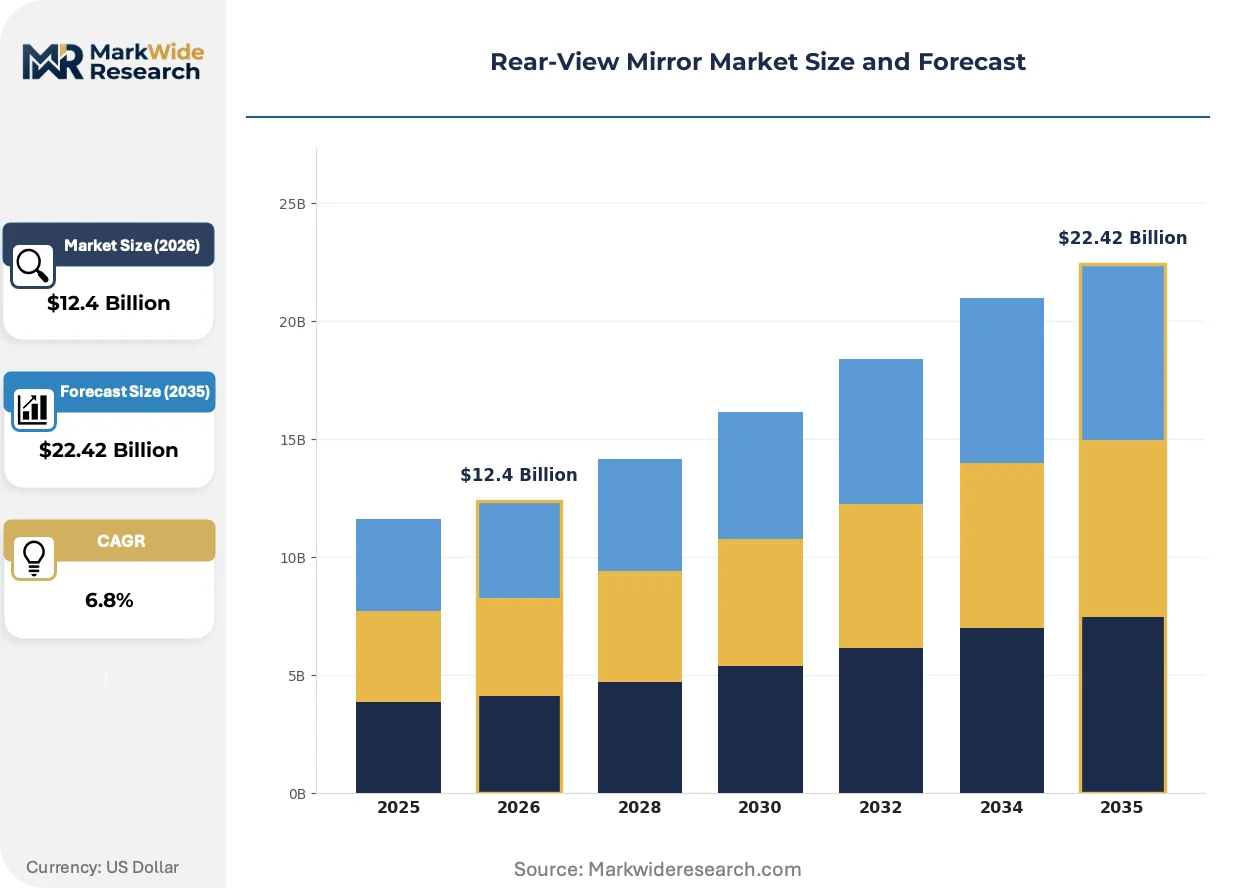
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $22.42 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard, Electrochromatic, Digital, Camera-Based Application: Passenger Vehicles, Commercial Vehicles, Motorcycles, Heavy-Duty Trucks Technology: LED, LCD, Optical, Advanced Driver Assistance Systems Customer Type: OEMs, Aftermarket Providers, Retailers, Fleet Operators |
| Companies Covered | Gentex Corporation, Magna International, Ficosa International, Continental AG, Valeo, Murakami Corporation, Samvardhana Motherson Reflectec, SL Corporation, Ishizaki Holdings, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rear-View Mirror Market Strategic Shifts & Innovations
Camera-based mirror technology is collapsing the boundary between exterior visibility hardware and interior display electronics. This convergence is redrawing supplier relationships and compressing the value chain into integrated cockpit system providers.
Camera monitor systems are migrating from glass substrate and polymer housing assemblies toward solid-state image sensors and OLED display streams. Luxury and performance EV manufacturers are specifying these configurations to reduce aerodynamic drag and wind noise. The technology is migrating from premium segment exclusivity into mid-range vehicle programs as sensor costs fall below critical thresholds.
ECE R46 mirror regulations are undergoing revision across EU member states to accommodate camera-based visibility systems in commercial and passenger vehicle categories. Germany's KBA and France's transport ministry are coordinating software-type approval procedures for embedded object detection algorithms. European OEMs are responding by pre-certifying unified cockpit electronics platforms that satisfy both conventional mirror and camera monitor compliance pathways.
Fleet procurement patterns are consolidating around total cost of ownership calculations that incorporate blind-spot liability exposure. Commercial logistics operators are specifying camera-based systems through direct supplier relationships rather than OEM option packages. This behavior is most visible in long-haul trucking corridors across the United States where insurance underwriters are adjusting premium structures for mirrorless configurations.
Rear-View Mirror Market Segmentation
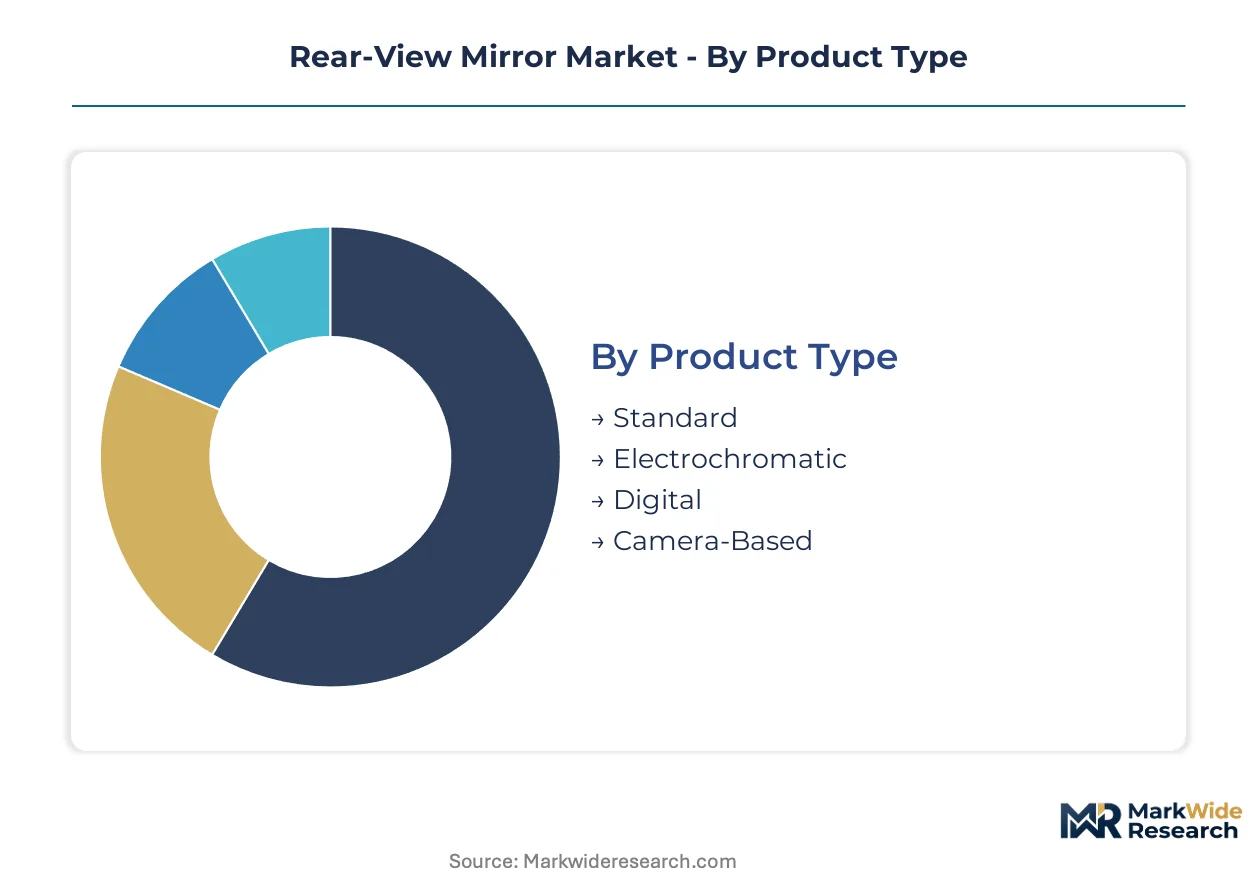
Rear-view mirror procurement splits across fundamentally different value chains. OEMs negotiate multi-year supply agreements for integrated cockpit systems, while aftermarket channels serve fragmented replacement demand across aging vehicle populations.
Product Type:
Mature glass-and-housing architectures coexist with emerging solid-state imaging platforms, creating parallel engineering investments.
- Standard:Conventional glass substrate with polymer housing remains the baseline specification for economy vehicle programs and commercial fleet procurement. Demand concentrates in India and Brazil where cost-sensitive OEMs prioritize mechanical reliability over electronic feature integration.
- Electrochromatic:Automatic glare suppression through electrochromic gel layers between glass substrates commands premium positioning in North American light-vehicle programs. Gentex Corporation anchors supply contracts with Detroit Three automakers seeking differentiation through nighttime driving comfort.
- Digital:LCD-integrated interior mirrors displaying rear camera feeds are penetrating mid-range segments as display costs decline. Japanese OEMs specify these configurations for hybrid vehicle lines targeting urban commuter demographics.
- Camera-Based:Solid-state exterior cameras with interior OLED streams eliminate physical mirror mass entirely.
Standard mirrors retain volume leadership; camera-based systems hold the steepest expansion curve.
Application:
Vehicle class determines regulatory pathway and liability exposure, shaping technology adoption speed.
- Passenger Vehicles:Light-duty OEM programs specify integrated dimming and camera monitor systems through tier-one supplier relationships. China's NEV manufacturers are accelerating camera-based procurement ahead of GB 15084 standard evolution.
- Commercial Vehicles:Fleet operators in long-haul trucking corridors calculate total cost of ownership including blind-spot liability exposure. Insurance underwriters in the United States are adjusting premium structures for mirrorless configurations.
- Motorcycles:Handlebar-mounted and fairing-integrated mirrors face vibration durability requirements distinct from automotive specifications.
- Heavy-Duty Trucks:Extended hood lengths create acute blind-spot challenges addressed through multi-camera surround-view systems.
Passenger vehicles dominate unit volume; heavy-duty trucks show the most rapid technology displacement.
Technology:
Display and sensor architectures are converging toward unified cockpit electronics platforms.
- LED:Indicator integration for turn signals and blind-spot warnings penetrates mass-market segments through simplified assembly processes.
- LCD:Thin-film transistor backplanes enable frameless mirror designs with embedded display zones.
- Optical:Prism-based and wide-angle glass formulations address field-of-view mandates without electronic complexity.
- Advanced Driver Assistance Systems:Embedded object detection algorithms require ISO 26262 functional safety certification and software-type approval under Germany's KBA frameworks.
Optical solutions maintain cost advantage; ADAS integration is climbing fastest among technology categories.
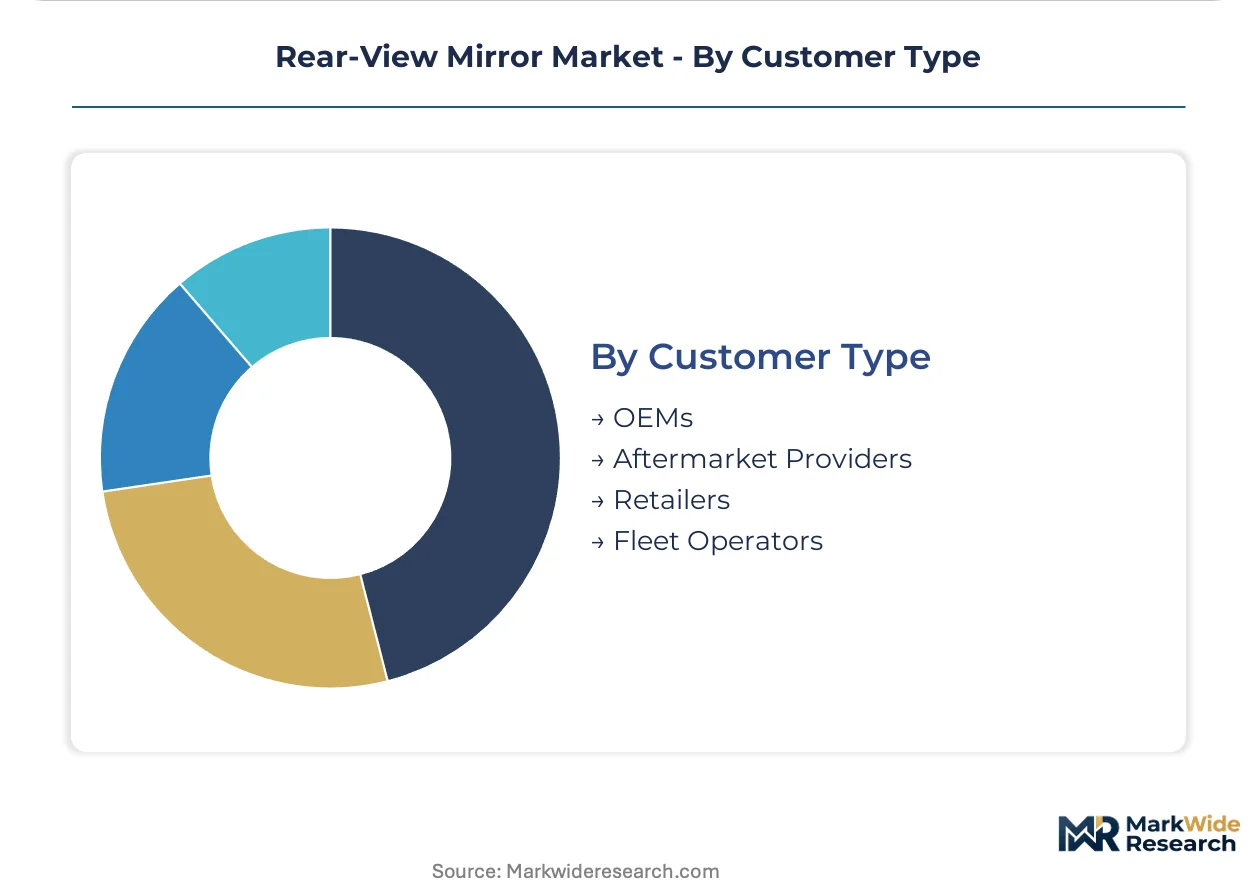
Customer Type:
Procurement authority determines specification control and margin capture location in the value chain.
- OEMs:Direct supply relationships with tier-one mirror manufacturers lock in multi-year pricing for electrochromatic and camera-based systems. NHTSA rear-visibility mandates are expanding specification authority for visibility system architects.
- Aftermarket Providers:Independent service networks capture replacement demand for power-adjustment mechanisms and glass substrate damage.
- Retailers:E-commerce channels and auto parts chains serve DIY installation segments with universal-fit mirror assemblies.
- Fleet Operators:Commercial logistics procurement teams negotiate direct supplier relationships bypassing OEM option packages.
OEMs command specification authority; fleet operators are gaining procurement sophistication fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
NHTSA rear-visibility mandates in the United States are reshaping procurement patterns across multiple geographies. Camera-based mirror systems are displacing conventional architectures in jurisdictions with regulatory alignment.
United States
Detroit Three automakers are consolidating electrochromatic supply contracts under expanded field-of-view requirements. NHTSA compliance deadlines are compressing tier-one supplier qualification timelines. Michigan and Ohio manufacturing corridors host concentrated mirror system assembly for light-vehicle programs.
China
Domestic NEV manufacturers are specifying camera monitor systems at production scale ahead of GB 15084 standard evolution. MIIT certification pathways are accelerating software-type approval for embedded visibility algorithms. Yangtze River Delta electronics clusters are scaling solid-state image sensor output for mirror replacement programs.
Germany
Premium OEMs are pre-certifying unified cockpit electronics platforms for dual mirror and camera compliance. KBA software-type approval frameworks are extending to embedded object detection algorithms. Baden-Württemberg automotive electronics suppliers are integrating display streams into interior mirror assemblies.
Japan
Hybrid vehicle lines are specifying LCD-integrated interior mirrors for urban commuter demographics. METI safety technology roadmaps are aligning with ECE R46 revision timelines. Nagoya-area tier-one suppliers are migrating frameless mirror designs into mid-range programs.
South Korea
Domestic automakers are adopting LED indicator integration for mass-market turn signal and blind-spot warning systems. MFDS automotive electronics guidelines are converging with ISO 26262 functional safety requirements. Seoul Capital Area manufacturing complexes are scaling thin-film transistor backplane production for display-embedded mirrors.
Rear-View Mirror Market Key Industry Players
Electrochromatic specialists and integrated cockpit system providers split the market along technology architecture lines. Tier-one mirror manufacturers anchor supply relationships through multi-year OEM contracts. Three archetypes dominate: glass substrate fabricators, electronics integration platforms, and camera monitor system architects. Competitive moves concentrate on strategic partnerships for sensor fusion capabilities and geographic expansion into NEV manufacturing clusters.
Within the electronics integration tier, Gentex Corporation and Magna International exemplify divergent scale strategies. Ficosa International occupies a position among European module complexity specialists. Gentex represents the electrochromatic premium-positioning archetype. Magna anchors the vertically integrated manufacturing model across multiple continents. Ficosa exemplifies the folding and dimming mechanism specialization vector serving platform diversity requirements.
| Leading Market Players |
|---|
| Gentex Corporation |
| Magna International |
| Ficosa International |
| Continental AG |
| Valeo |
| Murakami Corporation |
| Samvardhana Motherson Reflectec |
| SL Corporation |
| Ishizaki Holdings |
| Others |
Cost & Logistics Intelligence
The Yangtze River Delta freight corridor's container cost dynamics amplify pricing power for electrochromatic specialists while compressing margins on standard glass substrate assemblies. Supply concentration in Chinese solid-state sensor manufacturing feeds downstream price differentiation between camera-based configurations and conventional mirror architectures.
Pricing Analysis
The customization-premium spread separates configured-to-order camera monitor systems from standard glass-and-housing assemblies by a factor reflecting ISO 26262 certification investment and software-type approval costs. Three-tier pricing structure across premium electrochromatic, standard power-adjustment, and economy mechanical tiers stratifies procurement across OEM program levels. Cost compression in the economy tier intensifies as Indian and Brazilian OEMs consolidate volume around mechanical reliability specifications. Fleet operators in North American long-haul corridors demonstrate the lowest price sensitivity due to liability exposure calculations, while aftermarket retailers serving DIY replacement segments face acute margin pressure.
Supply Chain Analysis
Export-control regimes limiting solid-state image sensor flows from Yangtze River Delta clusters to European assembly plants constrain camera-based system output expansion. Geographic supply concentration centers on China for display backplanes and image sensors, Germany for electrochromic gel formulations, and Japan for precision glass substrates. Raw material dependencies include float glass from Asahi, indium tin oxide coatings, and specialized polymer housings. Single-source vulnerability in OLED display driver ICs from South Korean foundries threatens production continuity for digital mirror programs. Distribution runs through tier-one supplier direct contracts with OEM platform engineering teams, bypassing traditional aftermarket channels for camera-based configurations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among Detroit Three and Chinese NEV procurement teams, fragmenting specification authority away from traditional tier-one mirror suppliers toward integrated cockpit system architects.
For Market Incumbents: Entrench electrochromatic supply relationships through backward integration into gel formulation production and exclusive multi-year contracts with North American light-vehicle programs. Camera monitor system entrants from consumer electronics backgrounds threaten premium positioning; defend through ISO 26262 certification investment and KBA software-type approval pre-clearance for embedded object detection algorithms. For New Entrants and Emerging Players: Mid-market Japanese hybrid vehicle lines represent the most penetrable entry point for LCD-integrated interior mirror configurations, as these OEMs prioritize urban commuter comfort features over full camera replacement. European commercial fleet direct procurement channels offer secondary white-space access, particularly where insurance underwriters have adjusted premium structures for mirrorless configurations. Go-to-market execution should emphasize total cost of ownership modeling that incorporates blind-spot liability exposure reduction. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified automotive electronics parents seeking to divest non-core mirror module operations amid cockpit integration trends. Long-term viability over the next decade hinges on camera-based system certification breadth across NHTSA, ECE R46, and GB 15084 pathways. Monitor ECE R46 revision adoption velocity across EU member states as the critical inflection signal for technology displacement timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | Dedicated EV architectures from Chinese NEV manufacturers eliminate traditional mirror mounting points entirely. |
| Software-Type Approval Investment | Germany's KBA certification for embedded object detection algorithms creates defensible regulatory moats. |
| Backward Integration | In-house electrochromic gel production secures margin capture against float glass cost volatility. |
| Fleet Direct Procurement Channel | Bypassing OEM option packages captures commercial logistics operators calculating liability exposure. |
| Geographic Manufacturing Footprint | Michigan and Ohio corridors anchor NHTSA-compliant assembly for Detroit Three program volume. |
Research Approach
Cross-validation between tier-one supplier procurement disclosures and OEM platform engineering specifications anchors the qualitative findings on technology migration timelines. Primary interviews with mirror system R&D directors, automotive electronics integration specialists, fleet procurement managers, and insurance underwriting officers combined with secondary validation from NHTSA rulemaking dockets, ECE R46 revision documents, GB 15084 standard drafts, and vehicle production registration databases. Bottom-up bill-of-materials analysis and top-down OEM program content assumptions triangulate market sizing.
Calibration against historical adoption curves for automotive electronics integration governs the projection framework across the analysis window. Segmentation dimensions modeled include product architecture, vehicle class, propulsion type, and regional regulatory cluster. CAGRs derive from fitted diffusion curves for camera-based system penetration, adjusted for multi-jurisdiction certification timeline delays. Industry-specific inputs encompass electrochromatic content per vehicle trajectories and fleet operator liability cost calculations.
Macroeconomic conditions sit as an overlay; deviation in automotive production volumes, semiconductor availability, and freight cost indices would shift the trajectory. Forecasts reflect documented assumptions on regulatory harmonization timing and technology cost reduction curves. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Interior & Exterior
Automotive Floor Carpet Market
Automotive Interior & Exterior
Automotive Windshield Market
Automotive Interior & Exterior
North America Automotive Seat Market
Automotive Interior & Exterior
Seat Comfort and Lumbar Actuator Systems Market
Automotive Interior & Exterior
Automotive Floor Mats Market
Automotive Interior & Exterior
Heated Windshield Market
Automotive Interior & Exterior
Car Covers Market
Automotive Interior & Exterior
Automotive Rocker Panel Market
Automotive Interior & Exterior
Asia-Pacific Automotive Flooring Market
Automotive Interior & Exterior
Automotive Intelligent Rear-View Mirror Market
Automotive Interior & Exterior
Automotive Upholstery Market
Automotive Interior & Exterior
Asia Pacific Automotive Interiors Market
Automotive Interior & Exterior
Sun Visor Market
Automotive Interior & Exterior
Automotive Convertible Top Market
Automotive Interior & Exterior
Automotive Door Seal Market
Automotive Interior & Exterior
North America Automotive Upholstery Market