
 Automotive Exterior Smart Lighting Market | 2026-2036
Automotive Exterior Smart Lighting Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Exterior Smart Lighting Market Analysis
The EU General Safety Regulation is rebalancing investment toward pedestrian-protective adaptive beam technologies across European vehicle platforms. Valeo Group leverages its matrix LED portfolio to anchor premium OEM contracts in France and Germany. Koito Manufacturing Co., Ltd sustains R&D intensity in laser headlamp modules for Japanese luxury marques. HELLA KGaA Hueck & Co. competes through specialized adaptive lighting control systems that integrate with advanced driver-assistance architectures.
Automotive exterior smart lighting encompasses electronically controlled illumination systems mounted on vehicle exteriors, typically employing semiconductor-based emitters with photometric outputs ranging from 1,000 to 3,000 lumens and color temperatures of 5,000-6,000 Kelvin for headlamp applications, designed to enhance visibility, communicate vehicle intent, and enable active safety interventions. LED Headlights occupy the dominant revenue position due to universal OEM fitment mandates and declining per-unit costs at manufacturing scale. Matrix LED technology captures the fastest expansion trajectory as regulatory frameworks in multiple jurisdictions permit pixel-level beam shaping that reduces glare for oncoming traffic while maintaining road illumination.
NHTSA in the United States, ECE R48 in Europe, and GB standards under China's SAMR collectively define photometric performance, electromagnetic compatibility, and software integrity requirements that determine market access for smart lighting suppliers. The EU AI Act introduces additional compliance layers for lighting systems incorporating machine-vision-based adaptive control. Stakeholders must monitor divergence between NHTSA's pending adaptive driving beam rulemaking and ECE provisions already permitting matrix operation, as this regulatory asymmetry will shape regional product development prioritization and capital allocation across engineering centers.
Market Dynamics
Matrix LED beam-shaping capabilities are compressing development cycles across automotive lighting supply chains as regulatory frameworks in Germany, Japan, and China simultaneously enable pixel-level glare reduction protocols.
Growth Catalysts
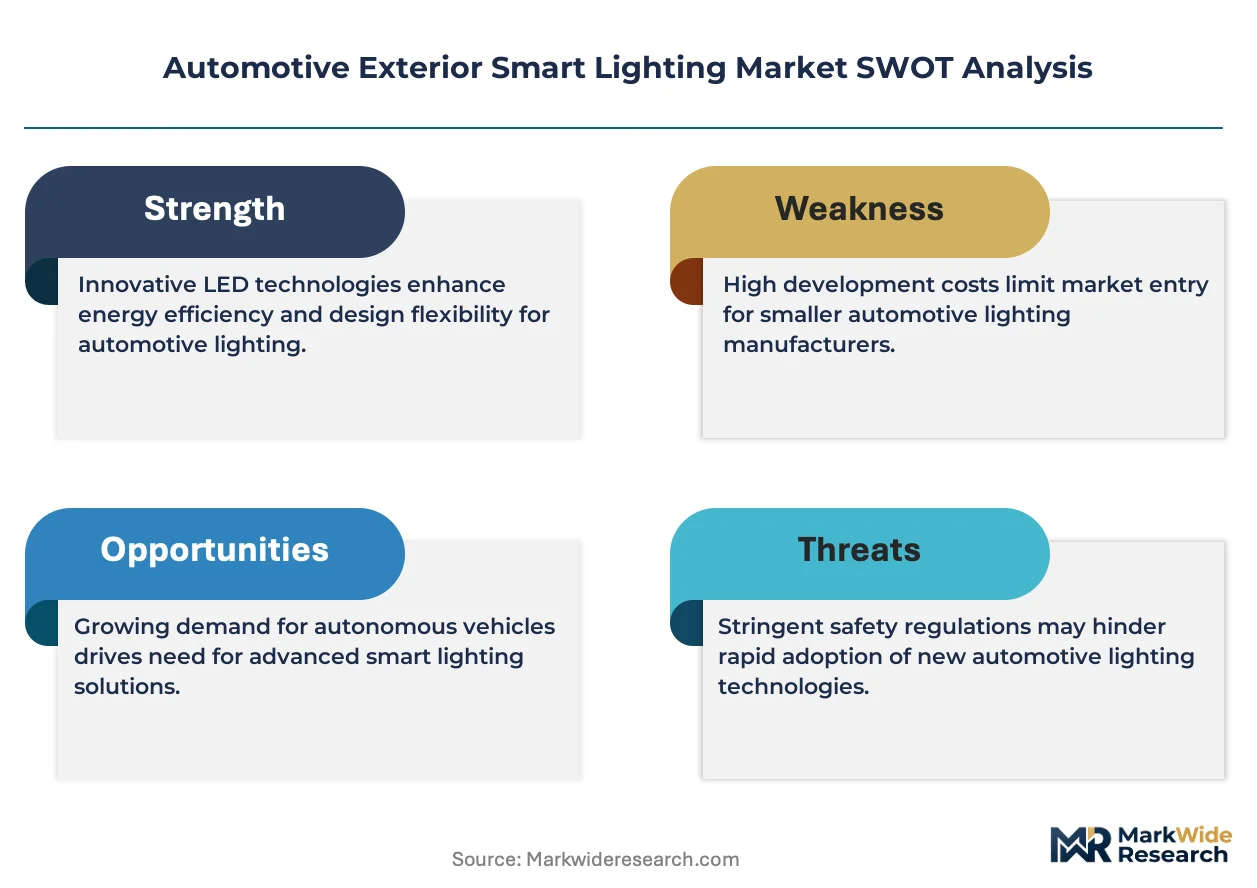
- EU General Safety Regulation:Mandates for pedestrian-detecting adaptive beams are pulling investment toward intelligent lighting architectures in French and German vehicle platforms.
- Domestic EV brands in China:Signature exterior lighting serves as a primary design differentiator, accelerating semiconductor-based emitter integration across mass-market electric vehicle lineups.
- Laser headlamp modules:Japanese luxury marques are driving R&D intensity in high-luminance solid-state sources for extended-range illumination.
Market Restraints
- Semiconductor supply concentration:LED driver ICs and microcontrollers face geographic concentration risk in East Asian foundry networks, creating vulnerability in photonic subsystem sourcing.
- Software integrity certification:ECE R48 and pending NHTSA rulemaking impose divergent validation protocols, fragmenting engineering resource allocation across regional product variants.
- Halogen residual fitment:Price-sensitive vehicle segments in emerging markets retain tungsten-halogen architectures, limiting addressable volume for solid-state adaptive systems.
Strategic Opportunities
- EU AI Act compliance layers:Machine-vision-based adaptive control systems create premium positioning for suppliers capable of integrating photometric performance with algorithmic transparency documentation.
- Aftermarket retrofit channels:Authorized dealer networks in Germany and Japan are developing certified upgrade pathways for matrix LED conversion of legacy LED headlamp platforms.
- Vehicle-to-pedestrian communication:Exterior light sequencing for autonomous intent signaling represents unregulated white space ahead of anticipated GB standards revisions under SAMR.
Industry Challenges
- Optomechanical design talent scarcity:The intersection of thermal management, photometric engineering, and software-defined beam control exceeds conventional automotive lighting workforce capabilities.
- Legacy ADAS integration:Adaptive lighting control units must reconcile proprietary CAN bus architectures from disparate Tier 1 suppliers without degrading real-time response latency.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Exterior Smart Lighting Market |
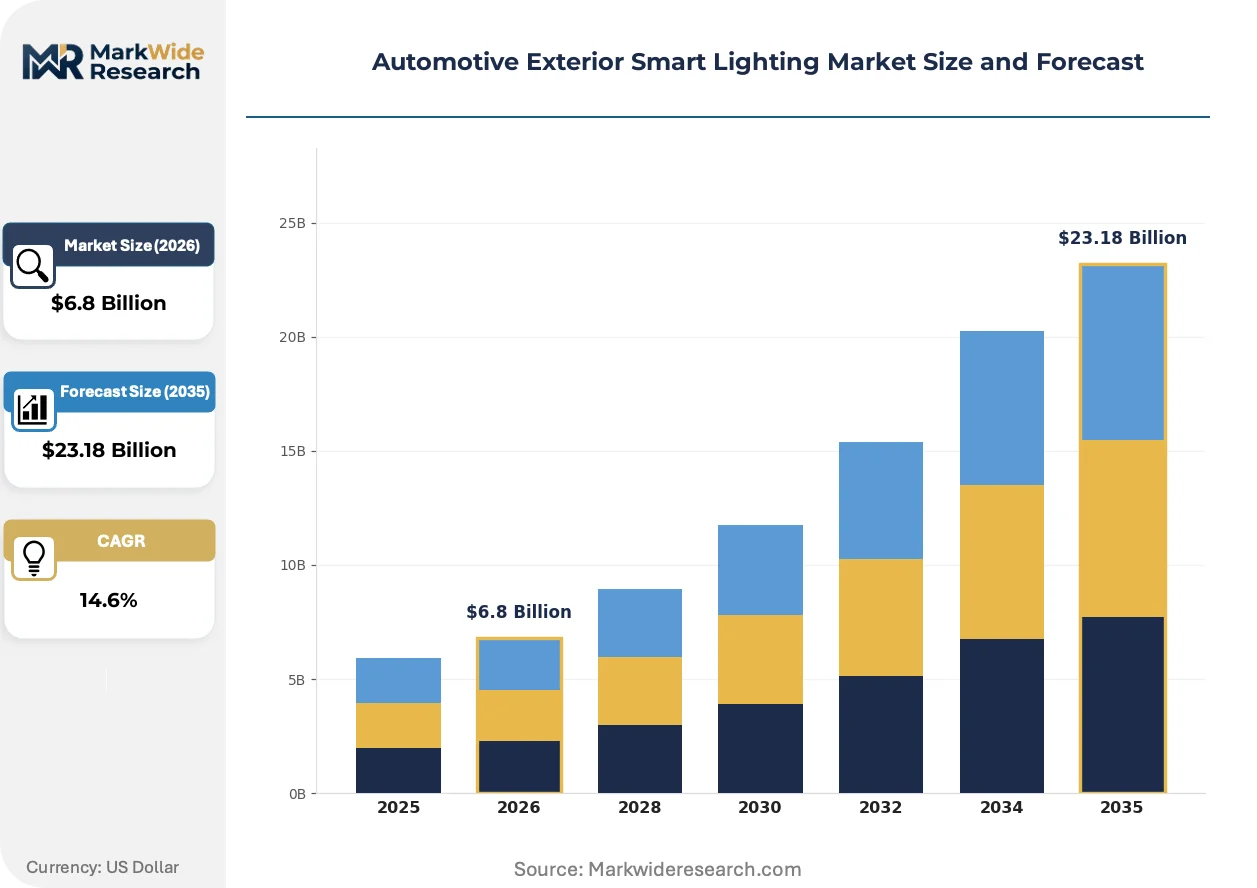
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $23.18 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LED Headlights, Taillights, Fog Lights, Daytime Running Lights Technology: Laser Technology, Adaptive Lighting, Matrix LED, Organic LED End User: OEMs, Aftermarket Providers, Tier-1 Suppliers, Vehicle Assemblers Vehicle Type: SUVs, Sedans, Trucks, Coupes |
| Companies Covered | Koito Manufacturing Co., Ltd, Valeo Group, HELLA KGaA Hueck & Co., Stanley Electric Co., Ltd., Osram GmbH, ZKW Group, Marelli Holdings Co., Ltd., Hyundai Mobis, Varroc Lighting Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Exterior Smart Lighting Market Emerging Trajectories
Digital light processing is dissolving the boundary between illumination and information display, converting headlamp housings into programmable communication surfaces.
Micro-LED arrays with individually addressable pixels are rewriting the technical foundation of adaptive driving beams. Premium OEMs in Germany are deploying these semiconductor emitters to project navigational cues and warning symbols directly onto road surfaces. The technology is compressing the functional separation between headlamps and head-up displays into a unified exterior interface.
ECE R48 provisions permitting matrix operation are diverging from pending NHTSA adaptive driving beam rulemaking, creating asymmetric compliance burdens. European suppliers are engineering dual-mode control firmware to satisfy pixel-level beam shaping under ECE while maintaining binary high-low states for US homologation. This regulatory friction is fragmenting platform engineering resources and delaying unified global product architectures.
Fleet procurement of commercial vehicles is attaching lighting performance to total cost of ownership calculations rather than upfront capital expenditure. Logistics operators in Germany and Japan are specifying predictive maintenance contracts for LED modules with lumen depreciation guarantees. This contractual evolution is transferring lifecycle risk from vehicle operators back to lighting system suppliers.
Automotive Exterior Smart Lighting Market Segmentation
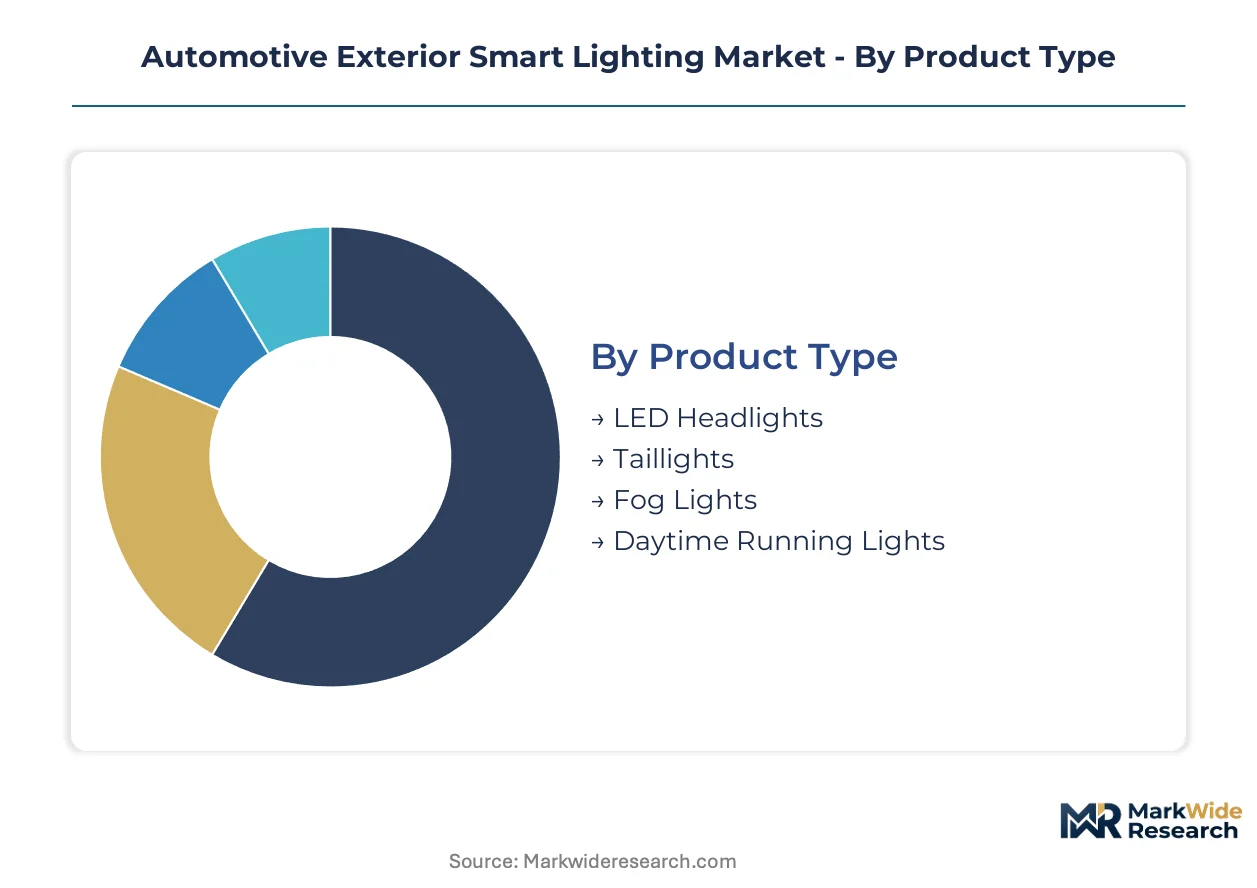
Smart lighting architectures fragment across multiple technical and commercial dimensions, each carrying distinct integration requirements and margin profiles. Understanding where semiconductor-based emitters embed versus operate standalone clarifies supplier positioning and capital allocation priorities.
Product Type:
Integration depth varies sharply across exterior lighting positions, with forward-facing systems embedding most deeply into ADAS architectures while rear and auxiliary units retain greater modularity.
- LED Headlights:Matrix-capable forward illumination modules integrate pixel-level beam-shaping controllers, thermal management substrates, and machine-vision interfaces directly into vehicle electrical architectures. Demand concentrates in German and Japanese premium platforms where adaptive driving beam mandates from ECE R48 and equivalent national provisions drive specification intensity.
- Taillights:Sequential and animated rear signaling systems employ addressable LED strings with localized driver electronics, functioning as semi-autonomous subsystems that communicate over LIN bus rather than deep CAN integration. Chinese EV manufacturers specify signature lighting patterns as brand-defining exterior elements, pulling volume toward domestic assembly plants.
- Fog Lights:Supplementary low-mount illumination units with cornering assist functionality.
- Daytime Running Lights:High-efficiency signature strips with minimal adaptive capability.
Volume placements concentrate in LED Headlights; the faster expansion belongs to Taillights.
Technology:
Cost tier stratification separates established semiconductor platforms from emerging solid-state sources, with price-performance thresholds determining accessible vehicle segments.
- Matrix LED:Individually addressable pixel arrays enabling dynamic beam shaping without mechanical actuators, requiring sophisticated thermal substrates and real-time glare-free algorithms. German OEMs deploy these systems across mid-luxury and above segments, while pending NHTSA rulemaking delays full US deployment.
- Adaptive Lighting:Mechanically or electronically controlled beam adjustment responding to steering angle, vehicle pitch, and ambient conditions, representing the dominant installed base across price-accessible vehicle tiers.
- Laser Technology:High-luminance solid-state sources for extended-range illumination in luxury applications.
- Organic LED:Thin-film emissive surfaces enabling conformal lighting geometries.
Adaptive Lighting commands current volume leadership; Matrix LED is climbing the fastest as regulatory permissions expand.
End User:
Customer type determines specification authority and lifecycle revenue capture, with direct vehicle manufacturer relationships carrying fundamentally different technical validation burdens than post-assembly channels.
- OEMs:Original equipment manufacturers specifying complete lighting systems at platform conception, capturing design-in permanence and multi-year supply agreements. Japanese and German passenger car producers maintain the most stringent photometric and software integrity requirements, filtering supplier eligibility.
- Tier-1 Suppliers:Specialized lighting system integrators serving as technical intermediaries between semiconductor component vendors and final vehicle assembly, controlling substantial value-add through optomechanical packaging and control firmware.
- Aftermarket Providers:Certified upgrade and replacement channels with homologation responsibilities.
- Vehicle Assemblers:Contract manufacturing operations with limited design authority.
Specification authority rests with OEMs; Tier-1 Suppliers are gaining share fastest through subsystem consolidation.
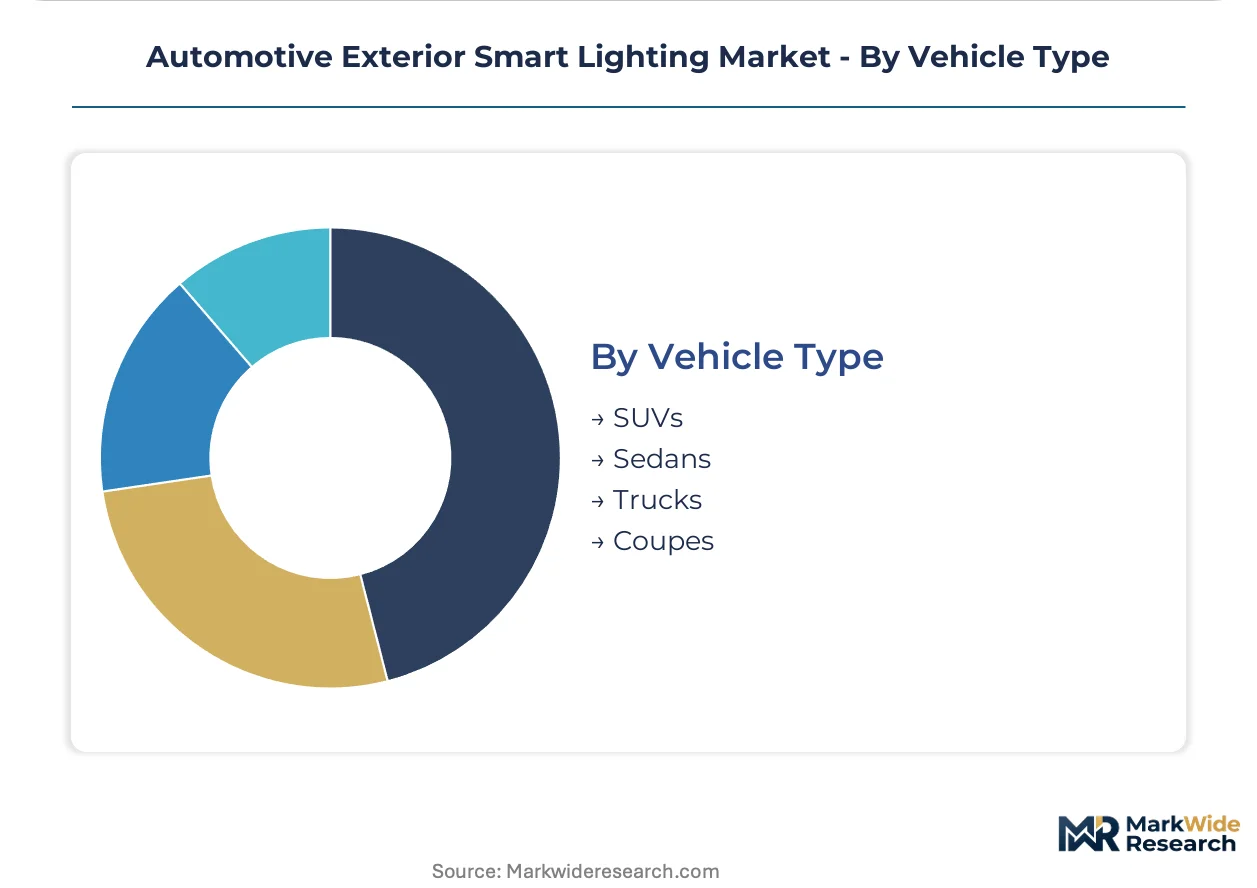
Vehicle Type:
Platform scale and price positioning dictate lighting system complexity, with larger body styles accommodating more extensive emitter arrays and higher thermal budgets.
- SUVs:High-mount, high-volume platforms with frontal area supporting extensive headlamp housings and premium specification tolerance, particularly in Chinese and US market configurations where SUV dominance translates to lighting revenue concentration.
- Sedans:Aerodynamically constrained front fascias demanding compact optical packages with maintained performance, driving adoption of advanced thermal management and dense LED arrays in German and Japanese executive segments.
- Trucks:Commercial and consumer pickup platforms with durability-focused specifications.
- Coupes:Low-volume performance-oriented body styles with styling-priority lighting.
SUVs anchor current revenue; Sedans show the steepest specification upgrade trajectory as electrification reshapes platform economics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stuttgart anchors the highest concentration of automotive lighting engineering, with German OEMs specifying matrix LED architectures for premium vehicle platforms. The regulatory divergence between ECE R48 permissions and NHTSA pending rulemaking fragments engineering resource allocation across regional development centers.
Germany
Adaptive driving beam mandates under ECE R48 specifications pull investment toward pixel-level glare reduction systems in mid-luxury and above segments. KBA homologation protocols filter supplier eligibility through stringent photometric and software integrity requirements. Stuttgart and Ingolstadt clusters concentrate Tier-1 integration facilities for matrix LED control firmware development.
China
Domestic EV manufacturers specify signature exterior lighting as brand-defining design elements across mass-market electric vehicle lineups. GB standards under SAMR define photometric performance requirements with anticipated revisions addressing vehicle-to-pedestrian communication protocols. Yangtze River Delta assembly plants concentrate semiconductor-based emitter integration for domestic marques.
Japan
Luxury marques drive R&D intensity in laser headlamp modules for extended-range illumination applications. METI coordinates national standards alignment with ECE provisions while maintaining distinct domestic certification pathways. Nagoya and Tokyo metropolitan areas host concentrated optomechanical design talent pools for solid-state source development.
United States
Pending NHTSA adaptive driving beam rulemaking delays full deployment of matrix-capable systems, maintaining binary high-low beam architectures in domestic homologation. SUV platform dominance translates to lighting revenue concentration in high-mount, high-volume configurations. Detroit engineering centers prioritize dual-mode control firmware development for eventual regulatory convergence.
South Korea
Domestic vehicle manufacturers integrate semiconductor-based emitters across electrified platform lineups with specification authority retained at OEM level. MFDS maintains separate regulatory frameworks for automotive component certification distinct from ECE harmonization. Seoul Capital Area suppliers concentrate on LIN bus-based rear lighting subsystems for animated signaling applications.
Automotive Exterior Smart Lighting Market Vendor Landscape
The competitive structure tilts toward diversified automotive component conglomerates with captive lighting divisions. Consolidation pressure intensifies as subsystem integration demands exceed standalone photonic specialist capabilities. Two strategic archetypes dominate: full-service Tier-1 integrators controlling optomechanical packaging and control firmware, and semiconductor component suppliers capturing value through LED driver IC and emitter array provision. M&A activity concentrates on control electronics capabilities, while strategic partnerships proliferate between lighting system houses and ADAS platform vendors.
Within the full-service Tier-1 tier, Koito Manufacturing Co., Ltd and Valeo Group occupy positions exemplifying integrated optomechanical and software-defined beam control capabilities. HELLA KGaA Hueck & Co. represents the specialized adaptive lighting control archetype, anchoring engineering resource concentration in German regulatory compliance expertise. These three entities collectively illustrate the competitive imperative of reconciling proprietary vehicle network architectures with real-time photonic subsystem response.
| Leading Market Players |
|---|
| Koito Manufacturing Co., Ltd |
| Valeo Group |
| HELLA KGaA Hueck & Co. |
| Stanley Electric Co., Ltd. |
| Osram GmbH |
| ZKW Group |
| Marelli Holdings Co., Ltd. |
| Hyundai Mobis |
| Varroc Lighting Systems |
| Others |
Supply Flow & Price Mechanics
Matrix-to-halogen capability divergence separates premium adaptive systems from commodity forward illumination, compressing margins at the standard tier while concentrating pricing power with semiconductor-integrated suppliers in Germany and Japan. This bifurcation manifests in divergent sourcing strategies: premium platforms secure multi-year emitter contracts with lumen depreciation guarantees, while price-sensitive segments retain tungsten-halogen architectures from concentrated East Asian foundry networks.
Pricing Analysis
Lumen-maintenance guarantees anchor value-based pricing for matrix LED modules, with German logistics operators specifying predictive maintenance contracts that transfer lifecycle risk to suppliers. Three-tier pricing structure across premium adaptive, standard LED, and residual halogen levels differentiates by certification grade under ECE R48 and software integrity documentation. Cost compression in standard LED tiers intensifies because Chinese domestic EV brands negotiate volume scale for signature lighting integration. Fleet procurement teams show highest price sensitivity; luxury OEM platform engineers least.
Supply Chain Analysis
Optomechanical design talent scarcity in Nagoya and Stuttgart constrains matrix LED control firmware production capacity despite foundry availability. LED driver ICs and microcontrollers draw from Taiwan, South Korea, and Japan; thermal management substrates source from German ceramics specialists. Single-source vulnerability concentrates in East Asian semiconductor foundry networks for photonic subsystem components. Distribution runs through Tier-1 integrator facilities co-located with OEM engineering centers in Germany, Japan, and China.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automotive exterior smart lighting has become a vertical-integration race, with control electronics capabilities determining margin capture as subsystem consolidation accelerates. Players are pursuing backward integration into LED driver IC design to secure supply continuity and differentiate algorithmic beam control.
For Market Incumbents: Deepen captive semiconductor sourcing relationships to mitigate East Asian foundry concentration risk. Expand software-defined beam control R&D in Stuttgart and Ingolstadt clusters to defend against emerging ADAS platform vendors encroaching on lighting-electronics integration. Lock in multi-year lumen depreciation guarantee contracts with German fleet operators to secure recurring revenue streams.
For New Entrants and Emerging Players: Capture aftermarket retrofit certification pathways for matrix LED conversion of legacy platforms in Germany and Japan, where regulatory frameworks permit dealer-authorized upgrades. Vehicle-to-pedestrian communication lighting represents the most penetrable white space ahead of anticipated GB standards revisions. Partner with domestic Chinese EV brands on signature lighting pattern development to bypass entrenched Tier-1 relationships.
For Investors and Strategic Acquirers: Re-rating potential sits with specialized adaptive lighting control firmware developers given EU AI Act compliance layer requirements and machine-vision integration mandates. Long-term viability over the projection horizon favors suppliers capable of reconciling proprietary CAN bus architectures with real-time photonic response. Monitor NHTSA adaptive driving beam rulemaking finalization as inflection indicator for US market architecture convergence.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Driver IC Design | Captive semiconductor sourcing mitigates East Asian foundry concentration risk for German Tier-1 suppliers. |
| Software-Defined Beam Control Investment | Algorithmic transparency documentation satisfies EU AI Act compliance layers for premium OEM contracts. |
| Aftermarket Certification Pathway Development | Authorized dealer networks in Germany and Japan unlock retrofit revenue from legacy LED platforms. |
| Vehicle-to-Pedestrian Communication R&D | Unregulated white space ahead of SAMR GB standards revisions offers first-mover positioning. |
| Dual-Mode Control Firmware Engineering | ECE R48 and pending NHTSA divergence requires dual-mode architectures for regulatory coverage. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews across Tier-1 supplier procurement leads, OEM platform engineers, aftermarket distributors, and dealership operations personnel. KBA homologation protocols, ECE R48 submissions, NHTSA docket records, and vehicle production databases supplied quantitative validation. Bottom-up emitter shipment analysis triangulated against top-down OEM platform specification tracking.
Production volume, content-per-vehicle, and regional specification intensity streams reconciled across the analysis window. Segmentation dimensions modeled encompass vehicle class, propulsion architecture, OEM tier, and regional regulatory cluster. CAGRs derived from fitted growth curves applied to technology-specific adoption rates. Forecast inputs incorporated ECE R48 implementation timelines, pending NHTSA rulemaking status, and Chinese domestic EV brand platform rollout schedules.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to semiconductor supply disruption, regulatory divergence persistence, and optomechanical design talent availability. Forecasts reflect documented assumptions regarding ECE-NHTSA convergence timing and matrix LED cost curves. Material deviation in foundry capacity allocation or adaptive beam regulatory finalization warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Interior & Exterior
Global Automotive Tinted Window Pane Market
Automotive Interior & Exterior
Automotive Head Up Display (HUD) Market
Automotive Interior & Exterior
Automotive Sunroof Market
Automotive Interior & Exterior
Car Oxygen Bar Market
Automotive Interior & Exterior
Weatherstrip Market
Automotive Interior & Exterior
Automotive Door Frame Market
Automotive Interior & Exterior
Truck Parking Air Conditioner Market
Automotive Interior & Exterior
Asia-Pacific Automotive Interior Materials Market
Automotive Interior & Exterior
Argentina Automotive Adaptive Lighting System Market
Automotive Interior & Exterior
Convertible Roof Control Unit Market
Automotive Interior & Exterior
Automotive Encapsulated Glass Market
Automotive Interior & Exterior
Car Canopies Market
Automotive Interior & Exterior
Automotive Energy Absorption (EA) Pads Market
Automotive Interior & Exterior
All Plastic Front End Module Market
Automotive Interior & Exterior
Automotive Floor Carpet Market
Automotive Interior & Exterior
Auto Internal Connector Market