
 Automotive Lighting Molds Market | 2026-2036
Automotive Lighting Molds Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Lighting Molds Market Insights
China's injection mold base is hardening around automotive lighting applications. Changzhou Xingyu Automotive Lighting System Co., Ltd. leverages captive mold capabilities to serve domestic OEM programs. JMT Mould anchors export-oriented production for European tier-1 lighting suppliers. Marelli Automotive Lighting competes through integrated design-to-mold workflows across multiple manufacturing geographies.
Automotive lighting molds are precision tooling systems that shape thermoplastic and thermoset polymers into complex optical components, typically achieving surface finishes below Ra 0.05 micrometers to ensure beam pattern compliance. These molds enable mass production of headlamp lenses, light-guide elements, and housing assemblies that must withstand thermal cycling, UV exposure, and vibration loads across vehicle lifespans. Headlamp molds command the largest value share given multi-cavity complexity and cooling channel intricacy, while polycarbonate dominates material-specific tooling demand due to its impact resistance and optical clarity requirements. Injection molding sustains its position as the primary process technology, though 3D printing is gaining traction for prototype and short-run mold inserts.
NHTSA Federal Motor Vehicle Safety Standard 108 governs headlamp photometric performance in the United States, directly specifying mold-controlled lens geometry and beam cutoff precision. ECE Regulation 48 and the EU's CE marking framework enforce comparable optical standards across European type approvals, while China's GB 4599 and GB 21259 national standards mandate localized testing protocols that influence mold design parameters. Stakeholders must monitor regulatory divergence between photometric testing methodologies, as regional compliance gaps are widening tooling qualification costs and complicating platform-standardization strategies.
Market Dynamics
LED headlamp adoption by premium vehicle OEMs is compressing tooling refresh cycles from seven years to four years, forcing mold makers to absorb higher amortization rates while maintaining sub-micron surface precision.
Growth Catalysts
- GB 4599 Compliance Mandates:China's tightening headlamp safety standards require mold-controlled beam cutoff precision that obsolete tooling cannot achieve, triggering replacement demand across domestic supplier networks.
- Polycarbonate Optical Clarity Requirements:Advanced driver-assistance systems demand lens materials with minimal birefringence, necessitating multi-cavity molds with precision cooling channel architectures.
- Jiangsu-Zhejiang Cluster Concentration:East China's mold-making agglomeration generates knowledge spillovers and specialized labor pools that accelerate prototyping cycles for export programs.
Market Restraints
- Specialized Alloy Input Volatility:Mold core and cavity inserts rely on precipitation-hardened tool steels whose nickel and cobalt content exposes fabricators to commodity price swings.
- Single-Source Supplier Risk:High-precision EDM wire and electrode materials concentrate among Japanese and Swiss producers, creating geographic chokepoints in the upstream supply chain.
- Thermal Cycling Durability Limits:Polycarbonate injection molds face fatigue failure modes above 500,000 shots, constraining asset utilization rates in high-volume programs.
Strategic Opportunities
- India PLI Scheme Alignment:India's production-linked incentive framework for automotive components creates localized mold demand as global lighting suppliers establish domestic manufacturing.
- 3D-Printed Conformal Cooling:Additive manufacturing of mold inserts with topology-optimized cooling channels reduces cycle times and warpage in complex light-guide geometries.
- EU F-Gas Regulation Phase-Down:Restrictions on fluorinated greenhouse gases in manufacturing processes favor electric injection molding systems that require retooling investment.
Industry Challenges
- Multi-Axis CNC Programming Shortage:Mold finishing operations require simultaneous five-axis machining expertise that outpaces vocational training pipeline output.
- Photometric Certification Timelines:ECE Regulation 48 type-approval testing for new headlamp designs extends mold qualification cycles and strains working capital.
- Retrofit Integration Complexity:Aftermarket LED conversion modules must interface with legacy reflector geometries designed for halogen sources, complicating mold standardization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Lighting Molds Market |
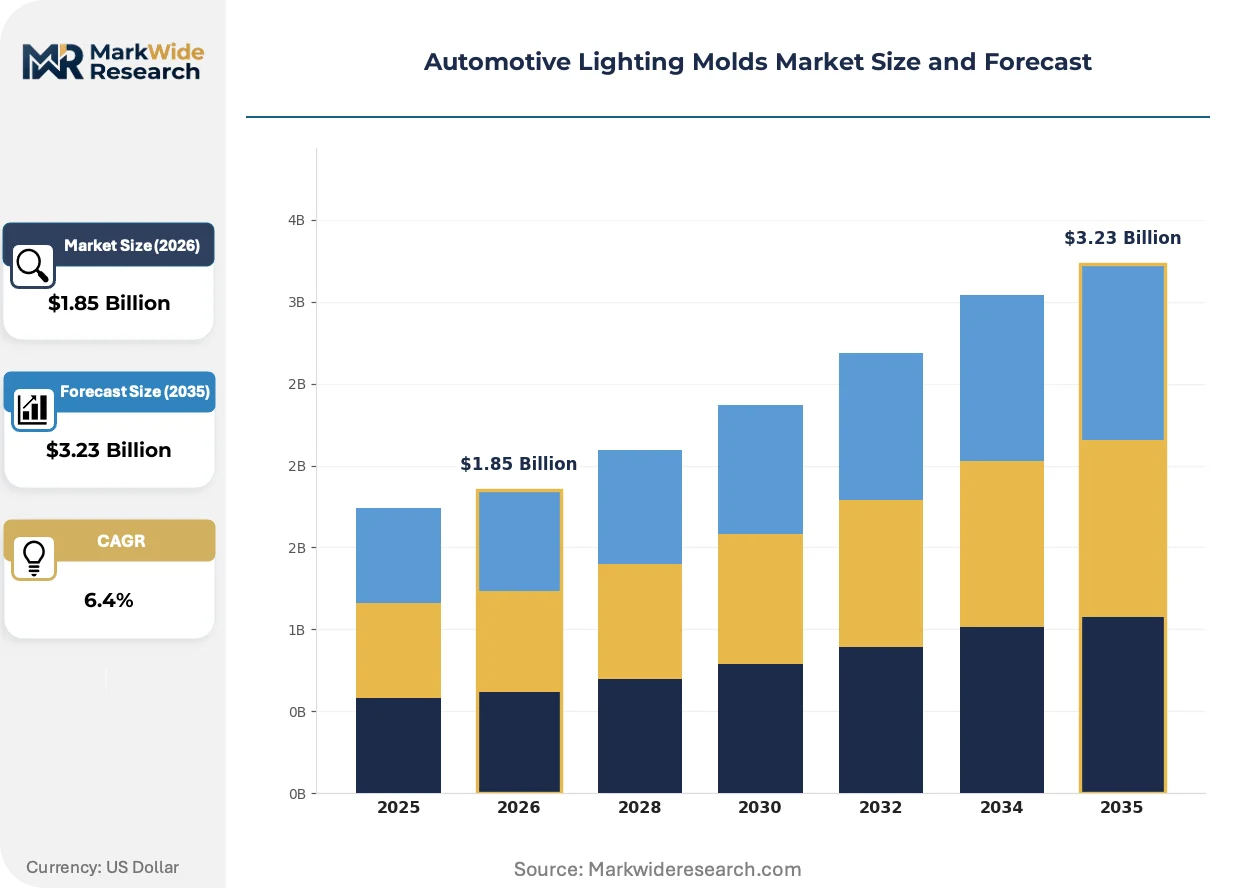
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Headlamps, Taillights, Turn Signal Lights, Fog Lights Material: Polycarbonate, Acrylic, Glass, Thermoplastic Elastomer Manufacturing Process: Injection Molding, Blown Film Extrusion, Compression Molding, 3D Printing End User: OEMs, Aftermarket Providers, Tier-1 Suppliers, Vehicle Assemblers |
| Companies Covered | Changzhou Xingyu Automotive Lighting System Co., Ltd., JMT Mould, CY Molds, Marelli Automotive Lighting, Bamwei, Guangdong Kaidaxing Plastic Mold, Redoe Group, 3Dimensional Group, Upmold, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Lighting Molds Market Trends and Innovations
Digital twin deployment and additive manufacturing are converging to compress mold development timelines while enabling geometries previously unreachable through conventional machining.
Conformal cooling channels produced via selective laser melting are electrifying thermal management in headlamp molds. European tier-1 lighting suppliers have adopted these inserts for multi-cavity polycarbonate lens production. The technology is compressing cycle times and reducing weld-line defects that previously required secondary polishing operations.
REACH restrictions on chromium VI surface treatments are forcing mold makers to adopt physical vapor deposition coatings for wear resistance. The industrial consequence is higher per-cavity coating costs and extended lead times for specialized service providers. Asian export-oriented mold fabricators are responding by qualifying domestic PVD suppliers to bypass European coating bottlenecks.
Buyer concentration among consolidated automotive lighting tier-1s is shifting procurement toward integrated design-to-mold contracts that bundle optical engineering with tooling fabrication. Direct OEM relationships are displacing traditional mold broker intermediaries in high-complexity programs. This pattern is most visible in Germany and China where Marelli, Hella, and domestic champions have absorbed former independent mold specification authority.
Automotive Lighting Molds Market Segmentation
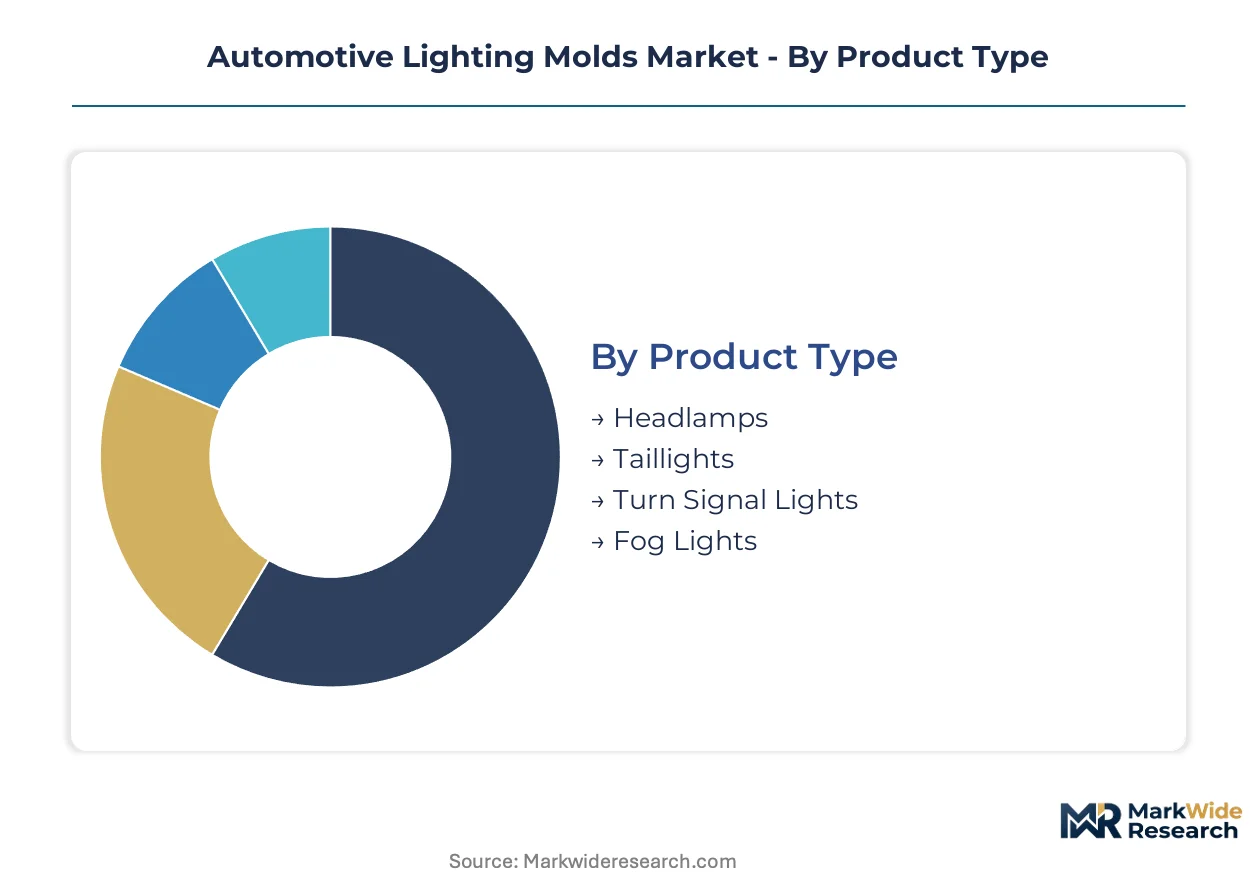
Automotive lighting molds fragment across optical performance tiers, material specifications, and supply chain integration models. Each segmentation axis carries distinct tooling precision requirements and qualification protocols that reshape procurement patterns across OEM and aftermarket channels.
Product Type:
Headlamps anchor volume demand while taillights command premium tooling rates for sequential animation features.
- Headlamps:Multi-cavity molds with conformal cooling architectures shape polycarbonate lenses achieving surface finishes below Ra 0.05 micrometers for beam pattern compliance. NHTSA Federal Motor Vehicle Safety Standard 108 and ECE Regulation 48 photometric requirements concentrate demand in Changzhou and Stuttgart supplier networks where integrated design-to-mold workflows dominate.
- Taillights:Sequential LED animation modules require precision light-guide geometries with micro-optical surface textures. Tooling for full-width light bars is concentrating in East China's Jiangsu province as domestic OEMs adopt premium rear-illumination signatures.
- Turn Signal Lights:Compact mirror-integrated and fender-mounted variants utilize standardized cavity designs with shorter qualification cycles.
- Fog Lights:Auxiliary positioning below bumper lines demands enhanced thermal cycling resistance in mold steel selection.
Today's leader: Headlamps. Tomorrow's challenger: Taillights.
Material:
Optical clarity specifications split procurement between amorphous thermoplastics and emerging elastomeric seals.
- Polycarbonate:Dominant lens material requiring birefringence-controlled molding to preserve ADAS camera compatibility. Multi-cavity tooling with precision temperature management is concentrating in Zhejiang province mold clusters serving European tier-1 export programs.
- Acrylic:Cost-sensitive interior and decorative lighting applications utilize simplified cooling channel geometries with reduced surface finish requirements.
- Glass:Legacy high-temperature applications persist in specialty vehicle segments with limited mold refresh demand.
- Thermoplastic Elastomer:Housing seals and gaskets utilize compression molding with lower capital intensity than optical-grade tooling.
Polycarbonate maintains installed base dominance. Acrylic gains share in cost-optimized programs.
Manufacturing Process:
Cycle time economics favor injection molding while additive manufacturing captures prototyping and conformal cooling insert production.
- Injection Molding:Sustains position as primary process technology with electric machine adoption accelerating under EU F-Gas Regulation phase-down requirements. High-volume polycarbonate lens production concentrates in automated Jiangsu-Zhejiang facilities.
- 3D Printing:Selective laser melting of mold inserts with topology-optimized cooling channels reduces warpage in complex light-guide geometries. European tier-1 suppliers have adopted these inserts for multi-cavity production.
- Blown Film Extrusion:Limited to flexible lighting diffuser films with minimal tooling capital requirements.
- Compression Molding:Thermoset housing components utilize lower cavity counts with extended cycle times.
Injection molding commands current volume. 3D-printed inserts represent the steepest expansion trajectory.
End User:
Procurement authority is consolidating among integrated lighting tier-1s while aftermarket channels fragment across retrofit specifications.
- Tier-1 Suppliers:Marelli, Hella, and Changzhou Xingyu bundle optical engineering with captive or contracted mold fabrication. Direct OEM relationships are displacing traditional mold broker intermediaries in high-complexity programs across Germany and China.
- OEMs:Premium vehicle manufacturers compress tooling refresh cycles from seven years to four years through LED headlamp adoption, forcing mold makers to absorb higher amortization rates.
- Aftermarket Providers:LED conversion modules must interface with legacy reflector geometries designed for halogen sources, complicating mold standardization across fragmented demand.
- Vehicle Assemblers:Emerging market localization under India's PLI scheme creates dedicated mold demand for domestic lighting component manufacturing.
Tier-1 suppliers control specification authority. Aftermarket channels resist standardization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany maintains tighter integration between optical engineering and mold fabrication than the United States, where procurement authority has shifted toward consolidated tier-1 suppliers over the past decade.
China
Domestic OEMs and export programs drive polycarbonate lens mold demand across Jiangsu and Zhejiang provinces. GB 4599 and GB 21259 standards mandate localized testing protocols that influence cooling channel design parameters. Changzhou mold clusters serve European tier-1 lighting suppliers with precision multi-cavity tooling.
Germany
Premium vehicle manufacturers compress tooling refresh cycles through LED headlamp adoption, forcing mold makers to absorb higher amortization rates. ECE Regulation 48 and CE marking frameworks enforce optical standards across European type approvals. Stuttgart supplier networks dominate integrated design-to-mold workflows.
United States
Aftermarket LED conversion modules interface with legacy reflector geometries designed for halogen sources, complicating mold standardization. NHTSA Federal Motor Vehicle Safety Standard 108 governs headlamp photometric performance and lens geometry requirements. Michigan and Ohio manufacturing corridors concentrate automotive supplier procurement.
India
Global lighting suppliers establish domestic manufacturing under the PLI scheme for automotive components, creating localized mold demand. BIS standards and DGFT import policies shape qualification timelines for optical-grade tooling. Maharashtra and Gujarat industrial corridors attract tier-1 lighting facility investments.
Japan
Precision mold finishing operations require simultaneous five-axis machining expertise that outpaces vocational training pipeline output. METI industrial policy and JIS standards govern automotive component manufacturing quality. Aichi Prefecture mold fabricators supply domestic and Southeast Asian OEM programs.
Automotive Lighting Molds Market Competitive Landscape
East Asian producers anchor the volume tier; European specialists hold premium positioning through integrated optical engineering. The vendor base separates into consolidated tier-1 lighting suppliers with captive mold capabilities and independent fabricators serving export programs. Three archetypes dominate: integrated design-to-mold operators, cluster-based precision specialists, and scale-driven commodity producers. Competitive moves center on backward integration into optical engineering and additive manufacturing adoption for conformal cooling inserts.
Within the integrated tier, Marelli Automotive Lighting and Changzhou Xingyu Automotive Lighting System Co., Ltd. exemplify design-to-mold workflow consolidation across multiple manufacturing geographies. JMT Mould occupies a position among export-oriented specialists serving European tier-1 procurement networks. These three anchors represent divergent strategic postures: captive vertical integration, domestic OEM alignment, and cross-border precision supply.
| Leading Market Players |
|---|
| Changzhou Xingyu Automotive Lighting System Co., Ltd. |
| JMT Mould |
| CY Molds |
| Marelli Automotive Lighting |
| Bamwei |
| Guangdong Kaidaxing Plastic Mold |
| Redoe Group |
| 3Dimensional Group |
| Upmold |
| Others |
Pricing and Supply Chain Analysis
EU F-Gas Regulation phase-down mandates gate qualified supply for electric injection molding systems and premium-tier pricing access, bifurcating the vendor base between certified European fabricators and cost-optimized Asian alternatives. Buyers face escalating qualification costs for conformal cooling inserts as REACH restrictions on chromium VI surface treatments force physical vapor deposition adoption.
Pricing Analysis
Capacity additions in Jiangsu and Zhejiang provinces are reshaping price floors for polycarbonate lens molds as domestic Chinese fabricators capture mid-tier export programs from European specialists. Three-tier pricing structure across premium optical-grade, standard automotive-certified, and economy aftermarket levels stratifies procurement, with premium tiers commanding substantial markups for sub-micron surface finishes and integrated design-to-mold workflows. Cost compression in the economy tier is intensifying because Indian PLI scheme localization is attracting second-tier Chinese producers to establish joint ventures with reduced duty exposure. Aftermarket LED conversion providers exhibit highest price sensitivity due to fragmented demand and legacy reflector compatibility requirements, while premium OEM captive programs demonstrate lowest sensitivity given four-year tooling refresh cycles.
Supply Chain Analysis
Five-axis CNC programming shortages in Aichi Prefecture and Changzhou constrain mold finishing throughput despite strong order backlogs from European tier-1 lighting suppliers. Geographic supply concentration centers on China, Germany, and Japan, with Jiangsu-Zhejiang clusters serving export programs and Stuttgart networks anchoring integrated optical engineering. Raw material dependencies rest on precipitation-hardened tool steels with nickel and cobalt content, Japanese and Swiss-sourced EDM wire and electrode materials, and polycarbonate resin grades with birefringence specifications. Single-source vulnerability in high-precision EDM consumables creates geographic chokepoints that strain working capital during mold qualification cycles. Distribution runs through consolidated tier-1 lighting suppliers with captive mold capabilities, displacing traditional broker intermediaries in high-complexity programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between EU F-Gas compliance costs driving European electric machine retooling and China's GB standard tightening creating replacement demand at lower fabrication cost bases.
For Market Incumbents: Anchor design-to-mold workflow consolidation through backward integration into optical engineering capabilities, capturing specification authority before tier-1 lighting suppliers internalize mold procurement. Defend against additive manufacturing disruption by qualifying domestic physical vapor deposition suppliers to bypass European coating bottlenecks and compress lead times. Prioritize certification investment for India's PLI scheme alignment as global lighting suppliers establish domestic manufacturing with localized mold demand. For New Entrants and Emerging Players: Tier-1 lighting suppliers seeking Indian PLI localization partners represent the most penetrable channel, offering design-to-mold contract entry points without legacy European supplier relationships. Target sequential LED animation tooling for full-width light bars in East China's domestic OEM programs, where knowledge spillovers from Jiangsu-Zhejiang clusters accelerate prototyping cycles. Pursue go-to-market positioning as conformal cooling insert specialists via selective laser melting capabilities, addressing cycle time reduction and warpage control in complex light-guide geometries. For Investors and Strategic Acquirers: Roll-up economics work for mid-cap precision mold fabricators with captive optical engineering because buyer concentration among consolidated tier-1s is displacing broker intermediaries and favoring integrated suppliers. Long-term viability hinges on additive manufacturing adoption for conformal cooling and electric injection molding system qualification under tightening environmental mandates. Acquisition target archetype: Jiangsu-Zhejiang cluster specialists with European tier-1 export relationships and underutilized five-axis CNC capacity. Watch for GB 4599 implementation acceleration as inflection indicator for replacement demand spikes across domestic Chinese supplier networks.| Strategic Initiative | Industry Significance |
|---|---|
| Conformal Cooling Insert Adoption | Selective laser melting of mold inserts reduces cycle times for polycarbonate lens production at European tier-1 suppliers. |
| Electric Injection Molding Transition | EU F-Gas Regulation compliance drives retooling investment toward electric systems with qualified supplier concentration. |
| India PLI Scheme Localization | Domestic manufacturing establishment by global lighting suppliers creates dedicated mold demand in Maharashtra and Gujarat corridors. |
| Physical Vapor Deposition Qualification | REACH chromium VI restrictions force coating technology shift with domestic Asian supplier bypass opportunities. |
| Design-to-Mold Workflow Integration | Optical engineering bundling captures specification authority from traditional mold broker intermediaries in Germany and China. |
Research Methodology
Bottom-up automotive lighting program modeling reconciled against top-down mold fabrication capacity tracking forms the analytical core of this study. Primary interviews with tier-1 lighting supplier procurement directors, OEM platform engineers, mold fabricator operations managers, and aftermarket distributor category buyers combined with secondary validation from vehicle production databases, customs and trade flow records, SEC filings of listed automotive suppliers, and regulatory submission documents from NHTSA and ECE frameworks. Triangulation across these sources ensures demand-side and supply-side estimates converge within acceptable variance bands.
Input-output matrices map polycarbonate resin consumption, tool steel alloy demand, and injection molding machine installations against headlamp and taillight production volumes across the projection horizon. Segmentation dimensions modeled include product type, material specification, manufacturing process technology, and end-user procurement authority, with additional granularity for regional regulatory cluster alignment. CAGRs derive from fitted trend analysis of historical tooling refresh cycles and projected LED adoption curves, incorporating GB 4599 compliance mandates and ECE Regulation 48 photometric testing timelines as industry-specific forecast inputs.
Revisions become necessary when regulatory implementation timelines accelerate, raw material alloy prices experience sustained volatility, or additive manufacturing adoption curves steepen beyond baseline assumptions. Forecasts reflect documented assumptions regarding tier-1 supplier consolidation trajectories and electric injection molding system qualification rates. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Interior & Exterior
Low-Noise Anti-Squeak Additives for Automotive Interiors Market
Automotive Interior & Exterior
Paint Protection Film Market
Automotive Interior & Exterior
Interior Materials for Pet-Friendly Vehicle Cabins Market
Automotive Interior & Exterior
Automotive Window and Exterior Sealing Systems Market
Automotive Interior & Exterior
Automotive Leather Upholstery Market
Automotive Interior & Exterior
Asia-Pacific Automotive Interior Materials Market
Automotive Interior & Exterior
Automotive Floor Mats Market
Automotive Interior & Exterior
Japan Automotive Flooring Market
Automotive Interior & Exterior
Global Automotive Intelligent Seats Market
Automotive Interior & Exterior
Automotive in-Vehicle Air Purifier Market
Automotive Interior & Exterior
Automotive Racing Seats Market
Automotive Interior & Exterior
Automotive Active Spoiler Market
Automotive Interior & Exterior
Automotive Mirror Dimming Market
Automotive Interior & Exterior
Bumper Sticker Market
Automotive Interior & Exterior
Germany Automotive Adaptive Lighting System Market
Automotive Interior & Exterior
Automotive Door Handle Sensors Market