
 Automotive Bovine Leather Market | 2026-2036
Automotive Bovine Leather Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Bovine Leather Market Analysis
The capital-intensity divergence between full-grain tanneries and split-leather processors is collapsing as automated cutting and digital grading technology penetrates mid-tier operations. Bader GmbH & Co. KG leverages its integrated beamhouse-to-finish capability across German and Mexican plants. Lear Corporation competes through just-in-sequence delivery contracts with Detroit and Stuttgart OEMs. Gruppo Mastrotto anchors its position via vertical control over Italian raw material sourcing.
Automotive bovine leather denotes cattlehide processed through chrome or vegetable tanning, dyed and finished to meet abrasion, fogging, and flame-resistance specifications for vehicle interiors, typically achieving thicknesses of 0.9 to 1.3 millimeters for seating applications. The material serves primarily as a premium surface covering that delivers tactile durability and aesthetic differentiation in passenger compartments. Full grain commands the highest margin pools among product types due to its intact fiber structure and natural grain character, while split leather expands volume in standard-grade seating programs where cost targets dominate specification sheets. Among applications, seats absorb the majority of hide square footage, though interior trims generate superior per-unit value through smaller cut sizes and complex stitching requirements.
EMA's REACH restrictions on hexavalent chromium compounds and the EU Green Deal's carbon border adjustments are reshaping tanning chemistry investment across European supply chains, with tanneries reformulating wet-white processes to maintain market access. EPA emissions standards and NHTSA flammability protocols in the United States impose parallel compliance burdens on imported finished leather. China's GB standards and MEE enforcement on wastewater discharge add further technical gates for suppliers serving domestic vehicle assemblers. Stakeholders must monitor regulatory divergence between jurisdictions while positioning vegetable-tanned and metal-free product lines for premium OEM qualification cycles.
Market Dynamics
REACH restrictions on hexavalent chromium compounds and the EU Green Deal's carbon border adjustments are forcing tanneries to reformulate wet-white processes, collapsing the cost advantage that chrome-tanned leather held over vegetable-tanned alternatives for decades.
Growth Catalysts
- Luxury electric vehicle cabin programs:Premium EV manufacturers are expanding hide procurement for interior differentiation as range and acceleration become table stakes.
- REACH and EU Green Deal compliance mandates:Regulatory pressure on chromium tanning is accelerating vegetable-tanned leather qualification cycles with Stuttgart and Munich OEMs.
- Automated cutting and digital grading:Mid-tier tanneries are deploying laser-guided hide optimization systems that compress capital-intensity gaps with full-grain specialists.
Market Restraints
- Raw hide supply concentration:Italian and German tanneries depend on constrained European and Brazilian cattlehide flows, exposing margin pools to livestock cycle volatility.
- Metal-free tanning technical limitations:Vegetable-tanned alternatives face fogging and flame-resistance specification gaps in NHTSA-certified seating programs.
- Synthetic leather substitution:Polyurethane microfiber suppliers are capturing standard-grade seating volume in cost-targeted vehicle programs.
Strategic Opportunities
- China domestic premium vehicle production:GB standards and MEE wastewater enforcement are creating qualification barriers that favor tanneries with pre-certified metal-free processes.
- Interior trim complexity premiums:Smaller cut sizes and intricate stitching requirements in dashboard and door panel applications generate superior per-unit value versus seating.
- Just-in-sequence delivery contracts:Proximity to final assembly plants in Mexico and Eastern Europe enables tanneries to capture logistics-adjacent margin pools.
Industry Challenges
- Wet-chemistry expertise scarcity:Vegetable-tanned leather production requires specialized beamhouse technicians that European vocational pipelines no longer produce at scale.
- Multi-jurisdiction certification timelines:Simultaneous EPA emissions, NHTSA flammability, and ECHA REACH compliance extends OEM qualification cycles by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Bovine Leather Market |
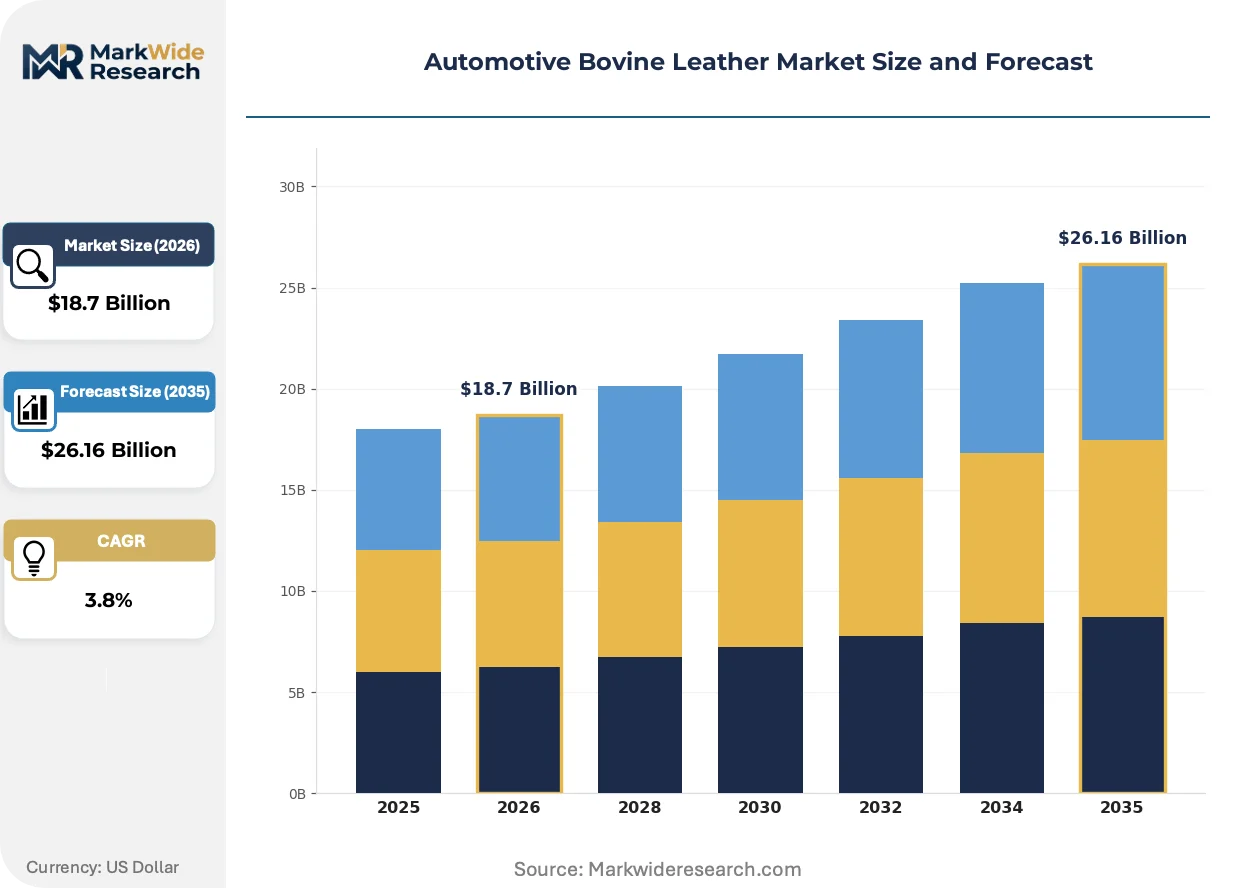
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $26.16 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Full Grain, Top Grain, Split Leather, Suede Application: Seats, Interior Trims, Upholstery, Accessories End User: OEMs, Aftermarket, Vehicle Assemblers, Upholsterers Grade: Premium, Standard, Economical, Specialty |
| Companies Covered | Bader GmbH & Co. KG, GST AutoLeather, Lear Corporation, Adient, Toyota Boshoku Corporation, Forvia SE, Gruppo Mastrotto, Boxmark Leather GmbH & Co. KG, Wollsdorf Leder, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Bovine Leather Market Emerging Trajectories
Digital grading systems and automated cutting platforms are redistributing competitive advantage across the tannery value chain, while regulatory chemistry shifts and EV interior premiumization rewrite specification standards.
AI-powered hide defect detection is supplanting manual grading labor in mid-tier operations. Stuttgart seating suppliers are adopting machine-vision systems that map blemish density across raw hides before cutting optimization. This technology is compressing yield variance between full-grain specialists and split-leather processors, collapsing historical margin stratification.
ECHA's REACH Annex XVII restrictions on hexavalent chromium compounds are forcing wet-white process reformulation across European tanneries. The regulation imposes substitution mandates that extend production cycles and elevate chemical R&D overhead. German and Italian suppliers are responding by qualifying metal-free tanning lines for premium OEM programs ahead of 2027 enforcement windows.
Vehicle assemblers are consolidating leather procurement under direct material management rather than tiered supplier delegation. Tier 1 seating manufacturers in Detroit and Stuttgart are losing specification control as OEMs mandate hide sourcing transparency and carbon footprint certification. This pattern concentrates most visibly in luxury EV programs where cabin differentiation drives consumer choice.
Automotive Bovine Leather Market Segmentation
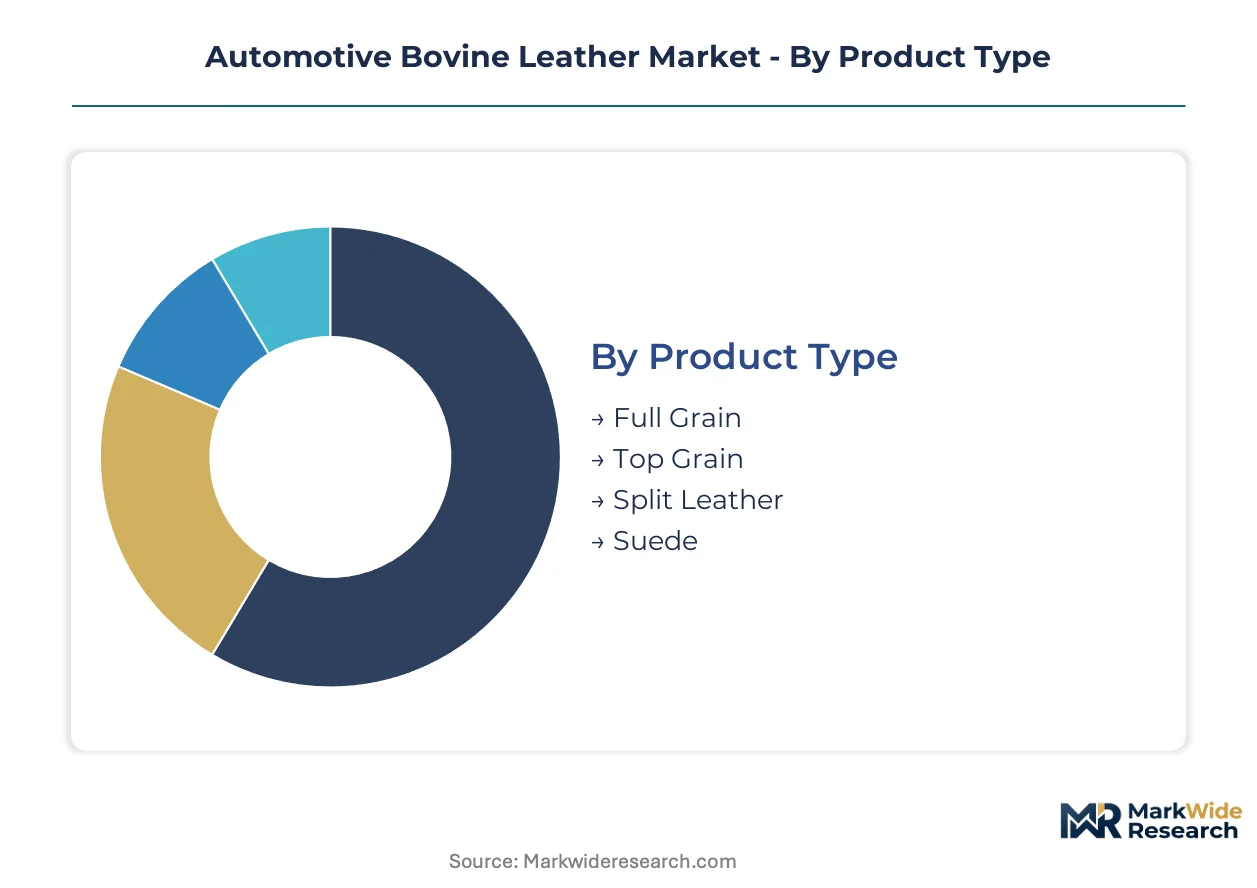
Segmentation in automotive bovine leather reveals how substitution pressures and regulatory chemistry shifts concentrate value across distinct material grades and supply channels. Understanding these fault lines exposes where vegetable-tanned alternatives displace chrome-tanned volume and where synthetic leather encroachment remains weakest.
Product Type:
Polyurethane microfiber suppliers target split leather and suede most aggressively for cost-driven seating programs, while full grain maintains defensive moats through tactile differentiation mandates.
- Full Grain:Retains the complete natural grain layer with intact fiber structure, delivering the highest abrasion resistance and fogging performance specifications. Stuttgart and Munich OEMs specify full grain for flagship EV cabin programs where interior differentiation drives purchase decisions amid range parity. REACH-compliant vegetable tanning processes concentrate investment here due to margin pools that absorb reformulation costs.
- Top Grain:Features a sanded and finished surface layer with uniform appearance, balancing durability against cost targets in mid-luxury vehicle lines. Italian tanneries in Arzignano and Santa Croce sull'Arno dominate qualification cycles for this grade, supplying German premium OEMs with carbon-footprint-certified lots.
- Split Leather:Derived from the corium layer beneath the grain, offering lower tensile strength but adequate performance for standard-grade seating where cost targets dominate specification sheets.
- Suede:Buffed split leather with a napped surface finish, deployed in accent applications and steering wheel wraps where tactile variety outweighs wear resistance requirements.
Full grain anchors the volume base while split leather gains share at the steepest rate through penetration of cost-targeted vehicle programs in China and Mexico.
Application:
Interior trims command superior per-unit economics through complex cutting patterns and smaller lot sizes that resist automation, insulating this application from synthetic substitution longer than seating.
- Seats:Absorbs the majority of hide square footage across vehicle programs, with surface area requirements of 3 to 4 square meters per vehicle in premium configurations. NHTSA flammability protocols and ECE R118 certification requirements create technical gates that synthetic alternatives struggle to clear for front-row positions.
- Interior Trims:Encompasses dashboard coverings, door panels, and console surfaces where intricate stitching and smaller cut sizes generate value premiums. German OEMs specify these applications for hand-finished vegetable-tanned lots that support cabin differentiation narratives in luxury EV marketing.
- Upholstery:Broad category spanning headliners, pillar covers, and rear compartment surfaces, typically utilizing split leather or corrected grain to manage cost exposure across high-volume vehicle lines.
- Accessories:Includes steering wheels, gear selectors, and armrest surfaces where wear concentration demands higher-grade specifications despite smaller material quantities per vehicle.
Seats deliver the largest absolute material offtake while interior trims expand value contribution most quickly through specification complexity premiums.
End User:
Direct material management by vehicle assemblers is collapsing traditional tiered supplier delegation, concentrating procurement leverage among OEMs with transparency mandates and carbon certification requirements.
- OEMs:Original equipment manufacturers with direct hide sourcing programs, particularly luxury EV producers in Germany and China specifying vegetable-tanned alternatives for cabin differentiation. These entities now mandate beamhouse-to-finish traceability and wet-chemistry disclosure that disqualifies traditional tiered supply structures.
- Aftermarket:Independent upholsterers and restoration specialists serving vehicle owners outside warranty periods, with demand concentrated in classic car preservation and premium vehicle retrimming where specification flexibility exceeds production-line constraints.
- Vehicle Assemblers:Contract manufacturers and joint-venture production facilities, primarily in China, sourcing through approved supplier lists with GB standard compliance and MEE wastewater certification requirements.
- Upholsterers:Tier 2 and Tier 3 seating component suppliers losing specification control as OEMs consolidate procurement authority, now functioning primarily as cut-and-sew operations without hide sourcing autonomy.
OEMs control the qualification pipeline while aftermarket channels deliver the most stable margin profiles through price-insensitive restoration demand.
Grade:
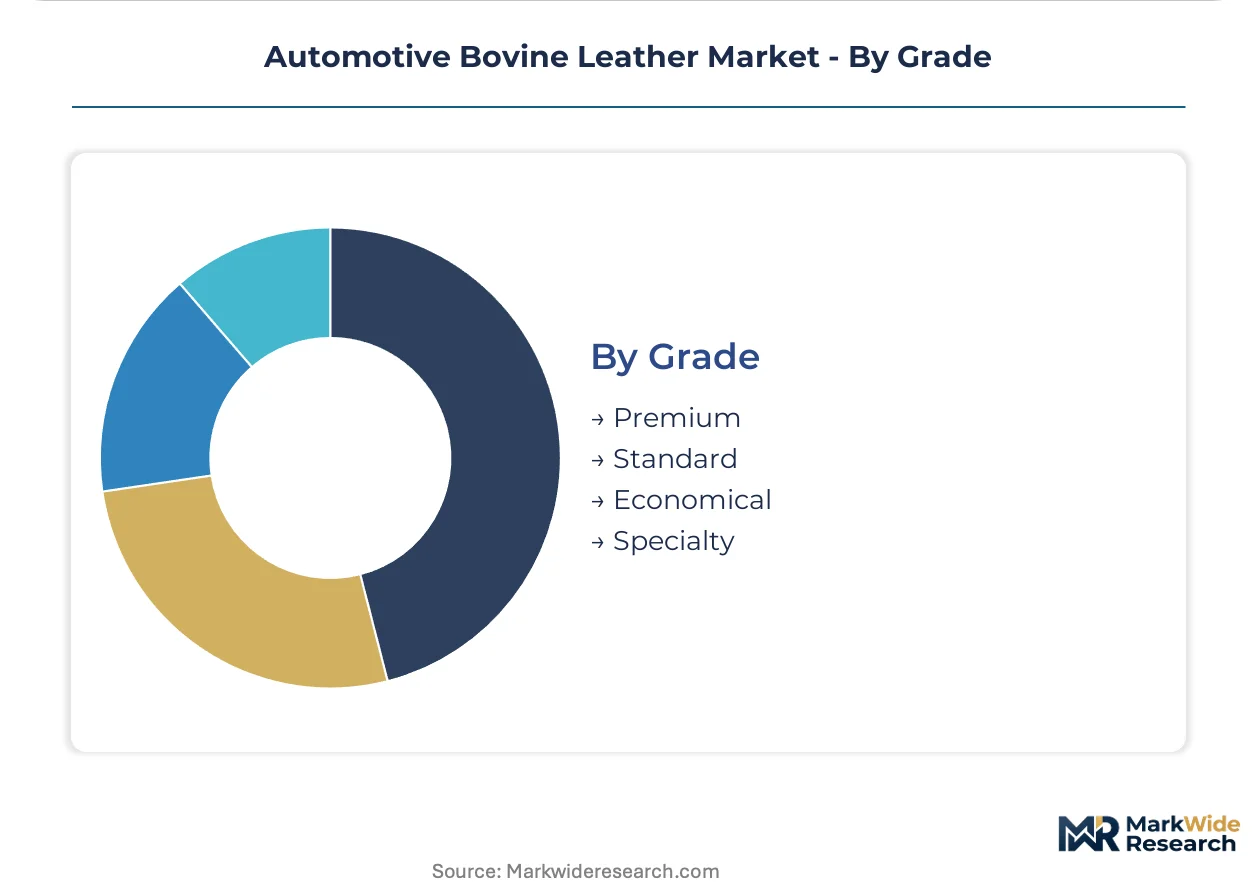
Premium grade absorbs the majority of vegetable-t tanning investment as regulatory compliance costs align with willingness-to-pay in luxury vehicle segments, while economical grade faces the steepest synthetic encroachment.
- Premium:Full-grain selections with minimal surface correction, natural aniline finishes, and metal-free tanning certification. German OEMs specify this grade for flagship EV interiors where REACH Annex XVII compliance and carbon border adjustment readiness justify 40-60% price premiums over standard alternatives.
- Standard:Corrected grain with pigmented finishes, balancing durability and cost across mid-luxury and mass-premium vehicle lines. Chrome-tanned processes still dominate this tier though wet-white reformulation is accelerating.
- Economical:Heavy-corrected split leather and embossed finishes for cost-targeted vehicle programs, experiencing the fastest displacement by polyurethane microfiber suppliers in standard-grade seating applications.
- Specialty:Custom-tanned lots with unique dye formulations, perforation patterns, or aroma treatments for limited-edition vehicle programs and designer collaboration interiors.
Premium grade commands the value pool concentration while economical grade contracts most rapidly under synthetic substitution pressure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across automotive leather procurement. Stuttgart and Munich OEMs absorb 40-60% premiums for REACH-compliant vegetable-tanned grades, while Mexican and Chinese assemblers prioritize cost-engineered splits. This elasticity gap drives divergent supply chain configurations.
Germany
Luxury EV cabin programs from BMW, Mercedes-Benz, and Porsche drive full-grain offtake. ECHA REACH Annex XVII enforcement on hexavalent chromium accelerates wet-white process reformulation across Bavarian tanneries. The Stuttgart-Munich corridor hosts Bader GmbH and Lear Corporation sequencing operations serving final assembly plants.
China
Domestic premium vehicle production from NIO, Li Auto, and BYD expands metal-free leather qualification. GB standards and MEE wastewater discharge enforcement create technical barriers favoring pre-certified European tanneries. Yangtze River Delta clusters in Shanghai and Zhejiang concentrate cut-and-sew capacity for German joint-venture assemblers.
Italy
Gruppo Mastrotto and Arzignano tanneries leverage vertical control over European and Brazilian raw hide flows. EU Green Deal carbon border adjustments elevate compliance investment for chrome-tanned exports. Santa Croce sull'Arno specialty houses supply hand-finished vegetable-tanned lots for limited-edition interiors.
United States
Detroit Three OEMs consolidate procurement authority under direct material management, displacing tiered supplier delegation. EPA emissions standards and NHTSA flammability protocols extend qualification cycles for imported finished leather. Michigan and Ohio seating plants source through just-in-sequence contracts with Mexican beamhouse operations.
Mexico
Proximity to US final assembly enables logistics-adjacent margin capture for tanneries with integrated finishing. Boxmark Leather operates beamhouse-to-cut capacity serving Detroit OEMs from Nuevo León facilities. NAFTA-era supply chain infrastructure supports rapid sequencing for high-volume vehicle programs.
Automotive Bovine Leather Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with ownership concentration in German family operations and Italian industrial groups. The upper tier commands qualification pipelines through captive beamhouse capacity and OEM direct relationships. Mid-tier specialists compete on cut-and-sew proximity and regional certification speed. Consolidation pressure operates through OEM procurement centralization rather than horizontal merger activity.
Among German-anchored integrated players, Bader GmbH & Co. KG and Boxmark Leather GmbH & Co. KG occupy positions defined by beamhouse-to-finish control across European and Mexican manufacturing footprints. Lear Corporation exemplifies the tier-one seating supplier archetype, functioning as a cut-and-sew intermediary now facing procurement authority erosion from direct OEM hide sourcing. Gruppo Mastrotto represents Italian vertical integration models built on regional raw material sourcing dominance and specialty finishing expertise for limited-volume programs.
| Leading Market Players |
|---|
| Bader GmbH & Co. KG |
| GST AutoLeather |
| Lear Corporation |
| Adient |
| Toyota Boshoku Corporation |
| Forvia SE |
| Gruppo Mastrotto |
| Boxmark Leather GmbH & Co. KG |
| Wollsdorf Leder |
| Others |
Supply Flow & Price Mechanics
Forty-five to sixty days of hide inventory at Italian beamhouses compresses margin buffers when Brazilian cattlehide flows tighten, concentrating pricing power among vertically integrated tanneries with captive raw material sourcing. This lead-time exposure shapes how Stuttgart OEMs negotiate contract structures and how Mexican cut-and-sew operations buffer against European supply shocks.
Pricing Analysis
After-sales service contracts for cabin retrimming and warranty-period repairs drive lifetime value capture beyond initial hide sales. Three-tier pricing structure across premium, standard, and economy levels stratifies by REACH certification status and chrome-free tanning chemistry. Cost compression in economical-grade splits intensifies as polyurethane microfiber suppliers capture standard seating volume. Mexican vehicle assemblers exhibit the sharpest price sensitivity, while German luxury EV programs absorb 40-60% premiums for vegetable-tanned full grain.
Supply Chain Analysis
Container availability on Asia-Europe trade lanes constrains finished leather flows to Yangtze River Delta assembly plants, elevating landed costs for European tanneries serving Chinese joint ventures. Supply concentrates in Italy, Germany, and Brazil, with beamhouse capacity drawing from European and Brazilian cattlehide flows. Wet-chemistry expertise scarcity in European vocational pipelines creates single-source vulnerability for vegetable-tanned production. Distribution runs through just-in-sequence contracts with Tier 1 seating suppliers in Michigan, Stuttgart, and Shanghai.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized beamhouse technicians capable of metal-free tanning process control have become the constraining asset, with European training pipelines failing to replenish expertise lost to retirement. This capability gap defines competitive positioning for the next qualification cycle.
For Market Incumbents: Compound qualification pipeline advantages by pre-certifying wet-white reformulations ahead of ECHA enforcement windows, while securing long-term offtake agreements with NIO and Li Auto to lock in Chinese premium EV volume. Synthetic leather substitution in economical-grade seating demands accelerated R&D investment in fogging-compliant vegetable-tanned alternatives. For New Entrants and Emerging Players: Aftermarket restoration services for classic vehicle interiors present an under-served margin pool where specification flexibility exceeds production-line constraints and price sensitivity remains muted. Target independent upholsterers in Germany and Italy with hand-finished specialty lots and carbon-footprint certification. A direct-to-restorer digital platform bypasses tiered supplier gatekeepers. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-compliance premium play because REACH Annex XVII expansion and EU carbon border adjustments will continuously elevate technical barriers to market entry. Acquisition targets should display pre-certified metal-free processes and established OEM direct relationships. The signal to watch is qualification cycle duration extension beyond 18 months, indicating compliance complexity sufficient to deter new entrants.| Strategic Initiative | Industry Significance |
|---|---|
| Wet-White Process Reformulation | ECHA REACH Annex XVII compliance preserves European market access for Bavarian and Arzignano tanneries. |
| Metal-Free Tanning Line Qualification | Pre-certified chrome-free chemistry captures Stuttgart and Munich OEM specification control. |
| Just-in-Sequence Delivery Contracts | Proximity to Nuevo León and Puebla assembly plants secures logistics-adjacent margin pools. |
| Direct OEM Material Management | Beamhouse-to-finish traceability displaces tiered supplier delegation in Detroit procurement. |
| Digital Grading Platform Deployment | AI-powered hide optimization compresses yield variance between full-grain and split-leather processors. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted across primary interview programs, including beamhouse operations managers at Italian and German tanneries, OEM procurement leads in Stuttgart and Detroit, Tier 1 seating supplier executives, and aftermarket restoration specialists. Secondary validation drew from ECHA REACH regulatory filings, EU Green Deal policy documentation, GB standards publications, vehicle production databases, and customs trade records. Bottom-up hide consumption estimates triangulated against top-down OEM interior specification surveys.
Across the analysis window, volume and value outputs reflect segmentation modeling across product type, application, end user, and grade tiers, with additional dimensioning by tanning chemistry and regional regulatory cluster. CAGRs were derived from trend-line extrapolation of hide procurement volumes against vehicle production forecasts and specification mix shifts. Key inputs included livestock cycle projections for European and Brazilian cattlehide supply, and OEM interior content per vehicle trajectories for luxury EV programs.
Underlying assumptions cover REACH Annex XVII enforcement timelines, EU carbon border adjustment implementation scope, and MEE wastewater discharge compliance trajectories in China, with deviation risk concentrated in regulatory delay or acceleration and synthetic leather technical performance breakthroughs. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Interior & Exterior
Automotive Liftgate Market
Automotive Interior & Exterior
India Automotive Door Seals Market
Automotive Interior & Exterior
Automotive Advanced Seating System Market
Automotive Interior & Exterior
Blind Spot Mirror Market
Automotive Interior & Exterior
Automotive Door Stabilizer Market
Automotive Interior & Exterior
Automotive Airbag Fabric Market
Automotive Interior & Exterior
Rear-View Mirror Market
Automotive Interior & Exterior
Germany Automotive Adaptive Lighting System Market
Automotive Interior & Exterior
Auto Dimming Mirror Market
Automotive Interior & Exterior
Automotive Ventilated Seats Market
Automotive Interior & Exterior
Automotive Automatic Liftgate Market
Automotive Interior & Exterior
Automotive Center Stack Display Market
Automotive Interior & Exterior
Automotive Air Suspension System Market
Automotive Interior & Exterior
United Kingdom Automotive Sunroof Market
Automotive Interior & Exterior
Global Automotive Side Window Sunshades Market
Automotive Interior & Exterior
China Automotive Seats Market