
 United Kingdom Automotive Sunroof Market | 2026-2036
United Kingdom Automotive Sunroof Market Size, Share, and Industry Trends Forecast 2026-2036
United Kingdom Automotive Sunroof Market Analytics
UN ECE R43 automotive safety glazing certification is reorganizing supplier eligibility across the United Kingdom Automotive Sunroof Market. Webasto Roof Systems leverages its captive glass laminating capacity to anchor premium OEM contracts with British-based vehicle assemblers. Aisin Seiki competes through precision rail mechanism specialization that sustains repeat platform wins with Japanese-British joint venture plants. Inalfa Roof Systems differentiates via modular frame architectures that reduce water management complexity for UK climate conditions.
An automotive sunroof constitutes a precision-engineered opening panel assembly, typically comprising tempered or laminated glass bonded to aluminum or composite frame rails, with integrated drainage channels, electric drive motors, and electronic control modules; its primary function delivers cabin ventilation, natural illumination, and perceived interior spaciousness to vehicle occupants. Panoramic configurations now command the highest absolute value contribution as British consumers prioritize cabin openness in premium segments. Glass material specifications dominate factory-installed volumes, while aluminum frames retain structural importance for weight-sensitive electric vehicle platforms. OEM channel concentration reflects the technical integration demands of modern roof systems, though aftermarket providers occupy a resilient niche for collision repair and used vehicle refurbishment.
The UK's Vehicle Certification Agency administers UN ECE R43 compliance for glazing integrity, while the Health and Safety Executive governs manufacturing workplace exposures to resin and adhesive chemistries. Type-approval alignment with EU REACH substance restrictions continues shaping material selections for seals and bonding agents used in British assembly operations. Stakeholders must monitor evolving Euro NCAP pedestrian protection protocols, as these influence glass retention system designs and frame edge radii requirements. Forward visibility demands integration of sunroof control logic with emerging vehicle autonomy sensor suites.
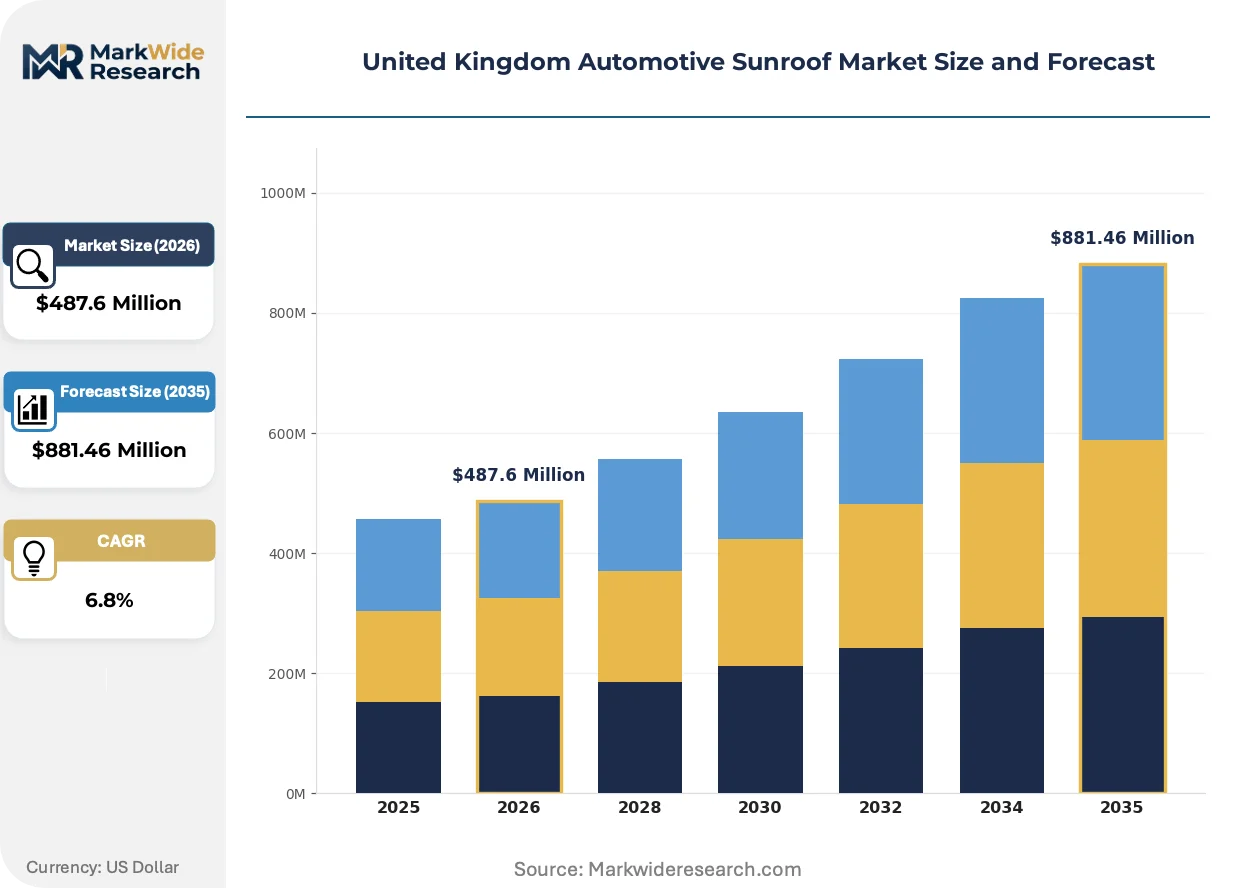
Market Dynamics
UN ECE R43 glazing safety certification is restructuring supplier eligibility across the United Kingdom Automotive Sunroof Market, forcing laminated glass substitution and eliminating uncertified component sources from OEM supply chains.
Growth Catalysts
- Electric vehicle platform expansion:British EV manufacturers prioritize panoramic glass configurations to offset battery weight through aluminum frame rails while delivering cabin spaciousness perception.
- REACH substance alignment:EU-UK regulatory continuity on adhesive and seal chemistry standards sustains material qualification pathways for British assembly operations.
- West Midlands manufacturing corridor concentration:Proximity to Jaguar Land Rover, Aston Martin, and Mini production sites creates localized demand density for just-in-time sunroof module delivery.
Market Restraints
- Specialized glass laminating capacity scarcity:Only three qualified suppliers operate captive UK laminating lines, creating single-source vulnerability for premium OEM programs.
- Aluminum frame input cost volatility:Primary aluminum price fluctuations from LME trading directly compress module margins for weight-optimized electric vehicle specifications.
- Polycarbonate substitution threat:Lightweight polymer glazing advances from German and Japanese material science firms threaten glass dominance in entry-segment applications.
Strategic Opportunities
- Greater London premium retail channel penetration:Flagship dealership networks for Mercedes-Benz, BMW, and Audi command higher attachment rates for factory panoramic options.
- Scotland EV infrastructure corridor development:Aberdeen-to-Edinburgh electrification initiatives create fleet demand for glass roof configurations in commercial lease vehicles.
- Vehicle Certification Agency type-approval streamlining:Proposed mutual recognition protocols with EU notified bodies could accelerate dual-market product launches for British suppliers.
Industry Challenges
- Mechatronics integration complexity:Synchronizing sunroof control modules with ADAS sensor calibration requires cross-functional engineering teams scarce in UK automotive electronics labor pools.
- UN ECE R43 certification timeline compression:Extended homologation cycles for novel glass retention systems delay platform launch windows for model-year dependent OEMs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Kingdom Automotive Sunroof Market |
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $881.46 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Panoramic, Standard, Solar, Inbuilt Material: Glass, Plastic, Aluminum, Carbon Fiber End User: OEMs, Aftermarket Providers, Tier-1 Suppliers, Dealerships Installation Type: Factory-installed, Retro-fit, Dealer-installed, Custom |
| Companies Covered | Aisin Seiki, Mitsuba Corp., Webasto Roof Systems, Sunroof Centre, Automotive Sunroof Company, Inalfa Roof Systems, Yachiyo Industry, Evana Automation, Inteva Products, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Kingdom Automotive Sunroof Market Evolving Landscape
Smart glass technology and regulatory chemistry restrictions are actively reshaping material specifications and control system architectures across British sunroof manufacturing.
Electrochromic dimmable glass is displacing traditional mechanical sunshade systems in premium SUV and executive sedan segments. Jaguar Land Rover and Bentley Motors have adopted variable-transmittance glazing across 2024-2026 model year platforms. This technology is displacing textile-based shade suppliers from tier-2 supply positions while requiring new wire harness and voltage management integration.
EU REACH substance restrictions on isocyanate-based adhesive formulations are forcing polyurethane substitution in British assembly operations. The Health and Safety Executive workplace exposure limits are accelerating water-based bonding agent qualification programs at West Midlands manufacturing plants. Laminated glass suppliers serving UK OEMs are reformulating interlayer chemistries to maintain structural integrity under revised compliance timelines.
Fleet procurement managers are consolidating sunroof specification decisions into centralized vehicle configuration platforms. Direct OEM-to-fleet relationships are replacing traditional dealer-option selection for corporate lease vehicles. This shift concentrates most visibly in Greater London financial services and technology sector fleet operations where standardized amenity packages reduce administrative overhead.
United Kingdom Automotive Sunroof Market Segmentation
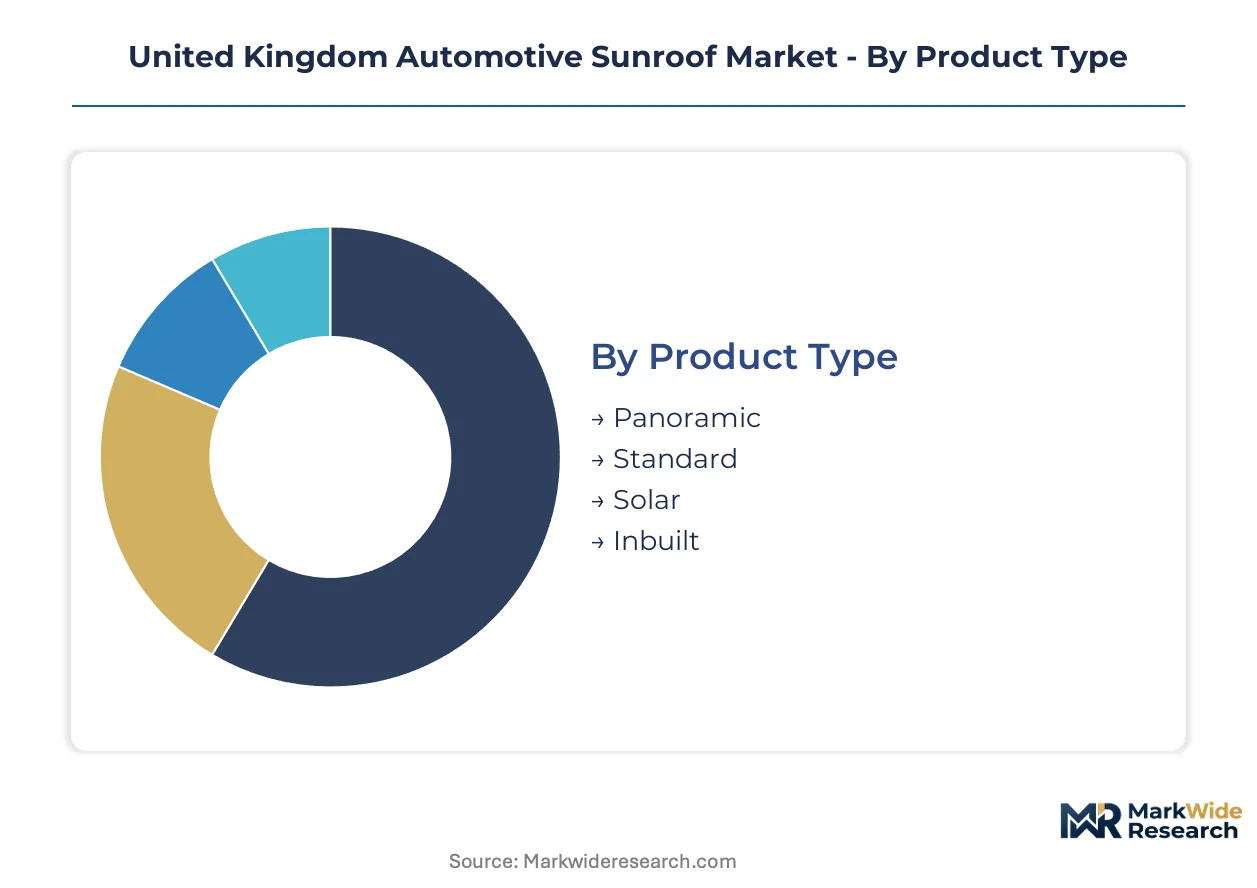
Segmentation reveals how sunroof demand fragments across vehicle specification tiers, material performance requirements, and channel economics within the United Kingdom. Understanding these divisions exposes where premium pricing power concentrates versus where volume commoditization pressures margins.
Product Type:
Panoramic configurations dominate export-oriented production from British luxury OEMs, while standard formats serve domestic fleet procurement with tighter cost constraints.
- Panoramic:Multi-panel glass assemblies spanning front and rear cabin zones, bonded to reinforced aluminum perimeter frames. Jaguar Land Rover and Bentley Motors anchor demand from West Midlands assembly plants, driven by premium SUV buyer preference for cabin spaciousness perception. Factory-installed panoramic options command the highest absolute value contribution across all product categories.
- Standard:Single-panel pop-up or spoiler designs with manual or electric actuation, typically 300-400mm aperture width. Concentrates in Mini and mainstream volume production serving Greater London retail channels, constrained by fleet procurement standardization that treats sunroofs as discretionary amenities.
- Solar:Photovoltaic-integrated glass panels with embedded silicon cells generating supplementary vehicle power. Emerging specification for electric vehicle platforms seeking range extension through cabin-top energy harvesting.
- Inbuilt:Flush-mounted sliding mechanisms with internal headliner integration, preserving exterior roofline continuity. Favored by executive sedan segments prioritizing aerodynamic efficiency and noise isolation.
Panoramic holds the largest share; momentum sits with solar as EV platform integration accelerates.
Material:
Material selection splits between weight-driven electric vehicle specifications and cost-optimized legacy platforms, with regulatory chemistry constraints reshaping bonding compatibility.
- Glass:Tempered or laminated configurations meeting UN ECE R43 glazing integrity standards, with interlayer chemistries reformulating under REACH substance restrictions. Webasto Roof Systems and Inalfa Roof Systems maintain captive laminating capacity for British OEM programs, though only three qualified suppliers operate UK-based lines creating supply concentration risk.
- Aluminum:Extruded frame rails and perimeter reinforcements delivering strength-to-weight ratios critical for battery electric vehicle roof structures. Primary aluminum price volatility from LME trading directly compresses module margins for weight-sensitive specifications.
- Plastic:Polycarbonate and acrylic glazing alternatives offering 40-50% mass reduction versus glass, primarily in aftermarket retro-fit applications where regulatory compliance requirements are less stringent.
- Carbon Fiber:High-modulus composite frame elements for ultra-low-volume specialist vehicles, limited to Aston Martin and niche motorsport-derived road car programs.
Glass maintains volume dominance; carbon fiber is climbing the fastest as lightweighting imperatives intensify.
End User:
Channel concentration reflects technical integration complexity, with factory-installed volumes dwarfing aftermarket fragmentation despite collision repair resilience.
- OEMs:Vehicle manufacturers specifying sunroof modules at platform design stage, requiring just-in-time delivery synchronization with body-in-white assembly sequences. West Midlands corridor concentration around Jaguar Land Rover, Aston Martin, and Mini plants creates localized demand density for tier-1 module suppliers.
- Tier-1 Suppliers:System integrators such as Aisin Seiki and Webasto Roof Systems managing rail mechanism precision engineering and electronic control module calibration for OEM assembly line installation.
- Aftermarket Providers:Independent specialists serving collision repair and used vehicle refurbishment demand, occupying a resilient niche despite declining new vehicle penetration of retro-fit installations.
- Dealerships:Retail channel intermediaries facilitating factory option selection, increasingly bypassed as fleet procurement managers consolidate configuration decisions into centralized platforms.
OEMs capture the largest share; tier-1 suppliers are gaining share fastest through module integration depth.
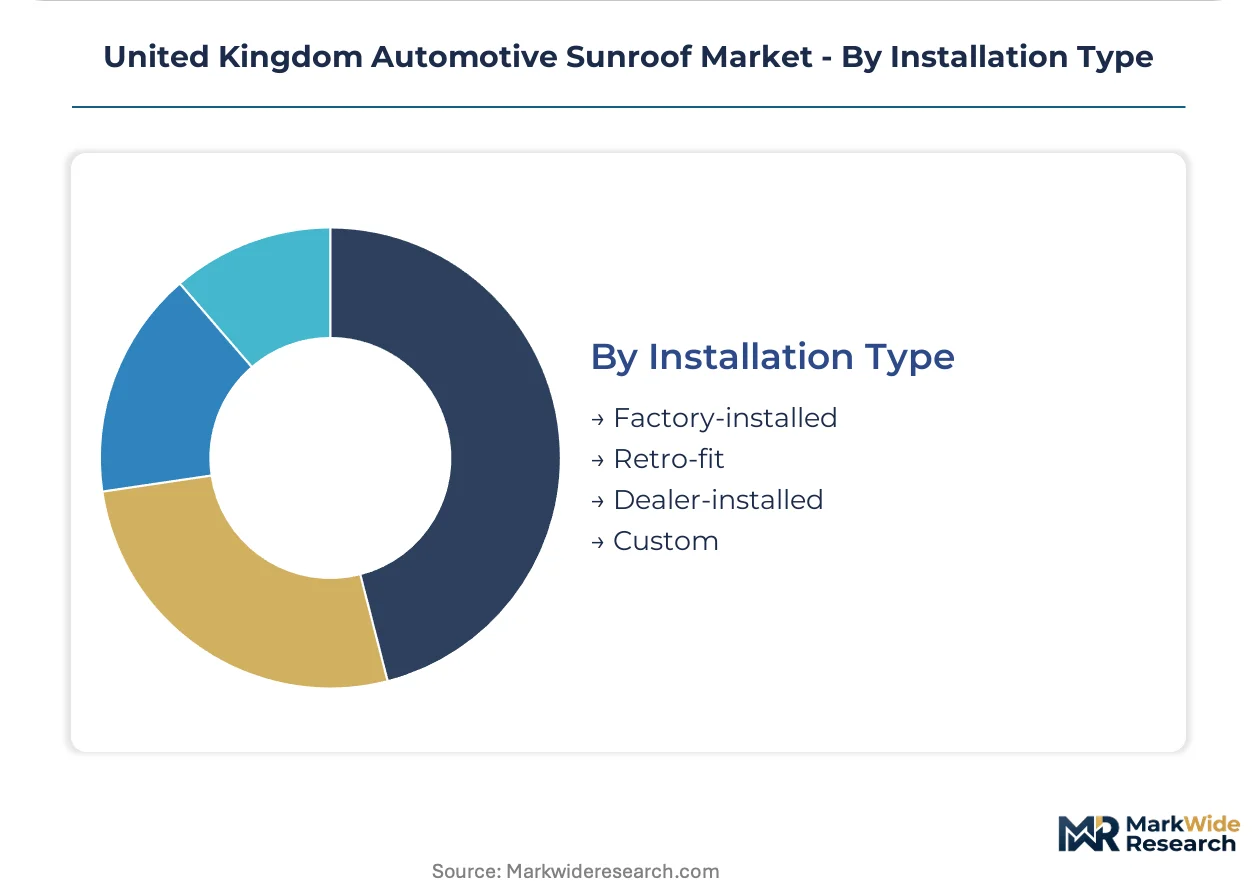
Installation Type:
Installation economics diverge sharply between capital-intensive factory automation and labor-intensive aftermarket customization, with regulatory type-approval barriers protecting OEM channel dominance.
- Factory-installed:Modules integrated during vehicle assembly with robotic sealing, drainage channel formation, and electronic calibration. Requires Vehicle Certification Agency type-approval alignment with UN ECE R43 standards, creating regulatory barriers to aftermarket competition.
- Dealer-installed:Port- or dealership-level installation of pre-approved accessory packages, primarily for standardized sunroof configurations avoiding complex bodywork modification.
- Retro-fit:Aftermarket modification of vehicles not originally specified with sunroof openings, constrained by structural integrity concerns and insurance classification complications.
- Custom:Bespoke fabrication for specialist vehicle conversions and luxury coachbuilding applications, limited to ultra-low volumes with manual craftsmanship economics.
Factory-installed holds the largest share; dealer-installed shows steepest expansion trajectory as fleet standardization reduces administrative overhead.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
UK government zero-emission vehicle mandates and corporate fleet electrification incentives are redistributing automotive sunroof demand toward England's manufacturing corridors and Scotland's emerging EV infrastructure zones.
England West Midlands
Jaguar Land Rover and Aston Martin assembly plants anchor panoramic sunroof consumption for premium SUV and luxury segments. The Vehicle Certification Agency enforces UN ECE R43 glazing standards that disqualify uncertified suppliers from OEM programs. Birmingham and Coventry host concentrated tier-1 module logistics operations serving just-in-time production schedules.
Greater London
Corporate fleet procurement from financial services and technology sectors standardizes factory-installed panoramic configurations across executive lease vehicles. Transport for London congestion charge exemptions for electric vehicles accelerate glass roof adoption as cabin spaciousness offsets battery packaging constraints. Flagship dealership networks in Kensington and Mayfair command premium attachment rates for electrochromic dimmable options.
England North West
Mini production at Plant Oxford draws standard sunroof specifications for volume hatchback platforms serving domestic retail channels. REACH substance alignment on adhesive chemistries shapes supplier qualification at Manchester-area component distribution hubs. Liverpool port facilities handle imported glass laminating equipment for regional assembly operations.
Scotland
Aberdeen-to-Edinburgh electrification corridors generate fleet demand for solar-integrated glass configurations in commercial lease vehicles. Scottish Enterprise low-carbon transport grants support EV infrastructure development that indirectly stimulates premium cabin amenity specification. Glasgow manufacturing technology parks host emerging rail mechanism calibration facilities.
Wales
Specialist vehicle conversion operations in South Wales occupy niche custom sunroof fabrication for motorsport-derived road car programs. The Health and Safety Executive workplace exposure limits on resin chemistries accelerate water-based bonding agent adoption at Cardiff-area assembly plants. Swansea University materials research partnerships influence lightweight frame composite development.
United Kingdom Automotive Sunroof Market Competitive Landscape
Player mix skews toward integrated glass-laminating specialists and precision mechanism engineers, with tier-1 module integrators commanding OEM channel access through captive certification assets. Strategic archetypes separate into three clusters: captive laminating capacity holders, rail mechanism precision specialists, and modular frame architecture innovators. Competitive moves concentrate on M&A for laminating line acquisition and strategic partnerships for ADAS integration capability.
Among Japanese-origin precision engineering groups, Aisin Seiki and Mitsuba Corp. occupy positions emphasizing electromechanical control specialization. Webasto Roof Systems and Inalfa Roof Systems represent European-heritage integrated module suppliers with captive glass processing assets. Yachiyo Industry anchors Asian-origin frame fabrication expertise within the supplier ecosystem.
| Leading Market Players |
|---|
| Aisin Seiki |
| Mitsuba Corp. |
| Webasto Roof Systems |
| Sunroof Centre |
| Automotive Sunroof Company |
| Inalfa Roof Systems |
| Yachiyo Industry |
| Evana Automation |
| Inteva Products |
| Others |
Value Network & Pricing Analysis
Long-term offtake agreements between Jaguar Land Rover and Webasto Roof Systems lock in laminated glass supply while anchoring price visibility against LME aluminum volatility. These contracts concentrate procurement power among three qualified UK laminating suppliers, amplifying margin pressure when primary metal costs spike.
Pricing Analysis
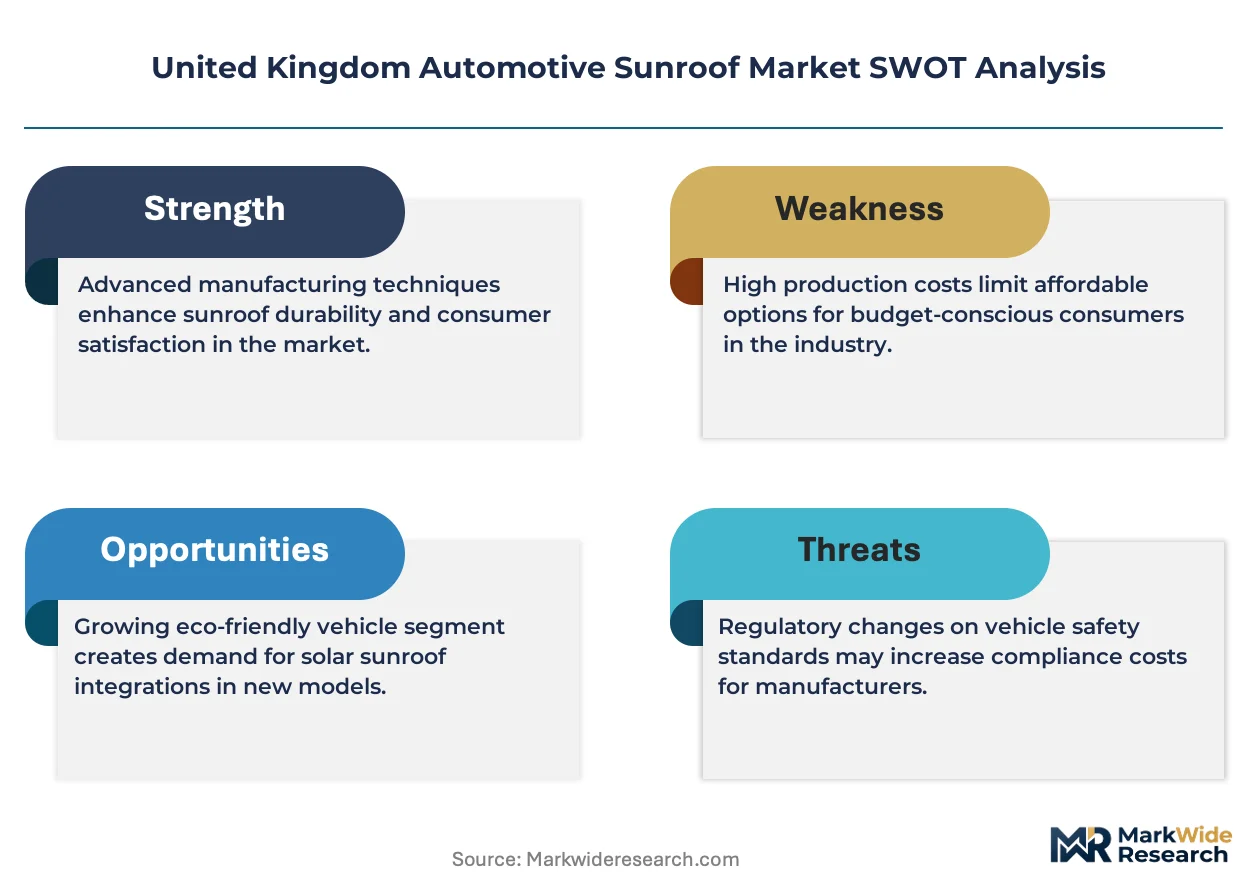
Certification level under UN ECE R43 creates the primary spread between premium OEM modules and aftermarket alternatives. Three-tier pricing structure separates factory-installed panoramic systems from dealer-accessory packages and collision-replacement components. Cost compression in standard-format segments is intensifying because fleet procurement managers treat sunroofs as discretionary amenities. Volume hatchback platforms exhibit highest price sensitivity; Bentley and Aston Martin programs show least.
Supply Chain Analysis
Just-in-time inventory strategies dominate West Midlands assembly corridors, with tier-1 suppliers holding maximum 72-hour glass stockpiles to minimize working capital. Geographic supply concentration rests on Germany for precision rail mechanisms, Belgium for specialized interlayer films, and China for aluminum extrusion feedstock. Raw material dependencies include primary aluminum from LME warehouses, PVB interlayer resin, and electrochromic coating chemicals. Single-source vulnerability threatens qualified UK laminating lines. Distribution runs through Birmingham logistics hubs synchronized to body-in-white sequences.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents must defend glass-based roof systems against polycarbonate substitution threats from German and Japanese material science firms advancing lightweight polymer glazing.
For Market Incumbents: Compound captive laminating capacity advantages by securing additional UN ECE R43 certification slots before regulatory timeline compression eliminates uncertified competitors. Deepen backward integration into aluminum frame extrusion to offset LME price volatility eroding electric vehicle module margins.
For New Entrants and Emerging Players: Anchor in Scotland's Aberdeen-to-Edinburgh electrification corridor where fleet standardization creates concentrated demand for solar-integrated glass configurations. Target commercial lease vehicles with range-extension value propositions bypassing entrenched premium OEM relationships.
For Investors and Strategic Acquirers: Capital is best deployed toward tier-1 module integrators possessing ADAS synchronization capabilities and Vehicle Certification Agency type-approval assets. Long-term viability hinges on mechatronics integration depth rather than commodity glass processing. Watch for electrochromic dimmable glass attachment rate inflections in Greater London flagship dealerships.
| Strategic Initiative | Industry Significance |
|---|---|
| Captive Glass Laminating Acquisition | UN ECE R43 certification scarcity creates defensive moats against uncertified imports. |
| ADAS Integration Partnership | Sunroof control module calibration with autonomous sensor suites commands premium positioning. |
| Scotland EV Fleet Penetration | Aberdeen-to-Edinburgh corridor electrification generates concentrated commercial lease demand. |
| Electrochromic Technology Licensing | Jaguar Land Rover and Bentley adoption validates variable-transmittance glazing economics. |
| Aluminum Frame Backward Integration | LME price hedging through in-house extrusion protects electric vehicle module margins. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across the United Kingdom Automotive Sunroof Market. Primary interviews captured tier-1 supplier procurement directors, OEM platform engineers, aftermarket distributors, and dealership operations managers. Secondary validation drew from Vehicle Certification Agency type-approval databases, UN ECE R43 compliance registries, IHS Markit vehicle production data, and Health and Safety Executive workplace exposure filings. Bottom-up volume modeling triangulated against top-down value estimates.
Across the analysis window, forecasts segmented by vehicle class, propulsion architecture, content per vehicle, and regional production cluster. CAGRs derived from production volume trajectories, content-per-vehicle trends, and pricing elasticity assumptions. Industry-specific inputs included laminated glass substitution rates under REACH substance restrictions and electrochromic dimmable glass penetration curves.
Material uncertainties — regulatory timeline compression for novel glass retention systems, LME aluminum price volatility, and polycarbonate substitution advances — sit outside the modeled envelope. Forecasts reflect assumptions about UN ECE R43 certification continuity and EU-UK REACH alignment durability. Revision becomes warranted when polycarbonate glazing achieves regulatory equivalence thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Interior & Exterior
Railway Interiors Market
Automotive Interior & Exterior
India Automotive Adaptive Lighting System Market
Automotive Interior & Exterior
Truck Parking Air Conditioner Market
Automotive Interior & Exterior
Fog Free Mirrors Market
Automotive Interior & Exterior
PVC and PU Leather for Automotive Market
Automotive Interior & Exterior
Automotive Underbody Coatings Market
Automotive Interior & Exterior
Argentina Automotive Adaptive Lighting System Market
Automotive Interior & Exterior
Automotive Roof Liners Market
Automotive Interior & Exterior
Automotive Decorative Exterior Trim Market
Automotive Interior & Exterior
Automotive Door Sills Market
Automotive Interior & Exterior
Automotive Tinting Film Market
Automotive Interior & Exterior
Global Headliner (OE) Market
Automotive Interior & Exterior
Automotive Energy Absorption (EA) Pads Market
Automotive Interior & Exterior
Door Panel Market
Automotive Interior & Exterior
Global Automotive Interiors Market
Automotive Interior & Exterior
Automotive Digital Rear View Mirror Market