
 Automotive Glove Box Market | 2026-2036
Automotive Glove Box Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Glove Box Market Analysis
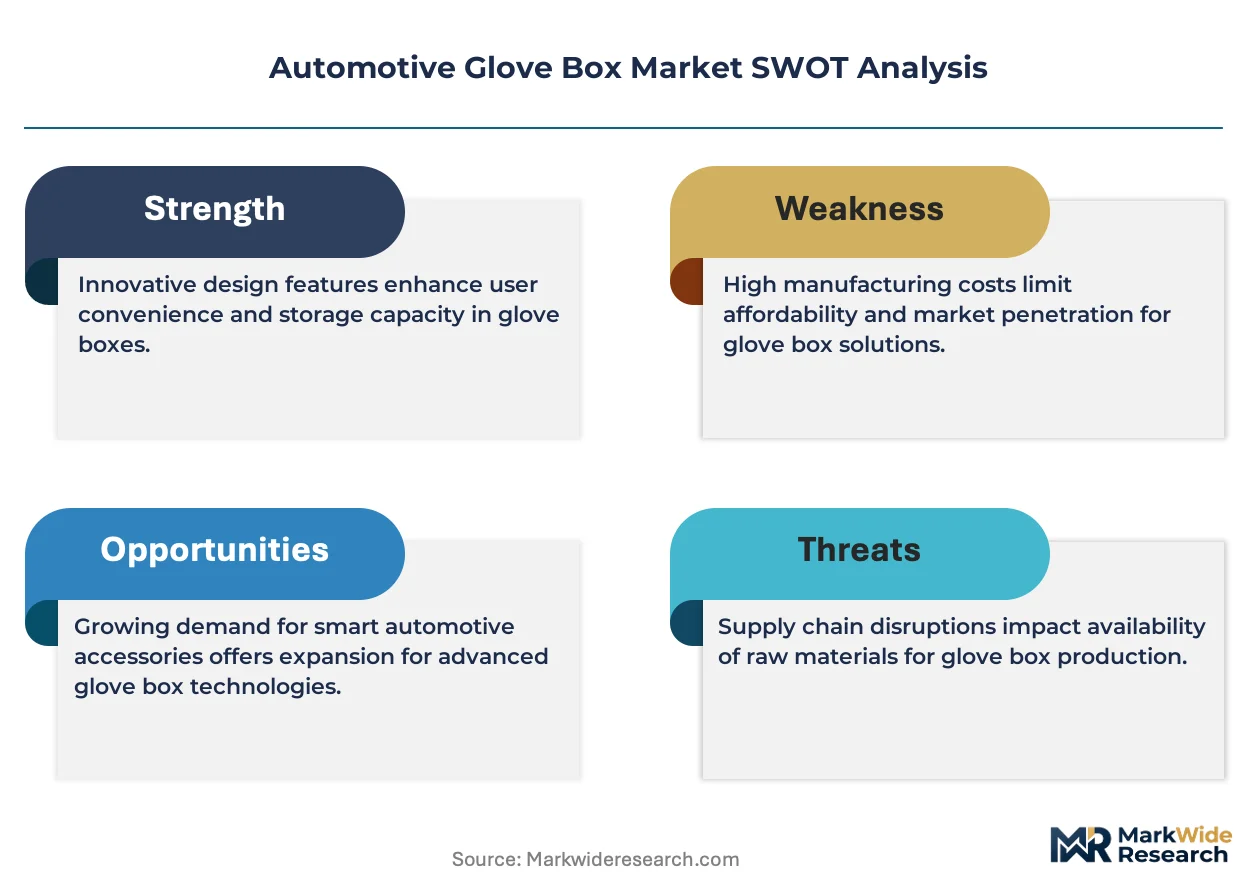
Asset-light leasing arrangements for injection-molding equipment is tilting competitive dynamics toward suppliers with flexible capital structures. Magna International leverages captive tooling partnerships to sustain volume flexibility across North American assembly lines. Yanfeng Automotive Interiors anchors its position through integrated cockpit module programs that bundle glove box units with dashboard assemblies. Faurecia competes by specializing in premium surface-finishing capabilities that meet OEM tactile specifications.
An automotive glove box is a sealed or ventilated storage compartment integrated into the passenger-side dashboard, typically constructed from polypropylene or ABS plastic substrates with steel or aluminum hinge mechanisms, designed to secure documents, electronics, and personal items while withstanding temperature cycles from minus forty to eighty-five degrees Celsius. The primary commercial purpose centers on occupant convenience and cabin organization within passenger and commercial vehicles. Lockable glove box variants command margin premiums as theft-deterrence features spread across mid-range vehicle segments. Composite materials represent the fastest-growing material category as weight-reduction targets intensify across OEM platforms. Refrigerated glove box configurations occupy niche positioning within luxury and electric vehicle lineups where cabin comfort differentiation drives specification.
The US NHTSA and EPA regulate interior material flammability and volatile organic compound emissions that directly constrain polymer selection and adhesive formulations in glove box manufacturing. EU REACH and the F-Gas Regulation govern chemical substances and climate-control refrigerants used in cooled compartment variants, creating compliance cost layering for exporters. China's SAMR enforces GB standards for automotive interior plastics that mandate specific thermal stability and fogging-resistance thresholds. Stakeholders must monitor evolving cross-border material certification reciprocity to avoid stranded inventory in multi-regional supply chains.
Market Dynamics
Electric vehicle OEM procurement is expanding glove box specification complexity beyond traditional storage functions toward integrated cabin modules with cooling, connectivity, and premium surface requirements.
Growth Catalysts
- EU REACH chemical compliance:Stricter substance restrictions are accelerating substitution of legacy plasticizers with bio-based polymer alternatives in dashboard-integrated compartments.
- Composite material adoption:Glass-fiber-reinforced polypropylene compounds are displacing conventional ABS substrates as weight-reduction targets intensify across passenger vehicle platforms.
- China's GB standards enforcement:Mandatory thermal stability and fogging-resistance thresholds for automotive interior plastics are upgrading specification tiers across domestic and export-oriented supply chains.
Market Restraints
- Polypropylene resin price volatility:Feedstock cost swings tied to naphtha cracking margins compress margin predictability for injection-molding suppliers.
- German supplier concentration:Premium cockpit module production clusters heavily in Baden-Württemberg and Bavaria, creating geographic vulnerability to regional logistics disruptions.
- Refrigerant regulatory friction:EU F-Gas Regulation phase-down schedules constrain cooled glove box configurations using conventional hydrofluorocarbon climate-control systems.
Strategic Opportunities
- India's PLI scheme for auto components:Production-linked incentives for advanced automotive plastics are attracting glove box subsystem investment toward Pune and Chennai manufacturing corridors.
- Biometric access integration:Fingerprint-activated locking mechanisms are converging with connected vehicle architectures to create premium feature differentiation in electric SUV segments.
- SAMR certification reciprocity expansion:China's evolving mutual recognition agreements for automotive interior material testing are reducing redundant compliance costs for multi-regional suppliers.
Industry Challenges
- Multi-material bonding expertise:Shortages of process engineers skilled in laser welding polypropylene to aluminum hinge substrates constrain production scaling for lightweight designs.
- Cross-border certification lag:Divergent flammability testing protocols between NHTSA FMVSS 302 and EU ECE R118 create extended validation timelines for unified product platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Glove Box Market |
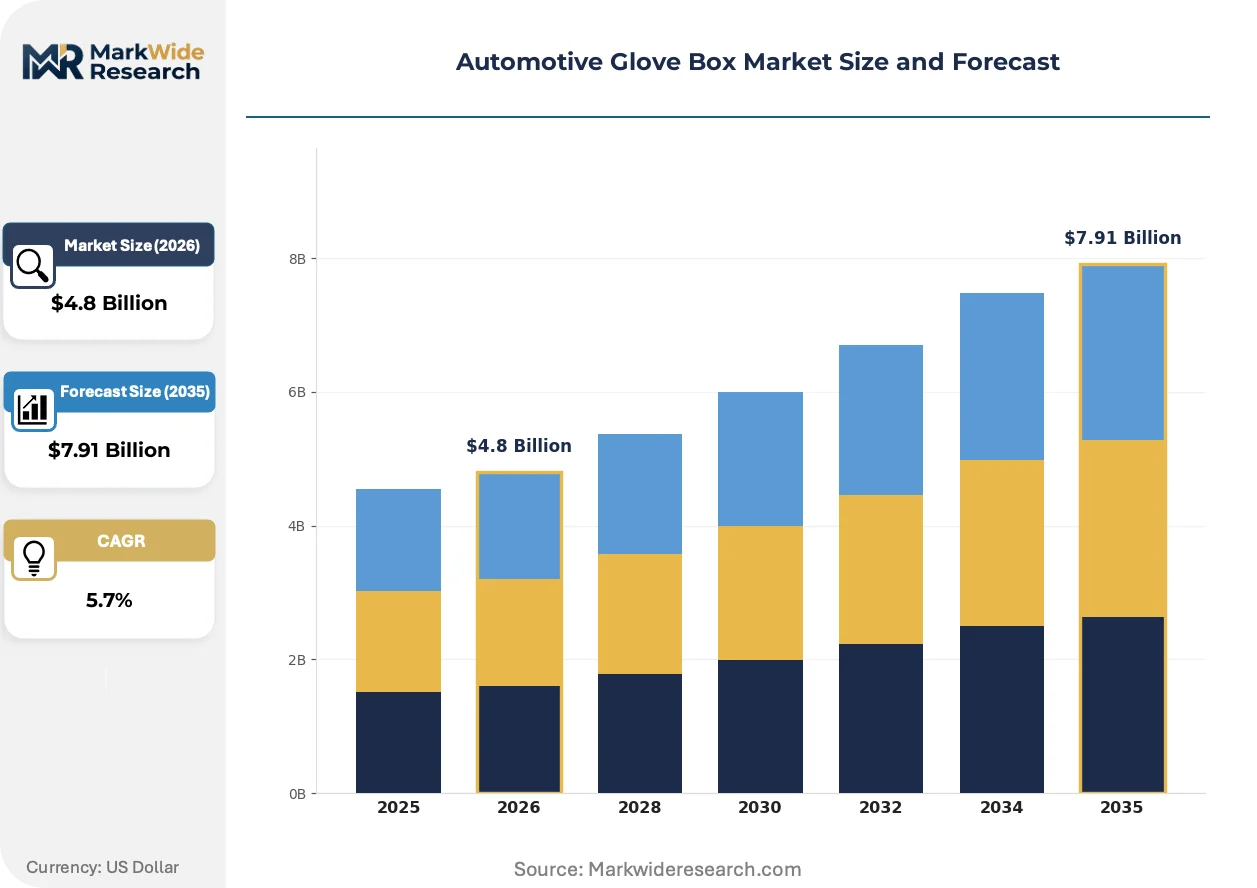
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Glove Box, Lockable Glove Box, Refrigerated Glove Box, Folding Glove Box Material: Plastic, Metal, Leather, Composite Feature: Illuminated, Adjustable, Dustproof, Waterproof Installation: OEM, Aftermarket, Custom, Integrated |
| Companies Covered | Magna International Inc., IAC Group, Visteon Corporation, Yanfeng Automotive Interiors, Faurecia, Hyundai Mobis, Grupo Antolin, Toyoda Gosei, Lear Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Glove Box Market Emerging Trajectories
Material science breakthroughs and regulatory chemistry constraints are simultaneously pulling glove box manufacturing toward lighter substrates and cleaner formulation portfolios.
Active grille ventilation systems are migrating from passive airflow designs to thermostatically controlled fan-assisted configurations. Electric vehicle OEMs in Germany and South Korea are specifying these units for battery thermal management integration. This technology shift is compressing the addressable market for purely mechanical hinge-and-damper assemblies while expanding electronics content requirements.
REACH Annex XVII restrictions on phthalate plasticizers are forcing reformulation of soft-touch overmolding compounds used in premium surface finishes. Compounders serving Faurecia and Yanfeng supply chains are accelerating bio-based adipate ester substitutions. Tier-1 suppliers with in-house polymer laboratories are capturing specification influence previously held by raw material distributors.
Fleet procurement managers are consolidating glove box sourcing through integrated cockpit module contracts rather than discrete component purchases. This buying-pattern compression is displacing standalone glove box specialists from mid-volume vehicle programs. The structural shift is most visible in North American light-truck segments where Magna International and similar tier-0.5 suppliers bundle dashboard, glove box, and HVAC ducting into single-source agreements.
Automotive Glove Box Market Segmentation
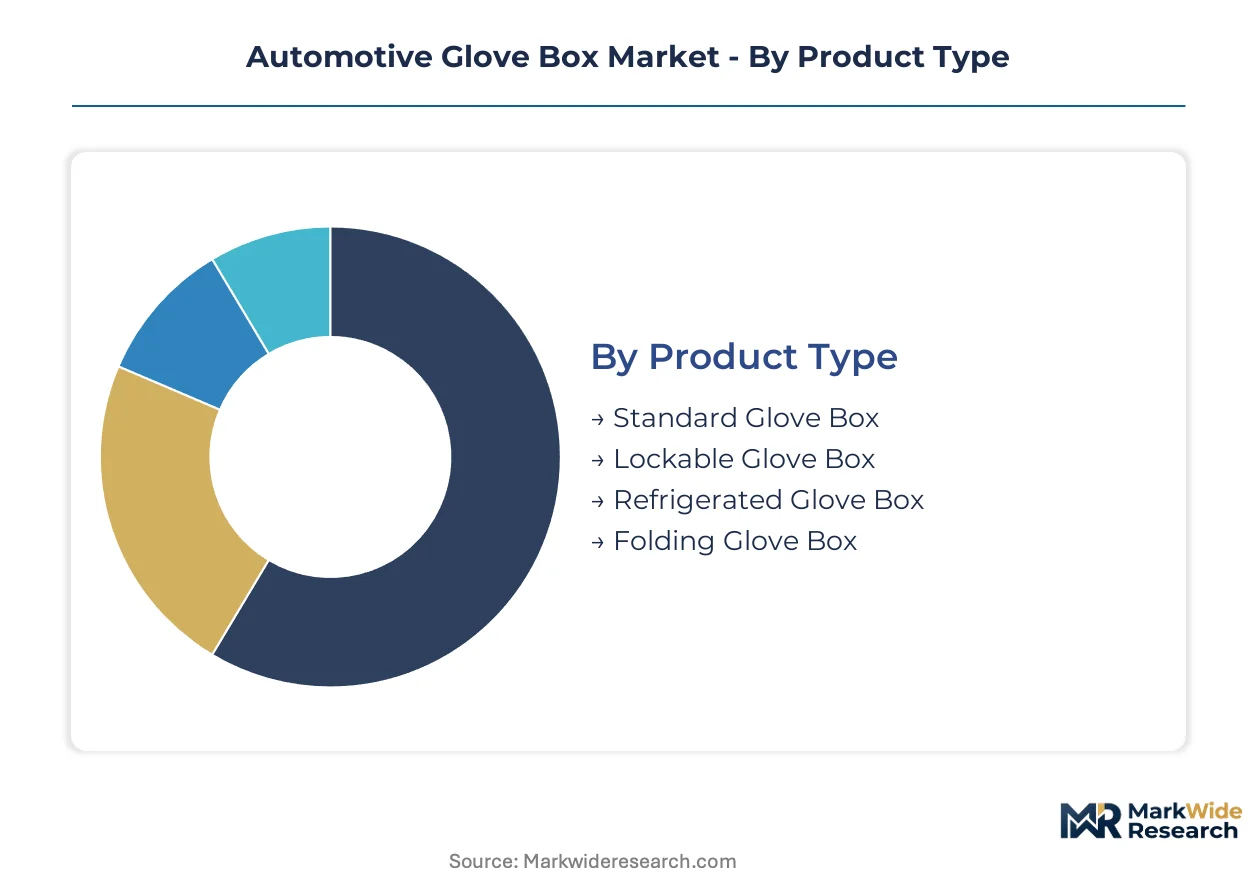
Glove box specification varies sharply across vehicle tiers and electrification strategies, with material choices and feature bundling determining supplier positioning. OEM procurement patterns favor integrated cockpit modules over standalone components, compressing the addressable market for discrete segment specialists.
Product Type:
Mature configurations dominate volume production while emerging variants capture specification premiums in electric vehicle lineups.
- Standard Glove Box:Polypropylene shell construction with steel hinge mechanisms handles routine storage across mass-market passenger vehicles. Demand concentrates in India's compact car manufacturing corridors where cost engineering governs sourcing decisions.
- Lockable Glove Box:Integrated key-cylinder or electronic latch systems secure valuables against theft in fleet and personal-use vehicles. Share is climbing fastest in mid-range electric SUVs where cabin security features differentiate trim levels.
- Refrigerated Glove Box:Thermoelectric or compressor-based cooling maintains beverage and medication temperatures. Premium electric vehicle OEMs in South Korea specify these for cabin comfort differentiation.
- Folding Glove Box:Collapsible internal architecture maximizes storage flexibility in compact vehicle platforms. Urban-focused European OEMs deploy these where dashboard packaging constraints intensify.
Standard configurations handle the majority of throughput; refrigerated variants are gaining share fastest as cabin comfort specifications escalate.
Material:
Cost tier stratification separates commodity substrates from performance-engineered compounds.
- Plastic:Injection-molded polypropylene and ABS substrates deliver cost-efficient volume production across entry and mid-range vehicle segments. NHTSA flammability testing and EU REACH chemical compliance constrain formulation flexibility for exporters.
- Metal:Aluminum and steel alloys reinforce hinge mechanisms and structural frames. German premium OEMs specify these for tactile quality and durability in luxury cockpit modules.
- Leather:Upholstered surface finishes elevate perceived quality in executive vehicle tiers. Italian and British marques source these through integrated dashboard assembly contracts.
- Composite:Glass-fiber-reinforced thermoplastics achieve weight reduction targets without sacrificing structural integrity. This category expands most quickly as OEM platform electrification intensifies mass reduction priorities.
Plastic substrates anchor volume production; composites show the steepest expansion trajectory amid platform lightweighting mandates.
Feature:
Application context determines feature bundling, with visibility and environmental protection driving specification divergence.
- Illuminated:LED or incandescent interior lighting improves content visibility during nighttime operation. Night-shift fleet operators in North America prioritize these for document accessibility.
- Adjustable:Modular internal dividers and shelf positioning adapt storage geometry to varying payload dimensions. Family-oriented vehicle platforms in Japan integrate these for flexible cabin organization.
- Dustproof:Sealed gasket construction protects sensitive electronics and documents from particulate intrusion. Desert-climate markets in the Middle East specify these for reliability under sand exposure.
- Waterproof:Submersible-rated sealing maintains contents through cabin flooding or liquid spill events. Marine-adjacent vehicle applications and convertible platforms drive niche demand.
Illuminated features dominate mainstream specification; waterproof configurations remain the smallest segment by installed base.
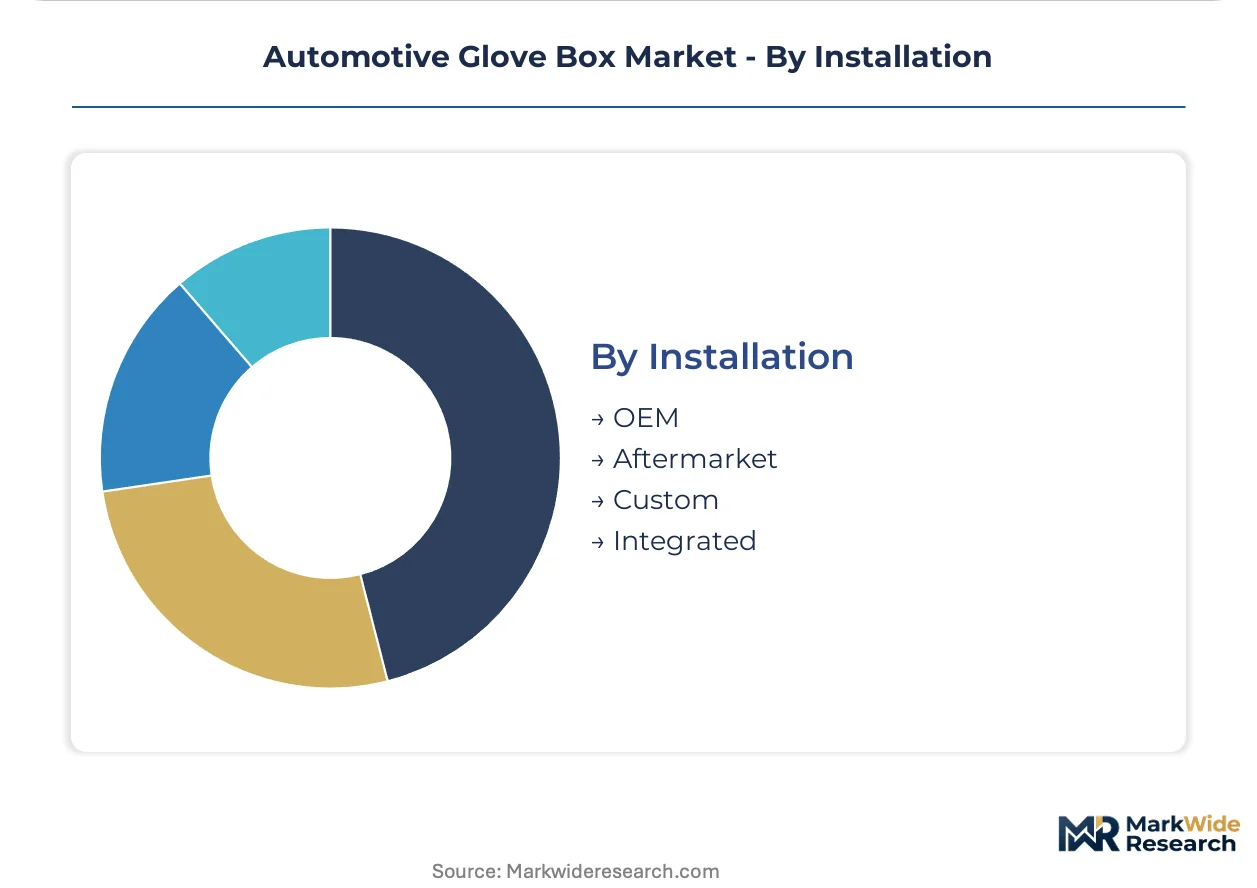
Installation:
Customer type bifurcation separates factory-integrated supply from post-production customization channels.
- OEM:Factory-installed units engineered to vehicle-specific dashboard architectures and quality protocols. Magna International and Yanfeng Automotive Interiors capture this channel through cockpit module bundling.
- Aftermarket:Retrofit replacements and upgrades sold through independent distributors and service channels. Price compression and compatibility verification challenges constrain margin structures.
- Custom:Bespoke fabrication for restoration, luxury conversion, and specialty vehicle applications. Low volume and high labor content limit supplier participation.
- Integrated:Glove box subsystems fused into unified dashboard-HVAC-instrument panel assemblies. This channel is expanding most quickly as OEM procurement consolidates around tier-0.5 supply models.
OEM supply handles the majority of throughput; integrated installation is climbing fastest as cockpit module consolidation accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's PLI scheme for auto components is redirecting glove box subsystem investment toward Pune and Chennai manufacturing corridors. Germany's premium automotive manufacturing belt maintains specification leadership through integrated cockpit module programs. China's SAMR enforcement of GB standards for automotive interior plastics is upgrading compliance tiers across export-oriented supply chains.
Germany
Premium electric vehicle OEM procurement is driving specification complexity for cooled and connected glove box configurations. EU REACH chemical compliance and the F-Gas Regulation govern refrigerant phase-down schedules for climate-controlled variants. Production clusters in Baden-Württemberg and Bavaria concentrate tier-1 cockpit module assembly for Mercedes-Benz, BMW, and Audi platforms.
China
Domestic EV manufacturers are specifying integrated cabin modules that bundle glove box units with dashboard assemblies and thermal management systems. SAMR enforces GB standards mandating thermal stability and fogging-resistance thresholds for automotive interior plastics. Manufacturing gravity centers on the Yangtze River Delta and Pearl River Delta where Yanfeng Automotive Interiors operates major production facilities.
United States
Light-truck fleet procurement is consolidating glove box sourcing through integrated cockpit module contracts rather than discrete component purchases. NHTSA FMVSS 302 flammability testing and EPA volatile organic compound emissions rules constrain polymer selection for dashboard-integrated compartments. Magna International leverages captive tooling partnerships across Michigan and Ohio assembly corridors to sustain volume flexibility.
India
Compact car manufacturing for domestic and export markets is sustaining demand for standard polypropylene glove box configurations. The PLI scheme for advanced automotive plastics is attracting subsystem investment toward Pune and Chennai manufacturing corridors. Cost engineering governs sourcing decisions as Maruti Suzuki, Tata Motors, and Hyundai expand production capacity.
South Korea
Premium electric vehicle OEMs are specifying refrigerated glove box configurations for cabin comfort differentiation. MFDS and environmental regulations align with EU F-Gas phase-down schedules for cooled compartment variants. Hyundai Mobis anchors domestic supply through integrated cockpit module programs serving Hyundai and Kia platforms.
Automotive Glove Box Market Vendor Landscape
Channel-controlling players compete with product-specialist players across a tiered supplier base. Tier-0.5 integrators dominate OEM procurement through bundled cockpit module contracts that compress the addressable market for standalone component specialists. Three archetypes define competitive positioning: integrated cockpit module suppliers, surface-finishing specialists, and regional component fabricators. Dominant competitive moves include captive tooling partnerships and integrated dashboard assembly bundling.
Among North American-anchored tier-1 suppliers, Magna International and Lear Corporation exemplify the channel-control archetype through cockpit module integration. Visteon Corporation occupies a position within the electronics-forward tier where climate-controlled and connected glove box specifications converge. These three entities represent the scale-driven end of competitive positioning, with geographic naming conventions signaling operational footprints rather than exclusive market dominance.
| Leading Market Players |
|---|
| Magna International Inc. |
| IAC Group |
| Visteon Corporation |
| Yanfeng Automotive Interiors |
| Faurecia |
| Hyundai Mobis |
| Grupo Antolin |
| Toyoda Gosei |
| Lear Corporation |
| Others |
Supply Flow & Price Mechanics
Polypropylene resin price volatility tied to naphtha cracking margins compresses margin predictability for injection-molding suppliers while simultaneously widening spreads between commodity-grade and REACH-compliant material tiers across German and Chinese supply chains.
Pricing Analysis
Certification level creates the primary spread across material grades, with EU REACH-compliant bio-based polymer formulations commanding premium positioning over legacy phthalate-plasticizer compounds in premium cockpit module contracts. Three-tier pricing structure separates OEM-integrated dashboard assemblies from standalone component supply and aftermarket retrofit channels, with fleet procurement managers in North American light-truck segments showing highest price sensitivity due to volume consolidation pressures. Cost compression in standard polypropylene configurations is intensifying because India's PLI scheme for auto components attracts capacity expansion toward Pune and Chennai manufacturing corridors.
Supply Chain Analysis
EU F-Gas Regulation phase-down schedules act as export-control regime analogues for cooled glove box configurations, constraining conventional hydrofluorocarbon climate-control system flows and fragmenting supplier qualification tiers. Manufacturing gravity centers on Germany's Baden-Württemberg and Bavaria clusters, China's Yangtze River Delta and Pearl River Delta, and India's emerging Pune-Chennai corridor, with glass-fiber-reinforced polypropylene compounds and aluminum hinge substrates representing critical input dependencies. Single-source vulnerability concentrates in German premium cockpit module production, where regional logistics disruptions would cascade through Mercedes-Benz, BMW, and Audi platform supply. Distribution runs through tier-0.5 integrators bundling glove box units with unified dashboard-HVAC-instrument panel assemblies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automotive glove box procurement follows cyclical recovery patterns tied to electric vehicle platform launches, with OEM cockpit module consolidation accelerating specification complexity premiums.
For Market Incumbents: Build captive tooling partnerships as the defensive moat against asset-light leasing arrangements that favor suppliers with flexible capital structures. Deepen backward integration into in-house polymer laboratories to capture specification influence from raw material distributors as REACH Annex XVII restrictions accelerate bio-based adipate ester substitutions. Anchor volume flexibility across North American assembly lines through integrated cockpit module programs that bundle glove box units with dashboard assemblies. For New Entrants and Emerging Players: India's aftermarket retrofit channel exhibits the most penetrable white-space opportunity, where price compression and compatibility verification challenges have constrained incumbent margin structures and created service-gap openings. Target biometric access integration for electric SUV segments as the premium feature differentiation angle, with fingerprint-activated locking mechanisms converging with connected vehicle architectures. Pursue SAMR certification reciprocity expansion as the regulatory pathway to reduce redundant compliance costs for multi-regional supply chain entry. For Investors and Strategic Acquirers: EU F-Gas Regulation phase-down schedules reshape the acquisition landscape by disqualifying conventional refrigerant-dependent cooled glove box specialists from premium electric vehicle platform qualification. Long-term viability favors compounders with in-house polymer laboratories and surface-finishing capabilities that meet OEM tactile specifications. Monitor active grille ventilation system adoption rates as the inflection signal, with thermostatically controlled fan-assisted configurations displacing mechanical hinge-and-damper assemblies and expanding electronics content requirements.| Strategic Initiative | Industry Significance |
|---|---|
| Integrated Cockpit Module Bundling | Magna International and Yanfeng capture OEM procurement through single-source dashboard-HVAC-glove box contracts. |
| Bio-Based Polymer Laboratory Investment | Tier-1 suppliers reformulate soft-touch overmolding compounds to meet REACH Annex XVII phthalate restrictions. |
| India PLI Scheme Manufacturing Footprint | Subsystem investment redirects toward Pune and Chennai corridors for compact car cost engineering. |
| Biometric Access Technology Integration | Fingerprint-activated locking converges with connected vehicle architectures in electric SUV segments. |
| Composite Material Capacity Expansion | Glass-fiber-reinforced polypropylene compounds displace ABS substrates for platform lightweighting mandates. |
Methodological Framework
Cross-validation between OEM platform engineering disclosures and tier-1 supplier procurement patterns anchors the qualitative findings in this study. Primary interviews with Tier 1 supplier procurement leads, OEM platform engineers, aftermarket distributors, and dealership operations heads combined with secondary validation from vehicle production databases, IHS Markit registration data, SEC filings, and customs/trade records. Bottom-up segment sizing and top-down market reconciliation triangulate volume estimates across material, feature, and installation dimensions.
Calibration against historical production volumes and announced OEM platform electrification timelines shapes the analytical framework across the projection horizon. Segmentation dimensions modeled include vehicle class, propulsion architecture, content per vehicle, OEM tier, and regional production cluster. CAGRs derive from regression analysis of material substitution rates and regulatory compliance cost layering. Industry-specific forecast inputs encompass REACH chemical restriction phase-in schedules and China's GB standards enforcement timelines for automotive interior plastics.
Practitioners should monitor polypropylene resin price volatility, EU F-Gas Regulation refrigerant phase-down acceleration, and SAMR certification reciprocity expansion for early signals of forecast deviation. Forecasts reflect assumptions regarding OEM procurement consolidation trajectories and electric vehicle platform launch cadences. Material shifts in composite material adoption rates or biometric access integration penetration would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Interior & Exterior
Automotive OEM Interior Coatings Market
Automotive Interior & Exterior
Automotive Underbody Coatings Market
Automotive Interior & Exterior
Automotive Steering Wheel Market
Automotive Interior & Exterior
Global Luxury Car Coachbuilding Market
Automotive Interior & Exterior
Automotive Auto Dimming Mirror Market
Automotive Interior & Exterior
Global Automotive Window Power Sunshade Market
Automotive Interior & Exterior
Automotive Interior Trims Market
Automotive Interior & Exterior
Automotive Drawer Slides Market
Automotive Interior & Exterior
Blind Spot Mirror Market
Automotive Interior & Exterior
Rear-View Mirror Market
Automotive Interior & Exterior
Automotive Floor Mats Market
Automotive Interior & Exterior
Automotive Heat Shield Market
Automotive Interior & Exterior
Global Automotive Windscreen Glazing Market
Automotive Interior & Exterior
Glass for Electric Vehicle Glass Roof Market
Automotive Interior & Exterior
Automotive Seats Market
Automotive Interior & Exterior
Power Sunroof Market