
 Cup Holder Market | 2026-2036
Cup Holder Market Size, Share, and Industry Trends Forecast 2026-2036
Cup Holder Market Outlook
Polypropylene is restructuring cost structures across molded cup holder assemblies as brands seek lighter, recyclable alternatives to ABS. Huhtamaki Oyj leverages its fiber-based packaging expertise to extend into molded pulp automotive inserts. WestRock Company anchors North American supply through integrated paperboard and converted packaging operations. Georgia-Pacific Consumer Products competes via scale advantages in thermoformed plastic substrates for mass-market vehicle programs.
A cup holder is a receptacle engineered to secure beverage containers against motion, vibration, and thermal transfer, typically injection-molded or thermoformed with retention features sized to standardized diameters. Automotive applications dominate volume, with dashboard-integrated and door-panel variants specified to OEM crash safety and flammability protocols. Plastic material formulations command the largest share of unit economics, while silicone segments gain traction in premium vehicle interiors and travel accessories where grip performance and temperature insulation justify higher unit costs. Custom design types capture margin pools in luxury automotive programs, whereas universal configurations sustain volume across aftermarket channels.
FDA food-contact regulations govern material migration limits for cup holders serving consumable beverages, while EPA guidelines shape recycled content mandates for plastic components in US-manufactured vehicles. REACH compliance in Europe restricts certain phthalates and flame retardants, redirecting formulation roadmaps toward compliant polymer blends. Stakeholders must monitor evolving extended producer responsibility frameworks and material disclosure requirements as jurisdictions tighten circular economy obligations.
Market Dynamics
Automotive OEMs now embed cup holders as configurable cabin modules rather than fixed fixtures, forcing tier-1 suppliers to retool for rapid design iteration cycles and multi-material bonding processes.
Growth Catalysts
- EU F-Gas Regulation:Pressure toward lower-GWP refrigerants cascades into automotive interior material specifications, accelerating bio-based polymer adoption for thermally stable cup holder substrates.
- China vehicle production scaling:Domestic automakers specify higher cup holder counts per vehicle as interior amenity competition intensifies in the world's largest automotive market.
- Recyclable polypropylene formulations:Injection molders achieve weight reduction targets while maintaining crash safety compliance, satisfying OEM sustainability scorecard requirements.
Market Restraints
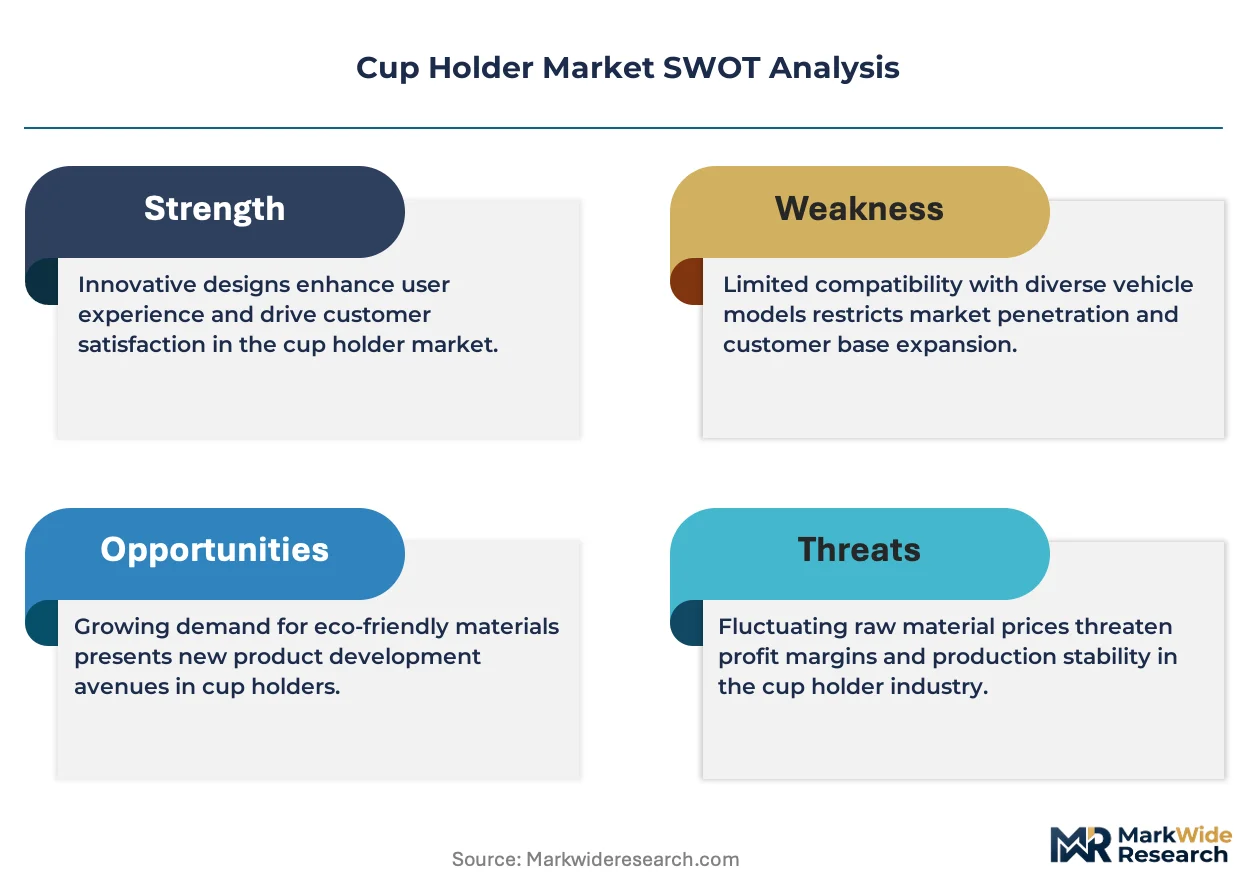
- Petrochemical feedstock volatility:Polypropylene resin prices fluctuate with propylene monomer supply disruptions, compressing margins for high-volume molded component suppliers.
- Tooling cost concentration:Precision injection molds for complex retention mechanisms require capital outlays concentrated among German and Japanese toolmaking specialists.
- REACH substance restrictions:Phased bans on specific flame retardants and plasticizers force reformulation cycles that delay program approvals by 12-18 months.
Strategic Opportunities
- India automotive market penetration:Domestic OEMs and joint ventures are specifying Western-equivalent interior amenities as per-vehicle content value rises.
- Silicone-overmolding convergence:Combining liquid silicone rubber with structural plastics enables premium tactile properties and thermal insulation in luxury vehicle programs.
- Extended producer responsibility frameworks:EU circular economy mandates create first-mover advantage for suppliers with verified closed-loop recycling infrastructure.
Industry Challenges
- Multi-material bonding expertise:OEMs demand seamless polypropylene-silicone-TPO assemblies, but adhesive chemistry and process control talent remains scarce.
- Homologation timeline compression:Crash safety validation under NHTSA and ECE R21 protocols now overlaps with sustainability certification, straining testing capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cup Holder Market |
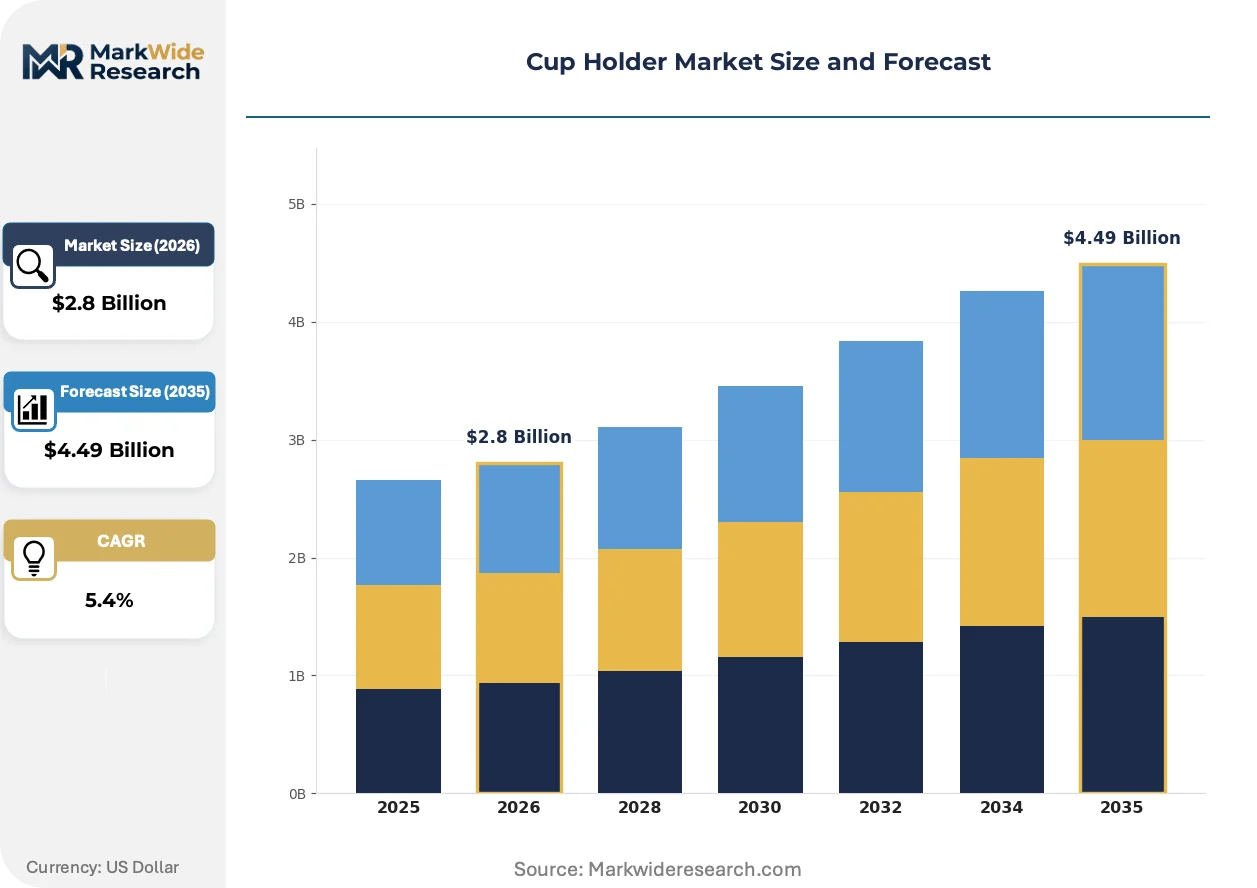
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.49 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automotive, Desktop, Travel, Furniture Material: Plastic, Metal, Silicone, Wood End User: Households, Offices, Vehicles, Cafes Design Type: Universal, Custom, Collapsible, Fixed |
| Companies Covered | MULTIPAP, Huhtamaki Oyj, Georgia-Pacific Consumer Products, WestRock Company, Sabert Corporation, Pactiv LLC, Graphic Packaging International, PakTech, Southern Champion Tray, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cup Holder Market Strategic Shifts
Material science advances and regulatory chemistry constraints are converging to redefine how cup holder assemblies perform, comply, and integrate with evolving vehicle architectures.
Molded pulp fiber technology is expanding into automotive interior applications as Huhtamaki Oyj and packaging specialists transfer forming expertise from food service to cabin trim. European OEM sustainability targets compress adoption timelines, with pilot programs now validating moisture resistance and odor performance. This expansion is compressing reliance on petroleum-derived substrates in mass-market vehicle segments where weight and recyclability trade-offs favor fiber-based solutions.
REACH substance restrictions and the EU F-Gas Regulation are redirecting formulation roadmaps across the supply base. ECHA's expanding candidate list of substances of very high concern forces proactive substitution of legacy plasticizers and flame retardants. Tier-1 suppliers serving German OEMs face the most compressed compliance timelines, accelerating partnerships with polymer compounders holding pre-certified material libraries.
Buyer concentration among platform-sharing automotive alliances is consolidating procurement authority. Volkswagen Group, Stellantis, and Renault-Nissan-Mitsubishi now specify common cup holder modules across multiple brands, displacing bespoke designs. Tier-2 molders in China and Mexico capture volume through direct platform nominations, compressing traditional tier-1 intermediary roles in supply chain architecture.
Cup Holder Market Segmentation
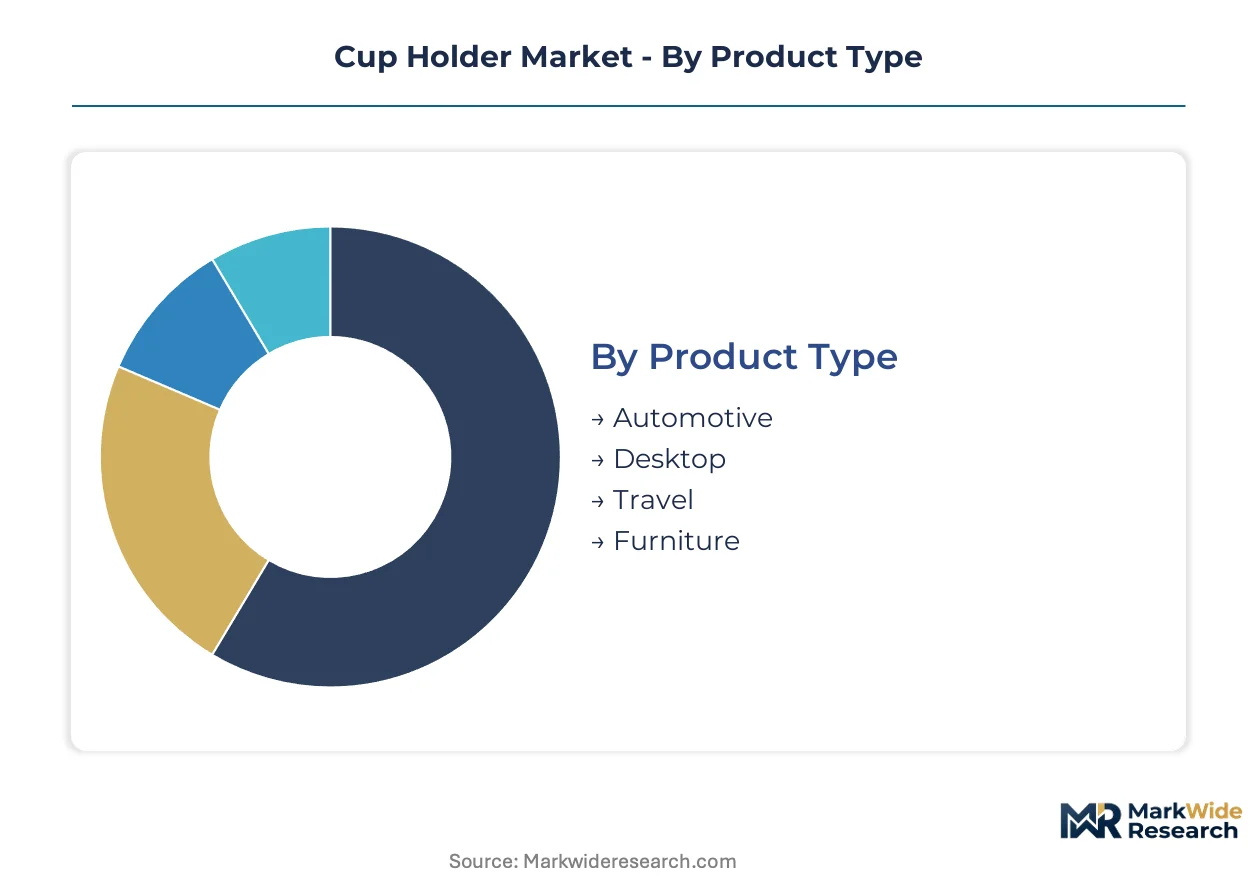
Cup holder procurement patterns diverge sharply across application contexts, with automotive OEMs demanding crash-certified assemblies while furniture and travel segments prioritize aesthetic differentiation. Material selection and design complexity scale directly with performance requirements and regulatory exposure.
Product Type:
Application context dictates retention mechanism complexity, thermal specification, and bonding chemistry requirements.
- Automotive:Injection-molded or thermoformed assemblies integrate retention fingers, anti-tip geometry, and HVAC ducting compatibility. Dashboard-integrated and door-panel variants dominate OEM specifications in China and Germany as per-vehicle cup holder counts rise. Crash safety validation under NHTSA and ECE R21 protocols constrains design freedom.
- Desktop:Freestanding or clamp-mounted receptacles emphasize stability on flat surfaces without vehicle-grade vibration resistance. Demand concentrates in corporate procurement programs across the United States and Japan where workstation amenity specifications are formalizing.
- Travel:Portable designs prioritize collapsibility and lightweight construction for airline and commuter use. Silicone-overmolded variants gain traction in premium luggage and travel accessory channels.
- Furniture:Integrated receptacles in seating and side tables emphasize aesthetic cohesion over retention engineering. Wood and metal finishes dominate residential and hospitality specifications.
Mature deployment sits with Automotive. Newer deployment is concentrated in Travel.
Material:
Cost tier and recyclability mandate determine substrate selection across end-use categories.
- Plastic:Polypropylene and ABS formulations command the largest production volumes, with recyclable polypropylene restructuring cost structures in molded assemblies. REACH substance restrictions and ECHA's expanding SVHC list force proactive substitution of legacy plasticizers in European supply chains.
- Metal:Aluminum and stainless steel variants serve premium automotive and furniture applications where thermal mass and durability justify higher unit economics. Brushed and anodized finishes differentiate luxury vehicle programs.
- Silicone:Liquid silicone rubber enables overmolded assemblies combining structural plastics with premium tactile properties. Thermal insulation performance drives adoption in luxury vehicle interiors and high-end travel accessories.
- Wood:Sustainable timber and engineered wood products serve furniture-integrated and premium desktop segments. Moisture resistance treatments remain a formulation challenge for beverage-contact applications.
Volume concentration sits with Plastic. Margin expansion is concentrated in Silicone.
End User:
Procurement authority and specification authority vary dramatically across buyer types.
- Households:Individual consumers purchase through retail and e-commerce channels, prioritizing aesthetic compatibility with interior design schemes. Price sensitivity drives universal design adoption over custom configurations.
- Offices:Corporate facilities managers specify workstation accessories through centralized procurement, with sustainability scorecards increasingly influencing material selection. Bulk purchasing concentrates volume with large-format retailers.
- Vehicles:Automotive OEMs and tier-1 suppliers dominate value capture through platform-shared module specifications. Volkswagen Group, Stellantis, and Renault-Nissan-Mitsubishi procurement consolidation displaces bespoke tier-2 designs.
- Cafes:Food service operators demand commercial-grade durability and rapid replacement cycles. FDA food-contact regulations govern material migration limits for reusable serving accessories.
Specification authority sits with Vehicles. Volume fragmentation is concentrated in Households.
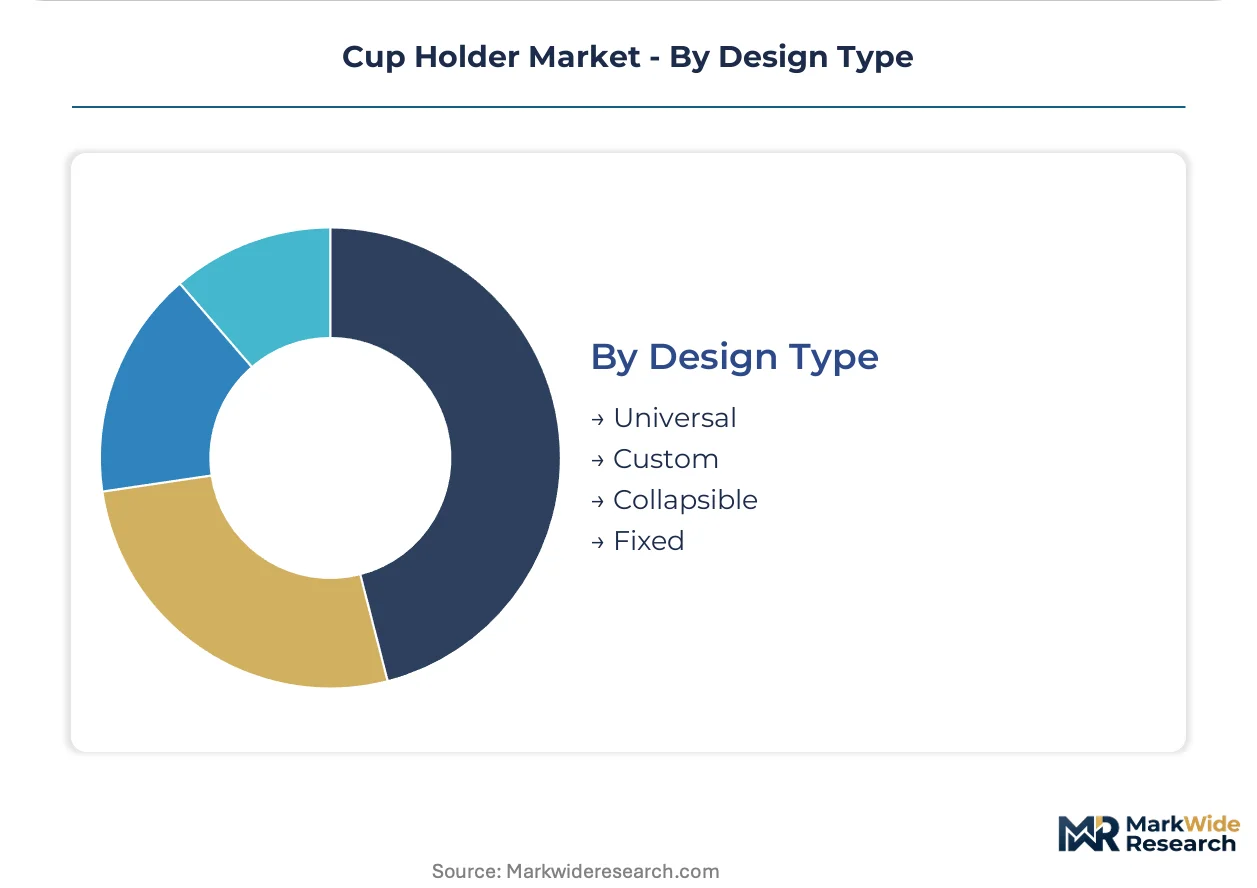
Design Type:
Customization depth and tooling amortization scale inversely across the configuration spectrum.
- Universal:Standardized diameter compatibility and snap-fit retention serve aftermarket channels and price-sensitive OEM programs. Tooling cost concentration among German and Japanese moldmaking specialists constrains new entrant participation.
- Custom:Bespoke geometry and branded retention mechanisms capture margin pools in luxury automotive programs. Tier-1 suppliers retool for rapid design iteration cycles as OEMs treat cup holders as configurable cabin modules.
- Collapsible:Hinge and fold mechanisms prioritize storage efficiency in travel and compact vehicle applications. Silicone and fabric-based constructions dominate this emerging specification tier.
- Fixed:Permanent mounting integration in furniture and heavy-duty commercial vehicles emphasizes structural load-bearing capacity over adjustability.
Revenue concentration sits with Custom. Steepest expansion trajectory is concentrated in Collapsible.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Automotive OEM procurement concentrates in China as domestic vehicle production scales and per-vehicle cup holder counts rise. Consumer expectations for interior amenities reshape specification patterns across manufacturing clusters. Regulatory chemistry constraints in Europe redirect material formulation roadmaps toward compliant polymer alternatives.
China
Domestic automakers specify Western-equivalent interior amenities as per-vehicle content value climbs. MIIT fuel economy standards and SAMR consumer protection frameworks shape component durability requirements. Manufacturing clusters in Shanghai and Guangzhou host tier-1 injection molding operations serving BYD, NIO, and Geely platform programs.
Germany
Volkswagen Group, BMW, and Mercedes-Benz procurement consolidation drives common module specifications across brand portfolios. REACH substance restrictions and ECHA's expanding SVHC list force proactive substitution of legacy plasticizers and flame retardants. Stuttgart and Munich anchor precision toolmaking concentration for complex retention mechanism molds.
United States
Detroit Three OEMs embed cup holders as configurable cabin modules requiring rapid design iteration cycles. NHTSA crash safety validation under FMVSS protocols constrains design freedom alongside EPA recycled content mandates for plastic components. Southeast manufacturing corridors in Tennessee and Alabama attract tier-1 supplier facility investments.
Japan
Toyota, Honda, and Nissan platform-sharing alliances consolidate procurement authority for common interior modules. METI carbon neutrality roadmaps and JIS quality standards influence material selection criteria. Nagoya and Tokyo-Yokohama clusters concentrate precision injection molding expertise for multi-material bonding processes.
India
Maruti Suzuki, Hyundai, and Tata Motors joint ventures specify higher amenity content as passenger vehicle demand urbanizes. BIS automotive component standards and PLI scheme incentives reshape supplier qualification requirements. Chennai and Pune manufacturing corridors attract tier-2 molders capturing volume through direct platform nominations.
Cup Holder Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with automotive OEM channels consolidating around tier-1 integrators while aftermarket and food service routes sustain independent fabricators. The supply base organizes into three archetypes: diversified packaging conglomerates leveraging fiber forming expertise, specialized automotive tier-1 suppliers with crash certification capabilities, and regional injection molders competing on tooling amortization cycles. Competitive moves concentrate on multi-material bonding process development and geographic proximity to platform-sharing OEM assembly plants.
Among diversified packaging specialists, Huhtamaki Oyj and WestRock Company occupy positions that exemplify fiber-based and paperboard-anchored approaches to molded interior components. Georgia-Pacific Consumer Products represents the scale-driven thermoformed plastic substrate tier serving mass-market vehicle programs with consolidated procurement authority.
| Leading Market Players |
|---|
| MULTIPAP |
| Huhtamaki Oyj |
| Georgia-Pacific Consumer Products |
| WestRock Company |
| Sabert Corporation |
| Pactiv LLC |
| Graphic Packaging International |
| PakTech |
| Southern Champion Tray |
| Others |
Value Chain & Pricing Dynamics
Polypropylene resin prices cascade through injection molding operations into three distinct procurement tiers serving automotive OEMs, aftermarket distributors, and furniture manufacturers. Raw material volatility from propylene monomer supply disruptions compresses margins for high-volume molded component suppliers while premium silicone-overmolded assemblies retain pricing power through scarce multi-material bonding expertise.
Pricing Analysis
Volume concentration in universal automotive configurations trades margin for scale, whereas custom luxury programs capture premium through bespoke retention geometry and branded tactile surfaces. Price differentiation hinges on REACH compliance certification tiers and crash safety validation under NHTSA protocols. Cost compression in mass-market polypropylene assemblies intensifies as Chinese tier-2 molders amortize tooling across platform-shared nominations. Aftermarket distributors exhibit highest price sensitivity, while German OEM procurement tolerates premium for rapid design iteration cycles.
Supply Chain Analysis
Freight costs from German and Japanese precision toolmaking specialists to tier-1 assembly plants in Tennessee and Alabama amplify landed costs for complex retention mechanism molds. Supply concentrates in China, Germany, and Mexico for injection-molded assemblies, with molded pulp fiber inputs drawing from Nordic and North American pulp operations. Raw material dependencies span polypropylene resin, liquid silicone rubber, and thermoplastic olefin substrates. Single-source vulnerability in specialized adhesive chemistry for polypropylene-silicone-TPO bonding threatens program timelines. Distribution runs through tier-1 integrators to OEM assembly plants, with aftermarket channels served by regional distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The cup holder market sits at a materials-transition inflection as molded pulp fiber technology displaces petroleum-derived substrates in mass-market automotive programs. Fiber-based forming expertise from packaging specialists now migrates into cabin trim applications.
For Market Incumbents: Hedge against REACH substance restriction delays by pre-certifying compliant polymer libraries with compounders serving German OEMs. Backward integration into recycled polypropylene compounding secures feedstock against petrochemical volatility while satisfying EPA recycled content mandates for US-manufactured vehicles.
For New Entrants and Emerging Players: The mid-tier pricing gap between premium silicone-overmolded luxury assemblies and economy polypropylene aftermarket units offers white-space opportunity. Target collapsible travel configurations where silicone and fabric-based constructions face limited incumbent specialization. Pursue direct platform nominations with Indian joint ventures specifying Western-equivalent interior amenities as per-vehicle content value rises.
For Investors and Strategic Acquirers: Distressed-cycle entries favor tier-2 molders with verified closed-loop recycling infrastructure in EU manufacturing corridors. Long-term viability rests on multi-material bonding process capabilities as OEMs demand seamless polypropylene-silicone-TPO assemblies. Monitor ECHA SVHC list expansion velocity as inflection indicator for reformulation cycle intensity and supplier qualification disruption.
| Strategic Initiative | Industry Significance |
|---|---|
| Molded Pulp Fiber Scale-Up | Huhtamaki Oyj and packaging specialists transfer food-service forming expertise into automotive cabin trim applications. |
| Multi-Material Bonding Process Development | Liquid silicone rubber overmolding capabilities unlock premium tactile properties for luxury vehicle programs. |
| REACH-Compliant Material Library Investment | Pre-certified polymer compounds accelerate German OEM program approvals ahead of SVHC restriction phases. |
| Direct Platform Nomination Pursuit | Tier-2 molders in Chennai and Pune capture volume through Indian joint venture procurement consolidation. |
| Closed-Loop Recycling Infrastructure | Verified circular systems create first-mover advantage under EU extended producer responsibility frameworks. |
Study Parameters
Document review covered automotive production databases, customs and trade flow records, and regulatory filings from ECHA and EPA, complemented by interviews with tier-1 supplier procurement officers, OEM platform engineers, injection molding plant managers, and aftermarket distribution channel heads. Secondary sources included vehicle registration data, IHS Markit production forecasts, and SEC filings from packaging conglomerates. Bottom-up volume modeling triangulated against top-down value estimates across material and design type segmentations.
Unit shipment and revenue estimates were generated across the projection horizon by vehicle class, propulsion architecture, content per vehicle, and regional production cluster. CAGRs were derived from regression analysis of historical automotive interior component penetration rates, adjusted for MIIT fuel economy standards and per-vehicle amenity specification trends. Forecast inputs incorporated polypropylene resin price indices, REACH substance restriction timelines, and OEM sustainability scorecard weightings.
Inputs from tier-1 supplier interviews and regulatory agency filings were available through the study window; gaps in real-time tooling cost data from German and Japanese moldmaking specialists introduce uncertainty bands around capital intensity assumptions. Forecasts reflect documented assumptions regarding platform-sharing alliance procurement consolidation and fiber-based material adoption curves. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Interior & Exterior
North America Automotive Interiors Market
Automotive Interior & Exterior
Seat Comfort and Lumbar Actuator Systems Market
Automotive Interior & Exterior
Car Door Latch Market
Automotive Interior & Exterior
Automotive Windshield Market
Automotive Interior & Exterior
Decorative Car Accessories Market
Automotive Interior & Exterior
Automotive Backlight Moldings Market
Automotive Interior & Exterior
Automotive Tinting Film Market
Automotive Interior & Exterior
Automotive Front Windshield Market
Automotive Interior & Exterior
Automotive Digital Rear View Mirror Market
Automotive Interior & Exterior
United Kingdom Automotive Sunroof Market
Automotive Interior & Exterior
Automotive Window Seals Market
Automotive Interior & Exterior
Auto Dimming Mirror Market
Automotive Interior & Exterior
Exterior Car Accessories Market
Automotive Interior & Exterior
Auto Glass Encapsulation Market
Automotive Interior & Exterior
Heated Windshield Market
Automotive Interior & Exterior
Automotive Head Up Display (HUD) Market