
 Small Commercial Vehicle Market | 2026-2036
Small Commercial Vehicle Market Size, Share, and Industry Trends Forecast 2026-2036
Small Commercial Vehicle Market Analysis
Commercial driver shortages across North America and Western Europe is bifurcating fleet procurement strategies between autonomous-ready platforms and simplified manual-transmission models. Ford Motor Company leverages its Transit van architecture to sustain dominance in North American last-mile configurations. Tata Motors Limited anchors South Asian demand with cost-optimized compact trucks engineered for narrow urban corridors. Isuzu Motors dominates diesel powertrain reliability perceptions among Japanese and Southeast Asian fleet operators.
Small commercial vehicles span light-duty to medium-duty chassis with gross vehicle weight ratings typically below 8,500 pounds, designed for urban freight movement, tradesman tool transport, and passenger shuttle services with maneuverability specifications tighter than heavy-duty alternatives. Van configurations lead volume globally due to enclosed cargo security and adaptable interior architecture serving delivery services and e-commerce fulfillment networks. Electric fuel type represents the fastest-expanding segment as battery-electric drivetrains displace diesel in European city centers with strict low-emission zone enforcement. Diesel retains margin concentration in emerging-market full-size pickup and box truck categories where charging infrastructure remains sparse.
The US EPA and NHTSA coordinate fuel economy and safety standards that dictate powertrain investment calendars for manufacturers selling into North America. The EU Green Deal and F-Gas Regulation compel European fleet operators toward zero-emission vehicle procurement with binding CO2 reduction timelines. India's BIS certification and PLI scheme for automotive manufacturing shape local content requirements and technology transfer obligations for multinational entrants. Stakeholders must monitor how divergent regulatory timelines across Washington, Brussels, and New Delhi fragment platform development budgets and regional product line rationalization.
Market Dynamics
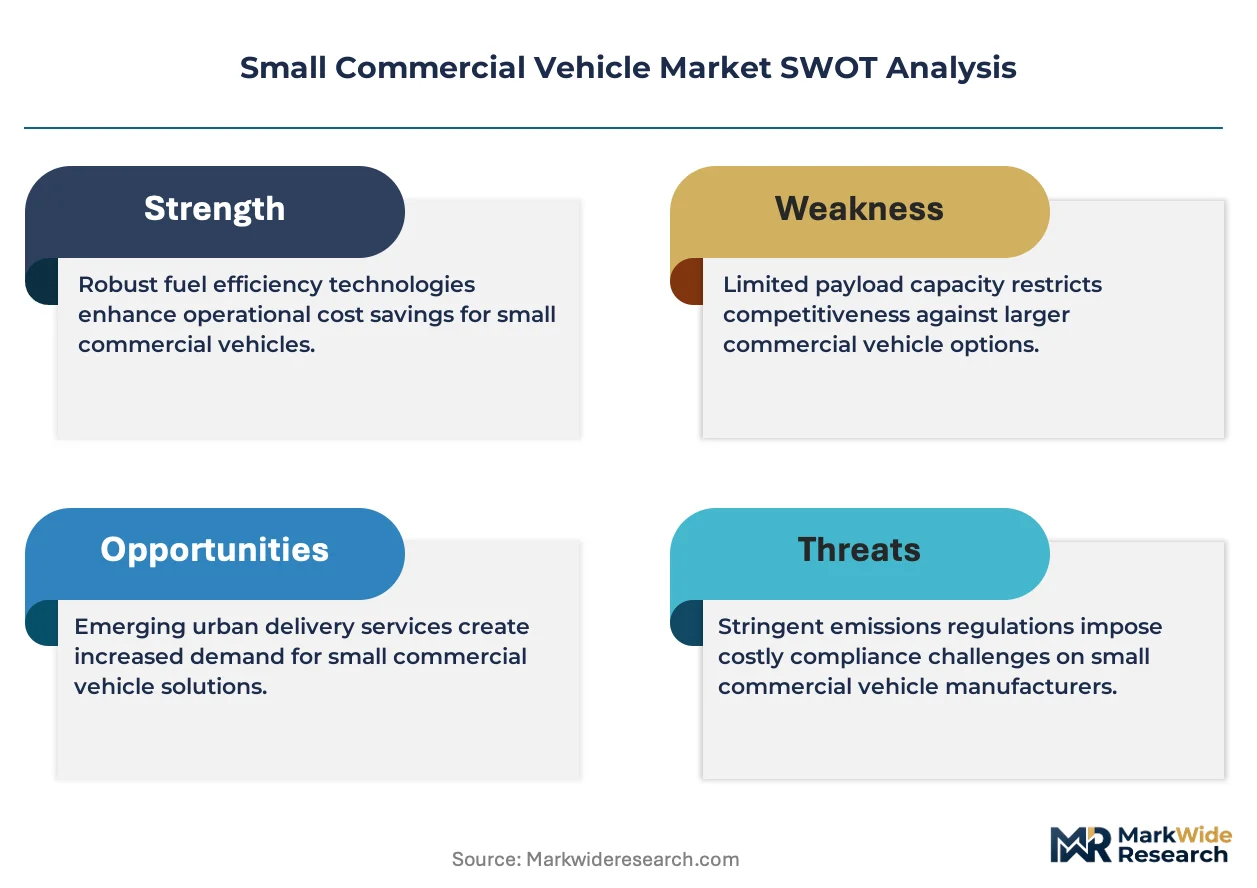
Powertrain electrification is fragmenting platform development budgets as manufacturers simultaneously engineer battery-electric architectures while maintaining internal combustion variants for markets with sparse charging infrastructure. Fleet procurement calendars now synchronize with regulatory compliance timelines rather than traditional replacement cycles.
Growth Catalysts
- EU Green Deal mandates:Binding CO2 reduction timelines compel European fleet operators toward zero-emission vehicle procurement, accelerating van electrification across German and French urban delivery networks.
- Last-mile logistics intensification:E-commerce fulfillment networks demand compact, maneuverable chassis configurations optimized for dense urban corridors and restricted access zones.
- India's PLI scheme:Production-linked incentives for automotive manufacturing attract technology transfer and localize compact commercial vehicle supply chains for domestic small enterprises.
Market Restraints
- Lithium-ion cell supply concentration:Battery raw material processing and cathode production cluster in limited jurisdictions, exposing OEMs to input cost volatility and geopolitical supply disruptions.
- Diesel powertrain residual value collapse risk:Low-emission zone expansion in European city centers compresses secondary market liquidity for internal combustion assets, stranding fleet balance sheets.
- Charging infrastructure asymmetry:Rural and peri-urban geographies lack depot and public fast-charging capacity, constraining electric van deployment outside metropolitan cores.
Strategic Opportunities
- Battery-swapping networks:Stationary energy storage integration with commercial vehicle operations enables rapid replenishment without grid upgrade dependency, particularly viable for fixed-route urban logistics.
- Software-defined vehicle architectures:Over-the-air capability expansion and fleet telematics monetization transform hardware margins into recurring service revenue streams.
- Indonesian archipelago logistics:Island economies with fragmented road networks present demand for compact, high-payload-efficiency vehicles suited to intermodal freight transfer.
Industry Challenges
- High-voltage technician scarcity:Fleet maintenance networks lack certified personnel for battery-electric drivetrain diagnosis and repair, extending vehicle downtime and inflating service costs.
- Homologation timeline compression:Divergent certification requirements across Washington, Brussels, and New Delhi force parallel validation tracks that consume engineering resources and delay market entry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Small Commercial Vehicle Market |
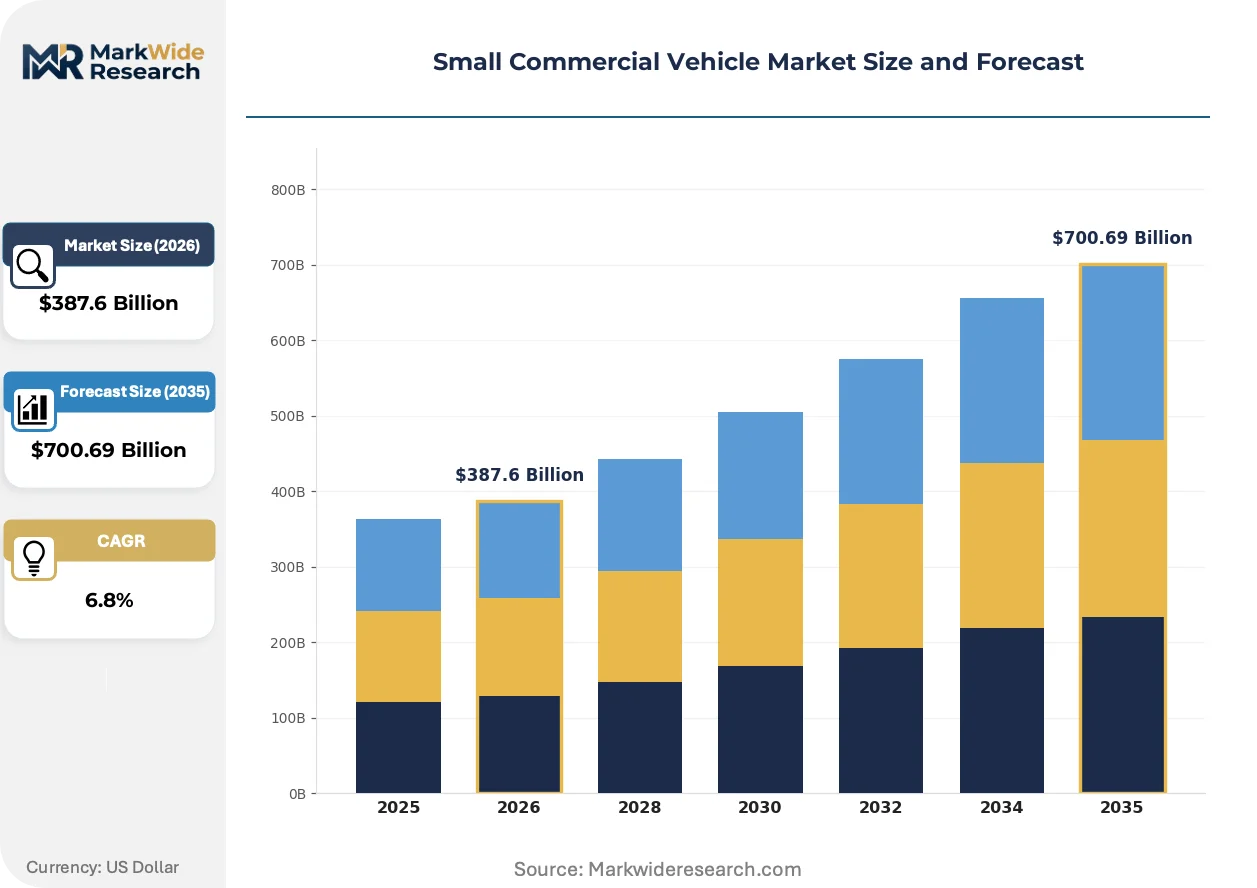
| Market Size in 2026 | $387.6 Billion |
| Market Size in 2035 | $700.69 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Van, Pickup Truck, Minibus, Box Truck Fuel Type: Diesel, Gasoline, CNG, Electric Size Class: Light-duty, Medium-duty, Compact, Full-size End User: Logistics, Construction, Delivery Services, E-commerce |
| Companies Covered | Ford Motor Company, General Motors, Toyota Motor Corporation, Volkswagen AG, Stellantis, Isuzu Motors, Tata Motors Limited, Renault SA, Daimler AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Small Commercial Vehicle Market Emerging Trajectories
Electrification is compressing vehicle architecture generations as software and battery chemistry advance faster than traditional chassis replacement cycles. Platform modularity now determines competitive survival.
Silicon carbide power electronics is miniaturizing inverter and onboard charger packaging, enabling higher energy density without sacrificing cabin or cargo volume. European van OEMs are adopting these components aggressively to maximize range within constrained wheelbase dimensions. This semiconductor transition is compressing thermal management system complexity and reducing parasitic energy losses.
The US EPA and NHTSA coordinate fuel economy and safety standards that dictate powertrain investment calendars for manufacturers selling into North America. Stringent Corporate Average Fuel Economy thresholds force portfolio-wide electrification commitments regardless of regional demand heterogeneity. Light-duty van segments face the most acute compliance cost pressure due to their high sales volume and limited pricing elasticity.
Fleet operators are unbundling after-sales service contracts from vehicle acquisition, selecting third-party maintenance providers based on telematics-enabled predictive capability rather than OEM affiliation. This procurement behavior shift disrupts traditional dealer network economics and compresses spare parts margin capture. German and Dutch logistics consortia are pioneering this disaggregation, pressuring incumbent distribution structures across Northern Europe.
Small Commercial Vehicle Market Segmentation
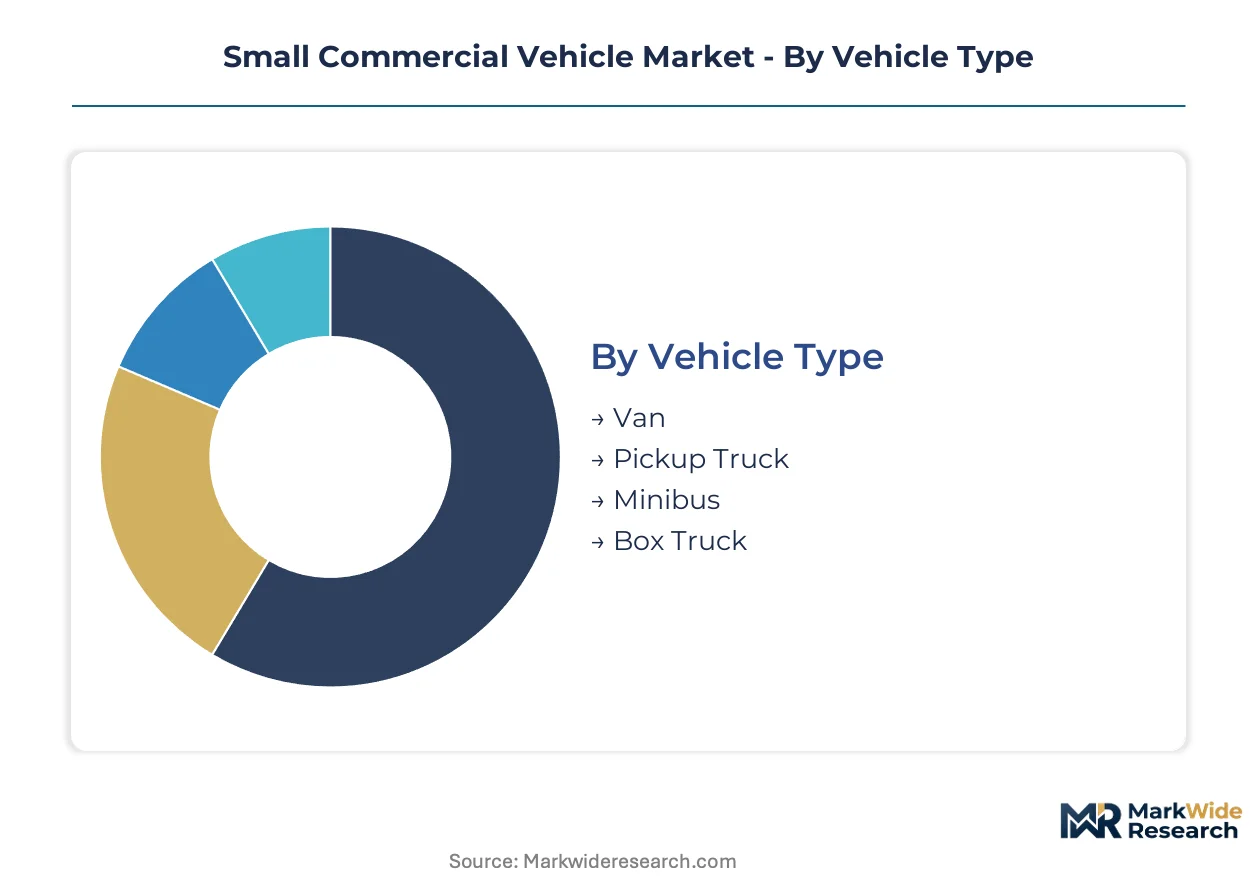
Small commercial vehicle procurement diverges sharply across geographies, with European fleets prioritizing zero-emission compliance while emerging markets optimize for acquisition cost and terrain adaptability. Understanding these segment boundaries reveals where platform engineering investments concentrate versus where derivative variants suffice.
Vehicle Type:
Domestic production dominates van and pickup categories across India and Thailand, while German and Japanese exports anchor premium minibus and box truck supply.
- Van:Enclosed cargo architecture with adaptable interior mounting points serves last-mile delivery density in Paris, Berlin, and Amsterdam. EU Green Deal mandates compress diesel van residual values, accelerating battery-electric conversion timelines for German parcel networks.
- Pickup Truck:Open-bed configurations with reinforced chassis rails address construction site access and agricultural hauling across rural India and Indonesia. Demand concentrates in states with underdeveloped road infrastructure where ground clearance and wading depth determine procurement.
- Minibus:High-roof passenger variants with flexible seating arrays serve urban shuttle contracts and rural school transport in Maharashtra and Gujarat.
- Box Truck:Rigid-sided cargo compartments with liftgate compatibility support fixed-route distribution between metropolitan distribution centers and retail endpoints.
Van holds the largest share; momentum sits with electric van configurations as low-emission zones expand.
Fuel Type:
Cost tier stratification separates premium electric drivetrains from economy diesel and CNG alternatives, with gasoline occupying mid-market fleet niches.
- Diesel:Compression-ignition engines with high torque density sustain long-haul efficiency and heavy-payload ratings. Secondary market liquidity is compressing across EU member states as Brussels enforces stricter CO2 reduction timelines.
- Electric:Battery-electric architectures with silicon carbide inverters maximize range within constrained wheelbase dimensions for urban delivery corridors. Charging infrastructure asymmetry constrains deployment outside metropolitan cores in France and Germany.
- Gasoline:Spark-ignition powertrains with lower upfront cost serve price-sensitive owner-operators in peri-urban Indian markets.
- CNG:Compressed natural gas systems with domestic fuel availability anchor fleet procurement in Delhi and Mumbai where pipeline distribution is dense.
Diesel retains volume leadership; steepest expansion trajectory belongs to electric as battery costs decline and depot charging scales.
Size Class:
Application intensity varies by urban density, with compact and light-duty chassis dominating narrow European streets while full-size vehicles serve intercity freight.
- Light-duty:GVWR ratings below 6,000 pounds optimize maneuverability for dense urban cores with restricted access zones. London and Amsterdam congestion pricing schemes favor this category for central business district penetration.
- Compact:Short-wheelbase configurations with tight turning circles navigate narrow urban corridors in Mumbai and Jakarta where road width averages under 5 meters.
- Medium-duty:Intermediate payload ratings bridge urban last-mile and suburban distribution routes with moderate range requirements.
- Full-size:Maximum payload capacity within the small commercial vehicle threshold serves rural logistics and construction material transport across Indian states with highway connectivity.
Light-duty captures the greatest fleet volume; compact configurations are gaining share fastest as Asian urbanization intensifies.
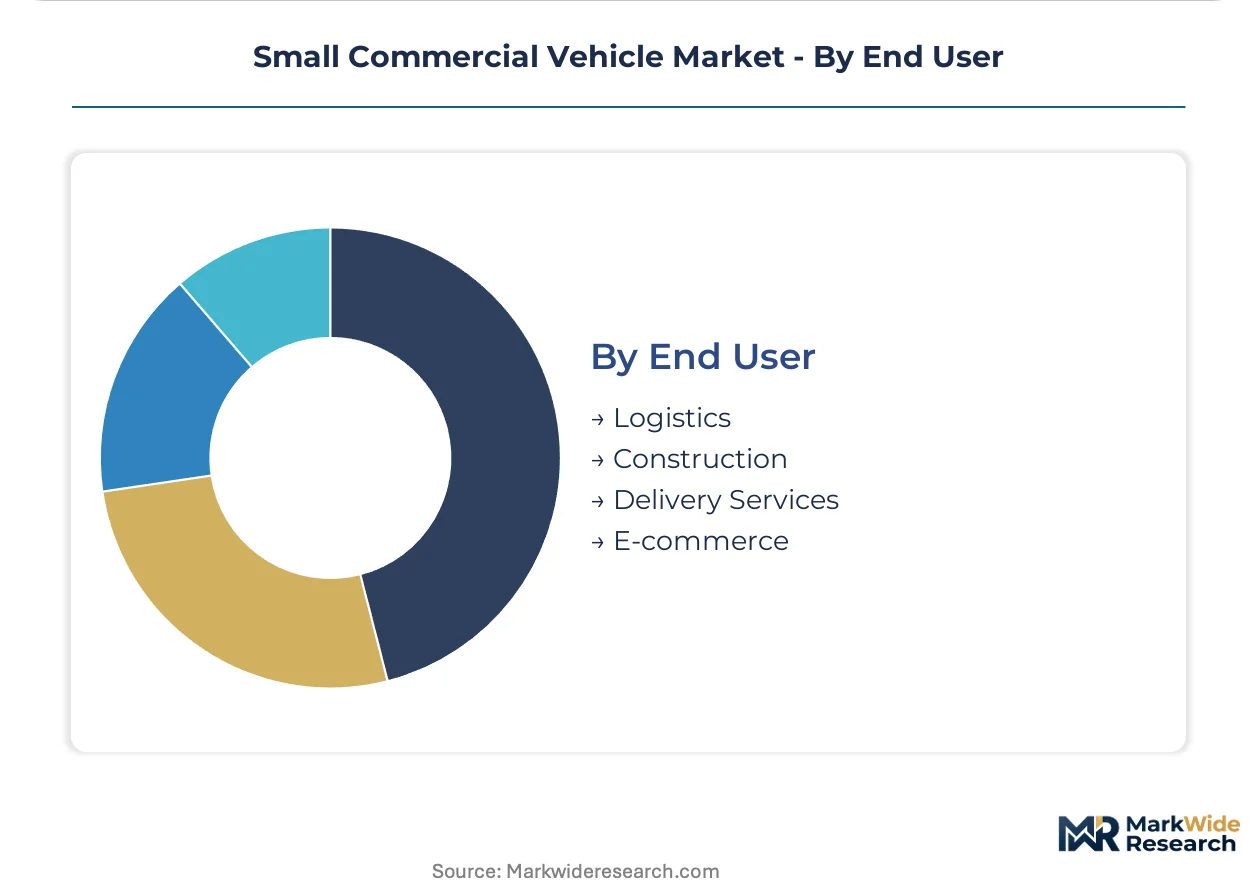
End User:
Customer type determines specification priority, with e-commerce and logistics demanding telematics integration while construction prioritizes durability.
- E-commerce:High-frequency stop-start duty cycles with parcel tracking integration dominate fleet procurement for Amazon and Flipkart last-mile networks. Real-time delivery confirmation systems mandate CAN bus connectivity and over-the-air update capability.
- Logistics:Hub-and-spoke distribution patterns with standardized pallet dimensions drive van and box truck demand across German and Dutch freight corridors. Fleet operators unbundle maintenance contracts based on predictive telematics capability.
- Delivery Services:Food and grocery platforms with sub-30-minute service windows require thermal insulation and rapid access configurations.
- Construction:Rough-terrain durability with high ground clearance and tool storage integration anchors pickup and medium-duty truck demand.
Logistics represents the largest installed base; e-commerce is expanding most quickly as fulfillment network density increases.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Procurement patterns diverge sharply across major economies, with European fleets prioritizing zero-emission compliance while emerging markets optimize for terrain adaptability and acquisition cost. This consumption-mix differential shapes where manufacturers concentrate platform engineering versus derivative variants.
United States
E-commerce fulfillment networks drive van demand across Dallas-Fort Worth and Atlanta distribution corridors. EPA and NHTSA coordinate fuel economy standards that compress powertrain investment calendars for Detroit manufacturers. Ford leverages its Transit architecture to sustain dominance in last-mile configurations serving Amazon and UPS fleets.
Germany
Parcel networks in Berlin and Hamburg accelerate battery-electric van procurement ahead of EU Green Deal CO2 reduction timelines. The F-Gas Regulation compounds powertrain transition pressure by restricting refrigerants in thermal management systems. Daimler and Volkswagen anchor production in Baden-Württemberg and Lower Saxony with silicon carbide inverter integration.
India
Small enterprises and urban transporters concentrate demand in Maharashtra and Gujarat for compact trucks engineered to navigate sub-5-meter road widths. The BIS certification and PLI scheme for automotive manufacturing localize supply chains and mandate technology transfer. Tata Motors and Mahindra dominate sales to construction and agricultural operators in rural corridors.
Japan
Fleet operators prize diesel powertrain reliability perceptions for last-mile logistics across Tokyo and Osaka metropolitan areas. METI standards shape domestic certification requirements that Isuzu and Toyota navigate for kei-truck and compact commercial segments. Manufacturing clusters in Aichi and Shizuoka prefectures export to Southeast Asian markets with similar terrain demands.
Indonesia
Island economies with fragmented road networks present demand for compact, high-payload-efficiency vehicles suited to intermodal freight transfer across Java and Sumatra. Domestic fuel subsidies and sparse charging infrastructure sustain gasoline and diesel procurement preferences. Local assemblers in Bekasi and Karawang industrial zones serve archipelago logistics operators with reinforced chassis configurations.
Small Commercial Vehicle Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with the former commanding platform development budgets and the latter occupying derivative niches. The market structure rewards scale in powertrain electrification and regulatory compliance engineering. Three archetypes dominate: full-line OEMs with van-to-truck portfolios, regional specialists with terrain-optimized chassis, and electric-native entrants with software-defined architectures. Competitive moves concentrate on strategic partnerships for battery supply security and geographic licensing to access protected markets.
Within the full-line OEM tier, Ford Motor Company and Tata Motors Limited exemplify divergent regional dominance patterns. Ford anchors North American last-mile configurations through Transit platform derivatives. Tata Motors occupies a parallel position in South Asian compact commercial segments with cost-optimized engineering for narrow urban corridors. Isuzu Motors represents the regional specialist archetype, with Japanese and Southeast Asian fleet operators associating its diesel powertrains with durability benchmarks.
| Leading Market Players |
|---|
| Ford Motor Company |
| General Motors |
| Toyota Motor Corporation |
| Volkswagen AG |
| Stellantis |
| Isuzu Motors |
| Tata Motors Limited |
| Renault SA |
| Daimler AG |
| Others |
Supply Flow & Price Mechanics
Silicon carbide inverter substitution for traditional silicon IGBT modules simultaneously concentrates power electronics sourcing in Taiwanese and German semiconductor foundries while compressing per-unit inverter costs for European van OEMs. This materials transition redistributes value capture upstream to substrate manufacturers and downstream to fleet operators through improved energy density economics.
Pricing Analysis
Long-term offtake contracts for battery cell supply dominate procurement between OEMs and Korean cathode producers, insulating large fleet customers from spot lithium volatility that squeezes smaller operators. Price differentiation hinges on volume scale and after-sales service bundling, with German parcel networks securing fixed-price maintenance clauses unavailable to Indian owner-operators. Cost compression in the electric van tier is intensifying because silicon carbide adoption reduces thermal management overhead. Construction fleet buyers in rural Indonesia exhibit highest price sensitivity, while EU compliance-driven operators in Berlin and Hamburg absorb premium pricing for zero-emission certification.
Supply Chain Analysis
Inbound logistics costs from Shanghai port congestion and Red Sea route disruptions inflate landed costs for European OEMs sourcing battery cells through Asian trade lanes. Manufacturing concentration clusters in China, South Korea, and Germany for lithium-ion cells, with silicon carbide substrates drawing from Japanese and Taiwanese wafer facilities. Supply chain risk centers on single-source vulnerability for high-purity nickel cathode precursors. Distribution runs through OEM captive networks in developed markets and independent dealer structures across South Asia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market rewards incumbents with regulatory entrenchment moats, as EU Green Deal compliance timelines and India's PLI localization requirements erect asymmetric capital barriers against unqualified entrants.
For Market Incumbents: Consolidate battery supply security through backward integration into cathode precursor production or binding offtake agreements with Korean cell manufacturers. Deepen software-defined vehicle architectures to capture recurring telematics revenue as fleet operators disaggregate maintenance contracts. The emerging threat of electric-native entrants with over-the-air capability demands rapid CAN bus standardization across Transit and compact truck platforms. For New Entrants and Emerging Players: CE marking fast-track for battery-electric vans targeting Indonesian archipelago logistics presents the most penetrable white-space opportunity, with domestic fuel subsidies and sparse charging infrastructure delaying incumbent electrification timelines. Fixed-route urban delivery in secondary Indian cities offers parallel entry vectors. A battery-swapping network partnership with stationary storage providers enables rapid replenishment without grid upgrade dependency, bypassing infrastructure asymmetry that constrains depot-charging competitors. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regional specialists in Southeast Asian diesel powertrain manufacturing, where consolidation pressure from EU emission standards compresses exit timelines. Five-to-ten year viability favors platforms with software-defined architectures and certified high-voltage technician training networks. The signal to monitor is EU low-emission zone expansion velocity, which would accelerate diesel residual value collapse and strand combustion-heavy portfolios.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Supply Agreement | Binding offtake with Korean cathode producers secures cell allocation ahead of EU fleet electrification mandates. |
| Software-Defined Vehicle Investment | Over-the-air capability expansion transforms hardware margins into recurring telematics revenue streams for German logistics consortia. |
| Geographic Manufacturing Footprint | PLI scheme compliance in Maharashtra localizes supply chains for Tata Motors and Mahindra's compact truck dominance. |
| Charging Infrastructure Partnership | Depot fast-charging networks with stationary storage integration enable electric van deployment beyond metropolitan cores in France. |
| Platform Standardization | Transit architecture derivatives sustain Ford's last-mile configuration dominance across Dallas-Fort Worth distribution corridors. |
Methodological Framework
The analysis maps van, pickup, minibus, and box truck sub-sectors, each validated through fleet procurement managers at German parcel networks, Indian small enterprise operators, and Indonesian logistics consortia. Primary interviews with OEM platform engineers, Tier 1 power electronics suppliers, and aftermarket service directors combined with secondary validation from vehicle production databases, IHS Markit registration data, EU CO2 compliance filings, and India's PLI scheme disclosures. Bottom-up unit economics triangulated against top-down market sizing across the analysis window.
Consistency checks validated volume and value outputs against external benchmarks including IEA electric vehicle deployment tracking and national automotive association production statistics. The analytical framework modeled segmentation across vehicle class, propulsion architecture, content per vehicle, OEM tier, and regional production cluster throughout the forecast period. CAGRs derived from regression analysis of historical fleet procurement cycles synchronized with regulatory compliance timelines rather than traditional replacement patterns.
Decision-makers should treat outputs as directional under assumptions of sustained EU Green Deal enforcement and lithium-ion cell cost decline curves; material deviation in battery raw material geopolitics or charging infrastructure deployment velocity would warrant model refresh. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Commercial Vehicles
Global Light Commercial Vehicles Market
Commercial Vehicles
Global Commercial Vehicle Remote Diagnostics Market
Commercial Vehicles
US Semi-Trailer Dealership Market
Commercial Vehicles
Global Commercial Vehicle Fuel Tank Market
Commercial Vehicles
Commercial Vehicle Calibration Market
Commercial Vehicles
Commercial Air Brake Market
Commercial Vehicles
Mini Truck Market
Commercial Vehicles
Europe Vacuum Truck Market
Commercial Vehicles
Europe Light Commercial Vehicle Trailer Market
Commercial Vehicles
Aerial Work Platform (AWP) Truck Market
Commercial Vehicles
Automated Truck Market
Commercial Vehicles
Used Truck Market
Commercial Vehicles
Heavy Haulage Trucks Market
Commercial Vehicles
Europe LCV Rental Market
Commercial Vehicles
Truck Market
Commercial Vehicles
Electric LCV Market