
 Automotive Tinting Film Market | 2026-2036
Automotive Tinting Film Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Tinting Film Market Analysis
REACH is repositioning the cost-of-entry calculus for European suppliers by mandating disclosure of chemical substances in adhesive layers. Eastman Chemical Company leverages its polyester manufacturing scale to control raw material flows for metalized film substrates. 3M Company sustains technology leadership through dense patent portfolios spanning ceramic nanoparticle dispersions. Avery Dennison Corporation anchors its position in professional installation channels through certified dealer networks.
Automotive tinting film consists of multi-layered polymer constructions, typically 0.5 to 2.0 mils thick, incorporating UV-absorbing dyes, metallic or ceramic particle coatings, and pressure-sensitive adhesives bonded to polyethylene terephthalate substrates. The primary commercial purpose is solar heat rejection, glare reduction, and interior protection for vehicle cabins. Ceramic film commands the fastest expansion trajectory among product types due to its non-metallic composition eliminating signal interference for GPS and cellular systems. Professional installation dominates the value chain among installation types, capturing premium pricing through warranty-backed service models. Factory installation is gaining structural importance as automotive manufacturers integrate tint specifications into original equipment configurations.
The US EPA regulates volatile organic compound emissions from adhesive manufacturing processes, while NHTSA maintains visibility standards through Federal Motor Vehicle Safety Standard 205. The EU Green Deal and REACH collectively push formulation shifts toward water-based adhesives and recycled PET substrates. India's BIS certification requirements for automotive glazing accessories create compliance thresholds for import market access. Stakeholders must monitor regulatory divergence between jurisdictions as compliance costs fragment competitive positioning across supply regions.
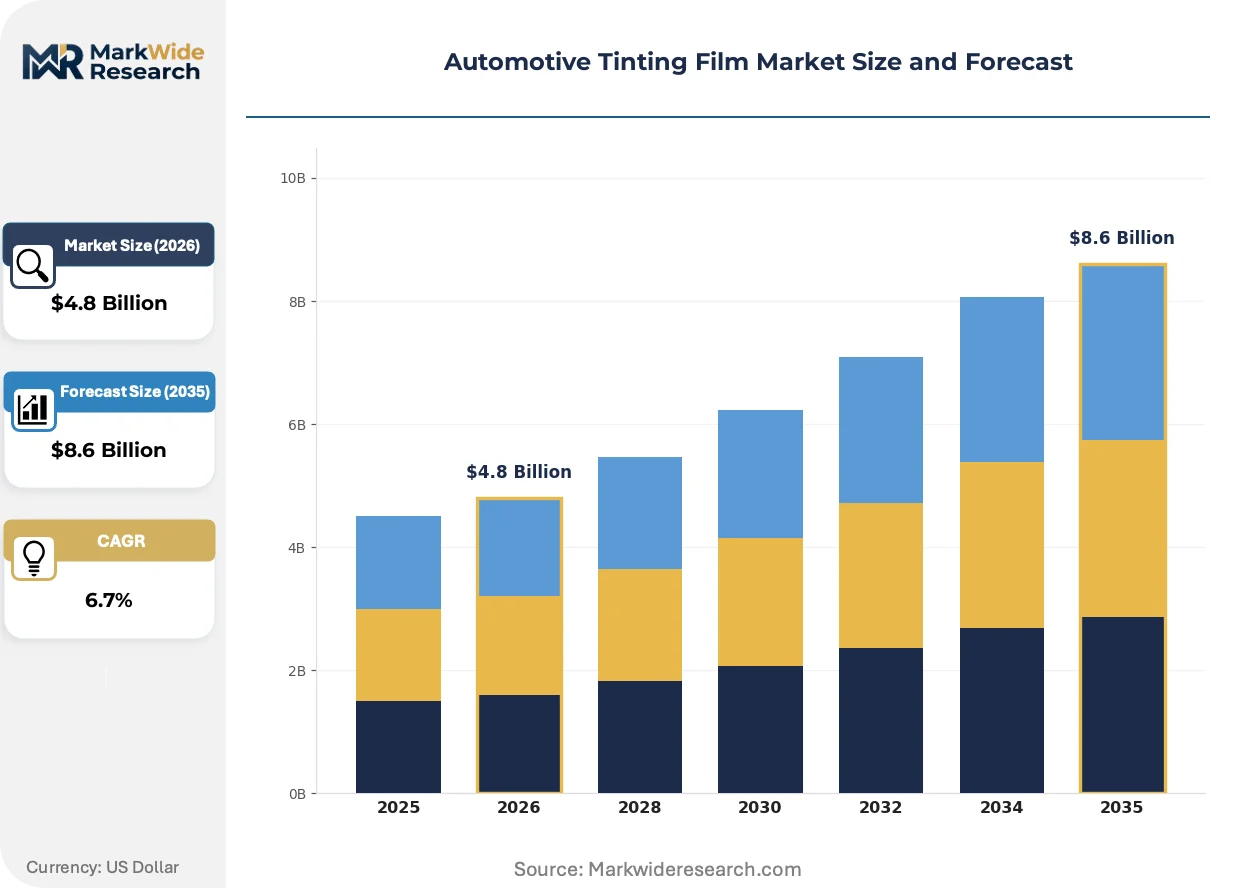
Market Dynamics
Factory-installed tint specifications by electric vehicle OEMs are compressing aftermarket demand while accelerating formulation standardization across the supply base. This OEM pull-through is restructuring channel economics and consolidating specification authority at the vehicle design stage.
Growth Catalysts
- EU Green Deal solvent mandates:Sustainability requirements are accelerating water-based adhesive adoption and creating first-mover advantages for compliant European suppliers.
- Ceramic nanoparticle technology:Non-metallic compositions eliminating GPS and cellular interference are displacing dyed films in premium vehicle segments.
- Germany's automotive supply corridor:Concentrated OEM engineering centers in Stuttgart, Munich, and Wolfsburg are driving specification centralization for factory tint programs.
Market Restraints
- PET substrate cost volatility:Crude oil derivative pricing swings compress margin predictability for film laminators dependent on petroleum-based feedstocks.
- REACH disclosure requirements:Chemical substance registration mandates for adhesive layers impose fixed compliance costs that disproportionately burden smaller European formulators.
- Visibility standard enforcement:NHTSA Federal Motor Vehicle Safety Standard 205 testing protocols create technical barriers for infrared-blocking formulations in the US market.
Strategic Opportunities
- India BIS certification pathway:Mandatory automotive glazing accessory standards create structured market access for compliant foreign manufacturers.
- Recycled PET substrate integration:Circular material flows align with EU Green Deal targets and open differentiated positioning against conventional virgin PET supply.
- Dealer network certification programs:Warranty-backed professional installation channels capture lifetime value through recurring replacement cycles and service attachment.
Industry Challenges
- Skilled installer scarcity:Precision application techniques for ceramic and metalized films require specialized training that outpaces vocational program output.
- Multi-jurisdiction compliance synchronization:Divergent VOC emission limits between EPA state implementation plans and REACH substance restrictions fragment formulation strategies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Tinting Film Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dyed Film, Metalized Film, Ceramic Film, Carbon Film Application: Passenger Vehicles, Commercial Vehicles, SUVs, Electric Vehicles End User: Vehicle Owners, Installers, Fleet Operators, Automotive Manufacturers Installation Type: DIY Installation, Professional Installation, Factory Installation, Mobile Installation |
| Companies Covered | 3M Company, Eastman Chemical Company, Avery Dennison Corporation, Saint-Gobain Performance Plastics, Johnson Window Films, Inc., Madico, Inc., XPEL, Inc., Garware Hi-Tech Films Ltd., NEXFIL Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Tinting Film Market Emerging Trajectories
Formulation chemistry and installation methodology are converging to redefine performance benchmarks and channel economics across the tinting film value chain.
Ceramic nanoparticle dispersion technology is consolidating market structure by enabling non-conductive heat rejection without signal degradation. Luxury electric vehicle manufacturers are specifying ceramic constructions as standard equipment, compressing demand for conventional dyed and metalized alternatives. This specification shift is consolidating purchasing power among OEM engineering teams and displacing fragmented aftermarket decision-making.
REACH substance disclosure mandates are forcing adhesive reformulation across European manufacturing facilities. ECHA registration requirements for isocyanates and solvent components are accelerating water-based system development and disqualifying legacy formulations. German and French suppliers are responding with dedicated low-VOC production lines to defend market access.
Factory tint specification is compressing traditional aftermarket installation cycles. OEM-integrated solar control glazing is displacing dealer add-on programs in premium segments, particularly among German and South Korean vehicle brands. This channel rotation is most visible in corporate fleet procurement, where total cost of ownership calculations favor pre-installed specifications over post-purchase retrofitting.
Automotive Tinting Film Market Segmentation
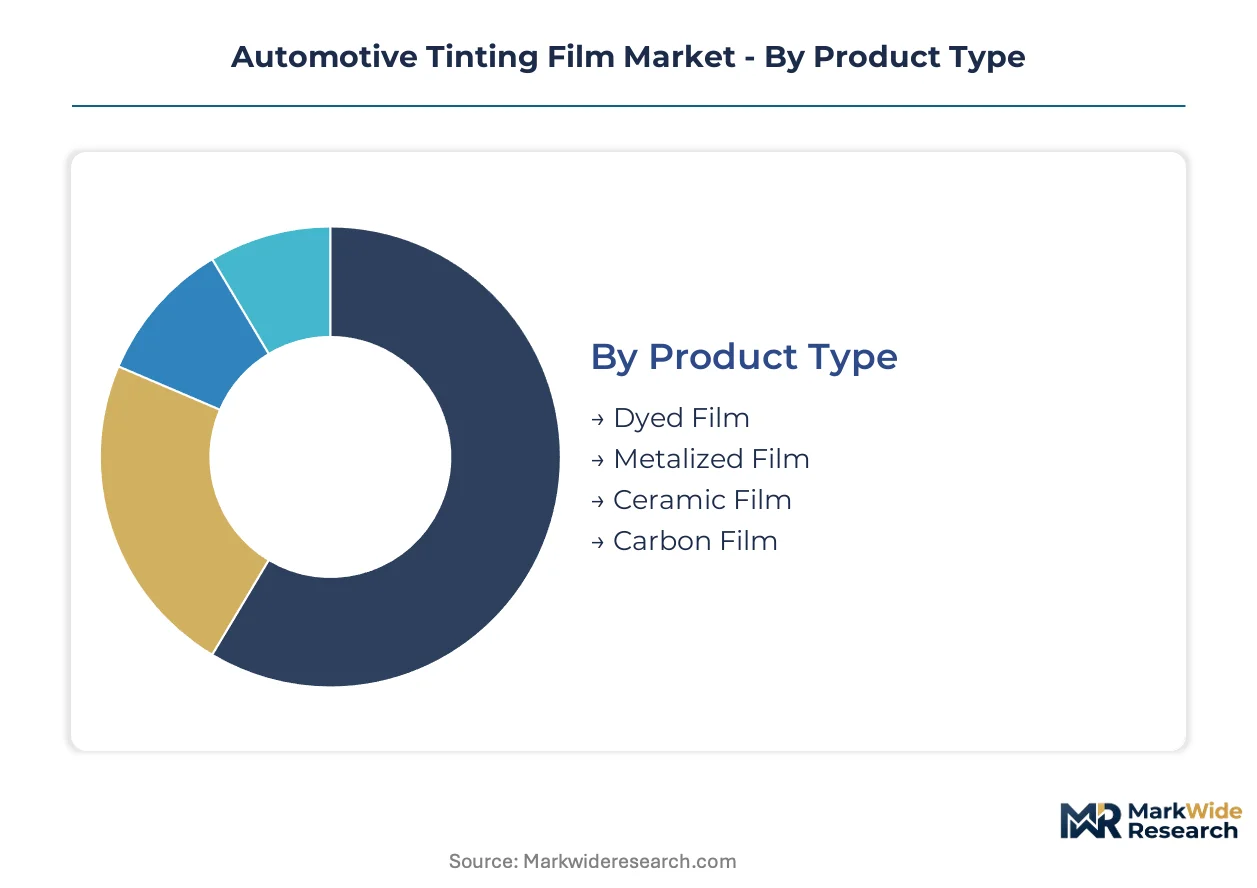
Automotive tinting film segmentation reveals how formulation chemistry, installation channel, and end-user procurement authority fragment pricing power across the value chain. Understanding these fault lines exposes where specification control concentrates and where margin compression threatens.
Product Type:
REACH substance disclosure mandates and NHTSA Federal Motor Vehicle Safety Standard 205 visibility testing create divergent certification burdens across film constructions, with ceramic and metalized variants facing distinct adhesive and optical compliance pathways.
- Dyed Film:UV-absorbing dye layers embedded in PET substrates provide basic glare reduction and privacy at lowest unit cost. Demand concentrates in price-sensitive aftermarket channels across India's tier-2 cities, where BIS certification thresholds remain manageable for regional distributors.
- Metalized Film:Vacuum-deposited aluminum or nickel-chrome layers deliver superior infrared rejection through reflective properties. Germany's premium automotive supply corridor drives specification for this construction, though GPS interference concerns constrain adoption in connected vehicle platforms.
- Ceramic Film:Non-conductive nanoparticle dispersions eliminate signal degradation while maintaining heat rejection performance. Electric vehicle OEMs in Stuttgart and Wolfsburg are specifying this construction as factory standard, accelerating displacement of metallic alternatives.
- Carbon Film:Carbon particle-infused layers offer matte aesthetic finishes with moderate thermal performance. Niche demand persists among custom automotive shops in California and Florida seeking differentiated visual positioning.
Dyed film sits at the top of the volume ranking, with ceramic film climbing the fastest.
Application:
Factory specification authority varies dramatically by vehicle category, with fleet procurement and OEM engineering teams exercising divergent influence over tint selection criteria.
- Passenger Vehicles:Individual owner preference dominates aftermarket decision-making, with ceramic film penetration rising fastest among luxury sedan buyers. Professional installation channels capture recurring replacement demand through warranty-backed service models.
- Commercial Vehicles:Fleet operators prioritize total cost of ownership calculations, favoring pre-installed specifications that reduce downtime and standardize maintenance protocols. Long-haul trucking corridors across Texas and Arizona drive concentrated demand for high-rejection formulations.
- SUVs:Larger glass surface areas amplify heat load challenges, pushing specification toward premium ceramic constructions. Family-oriented buyers in suburban markets show elevated willingness-to-pay for UV protection claims.
- Electric Vehicles:Battery thermal management requirements integrate tint specifications into cabin efficiency engineering. South Korean and German OEMs are embedding solar control glazing into original equipment configurations, compressing aftermarket opportunity.
Passenger vehicles command the largest installed base, though electric vehicles are gaining specification authority fastest.
End User:
Procurement sophistication and volume scale fragment pricing leverage across customer types, with automotive manufacturers consolidating purchasing power while installers compete on service differentiation.
- Vehicle Owners:Fragmented individual decision-making favors brand recognition and installer proximity over technical specification comparison. Online review platforms increasingly influence selection among ceramic film options.
- Installers:Certified dealer networks for Avery Dennison and comparable suppliers capture lifetime value through warranty registration and replacement cycle management. Technical training investments create switching costs that protect margin structures.
- Fleet Operators:Corporate procurement teams negotiate volume contracts with direct film manufacturers, bypassing distribution markups. Specification standardization across vehicle classes reduces inventory complexity.
- Automotive Manufacturers:OEM engineering teams in Munich, Stuttgart, and Wolfsburg centralize tint specification for factory installation programs. Tier-1 supplier qualification requirements exclude smaller formulators from direct supply relationships.
Vehicle owners represent the broadest addressable base, with automotive manufacturers capturing the steepest expansion trajectory through factory integration.
Installation Type:
Channel economics diverge sharply between self-application convenience and precision-engineered professional outcomes, with mobile services emerging as a hybrid disruption vector.
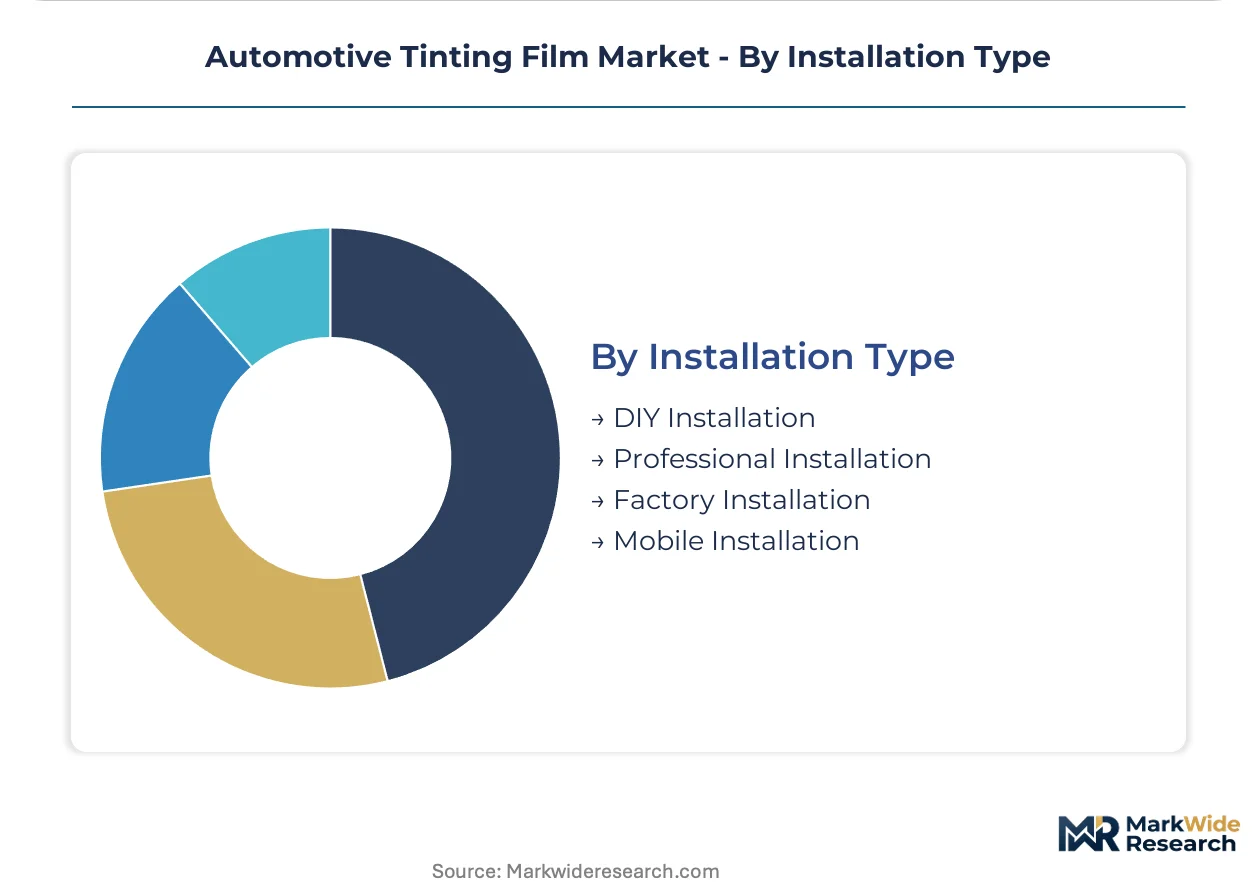
- DIY Installation:Pre-cut kit formats and online tutorial accessibility sustain demand among cost-conscious consumers. Quality variance and warranty exclusion limit penetration in premium film categories.
- Professional Installation:Climate-controlled facilities and certified technician programs deliver defect-free application for ceramic and metalized constructions. Dealer network density in Germany's automotive corridor supports OEM warranty compliance requirements.
- Factory Installation:OEM-integrated production lines eliminate post-purchase friction and capture specification authority at vehicle design stage. Electric vehicle platforms are accelerating this channel's structural importance.
- Mobile Installation:On-site service vans reduce customer time investment while maintaining professional application standards. Fleet contract servicing and corporate campus programs drive volume concentration in metropolitan markets.
Professional installation retains the largest revenue share, with factory installation expanding most quickly as OEM specification authority consolidates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Automotive tinting film production scaled from early polyester extrusion operations in the United States during the 1960s, migrating toward German chemical corridors as OEM specification authority consolidated in Stuttgart and Wolfsburg engineering centers.
United States
Long-haul trucking corridors across Texas and Arizona drive concentrated demand for high-rejection formulations, while EPA volatile organic compound regulations from adhesive manufacturing reshape formulation economics. NHTSA Federal Motor Vehicle Safety Standard 205 visibility testing creates technical barriers for infrared-blocking constructions, compressing market access for non-compliant suppliers.
Germany
Premium automotive OEM engineering teams in Stuttgart, Munich, and Wolfsburg centralize factory tint specifications, consolidating purchasing power among Tier-1 suppliers. REACH substance disclosure mandates for adhesive layers accelerate water-based system development across manufacturing facilities. The Baden-Württemberg chemical corridor hosts specialized low-VOC production lines defending European market access.
China
Domestic electric vehicle manufacturers integrate solar control glazing into original equipment configurations, compressing aftermarket opportunity while accelerating ceramic nanoparticle adoption. MIIT vehicle glazing standards create compliance thresholds for foreign film suppliers. Yangtze River Delta manufacturing clusters concentrate PET substrate extrusion capacity serving regional laminators.
India
Tier-2 city aftermarket channels sustain dyed film demand among price-sensitive vehicle owners, while BIS certification requirements for automotive glazing accessories structure import market access. Corporate fleet procurement in Delhi-NCR and Mumbai metropolitan regions favors pre-installed specifications reducing retrofit downtime. Maharashtra-based distributors navigate compliance complexity for ceramic and metalized constructions.
South Korea
Battery thermal management engineering integrates tint specifications into electric vehicle cabin efficiency design, with Seoul Capital Area OEMs embedding solar control glazing at factory stage. MFDS chemical substance regulations align with broader Asian regulatory convergence trends. Busan-Ulsan industrial complexes supply specialized adhesive chemistries for regional film laminators.
Automotive Tinting Film Market Vendor Landscape
The competitive structure tilts toward diversified chemical conglomerates with captive polyester manufacturing capabilities. Consolidation pressure concentrates specification authority among OEM engineering teams, while aftermarket channels fragment across certified installer networks. Three archetypes dominate: integrated chemical producers controlling upstream substrate supply, specialized film laminators with regional certification advantages, and technology licensors leveraging patent portfolios for royalty extraction. Dominant competitive moves include backward integration into PET resin production and strategic partnerships with electric vehicle OEMs for factory specification lock-in.
Among North American diversified manufacturers, 3M Company and Eastman Chemical Company exemplify the integrated chemical archetype, anchoring competitive positioning through dense patent holdings and captive raw material flows. Avery Dennison Corporation occupies the professional installation channel specialist position, with certified dealer networks creating switching costs that protect margin structures in warranty-backed service models. These three entities collectively represent how specification authority concentrates at the intersection of materials science and OEM engineering relationships.
| Leading Market Players |
|---|
| 3M Company |
| Eastman Chemical Company |
| Avery Dennison Corporation |
| Saint-Gobain Performance Plastics |
| Johnson Window Films, Inc. |
| Madico, Inc. |
| XPEL, Inc. |
| Garware Hi-Tech Films Ltd. |
| NEXFIL Co., Ltd. |
| Others |
Supply Flow & Price Mechanics
Skilled ceramic film installers concentrated in Germany's Baden-Württemberg corridor command wage premiums that widen spreads between professional application tiers and DIY alternatives, compressing margin structures for uncertified operators while elevating pricing floors for warranty-backed service models.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels segments the market by film construction complexity and installation channel. Price differentiation rests on REACH compliance certification and ceramic nanoparticle formulation grade, with OEM factory specifications capturing the lowest price sensitivity among electric vehicle manufacturers. Cost compression in dyed film aftermarket channels intensifies as Indian tier-2 distributors compete on landed cost, while premium ceramic constructions maintain pricing power through signal-interference-free performance guarantees.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from Stuttgart and Wolfsburg engineering centers, while certified dealer networks serve fragmented aftermarket installation. Geographic supply concentrates in Germany, China, and South Korea, with PET substrate extrusion feeding from Yangtze River Delta clusters and specialized adhesive chemistries sourcing from Busan-Ulsan industrial complexes. Raw material dependencies center on petroleum-based PET resin, ceramic nanoparticle dispersions, and pressure-sensitive adhesive polymers. Single-source vulnerability in virgin PET supply creates exposure to crude oil derivative volatility. Distribution runs through Tier-1 supplier qualification pathways for factory programs and regional distributor networks for aftermarket channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story, with specification authority consolidating around ceramic nanoparticle formulations as electric vehicle OEMs embed solar control glazing into original equipment configurations.
For Market Incumbents: To counter factory-installed tint compression of aftermarket demand, deepen backward integration into PET resin production to defend margin structures against feedstock volatility, and accelerate water-based adhesive R&D to secure REACH-compliant supply positions for European OEM qualification. For New Entrants and Emerging Players: Certified installer networks in India's tier-2 cities offer the most penetrable white-space target, with BIS certification pathways creating structured market access for compliant ceramic film suppliers seeking to bypass saturated premium OEM channels through regional distributor partnerships. For Investors and Strategic Acquirers: Diversified chemical conglomerates with captive polyester manufacturing capabilities are the most active acquirer in this space, targeting specialized film laminators with regional certification advantages. Long-term viability favors targets with OEM engineering relationships and low-VOC production assets. Watch ceramic nanoparticle patent expiration schedules as inflection indicators for competitive entry pressure.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into PET Resin Production | Captive substrate supply insulates margin structures from petroleum derivative volatility affecting German and Chinese laminators. |
| Water-Based Adhesive System Development | REACH-compliant formulations secure ECHA registration for European OEM factory specification programs. |
| Ceramic Nanoparticle Patent Licensing | Royalty extraction from non-conductive heat rejection technology extends revenue streams beyond direct manufacturing. |
| Certified Installer Network Expansion | Warranty-backed service models in Germany's automotive corridor create switching costs protecting aftermarket pricing power. |
| Recycled PET Substrate Integration | Circular material flows align with EU Green Deal targets and differentiate supply positions against virgin PET competitors. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with OEM platform engineers, Tier-1 supplier procurement leads, aftermarket distributors, and certified installation technicians with secondary validation against vehicle production databases, IHS Markit registration data, SEC filings from diversified chemical manufacturers, and customs trade records for PET substrate flows. Bottom-up segment sizing and top-down market triangulation cross-checked volume estimates across the analysis window.
Comparable-period anchoring linked projection models to historical reference data spanning pre-pandemic baseline through current specification shifts, with segmentation dimensions covering film construction type, installation channel, vehicle propulsion architecture, and regional regulatory cluster. CAGRs were derived from modeled adoption curves for ceramic nanoparticle formulations and factory-installed specification penetration rates, incorporating battery thermal management engineering requirements as electric vehicle-specific demand drivers.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to REACH substance restriction amendments, crude oil derivative pricing trajectories, and electric vehicle platform standardization decisions by German and South Korean OEMs. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Interior & Exterior
Automotive Inside Rearview Mirrors (IRVM) Market
Automotive Interior & Exterior
Automotive Heated Steering Wheel Market
Automotive Interior & Exterior
Automotive Interior Materials Market
Automotive Interior & Exterior
Automotive Seats Market
Automotive Interior & Exterior
Automotive Steering Wheel Market
Automotive Interior & Exterior
Glazing for Automotive Market
Automotive Interior & Exterior
Automotive Panoramic Sunroof Market
Automotive Interior & Exterior
Capacitive Touch Switch Panels for Vehicle Interiors Market
Automotive Interior & Exterior
Mexico Automotive OEM Coatings Market
Automotive Interior & Exterior
Automotive Overhead Console Market
Automotive Interior & Exterior
Automotive Air Suspension System Market
Automotive Interior & Exterior
Automotive Center Console Market
Automotive Interior & Exterior
Interior Materials for Pet-Friendly Vehicle Cabins Market
Automotive Interior & Exterior
Automotive Exterior Trim Parts Market
Automotive Interior & Exterior
Car Oxygen Bar Market
Automotive Interior & Exterior
Smart Automotive Headlight Market