
 Automotive E/ E Architecture Market | 2026-2036
Automotive E/ E Architecture Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive E/ E Architecture Market Analysis
Project finance for semiconductor foundries and leasing models for ECU testing equipment is tilting competitive dynamics toward capital-rich participants. Robert Bosch GmbH leverages captive semiconductor partnerships to sustain in-house E/E platform development. Continental AG anchors its position through dedicated zonal controller R&D centers across Central Europe. Aptiv PLC differentiates via software-defined vehicle stacks that compete directly with traditional hardware-centric architectures.
Automotive E/E architecture encompasses the hierarchical network of electronic control units, wiring harnesses, and communication protocols that manage vehicle functions, with modern zonal designs consolidating up to 100 discrete ECUs into domain controllers linked by Ethernet backbone operating at 1-10 Gbps. Its primary purpose is to enable scalable software updates, reduce wiring mass, and support autonomous driving sensor fusion. Ethernet-based connectivity solutions are capturing the fastest expansion as bandwidth requirements for ADAS camera arrays multiply, while CAN and LIN protocols retain dominance in cost-sensitive body electronics where data throughput demands stay modest. Battery Management System integration represents the deepest margin pool, since thermal runaway protection and cell balancing algorithms require ASIL-D certified hardware that commands premium pricing from OEMs.
The UNECE R155 cybersecurity regulation and the EU's proposed Cyber Resilience Act mandate type-approved intrusion detection across all new vehicle categories, compelling Tier-1 suppliers to redesign gateway architectures. China's MIIT enforces GB/T standards for electric vehicle controller area networks that diverge from ISO 26262 functional safety frameworks, fragmenting validation requirements. Japan's METI coordinates domestic OEM alignment on next-generation vehicle operating systems that will reshape supplier qualification criteria. Stakeholders must decide whether to pursue multi-standard certification or specialize within single regulatory blocs before platform consolidation locks in design choices.
Market Dynamics
Zonal consolidation of electronic control units is compressing Tier-1 supplier margins while forcing semiconductor foundries to requalify automotive-grade silicon at unprecedented velocity. This architectural shift from distributed to domain-centralized computing creates winner-take-most dynamics in gateway controller procurement.
Growth Catalysts
- China's MIIT GB/T mandates:Domestic NEV certification requirements accelerate zonal architecture adoption among local OEMs seeking compliance efficiency.
- Ethernet backbone proliferation:10 Gbps data throughput specifications for ADAS sensor fusion are displacing legacy CAN-FD in premium vehicle segments.
- Stuttgart-Munich engineering corridor:Concentrated OEM R&D investment pulls Tier-1 engineering resources into Germany's southwestern automation belt.
Market Restraints
- Automotive-grade silicon scarcity:Foundry capacity allocation to consumer electronics constrains ECU microcontroller supply from Taiwan-based semiconductor manufacturers.
- UNECE R155 compliance costs:Cybersecurity type-approval requirements add non-recurring engineering overhead that disadvantages mid-volume suppliers.
- Wiring harness legacy lock-in:Existing manufacturing tooling for copper-intensive harness architectures resists rapid retooling for optical Ethernet.
Strategic Opportunities
- Software-defined vehicle stacks:Over-the-air update capabilities create recurring revenue streams for platform-agnostic middleware providers.
- India's PLI scheme for automotive electronics:Production-linked incentives attract zonal controller assembly capacity to Pune and Chennai manufacturing zones.
- Battery Management System integration:ASIL-D certified thermal runaway protection modules command premium positioning in electric vehicle platforms.
Industry Challenges
- Functional safety engineer scarcity:ISO 26262 certification expertise concentrates among German and Japanese engineering consultancies, constraining supplier scaling.
- Multi-standard validation complexity:Divergent Chinese GB/T and European UNECE frameworks force parallel testing protocols that extend product launch timelines.
- Legacy ECU obsolescence management:End-of-life component sourcing for 10+ year vehicle support cycles strains semiconductor inventory planning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive E/ E Architecture Market |
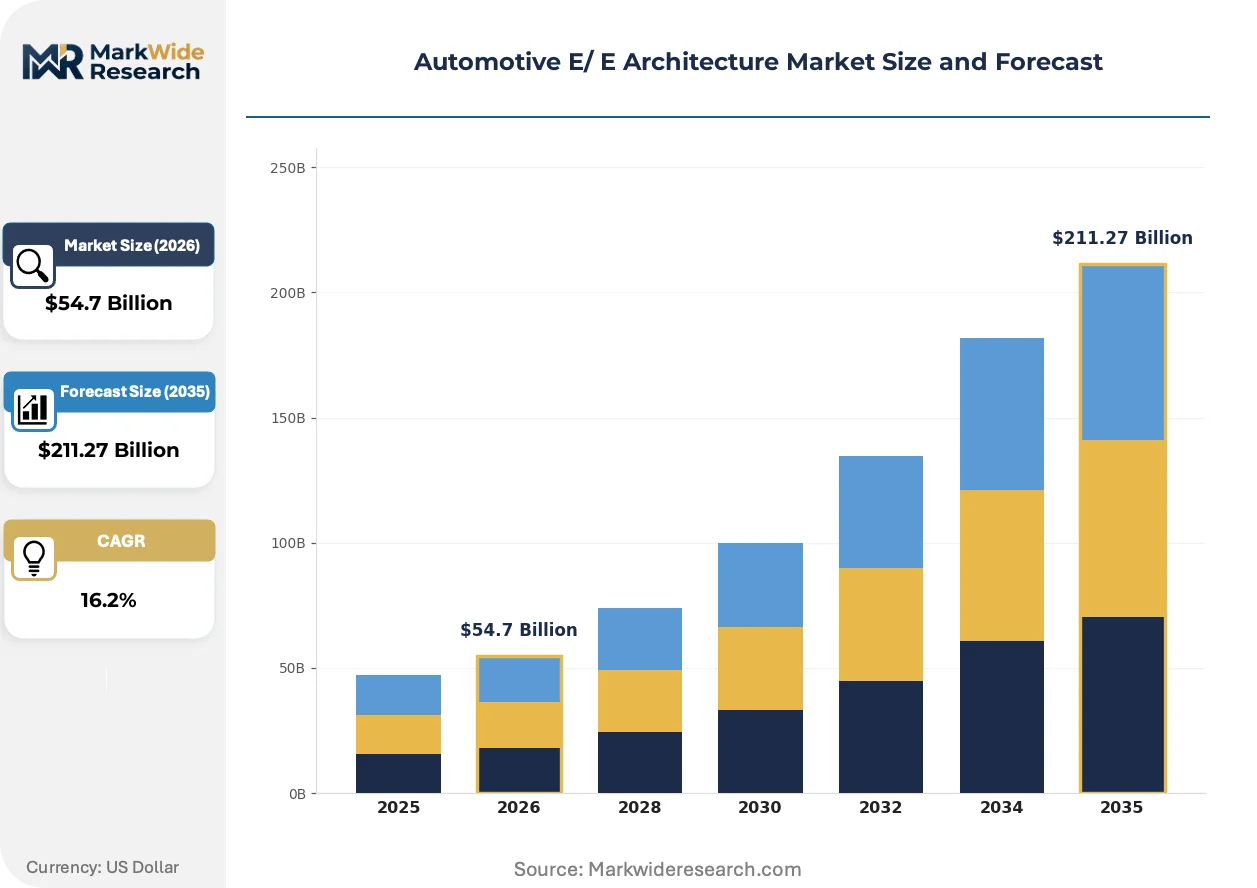
| Market Size in 2026 | $54.7 Billion |
| Market Size in 2035 | $211.27 Billion |
| CAGR (2026 – 2036) | 16.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Battery Management System, ADAS, Connectivity Solutions, Body Control Module Technology: Ethernet, CAN, LIN, FlexRay End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers Application: Powertrain, Comfort Electronics, Safety Systems, Infotainment |
| Companies Covered | Robert Bosch GmbH, Continental AG, Aptiv PLC, ZF Friedrichshafen AG, DENSO Corporation, Magna International Inc, Valeo SE, Hitachi, Ltd., Panasonic Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive E/ E Architecture Market Emerging Trajectories
Automotive electrical architectures are undergoing forced convergence between semiconductor supply constraints and software-defined vehicle requirements. This tension accelerates design standardization while fragmenting regulatory compliance pathways.
Domain controller computing is migrating from distributed 8-bit microcontrollers to centralized 32-bit multi-core processors with hardware virtualization. Premium OEMs in Germany and California are consolidating 70-100 discrete ECUs into 5-6 zonal gateways. This migration from hardware-centric to software-defined architectures compresses wiring mass by 30 kilograms per vehicle while enabling subscription-based feature activation.
UNECE R155 cybersecurity regulations now mandate intrusion detection systems across all new vehicle categories sold in EU member states. Tier-1 suppliers must redesign gateway architectures with hardware security modules and encrypted firmware pipelines. European OEMs face the steepest compliance curve as type-approval deadlines approach, forcing accelerated partnerships with semiconductor vendors holding pre-certified ASIL-B components.
Fleet operators and mobility service providers now specify open API architectures in procurement contracts rather than accepting proprietary Tier-1 software stacks. This specification pattern disrupts traditional hardware-software bundling models that dominated OEM-Tier-1 relationships. North American commercial vehicle segments show the fastest contract language evolution, with telematics unbundling from powertrain controllers becoming standard in heavy-duty truck platforms.
Automotive E/ E Architecture Market Segmentation
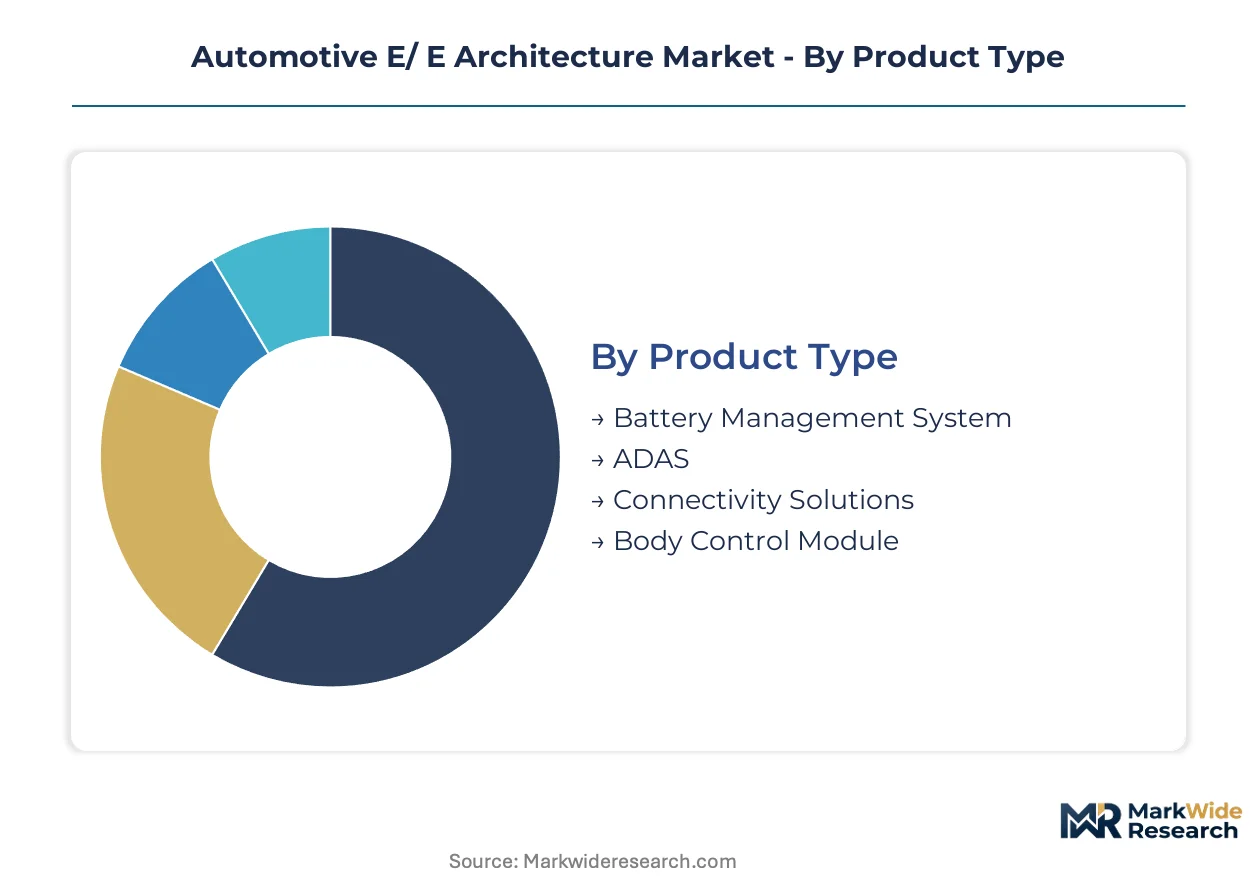
Architectural choices in automotive E/E systems cascade through semiconductor procurement, software licensing, and regulatory validation timelines. Segment-level dynamics determine which suppliers capture recurring revenue versus one-time hardware margins.
Product Type:
Cycle times diverge sharply: battery management systems lock in for platform generations, while connectivity modules refresh annually to match consumer electronics benchmarks.
- Battery Management System:ASIL-D certified hardware manages cell balancing and thermal runaway protection across high-voltage electric vehicle platforms. Stuttgart-based OEMs specify these modules for premium NEV architectures, with certification cycles spanning 4-5 years per design generation.
- ADAS:Sensor fusion computers process camera, radar, and lidar inputs through centralized domain controllers. California and Bavarian engineering centers drive specification evolution as automated driving levels advance.
- Connectivity Solutions:Telematics control units enable over-the-air updates and V2X communication.
- Body Control Module:Zonal gateways consolidate lighting, climate, and access functions.
Battery Management System dominates installed base. Connectivity Solutions is where expansion concentrates.
Technology:
Cost tiers separate premium vehicle Ethernet deployments from mass-market legacy protocols.
- Ethernet:1-10 Gbps backbone networks support ADAS camera arrays and software-defined vehicle stacks. German premium OEMs mandate this specification for zonal architectures, displacing CAN-FD in high-bandwidth domains.
- CAN:Controller Area Network protocols retain cost advantages in powertrain and chassis applications where data rates remain modest.
- LIN:Low-cost single-wire buses serve door modules and seat controls.
- FlexRay:Deterministic high-speed protocol persists in brake-by-wire and steer-by-wire safety systems.
CAN dominates installed base. Ethernet is climbing the fastest.
End User:
Volume concentration varies by procurement authority: OEMs specify architecture, Tier-1s execute integration, assemblers focus on cost minimization.
- OEMs:Vehicle manufacturers define E/E platform roadmaps and gateway specifications. China's MIIT GB/T compliance requirements pull domestic OEMs toward zonal consolidation faster than legacy redesign cycles.
- Tier-1 Suppliers:Bosch, Continental, and Aptiv engineer domain controllers to OEM specifications.
- Aftermarket Providers:Retrofit telematics and diagnostic tools for fleet operators.
- Vehicle Assemblers:Contract manufacturers execute wiring harness installation and ECU mounting.
Tier-1 Suppliers dominate installed base. OEMs is where expansion concentrates.
Application:
Maturity gradients separate safety-critical systems with decade-long validation from consumer-facing electronics with smartphone-like refresh rates.
- Powertrain:Motor control and battery management systems require ISO 26262 ASIL-C/D certification. Japan's METI coordinates domestic OEM alignment on next-generation operating systems that reshape supplier qualification for this domain.
- Safety Systems:Airbag controllers and crash sensors demand deterministic response timing.
- Infotainment:Touchscreen and audio systems follow consumer electronics innovation cycles.
- Comfort Electronics:Climate control and ambient lighting modules prioritize cost optimization.
Powertrain dominates installed base. Infotainment is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics for automotive E/E architecture components favor manufacturing economies with integrated semiconductor ecosystems. China runs substantial trade surpluses in zonal controllers and battery management systems. Germany maintains export leadership in high-margin ASIL-D certified hardware despite rising import dependency on Taiwanese silicon.
Germany
Stuttgart and Munich engineering corridors concentrate Tier-1 R&D investment for domain controllers. KBA enforces UNECE R155 cybersecurity type-approval deadlines that compress supplier redesign cycles. Baden-Württemberg hosts captive semiconductor partnerships between Robert Bosch GmbH and foundry operators securing automotive-grade silicon allocation.
China
Domestic NEV platforms from BYD and NIO accelerate zonal architecture adoption beyond legacy redesign timelines. MIIT GB/T mandates for electric vehicle controller networks diverge from ISO 26262 frameworks, fragmenting validation requirements. Yangtze River Delta manufacturing zones in Shanghai and Suzhou concentrate zonal controller assembly capacity serving both domestic OEMs and export markets.
United States
California and Michigan engineering centers drive specification evolution for ADAS sensor fusion computers. NHTSA coordinates with EPA on autonomous vehicle safety standards that reshape gateway architecture requirements. Detroit-Warren automotive corridor anchors Tier-1 supplier engineering resources for North American OEM platform development.
Japan
Tokyo and Nagoya OEMs coordinate through METI on next-generation vehicle operating systems that reshape supplier qualification criteria. PMDA-aligned functional safety frameworks govern ASIL-C/D certification for powertrain controllers. Kanto region semiconductor packaging facilities support domestic ECU microcontroller supply chains against Taiwanese foundry constraints.
South Korea
Seoul Capital Area OEMs specify open API architectures in procurement contracts disrupting traditional hardware-software bundling. MFDS coordinates with METI-aligned standards for battery management system thermal runaway protection modules. Busan-Ulsan manufacturing belt concentrates wiring harness retooling investment for optical Ethernet migration.
Automotive E/ E Architecture Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream supplying certified silicon and sensor modules. The vendor base concentrates among German and Japanese conglomerates with captive semiconductor access, while mid-volume suppliers face margin compression from zonal consolidation. Three archetypes dominate: integrated platform developers, domain controller specialists, and semiconductor-anchored Tier-1s. Competitive moves center on strategic partnerships with foundry operators and portfolio diversification into software-defined vehicle middleware.
Within the integrated platform tier, Robert Bosch GmbH and Continental AG exemplify archetypes combining captive semiconductor partnerships with in-house E/E development. Aptiv PLC occupies a position representing software-centric challengers competing against hardware-centric incumbents. These three anchors illustrate the competitive tension between semiconductor-secured conglomerates and software-defined vehicle stack specialists.
| Leading Market Players |
|---|
| Robert Bosch GmbH |
| Continental AG |
| Aptiv PLC |
| ZF Friedrichshafen AG |
| DENSO Corporation |
| Magna International Inc |
| Valeo SE |
| Hitachi, Ltd. |
| Panasonic Corporation |
| Others |
Supply Flow & Price Mechanics
Single-source dependency on Taiwan-based semiconductor foundries determines both pricing tier spreads and supply chain shape across automotive E/E architecture procurement. UNECE R155 cybersecurity certification costs widen spreads between ASIL-D certified premium controllers and uncertified economy alternatives, while foundry allocation constraints force OEMs into long-term offtake commitments that reshape Tier-1 supplier relationships.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Premium tiers command substantial markups for ASIL-D certified battery management systems and hardware security modules, while standard segments compete on per-unit microcontroller costs and economy tiers sacrifice customization for volume scale. Cost compression in mid-volume gateway controllers is intensifying because zonal consolidation reduces discrete ECU counts per vehicle. Fleet operators and mobility service providers exhibit lowest price sensitivity due to total-cost-of-ownership calculations, whereas contract vehicle assemblers face acute margin pressure from fixed-price wiring harness contracts.
Supply Chain Analysis
Tariff exposure between Germany and China dominates strategic sourcing decisions for domain controller assembly. Taiwan, South Korea, and Japan anchor semiconductor wafer supply, while Germany and China concentrate zonal controller manufacturing. The supply chain draws from automotive-grade silicon wafers, copper-intensive wiring harnesses, and optical Ethernet transceivers. Single-source vulnerability persists at the foundry level where TSMC and Samsung Foundry control advanced automotive node allocation. Distribution runs through captive Tier-1 supplier networks rather than open component markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automotive E/E architecture represents a service-attach opportunity where software-defined vehicle stacks and over-the-air update subscriptions expand faster than hardware margins. Recurring revenue from cybersecurity monitoring and predictive maintenance algorithms outpaces one-time controller sales.
For Market Incumbents: Insulate market position through backward integration into automotive-grade semiconductor supply and accelerated ASIL-D certification investment. Software-centric challengers threaten hardware-centric revenue models by unbundling telematics from powertrain controllers. Capacity addition in India's Pune and Chennai manufacturing zones under PLI incentives secures cost-competitive assembly footprint against emerging regional competitors.
For New Entrants and Emerging Players: Establish a beachhead in aftermarket retrofit telematics for commercial fleet operators seeking open API architectures. India's production-linked incentive zones offer the most penetrable geography given nascent zonal controller assembly capacity and favorable policy terms. A direct-to-fleet go-to-market angle bypasses entrenched OEM-Tier-1 relationships that resist new supplier qualification.
For Investors and Strategic Acquirers: UNECE R155 full enforcement reshapes the acquisition landscape toward cybersecurity-certified gateway specialists. Long-term viability across the next decade hinges on software-defined vehicle middleware capabilities rather than discrete hardware volumes. Acquisition targets should demonstrate pre-certified ASIL-B component libraries and established foundry partnerships. The signal to watch is open API contract language penetration in North American commercial vehicle procurement.
| Strategic Initiative | Industry Significance |
|---|---|
| Software-Defined Vehicle Investment | Enables subscription revenue streams through over-the-air feature activation for Stuttgart-based OEM platforms. |
| Battery Supply Agreement | Secures ASIL-D certified thermal runaway protection modules commanding premium positioning in NEV architectures. |
| Geographic Manufacturing Footprint | Positions capacity in Yangtze River Delta zones to serve both domestic Chinese OEMs and export markets. |
| Platform Standardization | Reduces ECU variety from 70-100 discrete units to 5-6 zonal gateways, compressing wiring mass and validation costs. |
| Charging Infrastructure Partnership | Integrates battery management systems with V2X communication stacks for grid-interactive electric vehicle fleets. |
Methodological Framework
Initial hypotheses were tested against primary input from OEM platform engineers, Tier-1 supplier procurement leads, semiconductor foundry account managers, and aftermarket fleet operators and refined through secondary validation. OEM platform roadmaps, MIIT GB/T regulatory filings, UNECE R155 type-approval databases, and vehicle production registration data provided foundational benchmarks. Bottom-up unit economics triangulated against top-down market sizing from regional production cluster analysis.
Demand-supply balance framing anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include propulsion architecture, vehicle class, content per vehicle, OEM tier, and regional production cluster. CAGRs derived from S-curve adoption modeling for zonal architecture penetration rates, with inputs from foundry capacity expansion announcements and OEM platform lifecycle disclosures. Ethernet backbone displacement timelines and cybersecurity certification backlog estimates informed technology transition assumptions.
Sensitivities concentrate around Taiwan semiconductor foundry allocation decisions, MIIT GB/T standard evolution diverging from ISO 26262 frameworks, and zonal consolidation velocity compressing Tier-1 supplier margins. Forecasts reflect documented assumptions on NEV platform rollout schedules and regulatory compliance deadlines. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Electrical & Electronics
Wire Harness Market
Automotive Electrical & Electronics
New Energy Automotive Antenna Module Market
Automotive Electrical & Electronics
Mexico Automotive Electric Actuators Market
Automotive Electrical & Electronics
UK Automotive Eps Market
Automotive Electrical & Electronics
Switchrack Assemblies Market
Automotive Electrical & Electronics
Electric Vehicle High-Voltage Cables Market
Automotive Electrical & Electronics
South Korea Automotive Camera Market
Automotive Electrical & Electronics
Steering Wheel Switches Market
Automotive Electrical & Electronics
EPS Motors Market
Automotive Electrical & Electronics
Automotive EMI Shielding Market
Automotive Electrical & Electronics
Global Automotive DC-DC Converters Market
Automotive Electrical & Electronics
Europe Automotive Pressure Sensor Market
Automotive Electrical & Electronics
North America Automotive Lead-Acid Battery Market
Automotive Electrical & Electronics
Europe Automotive Steering Sensor Market
Automotive Electrical & Electronics
Stair Lift Motors Market
Automotive Electrical & Electronics
Automotive Thermal Management System Market