
 Pre-Mature Baby Monitoring Equipment Market | 2026-2036
Pre-Mature Baby Monitoring Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Pre-Mature Baby Monitoring Equipment Market Analytics
Asian contract manufacturers of pulse oximetry sensors is rebalancing capacity toward integrated monitoring platforms. GE HealthCare leverages its imaging-to-monitoring workflow to sustain neonatal ICU bundling. Drägerwerk anchors European ventilator supply through German engineering centers. Masimo Corporation differentiates via proprietary signal extraction technology for low-perfusion neonatal readings.
Pre-mature baby monitoring equipment comprises sensor arrays, display modules, and alarm algorithms designed for infants below 37 weeks gestational age, typically operating at measurement resolutions exceeding adult-critical-care standards by a factor of two to five. These systems enable continuous surveillance of cardiorespiratory stability in neonates weighing under 1,500 grams. Cardiac monitors and pulse oximeters command the largest installed base, while wearable technology segments attract the fastest replacement cycles as hospitals seek to reduce skin injury incidence. Wireless telemetry architectures are displacing hardwired bedside configurations in newly constructed neonatal intensive care units across North America and Western Europe.
FDA premarket notification requirements and EU MDR Class IIa/IIb conformity pathways shape device development timelines and clinical evidence burdens for manufacturers seeking market access. ISO 80601-2-56 and IEC 60601-1-10 standards govern alarm fatigue mitigation and electromagnetic compatibility, respectively, forcing engineering trade-offs between sensitivity and false-alert suppression. Stakeholders must weigh regulatory compliance investment against the pace of wearable sensor miniaturization when allocating R&D budgets across product generations.
Market Dynamics
Wireless telemetry architectures are overtaking hardwired bedside configurations in newly constructed neonatal intensive care units, compressing installation timelines and enabling flexible ward reconfigurations that hardwired systems cannot accommodate.
Growth Catalysts
- EU MDR Class IIb conformity pathways:Regulatory tightening around neonatal device safety standards accelerates product innovation cycles as manufacturers invest in higher-grade clinical evidence packages to secure market access.
- Tertiary hospital NICU expansion:Public investment in perinatal healthcare infrastructure across the United States, Germany, and China sustains procurement volumes for integrated monitoring platforms.
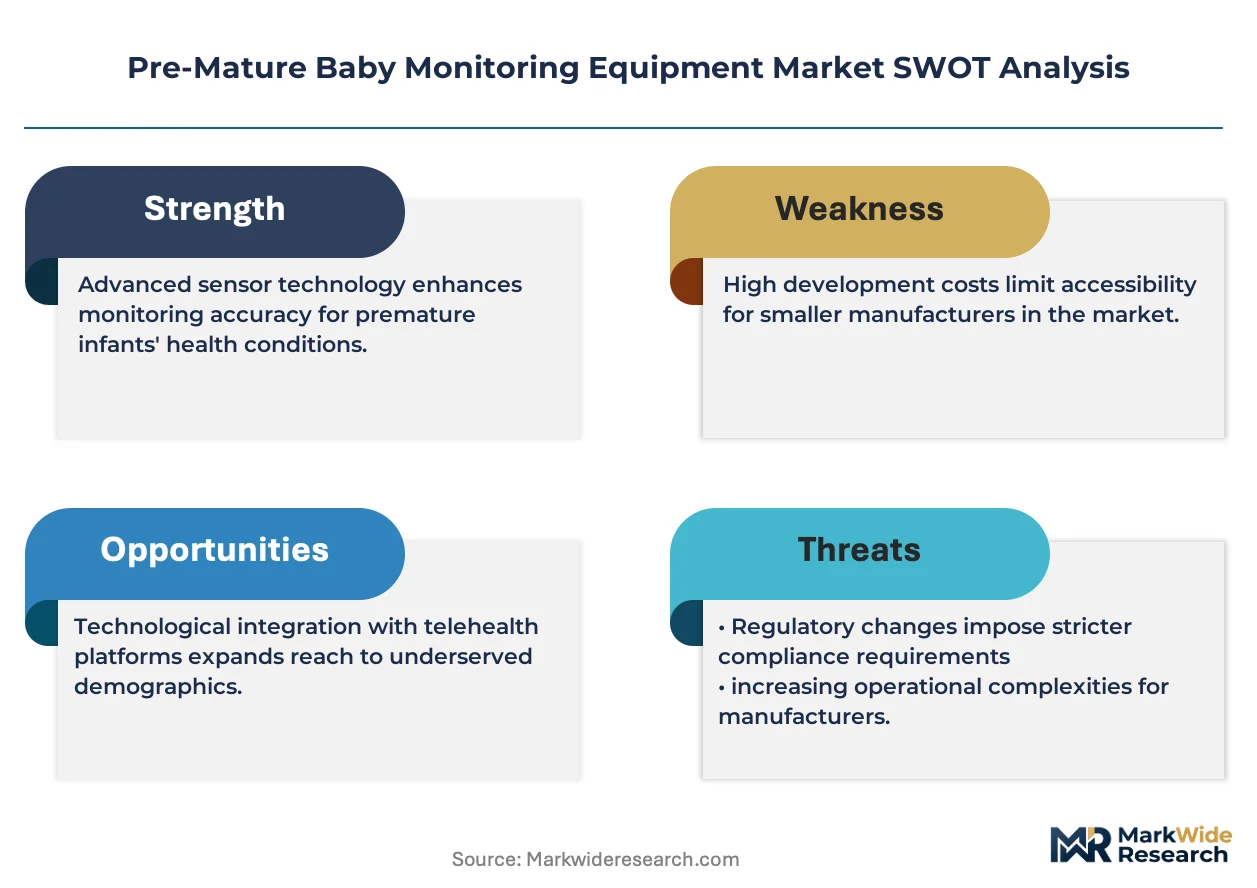
- Wearable sensor miniaturization:Advances in flexible electronics and low-power Bluetooth protocols enable continuous cardiorespiratory surveillance without skin injury risks associated with adhesive electrodes.
Market Restraints
- ISO 80601-2-56 alarm fatigue mitigation standards:Engineering trade-offs between sensitivity and false-alert suppression extend development timelines and increase firmware validation costs.
- Asian contract manufacturer concentration:Pulse oximetry sensor production clusters in specific East Asian manufacturing zones create single-source vulnerability for integrated platform supply chains.
- Adult-critical-care specification gaps:Measurement resolution requirements exceeding adult standards by two to five factors necessitate specialized sensor calibration infrastructure that generalist device makers lack.
Strategic Opportunities
- Underpenetrated Indian tertiary care:CDSCO regulatory harmonization with ISO standards lowers import barriers for CE-marked devices, opening procurement channels in emerging perinatal hubs.
- Remote NICU telemetry:Cloud-native monitoring platforms enable centralized specialist oversight of satellite neonatal units, addressing pediatric intensivist shortages in rural hospital networks.
- Japanese METI sustainable healthcare procurement:National reimbursement incentives for energy-efficient medical devices create preference windows for low-power wireless architectures.
Industry Challenges
- Electromagnetic compatibility certification:IEC 60601-1-10 testing protocols for wireless neonatal monitors require specialized anechoic chamber facilities that extend time-to-market by six to twelve months.
- Neonatal signal processing expertise scarcity:Low-perfusion physiology algorithm development demands cross-disciplinary teams combining pediatric cardiology knowledge with embedded systems engineering, a combination rarely found in single labor markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pre-Mature Baby Monitoring Equipment Market |
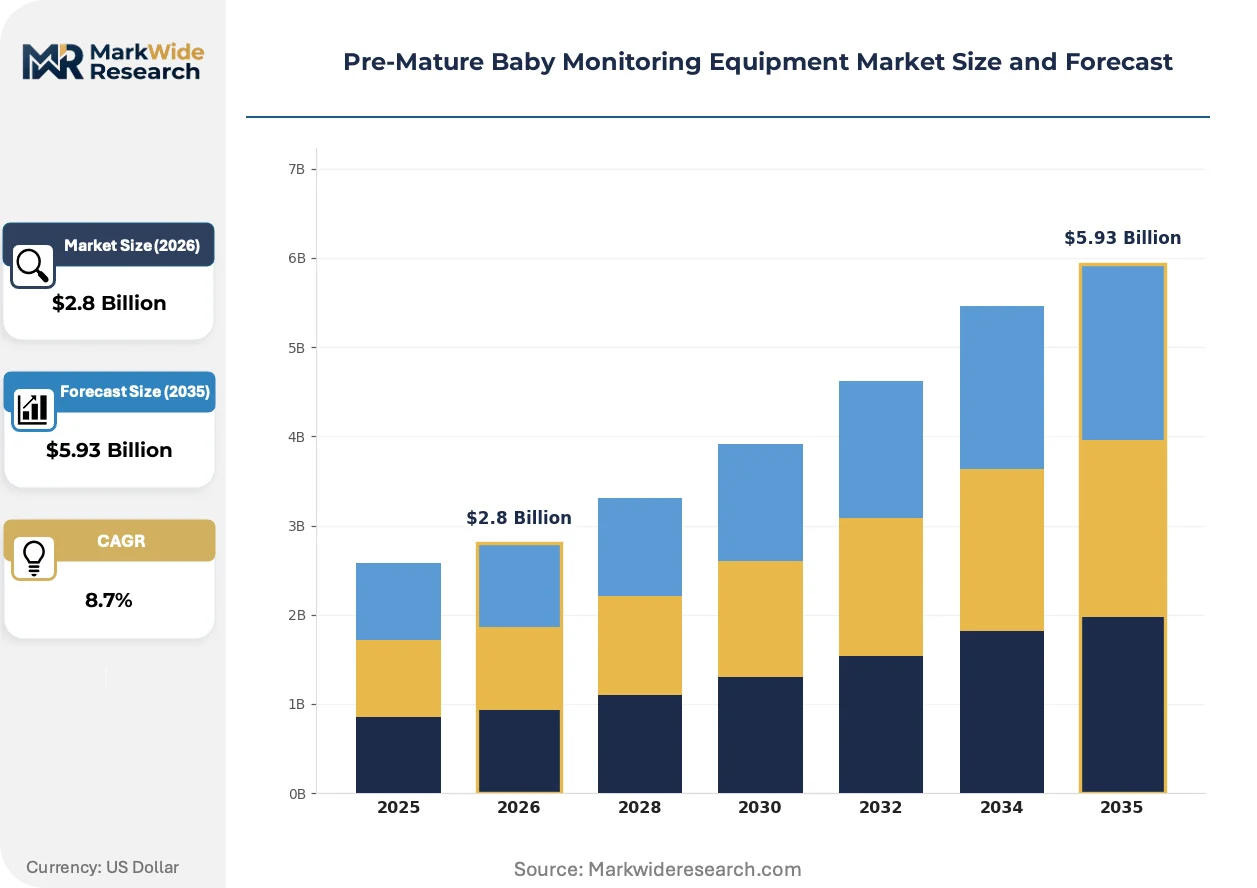
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.93 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cardiac Monitors, Temperature Monitors, Pulse Oximeters, Ventilators Technology: Wireless, Wearable, Telemetry, Integrated Systems Application: Neonatal Intensive Care, Home Monitoring, Transport Monitoring, Clinical Trials End User: Hospitals, Clinics, Research Institutions, Home Care Providers |
| Companies Covered | Koninklijke Philips N.V., GE HealthCare, Drägerwerk AG & Co. KGaA, Medtronic, Siemens Healthineers, Masimo Corporation, Natus Medical Incorporated, Fisher & Paykel Healthcare Limited, Shenzhen Mindray Bio-Medical Electronics Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pre-Mature Baby Monitoring Equipment Market Evolving Landscape
Signal extraction algorithms and disposable sensor economics are reshaping competitive positioning in neonatal monitoring, compressing replacement cycles and elevating software differentiation above hardware parity.
Photoplethysmography signal extraction technology is overtaking conventional pulse oximetry in neonatal applications by enabling accurate SpO2 readings during motion artifact and low-perfusion states that compromise standard devices. Level III NICUs in the United States and Germany are adopting these platforms at replacement cycle intervals of eighteen to twenty-four months. The technology is overtaking legacy amplitude-based detection methods by reducing false desaturation alarms that contribute to clinician cognitive load and alarm fatigue.
FDA premarket notification requirements for neonatal-specific indications now mandate controlled clinical studies demonstrating safety in infants below 1,500 grams, a threshold that excludes extrapolation from adult or pediatric data. This regulatory evolution forces manufacturers to maintain dedicated neonatal clinical trial infrastructure rather than relying on predicate device pathways. Device categories incorporating machine learning algorithms face heightened scrutiny under FDA software-as-medical-device guidance, particularly for alarm threshold automation features.
Hospital procurement departments are unbundling sensor consumables from capital equipment contracts, creating separate competitive arenas for disposable electrode and pulse oximetry probe suppliers. This purchasing pattern shift disrupts traditional bundling strategies employed by integrated platform vendors. The unbundling trend is most pronounced in German and Dutch hospital systems where centralized procurement consortia negotiate national framework agreements for consumables independent of monitor hardware.
Pre-Mature Baby Monitoring Equipment Market Segmentation
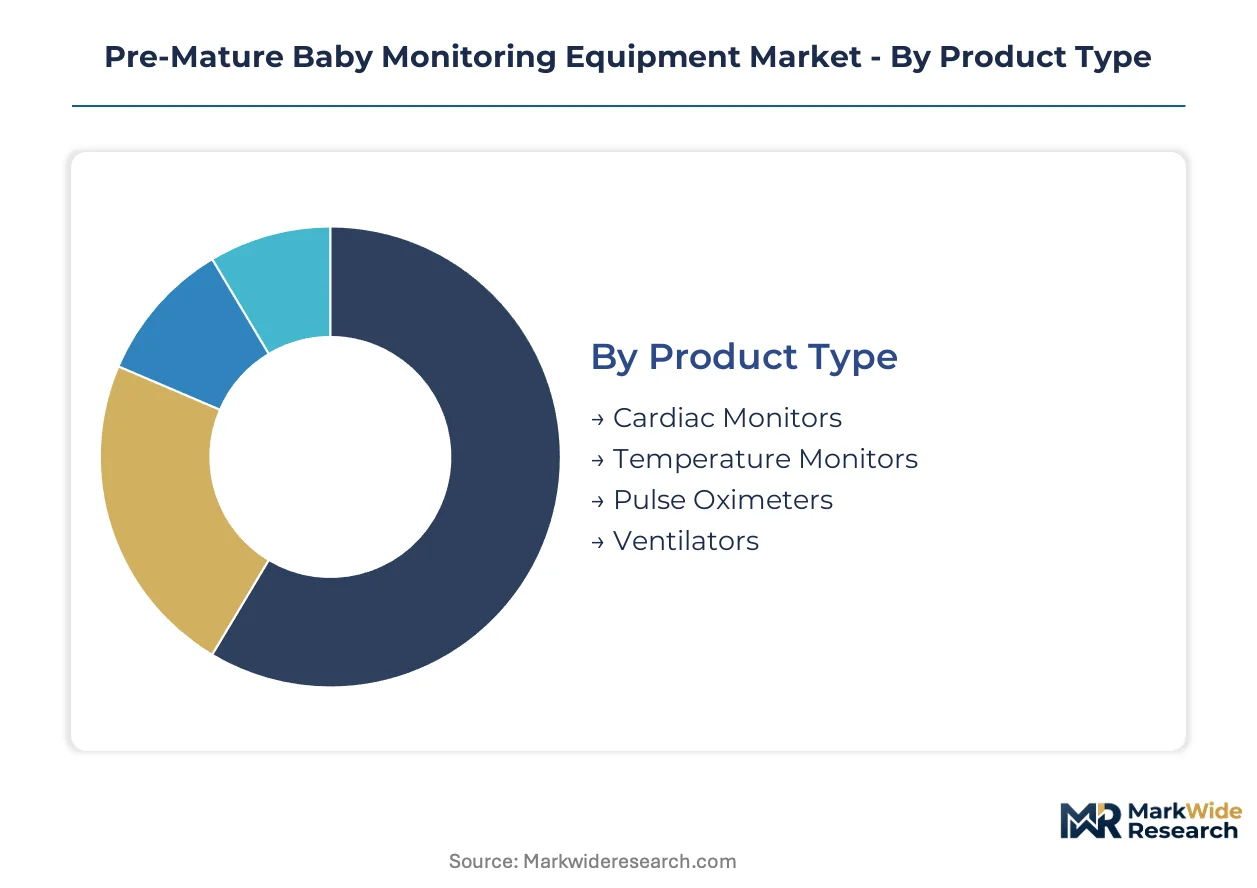
Equipment replacement cycles and technology upgrade timelines vary sharply across product categories in neonatal monitoring. Procurement decisions in tertiary NICUs increasingly favor integrated platforms over standalone devices, reshaping vendor competitive dynamics.
Product Type:
Replacement cycles for core monitoring hardware drive procurement timing across hospital capital budgets, with wireless-enabled upgrades commanding priority allocations.
- Cardiac Monitors:Multi-lead ECG systems with neonatal-specific electrode configurations capture electrical activity in infants below 1,500 grams. Demand concentrates in United States Level III NICUs where continuous arrhythmia surveillance is mandatory for extremely low birth weight cohorts. Upgrade cycles compress as hospitals replace legacy hardwired units with wireless telemetry architectures.
- Pulse Oximeters:Photoplethysmography-based SpO2 sensors with proprietary signal extraction algorithms enable accurate readings during motion artifact and low-perfusion states. German tertiary hospitals lead European adoption of disposable probe configurations to reduce cross-contamination risks in multi-patient bays. Procurement unbundling from monitor hardware creates separate competitive arenas for probe suppliers.
- Temperature Monitors:Continuous skin-surface or core temperature tracking systems maintain thermoregulatory stability in incubated neonates. Chinese tertiary hospitals expand installed base amid NICU construction surge.
- Ventilators:Neonatal-specific respiratory support devices with synchronized intermittent mandatory ventilation modes. Drägerwerk anchors European supply through German engineering centers.
Volume placements concentrate in Cardiac Monitors; the faster expansion belongs to Pulse Oximeters.
Technology:
Cost tier differentiation separates capital-intensive integrated platforms from modular wearable additions that retrofit existing bedside configurations.
- Wireless:Low-power Bluetooth and proprietary radio protocols eliminate cable clutter and enable parental kangaroo care without disconnection. North American greenfield NICU construction favors these architectures for installation flexibility.
- Wearable:Flexible electronics and adhesive-free sensor designs reduce skin injury incidence in fragile neonatal dermis. Fastest replacement cycles attract hospital procurement seeking disposable sensor economics.
- Telemetry:Centralized monitoring stations aggregate data from multiple bedside units for remote specialist oversight. Rural hospital networks in the United States deploy these for pediatric intensivist shortage mitigation.
- Integrated Systems:Multi-parameter platforms combining cardiac, respiratory, and temperature surveillance with unified alarm management. Tertiary hospital NICUs in Germany and China sustain procurement volumes for these bundled configurations.
Revenue concentration sits with Integrated Systems; Wearable technology climbs the fastest amid skin safety prioritization.
Application:
Customer type maturity separates established tertiary care settings from emerging distributed care models that extend monitoring beyond traditional hospital walls.
- Neonatal Intensive Care:Continuous multi-parameter surveillance in Level II and Level III NICU environments for infants below 37 weeks gestational age. United States academic medical centers drive specification standards that cascade to community hospital upgrades.
- Home Monitoring:Discharged pre-term infant surveillance for apnea and bradycardia detection in domestic settings. FDA premarket notification requirements for home-use indications create regulatory barriers that slow commercialization timelines.
- Transport Monitoring:Portable devices for inter-facility neonatal transfer and ambulance-based stabilization. Compact battery-powered designs prioritize electromagnetic compatibility certification for aviation medical evacuation.
- Clinical Trials:Validated monitoring equipment for pharmaceutical studies in neonatal populations. ISO 14155 compliance and FDA IDE pathways shape device selection for contract research organizations.
Procedure volume concentrates in Neonatal Intensive Care; Home Monitoring gains share fastest as early discharge protocols expand.
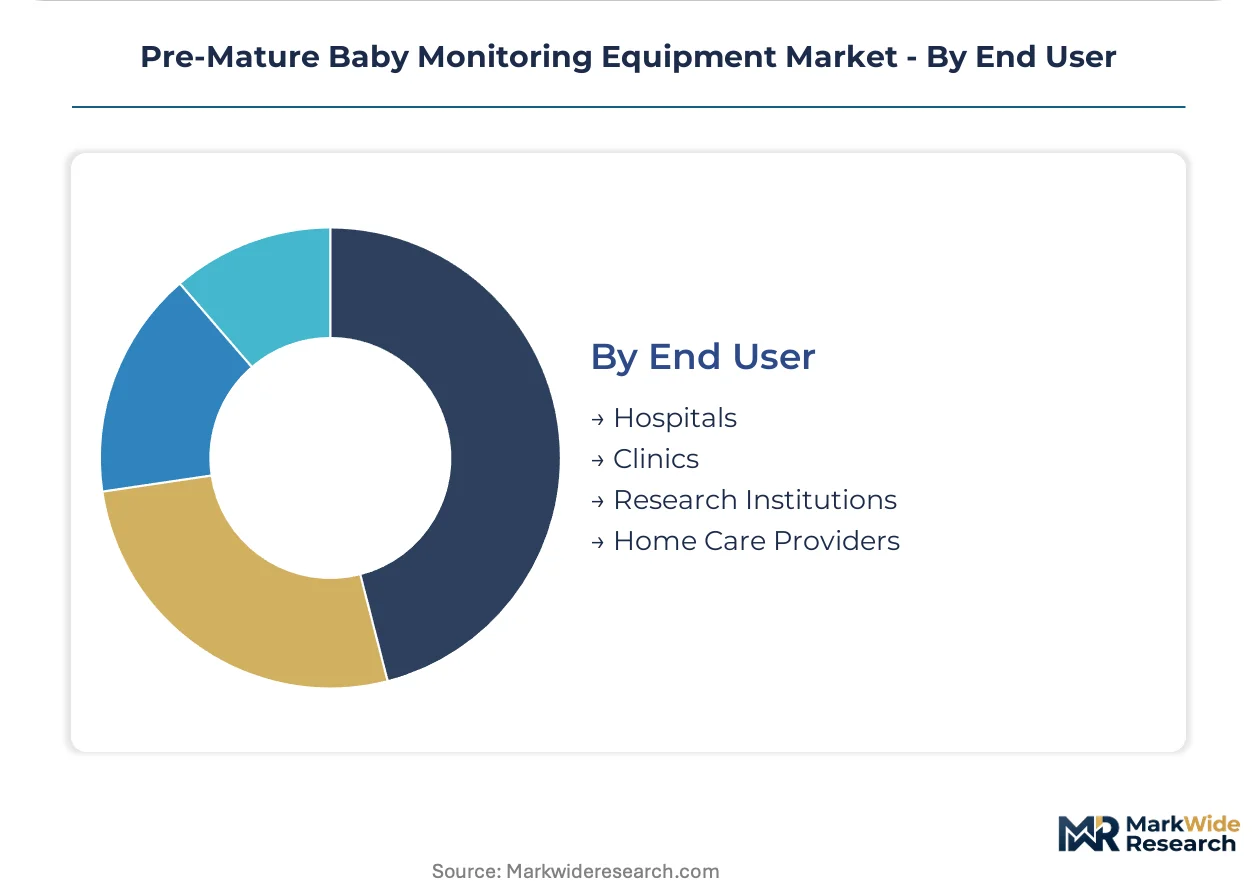
End User:
Supply concentration in tertiary hospital procurement departments determines pricing leverage and vendor relationship structures across buyer segments.
- Hospitals:Tertiary and community hospital NICUs with dedicated neonatology departments and 24-hour intensivist coverage. Centralized procurement consortia in German and Dutch systems negotiate national framework agreements.
- Clinics:Outpatient pediatric facilities and Level I nursery settings with limited critical care capabilities. Lower acuity patient mix drives demand for simplified monitoring configurations.
- Research Institutions:Academic medical centers and contract research organizations conducting neonatal physiology studies. Specialized calibration requirements exceed standard clinical specifications.
- Home Care Providers:Durable medical equipment suppliers and visiting nurse services supporting discharged pre-term infant monitoring. Reimbursement coding complexity constrains market development.
Capital deployment concentrates in Hospitals; Research Institutions expand procurement most quickly amid clinical trial infrastructure investment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicon wafer fabrication clusters in Taiwan and South Korea supply sensor substrates for photoplethysmography modules. Raw material proximity to East Asian contract manufacturers concentrates pulse oximetry probe assembly in Shenzhen and Suzhou industrial zones. Finished device distribution radiates from these hubs toward tertiary hospital networks in North America and Western Europe.
United States
Level III NICU construction in academic medical centers drives integrated monitoring platform procurement. FDA premarket notification requirements for neonatal-specific indications mandate controlled clinical studies in infants below 1,500 grams. Boston and Philadelphia hospital clusters set specification standards that cascade to community hospital upgrade cycles.
Germany
Centralized procurement consortia negotiate national framework agreements for disposable sensor consumables independent of monitor hardware. EU MDR Class IIb conformity pathways accelerate clinical evidence investment for ventilator and cardiac monitor manufacturers. Engineering centers in Lübeck and Telfs anchor European respiratory device supply chains.
China
NICU construction surges in tertiary hospitals across provincial capitals sustain temperature monitor and integrated system volumes. NMPA regulatory harmonization with ISO 80601 standards streamlines domestic device approval timelines. Shenzhen and Suzhou manufacturing clusters pulse oximetry sensors for export to European and North American hospital networks.
India
CDSCO regulatory alignment with ISO standards lowers import barriers for CE-marked devices in emerging perinatal hubs. Public health infrastructure investment in Maharashtra and Karnataka expands tertiary NICU capacity. Delhi and Mumbai hospital procurement departments negotiate direct vendor relationships bypassing traditional distributor networks.
Japan
METI sustainable healthcare procurement incentives create preference windows for low-power wireless monitoring architectures. Pediatric intensivist shortages in rural prefectures drive remote telemetry adoption for centralized specialist oversight. Osaka and Nagoya medical device clusters develop compact transport monitoring configurations for aviation medical evacuation.
Pre-Mature Baby Monitoring Equipment Market Competitive Landscape
Global majors compete with regional champions across integrated platform versus modular device positioning. Market structure tilts toward consolidated vendor relationships in tertiary hospital procurement, though unbundling of sensor consumables creates separate competitive arenas. Three archetypes dominate: diversified health technology conglomerates with imaging-to-monitoring workflows, specialized neonatal device engineering houses, and Asian scale manufacturers with cost-optimized sensor economics. Competitive moves center on strategic partnerships for wireless telemetry integration and portfolio diversification into wearable form factors.
Within the diversified health technology tier, Koninklijke Philips N.V. and GE HealthCare occupy positions spanning imaging and monitoring workflows. Siemens Healthineers exemplifies European engineering-centric positioning. Among specialized neonatal engineering houses, Drägerwerk AG & Co. KGaA represents German respiratory device heritage, while Masimo Corporation anchors proprietary signal extraction technology. Shenzhen Mindray Bio-Medical Electronics Co., Ltd. sits within the Asian scale manufacturing archetype with cost-optimized production capabilities.
| Leading Market Players |
|---|
| Koninklijke Philips N.V. |
| GE HealthCare |
| Drägerwerk AG & Co. KGaA |
| Medtronic |
| Siemens Healthineers |
| Masimo Corporation |
| Natus Medical Incorporated |
| Fisher & Paykel Healthcare Limited |
| Shenzhen Mindray Bio-Medical Electronics Co., Ltd. |
| Others |
Value Network & Pricing Analysis
Procurement unbundling of sensor consumables from capital equipment contracts is forcing Asian contract manufacturers to recalibrate production economics around disposable probe volumes rather than bundled monitor margins. This demand-side restructuring compresses unit economics for integrated platform vendors while elevating price competition among standalone sensor suppliers.
Pricing Analysis
Warranty and service bundling separates premium-tier vendors from economy competitors, with multi-year calibration contracts and field engineering support included in German and United States tertiary hospital agreements. Three-tier pricing structure across premium, standard, and economy levels stratifies by FDA 510(k) clearance status and ISO 80601-2-56 compliance depth. Cost compression in disposable probe segments intensifies because procurement consortia negotiate national framework agreements independent of hardware purchases. Community hospital NICUs exhibit highest price sensitivity; academic medical centers prioritize signal extraction performance over unit cost.
Supply Chain Analysis
Air freight costs for temperature-sensitive photoplethysmography modules from Shenzhen and Suzhou manufacturing clusters add fifteen to twenty percent landed cost premiums for European and North American distributors. Silicon wafer fabrication draws from Taiwan and South Korea; flexible substrate lamination rests on Japanese materials science capabilities; final probe assembly concentrates in China's Pearl River Delta. Single-source vulnerability in East Asian pulse oximetry sensor production creates exposure to customs processing delays and export license fluctuations. Distribution runs through authorized medical device distributors with cold-chain capabilities for sensor preservation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Wireless telemetry architectures are displacing hardwired bedside configurations, creating a technology-transition window where firmware and signal processing capabilities determine competitive survival more than legacy hardware installed base.
For Market Incumbents: To counter unbundling pressure from centralized procurement consortia, deepen captive production of photoplethysmography sensor substrates through backward integration into Taiwanese silicon wafer partnerships. Anchor hospital relationships via exclusive telemetry integration contracts that lock in replacement cycle continuity across wireless platform upgrades. For New Entrants and Emerging Players: Rural United States hospital networks with pediatric intensivist shortages represent the most penetrable buyer archetype for cloud-native remote monitoring platforms with subscription-based telemetry pricing. Target Indian tertiary NICU construction in Maharashtra and Karnataka where CDSCO regulatory harmonization lowers import barriers for CE-marked devices. Lead with disposable wearable sensor economics that bypass capital equipment procurement committees entirely. For Investors and Strategic Acquirers: The window for entry favors specialized neonatal signal processing engineering houses with proprietary low-perfusion algorithms and existing FDA clinical trial infrastructure. Long-term viability hinges on software-as-medical-device regulatory navigation capabilities rather than hardware manufacturing scale. Watch for FDA software guidance enforcement actions against machine learning alarm automation as the inflection signal for compliance-cost barriers rising.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Submission for Neonatal-Specific Indications | Premarket notification pathways for infants below 1,500 grams exclude predicate device reliance, forcing dedicated clinical infrastructure. |
| CE Marking Pathway under EU MDR Class IIb | Conformity assessment for ventilator and cardiac monitor manufacturers demands higher-grade clinical evidence packages than legacy MDD requirements. |
| Hospital System Partnership for Wireless Telemetry | Greenfield NICU construction in Boston and Philadelphia academic medical centers sets specification standards cascading to community upgrades. |
| Software Companion Development for Alarm Fatigue Mitigation | ISO 80601-2-56 compliance for false-alert suppression algorithms differentiates platforms in German centralized procurement evaluations. |
| Reimbursement Strategy for Home Monitoring Indications | FDA premarket notification requirements for domestic apnea and bradycardia detection create regulatory barriers that slow commercialization timelines. |
Research Methodology
Document review covered FDA 510(k) databases, EU MDR notified body certificates, and hospital procurement records from German and Dutch centralized consortia, complemented by interviews with neonatology department heads, biomedical engineering directors, GPO contracts managers, and pulse oximetry sensor manufacturing executives. Secondary validation drew from ISO 80601-2-56 technical committee documentation, NMPA registration filings, and CDSCO import license records. Bottom-up unit placement estimates triangulated against top-down tertiary NICU capital expenditure surveys.
Historical replacement cycle patterns cross-referenced against panel input from hospital procurement committees and contract manufacturer capacity planners shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, wireless versus hardwired architecture, Level II versus Level III NICU application, and regional regulatory cluster. CAGRs derived from weighted average of equipment replacement intervals and technology upgrade adoption curves. Neonatal signal processing patent filings and FDA software guidance enforcement trends informed trajectory inflection assumptions.
Revisions become necessary when EU MDR notified body capacity constraints extend approval timelines, when East Asian export controls disrupt sensor substrate supply, or when Medicare reimbursement coding shifts alter home monitoring economics. Forecasts reflect documented assumptions about regulatory harmonization progress and procurement unbundling velocity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Patient Monitoring
Epro, E-Patient Diaries and Ecoa Market
Patient Monitoring
Holter Monitor Market
Patient Monitoring
Asthma Monitoring Devices Market
Patient Monitoring
Compartment Syndrome Monitoring Devices Market
Patient Monitoring
Neonatal and Fetal Monitors Market
Patient Monitoring
Respiratory Monitoring Devices Market
Patient Monitoring
Multiparameter Patient Monitoring System Market
Patient Monitoring
Germany Patient Monitoring Market
Patient Monitoring
Remote Patient Monitoring Devices Market
Patient Monitoring
Real-Time Location System (RTLS) in Healthcare Market
Patient Monitoring
Multi-Parameter Patient Monitoring Market
Patient Monitoring
Cerebral Oximetry Monitoring Market
Patient Monitoring
South America Patient Monitoring Market
Patient Monitoring
Global Bed Monitoring System and Baby Monitoring System Market
Patient Monitoring
Multi-Item Patient Monitor Market
Patient Monitoring
Asia-Pacific Hemodynamic Monitoring Market