
 United Kingdom Neonatal and Prenatal Devices Market | 2026-2036
United Kingdom Neonatal and Prenatal Devices Market Size, Share, and Industry Trends Forecast 2026-2036
United Kingdom Neonatal and Prenatal Devices Market Analytics
Ireland's medtech manufacturing corridor is rewriting supply dynamics for UK-bound neonatal equipment. GE Healthcare leverages its Belfast-based respiratory device assembly to sustain just-in-time delivery across NHS trusts. Philips Healthcare anchors its prenatal ultrasound presence through Cambridge R&D partnerships with university hospitals. Drägerwerk competes on thermal regulation technology, specializing in incubator platforms that meet updated MHRA electromagnetic compatibility standards.
Neonatal and prenatal devices comprise engineered systems for fetal assessment, newborn resuscitation, thermoregulation, and physiological monitoring, typically operating within precision ranges such as incubator air temperature control to 0.5°C accuracy and pulse oximetry at 70-100% SpO2 measurement bands. These devices serve the clinical imperative of reducing neonatal mortality and morbidity through early intervention and continuous surveillance. Incubators and phototherapy devices capture the largest installed base, while ventilators and monitors command premium pricing due to integrated software analytics and remote telemetry capabilities. Hospitals dominate end-user procurement volumes, though homecare segments are gaining traction as NHS England expands transitional care programmes for preterm infants.
MHRA enforces UKCA marking and post-market vigilance under the UK Medical Devices Regulations 2002, as amended, while NHS Supply Chain coordinates centralised tendering that shapes vendor access and pricing transparency. The Care Quality Commission inspects neonatal unit compliance with National Institute for Health and Care Excellence guidelines on thermoregulation and respiratory support protocols. Stakeholders must monitor how the UK's divergence from EU MDR timelines affects mutual recognition agreements and component sourcing from continental suppliers.
Market Dynamics
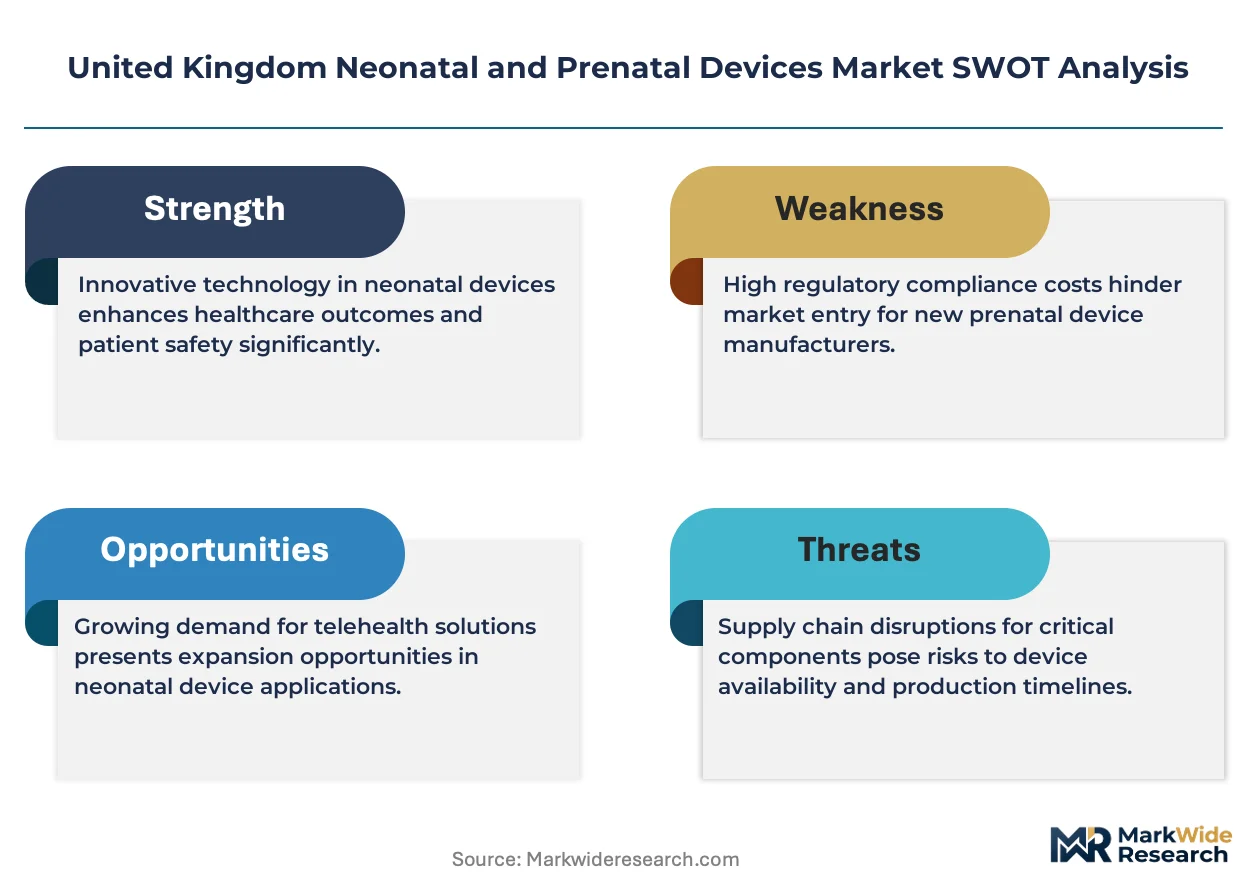
NHS England's regional neonatal network consolidation is compressing vendor access points while MHRA's tightened post-market surveillance for Class IIb and III devices is extending product validation timelines.
Growth Catalysts
- Integrated monitoring systems:NHS maternity units are expanding procurement of platforms combining respiratory, cardiac, and thermoregulatory surveillance into unified dashboards. Tertiary centres drive this refresh cycle.
- UK Medical Devices Regulations 2002:Amended post-market vigilance requirements create compliance barriers that favour established suppliers with robust quality management systems.
- Transitional care programmes:NHS England's expansion of home-based monitoring for preterm infants is opening ambulatory channels for portable pulse oximetry and feeding support devices.
Market Restraints
- Component sourcing concentration:Electromagnetic compatibility-certified sensors and heating elements concentrate among continental European suppliers, exposing UK assemblers to customs friction.
- UKCA marking divergence:Mutual recognition gaps with EU MDR timelines force dual certification runs, inflating regulatory overhead for manufacturers serving both markets.
- Specialised polymer supply:Medical-grade polycarbonate for incubator housings faces price volatility tied to petrochemical feedstock fluctuations.
Strategic Opportunities
- Scotland's neonatal transport network:Underpenetrated demand for portable ventilators and thermal regulation units serving remote maternity units across the Highlands and Islands.
- AI-enabled predictive analytics:Convergence of machine learning with continuous cardiorespiratory monitoring enables early deterioration alerts before clinical decompensation.
- Remote telemetry reimbursement:NHS tariff reforms are creating payment pathways for home-based physiological monitoring, shifting device economics toward subscription models.
Industry Challenges
- Clinical engineering workforce:Biomedical technician shortages across NHS trusts extend equipment downtime and compress preventive maintenance schedules.
- Legacy system integration:New monitoring platforms face interoperability barriers with existing electronic patient record architectures, delaying ward deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Kingdom Neonatal and Prenatal Devices Market |
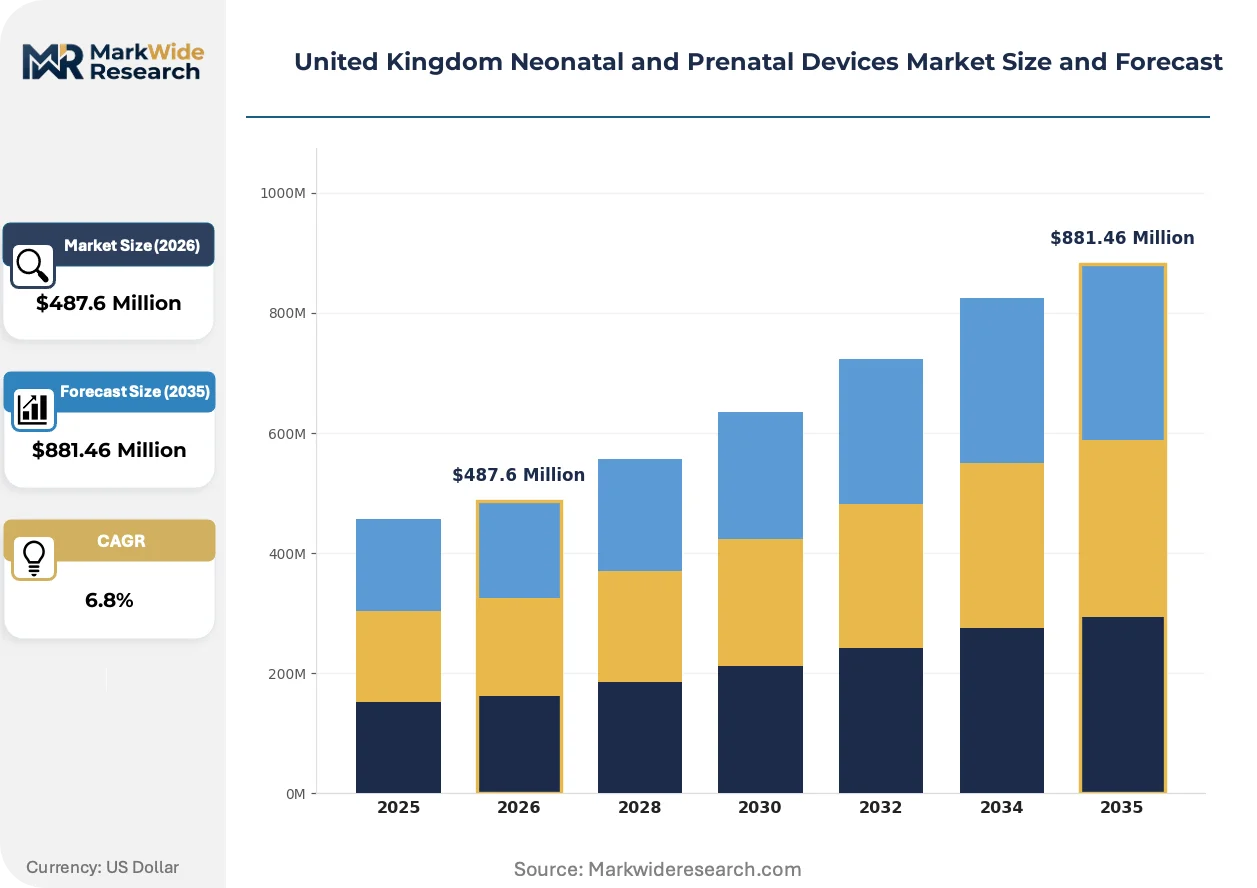
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $881.46 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: Incubators, Phototherapy Devices, Ventilators, Monitors End User: Hospitals, Clinics, Homecare, Research Institutions Technology: Continuous Positive Airway Pressure, Thermal Regulation, Oxygen Delivery, Cardiac Monitoring Application: Preterm Care, Respiratory Support, Neonatal Surgery, Diagnostics |
| Companies Covered | GE Healthcare, Getinge, Philips Healthcare, Medtronic, Drägerwerk, Masimo Corporation, Natus Medical, Cardinal Health, Fisher & Paykel Healthcare, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Kingdom Neonatal and Prenatal Devices Market Evolving Landscape
Wireless sensor networks and edge computing architectures are displacing wired bedside configurations, while regulatory divergence is fragmenting certification pathways across UK-EU supply chains.
Non-invasive cerebral oximetry using near-infrared spectroscopy is penetrating tertiary neonatal intensive care units for real-time brain oxygenation monitoring. Oxford and Cambridge university hospitals pilot these systems for hypoxic-ischaemic encephalopathy management. Conventional intermittent blood sampling for lactate and base excess is rendering obsolete as continuous metabolic monitoring achieves validation.
MHRA's electromagnetic compatibility standards for incubators and radiant warmers entered force with stricter emission limits than predecessor CE frameworks. Manufacturers must redesign heating element shielding and control module architectures. Thermal regulation device categories face the steepest retooling costs and longest re-certification queues.
Consolidated procurement through NHS Supply Chain's national frameworks is displacing trust-level tendering, concentrating purchasing power among fewer authorised suppliers. Regional neonatal networks now mandate standardised equipment platforms across constituent units to simplify training and interoperability. England's tertiary centre clusters exhibit this pattern most acutely, with Scotland and Wales trailing by approximately two contract cycles.
United Kingdom Neonatal and Prenatal Devices Market Segmentation
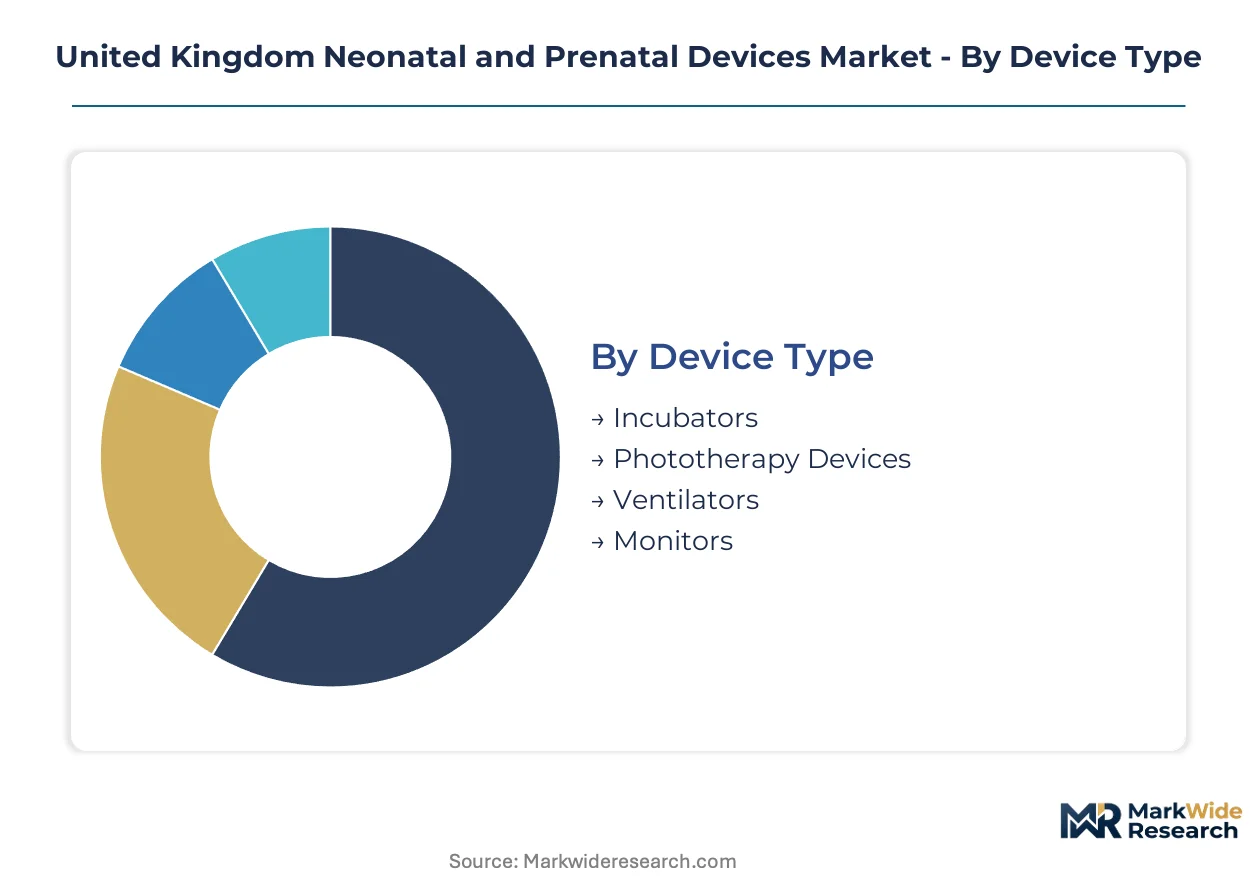
Segmentation reveals how procurement concentrates around high-acuity tertiary centres while technology choices diverge between capital-intensive hospital platforms and emerging ambulatory formats. Understanding these splits illuminates where NHS tariff reforms and MHRA compliance burdens reshape vendor economics.
Device Type:
Cost tier differentiation separates capital equipment with extended depreciation schedules from consumable-heavy platforms with recurring revenue streams.
- Incubators:Precision thermal regulation systems maintaining 0.5°C accuracy through servo-controlled heating elements and humidity management. NHS England's tertiary neonatal networks in London, Birmingham and Manchester drive replacement cycles as MHRA electromagnetic compatibility standards force hardware redesigns.
- Phototherapy Devices:LED-based bilirubin reduction systems with spectral output calibrated to 450-470nm wavelengths for optimal unconjugated bilirubin breakdown. England's regional neonatal networks standardise procurement across constituent units, compressing vendor access to national framework agreements.
- Ventilators:Neonatal-specific respiratory support with tidal volumes calibrated to 2-20ml range.
- Monitors:Multi-parameter platforms integrating pulse oximetry, cardiorespiratory and temperature surveillance.
Incubators command the established base. The steepest expansion runs through ventilators as non-invasive support protocols displace intubation.
End User:
Customer type determines purchasing authority, with centralised NHS frameworks diverging sharply from direct-to-consumer channels.
- Hospitals:Tertiary neonatal intensive care units and district general maternity units operating Level 1-3 care pathways. England's 13 regional neonatal networks consolidate procurement through NHS Supply Chain, mandating interoperable platforms across constituent trusts.
- Homecare:Transitional care programmes for preterm infants discharged with portable monitoring and feeding support. NHS England's expanding ambulatory reimbursement tariffs create subscription revenue models for pulse oximetry and apnea monitoring devices.
- Clinics:Community midwifery hubs and private maternity facilities.
- Research Institutions:University hospitals piloting novel monitoring modalities.
Hospitals retain volume concentration. Homecare gains share fastest as transitional care pathways extend monitoring beyond ward boundaries.
Technology:
Maturity curves separate established modalities with extensive clinical validation from emerging platforms requiring evidence generation for NICE appraisal.
- Thermal Regulation:Servo-controlled incubator and radiant warmer systems with skin-probe feedback loops maintaining neutral thermal environment. MHRA's updated electromagnetic compatibility standards impose shielding redesigns that extend recertification timelines for heating element architectures.
- Continuous Positive Airway Pressure:Non-invasive respiratory support delivering heated, humidified gas via nasal prongs or masks. Scotland's neonatal transport network generates underpenetrated demand for portable CPAP units serving remote Highlands and Islands maternity units.
- Oxygen Delivery:Blender systems and high-flow nasal cannula configurations.
- Cardiac Monitoring:ECG and impedance-based cardiorespiratory surveillance.
Thermal regulation holds the installed base. Continuous positive airway pressure climbs the fastest as non-invasive protocols expand across gestational age thresholds.
Application:
Clinical acuity stratifies equipment specifications, with life-support functions commanding premium pricing against diagnostic or stabilisation roles.
- Preterm Care:Integrated management of thermoregulation, nutrition and developmental support for infants below 37 weeks gestation. England's regional network consolidation concentrates extremely preterm deliveries in tertiary centres, driving capital equipment refresh cycles.
- Respiratory Support:Ventilation, oxygenation and surfactant administration for respiratory distress syndrome. NICE guideline updates on caffeine therapy and non-invasive support protocols reshape device utilisation patterns across NHS trusts.
- Neonatal Surgery:Perioperative monitoring and thermal management.
- Diagnostics:Imaging, laboratory and point-of-care testing platforms.
Preterm care anchors procurement volumes. Respiratory support shows the steepest trajectory as early intervention protocols expand to lower gestational thresholds.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Channel Tunnel and North Sea freight corridors sustain just-in-time component flows from continental Europe into UK neonatal device assembly plants. NHS England's regional network consolidation concentrates procurement authority in tertiary centres across England, while devolved administrations in Scotland, Wales and Northern Ireland operate parallel procurement frameworks with distinct technology adoption timelines.
England
England's 13 regional neonatal networks drive capital equipment refresh cycles through NHS Supply Chain centralised tendering. MHRA enforces UKCA marking and post-market vigilance for Class IIb and III devices under amended UK Medical Devices Regulations 2002. London, Birmingham and Manchester tertiary centres consolidate high-dependency care and mandate interoperable monitoring platforms across constituent trusts.
Scotland
Scotland's neonatal transport network generates underpenetrated demand for portable ventilators and thermal regulation units serving remote Highlands and Islands maternity units. NHS Scotland coordinates procurement through National Services Scotland with technology assessment input from the Scottish Health Technologies Group. Edinburgh and Glasgow anchor specialist neonatal surgical services while Aberdeen supports North Sea offshore worker maternity evacuation pathways.
Wales
Wales operates three regional neonatal networks with Cardiff, Swansea and Wrexham hosting Level 3 intensive care units. Welsh Government health technology appraisal processes run parallel to NICE guidance with variable adoption timelines for novel monitoring modalities. South Wales valleys maternity units face equipment refresh backlogs as capital allocation prioritises Cardiff-centric tertiary capacity.
Northern Ireland
Northern Ireland's single neonatal network centres on Belfast's Royal Maternity Hospital with cross-border referral agreements to Dublin maternity units. GE Healthcare's Belfast-based respiratory device assembly sustains just-in-time delivery across NHS trusts and Republic of Ireland hospitals. The all-island supply chain configuration exposes procurement to dual UK-EU regulatory divergence risks post-Brexit.
United Kingdom Neonatal and Prenatal Devices Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying sensors, heating elements and electromagnetic compatibility-certified subassemblies. The vendor base stratifies between diversified medtech conglomerates with full neonatal portfolios and niche thermal regulation or monitoring specialists. Three archetypes dominate: integrated critical care platform vendors, precision thermal regulation specialists, and portable monitoring device innovators. Competitive dynamics centre on strategic partnerships with NHS Supply Chain for national framework inclusion and backward integration into sensor manufacturing to mitigate continental sourcing friction.
Among diversified platform vendors, GE Healthcare and Philips Healthcare exemplify the integrated critical care archetype with broad neonatal portfolios spanning incubators, ventilators and multi-parameter monitors. Drägerwerk occupies a specialist position in thermal regulation technology with servo-controlled incubator platforms. Masimo Corporation represents the monitoring innovation tier with pulse oximetry and cerebral oximetry systems penetrating tertiary units. Getinge, Medtronic and Fisher & Paykel Healthcare sit within the respiratory support segment with distinct positioning across invasive ventilation, non-invasive support and humidification subsystems. Cardinal Health and Natus Medical exemplify the consumables and diagnostic equipment archetypes respectively.
| Leading Market Players |
|---|
| GE Healthcare |
| Getinge |
| Philips Healthcare |
| Medtronic |
| Drägerwerk |
| Masimo Corporation |
| Natus Medical |
| Cardinal Health |
| Fisher & Paykel Healthcare |
| Others |
Value Network & Pricing Analysis
MHRA electromagnetic compatibility recertification backlogs create dual-tier pricing spreads between compliant and non-compliant thermal regulation equipment while reshaping supplier consolidation patterns across UK-EU component corridors. NHS Supply Chain's national framework tendering amplifies this divergence by mandating UKCA-marked platforms that exclude continental assemblers awaiting dual certification completion.
Pricing Analysis
Volume-discount tiering structures separate NHS England's consolidated regional network procurement from trust-level spot purchasing for emergency replacements. Three-tier pricing stratification across premium servo-controlled incubators, standard radiant warmers, and economy phototherapy units reflects MHRA certification status and software analytics bundling. Pricing pressure stems from NHS tariff compression on capital equipment as operational budgets absorb rising energy costs. District general maternity units exhibit highest price sensitivity, while London tertiary centres prioritize interoperability premiums over unit cost.
Supply Chain Analysis
Export-control restrictions on high-precision pulse oximetry sensors and electromagnetic compatibility-certified heating elements limit flows from German and Dutch component specialists into UK assembly plants. Medical-grade polycarbonate for incubator housings draws from Belgian and German petrochemical processors, with servo-control modules resting on Taiwanese semiconductor foundries. Single-source vulnerability concentrates in electromagnetic compatibility testing capacity, where UK notified body queues extend validation timelines. Distribution runs through NHS Supply Chain's centralised warehousing with just-in-time replenishment from Belfast and Cambridge R&D-integrated manufacturing nodes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity emerges as NHS England's transitional care expansion creates ambulatory monitoring niches outside incumbent hospital platform dominance. Home-based pulse oximetry and feeding support devices attract specialist entrants lacking capital equipment manufacturing scale.
For Market Incumbents: Build regulatory compliance moats through captive UKCA certification consulting services bundled with equipment sales. Deepen backward integration into sensor manufacturing to mitigate continental sourcing friction from electromagnetic compatibility component bottlenecks. Acquire Scottish transport network specialists before NHS Scotland consolidates portable ventilator procurement under National Services Scotland frameworks.
For New Entrants and Emerging Players: Pursue AI-enabled predictive analytics modules that integrate with existing GE Healthcare and Philips Healthcare monitoring platforms without full system replacement. Scotland's Highlands and Islands maternity units represent the most penetrable geography, with under-served portable CPAP demand and limited incumbent service presence. Go-to-market through Scottish Health Technologies Group assessment pathways accelerates NHS adoption.
For Investors and Strategic Acquirers: The market sits at a regulatory divergence phase that favors compliance-specialist component suppliers over diversified platform vendors. Five-to-ten-year viability hinges on UK-EU mutual recognition resolution timing. Acquisition targets should exhibit electromagnetic compatibility testing capabilities or Belfast-based manufacturing footprints shielded from customs friction. Watch MHRA notification body capacity expansion announcements as inflection signals for certification timeline normalization.
| Strategic Initiative | Industry Significance |
|---|---|
| UKCA Marking Pathway | Accelerates NHS Supply Chain framework eligibility before EU MDR divergence widens. |
| Hospital System Partnership | Locks in multi-year equipment refresh cycles across England's 13 regional neonatal networks. |
| Software Companion Development | Enables AI-enabled predictive analytics reimbursement under NHS tariff reforms. |
| Backward Integration into Sensors | Reduces electromagnetic compatibility component exposure to continental supply friction. |
| Reimbursement Strategy | Aligns portable monitoring devices with NHS England transitional care programme payment pathways. |
Research Methodology
Initial hypotheses were tested against primary input from neonatal intensive care unit clinicians, NHS Supply Chain procurement managers, biomedical engineering directors, and medical device regulatory consultants, then refined through secondary validation against MHRA device registration databases, NHS England procurement transparency releases, and UK trade customs records. Bottom-up equipment installation counts triangulated with top-down market size estimates from healthcare capital expenditure tracking.
Demand-supply balance framing anchored the analytical framework across the projection horizon, modeling device type, end user channel, technology maturity, and clinical application acuity dimensions. CAGRs derived from installed base replacement cycles weighted by MHRA recertification timeline delays. Forecast inputs incorporated NHS regional network consolidation schedules and Scottish transport network expansion plans.
Sensitivities concentrate around MHRA-EU MDR mutual recognition agreement negotiations and electromagnetic compatibility testing capacity expansion. Forecasts reflect documented assumptions on NHS capital allocation continuity and petrochemical feedstock price stability. Material shifts in UK-EU regulatory divergence timelines or single-source component supply disruptions would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Canada Varicose Vein Treatment Devices Market
Medical Devices
UHD Surgical Display Market
Medical Devices
Parenteral Feeding Devices Market
Medical Devices
Global Medical Tricorder Device Market
Medical Devices
Asia-Pacific Radiotherapy Market
Medical Devices
Vein Illumination Devices Market
Medical Devices
Implantable Cardiac Rhythm Management Device Market
Medical Devices
Veterinary Glucometers Market
Medical Devices
Orthokeratology Lens Market
Medical Devices
Global Veress Needle Market
Medical Devices
Germany Artificial Organs and Bionics Market
Medical Devices
North America Oxygen Concentrators Market
Medical Devices
Indwelling Pleural Catheters Market
Medical Devices
US Prefilled Syringes Market
Medical Devices
Global Endodontic Reparative Cement Market
Medical Devices
Mexico Respiratory Devices Market