
 High Frequency Chest-Wall Oscillation Devices Market | 2026-2036
High Frequency Chest-Wall Oscillation Devices Market Size, Share, and Industry Trends Forecast 2026-2036
High Frequency Chest-Wall Oscillation Devices Market Foresight
Lightweight polymer composites are displacing conventional metal housings in device chassis fabrication, which is rebalancing unit economics toward portable configurations. Electromed leverages vertical integration across compressor assembly and garment manufacturing to sustain margin control. International Biophysics Corporation anchors its position through specialized R&D intensity in oscillation frequency modulation. Hill-Rom competes on brand strength and channel control within hospital procurement networks.
High frequency chest-wall oscillation devices apply rapid mechanical percussion to the thorax through inflatable garments, typically operating at frequencies between 5 and 25 Hz with calibrated pressure cycling to mobilize airway secretions; their primary purpose is to augment mucus clearance in patients with cystic fibrosis, bronchiectasis, and neuromuscular respiratory compromise. Portable devices lead volume shipments as reimbursement codes increasingly cover domiciliary use, while pneumatic technology dominates the installed base due to its established reliability profile. Home care applications represent the fastest-expanding demand pool as payors redirect post-acute pulmonary rehabilitation from facility-based to residential settings.
The FDA governs these devices as Class II medical products under 510(k) premarket notification pathways, while ISO 13485 quality management standards and IEC 60601 electrical safety requirements shape international market access conditions. The Centers for Medicare & Medicaid Services reimbursement determinations directly influence adoption velocity among homecare providers. Stakeholders must monitor evolving clinical evidence requirements for expanded indications and track competitive positioning across wearable form-factor development.
Market Dynamics
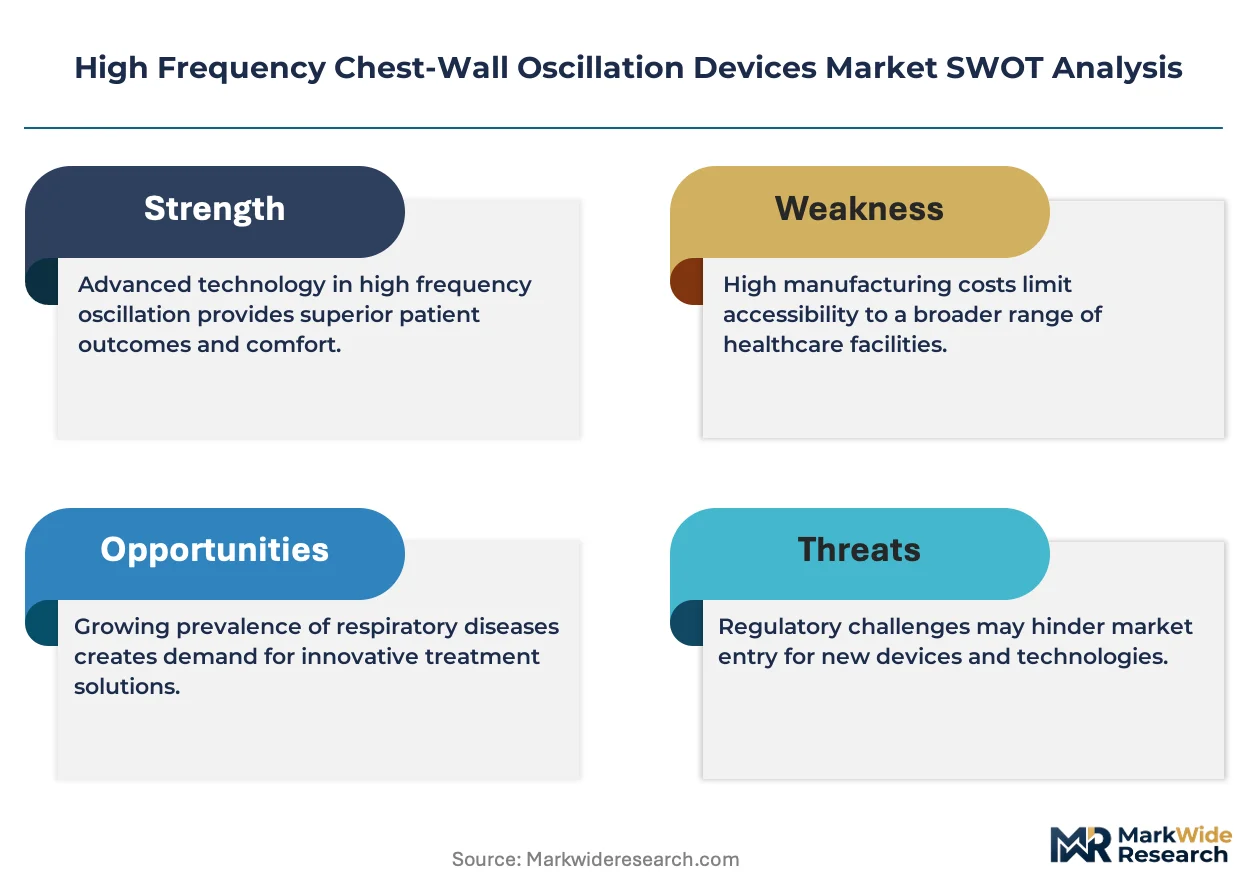
The High Frequency Chest-Wall Oscillation Devices Market is experiencing a structural reorientation as CMS reimbursement codes increasingly favor domiciliary deployment over facility-based respiratory therapy, compressing traditional hospital procurement cycles while accelerating direct-to-patient distribution models.
Growth Catalysts
- CMS Home Health Reimbursement Expansion:Medicare's expanded coverage for durable medical equipment in residential settings is pulling device volumes toward home care providers and reducing patient cost barriers.
- Aging Cystic Fibrosis Population:Extended survival among adult CF patients is creating sustained demand for portable secretion clearance solutions that integrate with active lifestyles.
- Polymer Composite Chassis Technology:Lightweight material substitution is enabling wearable form factors that expand addressable patient populations beyond bedbound users.
Market Restraints
- Compressor Component Supply Concentration:Precision pneumatic subassembly manufacturing clusters in East Asian supplier networks, exposing OEMs to logistics disruption and input cost volatility.
- FDA 510(k) Clinical Evidence Requirements:The premarket notification pathway demands substantial equivalence demonstrations that extend development timelines and compress R&D productivity for novel oscillation modalities.
- Manual Chest Physiotherapy Substitution:Low-cost respiratory therapist services in emerging markets and resource-constrained settings limit device penetration where labor arbitrage favors manual techniques.
Strategic Opportunities
- Neuromuscular Disease Expansion:ALS and muscular dystrophy patient registries in Germany and France represent underpenetrated cohorts with unmet secretion management needs and favorable reimbursement profiles.
- Remote Patient Monitoring Convergence:Integration of oscillation compliance sensors with telehealth platforms creates subscription revenue streams and strengthens payor value demonstration.
- India CDSCO Medical Device Rules:Streamlined import licensing and local manufacturing incentives under the 2017 Medical Device Rules are lowering market entry barriers for cost-optimized device configurations.
Industry Challenges
- Biomedical Engineering Talent Scarcity:Specialized expertise in pneumatic system miniaturization and respiratory biomechanics concentrates in established medical device hubs, constraining R&D scaling for mid-cap entrants.
- ISO 13485 Certification Timeline Compression:Accelerated audit backlogs at notified bodies are extending quality management system validation cycles and delaying commercial launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High Frequency Chest-Wall Oscillation Devices Market |
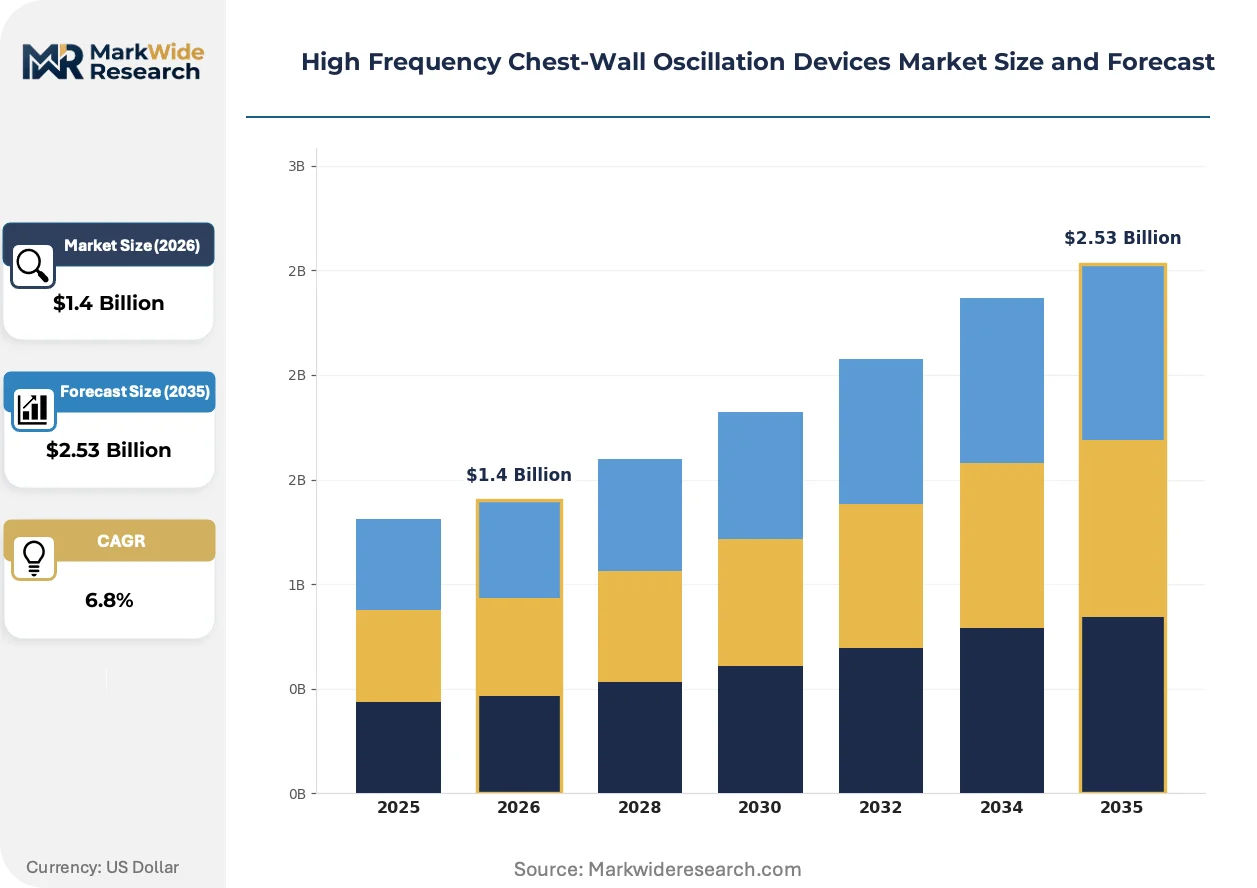
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.53 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Devices, Stationary Devices, Accessories, Therapy Systems Application: Pulmonary Therapy, Acute Care, Rehabilitation, Home Care End User: Hospitals, Clinics, Homecare Providers, Rehabilitation Centers Technology: Vibrating Technology, Pneumatic Technology, Electronic Technology, Manual Therapy |
| Companies Covered | Electromed, International Biophysics Corporation, Hill-Rom, Respiratory Technologies, RespirTech, Monaghan Medical Corporation, DJO Global, Med Systems, BMC Medical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High Frequency Chest-Wall Oscillation Devices Market Shifts & Advancements
Active material science breakthroughs and regulatory pathway refinements are compressing product development cycles while expanding the clinical addressable population for mechanical secretion clearance.
Micro-pump pneumatic architectures are replacing conventional compressor-based systems in next-generation portable units. Home care providers are adopting these configurations for pediatric and ambulatory adult populations where device weight and acoustic signature determine compliance. This technology is expanding into previously unreachable patient segments including school-age cystic fibrosis patients requiring daytime therapy administration.
The FDA's evolving approach to powered respiratory device predicates under 510(k) pathways is tightening clinical evidence standards for oscillation frequency claims. Manufacturers must now submit biomechanical secretion clearance validation data that exceeds historical bench-testing requirements. Hospital procurement networks are responding by demanding enhanced clinical dossiers that extend vendor qualification timelines.
Direct-to-patient subscription models are displacing traditional durable medical equipment rental structures in United States domiciliary respiratory care. Specialty pharmacy distributors and respiratory therapy service aggregators are capturing patient relationships that previously flowed through hospital discharge planners. This channel reconfiguration is most visible in Medicare Advantage plan networks where capitated payment structures favor predictable per-member-per-month device provisioning.
High Frequency Chest-Wall Oscillation Devices Market Segmentation
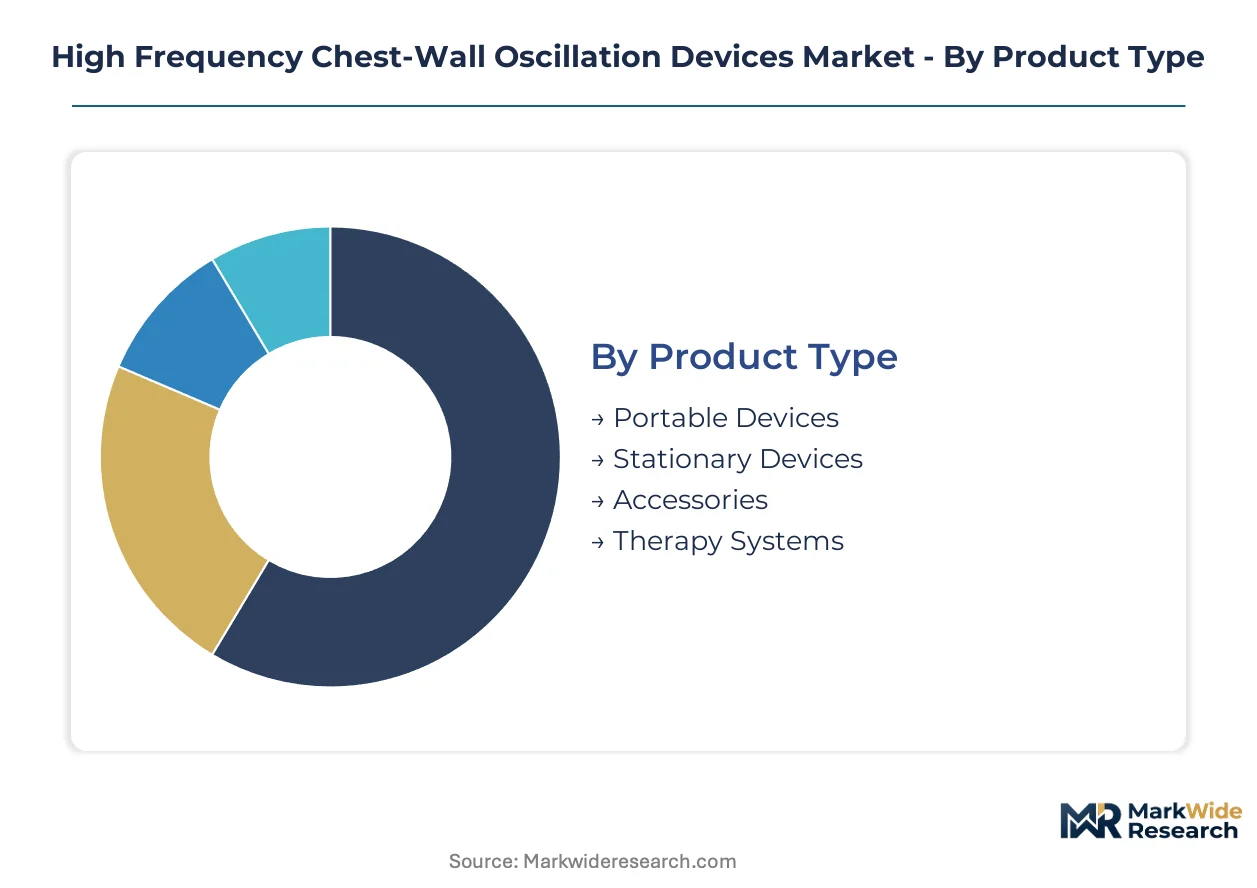
Segmentation in high frequency chest-wall oscillation devices reveals how supply chain configuration and reimbursement pathways shape competitive positioning. Understanding these divisions exposes where technology substitution, channel migration, and margin compression concentrate.
Product Type:
Compressor manufacturing clusters in East Asian supplier networks dictate which form factors OEMs can profitably scale.
- Portable Devices:Lightweight polymer composite chassis house micro-pump pneumatic architectures weighing under 3 kg. Demand concentrates among adult cystic fibrosis patients in the United States seeking daytime therapy administration outside clinical settings; CMS domiciliary reimbursement codes accelerate substitution for stationary units.
- Stationary Devices:Conventional compressor-based systems with metal housings dominate hospital-installed bases. Procurement in Germany and France favors these configurations for ICU secretion management where acoustic signature and weight matter less than continuous duty cycling.
- Accessories:Inflatable garments, hoses, and replacement compressors generate recurring revenue streams.
- Therapy Systems:Integrated platforms combining oscillation hardware with compliance monitoring software.
Today's leader: Stationary Devices. Tomorrow's challenger: Portable Devices.
Application:
Reimbursement pathway divergence separates facility-based from residential revenue pools.
- Home Care:Direct-to-patient distribution models displace durable medical equipment rental structures in United States Medicare Advantage networks. Capitated payment structures favor predictable per-member-per-month device provisioning; remote patient monitoring convergence creates subscription revenue streams.
- Pulmonary Therapy:Standard-of-care secretion clearance for bronchiectasis and COPD exacerbations. Demand clusters in United States pulmonology practices where prior authorization requirements favor established pneumatic technology predicates.
- Acute Care:ICU and emergency department deployment for post-extubation secretion retention.
- Rehabilitation:Post-acute pulmonary rehabilitation in skilled nursing facilities.
Home Care is climbing the fastest as payors redirect respiratory therapy from facility-based to residential settings.
End User:
Channel control determines pricing realization and patient relationship ownership.
- Homecare Providers:Specialty pharmacy distributors and respiratory therapy service aggregators capture patient relationships that previously flowed through hospital discharge planners. United States Medicare Advantage plan networks drive fastest volume expansion.
- Hospitals:IDN procurement networks demand enhanced clinical dossiers extending vendor qualification timelines; Hill-Rom and Electromed compete on brand strength and channel control.
- Clinics:Outpatient pulmonology and CF center prescribing.
- Rehabilitation Centers:Skilled nursing and long-term acute care facilities.
Homecare Providers are gaining share fastest as distribution reconfigures around direct-to-patient models.
Technology:
Pneumatic subsystem reliability and miniaturization capability separate incumbent from insurgent suppliers.
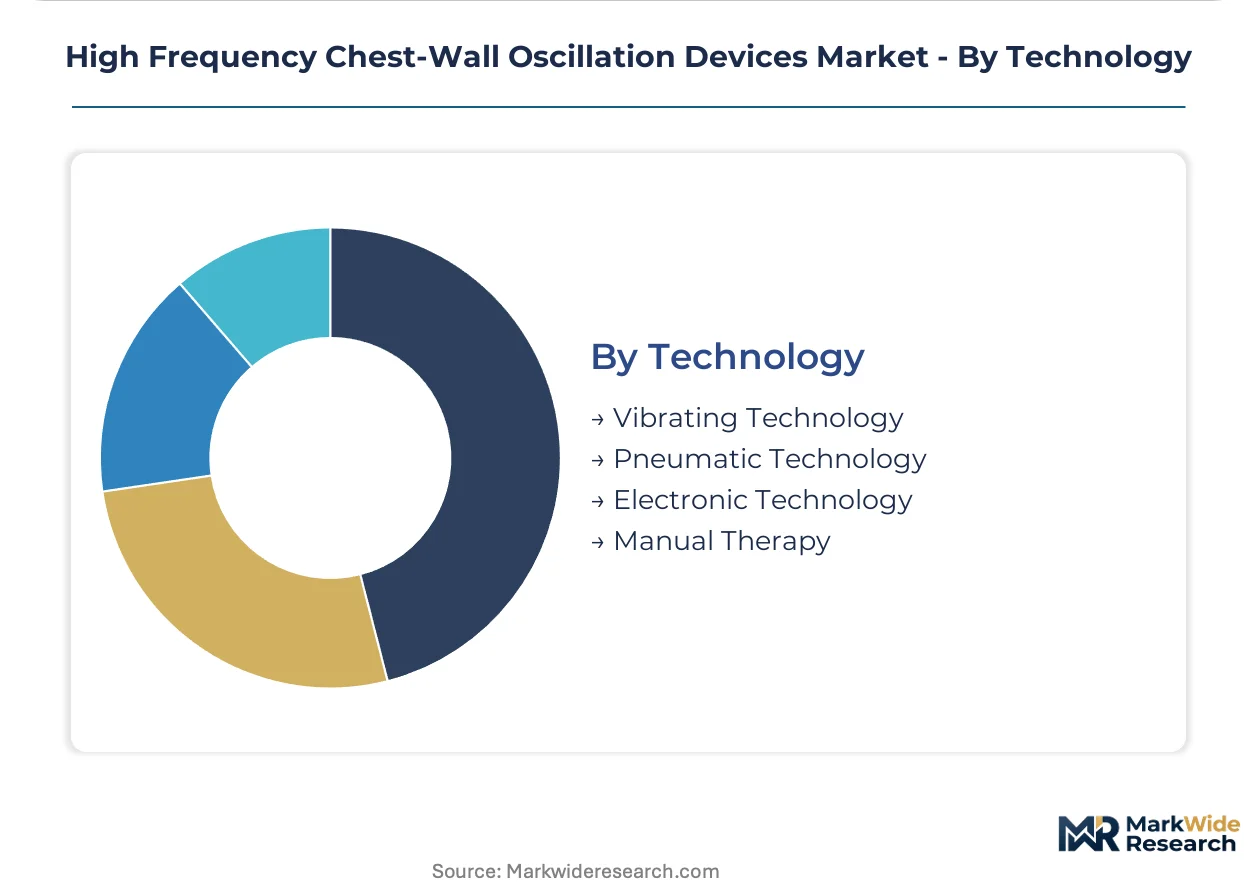
- Pneumatic Technology:Compressor-driven air pulse generation operating at 5-25 Hz with calibrated pressure cycling. Established reliability profile dominates hospital-installed bases; International Biophysics Corporation anchors position through specialized R&D intensity in oscillation frequency modulation.
- Vibrating Technology:Electromechanical oscillation mechanisms enabling wearable form factors. Pediatric and ambulatory adult populations in Germany and France drive adoption where device weight determines compliance.
- Electronic Technology:Software-controlled waveform customization and compliance logging.
- Manual Therapy:Low-cost respiratory therapist services limiting device penetration in emerging markets.
Pneumatic Technology holds current share leadership. Vibrating Technology presents the steepest expansion trajectory for next-generation portable configurations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Minnesota's medical device corridor anchors global production capacity for powered respiratory equipment, with precision pneumatic subassembly manufacturing clustering around Minneapolis-Saint Paul. Supply chain configuration in this sector favors proximity to FDA review centers and CMS policy formulation.
United States
Cystic fibrosis patient registries in Boston and Denver sustain demand for portable secretion clearance solutions. The FDA's 510(k) premarket notification pathway governs device predicates under Class II medical product classification. Minneapolis-Saint Paul hosts compressor assembly operations serving domestic OEMs.
Germany
ALS and muscular dystrophy patient cohorts in Munich and Heidelberg drive neuromuscular disease expansion. The EU Medical Device Regulation (MDR) tightens clinical evidence requirements for oscillation frequency claims. Baden-Württemberg precision engineering clusters supply pneumatic subsystem components.
France
Bronchiectasis prevalence in Paris and Lyon maintains hospital-installed base demand for stationary configurations. ANSM oversees post-market surveillance under MDR implementation timelines. The Grenoble alpine region concentrates polymer composite chassis fabrication for lightweight portable units.
India
Cost-optimized device configurations target emerging market penetration in Delhi and Mumbai. CDSCO Medical Device Rules streamline import licensing under 2017 regulatory reforms. Bengaluru medical technology parks attract contract manufacturing for pneumatic garment assembly.
Japan
Aging COPD demographics in Tokyo and Osaka sustain reimbursement-supported uptake. PMDA reviews powered respiratory devices under pharmaceutical and medical device consolidated frameworks. Nagoya industrial corridors host electromechanical oscillation mechanism production.
High Frequency Chest-Wall Oscillation Devices Market Competitive Landscape
Global majors compete with regional champions across channel control and reimbursement navigation. The vendor base separates into three tiers: integrated respiratory therapy platforms, specialized pneumatic device fabricators, and contract manufacturers supplying inflatable garment assemblies. Two strategic archetypes dominate—vertically integrated OEMs capturing margin through captive compressor production, and focused specialists anchoring position through oscillation frequency R&D intensity. Competitive moves concentrate on direct-to-patient distribution model expansion and remote patient monitoring convergence.
Among US-based respiratory device specialists, Electromed and International Biophysics Corporation occupy distinct positioning archetypes. Electromed exemplifies vertical integration through in-house production of compressor assemblies and pneumatic garments. International Biophysics Corporation represents specialized R&D intensity in oscillation frequency modulation. Hill-Rom, as a broader medical technology platform, anchors hospital procurement network relationships that smaller specialists cannot replicate.
| Leading Market Players |
|---|
| Electromed |
| International Biophysics Corporation |
| Hill-Rom |
| Respiratory Technologies |
| RespirTech |
| Monaghan Medical Corporation |
| DJO Global |
| Med Systems |
| BMC Medical |
| Others |
Supply & Pricing Matrix
Medicare Advantage capitated payment structures are compressing reimbursement rates for durable medical equipment, forcing OEMs to absorb cost volatility from precision pneumatic subassemblies or surrender margin to specialty pharmacy distributors capturing patient relationships.
Pricing Analysis
Polymer composite chassis substitution and micro-pump pneumatic miniaturization are passing through to end-user pricing in portable configurations. Pricing stratifies across premium FDA-cleared predicates, standard 510(k) equivalents, and economy-tier contract manufacturing imports. Cost compression in the economy tier intensifies because CDSCO streamlined licensing invites Indian contract manufacturers into direct competition. Home care providers exhibit highest price sensitivity; hospital IDNs prioritize clinical dossier depth over unit cost.
Supply Chain Analysis
ISO 13485 certification and FDA 510(k) predicate qualification gate supplier entry, concentrating pneumatic subassembly production in the United States, Germany, and Japan. Precision compressor manufacturing draws from East Asian rare-earth magnet supplies and Baden-Württemberg precision machining clusters. Single-source vulnerability concentrates in micro-pump electromechanical components sourced through Nagoya industrial corridors. Distribution runs through specialty pharmacy aggregators and respiratory therapy service networks displacing hospital discharge planners.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where reimbursement compression and FDA evidence escalation favor incumbents with established clinical dossiers and captive manufacturing, particularly as neuromuscular disease expansion demands higher-specification oscillation frequency modulation.
For Market Incumbents: Hedge compressor supply exposure through dual-sourcing agreements with Baden-Württemberg and Minneapolis-Saint Paul precision engineering clusters. Deepen backward integration into polymer composite chassis fabrication to defend margin against Indian contract manufacturing entrants exploiting CDSCO regulatory streamlining. For New Entrants and Emerging Players: Launch via direct-to-patient subscription models in United States Medicare Advantage networks where capitated structures favor per-member-per-month predictability over capital-intensive hospital procurement cycles. Target ALS and muscular dystrophy patient registries in Germany and France as the most penetrable white-space cohort with unmet secretion management needs and favorable reimbursement profiles. For Investors and Strategic Acquirers: Asymmetric upside sits with specialized pneumatic device fabricators possessing ISO 13485 certification and oscillation frequency R&D intensity rather than diversified respiratory platforms. Long-term viability hinges on convergence with remote patient monitoring telemetry and software-controlled waveform customization. The signal to watch is FDA 510(k) clearance velocity for micro-pump architectures as inflection indicator for next-generation portable adoption curves.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission | Premarket notification pathway governs Class II powered respiratory device predicates and oscillation frequency claims. |
| CE Marking Pathway | EU MDR implementation tightens clinical evidence requirements for pneumatic subsystem biocompatibility validation. |
| Hospital System Partnership | IDN procurement networks demand enhanced clinical dossiers extending vendor qualification timelines beyond historical benchmarks. |
| Software Companion Development | Compliance logging and telehealth platform integration create subscription revenue streams strengthening payor value demonstration. |
| Reimbursement Strategy | CMS domiciliary coverage expansion and Medicare Advantage capitation reshape channel economics toward direct-to-patient models. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with biomedical engineers, hospital purchasing committee members, GPO contracts managers, and respiratory therapy service aggregators with secondary validation against FDA 510(k) filings, CMS Medicare reimbursement databases, hospital procurement records, and ISO 13485 certification registries. Bottom-up patient registry analysis and top-down equipment shipment triangulation anchored market sizing.
Comparable historical reference periods spanning pre-pandemic baselines through CMS home health reimbursement expansion informed the projection horizon. The analytical framework modeled segmentation across product type, application, end user, and technology dimensions, with oscillation frequency modulation capability and pneumatic subsystem reliability as industry-specific forecast inputs. CAGRs were derived from patient population epidemiology, reimbursement code velocity, and substitution elasticities between portable and stationary configurations.
Forecast precision tightens around the base case; tail outcomes carry wider variance under FDA 510(k) pathway delays or East Asian logistics disruption scenarios. Forecasts reflect assumptions regarding CMS reimbursement stability and polymer composite cost curves. A model refresh is warranted upon material change in FDA clinical evidence requirements for oscillation frequency claims or CDSCO manufacturing incentive structures.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Muscle Stimulation Devices Market
Medical Devices
Epilepsy Devices Market
Medical Devices
Europe Aligner Sheet Market
Medical Devices
Heel Incision Devices Market
Medical Devices
Global Non-Surgical Aesthetic Devices Market
Medical Devices
Global Cranial and Facial Implants Market
Medical Devices
Breast Prosthesis Market
Medical Devices
Europe 3D Printing in Healthcare Market
Medical Devices
Electroencephalography Devices Market
Medical Devices
Global PC-Based Audiometer Market
Medical Devices
Italy Aesthetic Devices Market
Medical Devices
Bone Anchored Hearing Aids Market
Medical Devices
India Minimally Invasive Surgery Devices Market
Medical Devices
Leadless Pacing Systems Market
Medical Devices
Global Casting Devices Market
Medical Devices
Gum Grafting Market