
 Compartment Syndrome Monitoring Devices Market | 2026-2036
Compartment Syndrome Monitoring Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Compartment Syndrome Monitoring Devices Market Analysis
Software-defined diagnostic features embedded in monitoring platforms is consolidating value around recurring analytics subscriptions rather than one-time hardware sales. RAUMEDIC leverages its European manufacturing footprint to sustain supply chain control across invasive catheter production. MY01, Inc. specializes in disposable sensor technology that competes with reusable legacy systems in cost-sensitive hospital procurement. Millar anchors the premium tier through proprietary microsensor fabrication that differentiates its pressure transducers from commodity alternatives.
Compartment syndrome monitoring devices measure intracompartmental pressure through invasive needle catheters or non-invasive near-infrared spectroscopy to detect tissue ischemia before irreversible muscle necrosis occurs, with typical pressure thresholds triggering intervention at 30 mmHg delta from diastolic pressure. Invasive devices dominate current revenue as the clinical gold standard, while non-invasive devices represent the fastest-expanding segment as hospitals seek to reduce iatrogenic infection risk from repeated needle insertions. Emergency care applications command concentrated demand due to time-critical decision requirements, whereas post-surgery monitoring offers expanding volume as orthopedic procedure volumes rise and automated reporting technology reduces nursing burden.
The FDA's 510(k) clearance requirements for pressure monitoring systems shape product development timelines and clinical validation burdens for US market entry, while the EU Medical Device Regulation mandates post-market surveillance systems that increase compliance costs but strengthen barriers against low-quality competitors. ISO 13485 quality management certification functions as a baseline credential for supplier qualification by major hospital purchasing groups. Stakeholders must weigh the capital efficiency of sensor-as-a-service models against traditional equipment ownership as reimbursement frameworks evolve toward episode-based payment structures.
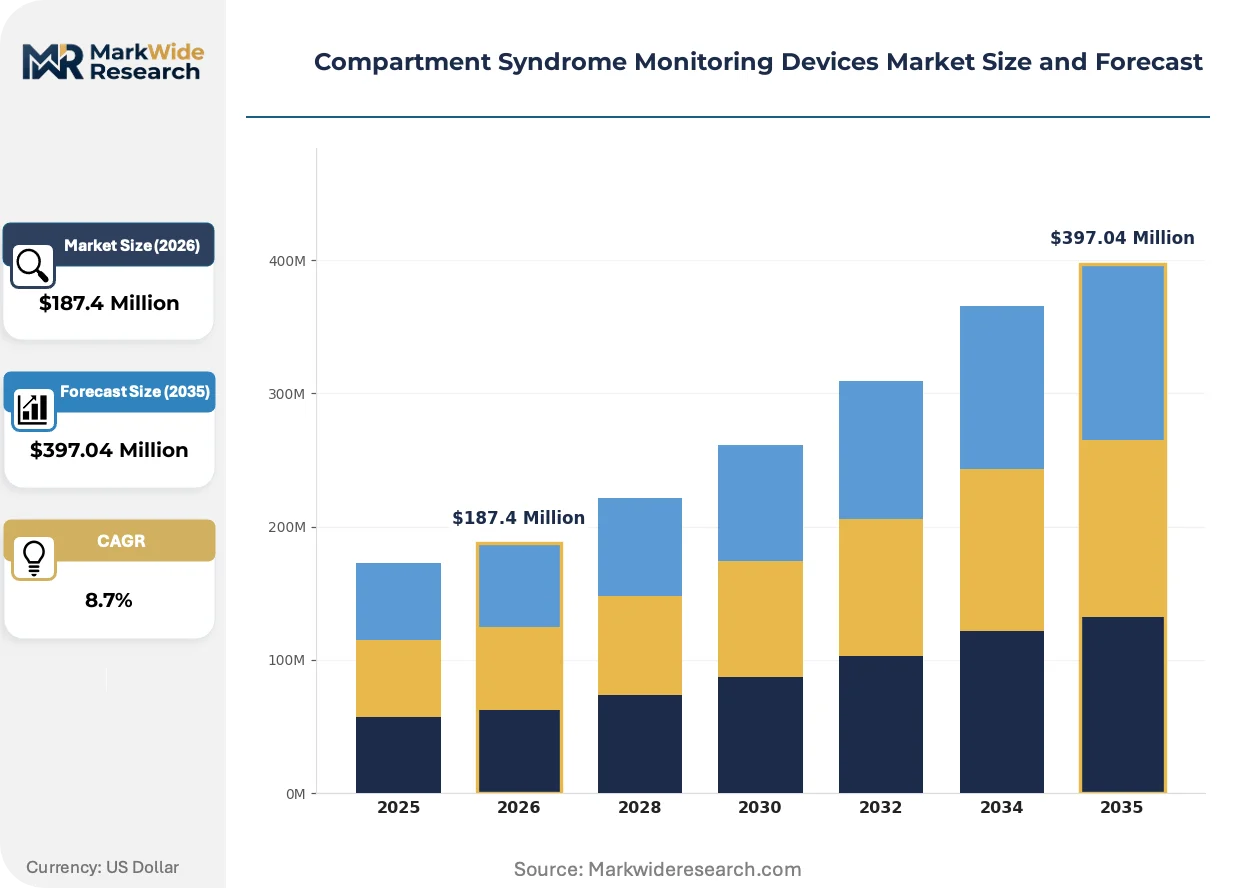
Market Dynamics
Continuous pressure monitoring systems are displacing intermittent manual measurement in trauma centers, consolidating clinical workflow around automated alerts and reducing nursing documentation burden. The shift from reusable to disposable sensor platforms is redistributing value capture toward consumable revenue streams and away from capital equipment sales.
Growth Catalysts
- FDA 510(k) pathway efficiency:The premarket notification framework for Class II medical devices accelerates sensor platform iterations, compressing time-to-market for pressure monitoring innovations.
- Orthopedic procedure volume expansion:Rising surgical caseloads in university hospitals generate recurring demand for post-operative compartment surveillance systems.
- Wireless telemetry integration:Bluetooth-enabled intra-compartmental sensors eliminate tethered connections, enabling patient mobility during extended monitoring protocols.
Market Restraints
- Single-use sensor cost structure:Disposable catheter economics strain procurement budgets in cost-sensitive hospital systems compared to reusable legacy alternatives.
- European supply concentration:Invasive catheter manufacturing clusters in Germany create geographic vulnerability to regional logistics disruptions.
- Non-invasive accuracy limitations:Near-infrared spectroscopy devices face clinical skepticism regarding false-negative rates in deep posterior compartment assessment.
Strategic Opportunities
- Episode-based reimbursement alignment:US Centers for Medicare & Medicaid Services bundled payment models incentivize continuous monitoring to prevent costly fasciotomy revisions.
- Ambulatory surgical center penetration:Outpatient orthopedic facilities represent underdeveloped deployment channels for portable pressure monitoring systems.
- AI-integrated predictive analytics:Machine learning algorithms processing pressure trend data enable pre-emptive intervention before threshold breaches.
Industry Challenges
- ISO 13485 certification timeline:Quality management system audits impose 12-18 month delays for new sensor manufacturers seeking supplier qualification.
- Legacy EMR integration complexity:Proprietary data formats from established monitoring platforms resist seamless connectivity with hospital information systems.
- Specialized biomedical engineering talent:Microsensor fabrication expertise concentrates in limited geographic clusters, constraining R&D expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Compartment Syndrome Monitoring Devices Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Invasive Devices, Non-invasive Devices, Diagnostic Equipment, Monitoring Systems Application: Orthopedics, Sports Medicine, Emergency Care, Post-surgery Monitoring End User: Hospitals, Clinics, Rehabilitation Centers, Emergency Services Technology: Wireless Monitoring, Sensor-based Systems, Automated Reporting, Data Analytics |
| Companies Covered | C2DX, Inc., MY01, Inc., RAUMEDIC, Millar, Medline, Potrero Medical, Becton, Dickinson and Company, Accuryn, Sentinel Medical Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Compartment Syndrome Monitoring Devices Market Emerging Trajectories
Software-defined diagnostic platforms are unbundling hardware from analytics, enabling subscription-based clinical decision support that extends vendor relationships beyond initial equipment deployment. This architectural shift reconfigures competitive advantage around data infrastructure and algorithmic accuracy.
Machine learning algorithms embedded in monitoring platforms are automating pressure trend interpretation, flagging compartment syndrome risk before manual threshold checks. Emergency departments at Level I trauma centers are deploying these systems to compress decision-to-intervention timelines. The technology is automating nursing workflow, reducing documentation burden while capturing reimbursement for continuous monitoring codes.
The EU Medical Device Regulation mandates post-market surveillance systems that increase compliance expenditure but strengthen barriers against low-quality competitors. Manufacturers must maintain clinical evidence registries and periodic safety updates, extending product lifecycle management costs. German university hospitals are prioritizing MDR-certified devices in procurement specifications, creating certification-driven supplier selection.
Hospital purchasing groups are consolidating sensor procurement through group purchasing organizations, compressing vendor margins while standardizing device platforms across health system networks. This concentration shifts negotiation leverage toward aggregated buyers and away from individual facility procurement. The pattern is most visible in US integrated delivery networks seeking interoperability across affiliated trauma centers.
Compartment Syndrome Monitoring Devices Market Segmentation
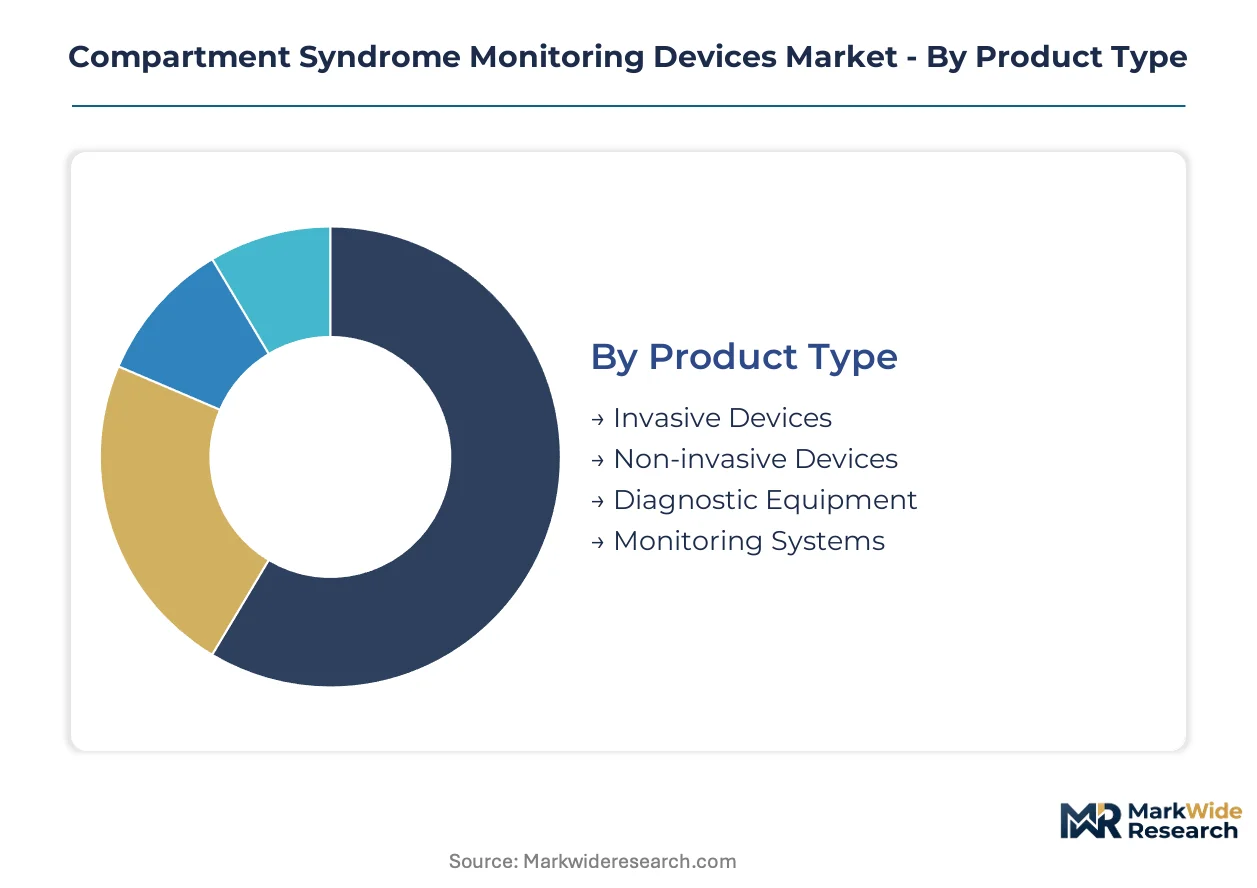
Compartment syndrome monitoring devices fragment across four intersecting dimensions that determine procurement workflows and reimbursement pathways. Product type splits the market between invasive catheters commanding premium pricing and non-invasive alternatives gaining traction in infection-control protocols. Application concentration in emergency care creates distinct volume patterns versus post-surgical surveillance with longer monitoring durations.
Product Type:
Invasive devices capture the revenue premium while non-invasive platforms expand volume fastest through reduced complication risk.
- Invasive Devices:Needle catheters and slit catheters measure intracompartmental pressure directly through tissue penetration, delivering the clinical gold standard accuracy required in Level I trauma centers. Demand concentrates in Germany's university hospital networks where orthopedic surgical volumes sustain high utilization rates.
- Non-invasive Devices:Near-infrared spectroscopy and ultrasound-based systems assess tissue perfusion without tissue penetration, addressing iatrogenic infection concerns in prolonged monitoring scenarios. Adoption is accelerating in US emergency departments seeking to minimize repeated needle insertions in multi-compartment assessments.
- Diagnostic Equipment:Standalone pressure measurement units serve resource-constrained facilities without integrated monitoring infrastructure.
- Monitoring Systems:Platform solutions combining hardware with data management capabilities support enterprise deployment across health system networks.
Mature deployment sits with Invasive Devices. Newer deployment is concentrated in Non-invasive Devices.
Application:
Emergency care generates acute volume spikes while post-surgical monitoring delivers extended revenue duration per patient encounter.
- Emergency Care:Time-critical decision requirements in trauma bays drive demand for continuous pressure monitoring with automated alert thresholds. Deployment concentrates in North American trauma centers expanding 24/7 coverage for high-energy extremity injuries.
- Post-surgery Monitoring:Extended surveillance protocols following orthopedic procedures capture revenue through longer monitoring durations and reduced nursing documentation burden. German hospitals lead adoption of wireless systems enabling patient mobility during recovery.
- Orthopedics:Surgical suites and recovery units require rapid pressure assessment capability integrated with operative workflows.
- Sports Medicine:Athletic training facilities and team physician practices utilize portable monitoring for exertional compartment syndrome evaluation.
Volume concentration rests with Emergency Care. Duration economics favor Post-surgery Monitoring.
End User:
Capital equipment ownership models dominate hospital procurement while service-based arrangements penetrate smaller clinical settings.
- Hospitals:Integrated delivery networks standardize device platforms across trauma centers and orthopedic service lines, consolidating vendor relationships and interoperability requirements. US hospital purchasing groups leverage aggregated volume for price compression.
- Emergency Services:Ambulance and air medical operations require ruggedized portable systems supporting field pressure assessment. German emergency medical services are expanding prehospital deployment of compact monitoring units.
- Clinics:Outpatient orthopedic practices seek cost-effective solutions for post-operative surveillance without inpatient infrastructure.
- Rehabilitation Centers:Extended care facilities utilize monitoring during aggressive physical therapy protocols for high-risk patients.
Technology investment capacity clusters in Hospitals. Service flexibility requirements concentrate in Emergency Services.
Technology:
Hardware commoditization pressures are redirecting competitive advantage toward software-defined analytics and connectivity infrastructure.
- Wireless Monitoring:Bluetooth-enabled intra-compartmental sensors eliminate tethered connections, enabling patient mobility during extended monitoring protocols. FDA 510(k) clearances for wireless platforms are accelerating vendor competition in the US market.
- Data Analytics:Machine learning algorithms processing pressure trend data enable pre-emptive intervention before threshold breaches, capturing subscription revenue beyond initial hardware deployment. German university hospitals prioritize analytics-integrated platforms for research data generation.
- Sensor-based Systems:Microelectromechanical pressure transducers deliver measurement accuracy in miniaturized form factors for invasive applications.
- Automated Reporting:Documentation workflow integration reduces nursing burden while supporting reimbursement capture for continuous monitoring codes.
Recurring revenue potential concentrates in Data Analytics. Regulatory clearance velocity favors Wireless Monitoring.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cologne anchors European manufacturing for invasive catheter systems, while trauma center networks in Baltimore and Houston drive North American deployment of continuous monitoring platforms.
United States
FDA 510(k) clearances for wireless pressure sensors accelerate vendor competition across Level I trauma centers in Baltimore, Houston, and Los Angeles. The Centers for Medicare & Medicaid Services bundled payment models incentivize continuous monitoring adoption to prevent costly fasciotomy revisions. Integrated delivery networks in the Southeast and Midwest standardize device platforms across affiliated hospitals.
Germany
University hospitals in Berlin, Munich, and Heidelberg sustain high utilization rates for invasive catheter systems through orthopedic surgical volumes. The EU Medical Device Regulation mandates post-market surveillance systems that increase compliance costs but strengthen barriers against low-quality competitors. Manufacturing clusters in the Cologne-Bonn corridor concentrate invasive catheter production.
Japan
PMDA regulatory pathways shape clinical validation requirements for pressure monitoring innovations entering Tokyo and Osaka medical centers. METI industrial policy supports precision medical device manufacturing in the Nagoya-Chubu corridor. Aging demographics and rising orthopedic procedure volumes expand post-surgical monitoring demand.
United Kingdom
NHS procurement frameworks standardize compartment syndrome monitoring across London trauma networks and regional major trauma centers. MHRA post-Brexit regulatory autonomy creates parallel clearance pathways distinct from EU MDR processes. Research hospitals in Oxford and Cambridge drive early adoption of AI-integrated predictive analytics platforms.
Canada
Health Canada Class II medical device licensing aligns with FDA precedents, accelerating US-cleared platform entry into Toronto and Vancouver hospital systems. Provincial health authorities in Ontario and British Columbia consolidate purchasing through group procurement organizations. Rural trauma networks in Alberta and Manitoba seek portable monitoring solutions for air medical transport.
Compartment Syndrome Monitoring Devices Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across the compartment syndrome monitoring landscape. The market structure concentrates around established medical device conglomerates with integrated manufacturing footprints and specialized sensor technology firms with focused R&D programs. Three archetypes dominate: diversified hospital supply conglomerates with broad critical care portfolios, European precision catheter manufacturers with captive production, and venture-backed disposable sensor specialists. Competitive moves center on regulatory clearance velocity for wireless platforms and strategic partnerships with integrated delivery networks for enterprise deployment.
Within the specialized sensor tier, MY01 exemplifies the venture-backed disposable technology archetype, while RAUMEDIC represents European manufacturing-anchored supply chain control. Millar occupies a position in the premium microsensor fabrication segment. These three companies illustrate the competitive vectors shaping procurement decisions across university hospital networks and trauma center systems.
| Leading Market Players |
|---|
| C2DX, Inc. |
| MY01, Inc. |
| RAUMEDIC |
| Millar |
| Medline |
| Potrero Medical |
| Becton, Dickinson and Company |
| Accuryn |
| Sentinel Medical Technologies |
| Others |
Supply Flow & Price Mechanics
Wireless telemetry integration in intra-compartmental sensors is simultaneously collapsing hardware margins and consolidating procurement power around consumable revenue streams, as German catheter manufacturers and US disposable specialists compete for hospital system contracts.
Pricing Analysis
Per-procedure throughput pricing anchors hospital procurement decisions, with disposable sensor platforms commanding premium positioning against reusable alternatives through reduced infection liability and nursing workflow efficiency. Price differentiation separates FDA-cleared wireless systems from basic needle-catheter configurations, while ISO 13485 certification tiers further stratify vendor selection. Cost compression in standard invasive catheter tiers is intensifying because group purchasing organizations aggregate volume across integrated delivery networks. Ambulatory surgical centers exhibit highest price sensitivity; Level I trauma centers prioritize clinical performance over unit economics.
Supply Chain Analysis
Microelectromechanical pressure transducer fabrication rests on specialty semiconductor foundries in Germany, Japan, and the United States, with precision polymer catheter extrusion concentrated in the Cologne-Bonn corridor and select Midwest US manufacturing zones. Raw material dependencies include medical-grade stainless steel for needle components, biocompatible polymers for disposable housings, and MEMS-grade silicon wafers for sensor elements. Single-source vulnerability concentrates in European polymer supply for invasive catheter production. Distribution runs through hospital group purchasing organizations and specialized medical device distributors serving trauma center networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Backward integration into MEMS sensor fabrication and forward integration into software analytics subscriptions constitute the primary vertical-integration race, as manufacturers seek to escape hardware commoditization.
For Market Incumbents: Anticipate disposable sensor specialists eroding market position through cost-per-procedure advantages by accelerating wireless platform FDA submissions and locking multi-year contracts with integrated delivery networks. Prioritize captive production of microelectromechanical transducers to defend margin structure against supply chain disruptions. For New Entrants and Emerging Players: Capture ambulatory surgical center deployment channels currently underserved by enterprise-focused monitoring systems, where portable pressure assessment devices face minimal incumbent saturation. Lead with per-procedure rental models that eliminate capital expenditure barriers for outpatient orthopedic facilities. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by diversified critical care conglomerates seeking compartment syndrome monitoring capabilities to complete surgical workflow portfolios. Long-term viability hinges on analytics platform recurring revenue exceeding hardware replacement cycles. Watch FDA clearance velocity for wireless multi-compartment systems as inflection indicator for competitive repositioning.| Strategic Initiative | Industry Significance |
|---|---|
| 510(k) Clearance Acceleration | FDA premarket notification efficiency compresses time-to-market for Bluetooth-enabled sensor platforms competing in US trauma centers. |
| Hospital System Partnership | Integrated delivery network standardization contracts lock multi-facility deployment and interoperability requirements across affiliated trauma centers. |
| Software Companion Development | Machine learning analytics subscriptions extend vendor relationships beyond initial hardware deployment into recurring revenue streams. |
| Reimbursement Strategy | CMS bundled payment alignment captures continuous monitoring codes and prevents costly fasciotomy revision penalties. |
| CE Marking Pathway | EU MDR post-market surveillance compliance strengthens barriers against low-quality competitors in German university hospital procurement. |
Methodological Framework
Document review covered FDA 510(k) clearances, EU MDR technical documentation, hospital procurement databases, and CMS reimbursement schedules, complemented by interviews with trauma surgeons, biomedical engineering directors, GPO contracts managers, and regulatory affairs specialists at sensor manufacturers. Secondary sources included SEC filings for publicly traded device conglomerates, ISO 13485 certification registries, and orthopedic procedure volume data from hospital associations. Bottom-up demand modeling and top-down market sizing triangulated volume estimates across the analysis window.
Segmented projections for invasive catheters, non-invasive devices, monitoring systems, and diagnostic equipment combined with technology splits across wireless, analytics-integrated, and traditional platforms produced volume and value outputs across the modeling period. CAGRs derived from orthopedic surgical volume trajectories, trauma center expansion patterns, and wireless adoption curves in emergency care settings. Pricing assumptions incorporated disposable-versus-reusable economics and subscription revenue migration trends.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to FDA regulatory pathway modifications, EU MDR enforcement intensity, and reimbursement framework shifts toward episode-based payment structures. Forecasts reflect documented assumptions regarding wireless sensor adoption velocity and hospital capital expenditure cycles. Regulatory clearance delays, supply chain disruptions in German manufacturing clusters, and non-invasive accuracy skepticism warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Patient Monitoring
Middle East and Africa Patient Monitoring Market
Patient Monitoring
Patient Monitoring Pods Market
Patient Monitoring
Fetal and Neonatal Heart Monitor Market
Patient Monitoring
Abetalipoproteinemia Monitoring Systems Market
Patient Monitoring
Home Care Monitoring and Diagnostics Market
Patient Monitoring
Digital Patient Monitoring Systems Market
Patient Monitoring
Asthma Monitoring Devices Market
Patient Monitoring
Cardiac Arrhythmia Monitoring Devices Market
Patient Monitoring
Smart Medication Adherence Sensors Market
Patient Monitoring
Global Consumer Healthcare Sensor Market
Patient Monitoring
Patient Monitoring and Ultrasound Devices Display Market
Patient Monitoring
Neuro-Monitoring System Market
Patient Monitoring
Sleep Monitoring Devices Market
Patient Monitoring
Blood Pressure Monitors Market
Patient Monitoring
Latin America Self -Monitoring Blood Glucose Market
Patient Monitoring
Global Intrapartum Monitoring Devices Market