
 Global Implantable Cardiac Monitor Market | 2026-2036
Global Implantable Cardiac Monitor Market Size, Share, and Industry Trends Forecast 2026-2036
Global Implantable Cardiac Monitor Market Foresight
Market Context with Strategic Players
Cloud-based analytics integration is rewriting how implantable cardiac monitors deliver longitudinal patient data to electrophysiologists. Medtronic leverages its vertically integrated manufacturing footprint to sustain cost advantages across the implantable loop recorder value chain. Abbott Laboratories anchors its competitive position through deep R&D investment in Bluetooth Low Energy connectivity protocols. Biotronik specializes in European market access, navigating CE marking complexities under the EU MDR framework.
Technical Definition and Structural Segments
An implantable cardiac monitor is a subcutaneous electrophysiological device, typically measuring 50-80 mm in length and incorporating leadless bipolar sensing electrodes, designed to continuously record heart rhythm data for periods extending from months to years. Its primary commercial purpose centers on detecting infrequent arrhythmias, unexplained syncope, and cryptogenic stroke risk in patients for whom external monitoring proves inadequate. Insertable loop recorders occupy the dominant revenue position due to established reimbursement pathways and procedural familiarity among electrophysiologists, while mobile cardiac telemetry segments are accelerating fastest as home healthcare providers expand remote patient monitoring capabilities. Cloud-based analytics platforms concentrate margin pools through recurring software licensing models attached to hardware deployments.
Regulatory Framework and Forward Outlook
FDA premarket notification requirements, EU MDR technical documentation standards, and Japan PMDA quality management system regulations collectively elevate barriers to market entry while standardizing safety benchmarks across jurisdictions. These frameworks shape demand by mandating extended battery longevity claims and cybersecurity validations that favor established manufacturers with dedicated regulatory affairs infrastructure. Stakeholders must monitor evolving FDA guidance on artificial intelligence-enabled arrhythmia classification algorithms, as predictive analytics capabilities increasingly differentiate competitive offerings.
Market Dynamics
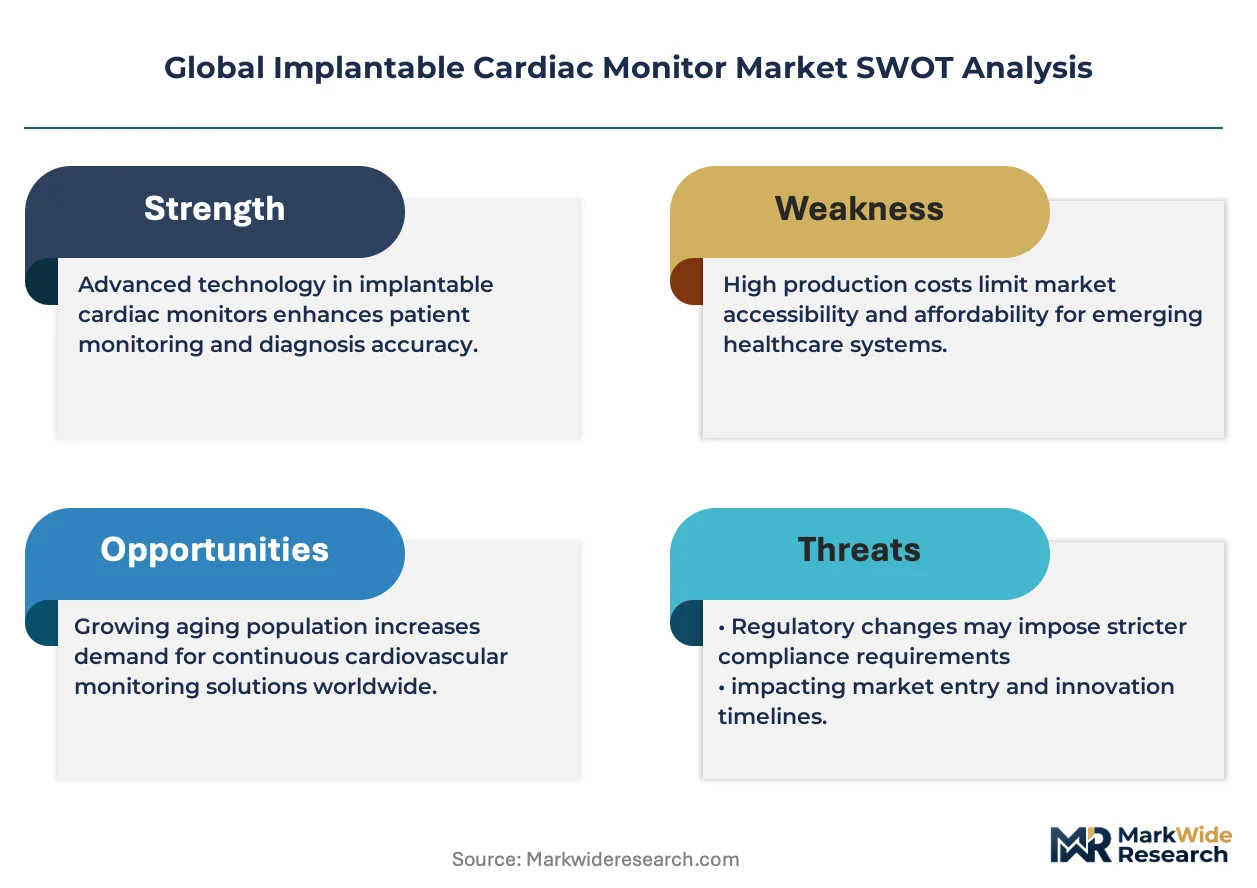
Cloud-based analytics integration is collapsing the traditional hardware-centric business model, forcing manufacturers to restructure revenue streams around recurring software licensing attached to implantable loop recorder deployments.
Growth Catalysts
- Aging demographics in Japan:The country's super-aged population generates procedural volume expansion for cryptogenic stroke monitoring, with electrophysiology infrastructure scaling to meet diagnostic demand.
- EU MDR framework harmonization:Standardized technical documentation requirements for long-term implantable devices accelerate cross-border market access for certified manufacturers.
- Bluetooth Low Energy protocols:Wireless connectivity advancement enables seamless patient-to-clinic data transmission, reducing manual interrogation burden on cardiology staff.
Market Restraints
- Lithium-iodine battery chemistry constraints:Raw material sourcing concentration limits manufacturing scale-up for multi-year longevity claims required by FDA premarket pathways.
- Single-supplier substrate dependence:Biocompatible titanium enclosure fabrication concentrates among specialized European foundries, creating geographic supply vulnerability.
- External patch monitor substitution:Extended-wear Holter alternatives capture low-risk syncope cases before implant consideration, narrowing addressable patient pools.
Strategic Opportunities
- Underpenetrated German outpatient cardiology:Ambulatory electrophysiology centers outside Berlin and Munich retain low insertable loop recorder penetration relative to hospital-based procedural volume.
- Artificial intelligence arrhythmia classification:Machine learning algorithm integration with cloud platforms creates differentiated subscription revenue models beyond device sale margins.
- Remote patient monitoring channel expansion:Home healthcare providers in the United States build direct-to-patient logistics for mobile cardiac telemetry, bypassing traditional hospital procurement.
Industry Challenges
- Electrophysiologist training pipeline constraints:Fellowship program output fails to match procedural volume growth, extending implant scheduling backlogs at high-volume United States centers.
- FDA cybersecurity validation timelines:Premarket documentation requirements for wireless-enabled devices extend regulatory review cycles, compressing product launch windows against competitive entries.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Implantable Cardiac Monitor Market |
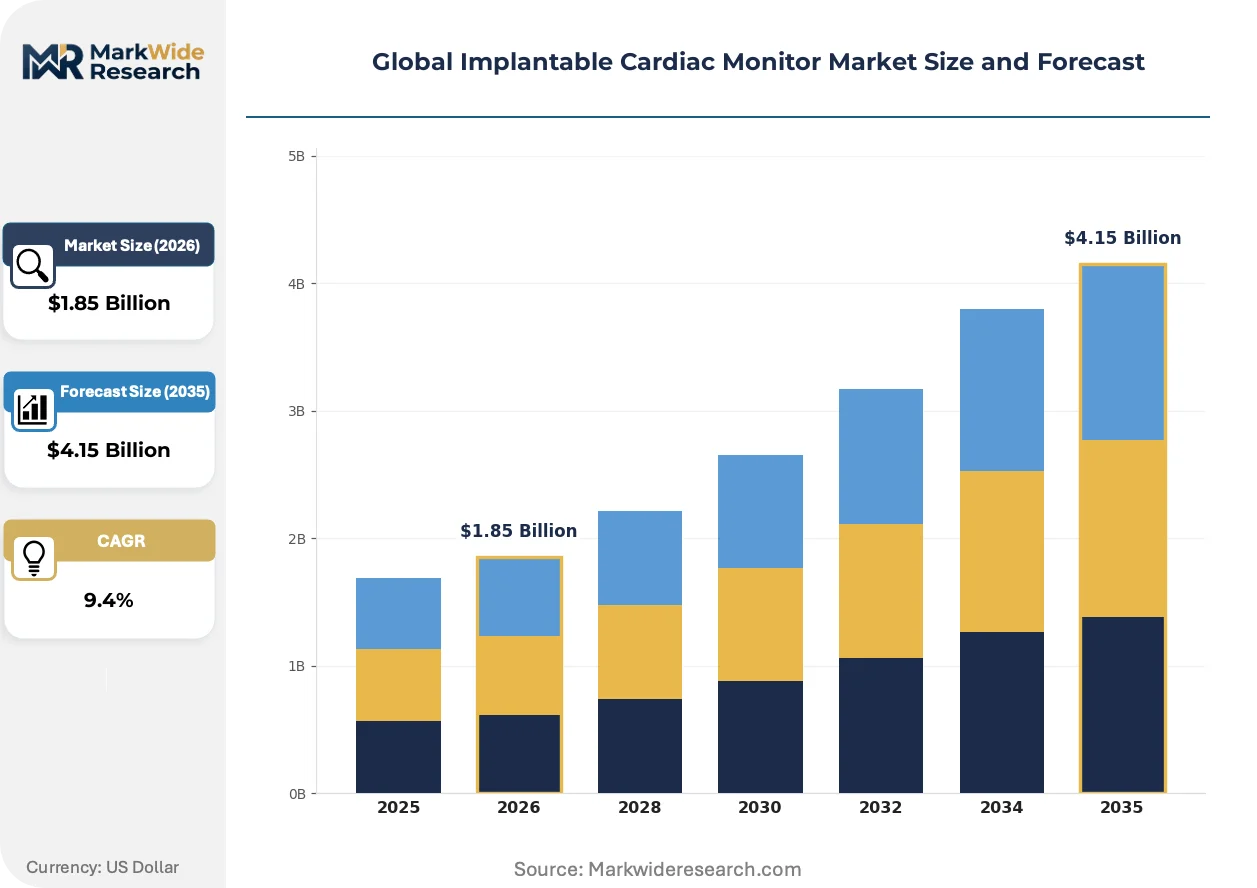
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $4.15 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Insertable Loop Recorder, Wearable Cardiac Monitor, Mobile Cardiac Telemetry, Holter Monitor Technology: Wireless Communication, Bluetooth Low Energy, Real-Time Data Transmission, Cloud-Based Analytics Application: Arrhythmia Detection, Bradycardia Monitoring, Tachycardia Diagnosis, Syncope Evaluation, Stroke Risk Assessment End User: Cardiology Clinics, Electrophysiology Labs, Diagnostic Centers, Home Healthcare Providers |
| Companies Covered | Medtronic, Abbott Laboratories, Boston Scientific Corporation, Biotronik, Koninklijke Philips, LivaNova, MicroPort Scientific Corporation, Angel Medical Systems, Nihon Kohden Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Implantable Cardiac Monitor Market Shifts & Advancements
Artificial intelligence integration and wireless connectivity protocols are fundamentally restructuring how cardiac rhythm data flows from patient to clinician, compressing diagnostic timelines and enabling predictive intervention models.
Leadless bipolar sensing electrode miniaturization is collapsing the size-performance tradeoff that historically constrained subcutaneous implant geometry. Electrophysiology practices in Germany and Japan are adopting 50-millimeter form factors for elderly patients with limited subcutaneous tissue depth. This dimensional reduction is collapsing the boundary between diagnostic implantability and patient comfort thresholds, expanding candidate pools for ambulatory monitoring.
EU MDR technical documentation standards for long-term implantable active devices mandate extended clinical follow-up data that manufacturers must submit for CE marking renewal. The regulation compresses competitive positioning around post-market surveillance capabilities rather than pre-market feature differentiation. Cardiology clinics across France, Germany, and Switzerland now prioritize suppliers with demonstrated regulatory affairs infrastructure for sustained market access.
Subscription-based analytics licensing is displacing perpetual software ownership in hospital procurement negotiations for implantable cardiac monitor ecosystems. United States health systems negotiate multi-year cloud platform agreements that bundle device hardware with algorithmic arrhythmia classification services. This purchasing pattern shift concentrates vendor selection criteria around data integration capabilities with existing electronic health record architectures rather than standalone device specifications.
Global Implantable Cardiac Monitor Market Segmentation
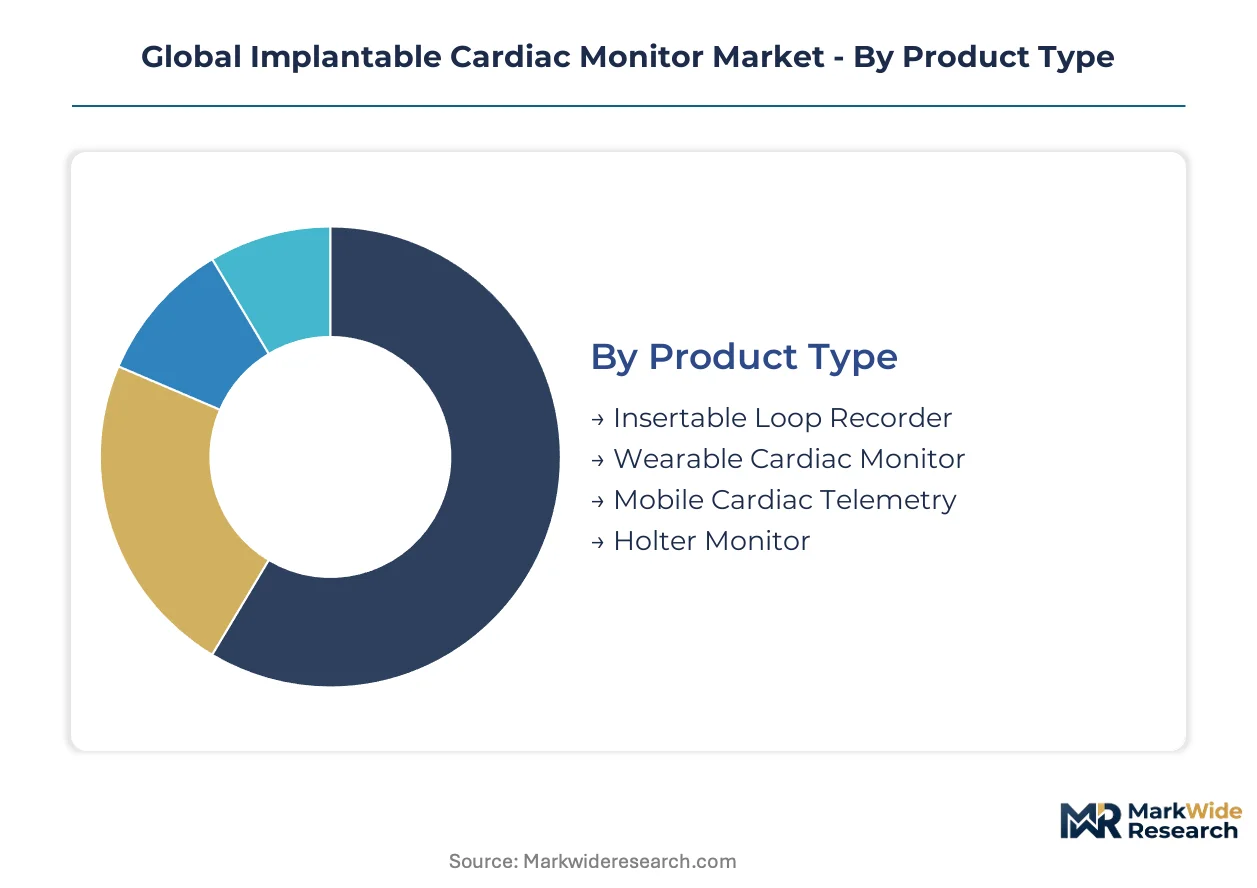
Segmentation in implantable cardiac monitoring reveals how clinical use cases, connectivity protocols, and care delivery settings fragment purchasing decisions. Manufacturers must align hardware specifications, software licensing models, and reimbursement pathways across distinct customer workflows.
Product Type:
The use-case spectrum spans diagnostic depth versus patient mobility tradeoffs, from multi-year subcutaneous implants to adhesive patch alternatives.
- Insertable Loop Recorder:A leadless bipolar sensing device measuring 50-80 mm, implanted subcutaneously to capture arrhythmia episodes over 2-4 year battery lifespans. Electrophysiology labs in the United States and Germany concentrate procedural volume for cryptogenic stroke and unexplained syncope workups, with FDA premarket approval pathways reinforcing manufacturer concentration around established regulatory affairs infrastructure.
- Mobile Cardiac Telemetry:External wearable systems transmitting real-time ECG data via cellular networks to centralized monitoring centers. Home healthcare providers in the United States bypass traditional hospital procurement by building direct-to-patient logistics, compressing diagnostic timelines for post-discharge arrhythmia surveillance.
- Wearable Cardiac Monitor:Extended-wear adhesive patch monitors capturing 7-14 day rhythm data without implantation. Diagnostic centers favor these for low-risk syncope screening where invasive procedures carry disproportionate patient burden.
- Holter Monitor:Traditional 24-48 hour external ECG recording with patient-activated event marking. Cardiology clinics retain these for high-frequency symptom correlation despite limited capture windows.
The dominant share belongs to insertable loop recorders, while mobile cardiac telemetry is closing the gap fastest.
Technology:
Cost tier stratification separates premium cloud-integrated platforms from basic wireless transmission modules.
- Cloud-Based Analytics:Centralized algorithmic processing platforms enabling machine learning arrhythmia classification and longitudinal trend analysis. United States health systems negotiate multi-year subscription bundles that tie hardware procurement to recurring software licensing, elevating vendor selection criteria around EHR integration capabilities.
- Bluetooth Low Energy:Ultra-low power wireless protocol enabling seamless patient-to-clinic data transmission with minimal battery drain. Japan PMDA quality management system regulations validate cybersecurity frameworks for these connectivity modules, accelerating adoption in Tokyo and Osaka electrophysiology networks.
- Wireless Communication:Broad-category radio frequency transmission encompassing proprietary and standard protocols. Diagnostic centers prioritize these for legacy device compatibility amid mixed fleet deployments.
- Real-Time Data Transmission:Continuous cellular or Wi-Fi streaming enabling immediate clinician notification of critical events. Home healthcare providers leverage these capabilities for remote patient monitoring expansion outside traditional hospital settings.
Cloud-based analytics commands premium pricing tiers, with Bluetooth Low Energy expanding most quickly across new device launches.
Application:
Volume concentration tracks procedural reimbursement codes and electrophysiologist training pipeline output.
- Arrhythmia Detection:Continuous rhythm monitoring to identify atrial fibrillation, ventricular tachycardia, and other episodic conduction disorders. Cardiology clinics in Germany scale ambulatory electrophysiology center capacity to address diagnostic backlogs from aging population demand.
- Syncope Evaluation:Correlation of transient loss-of-consciousness episodes with captured rhythm disturbances. Electrophysiology labs concentrate implant volume for recurrent unexplained cases where external monitoring proves inadequate.
- Stroke Risk Assessment:Detection of subclinical atrial fibrillation in cryptogenic stroke patients to guide anticoagulation therapy decisions. Japan's super-aged population generates procedural expansion specifically for this indication.
- Bradycardia Monitoring:Identification of pathologically slow heart rates requiring pacemaker intervention. Diagnostic centers deploy wearable and implantable options based on symptom frequency and severity.
- Tachycardia Diagnosis:Characterization of rapid rhythm disturbances to distinguish supraventricular from ventricular origins. Home healthcare providers capture growing volume for post-ablation surveillance.
Arrhythmia detection retains the largest indication share, though stroke risk assessment is climbing the fastest as cryptogenic stroke protocols proliferate.
End User:
Customer type fragmentation reflects divergent procurement authority and clinical workflow integration requirements.
- Cardiology Clinics:Outpatient settings managing longitudinal rhythm monitoring programs with direct device interrogation capabilities. Underpenetrated German centers outside Berlin and Munich present expansion opportunities relative to hospital-based procedural concentration.
- Home Healthcare Providers:Organizations delivering remote patient monitoring logistics and patient-facing technical support. United States operators build direct procurement relationships with manufacturers, bypassing traditional hospital supply chains for mobile cardiac telemetry.
- Electrophysiology Labs:Specialized hospital units performing implant procedures and complex arrhythmia ablations. Fellowship program output constraints in the United States extend scheduling backlogs at high-volume centers.
- Diagnostic Centers:Facilities focused on non-invasive testing including external monitor deployment and initial rhythm screening. These sites prioritize device fleet flexibility across multiple manufacturer platforms.
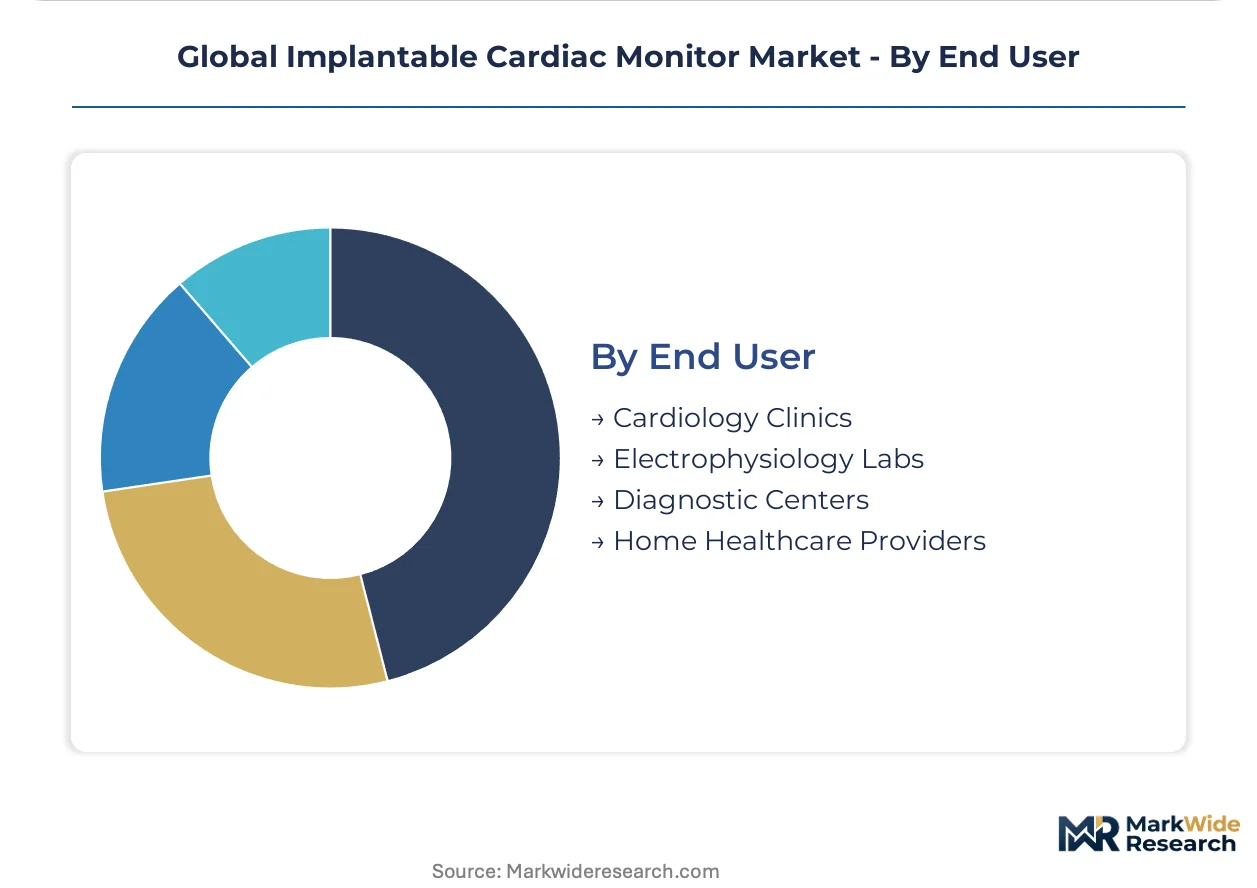
Cardiology clinics anchor current volume, while home healthcare providers are gaining share fastest through remote monitoring channel expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany exports precision electrophysiology equipment to United States hospital systems, while Japan ships advanced sensor components to European assembly facilities. This bilateral trade pattern concentrates manufacturing expertise in established medtech corridors while distributing finished devices through regional distribution networks.
United States
FDA premarket approval pathways for long-term implantable devices sustain procedural concentration at high-volume electrophysiology centers in Cleveland Clinic and Mayo Clinic networks. The agency's cybersecurity validation requirements for wireless-enabled devices compress product launch timelines. Boston and San Francisco metro areas anchor venture financing for arrhythmia classification algorithm startups.
Germany
EU MDR technical documentation standards for active implantable devices accelerate CE marking renewal cycles for manufacturers with dedicated regulatory affairs infrastructure. Ambulatory electrophysiology centers outside Berlin and Munich retain underpenetrated insertable loop recorder volumes relative to hospital-based procedural concentration. Baden-Württemberg's precision engineering cluster supplies biocompatible titanium enclosure fabrication to device manufacturers.
Japan
PMDA quality management system regulations validate Bluetooth Low Energy cybersecurity frameworks for wireless connectivity modules. Tokyo and Osaka electrophysiology networks scale procedural capacity to address diagnostic backlogs from super-aged population demand for cryptogenic stroke monitoring. METI funding programs support domestic battery chemistry research for multi-year longevity claims.
Switzerland
Swissmedic certification requirements for active implantable medical devices align with EU MDR standards while maintaining separate technical documentation pathways. Basel and Zurich medtech clusters concentrate regulatory consulting services for cross-border market access into EU member states. The country's bilateral agreements with the European Union streamline CE marking recognition procedures.
United Kingdom
MHRA post-Brexit regulatory frameworks for implantable devices maintain alignment with EU MDR safety benchmarks while establishing independent conformity assessment routes. London and Southeast England cardiology clinics expand remote patient monitoring partnerships with home healthcare providers. NHS procurement frameworks increasingly bundle device hardware with cloud-based analytics subscription models.
Global Implantable Cardiac Monitor Market Competitive Landscape
On the supply side, the industry is consolidating around vertically integrated manufacturers with captive regulatory affairs infrastructure and dedicated electrophysiology sales channels. Three strategic archetypes dominate: diversified medtech conglomerates with cardiovascular device portfolios, specialized cardiac rhythm management firms, and emerging Asian manufacturers building cost-optimized production platforms. Competitive dynamics center on M&A activity targeting algorithmic arrhythmia classification capabilities and strategic partnerships between device manufacturers and cloud platform providers.
Within the diversified medtech tier, Medtronic and Abbott Laboratories exemplify scale-driven positioning through vertically integrated manufacturing footprints and established FDA premarket approval track records. Biotronik occupies a specialized European-access position, navigating CE marking complexities under EU MDR frameworks. These three anchors represent distinct competitive vectors: manufacturing scale, connectivity protocol R&D, and regional regulatory expertise.
| Leading Market Players |
|---|
| Medtronic |
| Abbott Laboratories |
| Boston Scientific Corporation |
| Biotronik |
| Koninklijke Philips |
| LivaNova |
| MicroPort Scientific Corporation |
| Angel Medical Systems |
| Nihon Kohden Corporation |
| Others |
Supply & Pricing Matrix
Undercapacity in biocompatible titanium enclosure fabrication across Baden-Württemberg precision foundries is compressing supplier pricing power for implantable loop recorder manufacturers while elevating procurement premiums for battery chemistry inputs.
Pricing Analysis
Next-generation cloud-integrated implantable cardiac monitors command substantial premiums over legacy Bluetooth-enabled devices and prior-generation manual-interrogation units. Pricing stratifies across premium, standard, and economy tiers based on algorithmic sophistication and FDA premarket approval tier. Cost compression in economy-tier hardware is intensifying because external patch monitors capture low-risk diagnostic cases. Home healthcare providers exhibit highest price sensitivity due to direct-to-patient procurement models, while electrophysiology labs prioritize integration capabilities over unit cost.
Supply Chain Analysis
Raw material feeds for lithium-iodine battery cells concentrate in Japan METI-funded research corridors and specialized European chemical processors. Biocompatible titanium enclosures draw from German precision engineering clusters, while advanced sensor components source from Japanese semiconductor fabricators. Single-source vulnerability pervades the substrate supply base for leadless bipolar electrodes. Distribution runs through regional medtech distributors with hospital system and cardiology clinic direct relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbent manufacturers must defend against substitution by extended-wear external monitors that narrow implantable device addressable pools through improved adhesive patch longevity.
For Market Incumbents: Entrench cloud analytics subscription models to lock hospital systems into multi-year licensing bundles that resist external monitor displacement. Deepen backward integration into battery chemistry research to secure multi-year longevity claims required by FDA premarket pathways. Prioritize cybersecurity validation infrastructure to compress regulatory review cycles against competitive entries.
For New Entrants and Emerging Players: Build out regulatory affairs capabilities targeting EU MDR CE marking renewal cycles where established documentation infrastructure creates vendor selection criteria. Focus initial penetration on underpenetrated German ambulatory electrophysiology centers outside Berlin and Munich. Pursue direct procurement relationships with United States home healthcare providers bypassing hospital supply chains.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among manufacturers with integrated cloud platform licensing attached to hardware deployments. Five-to-ten-year viability favors firms with demonstrated post-market surveillance capabilities under EU MDR frameworks. Watch FDA guidance evolution on artificial intelligence-enabled arrhythmia classification as inflection signal for algorithmic differentiation value.
| Strategic Initiative | Industry Significance |
|---|---|
| Cloud Platform Integration | Subscription licensing attached to implantable loop recorders concentrates margin pools through recurring revenue models. |
| EU MDR CE Marking Pathway | Technical documentation infrastructure accelerates cross-border market access for certified manufacturers into German and Swiss clinics. |
| Hospital System Partnership | Direct procurement relationships with Cleveland Clinic and Mayo Clinic networks anchor high-volume electrophysiology procedural share. |
| Software Companion Development | Machine learning arrhythmia classification algorithms differentiate competitive offerings in United States health system negotiations. |
| Reimbursement Strategy | Cryptogenic stroke monitoring codes in Japan's super-aged population expansion drive procedural volume growth for insertable loop recorders. |
Research Methodology
Cross-validation between primary interviews with electrophysiologists, hospital procurement managers, biomedical engineers, and GPO contracts managers and secondary sources including FDA premarket filings, EU MDR technical documentation databases, hospital procurement records, and CMS Medicare reimbursement data anchors the qualitative findings. Bottom-up implant volume estimates triangulate against top-down market sizing across product type, connectivity protocol, clinical application, and end-user facility categories.
Calibration against historical procedural volume trajectories in United States, German, and Japanese electrophysiology networks informs the analytical framework across the projection horizon. Segmentation dimensions span insertable loop recorder versus mobile cardiac telemetry form factors, Bluetooth Low Energy versus cloud-based analytics connectivity tiers, arrhythmia detection versus stroke risk assessment applications, and cardiology clinic versus home healthcare provider end-user channels. CAGRs derive from patent filing trajectories, regulatory approval timelines, and reimbursement code expansion patterns specific to cryptogenic stroke monitoring protocols.
The forecast holds incumbent behavior within observed patterns; aggressive cloud platform acquisitions by diversified medtech conglomerates or rapid FDA artificial intelligence guidance shifts would shift outcomes. Regulatory restriction on lithium-iodine raw material sourcing or cybersecurity validation timeline extensions represent specific revision risks. Quarterly review of FDA premarket approval queue lengths and EU MDR CE marking renewal volumes is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Slit Lamps Market
Medical Devices
Global Hydrocephalus Shunts Market
Medical Devices
Breast Localization System Market
Medical Devices
At-Home Vaginal Ph Test Kit Market
Medical Devices
Partial Ossicular Replacement Prosthesis Market
Medical Devices
Surgical AR Systems Market
Medical Devices
Global Neurovascular Guidewires Market
Medical Devices
Bioimpedance Devices Market
Medical Devices
Japan Hemostats Market
Medical Devices
Implantable Drug Eluting Devices Market
Medical Devices
Europe Incontinence Devices and Ostomy Market
Medical Devices
United States Insulin Pumps Market
Medical Devices
GCC Implantable Medical Devices Market
Medical Devices
Saudi Arabia Minimally Invasive Surgery Devices Market
Medical Devices
USA Artificial Organs and Bionic Implants Market
Medical Devices
Global Brachytherapy Devices Market