
 Global Antipsychotic Drugs Market | 2026-2036
Global Antipsychotic Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Global Antipsychotic Drugs Market Foresight
The EU Green Deal's pharmaceutical sustainability framework is consolidating environmental compliance requirements across antipsychotic manufacturing supply chains. Eli Lilly and Company leverages its R&D intensity in novel neurotransmitter targets to sustain pipeline differentiation. Johnson & Johnson anchors its position through Janssen Pharmaceuticals' dominance in long-acting injectable formulations. Bristol-Myers Squibb competes via its established portfolio in atypical antipsychotics across major psychiatric indications.
Antipsychotic drugs constitute a class of psychopharmacological agents designed to modulate dopaminergic, serotonergic, and glutamatergic neurotransmission, primarily manufactured through multi-step organic synthesis with stringent purity thresholds exceeding 99.5% active pharmaceutical ingredient content. Their core commercial purpose centers on symptom management across schizophrenia spectrum disorders, bipolar mania, and treatment-resistant depression. Atypical antipsychotics command the largest revenue pool due to superior metabolic side-effect profiles, while long-acting injectables represent the fastest-expanding segment as psychiatric clinics prioritize adherence-driven outcomes. Tablet formulations retain volume leadership in outpatient settings, though orally disintegrating tablets gain traction in populations with swallowing difficulties.
The FDA's risk evaluation and mitigation strategies for antipsychotic metabolic monitoring, alongside EMA's pharmacovigilance requirements under the EU Medical Device Regulation for companion diagnostics, shape product labeling and post-market surveillance obligations. China's NMPA accelerated review pathways for innovative central nervous system therapies are opening manufacturing partnerships for multinational sponsors. Stakeholders must monitor evolving reimbursement criteria for digital therapeutics paired with pharmacological interventions.
Market Dynamics
Long-acting injectable formulations are restructuring competitive positioning across psychiatric care delivery, as adherence-driven reimbursement models from United States payers and European health technology assessment bodies reward sustained-release mechanisms with preferential formulary placement.
Growth Catalysts
- FDA Accelerated Approval Pathways:The FDA's breakthrough therapy designation for novel dopamine-serotonin modulators compresses clinical trial timelines, enabling faster market entry for mechanism-differentiated candidates targeting treatment-resistant schizophrenia.
- Psychiatric Clinic Infrastructure:Specialty mental health facilities in Germany and the United Kingdom are expanding long-acting injectable administration capacity, creating dedicated adherence monitoring programs that drive sustained demand for depot formulations.
- China NMPA CNS Fast-Track:China's National Medical Products Administration prioritizes innovative central nervous system therapies through conditional approval frameworks, attracting multinational manufacturing partnerships and localized production investments.
Market Restraints
- Active Pharmaceutical Ingredient Concentration:Multi-step organic synthesis of atypical antipsychotics depends on concentrated precursor supply from Indian and Chinese specialty chemical manufacturers, exposing formulation sponsors to input cost volatility and geopolitical trade friction.
- EMA Pharmacovigilance Burden:The European Medicines Agency's post-authorization safety study requirements for metabolic monitoring impose sustained clinical data collection obligations that elevate compliance costs across the product lifecycle.
- Generic Erosion in Oral Tablets:Patent expiry for established atypical antipsychotics has triggered price compression in outpatient tablet markets, constraining revenue pools for originator manufacturers despite continued volume expansion.
Strategic Opportunities
- Brazil ANVISA Digital Therapeutics Pairing:Brazil's national health regulator is developing reimbursement frameworks for smartphone-based cognitive behavioral therapy adjuncts to pharmacological treatment, opening combined intervention models in Latin America's largest psychiatric market.
- Orally Disintegrating Tablet Formats:Geriatric and neurodegenerative populations with dysphagia represent an underserved segment where taste-masked, rapid-dissolve formulations command premium positioning and limited competition.
- EU Green Deal Manufacturing Incentives:The European Union's pharmaceutical sustainability framework offers capital subsidies for green chemistry process retrofits, rewarding manufacturers that reduce solvent intensity and carbon footprint in antipsychotic synthesis.
Industry Challenges
- Central Nervous System Clinical Trial Recruitment:Schizophrenia and bipolar disorder studies face persistent patient enrollment bottlenecks due to informed consent complexity and site capacity constraints, extending development timelines.
- Companion Diagnostic Integration:Pharmacogenomic testing for CYP2D6 metabolizer status requires coordination between diagnostic laboratories and prescribing workflows, creating implementation friction in community mental health settings.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Antipsychotic Drugs Market |
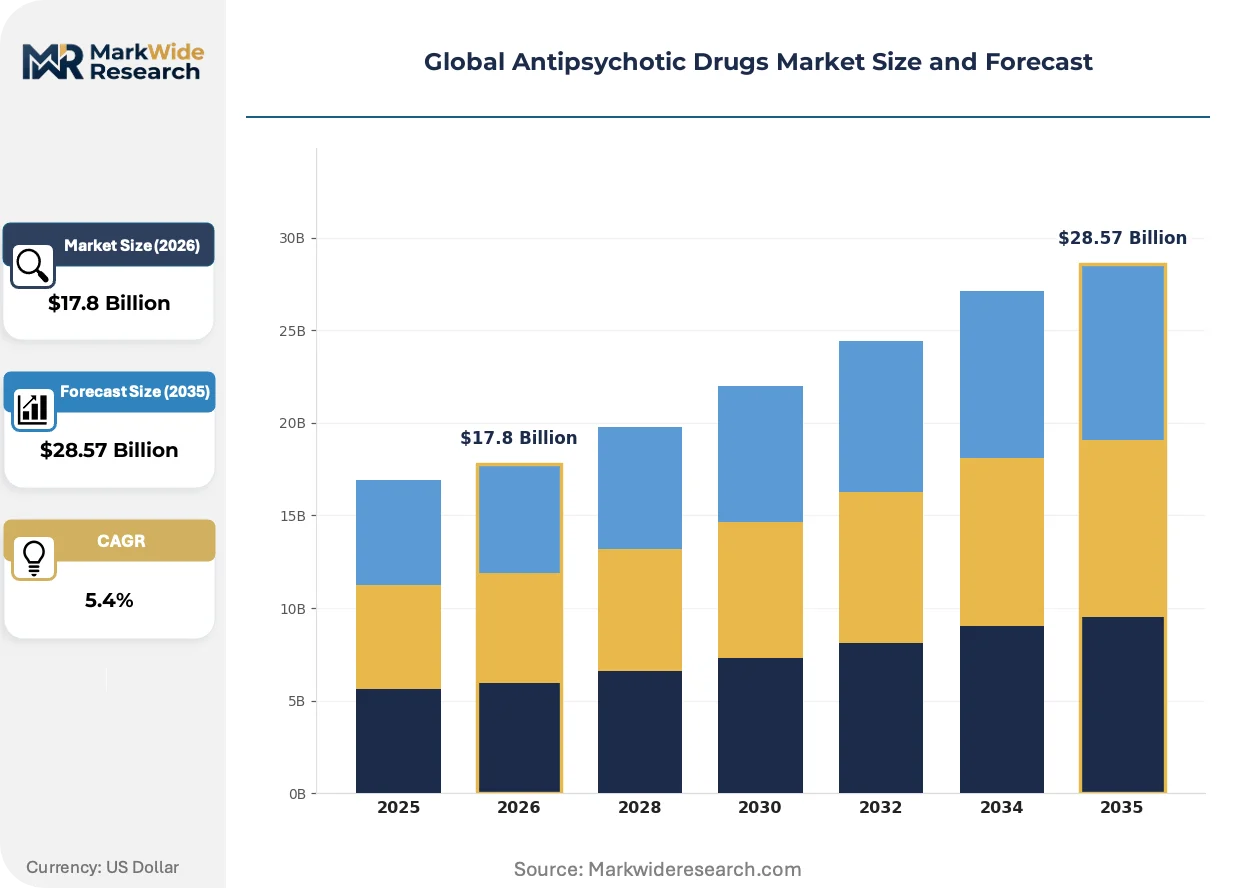
| Market Size in 2026 | $17.8 Billion |
| Market Size in 2035 | $28.57 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Drug Type: Typical Antipsychotics, Atypical Antipsychotics, Long-Acting Injectables, Combination Therapies Therapy Area: Schizophrenia, Bipolar Disorder, Major Depression, Psychotic Disorders, Tourette Syndrome Formulation: Tablet, Capsule, Injectable, Solution, Orally Disintegrating Tablet End User: Psychiatric Clinics, Specialty Hospitals, Outpatient Centers, Mental Health Facilities |
| Companies Covered | Eli Lilly and Company, Johnson & Johnson, Otsuka Pharmaceutical Co., Ltd., H. Lundbeck A/S, Janssen Pharmaceuticals, Inc., AbbVie, Inc., Teva Pharmaceutical Industries Ltd., Bristol-Myers Squibb Company, Dr. Reddy's Laboratories Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Antipsychotic Drugs Market Shifts & Advancements
Mechanism diversification beyond dopamine D2 antagonism is redefining therapeutic targets, while regulatory frameworks accelerate novel modality review and psychiatric care models shift toward longitudinal adherence management.
Trace amine-associated receptor 1 (TAAR1) agonists are electrifying pipeline development through a fundamentally distinct pharmacological approach that bypasses direct dopamine blockade. Psychiatric research institutes in the United States and Switzerland are advancing Phase III programs with unprecedented speed. This mechanism is electrifying competitive strategy by promising metabolic side-effect profiles that could displace established atypical antipsychotics in first-line schizophrenia treatment.
REACH pharmaceutical sustainability requirements are mandating environmental fate testing and green solvent substitution across European manufacturing operations. Active pharmaceutical ingredient producers must now submit comprehensive environmental risk assessments before market authorization renewal. Atypical antipsychotic manufacturers with integrated European synthesis operations are responding by retrofitting multi-step organic processes to eliminate dichloromethane and acetonitrile dependence.
Psychiatric clinic procurement is consolidating around outcome-based adherence contracts that tie formulary placement to measurable hospitalization reduction metrics. United States specialty pharmacy distributors and integrated delivery networks are displacing traditional wholesale purchasing with risk-sharing arrangements that align drug cost with patient stability outcomes. This restructuring is most visible in Medicaid-managed care populations where state agencies prioritize long-acting injectable coverage to reduce emergency department utilization.
Global Antipsychotic Drugs Market Segmentation
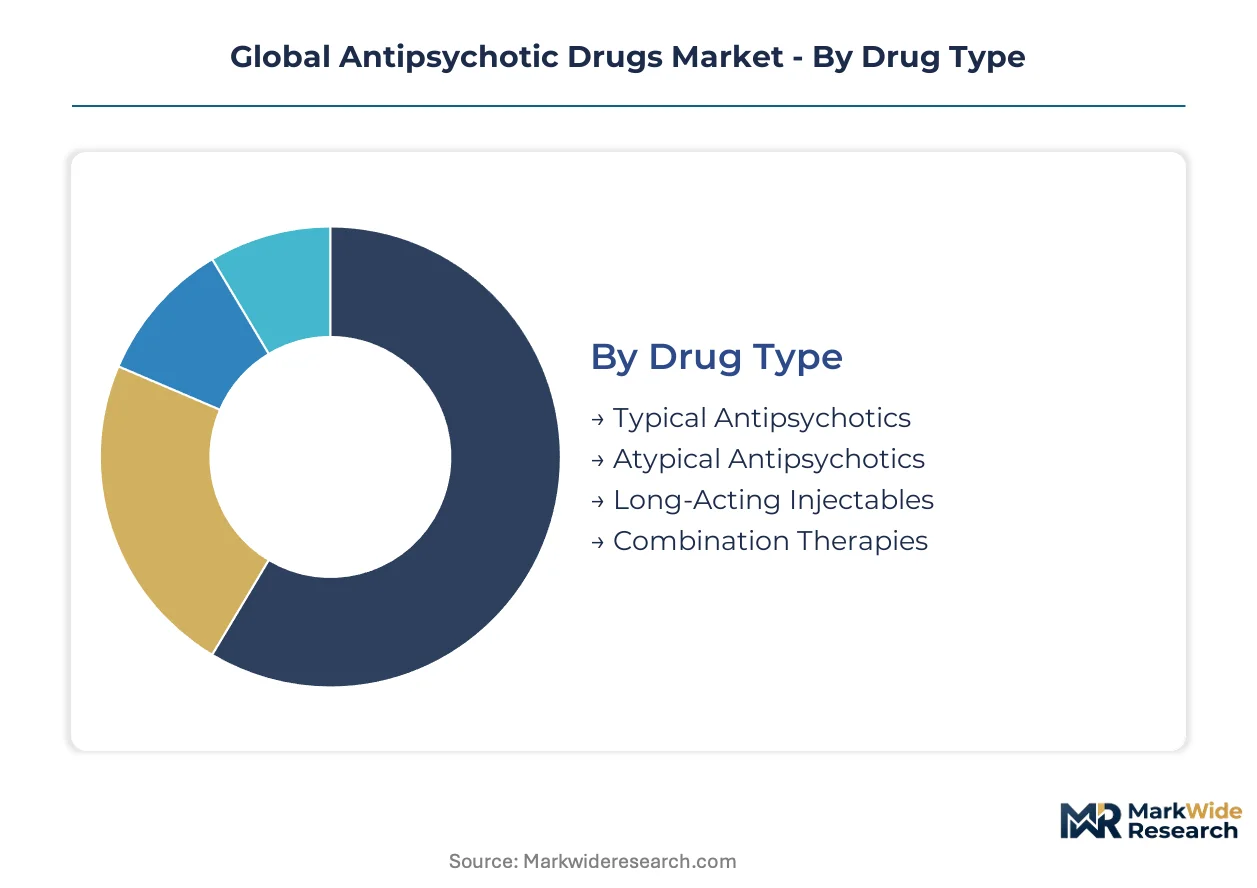
Antipsychotic market segmentation reveals distinct procurement patterns across therapeutic mechanisms, clinical settings, and patient compliance requirements. Drug type and formulation choices directly determine reimbursement eligibility, manufacturing complexity, and competitive positioning for pharmaceutical sponsors.
Drug Type:
Buyer differentiation centers on metabolic risk tolerance versus adherence enforcement needs, with psychiatric clinics and payers weighing side-effect profiles against long-term patient management costs.
- Atypical Antipsychotics:These agents modulate dopamine D2 and serotonin 5-HT2A receptors with reduced extrapyramidal symptoms compared to first-generation compounds. United States Medicaid formularies prioritize atypical agents for schizophrenia spectrum disorders, though metabolic monitoring requirements elevate total cost of care.
- Long-Acting Injectables:Sustained-release depot formulations employ esterified active pharmaceutical ingredients in microcrystalline suspensions for monthly or quarterly administration. Germany's psychiatric clinic networks are expanding dedicated adherence programs around risperidone and paliperidone palmitate injections, driven by hospitalization reduction metrics in regional health budgets.
- Typical Antipsychotics:First-generation dopamine antagonists retain niche use in treatment-resistant cases and resource-constrained settings.
- Combination Therapies:Fixed-dose co-formulations address polypharmacy compliance in complex mood disorders.
Volume sits with atypical antipsychotics; growth tilts toward long-acting injectables.
Therapy Area:
Regulatory approval pathways and clinical trial design complexity vary sharply across psychiatric indications, with schizophrenia commanding the most extensive safety databases.
- Schizophrenia:Chronic dopaminergic dysregulation management requires lifelong pharmacological intervention with progressive resistance patterns. FDA breakthrough therapy designations for novel mechanisms like TAAR1 agonists are accelerating pipeline investment in first-line and treatment-resistant segments.
- Bipolar Disorder:Mood stabilization with antimanic properties demands agents with robust maintenance data and tolerability for cycling patients. United Kingdom NICE guidelines favor atypical antipsychotics for acute mania, creating concentrated procurement within National Health Service mental health trusts.
- Major Depression:Adjunctive antipsychotic use in treatment-resistant cases represents expanding off-label and approved indications.
- Psychotic Disorders:Brief psychotic disorder and delusional disorder subsets require shorter-duration intervention protocols.
- Tourette Syndrome:Pediatric and adolescent tic suppression applications face restricted labeling and specialized prescriber requirements.
Schizophrenia absorbs the largest prescription volumes; bipolar disorder applications are climbing the fastest.
Formulation:
Patient population characteristics—swallowing capacity, cognitive status, and living situation—determine formulation selection and distribution channel requirements.
- Tablet:Compressed solid dosage forms dominate outpatient dispensing through retail pharmacy channels. Patent expiry for quetiapine and olanzapine tablets has triggered intense generic competition in United States Medicare Part D formularies.
- Orally Disintegrating Tablet:Lyophilized or compressed rapidly dissolving matrices disintegrate within seconds on the tongue without water. Japan's aging psychiatric population and nursing home infrastructure are driving demand for taste-masked donepezil-antipsychotic combinations in dementia-related psychosis.
- Injectable:Parenteral formulations span short-acting intramuscular emergency use and long-acting depot maintenance.
- Capsule:Gelatin or HPMC shells accommodate modified-release granules and combination bead technologies.
- Solution:Liquid formulations serve pediatric dosing flexibility and enteral administration requirements.
Tablets retain volume leadership; orally disintegrating formats are gaining share fastest.
End User:
Care setting determines reimbursement mechanics, administration infrastructure, and outcome measurement capabilities for antipsychotic therapy.
- Psychiatric Clinics:Dedicated mental health facilities with on-site nursing staff manage complex medication regimens and long-acting injectable administration. United States specialty pharmacy distributors are consolidating procurement for clinic networks through risk-sharing contracts tied to patient stability metrics.
- Specialty Hospitals:Inpatient psychiatric units and academic medical centers handle acute exacerbations and treatment-resistant cases requiring intensive monitoring. China's tertiary hospital psychiatry departments are expanding bed capacity for severe schizophrenia under national mental health infrastructure investments.
- Outpatient Centers:Community-based mental health services provide maintenance therapy and medication management.
- Mental Health Facilities:Residential and day treatment programs integrate pharmacological and psychosocial interventions.
Psychiatric clinics command the highest long-acting injectable volumes; specialty hospitals show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing concentration for antipsychotic active pharmaceutical ingredients clusters in India and China, while consumption and formulation innovation concentrate in the United States, Germany, and Japan. This divergence creates trade-dependent supply chains where regulatory alignment determines market access speed.
United States
Medicaid expansion and commercial insurance parity laws drive psychiatric medication volumes, with specialty pharmacy networks consolidating procurement around adherence metrics. FDA breakthrough therapy designations for novel mechanisms accelerate clinical trial investment. The Boston-Cambridge corridor hosts concentrated Phase III central nervous system research operations.
Germany
Psychiatric clinic networks in Bavaria and North Rhine-Westphalia are expanding dedicated long-acting injectable administration capacity. EMA pharmacovigilance requirements under the EU Medical Device Regulation shape post-market surveillance obligations. The Rhine-Main biotech cluster coordinates manufacturing partnerships for depot formulation technologies.
China
NMPA conditional approval frameworks for innovative central nervous system therapies attract multinational manufacturing investments. Tertiary hospital psychiatry departments in Shanghai and Beijing are expanding bed capacity for severe schizophrenia management. The Yangtze River Delta hosts concentrated active pharmaceutical ingredient synthesis operations serving global formulation sponsors.
Japan
PMDA priority review vouchers for psychiatric innovations accelerate market entry timelines for mechanism-differentiated candidates. Aging demographics and nursing home infrastructure expansion drive demand for orally disintegrating tablet formats. The Kansai region maintains concentrated pharmaceutical formulation expertise for taste-masked rapid-dissolve technologies.
India
Specialty chemical manufacturers in Gujarat and Maharashtra supply concentrated precursors for multi-step atypical antipsychotic synthesis. CDSCO accelerated approval pathways for generic complex formulations attract contract manufacturing investment. The Hyderabad-Visakhapatnam corridor hosts active pharmaceutical ingredient operations serving European and North American formulation sponsors.
Global Antipsychotic Drugs Market Competitive Landscape
The competitive structure tilts toward integrated pharmaceutical conglomerates with established central nervous system franchises. Market concentration reflects high regulatory barriers and specialized manufacturing requirements for long-acting injectable formulations. Three archetypes dominate: originator innovators with novel mechanism pipelines, generic complex formulation specialists, and vertically integrated active pharmaceutical ingredient-to-formulation operators. Capacity expansion in depot manufacturing and strategic partnerships for digital therapeutic pairing represent the dominant competitive moves.
Among originator innovators, Eli Lilly and Company, Johnson & Johnson, and Bristol-Myers Squibb occupy positions defined by neurotransmitter target diversification and metabolic side-effect profile differentiation. These entities exemplify the R&D-intensive archetype where pipeline depth determines formulary placement. Their geographic distribution across North American and European headquarters reflects regulatory filing strategy concentration.
| Leading Market Players |
|---|
| Eli Lilly and Company |
| Johnson & Johnson |
| Otsuka Pharmaceutical Co., Ltd. |
| H. Lundbeck A/S |
| Janssen Pharmaceuticals, Inc. |
| AbbVie, Inc. |
| Teva Pharmaceutical Industries Ltd. |
| Bristol-Myers Squibb Company |
| Dr. Reddy's Laboratories Ltd. |
| Others |
Supply & Pricing Matrix
Family-owned mid-cap active pharmaceutical ingredient producers in Gujarat and Maharashtra anchor precursor supply for atypical antipsychotic synthesis, translating concentrated upstream ownership into disciplined contract pricing for multinational formulation sponsors facing EMA pharmacovigilance cost burdens.
Pricing Analysis
Margin tightening in oral tablet tiers traces to patent expiry cascades for quetiapine and olanzapine, triggering generic price compression in United States Medicare Part D formularies. Three-tier pricing structure across originator, authorized generic, and commodity generic levels segments buyers by metabolic monitoring tolerance and adherence enforcement needs. Cost-down pressure on long-acting injectables accelerates because psychiatric clinic networks in Germany and the United Kingdom consolidate procurement around hospitalization reduction metrics. Medicaid-managed care populations exhibit highest price sensitivity; private-pay specialty pharmacy channels show lowest.
Supply Chain Analysis
REACH pharmaceutical sustainability certification gates European market access for active pharmaceutical ingredient producers, forcing solvent substitution retrofits before authorization renewal. Manufacturing gravity centers on India and China for concentrated precursors, with Italy and Switzerland hosting formulation finishing. Multi-step organic synthesis draws from dichloromethane, acetonitrile, and specialty catalyst feedstocks. Single-source vulnerability concentrates in Yangtze River Delta intermediate suppliers. Distribution runs through United States specialty pharmacy networks and European psychiatric clinic procurement consortia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Green Deal's pharmaceutical sustainability framework constructs a cost-of-compliance moat where REACH environmental fate testing requirements disadvantage non-integrated manufacturers, rewarding sponsors with captive green chemistry capabilities.
For Market Incumbents: Cement formulary positioning through backward integration into long-acting injectable manufacturing capacity in the Rhine-Main biotech cluster, countering generic erosion in oral tablets. Deepen pipeline differentiation around TAAR1 agonist mechanisms to defend against metabolic side-effect profile competition from mechanism-differentiated entrants. For New Entrants and Emerging Players: China's NMPA conditional approval framework for innovative central nervous system therapies opens a window for partnership-based market entry with domestic tertiary hospital psychiatry departments. Target orally disintegrating tablet formats for Japan's aging nursing home population, leveraging taste-masked rapid-dissolve technology gaps. Pursue digital therapeutic pairing reimbursement pathways under Brazil ANVISA emerging frameworks. For Investors and Strategic Acquirers: FDA breakthrough therapy designation awards for novel dopamine-serotonin modulators are the leading indicator that mechanism-differentiated pipelines warrant premium valuation multiples. Position for five-to-ten year horizon consolidation around depot formulation specialists with integrated European manufacturing footprints. Monitor China NMPA accelerated review pathway utilization rates as inflection signal for multinational partnership velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Green Chemistry Process Retrofit | REACH compliance secures EMA authorization renewal for European synthesis operations. |
| Long-Acting Injectable Capacity Expansion | Dedicated adherence programs in German psychiatric clinics drive depot formulation demand. |
| TAAR1 Agonist Clinical Advancement | FDA breakthrough therapy designation compresses timelines for treatment-resistant schizophrenia candidates. |
| Digital Therapeutic Pairing Development | Brazil ANVISA reimbursement frameworks enable smartphone-based cognitive behavioral therapy adjuncts. |
| Orally Disintegrating Tablet Launch | Japan's PMDA priority review vouchers accelerate market entry for dysphagia-addressing formats. |
Research Methodology
Independent corroboration across drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers underwrites the qualitative findings, triangulated against FDA filings, EMA submissions, ClinicalTrials.gov records, and formulary databases. Secondary validation incorporates SEC 10-K disclosures from central nervous system franchise holders and customs data on active pharmaceutical ingredient trade flows. Bottom-up patient volume modeling and top-down therapeutic class expenditure analysis converge on segment-level estimates.
Rate-of-change decomposition across the analysis window isolates volume drivers from price effects, with CAGRs derived from segmented trend extrapolation. The forecast framework models drug type, formulation, therapy area, end-user setting, and regional regulatory cluster dimensions. Pipeline probability-adjusted revenue forecasting incorporates Phase III transition rates and NMPA conditional approval pathway success patterns.
The model assumes a particular technology adoption path; alternative pathways for TAAR1 agonist mechanism uptake would alter the outlook for established atypical antipsychotic revenue pools. Forecasts reflect assumptions regarding psychiatric clinic infrastructure expansion rates and long-acting injectable administration capacity buildout. A model refresh is warranted upon material change in FDA breakthrough therapy designation award velocity or REACH pharmaceutical sustainability enforcement intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
G Protein Coupled Receptors (Gpcrs) Market
Pharmaceuticals
Global Orphan Drugs Market
Pharmaceuticals
Global Immunomodulators Market
Pharmaceuticals
Asia-Pacific Pharmaceutical Contract Manufacturing Organization Market
Pharmaceuticals
Global Erectile Dysfunction Drugs Market
Pharmaceuticals
Tenecteplase Drugs Market
Pharmaceuticals
North America Sodium-Dependent Glucose Co-Transporter 2 (Sglt2) Market
Pharmaceuticals
Propofol Market
Pharmaceuticals
Global Hepatitis a Vaccine Market
Pharmaceuticals
Global Low Molecular Weight Heparin Market
Pharmaceuticals
Oral Thin Film Drugs Market
Pharmaceuticals
High Potency API Contract Manufacturing Market
Pharmaceuticals
Budesonide Market
Pharmaceuticals
Mouth Ulcers Treatment Market
Pharmaceuticals
Infliximab Market
Pharmaceuticals
Naproxen Market