
 Endocavity Transducer Market | 2026-2036
Endocavity Transducer Market Size, Share, and Industry Trends Forecast 2026-2036
Endocavity Transducer Market Foresight
Aftermarket service revenue is reshaping profitability in the endocavity transducer sector as hospitals extend probe lifecycles rather than replace capital equipment. GE HealthCare Technologies Inc. leverages its installed base of ultrasound systems to sustain recurring calibration and repair contracts across North American hospital networks. Siemens Healthineers AG competes through specialized probe refurbishment programs that anchor long-term client relationships in European diagnostic centers. Koninklijke Philips N.V. differentiates via integrated probe-platform compatibility, controlling upgrade pathways across its imaging portfolio.
An endocavity transducer is a specialized ultrasound probe designed for insertion into body cavities, typically operating at frequencies between 5-12 MHz to generate high-resolution images of adjacent organs and tissues. These devices employ piezoelectric crystal arrays encased in biocompatible housing with specialized acoustic lensing to enable real-time visualization during gynecological, urological, and oncological procedures. Ultrasound probes and imaging systems capture the dominant share of product-related revenue, while 3D and 4D imaging technologies represent the fastest-expanding technology segment as clinicians demand volumetric data for complex diagnostic scenarios. Wireless technology adoption remains nascent but holds concentrated interest among ambulatory clinic operators seeking flexible examination room configurations.
FDA 510(k) premarket notification requirements govern probe safety and electromagnetic compatibility in the United States, while EU MDR and CE marking obligations enforce biocompatibility and sterilization validation standards across European markets. Japan's PMDA and METI frameworks impose additional clinical evidence requirements that shape product development priorities for Asia-Pacific market entry. China's NMPA and GB standards introduce localized testing protocols that influence manufacturing location decisions for multinational suppliers. Stakeholders must monitor evolving cybersecurity guidance for connected probe systems and anticipate harmonization pressures between FDA digital health pathways and EU AI Act risk classifications affecting automated image analysis features.
Market Dynamics
The endocavity transducer sector is experiencing structural pressure from probe lifecycle extension programs, as hospital capital expenditure constraints force procurement departments to prioritize refurbishment over replacement. This shift compresses new unit sales while expanding aftermarket service revenue pools across diagnostic imaging networks.
Growth Catalysts
- EU MDR enforcement:The Medical Device Regulation's enhanced biocompatibility and sterilization validation standards are accelerating hospital replacement cycles for legacy probes that cannot meet upgraded documentation requirements.
- 3D volumetric imaging:Gynecological and oncological procedures are demanding real-time volumetric data capture, expanding addressable procedure volumes for advanced transducer architectures.
- China's screening mandates:National early-detection programs for cervical and prostate cancers are institutionalizing transvaginal and transrectal ultrasound protocols across provincial hospital tiers.
Market Restraints
- Piezoelectric crystal supply concentration:Specialty ceramic substrate production concentrates in East Asian manufacturing clusters, exposing probe assemblers to input volatility and single-source dependency risks.
- EU MDR certification timelines:Extended notified body review periods and clinical evidence requirements are delaying product launches and freezing R&D roadmaps for European market entry.
- Disposable sheath economics:Single-use protective barrier costs per procedure create operational friction in high-volume screening environments, constraining throughput economics.
Strategic Opportunities
- Wireless probe architectures:Ambulatory clinic operators in Germany and the United States are piloting cable-free examination room configurations that eliminate tethering constraints and improve patient positioning flexibility.
- AI-assisted image analysis:Automated volumetric measurement algorithms are creating upgrade pathways for installed base systems, embedding software differentiation into hardware refresh decisions.
- India's diagnostic infrastructure expansion:Tier-2 and tier-3 city hospital networks are deploying compact ultrasound systems with endocavity capabilities, opening volume markets beyond metropolitan tertiary centers.
Industry Challenges
- Cross-functional engineering talent scarcity:The intersection of acoustic physics, biocompatible materials science, and embedded systems firmware requires specialized expertise that concentrates in legacy imaging equipment hubs.
- Legacy system integration complexity:Backward compatibility requirements for existing ultrasound console architectures constrain form factor innovation and limit wireless architecture adoption.
- Multi-jurisdiction certification synchronization:Divergent FDA 510(k), EU MDR, and NMPA evidence standards force parallel track development programs that dilute R&D efficiency.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Endocavity Transducer Market |
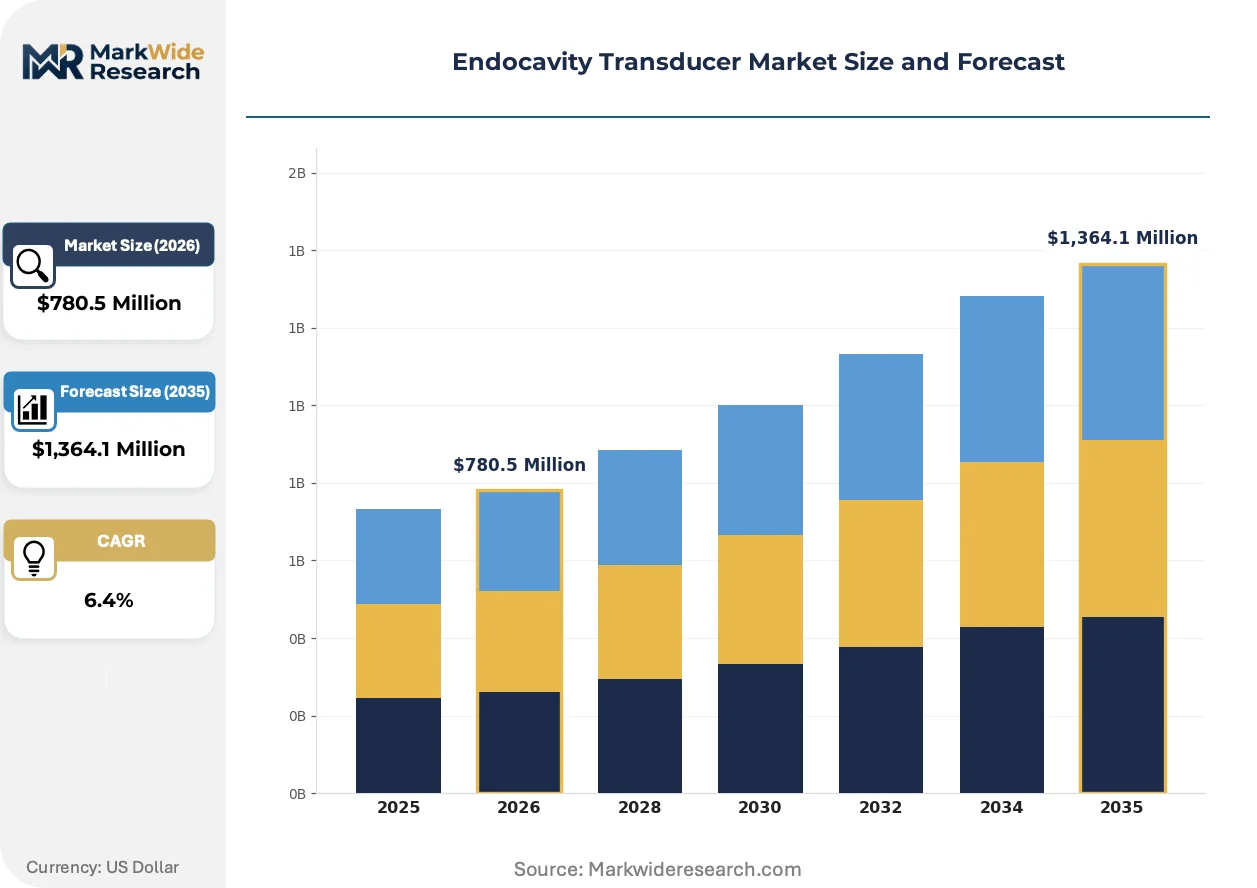
| Market Size in 2026 | $780.5 Million |
| Market Size in 2035 | $1,364.1 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ultrasound Probes, Catheters, Imaging Systems, Accessories Technology: 3D Imaging, 4D Imaging, Doppler Ultrasound, Wireless Technology End User: Hospitals, Clinics, Diagnostic Centers, Research Institutions Application: Gynecological Imaging, Urological Diagnoses, Oncology Procedures, Cardiology Evaluations |
| Companies Covered | Canon Medical Systems Corporation, Shenzhen Mindray Bio-Medical Electronics Co. Ltd., GE HealthCare Technologies Inc., FUJIFILM Holdings Corporation, Hitachi Ltd., Koninklijke Philips N.V., Samsung Medison Co. Ltd., BK Medical ApS, Siemens Healthineers AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Endocavity Transducer Market Shifts & Advancements
Probe virtualization and software-defined imaging architectures are displacing hardware-centric differentiation in the endocavity transducer market. Manufacturers are embedding computational capabilities that extend functional utility without physical redesign.
Capacitive micromachined ultrasonic transducer (CMUT) technology is virtualizing traditional piezoelectric crystal arrays through semiconductor fabrication processes that enable programmable frequency response. Academic medical centers in Boston and Heidelberg are validating CMUT-based probes for multi-frequency operation across gynecological and urological applications. This architecture is virtualizing the economics of probe manufacturing by collapsing discrete component assembly into wafer-scale production.
EU MDR Article 10 post-market surveillance obligations are mandating systematic clinical follow-up data collection that probe manufacturers must integrate into quality management systems. The regulation is forcing redesign of complaint handling and vigilance reporting workflows across European distribution networks. High-frequency transvaginal probes with extended field life are experiencing disproportionate documentation burden as legacy performance data must be reconstructed to meet new clinical evidence thresholds.
Hospital procurement departments are unbundling after-sales service contracts from equipment purchase agreements, creating discrete competitive arenas for calibration and repair services. Diagnostic imaging departments in the United States are negotiating multi-vendor maintenance agreements that aggregate probe fleets across ultrasound platform brands. This behavior is most visible in integrated delivery networks where central procurement functions have consolidated purchasing authority previously dispersed across individual hospital sites.
Endocavity Transducer Market Segmentation
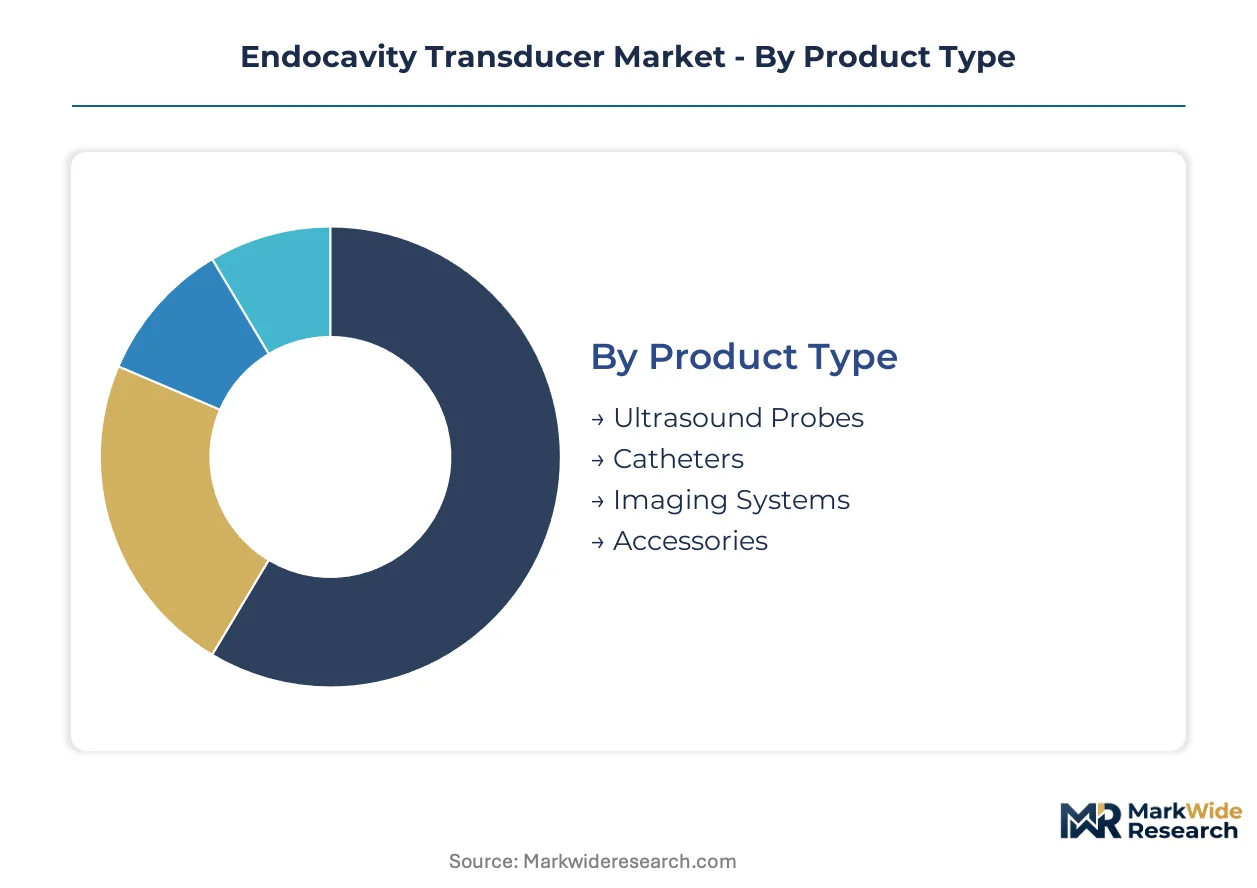
Endocavity transducer procurement patterns diverge sharply across product architectures, with service contract attachment rates varying from 15% in budget clinic deployments to 85% in integrated hospital networks. Understanding these segment boundaries illuminates where aftermarket revenue concentrates and which technology transitions warrant capital allocation.
Product Type:
After-sales service intensity correlates directly with product complexity, as ultrasound probes generate recurring calibration revenue while accessories rely on disposable replenishment economics.
- Ultrasound Probes:Piezoelectric crystal arrays encased in biocompatible housing with specialized acoustic lensing dominate hospital procurement budgets. Demand concentrates in the United States and Germany, where aging populations and early-detection screening programs sustain replacement cycles for transvaginal and transrectal configurations.
- Imaging Systems:Console-based ultrasound platforms with endocavity probe compatibility anchor capital expenditure decisions in tertiary care networks. Chinese provincial hospitals under national screening mandates are expanding installed bases fastest, though refurbishment programs in North America extend legacy system lifecycles.
- Catheters:Single-use delivery systems for specialized interventional procedures.
- Accessories:Disposable sheaths, gel applicators, and sterilization trays with lower service contract penetration.
Ultrasound probes hold the largest share; momentum sits with imaging systems as 3D/4D upgrade pathways deepen hardware-software bundling.
Technology:
Cost tier stratification separates premium volumetric platforms from standard 2D systems, with wireless architectures commanding 40-60% price premiums in ambulatory settings.
- 3D Imaging:Volumetric data capture enabling real-time reconstruction of anatomical structures for complex gynecological assessments. Academic medical centers in Boston and Heidelberg are validating multi-frequency operation protocols, expanding addressable procedure volumes beyond conventional 2D limitations.
- 4D Imaging:Time-resolved volumetric visualization for dynamic fetal and cardiac assessment.
- Doppler Ultrasound:Blood flow velocity measurement integrated into endocavity probes for oncological vascular mapping.
- Wireless Technology:Cable-free probe architectures eliminating tethering constraints in examination room configurations. Ambulatory clinic operators in Germany and the United States are piloting flexible deployment models, though legacy system integration complexity constrains rapid adoption.
3D imaging holds the largest share; momentum sits with wireless technology as cable-free configurations gain traction in outpatient settings.
End User:
Customer type determines procurement authority concentration, with integrated delivery networks aggregating fleet maintenance contracts across previously siloed hospital sites.
- Hospitals:Tertiary care networks with centralized biomedical engineering departments managing multi-vendor probe fleets. United States integrated delivery networks are unbundling service contracts from equipment purchases, creating discrete competitive arenas for calibration and repair.
- Diagnostic Centers:High-volume screening facilities with standardized protocols and rapid throughput requirements.
- Clinics:Ambulatory operators prioritizing examination room flexibility and lower capital intensity.
- Research Institutions:Academic medical centers validating novel probe architectures like CMUT-based multi-frequency systems.
Hospitals hold the largest share; momentum sits with diagnostic centers as China's tier-2 and tier-3 city networks expand screening infrastructure.
Application:
Volume concentration follows screening program mandates, with cervical and prostate cancer early-detection protocols institutionalizing transvaginal and transrectal ultrasound across national health systems.
- Gynecological Imaging:Transvaginal ultrasound for cervical cancer screening and fertility assessment. China's national early-detection programs are institutionalizing protocols across provincial hospital tiers, while EU MDR biocompatibility requirements accelerate replacement cycles for legacy probes.
- Oncology Procedures:Tumor localization and treatment monitoring in prostate and gynecological cancers.
- Urological Diagnoses:Transrectal imaging for prostate assessment and bladder dysfunction evaluation.
- Cardiology Evaluations:Specialized transesophageal applications with limited endocavity probe overlap.
Gynecological imaging holds the largest share; momentum sits with oncology procedures as automated volumetric measurement algorithms create software-driven upgrade pathways.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Endocavity transducer deployment patterns diverge sharply across national health systems, with screening program mandates in China and Germany institutionalizing high-volume protocols while United States procurement prioritizes refurbishment economics over new capital allocation.
United States
Integrated delivery networks in the United States are consolidating probe fleet maintenance across multi-vendor ultrasound platforms, unbundling service contracts from equipment purchases to negotiate aggregated calibration agreements. FDA 510(k) premarket notification requirements govern electromagnetic compatibility and biocompatibility validation, tightening documentation burdens for legacy probe replacements. Academic medical centers in Boston anchor CMUT technology validation studies, validating multi-frequency operation protocols for next-generation transducer architectures.
Germany
German ambulatory clinic operators are piloting wireless probe configurations that eliminate tethering constraints in examination room layouts, commanding 40-60% price premiums over standard systems. EU MDR enforcement accelerates hospital replacement cycles for legacy probes unable to meet upgraded biocompatibility and sterilization documentation requirements. Diagnostic centers in Heidelberg concentrate volumetric imaging research, validating 3D/4D protocols for complex gynecological assessments.
China
China's national early-detection programs for cervical and prostate cancers are institutionalizing transvaginal and transrectal ultrasound protocols across provincial hospital tiers, expanding installed base volumes fastest globally. NMPA and GB standards introduce localized testing protocols that influence manufacturing location decisions for multinational suppliers. Tier-2 and tier-3 city networks beyond Beijing and Shanghai are deploying compact ultrasound systems with endocavity capabilities, opening volume markets outside metropolitan tertiary centers.
Japan
Japanese diagnostic centers demand extended field-life documentation for high-frequency transvaginal probes as PMDA and METI frameworks impose additional clinical evidence requirements shaping product development priorities. Post-market surveillance obligations under domestic pharmaceutical and medical device regulations mandate systematic clinical follow-up data collection integrated into quality management systems. Tokyo-based academic medical centers concentrate validation research for automated volumetric measurement algorithms, embedding software differentiation into hardware procurement decisions.
India
Indian tier-2 and tier-3 city hospital networks are deploying compact ultrasound systems with endocavity capabilities, creating procurement volume beyond metropolitan tertiary centers previously dominating diagnostic infrastructure. CDSCO certification requirements and state-level health procurement policies shape equipment standards for national screening program participation. Maharashtra and Karnataka industrial clusters concentrate domestic assembly operations for cost-optimized probe configurations serving budget-conscious clinic deployments.
Endocavity Transducer Market Competitive Landscape
Capability concentration sits with specialized acoustic engineering firms possessing integrated piezoelectric crystal and firmware competencies; scale advantage sits with diversified imaging equipment manufacturers leveraging installed base relationships for aftermarket service capture. The vendor base stratifies across three archetypes: full-platform ultrasound system providers, dedicated probe specialists, and emerging semiconductor-fabrication entrants virtualizing traditional crystal arrays through CMUT architectures. Dominant competitive moves include probe lifecycle extension programs anchoring long-term service contracts and strategic partnerships with academic medical centers validating novel imaging protocols.
Among diversified imaging equipment manufacturers, GE HealthCare Technologies Inc., Koninklijke Philips N.V., and Siemens Healthineers AG exemplify scale-driven archetypes that control upgrade pathways across integrated probe-platform portfolios. These companies occupy positions where installed base density translates into recurring calibration and repair contract capture across North American and European hospital networks. Shenzhen Mindray Bio-Medical Electronics Co. Ltd. represents a China-based fabricator serving cost-optimized procurement segments in emerging diagnostic infrastructure markets.
| Leading Market Players |
|---|
| Canon Medical Systems Corporation |
| Shenzhen Mindray Bio-Medical Electronics Co. Ltd. |
| GE HealthCare Technologies Inc. |
| FUJIFILM Holdings Corporation |
| Hitachi Ltd. |
| Koninklijke Philips N.V. |
| Samsung Medison Co. Ltd. |
| BK Medical ApS |
| Siemens Healthineers AG |
| Others |
Supply & Pricing Matrix
Guangdong Province's piezoelectric ceramic manufacturing clusters anchor global probe component supply, with capacity utilization swings directly transmitting into OEM pricing power across North American and European hospital procurement cycles. This geographic concentration creates asymmetric bargaining leverage where input volatility propagates faster than finished-goods price adjustments.
Pricing Analysis
Long-term service contracts dominate hospital procurement, with multi-year calibration and refurbishment agreements locking in recurring revenue streams that offset compressed new-unit margins. Price differentiation rests on FDA 510(k) certification tier and after-sales bundling intensity, with premium configurations commanding substantial uplifts for integrated AI-assisted analysis modules. Pricing pressure stems from probe lifecycle extension programs as capital-constrained facilities prioritize refurbishment over replacement. Budget-conscious clinic operators in India's tier-2 cities exhibit highest price sensitivity, while integrated delivery networks in the United States demonstrate lowest sensitivity due to aggregated fleet maintenance economics.
Supply Chain Analysis
Specialty lead zirconate titanate ceramic substrates feed from concentrated East Asian fabrication facilities in China, Japan, and South Korea, with biocompatible polymer housings sourcing from German and Swiss precision molding operations. Raw material dependencies center on rare-earth dopants for piezoelectric crystal performance, medical-grade silicone elastomers, and semiconductor-grade epoxy encapsulants. Single-source vulnerability concentrates in high-purity ceramic powder processing, where limited qualified suppliers expose probe assemblers to allocation risk during demand surges. Distribution runs through authorized distributor networks serving hospital procurement departments and direct OEM relationships with integrated delivery networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Aftermarket service revenue layers expand faster than hardware sales as probe lifecycle extension programs institutionalize recurring calibration and refurbishment contracts across hospital networks.
For Market Incumbents: Harden installed base lock-in through backward integration into piezoelectric crystal fabrication, reducing single-source dependency exposure while capturing margin from captive ceramic supply. Fortify regulatory dossiers for EU MDR Article 10 post-market surveillance compliance, converting documentation burden into competitive moat against under-resourced challengers facing extended notified body review timelines. For New Entrants and Emerging Players: Pursue wireless probe architectures for ambulatory clinic operators in Germany and the United States, where cable-free configurations command substantial price premiums and legacy system integration complexity has slowed incumbent response. Target India's tier-2 and tier-3 diagnostic infrastructure expansion, deploying compact ultrasound systems through state-level health procurement channels with localized CDSCO certification support. For Investors and Strategic Acquirers: Long-term, this sits as a recurring-revenue infrastructure play because probe service contract attachment rates concentrate economic value in aftermarket capture rather than discrete hardware transactions. Acquisition targets should display specialized acoustic engineering capabilities paired with established hospital GPO relationships. The signal to watch is CMUT technology validation progress at academic medical centers, indicating semiconductor-fabrication entrants may virtualize traditional crystal array economics.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR compliance accelerates replacement cycles for legacy probes unable to meet upgraded biocompatibility documentation. |
| Hospital System Partnership | Integrated delivery network consolidation creates aggregated fleet maintenance contracts across multi-vendor ultrasound platforms. |
| Software Companion Development | AI-assisted volumetric measurement algorithms embed differentiation into hardware refresh decisions at academic medical centers. |
| Backward Integration | In-house piezoelectric ceramic production reduces single-source dependency and captures upstream margin from specialty substrate supply. |
| Reimbursement Strategy | Alignment with national early-detection screening mandates in China and Germany institutionalizes procedure volume and procurement continuity. |
Research Methodology
Desk research of FDA 510(k) premarket notification databases, EU MDR notified body guidance documents, and NMPA registration filings preceded structured interviews with hospital biomedical engineering directors, GPO contracts managers, ultrasound probe refurbishment technicians, and diagnostic imaging department heads. Secondary validation drew from hospital procurement database extracts, CMS Medicare reimbursement schedules, and trade customs records for piezoelectric ceramic substrate movements. Bottom-up probe shipment estimates triangulated against top-down imaging equipment capital expenditure surveys.
Assumptions held fixed include prevailing regulatory certification timelines across FDA, EU MDR, and NMPA jurisdictions, while variables included wireless technology adoption velocity and CMUT semiconductor-fabrication yield improvements. The analytical framework modeled product type, technology tier, end-user category, and application segment dimensions across the projection horizon. CAGRs derived from fitted growth curves applied to base-year market sizing, with procedure volume elasticity to screening program mandates serving as primary demand-side input and ceramic substrate pricing volatility as key supply-side modifier.
Macroeconomic conditions sit as an overlay; deviation in hospital capital expenditure cycles, medical device tariff regimes, or rare-earth element export restrictions would shift the trajectory materially. Forecasts embed these assumptions without claiming predictive certainty. Cross-checking against external hospital procurement spend benchmarks and imaging equipment manufacturer disclosed service revenue splits is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Sperm Separation Devices Market
Medical Devices
Accelerometers Medical Sensors Market
Medical Devices
US Neurothrombectomy Devices Market
Medical Devices
Radial Access Catheter Market
Medical Devices
Global Oxygen Cylinders and Concentrators Market
Medical Devices
Atrial Appendage Occluder Market
Medical Devices
Lacrimal Devices Market
Medical Devices
GCC Biopsy Devices Market
Medical Devices
Otorhinolaryngology Devices Market
Medical Devices
Human Anatomical Models Market
Medical Devices
Global Brachytherapy Devices Market
Medical Devices
Australia Contraceptive Devices Market
Medical Devices
Nurse Call Systems Market
Medical Devices
Microscope Market
Medical Devices
Asia-Pacific Vaginal Slings Market
Medical Devices
Electrocardiograph (ECG) Market