
 Global Intrauterine Contraceptive Devices (IUD) Market | 2026-2036
Global Intrauterine Contraceptive Devices (IUD) Market Size, Share, and Industry Trends Forecast 2026-2036
Global Intrauterine Contraceptive Devices (IUD) Market Foresight
Multi-source procurement for copper and hormonal IUDs is decoupling from legacy single-vendor contracts across public health systems. Bayer AG leverages its manufacturing scale to sustain supply agreements with national family planning programs. CooperSurgical Inc. differentiates through specialized product portfolios targeting gynecology clinics. DKT International competes aggressively on price in community health facilities across low-income markets.
Intrauterine contraceptive devices are T-shaped implants inserted into the uterus, typically measuring 32 millimeters in horizontal arm length and constructed from polyethylene with copper wire wrapping or levonorgestrel-el polymer reservoirs for sustained hormone release. Their primary commercial purpose is reversible long-term fertility regulation with minimal user compliance requirements. Hormonal IUDs command premium positioning due to extended duration and therapeutic applications in menorrhagia management, while copper IUDs anchor volume through lower cost and broader eligibility. Distribution through government health programs captures the largest patient reach, though online retailers represent the fastest-growing channel for refill and replacement cycles.
FDA clearance requirements for Class III medical devices establish baseline safety thresholds for US market entry, while WHO prequalification shapes procurement eligibility across donor-funded programs in Africa and South Asia. EMA's Medical Device Regulation imposes strengthened clinical evidence standards that EU manufacturers must satisfy for CE marking renewal. Stakeholders must monitor evolving reimbursement classifications under national health insurance schemes and prequalification status changes that determine competitive access to bulk purchasing tenders.
Market Dynamics
WHO prequalification requirements are fragmenting procurement eligibility across donor-funded health programs, forcing manufacturers to maintain dual regulatory dossiers for copper and hormonal device variants while national family planning authorities consolidate vendor panels.
Growth Catalysts
- India's National Family Planning Program:Government-subsidized distribution through community health facilities drives volume expansion for copper IUDs in rural districts.
- WHO Prequalification:Eligibility for bulk purchasing tenders in Africa and South Asia opens procurement access to standardized device specifications.
- Levonorgestrel-eluting polymer reservoirs:Extended-release hormonal formulations enable therapeutic applications beyond contraception, including menorrhagia management in gynecology clinics.
Market Restraints
- Copper wire supply concentration:Raw material sourcing depends on limited smelter capacity in Chile and Peru, creating input cost volatility for non-hormonal device manufacturers.
- FDA Class III device pathways:Premarket approval timelines extend 18-24 months for new hormonal formulations, compressing competitive windows for novel entrants.
- Subdermal contraceptive implants:Long-acting reversible alternatives with lower insertion skill requirements threaten IUD volume in youth-focused family planning programs.
Strategic Opportunities
- Brazil's SUS expansion:Underpenetrated public health infrastructure in Northeast and North regions creates white space for copper IUD distribution partnerships.
- EMA Medical Device Regulation:Strengthened clinical evidence standards for CE marking renewal favor established manufacturers with robust post-market surveillance systems.
- Telehealth platforms:Remote consultation and prescription services for IUD replacement cycles bypass traditional clinic-based distribution bottlenecks in urban markets.
Industry Challenges
- Insertion training capacity:Skilled provider shortages in sub-Saharan Africa limit deployment velocity despite device availability through donor channels.
- Post-market surveillance compliance:EUDAMED registration and periodic safety update report obligations impose ongoing regulatory resource demands on mid-scale manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Intrauterine Contraceptive Devices (IUD) Market |
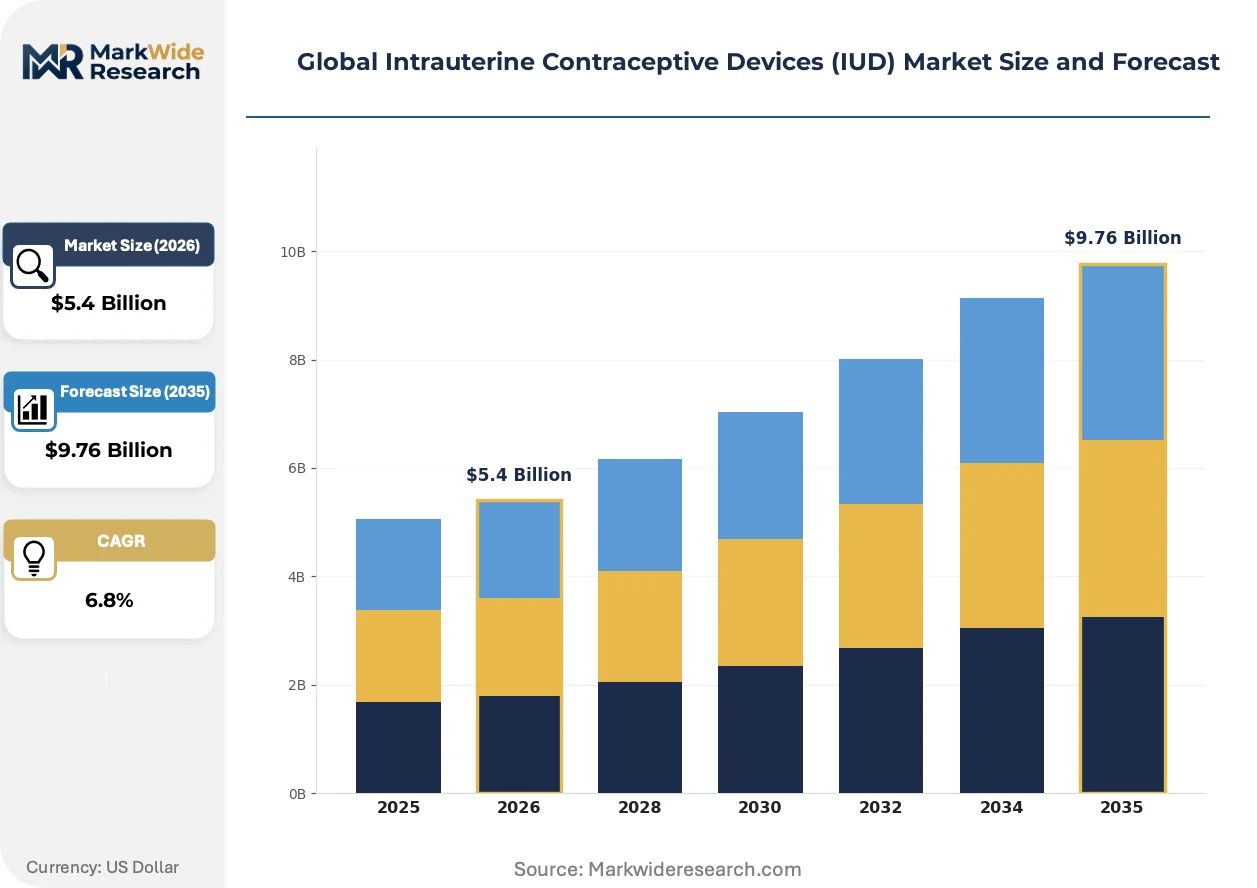
| Market Size in 2026 | $5.4 Billion |
| Market Size in 2035 | $9.76 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Copper IUD, Hormonal IUD, Ballerine IUD, Frameless IUD Application: Long-term Contraception, Emergency Contraception, Menorrhagia Management, Endometriosis Relief End User: Gynecology Clinics, Family Planning Centers, Women’s Health Hospitals, Community Health Facilities Distribution Channel: Pharmacies, Hospitals, Online Retailers, Medical Device Distributors, Government Health Programs |
| Companies Covered | Bayer AG, AbbVie Inc., CooperSurgical Inc., Merck & Co., DKT International, EUROGINE, Prosan International BV, HLL Lifecare Limited, Pregna International Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Intrauterine Contraceptive Devices (IUD) Market Shifts & Advancements
Device miniaturization and biocompatible material advances are compressing insertion trauma and expulsion rates, while digital health integration creates new data streams for adherence monitoring and replacement scheduling.
Frameless copper IUD designs utilizing nitinol anchoring systems are converging with conventional T-shaped polyethylene platforms, enabling gynecology clinics to offer customized options based on uterine cavity measurements. European specialty clinics have adopted these configurations for nulliparous patients at twice the rate of standard devices. This convergence is compressing the historical trade-off between expulsion risk and insertion ease that shaped product segmentation.
EMA's Medical Device Regulation imposes strengthened clinical evidence standards for CE marking renewal, requiring manufacturers to submit post-market clinical follow-up data for hormonal IUDs. EU notified bodies have extended review timelines by four to six months for legacy devices lacking contemporary safety cohorts. Hormonal device portfolios with therapeutic indications face the most stringent scrutiny, prompting some manufacturers to narrow labeling claims.
Direct-to-patient subscription models for IUD replacement cycles are displacing traditional clinic-dependent procurement in metropolitan markets. Online retailers in Germany and the United Kingdom now coordinate telehealth consultations, prescription verification, and specialist referral networks for insertion appointments. This channel shift is most visible among insured patients aged 25-34 seeking convenience and price transparency outside national health service queues.
Global Intrauterine Contraceptive Devices (IUD) Market Segmentation
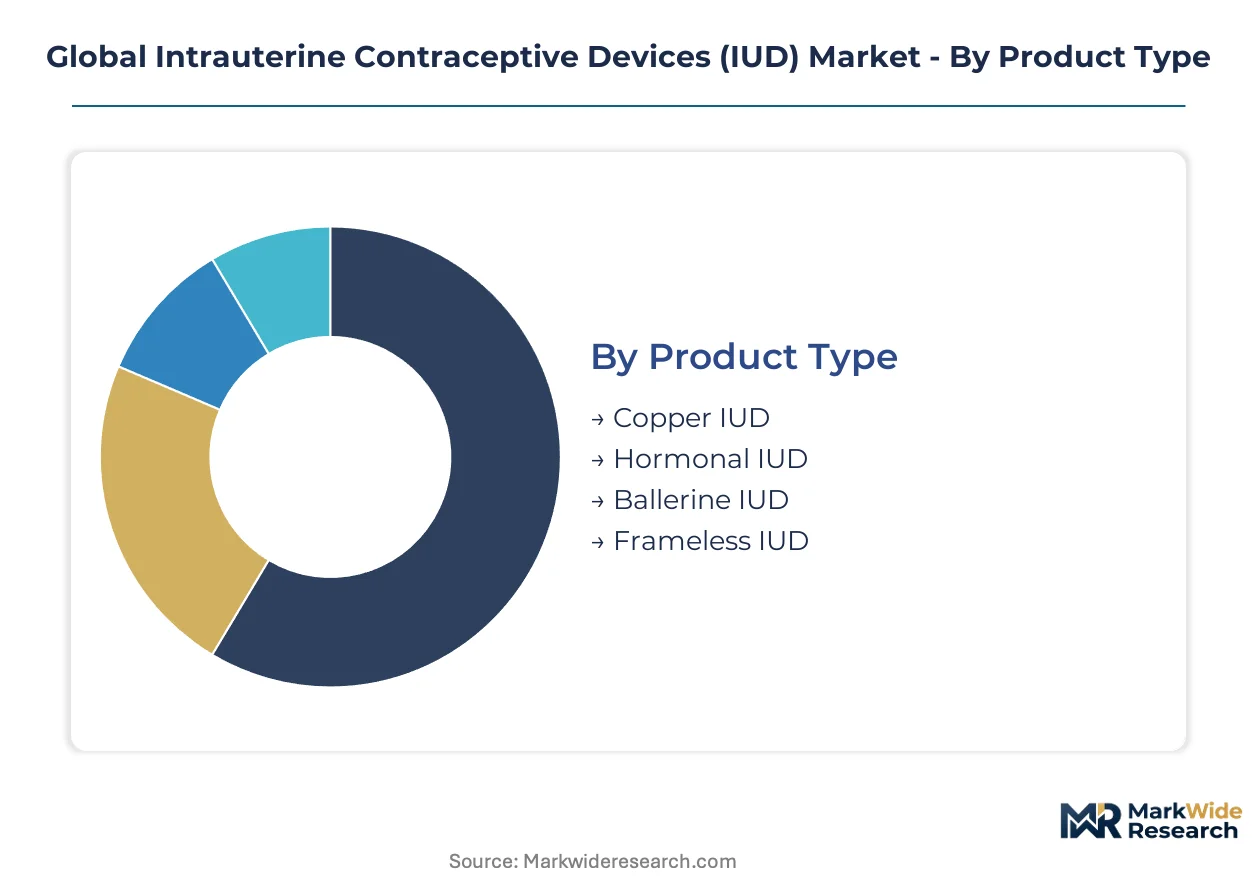
Device specification and insertion protocol variations create distinct procurement tiers across public and private health systems. Manufacturers align product portfolios to reimbursement classifications and provider training requirements that differ by channel and geography.
Product Type:
Material composition and hormone delivery mechanisms define clinical utility and regulatory pathway complexity for each variant.
- Hormonal IUD:Levonorgestrel-eluting polymer reservoirs release progestin locally over five to eight years, reducing systemic hormone exposure. Demand concentrates in gynecology clinics across Germany and the United Kingdom where therapeutic indications for menorrhagia command premium reimbursement.
- Copper IUD:Polyethylene frames wrapped with copper wire provide non-hormonal contraception through spermicidal ion release. India's National Family Planning Program drives volume procurement for rural community health facilities where cost sensitivity dominates selection criteria.
- Ballerine IUD:Spherical nitinol design conforms to uterine cavity irregularities without rigid frame structure. Compact dimensions suit nulliparous patients in private European clinics.
- Frameless IUD:Anchor-based copper systems eliminate horizontal arms entirely, reducing expulsion rates in smaller uterine cavities. Adoption trails conventional designs due to specialized insertion training requirements.
Mature deployment sits with copper IUDs. Newer deployment is concentrated in frameless and spherical configurations.
Application:
Clinical indication breadth determines pricing tier and prescriber specialization requirements.
- Long-term Contraception:Primary commercial purpose across all device categories with duration ranging from five to twelve years depending on copper mass or hormone reservoir specification.
- Menorrhagia Management:Hormonal IUDs reduce menstrual blood loss through endometrial suppression. Gynecology clinics in France and Spain prescribe for this indication at rates exceeding pure contraceptive use.
- Emergency Contraception:Copper IUD insertion within five days of unprotected intercourse provides post-coital efficacy superior to oral regimens. Family planning centers in Brazil and Mexico stock dedicated inventory for this protocol.
- Endometriosis Relief:Hormonal suppression of endometrial tissue growth extends device utility into pain management. Specialist referral networks in Italy and the Netherlands drive uptake for this secondary indication.
Volume concentrates in long-term contraception. Fastest expansion is occurring in menorrhagia management applications.
End User:
Provider infrastructure and reimbursement mechanisms shape device selection and procurement method.
- Family Planning Centers:Government-funded facilities across India, Kenya, and Bangladesh distribute subsidized copper IUDs through community health worker networks. Volume procurement dominates channel economics.
- Gynecology Clinics:Private specialist practices in Germany, France, and the United Kingdom prescribe hormonal devices for therapeutic indications with premium pricing. Patient self-pay and private insurance coverage predominate.
- Community Health Facilities:Primary care access points in rural India and Nigeria rely on government supply chains for copper device distribution. Insertion training capacity limits deployment velocity.
- Women's Health Hospitals:Tertiary referral centers manage complex cases including postpartum insertion and device complications. Academic medical centers in the United States and United Kingdom conduct training programs for regional provider networks.
Public sector procurement anchors volume through family planning centers. Margin concentration sits with gynecology clinics.
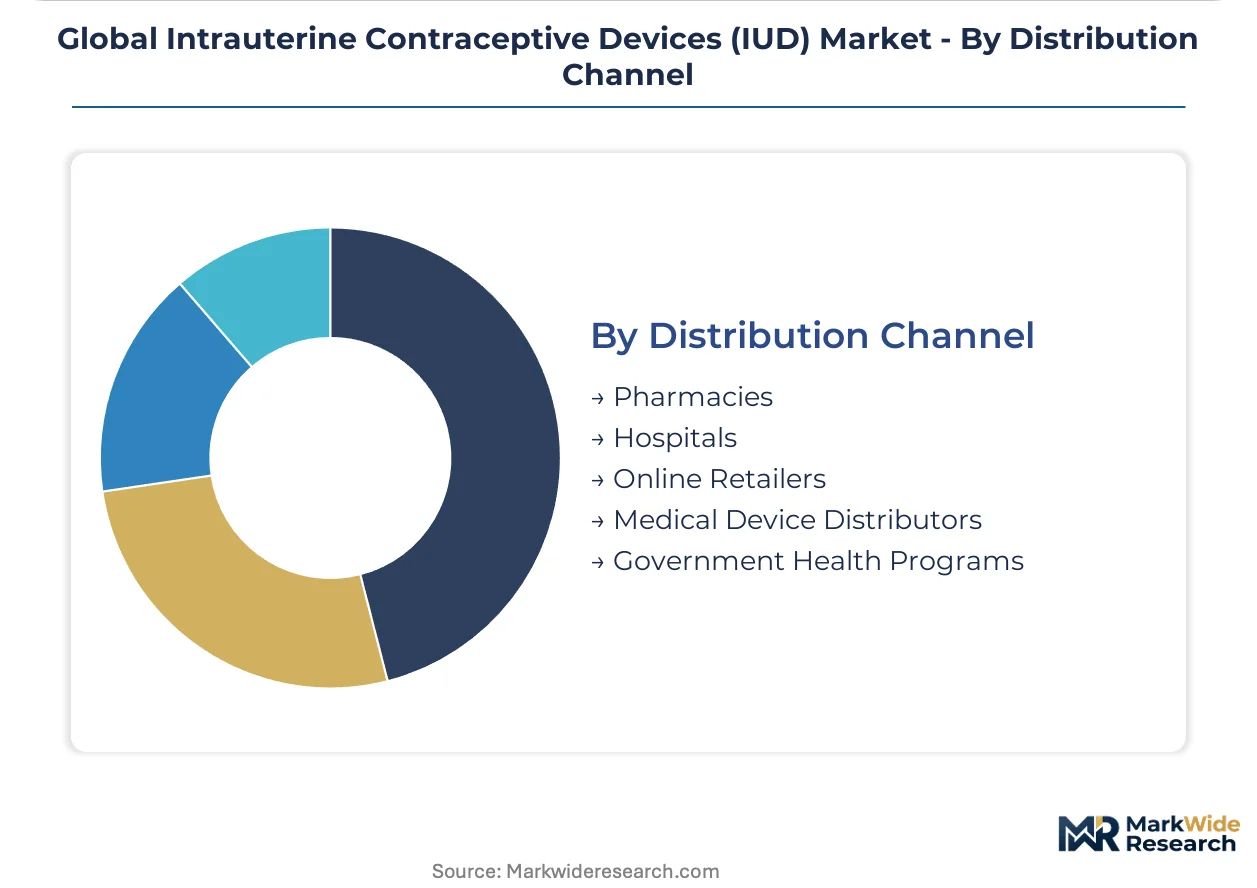
Distribution Channel:
Channel selection determines patient access speed, price transparency, and reimbursement processing complexity.
- Government Health Programs:National family planning authorities in India, Ethiopia, and Bangladesh conduct bulk tenders for copper IUD supply. WHO prequalification determines vendor eligibility.
- Online Retailers:Telehealth-integrated platforms in Germany and the United Kingdom coordinate prescription verification and specialist referral for replacement cycles. Insured patients aged 25-34 drive adoption.
- Medical Device Distributors:Regional wholesalers stock inventory for hospital and clinic procurement across Latin America and Southeast Asia. Credit terms and logistics capability determine competitive positioning.
- Hospitals:Inpatient and outpatient departments manage insertion for postpartum patients and complex cases. Group purchasing organizations in the United States negotiate pricing for member institutions.
- Pharmacies:Retail drugstores in Mexico, Brazil, and Thailand dispense devices for clinic-administered insertion. Over-the-counter availability remains limited due to insertion skill requirements.
Patient reach concentrates in government health programs. Steepest expansion trajectory belongs to online retailers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chilean and Peruvian copper smelter capacity anchors raw material sourcing for non-hormonal device manufacturers worldwide. Government procurement programs in emerging economies drive volume concentration. Regulatory harmonization through WHO prequalification reshapes competitive access across donor-funded markets.
United States
FDA Class III device pathways govern market entry for hormonal formulations with 18-24 month premarket approval timelines. Academic medical centers in Boston and New York conduct training programs for regional provider networks. Group purchasing organizations negotiate pricing for member hospitals managing postpartum insertion protocols.
Germany
EMA Medical Device Regulation imposes strengthened clinical evidence standards for CE marking renewal of legacy devices. Gynecology clinics in Berlin and Munich prescribe hormonal IUDs for menorrhagia management at rates exceeding pure contraceptive use. Online retailers coordinate telehealth consultations for replacement cycles among insured patients aged 25-34.
India
CDSCO registration requirements apply to imported devices while domestic manufacturers supply government health programs. The National Family Planning Program distributes subsidized copper IUDs through community health facilities in rural Maharashtra and Uttar Pradesh. HLL Lifecare Limited operates manufacturing clusters in Kerala serving public sector procurement.
Brazil
ANVISA medical device regulations establish safety thresholds for copper and hormonal device commercialization. The SUS public health system expansion targets underpenetrated infrastructure in Northeast and North regions. Family planning centers in São Paulo and Rio de Janeiro stock dedicated inventory for emergency contraception protocols.
United Kingdom
NICE guidelines influence reimbursement classifications for hormonal IUD therapeutic indications. Private specialist practices in London and Manchester command premium pricing for menorrhagia management applications. Telehealth-integrated platforms bypass national health service queues for replacement scheduling among metropolitan patients.
Global Intrauterine Contraceptive Devices (IUD) Market Competitive Landscape
Strategic partnerships dominate the current landscape as manufacturers navigate dual regulatory dossiers for WHO prequalification and national market entry. The vendor base concentrates around established pharmaceutical conglomerates with manufacturing scale and specialized gynecology device portfolios. Three archetypes define positioning: diversified pharmaceutical majors with hormonal platforms, surgical instrument specialists with clinic-focused portfolios, and price-competitive distributors serving public health programs. Geographic expansion into underpenetrated markets and portfolio diversification into frameless configurations represent the primary competitive vectors.
Within the diversified pharmaceutical tier, Bayer AG exemplifies manufacturing scale leverage for sustained supply agreements with national family planning authorities. CooperSurgical Inc. occupies a specialist position targeting gynecology clinics with differentiated product configurations. DKT International anchors the price-competitive archetype for community health facilities across low-income markets in Africa and South Asia.
| Leading Market Players |
|---|
| Bayer AG |
| AbbVie Inc. |
| CooperSurgical Inc. |
| Merck & Co. |
| DKT International |
| EUROGINE |
| Prosan International BV |
| HLL Lifecare Limited |
| Pregna International Limited |
| Others |
Supply & Pricing Matrix
WHO prequalification requirements gate qualified supply and premium-tier pricing access for manufacturers seeking entry into donor-funded procurement programs across Africa and South Asia. Copper wire sourcing from Chilean and Peruvian smelters anchors input cost structures for non-hormonal devices, while EMA MDR compliance costs compress margins for European hormonal IUD producers.
Pricing Analysis
Warranty and insertion training bundling separates premium hormonal IUD positioning from unbundled copper device procurement in public health tenders. Three-tier pricing structure across premium, standard, and economy levels reflects FDA versus WHO prequalification status and domestic versus imported manufacturing origin. Price differentiation hinges on therapeutic indication breadth and post-market surveillance data maturity. Cost compression in economy-tier copper IUDs intensifies as Indian domestic manufacturers expand capacity for government program supply. Family planning centers in sub-Saharan Africa exhibit highest price sensitivity; gynecology clinics in Germany and the United Kingdom demonstrate lowest sensitivity due to private insurance coverage.
Supply Chain Analysis
Reverse logistics for device explants and copper recovery remain underdeveloped, with most spent IUDs entering general medical waste streams rather than material reclamation. Raw material supply concentrates in Chile, Peru, and China for copper wire, polymer resins, and nitinol alloys respectively. Component dependencies rest on specialized extrusion equipment for polyethylene frames and precision winding machinery for copper coil production. Single-source vulnerability in Chilean smelter capacity exposes non-hormonal manufacturers to commodity price volatility. Distribution runs through government health program tenders for volume, medical device distributors for clinic supply, and telehealth-integrated platforms for replacement cycles in metropolitan markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Backward integration into copper wire drawing and polymer compounding represents the critical vertical-integration race as manufacturers seek margin protection against raw material volatility and regulatory compliance cost inflation.
For Market Incumbents: To counter subdermal contraceptive implant substitution in youth-focused family planning programs, Bayer AG and CooperSurgical should deepen backward integration into nitinol alloy sourcing and expand insertion training academy networks across sub-Saharan Africa. Certification investment for WHO prequalification renewal and EMA MDR compliance must absorb regulatory resource allocation to defend tender eligibility. For New Entrants and Emerging Players: Frameless copper IUD designs utilizing anchor-based insertion systems offer a technology-first wedge into nulliparous patient segments underserved by conventional T-shaped platforms. Brazil's SUS expansion in Northeast and North regions presents the most penetrable geography for copper device distribution partnerships. Telehealth-integrated replacement cycle coordination provides the optimal go-to-market angle for metropolitan insured populations. For Investors and Strategic Acquirers: WHO prequalification status changes for legacy hormonal devices are the leading indicator that vendor panel consolidation will accelerate across donor-funded programs. Mid-scale manufacturers with established CE marking and post-market surveillance infrastructure offer the strongest acquisition profile for portfolio diversification. Practitioners should monitor EUDAMED registration delays and periodic safety update report compliance gaps for early signals of competitive displacement.| Strategic Initiative | Industry Significance |
|---|---|
| WHO Prequalification Pathway | Opens bulk tender access across Gavi and UNFPA procurement programs in priority countries. |
| Backward Integration into Copper Wire | Captures margin from Chilean smelter volatility and secures supply for high-volume public tenders. |
| Telehealth Platform Partnership | Bypasses clinic distribution bottlenecks for replacement cycles among insured urban populations. |
| Insertion Training Academy Network | Addresses skilled provider shortages limiting deployment velocity in sub-Saharan Africa. |
| Frameless Device Portfolio Expansion | Targets nulliparous segments with customized uterine cavity conforming configurations. |
Research Methodology
Independent corroboration across regulatory filings, procurement tender databases, and copper trade statistics underwrites the qualitative findings in this study. Primary interviews with family planning program directors, gynecology clinic procurement managers, biomedical engineers, and medical device regulatory affairs specialists combined with secondary validation from FDA 510(k) and PMA databases, WHO prequalification lists, EUDAMED registrations, and Indian CDSCO import records. Bottom-up device shipment analysis and top-down healthcare expenditure triangulation anchored volume and value estimates.
Rate-of-change decomposition across product type, application, end user, and distribution channel dimensions structured the analytical framework throughout the projection horizon. CAGRs derived from regression analysis against family planning program budget trajectories and contraceptive prevalence rate shifts. Modeled inputs included WHO prequalification approval timelines, EMA MDR transition deadlines, and national health insurance reimbursement classification changes.
Several conditions sit outside the modeled scope, including abrupt regulatory pathway modifications, copper commodity price shocks, and contraceptive technology substitution accelerants. Forecasts reflect documented assumptions regarding procurement tender continuity and insertion training capacity expansion. Practitioners should monitor WHO prequalification panel revisions and subdermal implant program scale-up rates for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Intubation Tubes Market
Medical Devices
Ankle Syndesmosis Treatment Devices Market
Medical Devices
Global Diagnostic Catheter Market
Medical Devices
Occlusion Microcatheter Market
Medical Devices
Clot Management Devices Market
Medical Devices
Global Artificial Organ and Bionic Implants Market
Medical Devices
3D-Printed Maxillofacial Implants Market
Medical Devices
Australia Spinal Surgery Devices Market
Medical Devices
Global Electrosurgery Generator Market
Medical Devices
Nanomedical Devices Market
Medical Devices
Electric Handpiece Market
Medical Devices
Global Artificial Pancreas Device System Market
Medical Devices
Transcutaneous Oximetry Systems Market
Medical Devices
US Stethoscope Market
Medical Devices
Spinal Machined Bone Allograft Market
Medical Devices
Chordal Suture Systems Market