
 Middle East and Africa Medical Device Reprocessing Market | 2026-2036
Middle East and Africa Medical Device Reprocessing Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Medical Device Reprocessing Market Foresight
Multi-source outsourcing of sterilization services is consolidating across the Middle East and Africa as hospital groups seek economies of scale. Stryker Corporation leverages its established Gulf distribution infrastructure to anchor reprocessing contracts with ministry-of-health networks. Medline Industries competes through direct sourcing relationships with private hospital chains in South Africa and Nigeria. Cardinal Health differentiates by bundling reprocessing logistics with its existing medical-surgical supply agreements.
Medical device reprocessing encompasses the cleaning, functional testing, repackaging, and sterilization of pre-used devices to render them suitable for subsequent clinical application, typically validated through biological indicator testing and sterility assurance level verification. The practice reduces per-procedure supply costs while maintaining safety equivalence to original devices in catheter and endoscope applications. Steam sterilization dominates the technology landscape due to its compatibility with metallic surgical instruments and established validation protocols, while hydrogen peroxide plasma systems represent the fastest-growing segment as facilities adopt low-temperature methods for heat-sensitive endoscopes. On-premise delivery mode occupies the largest share of installed capacity, though hybrid models combining centralized offsite processing with satellite sterilization units are gaining traction among multi-hospital systems seeking operational flexibility.
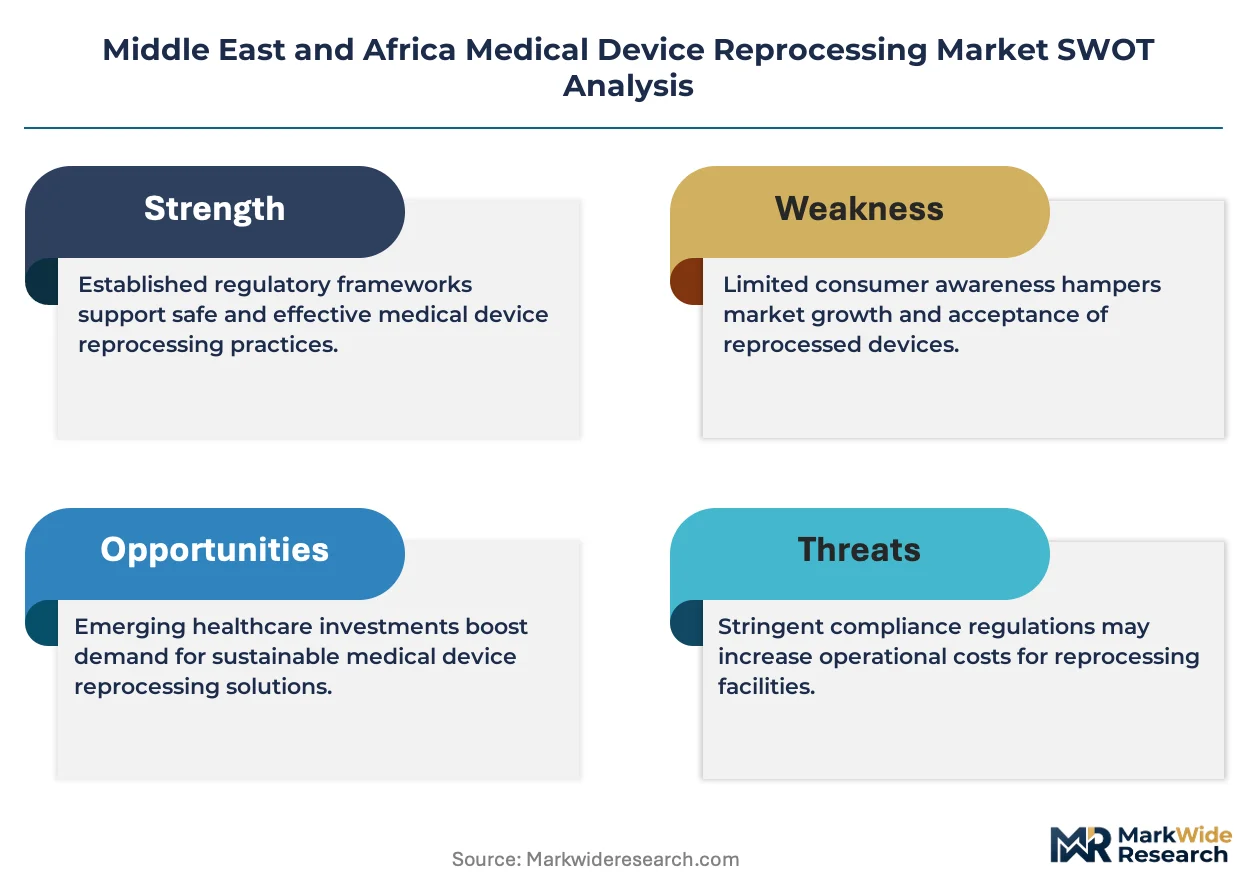
Saudi Food and Drug Authority and South African Health Products Regulatory Authority frameworks govern reprocessing quality systems, with both agencies requiring ISO 13485 certification and adverse-event reporting that shapes vendor qualification timelines. The UAE's Ministry of Health and Prevention aligns with GCC standardization initiatives for single-use device reprocessing, creating a regional compliance baseline that multinational suppliers must satisfy. Stakeholders should monitor how evolving national sterilization guidelines and hospital accreditation standards will reshape capital deployment priorities across the forecast horizon.
Market Dynamics
Centralized procurement mandates across Gulf Cooperation Council hospital networks are compressing vendor qualification timelines and forcing reprocessing service providers to consolidate quality management systems under unified ISO 13485 certifications.
Growth Catalysts
- SFDA sterilization validation protocols:Saudi Food and Drug Authority requirements for biological indicator testing create standardized entry barriers that favor established reprocessing operators with validated quality systems.
- Cardiovascular catheter demand:Government hospital networks in Saudi Arabia and the United Arab Emirates are expanding catheter reprocessing programs to manage procedural volume growth without proportional supply budget expansion.
- Hydrogen peroxide plasma adoption:Heat-sensitive endoscope reprocessing is accelerating facility upgrades to low-temperature sterilization methods that extend device lifecycle economics.
Market Restraints
- Ethylene oxide supply volatility:Input cost fluctuations for sterilization gas concentrate reprocessing margin pressure on independent service operators lacking long-term chemical supply contracts.
- South African compliance elevation:South African Health Products Regulatory Authority enforcement of adverse-event reporting extends vendor qualification timelines beyond eighteen months for new market entrants.
- Single-use device substitution:Original equipment manufacturers are deploying polymer innovations that render certain catheter categories technically non-reprocessable under current validation protocols.
Strategic Opportunities
- Nigerian private hospital chains:Direct sourcing relationships with multi-facility groups in Lagos and Abuja remain underpenetrated by certified reprocessing vendors despite rising surgical volumes.
- Hybrid delivery models:Multi-hospital systems are piloting satellite sterilization units that combine centralized offsite processing with on-demand regional capacity.
- GCC standardization alignment:UAE Ministry of Health and Prevention participation in Gulf Cooperation Council harmonization initiatives creates regulatory tailwinds for vendors with existing Saudi or Emirati certifications.
Industry Challenges
- ISO 13485 auditor scarcity:Certification body capacity constraints in the Middle East and Africa extend quality management system validation timelines for reprocessing startups.
- Legacy steam infrastructure integration:Hospital facilities with dated sterilization equipment face capital reconfiguration costs when adopting hydrogen peroxide plasma systems for heat-sensitive device categories.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Medical Device Reprocessing Market |
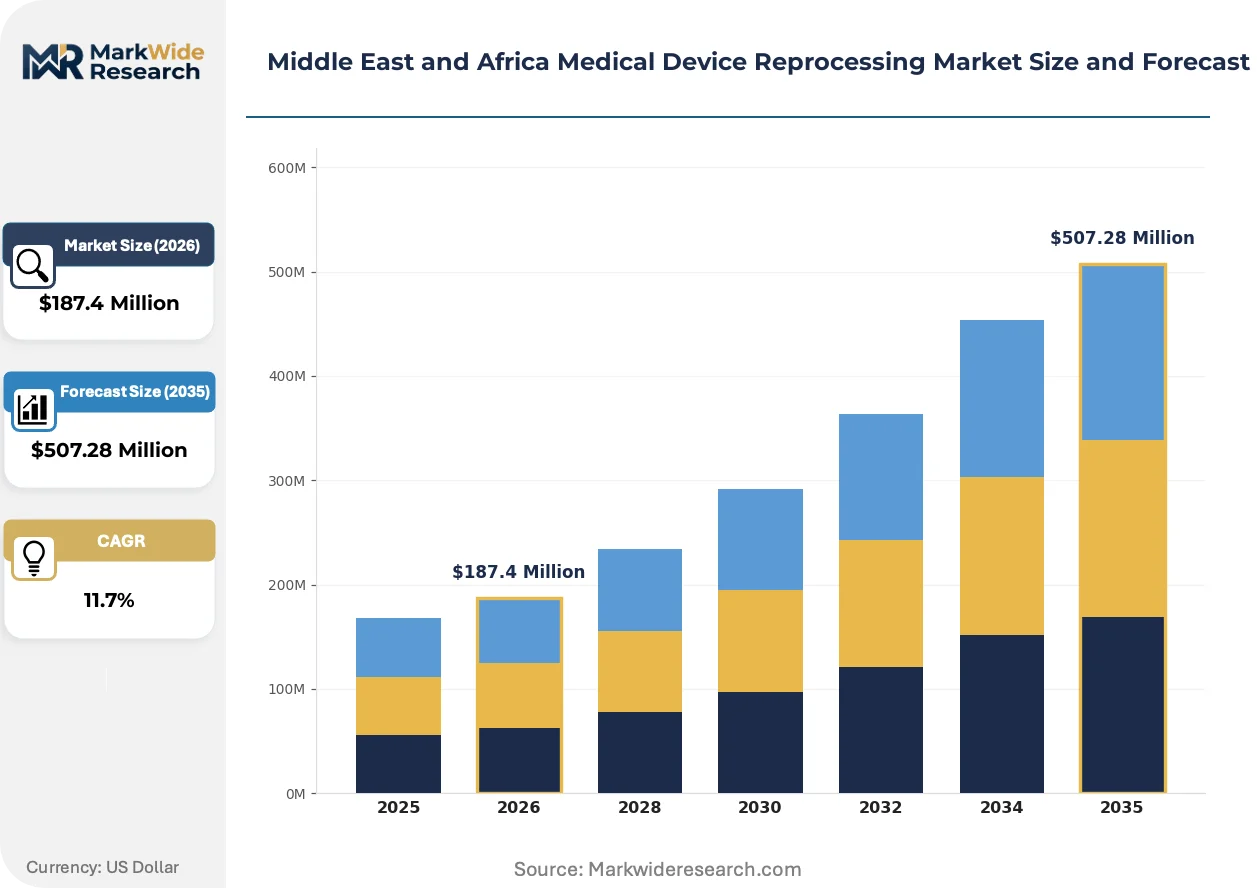
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $507.28 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Surgical Instruments, Endoscopes, Catheters, Diagnostic Devices Delivery Mode: On-premise, Offsite, Hybrid, Mobile End User: Hospitals, Ambulatory Surgical Centers, Clinics, Laboratories Technology: Steam Sterilization, Ethylene Oxide Sterilization, Hydrogen Peroxide, Plasma Sterilization |
| Companies Covered | Stryker Corporation, Medline Industries, Inc., Johnson & Johnson, Cardinal Health, STERIS, Getinge AB, Arjo, NEScientific, Vanguard AG, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Medical Device Reprocessing Market Shifts & Advancements
Reprocessing technology architectures are fragmenting as facilities pursue operational flexibility through distributed sterilization capacity rather than centralized monolithic systems.
Modular hydrogen peroxide plasma sterilizers are modularizing reprocessing workflows by enabling discrete low-temperature capacity deployment at satellite hospital sites. Cardiac catheterization laboratories in Dubai and Riyadh are adopting these units to reduce instrument turnaround times without central sterile supply department bottlenecks. This distributed architecture is modularizing competitive positioning by allowing mid-sized hospital groups to bypass large capital commitments to centralized reprocessing facilities.
SFDA and South African Health Products Regulatory Authority alignment with ISO 13485 quality system mandates is compressing vendor documentation requirements across the Middle East and Africa. Regulatory convergence reduces duplicate audit burdens for multinational reprocessing service providers operating across multiple national jurisdictions. Cardiovascular catheter reprocessing contracts are consolidating toward vendors with pre-existing dual-jurisdiction certifications.
Hospital procurement departments are unbundling reprocessing services from bundled medical-surgical supply agreements to negotiate direct sterilization service contracts. Ministry-of-health networks in Saudi Arabia are leading this disintermediation by establishing standalone reprocessing procurement categories with distinct technical specifications and performance metrics. This purchasing pattern shift is most visible in government hospital systems seeking transparent per-procedure cost accounting.
Middle East and Africa Medical Device Reprocessing Market Segmentation
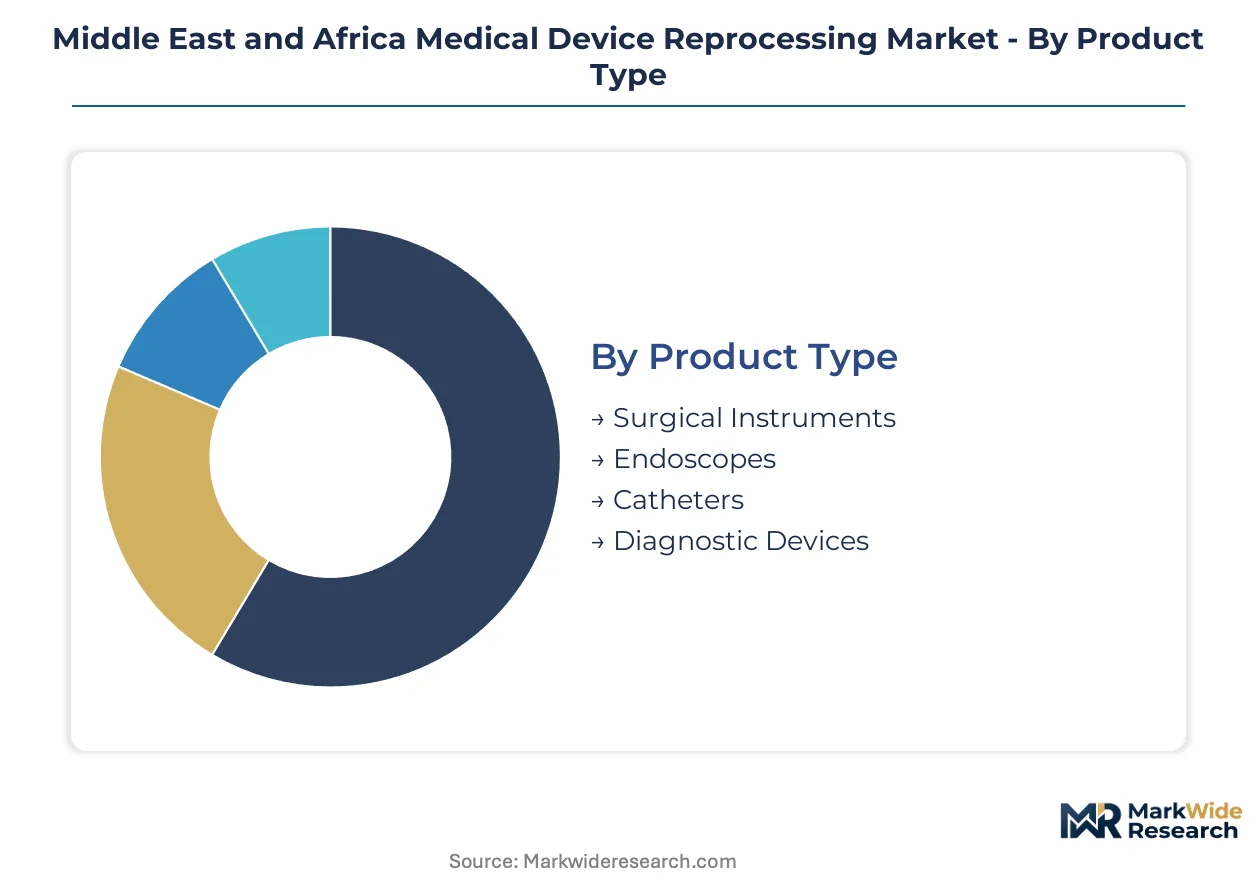
Segmentation in medical device reprocessing reveals how certification requirements, sterilization complexity, and procurement scale concentrate demand across distinct product and service categories. Understanding these divides exposes where ISO 13485 validation burdens fall heaviest and which delivery configurations offer operational flexibility.
Product Type:
Surgical instruments demand baseline sterilization validation, while endoscopes and catheters trigger extended biological indicator protocols under SFDA and South African Health Products Regulatory Authority frameworks.
- Surgical Instruments:Metallic forceps, scalpels, and retractors tolerate high-temperature steam sterilization with established validation cycles. Demand clusters in Saudi Arabia's ministry-of-health networks where centralized procurement mandates favor vendors with pre-certified quality systems for high-volume instrument categories.
- Endoscopes:Flexible gastrointestinal and bronchial scopes require low-temperature hydrogen peroxide plasma methods due to heat-sensitive optical fibers and polymer channels. Dubai's private hospital chains are expanding reprocessing capacity for these devices as procedural volumes rise without proportional capital budget expansion.
- Catheters:Cardiovascular and urological catheters dominate UAE government hospital reprocessing contracts.
- Diagnostic Devices:Ultrasound probes and electrophysiology catheters face polymer innovation barriers that limit reprocessability.
Surgical instruments sit at the top of the volume ranking, with endoscopes climbing the fastest.
Delivery Mode:
Capital deployment patterns vary sharply by delivery configuration, with on-premise installations requiring full ISO 13485 quality system audits while hybrid models distribute compliance burden across centralized and satellite facilities.
- On-premise:Hospital-based sterilization departments maintain captive reprocessing capacity with direct control over cycle validation and biological indicator testing. Saudi Arabia's government hospital networks favor this mode for cardiovascular catheter programs where procedural volume justifies dedicated infrastructure.
- Offsite:Centralized reprocessing facilities achieve economies of scale through consolidated sterilization batch processing. South African private hospital groups in Johannesburg and Cape Town are contracting with independent service operators to avoid capital expenditure on in-house plasma sterilization systems.
- Hybrid:Multi-hospital systems are piloting satellite sterilization units that combine centralized offsite processing with regional on-demand capacity.
- Mobile:Containerized sterilization units serve remote or temporary healthcare facilities lacking permanent infrastructure.
On-premise retains the largest installed base, though hybrid configurations are expanding most quickly.
End User:
Procurement scale and sterilization sophistication diverge across facility types, with hospitals absorbing full regulatory audit burdens while smaller sites rely on third-party validation.
- Hospitals:Acute care facilities with cardiac catheterization laboratories and surgical suites generate the highest reprocessing volumes. Government networks in Saudi Arabia and the UAE centralize procurement of reprocessed cardiovascular catheters under ministry-of-health contracts with distinct technical specifications.
- Ambulatory Surgical Centers:Same-day procedure facilities in Lagos and Abuja are emerging as direct sourcing targets for certified reprocessing vendors.
- Clinics:Outpatient settings typically outsource sterilization to offsite providers.
- Laboratories:Diagnostic testing facilities require specialized reprocessing for specimen collection devices.
Hospitals command the dominant revenue share, with ambulatory surgical centers gaining share fastest.
Technology:
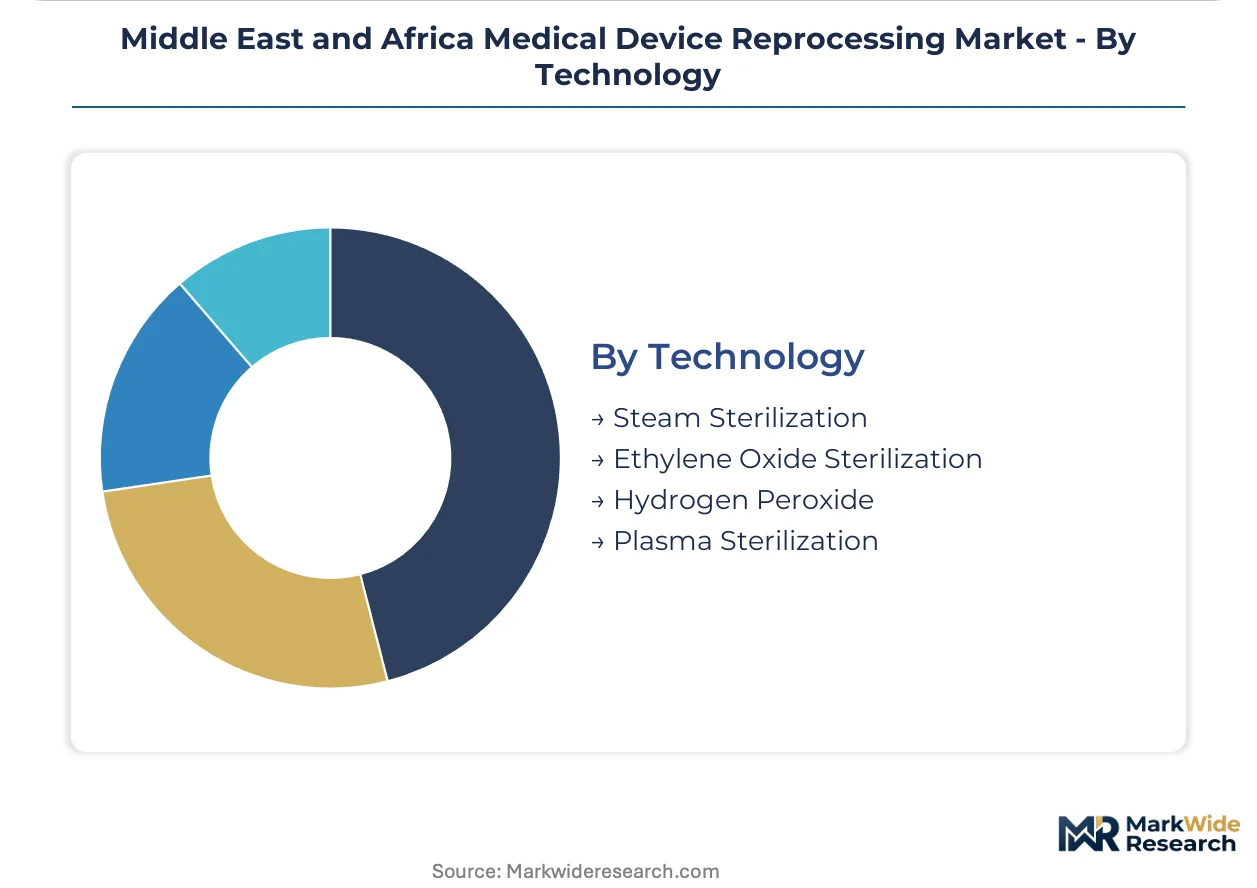
Heat tolerance of device materials dictates sterilization method selection, with metallic instruments compatible with steam while polymer-heavy categories require gas or plasma alternatives.
- Steam Sterilization:High-temperature saturated steam penetrates metallic surgical instruments with proven sporicidal efficacy. This technology dominates installed capacity across Middle East and Africa facilities due to lower capital costs and established validation protocols.
- Hydrogen Peroxide:Vaporized hydrogen peroxide achieves low-temperature sterilization compatible with heat-sensitive endoscopes and polymer catheters. Cardiac catheterization laboratories in Riyadh and Dubai are adopting modular plasma systems to reduce instrument turnaround times.
- Ethylene Oxide Sterilization:Gas-based method for temperature-sensitive devices faces supply volatility constraints.
- Plasma Sterilization:Low-temperature hydrogen peroxide plasma systems represent the steepest expansion trajectory.
Steam sterilization holds the largest installed base, with hydrogen peroxide plasma climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Gulf Cooperation Council hospital networks anchor reprocessing demand across the Middle East and Africa, with procurement centralization driving vendor consolidation toward ISO 13485-certified operators.
Saudi Arabia
Ministry-of-health cardiovascular catheter programs generate concentrated reprocessing volumes in Riyadh and Jeddah. SFDA sterilization validation protocols mandate biological indicator testing that extends vendor qualification timelines. King Faisal Specialist Hospital anchors regional reprocessing capacity for cardiac catheterization laboratories.
United Arab Emirates
Dubai's private hospital chains are expanding hydrogen peroxide plasma capacity for heat-sensitive endoscopes. MOHAP participation in GCC standardization initiatives creates regulatory alignment with Saudi frameworks. Cleveland Clinic Abu Dhabi exemplifies satellite sterilization unit deployment for procedural flexibility.
South Africa
Johannesburg and Cape Town private hospital groups are outsourcing sterilization to independent service operators. SAHPRA enforcement of adverse-event reporting extends vendor qualification beyond eighteen months. Netcare and Life Healthcare networks concentrate procurement scale for offsite reprocessing contracts.
Nigeria
Lagos and Abuja multi-facility hospital chains present underpenetrated sourcing opportunities for certified vendors. The country's national pharmaceutical regulator maintains quality system requirements that parallel ISO standards. Reddington Hospital and Lagoon Hospitals are emerging as direct contract targets for sterilization services.
Israel
Sheba Medical Center and Hadassah Medical Center drive sophisticated reprocessing demand for cardiovascular and electrophysiology devices. The Ministry of Health enforces sterilization validation protocols aligned with European MDR standards. Tel Aviv metropolitan hospitals concentrate regional procurement for catheter reprocessing programs.
Middle East and Africa Medical Device Reprocessing Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue hybrid delivery configurations and modular sterilization technologies. The vendor base concentrates around multinational medical device manufacturers with existing Gulf distribution infrastructure and independent service operators with specialized ISO 13485 certifications. Three archetypes dominate: integrated device manufacturers leveraging supply relationships, pure-play reprocessing specialists with quality system depth, and diversified healthcare distributors bundling sterilization logistics. Competitive moves center on ministry-of-health contract consolidation and satellite sterilization unit deployment for multi-hospital systems.
Among integrated device manufacturers, Stryker Corporation and Johnson & Johnson represent archetypes of supply-chain-anchored reprocessing expansion, while Cardinal Health exemplifies the distributor-bundling model. These entities occupy positions where existing hospital procurement relationships create qualification pathway advantages. Stryker Corporation and Medline Industries sit within the tier of vendors with established Gulf Cooperation Council infrastructure, though their strategic postures differ on private versus public hospital targeting. Cardinal Health anchors the logistics-integration archetype through medical-surgical supply agreement bundling.
| Leading Market Players |
|---|
| Stryker Corporation |
| Medline Industries, Inc. |
| Johnson & Johnson |
| Cardinal Health |
| STERIS |
| Getinge AB |
| Arjo |
| NEScientific |
| Vanguard AG |
| Others |
Supply & Pricing Matrix
Ethylene oxide sterilization gas costs cascade through reprocessing service tiers from chemical suppliers in Saudi Arabia and the United Arab Emirates toward ministry-of-health hospital networks and independent operators across Johannesburg and Cape Town. Input cost pass-through mechanics concentrate pricing power with established vendors holding long-term supply contracts, while spot-market-dependent independents absorb margin compression.
Pricing Analysis
Input-cost pass-through from sterilization chemicals and ISO 13485 certification audits shapes contract-based long-term pricing between reprocessing vendors and Gulf hospital procurement departments. Price differentiation separates premium-tier operators with dual-jurisdiction SFDA and SAHPRA certifications from standard-tier independents lacking adverse-event reporting infrastructure. Pricing pressure intensifies in the independent service operator segment due to ethylene oxide supply volatility and extended auditor scarcity timelines. Ministry-of-health networks exhibit lowest price sensitivity given centralized budget allocation for cardiovascular catheter programs, while Nigerian private hospital chains demonstrate highest sensitivity as they weigh reprocessing adoption against single-use device substitution.
Supply Chain Analysis
Domestic-content mandates under GCC standardization initiatives are reshaping sourcing patterns toward regional sterilization equipment distributors and in-country biological indicator manufacturers. Supply concentration rests on Germany, the United States, and Japan for hydrogen peroxide plasma sterilizer hardware, while ethylene oxide feedstock draws from Saudi petrochemical complexes and European import channels. Single-source vulnerability concentrates in specialized polymer channel components for flexible endoscope reprocessing. Distribution runs through ministry-of-health centralized procurement frameworks in Saudi Arabia and the UAE, with satellite sterilization units bypassing traditional central sterile supply department logistics in Dubai and Riyadh.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds steadily as procedural volume growth across Gulf cardiovascular catheterization laboratories outpaces proportional supply budget expansion, embedding reprocessing into permanent cost structures.
For Market Incumbents: Hedge against single-use device substitution by deepening backward integration into polymer validation testing capabilities that extend reprocessability to next-generation catheter designs. Lock in ministry-of-health contract renewals through preemptive ISO 13485 auditor capacity investments that compress qualification timelines for emerging competitors.
For New Entrants and Emerging Players: Private hospital chains in Lagos and Abuja present the most penetrable white-space target, as certified reprocessing vendors remain underrepresented despite rising surgical volumes. Direct sourcing relationships with multi-facility groups bypass entrenched distributor relationships in the Gulf. A satellite sterilization unit pilot program targeting Nigerian ambulatory surgical centers offers the clearest go-to-market angle.
For Investors and Strategic Acquirers: Consolidation pressure builds where ISO 13485 certification scarcity extends quality system validation timelines beyond eighteen months. Long-term viability over a multi-year window favors pure-play reprocessing specialists with dual-jurisdiction regulatory depth over diversified distributors lacking sterilization technical capabilities. Watch hydrogen peroxide plasma adoption rates in Dubai private hospital chains as the inflection indicator for modular technology displacement of centralized infrastructure.
| Strategic Initiative | Industry Significance |
|---|---|
| ISO 13485 Dual-Jurisdiction Certification | SFDA and SAHPRA alignment compresses audit burdens for multinational operators across Gulf and African markets. |
| Satellite Sterilization Unit Deployment | Modular plasma systems in Riyadh and Dubai cardiac catheterization laboratories reduce instrument turnaround bottlenecks. |
| Ministry-of-Health Contract Consolidation | Centralized procurement mandates in Saudi Arabia favor vendors with pre-existing cardiovascular catheter reprocessing infrastructure. |
| Biological Indicator Testing Integration | In-house validation capabilities insulate margins from third-party laboratory pricing volatility and extend service differentiation. |
| Hybrid Delivery Model Pilot Programs | Multi-hospital systems in Johannesburg and Cape Town test combined centralized offsite and regional on-demand capacity configurations. |
Research Methodology
Multiple input streams — primary interviews with biomedical engineers, hospital purchasing committee members, GPO contracts managers, and sterilization service operations directors; secondary validation through SFDA regulatory filings, SAHPRA adverse-event databases, hospital procurement contract registries, and GCC standardization initiative documentation; plus customs and trade data on sterilization equipment imports — were reconciled through bottom-up and top-down triangulation.
Data-stream reconciliation across the projection horizon applied analytical frameworks segmented by product type, delivery mode, end-user facility category, sterilization technology, and national regulatory jurisdiction. CAGRs were derived from procedural volume trajectories in cardiovascular catheterization, endoscope reprocessing adoption curves, and hydrogen peroxide plasma system installation rates. Forecast inputs incorporated ministry-of-health budget allocation patterns and ISO 13485 certification body capacity constraints.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to ethylene oxide supply disruptions, polymer innovation cycles rendering devices non-reprocessable, and evolving national sterilization guideline revisions. A small set of named triggers — SFDA auditor availability, GCC regulatory harmonization progress, and modular sterilization technology cost curves — warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Pacemaker Devices Market
Medical Devices
Global Pregnancy Detection Kits Market
Medical Devices
Digital Ureteroscopes Market
Medical Devices
Global Catheter Stabilization Devices Market
Medical Devices
Brachytherapy Catheters Market
Medical Devices
Surgical Smart Glasses Market
Medical Devices
Polyether Ether Ketone (PEEK) Interbody Devices Market
Medical Devices
Nasal Atomizer Devices Market
Medical Devices
Nerve Ablation Devices Market
Medical Devices
Global Diagnostic Catheter Market
Medical Devices
Saliva Collection Devices Market
Medical Devices
Handheld Red Light Therapy Device Market
Medical Devices
United Kingdom General Surgical Devices Market
Medical Devices
Active Wheelchair Market
Medical Devices
Manometry System Market
Medical Devices
Defibrillator Pads Market