
 Steam Inhaler Devices Market | 2026-2036
Steam Inhaler Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Steam Inhaler Devices Market Analytics
Modularization of steam inhaler systems into platform bases with swappable medication chambers is pivoting buyer choice toward customizable home-care configurations. OMRON Healthcare leverages its diagnostic device ecosystem to cross-sell inhaler peripherals through pharmacy channels. Guardian Technologies anchors its position in ultrasonic-enabled tabletop units for allergy management. MABIS Healthcare competes on value-engineered portable designs distributed through mass retail.
A steam inhaler device is an electrically powered apparatus that heats water to generate thermally aerosolized vapor, typically operating at temperatures between 43°C and 48°C with particle sizes exceeding 5 microns, designed to deliver humidified air directly to the upper and lower respiratory tract for therapeutic relief. Portable inhalers lead unit volume in direct-to-consumer channels where travel-sized formats address mobility-constrained patients, while combination devices integrating nebulizer functionality command premium positioning in clinical procurement. Ultrasonic technology segments attract R&D investment for quieter operation, though steam generation remains dominant in pediatric applications where simplicity overrides feature density.
FDA 510(k) premarket notification requirements shape device classification and clinical validation burdens for US market entry, while EU MDR technical documentation mandates strain conformity assessment timelines for CE-marked products. ISO 13485 quality management certification operates as a baseline procurement filter for hospital and clinic tenders across OECD markets. Stakeholders must monitor evolving harmonization between FDA and EU MDR clinical evidence standards to avoid duplicative testing expenditures that compress margins on mid-tier product lines.
Market Dynamics
Modular platform architectures are fragmenting procurement decisions across home healthcare and clinical settings, as buyers prioritize swappable medication chambers over fixed-format devices. This structural shift compresses replacement cycles and elevates software-enabled service contracts as margin anchors.
Growth Catalysts
- FDA 510(k) Clearance Pathway:The streamlined premarket notification process for Class II medical devices accelerates US market entry timelines for steam inhaler manufacturers. This regulatory efficiency reduces clinical validation burdens relative to PMA pathways.
- Home Healthcare Infrastructure:Chronic respiratory patient management is migrating from acute care facilities to residential settings, creating sustained equipment demand. Reimbursement coverage for home-use respiratory equipment in Germany, Japan, and the United States validates this shift.
- Ultrasonic Technology Integration:Quieter operation profiles are attracting R&D investment from manufacturers targeting sleep-sensitive applications. Pediatric segments particularly value reduced acoustic signatures during nighttime therapy sessions.
Market Restraints
- Heating Element Cost Volatility:Ceramic and metal alloy component prices fluctuate with energy-intensive manufacturing inputs, compressing margins on value-engineered portable units.
- EU MDR Conformity Assessment Strain:Technical documentation mandates and notified body capacity constraints extend CE-marking timelines, delaying European commercialization for mid-tier product lines.
- Nebulizer-Steam Hybrid Substitution:Combination devices integrating pressurized medication delivery threaten standalone steam inhaler volume in clinical procurement channels where multi-functionality commands premium positioning.
Strategic Opportunities
- Underpenetrated Rural India:Respiratory disease prevalence combined with limited specialist access creates whitespace for low-cost, durable portable inhalers distributed through pharmacy networks.
- ISO 13485-Certified Component Sourcing:Quality management certification is becoming a baseline procurement filter for OECD hospital tenders, favoring suppliers with integrated manufacturing traceability.
- Smartphone-Connected Dosing:Bluetooth-enabled adherence tracking is expanding into home-care configurations, enabling remote patient monitoring revenue streams for chronic condition management platforms.
Industry Challenges
- Biocompatibility Testing Bottlenecks:ISO 10993 material safety evaluations for medication-contact surfaces extend product development timelines and require specialized toxicology expertise.
- Legacy Hospital IT Integration:Home-use devices with connectivity features face interoperability friction with entreained electronic health record systems, complicating enterprise sales cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Steam Inhaler Devices Market |
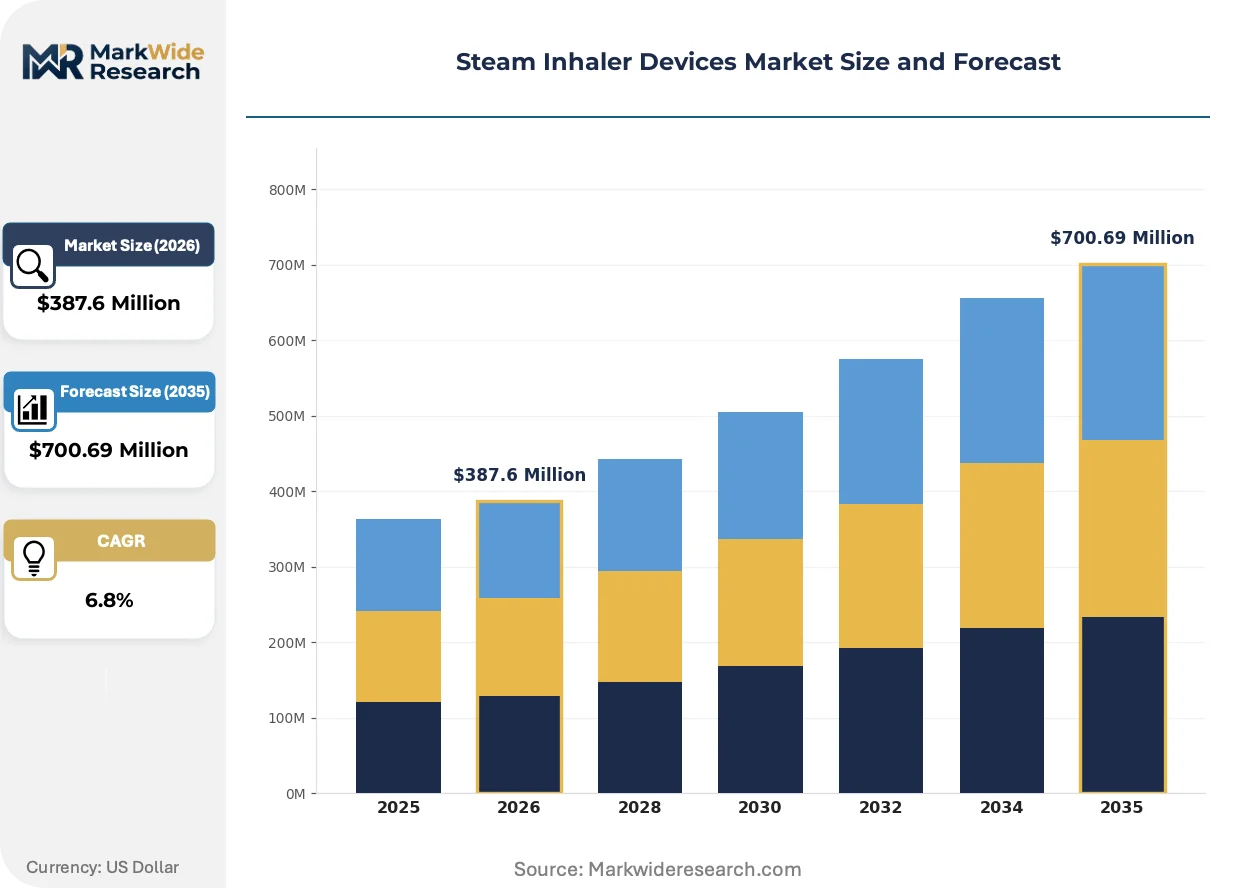
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $700.69 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Inhalers, Tabletop Inhalers, Combination Devices, Pediatric Inhalers End User: Home Users, Hospitals, Clinics, Rehabilitation Centers Application: Respiratory Therapy, Sinus Relief, Cold Treatment, Allergy Management Technology: Ultrasonic Technology, Steam Generation, Heat Exchange, Microchip-based |
| Companies Covered | Aura Medical, Dr. Dennis Gross Skincare, MABIS Healthcare, OMRON Healthcare, Conair Corporation, Crane USA, Guardian Technologies, PARI Medical Holding, Pure Daily Care, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Steam Inhaler Devices Market Evolving Landscape
Device intelligence and platform modularity are converging to redefine how respiratory therapy equipment is specified, procured, and serviced across patient care settings.
Ultrasonic vapor generation is expanding into premium home-care segments where acoustic comfort determines purchase decisions. Sleep-disturbed patients and pediatric caregivers are adopting these quieter units at rates exceeding steam-based alternatives. The technology is expanding into allergy management and wellness applications previously served by passive humidification, compressing addressable market boundaries between therapeutic and comfort categories.
EU MDR technical documentation requirements are reshaping clinical evidence standards for CE-marked respiratory devices. Stricter post-market surveillance obligations and notified body audit intensity are elevating compliance costs for mid-tier manufacturers. Class IIa inhaler devices face extended conformity assessment timelines, prompting some suppliers to prioritize FDA 510(k) clearance as a faster path to revenue generation.
Direct-to-consumer pharmacy channels are displacing durable medical equipment distributors for portable inhaler procurement. Mobility-constrained patients increasingly specify travel-sized formats through retail networks rather than clinical referral pathways. This behavioral shift is most visible in Japan and Germany, where aging demographics and pharmacy reimbursement parity accelerate self-directed equipment acquisition.
Steam Inhaler Devices Market Segmentation
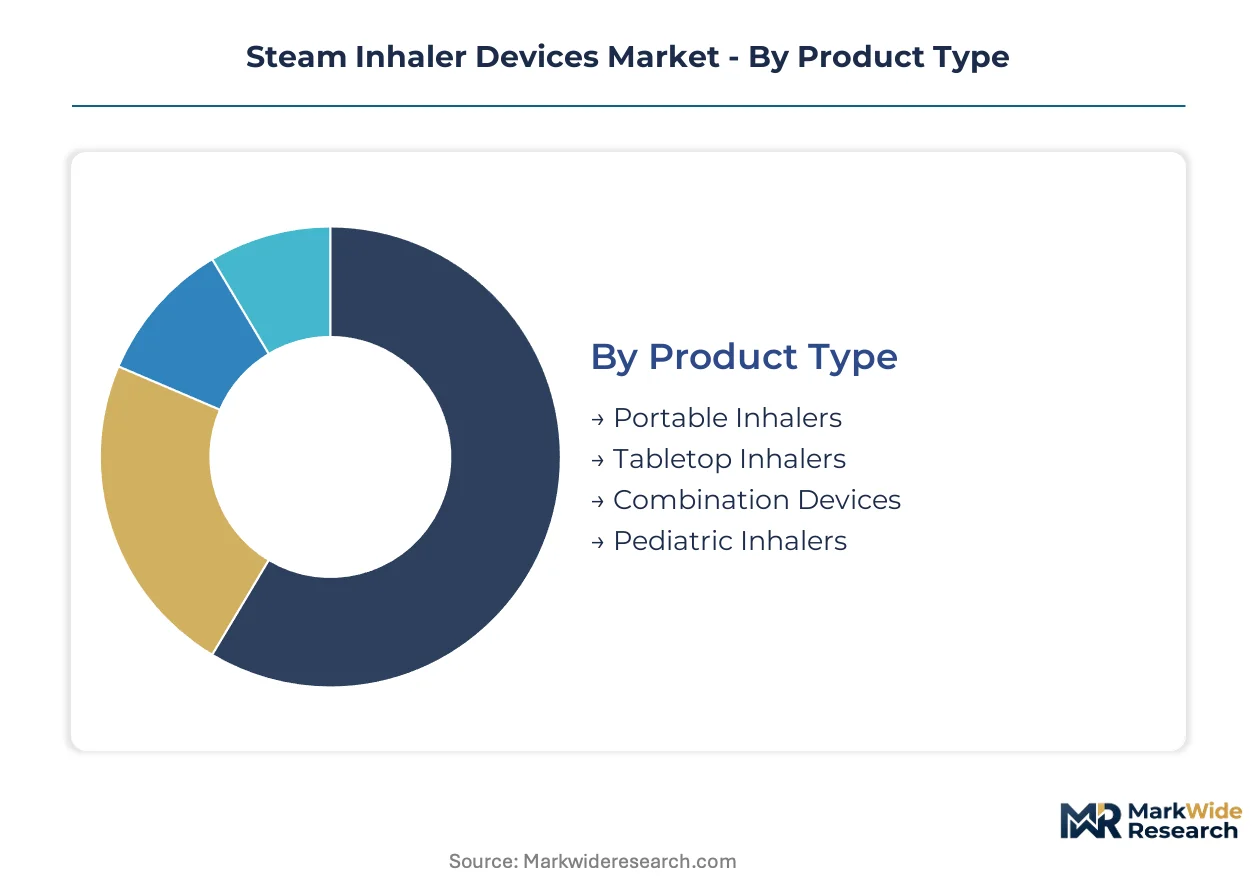
Segmentation in steam inhaler devices reveals how procurement splits between standalone home-use units and embedded clinical systems. Manufacturers configure product lines around mobility requirements, reimbursement pathways, and integration depth with respiratory care protocols.
Product Type:
Standalone portable units dominate direct-to-consumer channels where patients self-select travel formats, while embedded tabletop systems anchor clinical procurement tied to facility infrastructure.
- Portable Inhalers:Battery-powered or corded compact units weighing under 500 grams, engineered for mobility-constrained patients requiring therapy during travel. Demand concentrates in Japan and Germany where aging demographics and pharmacy reimbursement parity accelerate self-directed acquisition through retail networks.
- Tabletop Inhalers:Stationary units with larger water reservoirs and sustained operation cycles, typically deployed in residential settings with dedicated therapy spaces. Home healthcare infrastructure expansion in the United States validates sustained equipment demand for chronic respiratory patient management.
- Combination Devices:Integrated nebulizer-steam systems offering pressurized medication delivery alongside thermally aerosolized vapor.
- Pediatric Inhalers:Simplified interfaces with reduced acoustic signatures and child-safe temperature regulation.
Portable inhalers lead volumes today; combination devices are gaining share fastest in clinical procurement channels.
End User:
Cost tier stratification separates premium clinical systems from economy home-use configurations, with reimbursement eligibility determining effective price floors across patient segments.
- Home Users:Individual patients acquiring devices through retail pharmacy, durable medical equipment suppliers, or direct-to-consumer channels. FDA 510(k) clearance pathways accelerate US market entry for manufacturers targeting this segment with Class II medical device classifications.
- Hospitals:Acute care facilities procuring through group purchasing organizations with ISO 13485 quality management certification as baseline tender filters. EU MDR technical documentation mandates strain conformity assessment timelines for CE-marked products in European hospital systems.
- Clinics:Outpatient respiratory therapy centers requiring portable units for patient demonstration and loaner programs.
- Rehabilitation Centers:Post-acute facilities integrating inhaler therapy into pulmonary rehabilitation protocols.
Home users anchor volume today; hospitals are expanding fastest as chronic care migrates from acute settings.
Application:
Application segmentation tracks how therapeutic indications shape device specifications, with sinus and allergy management driving ultrasonic technology adoption while respiratory therapy maintains steam generation dominance.
- Respiratory Therapy:Primary indication for chronic obstructive pulmonary disease, asthma, and bronchitis management requiring sustained humidification. Steam generation technology retains preference in pediatric applications where operational simplicity overrides feature density.
- Sinus Relief:Targeted upper respiratory tract humidification for congestion and pressure relief, often requiring higher temperature vapor output. Ultrasonic technology segments attract R&D investment for quieter operation profiles in sleep-sensitive applications.
- Cold Treatment:Symptomatic relief for viral upper respiratory infections through short-duration therapy sessions.
- Allergy Management:Seasonal and perennial allergen response mitigation, expanding into wellness applications previously served by passive humidification.
Respiratory therapy leads volumes today; allergy management is climbing the fastest as boundaries compress between therapeutic and comfort categories.
Technology:
Technology maturity curves separate established steam generation from emerging ultrasonic platforms, with microchip-based systems representing the frontier of connected device integration.
- Ultrasonic Technology:Piezoelectric transducers generating vapor through high-frequency mechanical oscillation rather than thermal heating, enabling near-silent operation. Sleep-disturbed patients and pediatric caregivers in Japan and Germany adopt these units at rates exceeding steam-based alternatives for nighttime therapy sessions.
- Steam Generation:Resistive heating elements raising water temperature to 43°C-48°C for thermally aerosolized vapor with particle sizes exceeding 5 microns. Pediatric segments particularly value the operational transparency and failure-mode predictability of heated systems.
- Heat Exchange:Energy recovery systems improving thermal efficiency in sustained-use clinical configurations.
- Microchip-based:Embedded controllers enabling Bluetooth connectivity, dosing adherence tracking, and remote patient monitoring integration.
Steam generation leads volumes today; ultrasonic technology is expanding most quickly in premium home-care segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The steam inhaler device industry traces its commercial origins to post-war Japan and Germany, where precision manufacturing capabilities first enabled mass production of electrically powered respiratory therapy equipment for home use.
United States
Medicare reimbursement for home-use respiratory equipment drives sustained procurement through durable medical equipment channels. FDA 510(k) premarket notification requirements shape device classification timelines for Class II medical devices entering the market. Minneapolis-St. Paul anchors distribution infrastructure for Midwest healthcare networks serving chronic obstructive pulmonary disease patients.
Germany
Aging demographics and statutory health insurance coverage for home-care respiratory equipment validate self-directed acquisition patterns. EU MDR technical documentation mandates extend conformity assessment timelines for CE-marked products in European hospital systems. Baden-Württemberg hosts precision heating element suppliers serving mid-tier portable inhaler manufacturers.
Japan
Pharmacy reimbursement parity accelerates retail channel displacement of clinical referral pathways for portable units. METI standards for electrical medical devices establish baseline safety requirements for domestic market entry. Osaka-Kobe manufacturing clusters produce ultrasonic transducer components for premium sleep-sensitive applications.
India
Respiratory disease prevalence combined with limited specialist access creates whitespace for low-cost portable inhalers distributed through pharmacy networks. CDSCO medical device regulations govern import and domestic manufacturing compliance for respiratory therapy equipment. Gujarat pharmaceutical manufacturing corridors incubate component suppliers targeting price-sensitive rural markets.
United Kingdom
NHS community respiratory services expansion supports home-based chronic disease management equipment procurement. MHRA post-Brexit regulatory divergence from EU MDR creates parallel compliance pathways for device manufacturers. Greater Manchester health innovation clusters pilot remote patient monitoring integration with connected inhaler platforms.
Steam Inhaler Devices Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification depth and channel access, with ISO 13485-certified specialists commanding tender premiums in hospital procurement while value-engineered portable units compete on retail shelf price. The vendor base stratifies into three tiers: diagnostic device ecosystem extenders, ultrasonic technology specialists, and mass-market portable fabricators. Consolidation pressure concentrates among mid-tier players facing EU MDR compliance cost escalation. Dominant competitive moves include strategic partnerships with pharmacy chains and portfolio diversification into combination nebulizer-steam systems.
Within the diagnostic ecosystem tier, OMRON Healthcare leverages cross-selling infrastructure through pharmacy channels. MABIS Healthcare and Guardian Technologies occupy positions across the portable-to-tabletop spectrum, with the former representing value-engineered mass retail distribution and the latter exemplifying ultrasonic-enabled premium positioning for allergy management applications.
| Leading Market Players |
|---|
| Aura Medical |
| Dr. Dennis Gross Skincare |
| MABIS Healthcare |
| OMRON Healthcare |
| Conair Corporation |
| Crane USA |
| Guardian Technologies |
| PARI Medical Holding |
| Pure Daily Care |
| Others |
Value Network & Pricing Analysis
Captive integration of heating element manufacturing anchors supply positions for premium-tier steam inhaler producers while insulating them from ceramic and metal alloy cost volatility that erodes margins at the portable-unit tier. This vertical control over thermal components translates directly into pricing power across pharmacy and hospital procurement channels where ISO 13485 certification operates as a non-negotiable tender filter.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates ultrasonic-enabled tabletop units from basic steam-generation portables and value-engineered mass-market alternatives. Price differentiation rests on FDA 510(k) clearance status and acoustic performance specifications, with certification-bearing devices commanding tender premiums in US hospital systems. Cost compression in the economy tier intensifies because ceramic heating element prices fluctuate with energy-intensive manufacturing inputs. Home users through direct-to-consumer channels exhibit highest price sensitivity, while hospital purchasing committees demonstrate lowest sensitivity given reimbursement coverage for respiratory equipment.
Supply Chain Analysis
Regional distribution centers in Minneapolis-St. Paul, Baden-Württemberg, and Osaka-Kobe anchor hub-and-spoke patterns serving North American, European, and Asia-Pacific demand clusters respectively. Manufacturing concentrates in China for value-engineered portable units, Germany for precision heating elements, and Japan for ultrasonic transducer components. Raw material dependencies include ceramic substrates, piezoelectric crystals, and medical-grade polymers. Single-source vulnerability in piezoelectric crystal supply from Japanese producers presents structural risk. Distribution runs through pharmacy retail networks displacing durable medical equipment distributors for portable inhaler procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers geographic-arbitrage value through divergent regulatory timelines: FDA 510(k) clearance pathways accelerate US revenue generation while EU MDR conformity assessment delays create temporary supply gaps that agile entrants can exploit.
For Market Incumbents: Deepen backward integration into ceramic heating element production to defend margin position against commodity cost volatility threatening value-engineered portable lines. Prioritize ISO 13485 certification maintenance as hospital procurement filters tighten, and expand software-enabled service contracts to anchor recurring revenue as modular platform architectures compress hardware replacement cycles. For New Entrants and Emerging Players: Direct-to-consumer pharmacy channels in rural India offer the most penetrable whitespace, combining respiratory disease prevalence with limited specialist access and pharmacy network density. Target low-cost durable portable designs distributed through these networks, leveraging CDSCO regulatory pathways that present lower compliance burdens than FDA or EU MDR routes for initial market entry. For Investors and Strategic Acquirers: Roll-up economics work for mid-tier ISO 13485-certified manufacturers because EU MDR compliance cost escalation is forcing consolidation among players lacking scale to absorb extended conformity assessment timelines. Target specialists with established notified body relationships and hospital tender track records. Watch FDA 510(k) clearance velocity versus EU MDR approval delays as the inflection indicator for geographic revenue mix shifts.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission | Accelerates US market entry timelines relative to PMA pathways for Class II device classification. |
| CE Marking Pathway | EU MDR technical documentation mandates strain conformity assessment capacity for European commercialization. |
| Hospital System Partnership | GPO contracts with ISO 13485 requirements anchor procurement filters in acute care settings. |
| Software Companion Development | Bluetooth-enabled adherence tracking enables remote patient monitoring revenue streams for chronic respiratory management. |
| Reimbursement Strategy | Medicare and statutory health insurance coverage in Germany and Japan validate home-care equipment demand. |
Research Methodology
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combined with secondary validation across regulatory filings and procurement databases. Primary interviews engaged hospital purchasing committees, biomedical engineers, pharmacy chain category managers, and GPO contracts managers alongside regulatory affairs specialists at notified bodies. Secondary sources incorporated FDA 510(k) premarket notification databases, EU MDR technical documentation repositories, hospital procurement contract records, and statutory health insurance reimbursement schedules. Bottom-up unit shipment estimates triangulated against top-down market value reconstructions.
Rate-of-change decomposition across the projection horizon isolates volume growth from price-mix effects and technology substitution patterns. Segmentation dimensions modeled include product type hierarchy, end-user procurement channel, therapeutic application indication, and technology platform maturity. CAGRs derive from fitted growth curves applied to base-year estimates validated against historical shipment trajectories. Industry-specific forecast inputs incorporate FDA clearance pipeline velocity, EU notified body capacity constraints, and pharmacy reimbursement parity expansion timelines.
The model assumes a particular technology adoption path; alternative pathways for ultrasonic vapor generation displacing steam-based systems would alter the outlook through accelerated premium-tier conversion and compressed replacement cycles. Forecasts reflect documented assumptions regarding regulatory harmonization progress, reimbursement policy stability, and raw material cost trajectories. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Medical Radiation Detectors Market
Medical Devices
Asia-Pacific Wearable Medical Devices Market
Medical Devices
Peripheral Guidewires Market
Medical Devices
Cervical Implants Market
Medical Devices
Capsular Tension Rings Market
Medical Devices
Infusion Pump Market
Medical Devices
Tattoo Removal Lasers Market
Medical Devices
Veterinary Radiography Flat Panel Detectors Market
Medical Devices
Global Anti-Snoring Device Market
Medical Devices
Middle East and Africa C-Arms Market
Medical Devices
Epidural Anesthesia Sets Market
Medical Devices
Minimally Invasive Neurosurgical Devices Market
Medical Devices
Retinal Surgery Devices Market
Medical Devices
Latin America Insulin Syringes Market
Medical Devices
Brazil Contraceptive Devices Market
Medical Devices
Electrophysiology Ablation Market