
 Intelligent Prosthetics Market | 2026-2036
Intelligent Prosthetics Market Size, Share, and Industry Trends Forecast 2026-2036
Intelligent Prosthetics Market Foresight
ISO 13485 certification for medical device quality management is rotating as the primary gating standard for market entry, filtering out suppliers lacking validated design controls and risk management documentation. Ottobock leverages its vertically integrated manufacturing base in Germany to sustain cost advantages across myoelectric limb production. Open Bionics competes through open-source hardware architectures that reduce per-unit component costs for pediatric bionic hands. Ossur anchors Nordic market access with specialized rehabilitation center partnerships and direct clinician training programs.
Intelligent prosthetics integrate sensor arrays, microprocessors, and actuated joints to restore or augment motor function in amputee and mobility-impaired users, with myoelectric systems detecting electromyographic signals at residual limb sites to trigger proportional grip force. The primary commercial purpose centers on restoring Activities of Daily Living performance while reducing secondary musculoskeletal complications from compensatory gait patterns. Lower limb systems currently dominate procurement volumes among Veterans Affairs and statutory insurers, though neuroprosthetics represents the fastest-expanding technology segment as peripheral nerve interface reliability improves. Exoskeletons occupy a distinct margin pool targeting spinal cord injury rehabilitation, where hospital-based rental models generate recurring revenue distinct from conventional prosthetic sales.
FDA breakthrough device designation and the EU Medical Device Regulation create divergent compliance burdens, with the former accelerating neuroprosthetic review timelines and the latter mandating clinical evidence portfolios for myoelectric limb re-certification. Germany's statutory health insurance framework, administered by the National Association of Statutory Health Insurance Funds, directly shapes reimbursement thresholds that determine which smart sensor configurations reach standard care pathways. Stakeholders must monitor whether nerve decoding algorithm performance claims trigger new FDA software-as-medical-device oversight, as this would reshape R&D resource allocation across the competitive field.
Market Dynamics
The FDA's breakthrough device designation pathway is compressing neuroprosthetic commercialization timelines while simultaneously concentrating procurement authority within Veterans Affairs healthcare systems and Germany's statutory insurance framework.
Growth Catalysts
- Myoelectric signal processing:Peripheral nerve interface reliability improvements are expanding candidacy for upper-limb prosthetic users previously excluded from powered device prescriptions.
- US Veterans Affairs procurement:Centralized purchasing through the Veterans Health Administration is creating volume commitments that justify manufacturing scale investments for advanced prosthetic systems.
- Germany's statutory reimbursement:The National Association of Statutory Health Insurance Funds maintains defined benefit catalogs that standardize access to sensor-enabled limb systems.
Market Restraints
- Premium component costs:Precision strain gauges and high-torque brushless motors in myoelectric hands concentrate supply among Japanese and German component specialists.
- Clinical validation requirements:EU Medical Device Regulation mandates updated clinical evidence portfolios for myoelectric limb re-certification, extending compliance timelines.
- Passive mechanical substitutes:Body-powered hook terminal devices retain cost advantages for manual labor applications in emerging markets.
Strategic Opportunities
- Pediatric bionic expansion:Modular socket designs accommodating growth spurts address the underserved adolescent amputee population in North American and European healthcare systems.
- Hospital rental models:Exoskeleton systems for spinal cord injury rehabilitation generate recurring revenue streams distinct from conventional prosthetic sales.
- ISO 13485 certification gaps:Suppliers lacking validated design controls face market exit, creating acquisition targets for quality-system-compliant manufacturers.
Industry Challenges
- Rehabilitation therapist training:Clinician proficiency in myoelectric socket fitting and pattern recognition calibration lags device complexity.
- Software-as-medical-device oversight:Nerve decoding algorithm performance claims risk triggering new FDA regulatory frameworks for embedded artificial intelligence.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Intelligent Prosthetics Market |
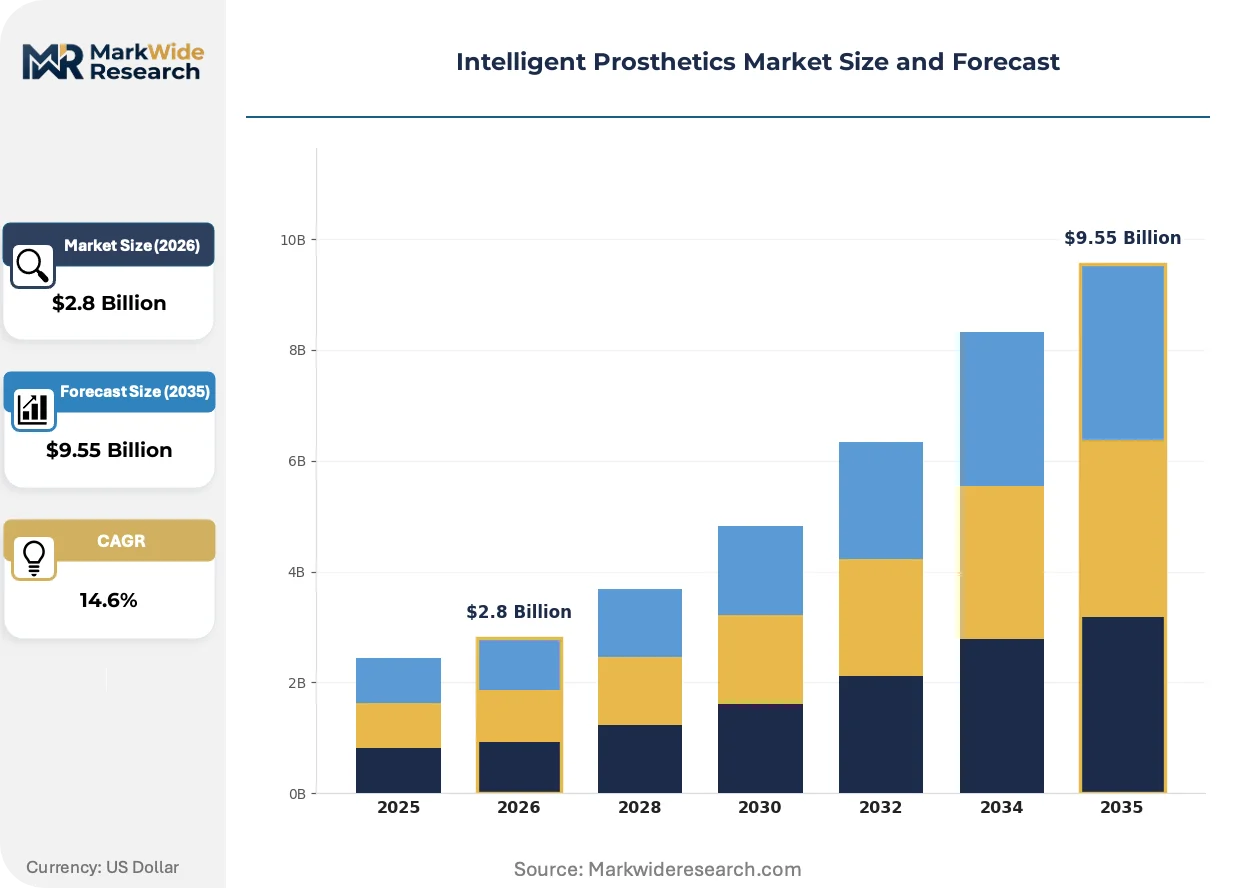
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $9.55 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Upper Limb, Lower Limb, Bionic Hands, Exoskeletons Technology: Myoelectric, Neuroprosthetics, Robotic, Smart Sensors End User: Hospitals, Rehabilitation Centers, Homecare, Fitness Facilities Application: Rehabilitation, Mobility Assistance, Cosmetic, Sports Enhancement |
| Companies Covered | Blatchford, HDT Global, Sarcos Technology and Robotics Corporation, Ekso Bionics, SynTouch, Ottobock, Touch Bionics Inc., Open Bionics, Ossur, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Intelligent Prosthetics Market Shifts & Advancements
Sensor fusion architectures and embedded machine learning are transforming prosthetic control from pre-programmed grip patterns toward adaptive intent recognition, compressing the latency between user neural signal and mechanical response.
Implantable myoelectric sensors are miniaturizing. These wireless electromyographic recording devices eliminate socket-mounted electrode arrays. Veterans Affairs rehabilitation centers are piloting the technology for transradial amputees. The shift is miniaturizing the boundary between residual limb and prosthetic hardware, enabling socket-less attachment systems.
EU Medical Device Regulation clinical evidence requirements are tightening. Manufacturers must submit post-market surveillance data for myoelectric limb re-certification. German statutory insurers are requiring this documentation for continued reimbursement eligibility, forcing suppliers to invest in longitudinal outcome studies.
Direct-to-clinic distribution is displacing traditional orthotics and prosthetics dealer networks. Manufacturers are building specialized training programs for rehabilitation center staff. This channel compression is most visible in Nordic markets, where Ossur's clinician certification programs bypass conventional distributor markups.
Intelligent Prosthetics Market Segmentation
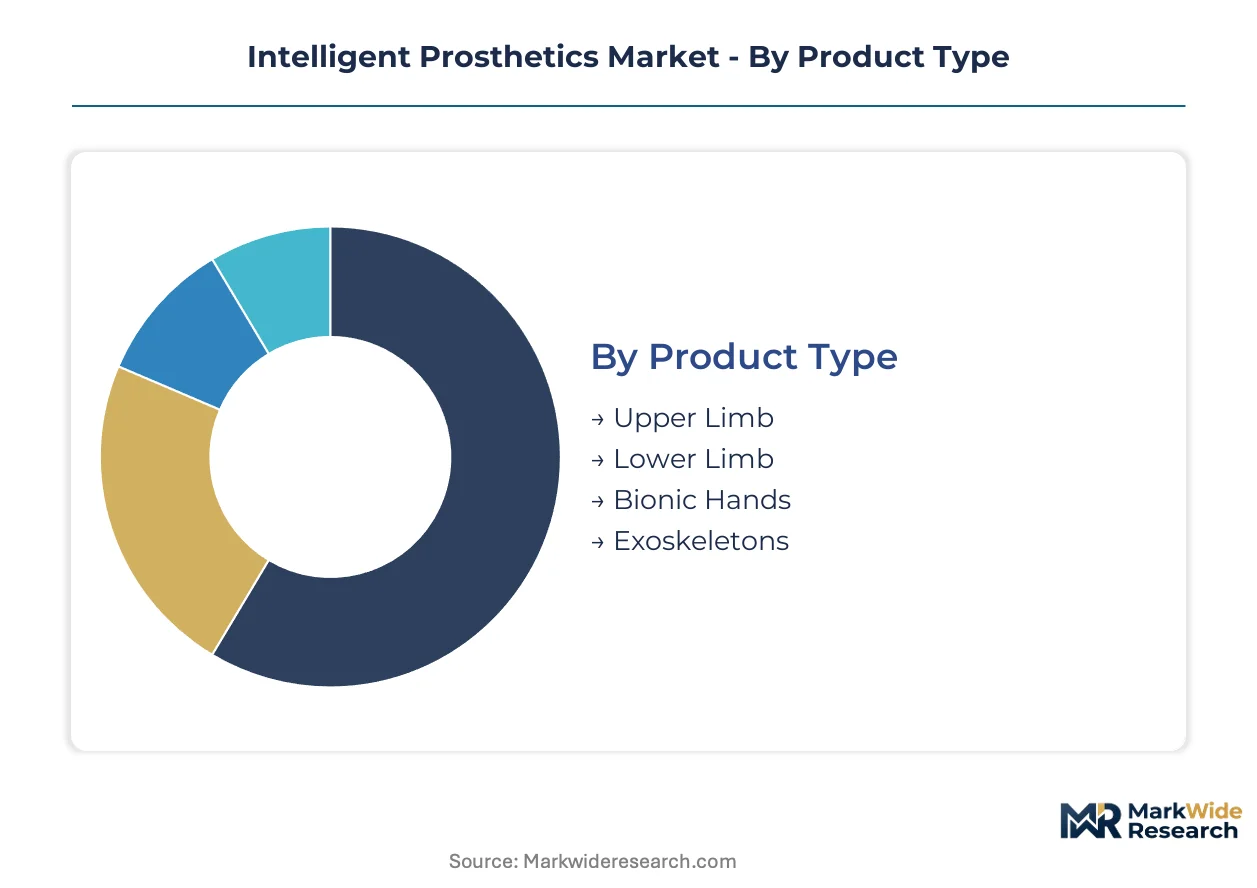
Segmentation in intelligent prosthetics reveals distinct margin architectures across limb categories, with technology tiers separating premium reimbursement pathways from volume-accessible segments. Procurement authority concentrates in institutional buyers whose technical specifications filter which configurations reach patient populations.
Product Type:
Margin pools concentrate in lower limb systems where Veterans Affairs and German statutory insurers maintain defined benefit catalogs, while exoskeletons command distinct rental economics in spinal cord rehabilitation.
- Lower Limb:Microprocessor-controlled knees and powered ankles dominate procurement volumes through centralized purchasing. Veterans Health Administration commitments justify manufacturing scale for advanced systems, though socket interface standardization lags device sophistication.
- Upper Limb:Myoelectric elbows and terminal devices detect electromyographic signals for proportional control. Demand concentrates in German manufacturing clusters where Ottobock's vertically integrated production sustains cost advantages across component sourcing.
- Bionic Hands:Multi-articulated digits with independent finger control serve transradial amputees seeking fine motor restoration.
- Exoskeletons:Powered gait orthoses for spinal cord injury generate recurring hospital rental revenue distinct from conventional prosthetic sales models.
The dominant share belongs to Lower Limb, while Exoskeletons are climbing the fastest through rehabilitation center adoption.
Technology:
Cost tiers separate FDA breakthrough-designated neuroprosthetics from established myoelectric platforms, with embedded AI triggering emerging software-as-medical-device oversight risks.
- Myoelectric:Surface electrode arrays capture residual limb muscle signals to trigger proportional grip force. German statutory reimbursement and Veterans Affairs procurement standardize access to sensor-enabled configurations in North American and European healthcare systems.
- Neuroprosthetics:Implantable peripheral nerve interfaces decode motor intent with reduced signal latency. FDA breakthrough device designation compresses review timelines for transhumeral and targeted muscle reinnervation candidates previously excluded from powered prescriptions.
- Robotic:Pre-programmed grip pattern sequencing serves cost-sensitive applications where pattern recognition calibration exceeds clinical resource availability.
- Smart Sensors:Inertial measurement units and pressure arrays enable gait phase detection for automatic joint resistance adjustment.
Myoelectric systems retain volume leadership, though Neuroprosthetics show the steepest expansion trajectory as interface reliability improves.
End User:
Application setting determines reimbursement pathway complexity, with institutional buyers filtering which smart sensor configurations reach standard care versus cash-pay segments.
- Rehabilitation Centers:Specialized fitting and training programs for myoelectric socket calibration concentrate procurement authority. Direct manufacturer-to-clinic distribution models displace traditional orthotics and prosthetics dealer networks in Nordic markets through Ossur's clinician certification programs.
- Hospitals:Acute care and post-surgical prosthetic provision operates within bundled payment frameworks. Exoskeleton rental models for spinal cord injury generate recurring revenue streams distinct from conventional device sales.
- Homecare:Remote monitoring and patient-managed maintenance programs serve rural and mobility-limited user populations.
- Fitness Facilities:Performance-oriented limb systems for athletic amputees occupy cash-pay segments outside statutory reimbursement.
Rehabilitation Centers command the dominant procurement volume, while Homecare is gaining share fastest through telehealth integration.
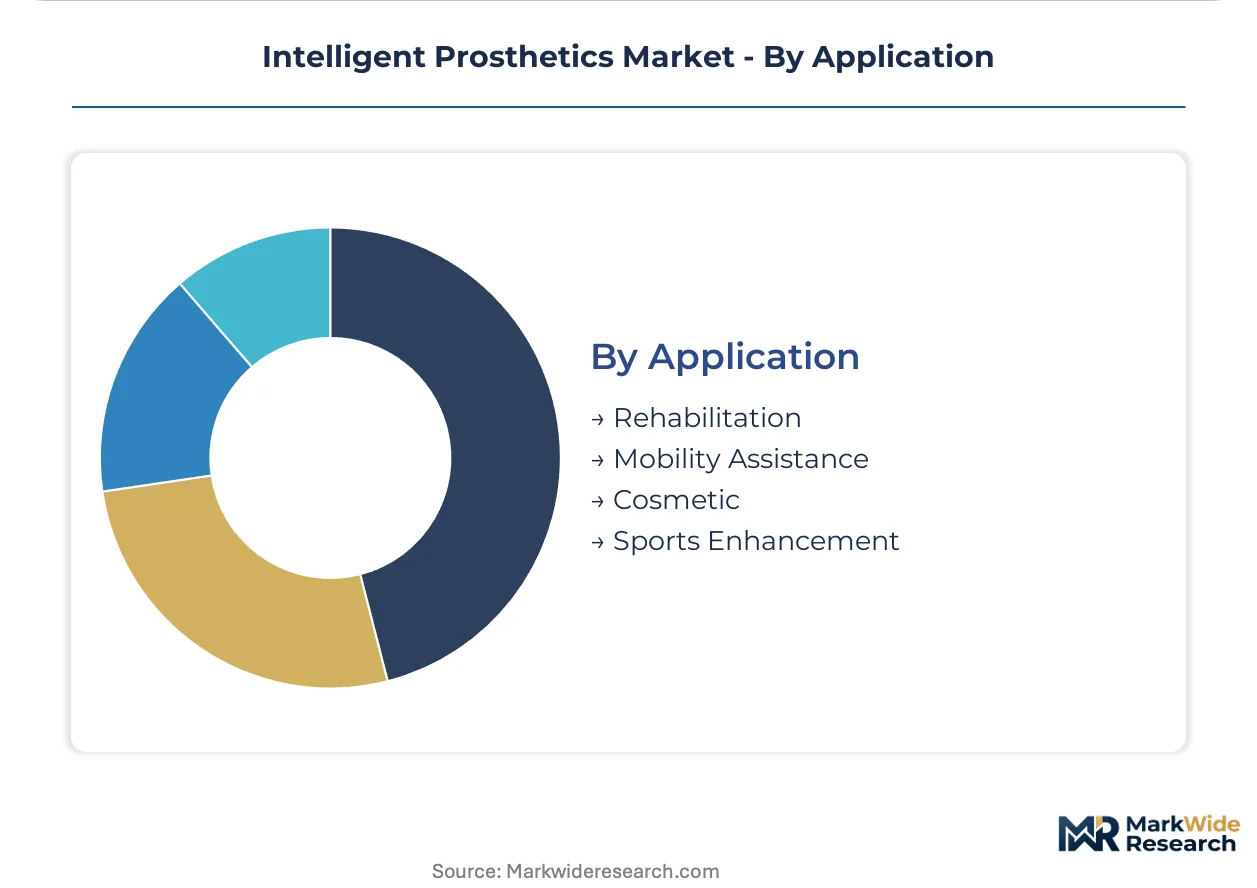
Application:
Customer type stratification separates medical necessity reimbursement from elective performance enhancement, with cosmetic applications occupying distinct regulatory and pricing frameworks.
- Rehabilitation:Post-amputation motor function restoration and gait training represent the core reimbursed indication. EU Medical Device Regulation mandates updated clinical evidence portfolios for myoelectric limb re-certification, extending compliance timelines for continued German statutory insurer eligibility.
- Mobility Assistance:Activities of Daily Living performance restoration drives lower limb system prescriptions. Secondary musculoskeletal complication prevention from compensatory gait patterns shapes clinical outcome documentation requirements.
- Cosmetic:Passive aesthetic prostheses without functional articulation serve appearance-focused user preferences.
- Sports Enhancement:Performance-optimized limb systems for competitive athletics fall outside standard reimbursement catalogs.
Rehabilitation holds the dominant share, while Mobility Assistance is expanding most quickly through aging population demand and diabetes-related amputation incidence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA breakthrough device designation and Germany's statutory reimbursement framework are concentrating procurement authority in specific national healthcare systems, creating divergent market access conditions across major economies.
United States
Veterans Affairs healthcare systems generate centralized demand for advanced prosthetic systems through the Veterans Health Administration's volume commitments. FDA's breakthrough device designation pathway compresses neuroprosthetic review timelines for transhumeral amputees. Rehabilitation centers in Pittsburgh and San Antonio pilot implantable myoelectric sensors for socket-less attachment systems.
Germany
The National Association of Statutory Health Insurance Funds maintains defined benefit catalogs that standardize access to sensor-enabled limb configurations. EU Medical Device Regulation mandates updated clinical evidence portfolios for myoelectric limb re-certification. Ottobock's vertically integrated manufacturing cluster in Duderstadt sustains cost advantages across component sourcing for myoelectric production.
Japan
PMDA regulatory frameworks govern neuroprosthetic device approvals with distinct clinical evidence requirements from Western pathways. METI industrial policy supports precision component manufacturing for strain gauges and brushless motors. Tokyo and Osaka rehabilitation centers concentrate demand for upper-limb myoelectric systems among aging amputee populations.
United Kingdom
NHS England specialized commissioning frameworks filter which smart sensor configurations reach standard care versus restricted access pathways. MHRA post-Brexit regulatory divergence from EU MDR creates parallel compliance obligations for manufacturers. London and Manchester rehabilitation hubs drive procurement for bionic hand systems among transradial amputees.
China
NMPA medical device registration requirements are tightening for imported neuroprosthetic technologies entering domestic markets. State Council healthcare reform initiatives expand rehabilitation service coverage in tier-1 cities. Beijing and Shanghai manufacturing zones host assembly operations for cost-sensitive robotic prosthetic platforms serving Asian markets.
Intelligent Prosthetics Market Competitive Landscape
Listed leaders compete with private specialists across technology tiers, with the market exhibiting moderate consolidation around established orthopedic device conglomerates and emerging venture-backed neuroprosthetic ventures. Strategic differentiation clusters around three archetypes: vertically integrated manufacturing conglomerates with captive component supply, open-source hardware disruptors targeting pediatric cost compression, and specialized sensor technology licensors. Dominant competitive moves include direct-to-clinic distribution channel compression and ISO 13485 certification acquisition to satisfy EU MDR compliance requirements.
Among German-based fabricators, Ottobock occupies a position exemplifying the integrated manufacturing archetype with captive production capabilities. Open Bionics represents the open-source cost-disruption model through modular hardware architectures. Ossur anchors Nordic market access through specialized rehabilitation center partnerships. These three players collectively illustrate the strategic spectrum from premium integrated systems to accessible modular platforms.
| Leading Market Players |
|---|
| Blatchford |
| HDT Global |
| Sarcos Technology and Robotics Corporation |
| Ekso Bionics |
| SynTouch |
| Ottobock |
| Touch Bionics Inc. |
| Open Bionics |
| Ossur |
| Others |
Supply & Pricing Matrix
Ninety-day component lead times for precision strain gauges and brushless motors concentrate pricing power with Japanese and German suppliers, compressing margins for myoelectric limb assemblers lacking captive component sourcing or long-term offtake agreements with Veterans Affairs procurement systems.
Pricing Analysis
Certification level creates the primary spread across the market, with FDA breakthrough-designated neuroprosthetics commanding premium positioning against CE-marked myoelectric platforms and economy-tier robotic systems. Three-tier pricing structure across premium, standard, and economy levels reflects ISO 13485 validation status, after-sales service bundling, and socket customization depth. Cost compression in standard-tier myoelectric hands is intensifying because Open Bionics' open-source architectures reduce per-unit electronics costs. German statutory insurance frameworks demonstrate lowest price sensitivity, while cash-pay segments in Asian markets exhibit highest elasticity.
Supply Chain Analysis
Brushless motor fabrication in Japan and precision sensor production in Germany constitute critical chokepoints that tether myoelectric hand assembly to regional component specialists. Supply chains draw from Taiwanese semiconductor foundries for microprocessor arrays, Swiss precision machining for prosthetic joint mechanisms, and Chinese rare earth processing for magnetic motor materials. Single-source vulnerability concentrates in German torque sensor specialists serving Ottobock's vertically integrated production. Distribution runs through direct-to-clinic channels displacing traditional orthotics and prosthetics dealer networks, with rehabilitation center certification programs bypassing conventional markup layers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hospital rental models for exoskeleton systems generate recurring revenue expanding faster than hardware sales, positioning service-attach strategies as the primary margin expansion lever for stakeholders across technology tiers.
For Market Incumbents: Compound defensive positioning through ISO 13485 certification acquisition of quality-system-deficient suppliers facing EU MDR exit pressure, while deepening backward integration into precision strain gauge sourcing to offset Japanese component specialist pricing leverage. Channel control through direct-to-clinic distribution investments in Nordic and German rehabilitation center networks protects margin pools from open-source hardware disruptors. For New Entrants and Emerging Players: Differentiate on pediatric modular socket architectures addressing growth-spur adaptation gaps in North American healthcare systems, where incumbent fitting protocols lag adolescent amputee demand. Target homecare telehealth integration as the most penetrable end-user segment, deploying remote myoelectric calibration support as the primary go-to-market angle against rehabilitation center incumbency. For Investors and Strategic Acquirers: Long-term, this sits as a neuroprosthetic platform play because peripheral nerve interface reliability improvements are expanding addressable populations previously excluded from powered device prescriptions. Acquisition targets cluster around ISO 13485-compliant sensor technology licensors lacking downstream distribution. The signal to watch is FDA software-as-medical-device guidance issuance for nerve decoding algorithms, which would trigger R&D resource reallocation across the competitive field.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 13485 Certification Acquisition | Quality-system compliance filters market entry under EU MDR re-certification timelines. |
| Direct-to-Clinic Distribution Buildout | Ossur's Nordic clinician certification programs demonstrate channel compression viability. |
| Implantable Sensor Pilot Expansion | Veterans Affairs Pittsburgh and San Antonio centers validate socket-less attachment economics. |
| Pediatric Modular Socket Development | Growth-spur adaptation addresses underserved adolescent amputee populations in statutory reimbursement systems. |
| Reimbursement Strategy Investment | Germany's National Association of Statutory Health Insurance Funds defines benefit catalog access thresholds. |
Research Methodology
A standing panel of rehabilitation center clinical directors, Veterans Health Administration procurement officers, biomedical engineers, and German statutory insurance fund administrators provided ongoing calibration across primary interview cycles, cross-referenced against FDA 510(k) filings, EU MDR technical documentation databases, hospital GPO contract repositories, and CMS Medicare prosthetic claims data. Bottom-up demand modeling from end-user facility surveys combined with top-down supply-side capacity assessments at Ottobock's Duderstadt manufacturing cluster and Japanese component specialist facilities.
Consistency checks validated volume and value outputs against external benchmarks across the projection horizon. Segmentation dimensions modeled include limb category, technology tier, end-user setting, application indication, and regional regulatory cluster. CAGRs derived from fitted growth curves incorporating myoelectric signal processing advancement rates, neuroprosthetic FDA breakthrough designation pacing, and statutory reimbursement expansion trajectories. Forecast inputs incorporated Veterans Affairs volume commitment schedules and German National Association of Statutory Health Insurance Funds benefit catalog revision cycles.
Material uncertainties — FDA software-as-medical-device guidance timing, EU MDR post-market surveillance data requirements, and Japanese PMDA neuroprosthetic approval pathway divergence — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding peripheral nerve interface reliability improvement curves and statutory insurance reimbursement threshold stability. Practitioners should keep alternative scenarios live as regulatory oversight frameworks for embedded artificial intelligence evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Middle Ear Implants Market
Medical Devices
Global Artificial Organ Market
Medical Devices
Needle-Free IV Connectors Market
Medical Devices
United States Anesthesia Devices Market
Medical Devices
Global Medical Footwear Market
Medical Devices
Annuloplasty Rings Market
Medical Devices
Mexico Ophthalmic Devices Market
Medical Devices
Prefilled Syringe Contract Manufacturing Market
Medical Devices
Japan Artificial Organs and Bionic Implants Market
Medical Devices
Non-Invasive Brain Stimulation System Market
Medical Devices
Pulse Lavage Market
Medical Devices
Plastic Surgery Scaffolds Market
Medical Devices
Anterior Cervical Plating Market
Medical Devices
Global Cardiac Pacemakers Market
Medical Devices
Surgical Incision Closure Devices Market
Medical Devices
Brazil Artificial Organs and Bionic Implants Market