
 Global Transdermal Skin Patches Market | 2026-2036
Global Transdermal Skin Patches Market Size, Share, and Industry Trends Forecast 2026-2036
Global Transdermal Skin Patches Market Foresight
Hospital and specialty clinic procurement channels are rewriting how transdermal patches reach end users, with group purchasing organizations consolidating vendor lists and squeezing out regional distributors. Teva Pharmaceutical Industries Ltd leverages its generic drug portfolio to anchor transdermal offerings across multiple therapeutic categories. Johnson & Johnson competes through its consumer health division, which sustains broad pharmacy shelf presence for nicotine and pain relief patches. Hisamitsu Pharmaceutical Co Inc dominates in Asian markets, where it controls established brand recognition for topical analgesic systems.
Transdermal skin patches are adhesive dosage forms designed to deliver active pharmaceutical ingredients through intact skin into systemic circulation, typically incorporating a backing layer, drug reservoir or matrix, adhesive, and release liner with controlled permeation rates measured in micrograms per hour. Their primary commercial purpose is to maintain steady plasma drug concentrations over extended periods while improving patient compliance versus oral or injectable alternatives. Pain relief and hormonal patches occupy mature volume positions with established manufacturing scale, whereas microneedle technology segments are capturing disproportionate R&D investment as developers target biologics previously excluded from transdermal delivery. Home healthcare end users represent the fastest-growing access point, driven by reimbursement shifts favoring outpatient chronic disease management.
FDA bioequivalence guidelines for transdermal products, EMA quality requirements under the Medical Device Regulation framework, and Japan's PMDA pharmaceutical standards collectively shape formulation complexity, clinical trial design, and market access timelines for patch developers. These regulatory structures elevate barriers for new entrants while rewarding manufacturers with established quality management systems and documented in-vitro permeation data. Stakeholders must monitor evolving equivalence standards for complex generics and emerging combination products that integrate active delivery mechanisms with traditional passive diffusion.
Market Dynamics
Microneedle array technology is compressing the boundary between topical and injectable delivery, forcing established passive diffusion manufacturers to rebuild formulation capabilities around active permeation mechanisms or cede biologics-capable segments to specialized entrants.
Growth Catalysts
- Home healthcare migration:Reimbursement pathways in the United States and Germany now favor outpatient chronic pain management, expanding patch-based opioid alternatives outside institutional settings.
- EMA Medical Device Regulation alignment:Streamlined quality requirements for combination products are accelerating European market access timelines for heat-activated delivery systems.
- Microneedle precision manufacturing:Advances in dissolvable polymer arrays are enabling macromolecule delivery previously excluded from transdermal routes, opening therapeutic categories in diabetes and immunology.
Market Restraints
- API supply concentration:Fentanyl and buprenorphine precursor sourcing clusters in South Asian chemical hubs, exposing formulators to export control volatility and geopolitical disruption.
- Skin permeability variance:Interpatient differences in stratum corneum thickness and lipid composition generate bioavailability uncertainty that complicates dosing standardization across pediatric and geriatric populations.
- FDA bioequivalence stringency:In-vitro permeation testing requirements for generic transdermal filings demand specialized Franz cell apparatus and validated synthetic membranes, elevating capital barriers for abbreviated new drug applications.
Strategic Opportunities
- Japan's aging demographic:PMDA fast-track designations for geriatric-friendly dosage forms are creating preferential review channels for once-weekly hormonal and cardiovascular patches in the world's oldest population.
- Biologic-microneedle convergence:Integration of dissolvable arrays with mRNA stabilization chemistry is rendering peptide and nucleic acid delivery economically viable through dermal routes.
- Direct-to-patient pharmacy channels:Specialty mail-order distributors in the United States are bypassing traditional hospital procurement, capturing margin previously allocated to group purchasing organizations.
Industry Challenges
- Formulation chemistry expertise scarcity:The intersection of polymer science, pharmacokinetic modeling, and adhesive rheology demands hybrid skill sets that outpace current graduate program output.
- Legacy manufacturing retrofit costs:Converting coating and laminating lines from solvent-based to hot-melt processes requires multi-year capital commitments with uncertain payback periods.
- Patent thickets around permeation enhancers:Sulfone and terpene derivative IP portfolios held by specialty chemical incumbents complicate freedom-to-operate for matrix formulation innovators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Transdermal Skin Patches Market |
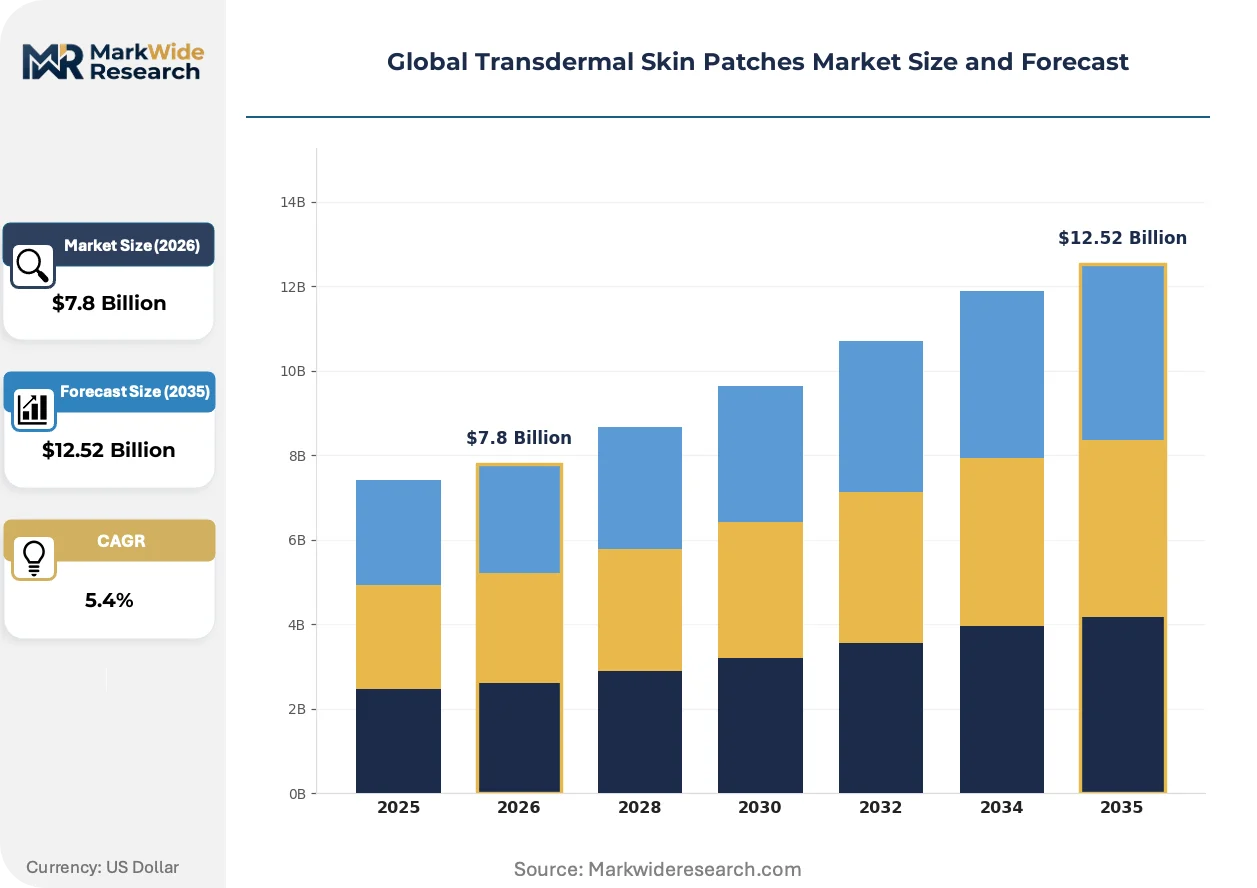
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $12.52 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hormonal, Pain Relief, Nicotine Replacement, Cardiovascular, Neurological, Antiallergic Technology: Microneedle, Matrix, Reservoir, Vapour Patch, Iontophoresis, Heat-Activated Application: Chronic Pain Management, Smoking Cessation, Hormone Regulation, Motion Sickness, Cardiovascular Disorders, Allergy Treatment End User: Home Healthcare, Specialty Clinics, Pharmacies, Research Institutions, Geriatric Care, Sports Medicine |
| Companies Covered | Teva Pharmaceutical Industries Ltd, Novartis AG, Johnson & Johnson, Viatris Inc, Hisamitsu Pharmaceutical Co Inc, Teikoku Pharma USA Inc, Luye Pharma Group, 3M Company, Nitto Denko Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Transdermal Skin Patches Market Shifts & Advancements
Active delivery mechanisms are overtaking passive diffusion as the dominant R&D investment vector, with thermal, iontophoretic, and micromechanical approaches commanding disproportionate capital allocation against mature reservoir technologies.
Solid-state microneedle arrays fabricated from biocompatible sugars and polymers are rendering obsolete the decade-old assumption that only small-molecule lipophilic drugs can achieve therapeutic plasma levels through dermal routes. Diabetes management programs in Germany and Japan are piloting these devices for continuous glucose monitor-integrated insulin delivery. The structural consequence is a bifurcation between commodity pain-relief patches and premium biologic-capable systems with diverging margin profiles.
EMA's 2023 guidance on quality and equivalence for transdermal products under the Medical Device Regulation framework is compressing clinical trial design timelines for combination device-drug filings. Manufacturers with established quality management systems are capturing first-mover advantage in complex generic categories. The guidance most acutely affects heat-assisted delivery systems seeking European market access, where notified body coordination previously created twelve-to-eighteen-month delays.
Hospital procurement consolidation through group purchasing organizations is fragmenting vendor access, with regional distributors losing shelf position to direct manufacturer contracts that bundle patch portfolios across multiple therapeutic categories. Specialty pharmacy networks in the United States are capturing patient volume previously routed through outpatient clinics, altering the service model from institutional administration to home-based training and adherence monitoring. This channel rotation is most visible in chronic pain management, where reimbursement coding changes have shifted site-of-care economics toward residential settings.
Global Transdermal Skin Patches Market Segmentation
Segmentation in transdermal patches reveals divergent commercial rhythms—commodity pain relief turns inventory rapidly while microneedle systems require extended validation cycles. Understanding these temporal patterns shapes capital allocation and portfolio balancing for manufacturers.
Product Type:
Pain relief patches rotate inventory fastest through retail pharmacy channels, whereas neurological and cardiovascular systems face extended clinical validation timelines before commercial deployment.
- Hormonal:Estrogen and testosterone matrix systems deliver controlled release over 3-7 day wear periods. Demand concentrates in Germany and Japan where aging populations drive menopause management and androgen replacement protocols through outpatient reimbursement pathways.
- Pain Relief:Fentanyl and buprenorphine reservoir patches dominate acute and chronic analgesic categories with established manufacturing scale. United States home healthcare channels capture the steepest volume expansion as site-of-care economics shift toward residential administration.
- Nicotine Replacement:Matrix-based cessation aids with 16-24 hour nicotine tartrate delivery. Pharmacy shelf presence sustains volume in markets with established smoking cessation reimbursement.
- Cardiovascular:Nitroglycerin and clonidine systems for hypertension and angina prophylaxis. Hospital procurement consolidation favors bundled contracts across cardiac therapeutic categories.
- Neurological:Rotigotine and rivastigmine patches for Parkinson's and Alzheimer's symptom management. PMDA fast-track designations in Japan accelerate review timelines for geriatric-friendly formulations.
- Antiallergic:Scopolamine and antihistamine transdermal systems for motion sickness and allergic rhinitis. Travel medicine and seasonal allergy segments drive intermittent demand patterns.
Pain relief dominates installed base. Neurological applications are where expansion concentrates.
Technology:
Cost stratification separates passive diffusion commodities from active delivery premiums, with manufacturing investment thresholds determining competitive entry feasibility.
- Microneedle:Dissolvable polymer arrays enable macromolecule delivery through created microchannels. Germany and Japan pilot diabetes programs integrate these with continuous glucose monitoring infrastructure.
- Matrix:Drug-homogenized adhesive layers dominate nicotine and hormonal categories with simplified manufacturing. Established coating lines in United States and European contract manufacturers sustain cost-competitive supply.
- Reservoir:Membrane-controlled drug release systems for high-potency opioids and cardiovascular actives. FDA bioequivalence stringency elevates capital barriers for generic entrants.
- Vapour Patch:Essential oil and menthol-based topical systems for congestion and mild analgesia. Consumer health divisions capture retail margin through pharmacy and mass-market channels.
- Iontophoresis:Electrically-assisted ion delivery for local anesthesia and anti-inflammatory administration. Sports medicine clinics in United States adopt these for acute injury management.
- Heat-Activated:Thermal enhancement of skin permeability for improved bioavailability. EMA Medical Device Regulation alignment accelerates European market access timelines.
Matrix systems dominate installed base. Microneedle platforms are climbing the fastest.
Application:
Volume concentration varies sharply by therapeutic category—chronic conditions sustain recurring demand while acute indications generate episodic procurement spikes.
- Chronic Pain Management:Long-acting opioid and non-opioid patches for osteoarthritis, neuropathy, and cancer-related pain. United States reimbursement shifts favor home-based administration over institutional settings.
- Smoking Cessation:Nicotine replacement protocols combining patch therapy with behavioral intervention. Pharmacy benefit managers in Germany bundle these with counseling services.
- Hormone Regulation:Menopause, contraception, and gender-affirming care applications. Japan's demographic profile sustains demand for once-weekly wear formulations.
- Motion Sickness:Scopolamine transdermal systems for travel and vestibular disorders. Cruise line and aviation medicine procurement generates seasonal volume.
- Cardiovascular Disorders:Hypertension and angina prophylaxis through nitroglycerin and clonidine delivery. Geriatric care facilities favor patch adherence over oral regimen complexity.
- Allergy Treatment:Antihistamine patches for seasonal and perennial allergic rhinitis. Pediatric and geriatric populations drive formulation demand for non-oral alternatives.
Chronic pain management dominates installed base. Hormone regulation is gaining share fastest.
End User:
Customer type determines service intensity—home healthcare requires training infrastructure while research institutions demand technical customization and protocol flexibility.
- Home Healthcare:Patient-administered chronic disease management with remote adherence monitoring. United States specialty pharmacy networks capture margin previously allocated to hospital outpatient departments.
- Specialty Clinics:Pain management and endocrinology practices with in-clinic patch initiation. Group purchasing organization consolidation squeezes regional distributor participation.
- Pharmacies:Retail and mail-order dispensing for nicotine, pain relief, and hormonal categories. Direct-to-patient channels bypass traditional wholesale distribution.
- Research Institutions:Clinical trial supply and pharmacokinetic study materials. Franz cell apparatus and validated synthetic membrane requirements elevate supplier qualification barriers.
- Geriatric Care:Long-term care and assisted living facilities managing polypharmacy simplification. Japan's aging population density supports dedicated formulary development.
- Sports Medicine:Athletic training facilities and orthopedic practices using iontophoretic and topical analgesic systems. Professional team medical staff drive premium product specification.
Pharmacies dominate installed base. Home healthcare is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's pharmaceutical cold-chain infrastructure anchors European distribution for temperature-sensitive patch formulations, while Japan's Kansai International Airport freight terminals expedite PMDA-regulated exports across Asia-Pacific markets.
United States
Home healthcare reimbursement shifts and specialty pharmacy network expansion drive patch volume through residential channels. FDA bioequivalence guidelines for transdermal generics mandate Franz cell apparatus validation, elevating supplier qualification barriers. The New Jersey-Pennsylvania corridor hosts contract manufacturing clusters serving reservoir and matrix system production.
Germany
EMA Medical Device Regulation alignment accelerates heat-activated combination product approvals while outpatient chronic pain protocols expand patch-based opioid alternatives. The country's national pharmaceutical regulator streamlines quality requirements for device-drug filings. Bavaria's medical technology corridor concentrates microneedle pilot programs integrating continuous glucose monitoring infrastructure.
Japan
PMDA fast-track designations for geriatric-friendly dosage forms prioritize once-weekly hormonal and cardiovascular patches. METI industrial policy supports domestic manufacturing scale for polymer adhesive systems. The Kansai region around Osaka anchors Hisamitsu Pharmaceutical's topical analgesic production and regional brand distribution networks.
China
NMPA pharmaceutical standards and domestic chronic disease management initiatives expand local patch manufacturing capacity for pain relief and cardiovascular categories. The Yangtze River Delta pharmaceutical corridor, centered on Shanghai and Suzhou, concentrates contract development and manufacturing organizations serving multinational formulators.
India
CDSCO regulatory harmonization efforts and export-oriented pharmaceutical manufacturing support fentanyl and buprenorphine precursor supply to global formulators. The Mumbai-Pune corridor hosts active pharmaceutical ingredient production clusters supplying South Asian chemical hubs for transdermal actives.
Global Transdermal Skin Patches Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying adhesive films, release liners, and permeation-enhancing chemistries. The vendor base organizes around three archetypes: diversified pharmaceutical conglomerates with generic portfolios, specialized transdermal technology developers, and materials science suppliers with healthcare divisions. Consolidation pressures favor manufacturers with documented in-vitro permeation data and established quality management systems. Competitive positioning hinges on bioequivalence filing expertise and direct-to-pharmacy channel access.
Among Israel-based pharmaceutical conglomerates, Teva Pharmaceutical Industries Ltd occupies a position exemplifying generic portfolio leverage across multiple therapeutic categories. Johnson & Johnson represents the consumer health division archetype sustaining broad pharmacy shelf presence through nicotine and pain relief patch distribution. Hisamitsu Pharmaceutical Co Inc anchors the Asian market specialization archetype with established brand recognition for topical analgesic systems in Japan and regional export markets.
| Leading Market Players |
|---|
| Teva Pharmaceutical Industries Ltd |
| Novartis AG |
| Johnson & Johnson |
| Viatris Inc |
| Hisamitsu Pharmaceutical Co Inc |
| Teikoku Pharma USA Inc |
| Luye Pharma Group |
| 3M Company |
| Nitto Denko Corporation |
| Others |
Supply & Pricing Matrix
Overcapacity in South Asian fentanyl precursor production compresses API margins and forces formulators toward long-term offtake contracts that lock in volume-discount tiering. This utilization dynamic concentrates pricing power with bulk chemical suppliers while squeezing finished-patch manufacturers into cost-plus arrangements that erode flexibility.
Pricing Analysis
Volume-discount tiering structures separate hospital GPO contracts from retail pharmacy spot purchases and direct-to-patient specialty mail-order channels. FDA bioequivalence certification tiers command 15-25% premiums over uncertified matrix alternatives in United States procurement. Cost compression in generic reservoir segments intensifies as Teva and Viatris consolidate manufacturing scale. Retail pharmacy buyers exhibit highest price sensitivity; specialty clinics with bundled reimbursement show lowest.
Supply Chain Analysis
Tariff exposure between India and United States dominates raw material cost volatility for opioid precursor sourcing. Active pharmaceutical ingredient production clusters in India, China, and Germany feed coating and laminating lines in New Jersey-Pennsylvania and Bavaria corridors. Polymer adhesive films, release liners, and permeation enhancers draw from specialty chemical incumbents with sulfone and terpene derivative IP portfolios. Single-source vulnerability around validated Franz cell membrane suppliers elevates qualification risk for generic entrants. Distribution runs through hospital GPOs, specialty pharmacy networks, and direct manufacturer contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Microneedle platform economics are inflecting toward interoperability with continuous glucose monitoring infrastructure, creating ecosystem lock-in effects that favor early movers with device-drug combination filing expertise.
For Market Incumbents: Harden bioequivalence documentation against FDA in-vitro permeation testing stringency by captive investment in Franz cell validation capacity. Consolidate adhesive polymer supply through backward integration into South Asian chemical hubs or long-term offtake with Indian CDSCO-registered precursor suppliers. Defend reservoir patch margins against matrix generic displacement by accelerating heat-activated combination product pipelines under EMA MDR alignment. For New Entrants and Emerging Players: Pursue white-space positioning in neurological patch categories where PMDA fast-track designations compress review timelines for geriatric-friendly rotigotine and rivastigmine formulations. Target Japan's aging demographic with once-weekly wear hormonal systems. Enter through contract manufacturing partnerships with established quality management systems rather than greenfield capacity. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across microneedle precision manufacturing as dissolvable polymer array production demands semiconductor-class cleanroom investment. Five-to-ten-year viability favors platform integrators with documented in-vitro permeation data over component specialists. Watch FDA bioequivalence guidance evolution for complex generics as signal of regulatory barrier height and incumbent protection duration.| Strategic Initiative | Industry Significance |
|---|---|
| Microneedle Array Manufacturing Scale-Up | Enables macromolecule delivery through Bavaria and Japan diabetes pilot programs. |
| Heat-Activated Combination Product Filing | Accelerates EMA MDR-aligned European market access for device-drug systems. |
| Backward Integration into API Precursors | Secures fentanyl and buprenorphine supply against Indian export control volatility. |
| Specialty Pharmacy Network Partnership | Captures United States home healthcare margin from hospital outpatient departments. |
| FDA Bioequivalence Certification Investment | Creates defensible positioning in generic reservoir patch categories. |
Research Methodology
Initial hypotheses were tested against primary input from regulatory affairs leads at patch developers, hospital GPO contracts managers, specialty pharmacy procurement directors, and polymer adhesive R&D heads, then refined against FDA 505(b)(2) filings, EMA combination product guidance documents, PMDA fast-track designation records, and United States CMS reimbursement coding updates. Bottom-up patient volume modeling and top-down pharmaceutical market sizing were triangulated to constrain forecast variance.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, with patient population epidemiology, site-of-care reimbursement shifts, and manufacturing capacity utilization as core demand drivers. Segmentation dimensions included product type, technology platform, application, and end-user channel. CAGRs were derived from slope-constrained growth curve fitting against historical volume trajectories and regulatory approval pipeline visibility.
The forecast holds incumbent behavior within observed patterns; aggressive moves by biologic-microneedle convergence specialists or heat-activated device entrants would shift outcomes beyond modeled bounds. API supply disruption, FDA bioequivalence guidance revision, or PMDA geriatric fast-track policy change represent specific revision triggers. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Defibrillator Pads Market
Medical Devices
Prescription Goggles Market
Medical Devices
Ultrasound Probe Market
Medical Devices
Depression Devices Market
Medical Devices
Cardiac Implants Market
Medical Devices
Allografts Market
Medical Devices
Pet Mobility Aids Market
Medical Devices
MRI Safe Defibrillator Market
Medical Devices
Knotless Suture Anchors Market
Medical Devices
External Nasal Dilator Market
Medical Devices
Smart Pills Drug Delivery Market
Medical Devices
China Anesthesia Devices Market
Medical Devices
Global Angioplasty Balloons Market
Medical Devices
Global Cardiac Holter Monitor Market
Medical Devices
South Africa Artificial Organs and Bionic Implants Market
Medical Devices
Skull Deformity Implants Market