
 Global Robotic Endoscopy Devices Market | 2026-2036
Global Robotic Endoscopy Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Global Robotic Endoscopy Devices Market Foresight
Market Context with Strategic Players
Disposable polymer sheaths and single-use instrument channels are shifting cost structures away from capital-intensive reusable systems toward per-procedure economics. Olympus Corporation leverages its vertically integrated optical component supply chain to sustain margin control across flexible endoscope production. Intuitive Surgical dominates the North American installed base with its Ion platform for lung biopsy navigation. Medtronic competes through GI Genius AI-assisted polyp detection modules that anchor its endoscopy software strategy.
Technical Definition and Structural Segments
Robotic endoscopy devices integrate electromechanical articulation, haptic feedback, and real-time imaging into catheter-based or laparoscopic instruments that enable remote manipulation of endoscopes during diagnostic and therapeutic procedures inside hollow organs or body cavities. These systems typically incorporate 3-6 degrees of freedom at the distal tip, sub-millimeter positioning accuracy, and 1080p or 4K video transmission to reduce tissue trauma and operator fatigue during extended interventions. Flexible endoscopes occupy the largest revenue pool due to colonoscopy and bronchoscopy volume, while single-use endoscopes represent the fastest-expanding category as infection control protocols harden in hospitals and ambulatory surgical centers. Artificial intelligence integration is concentrating margin capture in software layers, whereas electromechanical control hardware remains a fragmented, lower-margin component tier.
Regulatory Frame and Forward-Looking Close
The FDA enforces 510(k) and De Novo pathways for robotic surgical devices with escalating software validation demands, while the EU MDR requires notified body scrutiny of active therapeutic devices under Class IIa/IIb rules with post-market clinical follow-up obligations. Japan's PMDA maintains distinct QMS requirements that delay market entry for foreign manufacturers lacking local clinical data generation. China's NMPA now mandates domestic multi-center trials for innovative surgical robotics, reshaping how multinational firms sequence geographic launches. Stakeholders must monitor how divergent software-update approval frameworks across the FDA, EMA, and NMPA will fragment global product roadmaps and inflate regulatory compliance overhead.
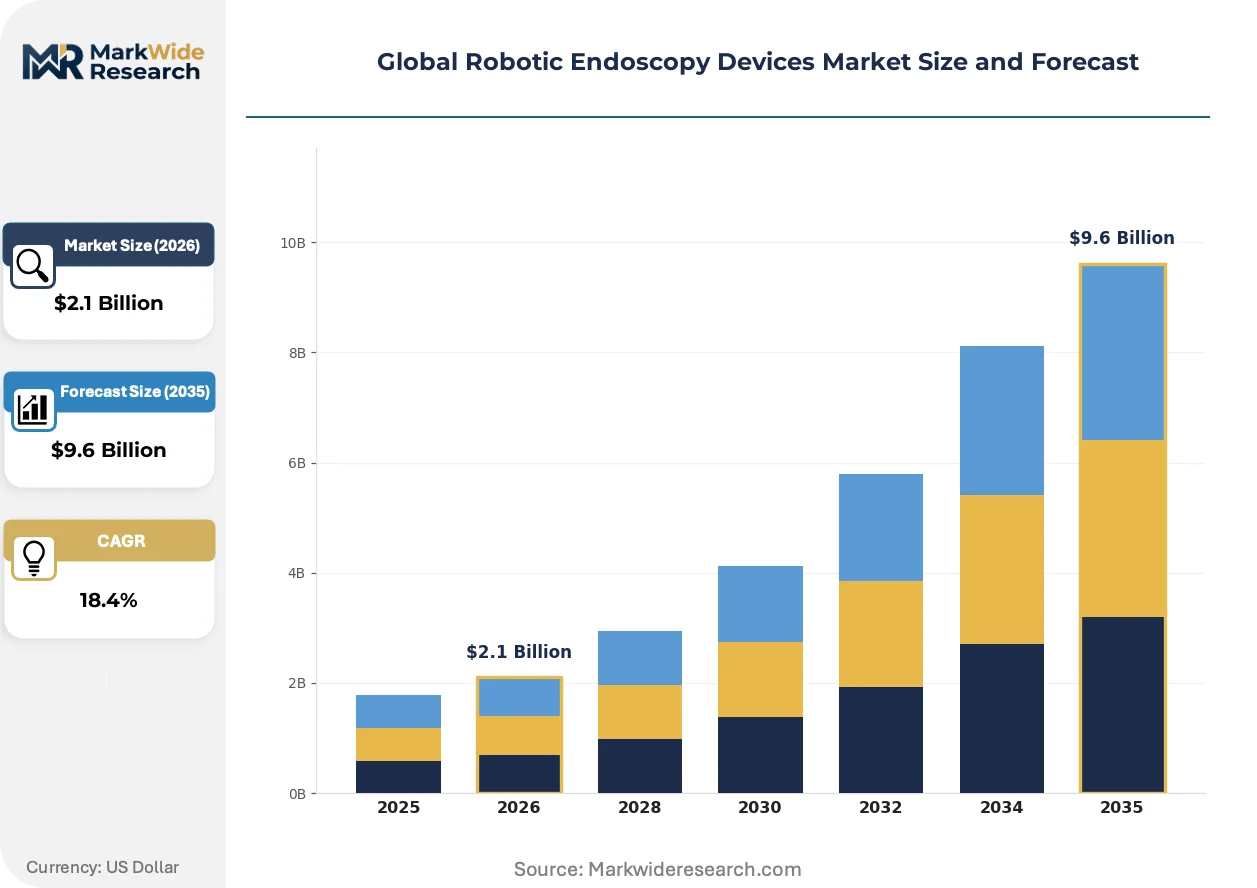
Market Dynamics
Single-use endoscope economics is electrifying capital allocation decisions across hospital procurement departments, forcing manufacturers to rebuild revenue models around per-procedure consumables rather than multi-year capital leases.
Growth Catalysts
- EU MDR clinical evidence mandates:Stricter post-market surveillance requirements for active implantable surgical equipment are accelerating hospital upgrades to compliant robotic platforms in Germany and France.
- AI-assisted polyp detection:Machine vision modules integrated into colonoscopy workflows are reducing missed adenoma rates and driving replacement demand across academic medical centers.
- Japan's aging surgical workforce:PMDA fast-track pathways for ergonomic robotic systems are addressing operator fatigue constraints in Tokyo and Osaka university hospitals.
Market Restraints
- Optical component supply concentration:Specialized CMOS sensors and fiber bundles depend on a limited supplier base in East Asia, creating input volatility for flexible endoscope manufacturers.
- FDA software validation timelines:De Novo pathway requirements for autonomous navigation algorithms extend commercialization cycles by 18-24 months for novel robotic platforms.
- Reusable system substitution pressure:High-volume ambulatory surgical centers in cost-sensitive markets continue deploying conventional flexible endoscopes with manual articulation.
Strategic Opportunities
- China NMPA domestic trial mandates:Multi-center clinical requirements for innovative surgical robotics create partnership openings for multinational firms seeking accelerated market entry.
- Bronchoscopic lung biopsy expansion:Peripheral nodule navigation represents an underpenetrated application segment with reimbursement tailwinds in United States outpatient settings.
- Subscription-based service models:Equipment-as-a-service contracts bundling maintenance, software updates, and disposable instruments are displacing traditional capital purchase arrangements.
Industry Challenges
- Haptic feedback engineering talent scarcity:Specialized electromechanical control expertise required for sub-millimeter force sensing remains concentrated among a limited pool of robotics engineers.
- Legacy PACS integration complexity:Robotic endoscopy platforms must interface with heterogeneous hospital imaging archives, prolonging deployment timelines and elevating IT support costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Robotic Endoscopy Devices Market |
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $9.6 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flexible Endoscopes, Rigid Endoscopes, Capsule Endoscopes, Single-Use Endoscopes Technology: Optical Imaging, Magnetic Navigation, Artificial Intelligence, 3D Visualization, Electromechanical Control Application: Gastroenterology, Pulmonology, Urology, Gynecology, ENT Procedures End User: Hospitals, Ambulatory Surgical Centers, Diagnostic Laboratories, Specialty Clinics |
| Companies Covered | Olympus Corporation, Asensus Surgical, Intuitive Surgical, KARL STORZ, CMR Surgical, Medtronic, Brainlab AG, Virtuoso Surgical, Johnson & Johnson, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Robotic Endoscopy Devices Market Shifts & Advancements
Convergence of disposable instrument architectures with cloud-native software stacks is compressing product lifecycles and fragmenting competitive advantage across hardware and data layers simultaneously.
Magnetic levitation distal tip actuation is electrifying flexible endoscope maneuverability by eliminating mechanical cable friction. Academic medical centers in the United States are piloting these systems for complex colorectal interventions. This technology is compressing the performance gap between manual and robotic platforms in cost-sensitive procurement evaluations.
EU MDR Class IIb active therapeutic device rules are mandating post-market clinical follow-up obligations that reshape product development roadmaps. Manufacturers must now embed real-world evidence collection infrastructure into commercial deployments. German notified bodies are experiencing backlog delays that extend time-to-certification for novel robotic platforms.
Hospital purchasing consortia are consolidating procurement authority for high-value surgical robotics through centralized capital committees. Independent ambulatory surgical centers are losing direct vendor negotiation leverage as health system integration accelerates. This concentration is most visible in United States metropolitan markets where IDN-affiliated centers dominate endoscopy volume.
Global Robotic Endoscopy Devices Market Segmentation
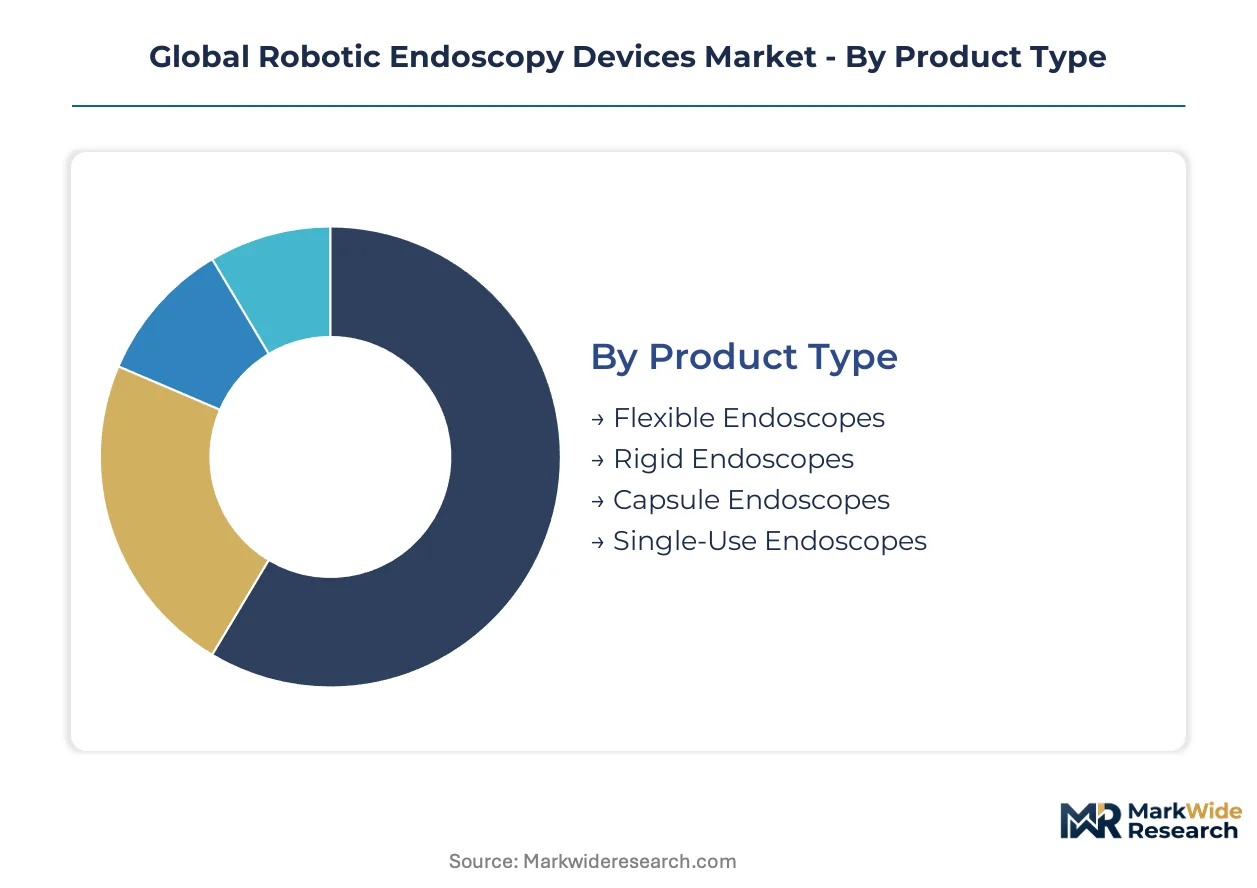
Segmentation in robotic endoscopy reveals how hardware architectures, software layers, and care settings partition value capture. Procurement committees weigh capital intensity against per-procedure economics differently across each dimension.
Product Type:
Standardization dominates reusable platforms while single-use formats enable customization at the procedure level.
- Flexible Endoscopes:These systems integrate 3-6 degrees of freedom at the distal tip with sub-millimeter positioning accuracy for colonoscopy and bronchoscopy workflows. Demand concentrates in German university hospitals building dedicated robotic endoscopy centers, driven by EU MDR compliance requirements for active therapeutic devices.
- Single-Use Endoscopes:Disposable polymer sheaths and instrument channels eliminate cross-contamination risks and reprocessing overhead. Ambulatory surgical centers in the United States are electrifying capital allocation decisions around per-procedure consumables rather than multi-year capital leases.
- Rigid Endoscopes:Laparoscopic platforms with electromechanical articulation serve urological and gynecological interventions.
- Capsule Endoscopes:Miniaturized ingestible devices with magnetic navigation enable small bowel examination without sedation.
Most installed capacity flows through Flexible Endoscopes. Expansion is steepest in Single-Use Endoscopes.
Technology:
Margin capture concentrates in software layers while electromechanical hardware fragments across suppliers.
- Artificial Intelligence:Machine vision modules for real-time polyp detection and autonomous navigation reduce missed adenoma rates in colonoscopy workflows. Academic medical centers in the United States drive replacement demand as AI-assisted detection becomes standard-of-care for academic credentialing.
- Optical Imaging:1080p and 4K video transmission systems with specialized CMOS sensors and fiber bundles form the visualization backbone. East Asian sensor suppliers create input volatility that constrains flexible endoscope manufacturers.
- Electromechanical Control:Haptic feedback systems with sub-millimeter force sensing enable remote manipulation.
- Magnetic Navigation:Magnetic levitation distal tip actuation eliminates mechanical cable friction for enhanced maneuverability.
- 3D Visualization:Stereoscopic imaging platforms enhance depth perception during complex interventions.
Revenue pools concentrate in Optical Imaging. Climbing the fastest is Artificial Intelligence.
Application:
Procedure volume and reimbursement intensity diverge sharply across anatomical targets.
- Gastroenterology:Colorectal cancer screening protocols and therapeutic polypectomy drive the highest procedure volumes. Screening mandates in Germany and France accelerate hospital upgrades to compliant robotic platforms under EU MDR post-market surveillance rules.
- Pulmonology:Peripheral lung nodule navigation for biopsy represents an underpenetrated segment with reimbursement tailwinds. United States outpatient settings are expanding adoption of robotic-assisted bronchoscopy for early-stage lung cancer diagnosis.
- Urology:Robotic cystoscopy and ureteroscopy procedures address upper tract urothelial carcinoma.
- Gynecology:Hysteroscopic and laparoscopic applications serve fertility and oncological interventions.
- ENT Procedures:Transoral robotic surgery for oropharyngeal lesions leverages narrow anatomical corridors.
Procedure volume concentrates in Gastroenterology. Steepest expansion trajectory appears in Pulmonology.
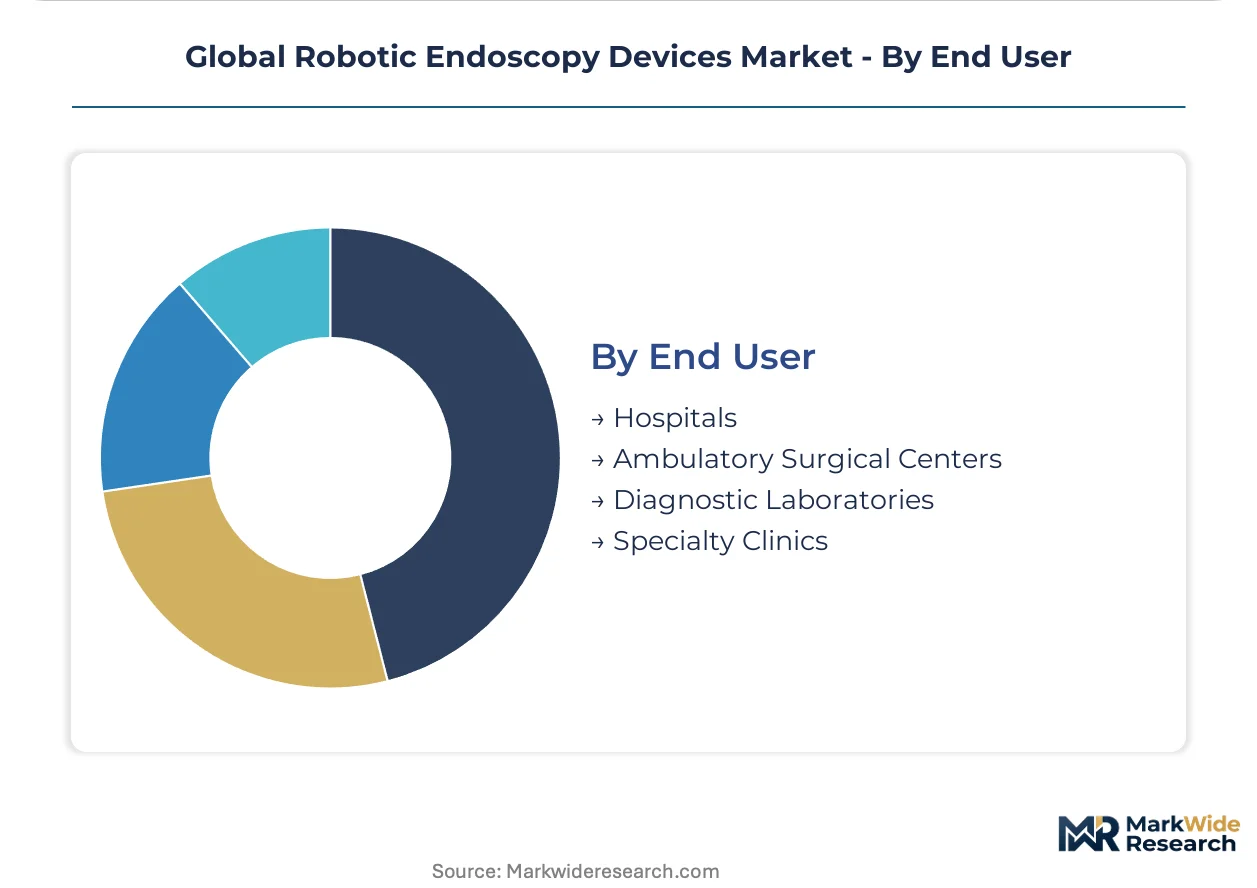
End User:
Purchasing authority centralization reshapes vendor access across care settings.
- Hospitals:Integrated delivery networks consolidate procurement through centralized capital committees with direct vendor negotiation leverage. IDN-affiliated centers in United States metropolitan markets dominate high-volume endoscopy procedures.
- Ambulatory Surgical Centers:Independent centers are losing direct vendor access as health system integration accelerates. Cost-sensitive markets continue deploying conventional flexible endoscopes with manual articulation.
- Diagnostic Laboratories:Specialized pathology and imaging centers require integrated robotic platforms for tissue acquisition.
- Specialty Clinics:Gastroenterology and pulmonology-focused practices seek procedure-specific configurations.
Capital deployment concentrates in Hospitals. Gaining share fastest are Ambulatory Surgical Centers adopting single-use economics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German university hospitals anchor installed capacity expansion for robotic endoscopy platforms, with procurement committees prioritizing EU MDR-compliant systems. Regulatory divergence across FDA, EMA, and NMPA jurisdictions fragments product roadmaps for multinational manufacturers. Capital allocation concentrates in metropolitan clusters with integrated delivery network consolidation.
United States
Academic medical centers in Boston and Stanford drive Ion platform adoption for peripheral lung biopsy navigation. FDA De Novo pathway requirements for autonomous navigation algorithms extend commercialization cycles by 18-24 months. IDN-affiliated centers in metropolitan markets dominate high-volume endoscopy procedures through centralized capital committees.
Germany
University hospitals in Munich and Heidelberg are building dedicated robotic endoscopy centers with EU MDR Class IIb compliance mandates. Notified body backlog delays extend time-to-certification for novel platforms under active therapeutic device rules. Bavarian medical technology clusters concentrate electromechanical control engineering talent for haptic feedback systems.
China
NMPA domestic multi-center trial mandates for innovative surgical robotics reshape geographic launch sequencing for multinational firms. Yangtze River Delta hospital procurement consortia prioritize equipment-as-a-service contracts bundling maintenance and disposable instruments. Shanghai medical device parks attract joint venture partnerships to satisfy local clinical data generation requirements.
Japan
Tokyo and Osaka university hospitals deploy PMDA fast-track pathways for ergonomic robotic systems addressing operator fatigue constraints. Aging surgical workforce demographics accelerate replacement demand for sub-millimeter positioning accuracy platforms. Kanto region medical centers concentrate capsule endoscope magnetic navigation pilot programs.
United Kingdom
NHS England integrated care systems consolidate procurement authority for high-value surgical robotics through specialized commissioning committees. London teaching hospitals pilot AI-assisted polyp detection modules within colonoscopy screening programs. MHRA post-market surveillance alignment with EU MDR clinical evidence requirements influences platform upgrade cycles.
Global Robotic Endoscopy Devices Market Competitive Landscape
Strategic partnerships dominate the current landscape as manufacturers seek to bridge hardware and software capability gaps. The vendor base organizes around three distinct tiers: diversified medical technology conglomerates with vertically integrated optical supply chains, pure-play surgical robotics specialists with focused electromechanical expertise, and emerging AI-software layers seeking hardware anchoring. Consolidation pressure intensifies as subscription-based service models displace traditional capital purchase arrangements. Technology licensing agreements and geographic co-development partnerships represent the primary competitive moves reshaping positioning.
Among diversified medical technology conglomerates, Olympus Corporation and Medtronic exemplify archetypes combining captive optical component supply with software-layer expansion. Intuitive Surgical occupies a position within the pure-play surgical robotics tier, anchoring North American installed base concentration. Johnson & Johnson represents the integrated health systems approach, sitting within portfolios that span pharmaceutical, medical device, and surgical platform segments.
| Leading Market Players |
|---|
| Olympus Corporation |
| Asensus Surgical |
| Intuitive Surgical |
| KARL STORZ |
| CMR Surgical |
| Medtronic |
| Brainlab AG |
| Virtuoso Surgical |
| Johnson & Johnson |
| Others |
Supply & Pricing Matrix
Specialized CMOS sensor pricing indices in East Asia cascade through flexible endoscope manufacturing into three-tier pricing structures across premium, standard, and economy levels. German university hospitals absorb premium tiers for EU MDR-compliant systems while ambulatory surgical centers in the United States gravitate toward per-procedure consumable economics.
Pricing Analysis
Input-cost pass-through from optical component volatility stratifies pricing across certification tiers. FDA 510(k) cleared platforms command premiums over CE-marked equivalents in North American procurement evaluations. Cost compression in standard-tier flexible endoscopes is intensifying because single-use alternatives are displacing reusable capital equipment leases. Ambulatory surgical centers exhibit highest price sensitivity; integrated delivery networks leverage volume scale for preferential service bundling.
Supply Chain Analysis
Single-source vulnerability sits with Japanese and South Korean CMOS sensor suppliers dominating high-resolution imaging cores. Robotic endoscope production draws from Taiwanese fiber bundle manufacturers, German precision electromechanical component specialists, and Chinese polymer sheath fabricators. Tariff exposure on optical subassemblies threatens margin stability for flexible platform assemblers. Distribution runs through hospital purchasing consortia and group purchasing organizations consolidating vendor access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Quality specifications are hardening as EU MDR post-market surveillance mandates and AI-assisted detection standards concentrate procurement authority around compliant, premium-tier platforms. This shift favors incumbents with embedded clinical evidence infrastructure.
For Market Incumbents: Cement software-layer anchoring through AI module integration that locks hospital workflows into proprietary data architectures. Deepen captive supply of optical components to insulate margin structures from East Asian sensor volatility. Defensive priority rests on pre-empting disposable platform entrants through subscription-based equipment-as-a-service contracts that blur capital-consumable boundaries. For New Entrants and Emerging Players: Magnetic levitation distal tip actuation offers a technology-first wedge into cost-sensitive flexible endoscope evaluations where manual platforms still dominate. Peripheral lung biopsy navigation in United States outpatient settings presents the most penetrable application white space. Go-to-market execution should prioritize pilot programs with academic medical centers seeking differentiated credentialing for early-stage lung cancer diagnosis. For Investors and Strategic Acquirers: Asymmetric upside sits with pure-play surgical robotics specialists possessing electromechanical control IP but lacking global regulatory infrastructure. Long-term viability in this market hinges on software update velocity and real-world evidence generation capabilities rather than hardware scale alone. Watch for FDA De Novo clearance velocity as the inflection signal separating sustainable platforms from stranded capital.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Notified Body Certification | Accelerates German hospital procurement cycles under Class IIb active therapeutic device rules. |
| AI-Assisted Detection Software Launch | Captures margin pools in academic medical centers seeking reduced missed adenoma rates. |
| Single-Use Platform Manufacturing Scale-Up | Addresses infection control protocols hardening in United States ambulatory surgical centers. |
| Hospital System Partnership Agreement | Secures installed base expansion through IDN-affiliated metropolitan cluster concentration. |
| Equipment-as-a-Service Contract Model | Displaces traditional capital purchases with bundled maintenance and disposable instrument economics. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary engagement captured perspectives from hospital purchasing committee chairs, biomedical engineering directors, GPO contracts managers, and regulatory affairs leads at device manufacturers. Secondary validation drew from FDA 510(k) and De Novo filings, EMA MDR certification databases, hospital procurement contract disclosures, and CMS Medicare reimbursement schedules. Bottom-up procedure volume estimates and top-down revenue triangulation anchored segmentation outputs.
Comparable historical periods anchored the projection horizon against pre-COVID baselines and post-MDR transition trajectories. Segmentation modeling spanned product architecture, technology layer, anatomical application, and care setting intensity. CAGRs derived from fitted growth curves applied to procedure volume elasticities and capital equipment replacement cycles. Forecast inputs incorporated regulatory pathway timelines, reimbursement code valuations, and health system consolidation velocity.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to FDA software validation delays, EU notified body backlog resolution, and NMPA domestic trial mandate evolution. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Pregnancy Detection Kits Market
Medical Devices
Implant-Borne Prosthetics Market
Medical Devices
Chordal Suture Systems Market
Medical Devices
Disabled and Elderly Assistive Technologies Market
Medical Devices
Electronic Pill Market
Medical Devices
Hemoconcentrators Market
Medical Devices
Atrial Fibrillation Devices Market
Medical Devices
Spain Contraceptive Devices Market
Medical Devices
Bone Power Tools Market
Medical Devices
Europe Ablation Technologies Market
Medical Devices
Ocular Adhesive Market
Medical Devices
Cardiac Catheters and Guidewires Market
Medical Devices
Global Intraoperative Neuromonitoring (IONM) Market
Medical Devices
Clinical Rollators Market
Medical Devices
Robot Assisted PCI Market
Medical Devices
Global Liposuction Surgery Devices Market