
 China Anesthesia Devices Market | 2026-2036
China Anesthesia Devices Market Size, Share, and Industry Trends Forecast 2026-2036
China Anesthesia Devices Market Outlook
A capital-intensity divergence between domestic and multinational players is redrawing competitive boundaries in China's anesthesia device sector. Mindray Medical International Limited leverages in-house manufacturing scale to dominate mid-tier hospital procurement tenders across provincial capitals. Draegerwerk AG sustains premium positioning through German-engineered closed-loop anesthesia systems that command price premiums in top-tier academic medical centers. GE Healthcare anchors its presence via long-term service contracts and installed-base upgrades that lock in replacement cycles.
Anesthesia devices encompass integrated systems for controlled delivery of inhalational and intravenous anesthetic agents, incorporating precision vaporizers, ventilator modules, and multi-parameter physiologic monitors maintaining end-tidal gas concentrations within 0.1% accuracy. These systems enable safe, reversible unconsciousness for surgical procedures ranging from outpatient dental extraction to multi-hour cardiac operations. Inhalation anesthesia machines and anesthesia monitoring systems together capture the dominant share of hospital capital expenditure, while closed-loop systems and wireless monitoring represent the fastest-expanding technology categories as Chinese facilities pursue operating-room digitization. Infusion pumps face margin compression from provincial centralized procurement programs, though smart pump variants with dose-error reduction software retain pricing power.
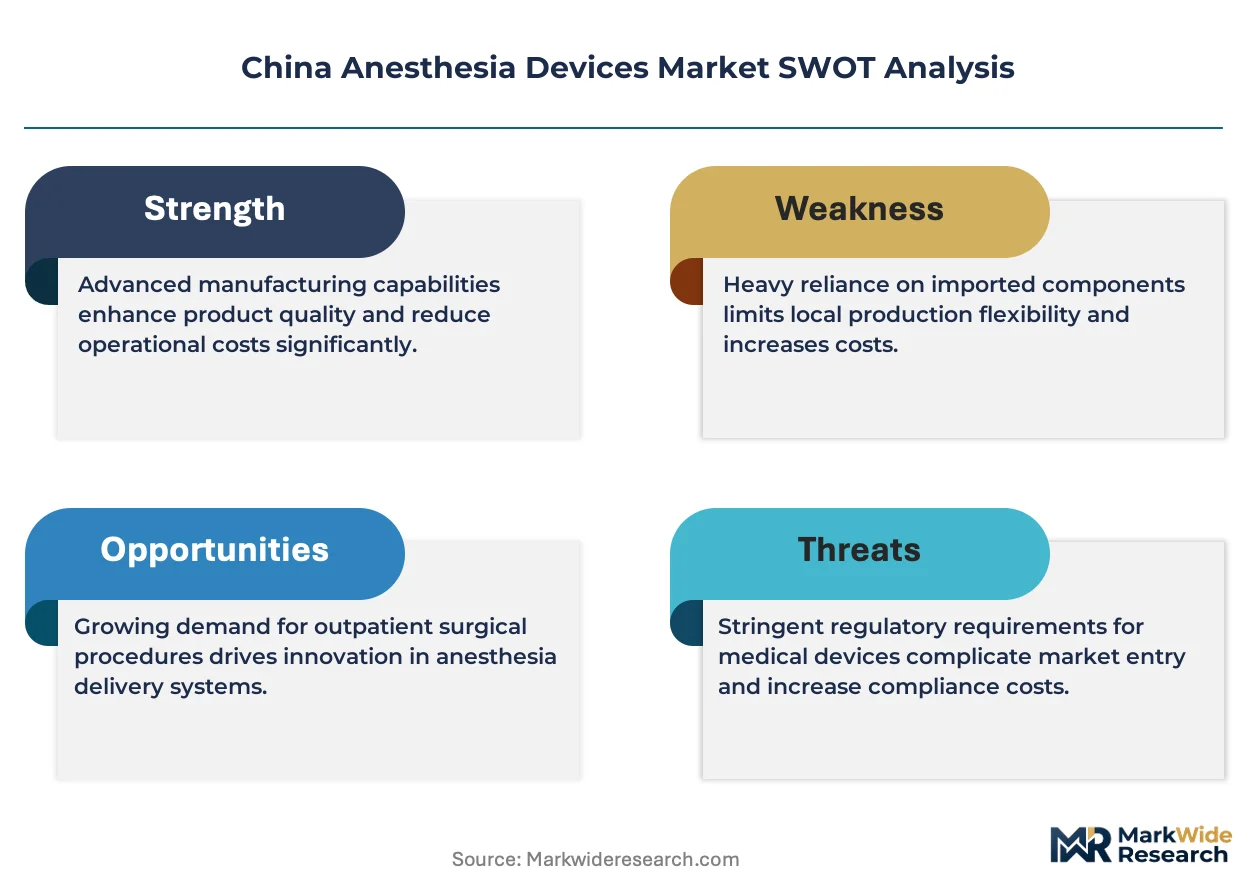
NMPA's medical device registration requirements and GB standards for electrical safety and electromagnetic compatibility shape product development timelines and market access conditions for both domestic and imported equipment. China's dual carbon goals are pressing manufacturers toward energy-efficient anesthesia machine designs with reduced desflurane consumption and lower greenhouse-gas footprints. Stakeholders must monitor how provincial health commission procurement policies balance domestic substitution targets against clinical performance requirements for complex anesthesia workstations.
Market Dynamics
NMPA's updated medical device classification rules are compressing registration timelines for domestic manufacturers while provincial centralized procurement programs in Jiangsu and Zhejiang are rewriting price discovery mechanisms for anesthesia workstations and infusion pumps.
Growth Catalysts
- Tier-three hospital expansion:Municipal public hospitals in East China are replacing legacy anesthesia machines with intelligent delivery systems as surgical volumes climb across Jiangsu and Zhejiang provinces.
- Dual carbon mandate:China's national carbon neutrality targets are accelerating hospital procurement of low-desflurane anesthesia machines with reduced greenhouse-gas footprints.
- Closed-loop technology diffusion:Automated anesthesia control systems are penetrating academic medical centers in Shanghai and Beijing as clinical evidence accumulates.
Market Restraints
- Provincial price compression:Centralized volume-based procurement programs in Anhui and Jiangsu provinces are collapsing margins for standard infusion pumps by 40-60 percent.
- Import dependency for precision components:German and Japanese suppliers dominate high-accuracy vaporizer manufacturing, exposing domestic assemblers to currency and logistics volatility.
- GB standards compliance costs:Electromagnetic compatibility testing under updated GB 9706 series requirements adds 8-14 months to product launch timelines for domestic innovators.
Strategic Opportunities
- Central China penetration:Hubei and Henan provinces show anesthesia device penetration rates 30-40 percent below East China levels, creating whitespace for mid-tier system vendors.
- Wireless monitoring convergence:Integration of anesthesia gas analysis with hospital information systems is opening recurring revenue streams through software subscription models.
- Service contract unbundling:Independent service organizations are capturing aftermarket maintenance from original equipment manufacturers in tier-two city hospital clusters.
Industry Challenges
- Biomedical engineer scarcity:Tier-three hospitals in western provinces face 40-60 percent vacancy rates for anesthesia equipment specialists, constraining utilization of advanced workstation features.
- Legacy system integration friction:Hospital information system vendors deploy proprietary data protocols that block seamless anesthesia monitoring data flow into electronic medical records.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Anesthesia Devices Market |
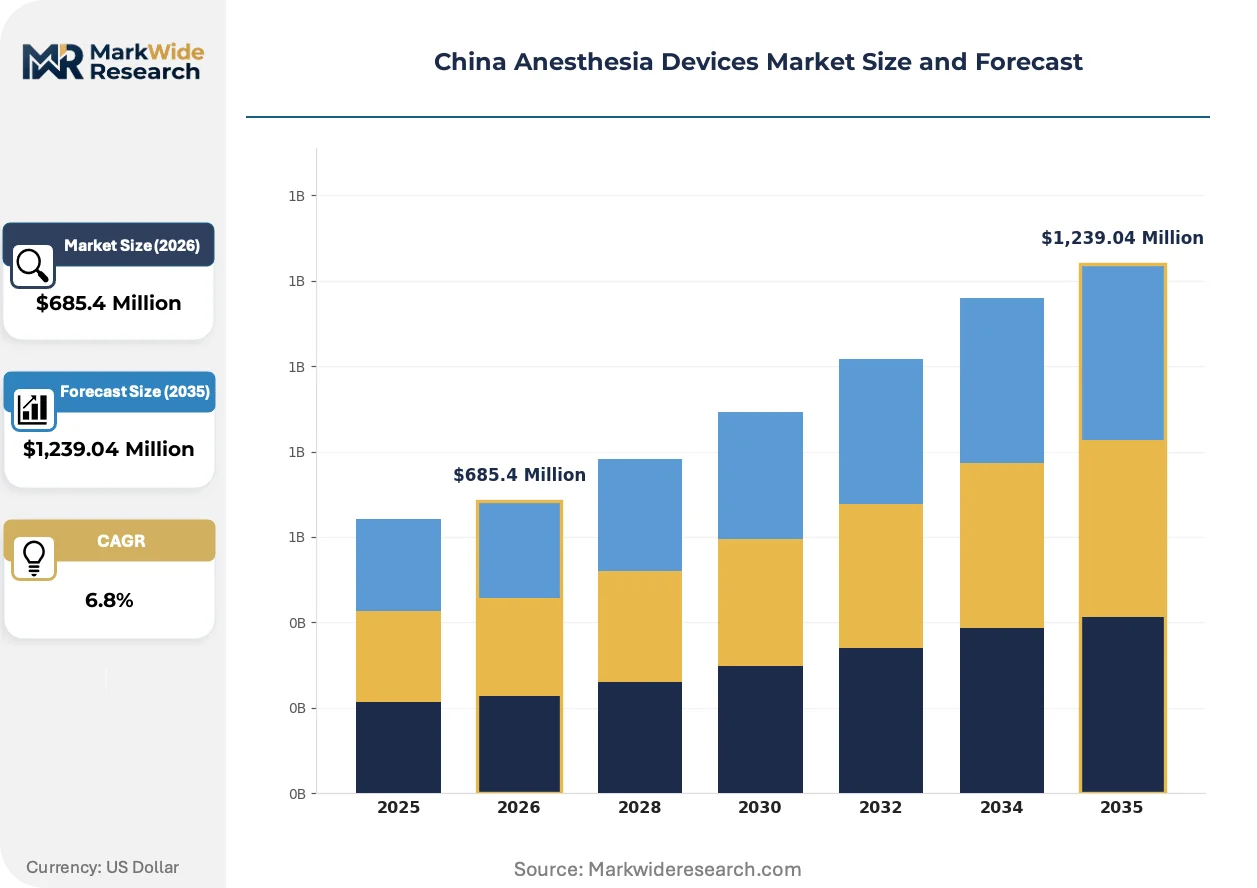
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,239.04 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: Inhalation Anesthesia Machines, Infusion Pumps, Anesthesia Monitoring Systems, Anesthesia Masks End User: Hospitals, Surgical Centers, Clinics, Pain Management Facilities Technology: Virtual Anesthesia Assistant, Closed-Loop Systems, Portable Anesthesia Devices, Wireless Monitoring Application: General Surgery, Orthopedic Surgery, Dental Procedures, Emergency Services |
| Companies Covered | B. Braun Melsungen AG, Beijing Aeonmed Co Ltd, Draegerwerk AG, Fisher & Paykel Healthcare, GE Healthcare, Medtronic PLC, Mindray Medical International Limited, Koninklijke Philips N.V., Smiths Medical, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Anesthesia Devices Market Strategic Shifts
Operating room digitization in Chinese hospitals is fragmenting along a fault line between premium closed-loop systems and cost-optimized conventional workstations, with procurement policy rather than clinical preference determining adoption trajectories.
Closed-loop anesthesia delivery technology is bifurcating the market into two distinct procurement tiers. These systems automatically adjust drug delivery based on real-time physiologic feedback, reducing anesthesiologist cognitive load during complex procedures. Top-tier academic medical centers in Beijing and Shanghai are deploying these systems at replacement cycle points, while provincial hospitals face NMPA registration delays for domestic alternatives. The technology is bifurcating vendor competitive positioning between premium German-engineered platforms and emerging domestic challengers.
China's updated medical device classification rules are accelerating market access for domestically manufactured infusion pumps and patient monitors. The 2021 rule revision reclassified numerous anesthesia accessories from Class III to Class II, cutting registration timelines from 18-24 months to 8-12 months. Domestic manufacturers in Shenzhen and Suzhou are exploiting this regulatory tailwind to displace imported mid-tier products in municipal hospital tenders.
Hospital procurement departments are consolidating anesthesia device purchasing through provincial centralized volume-based procurement platforms. Zhejiang and Jiangsu health commissions now bundle anesthesia workstations, monitors, and infusion pumps into single-tender lots, favoring vendors with full-suite manufacturing capabilities. This consolidation is most visible in East China municipal hospital clusters, where procurement officers prioritize total cost of ownership over discrete equipment performance specifications.
China Anesthesia Devices Market Segmentation
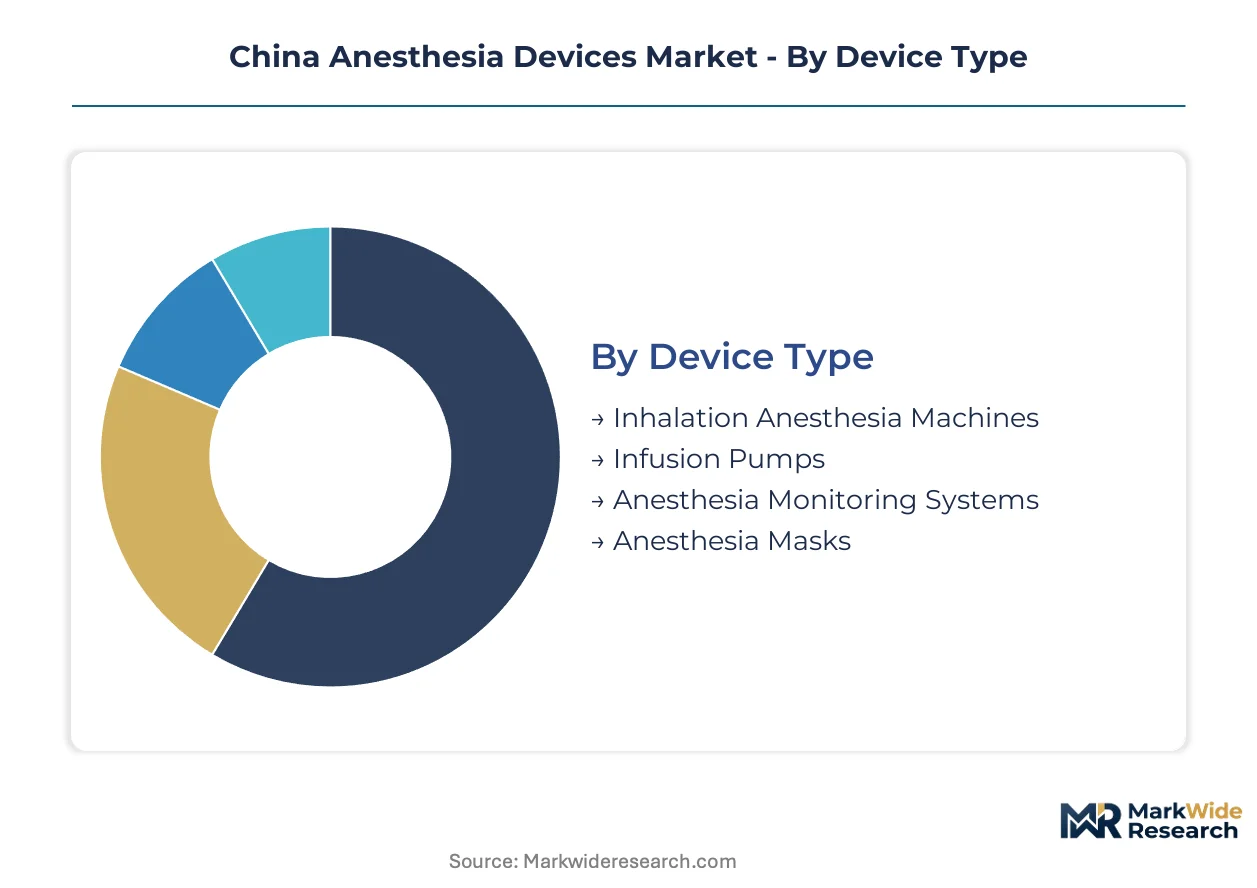
Anesthesia device procurement in China fragments across four intersecting dimensions that determine vendor access and pricing power. Device type and end-user concentration dominate capital allocation decisions, while technology tier and application urgency shape replacement cycles in municipal hospital clusters.
Device Type:
Domestic manufacturing capacity concentrates in infusion pumps and patient monitors, while German and Japanese suppliers retain captive positions in precision vaporizers for inhalation systems.
- Inhalation Anesthesia Machines:Integrated platforms combining precision vaporizers, ventilator modules, and gas delivery circuits maintain end-tidal concentrations within 0.1% accuracy. Tier-three hospitals in Jiangsu and Zhejiang are replacing legacy units with intelligent delivery systems as surgical volumes climb.
- Infusion Pumps:Electromechanical devices for controlled intravenous anesthetic administration face margin compression from provincial centralized procurement programs in Anhui and Jiangsu, though smart pump variants with dose-error reduction software retain pricing power in academic medical centers.
- Anesthesia Monitoring Systems:Multi-parameter physiologic monitors tracking SpO2, EtCO2, and anesthetic gas concentrations.
- Anesthesia Masks:Disposable patient interface devices for inhalational induction and maintenance.
Inhalation anesthesia machines hold the largest share; momentum sits with anesthesia monitoring systems as operating-room digitization accelerates.
End User:
Procurement authority and budget scale vary sharply across facility types, with municipal public hospitals commanding multi-million yuan tenders while pain management facilities purchase through distributor networks.
- Hospitals:Tier-three public institutions in East China municipal clusters drive replacement demand for intelligent anesthesia workstations. NMPA registration timelines for domestic equipment have compressed from 18-24 months to 8-12 months under revised classification rules.
- Surgical Centers:Ambulatory facilities performing same-day procedures favor portable anesthesia devices with rapid turnover capabilities. Central China provinces show penetration rates 30-40 percent below East China levels.
- Clinics:Primary care facilities with limited surgical capacity purchase basic anesthesia masks and manual ventilation equipment.
- Pain Management Facilities:Specialized centers for chronic pain intervention requiring targeted drug delivery systems.
Hospitals command the dominant procurement volume; surgical centers are expanding most quickly as outpatient procedure authorization broadens.
Technology:
Technology tiers separate premium academic medical center deployments from cost-optimized municipal hospital configurations, with wireless convergence enabling new software subscription revenue streams.
- Closed-Loop Systems:Automated anesthesia control platforms adjusting drug delivery based on real-time physiologic feedback reduce anesthesiologist cognitive load. Beijing and Shanghai academic medical centers deploy these at replacement cycle points.
- Wireless Monitoring:Anesthesia gas analysis integrated with hospital information systems enables recurring revenue through software subscriptions. Proprietary data protocols from HIS vendors currently block seamless EMR data flow.
- Virtual Anesthesia Assistant:AI-guided decision support tools for drug selection and dosing recommendations.
- Portable Anesthesia Devices:Compact systems for field deployment and ambulatory surgical applications.
Closed-loop systems anchor premium positioning; wireless monitoring is gaining share fastest as OR digitization mandates proliferate.
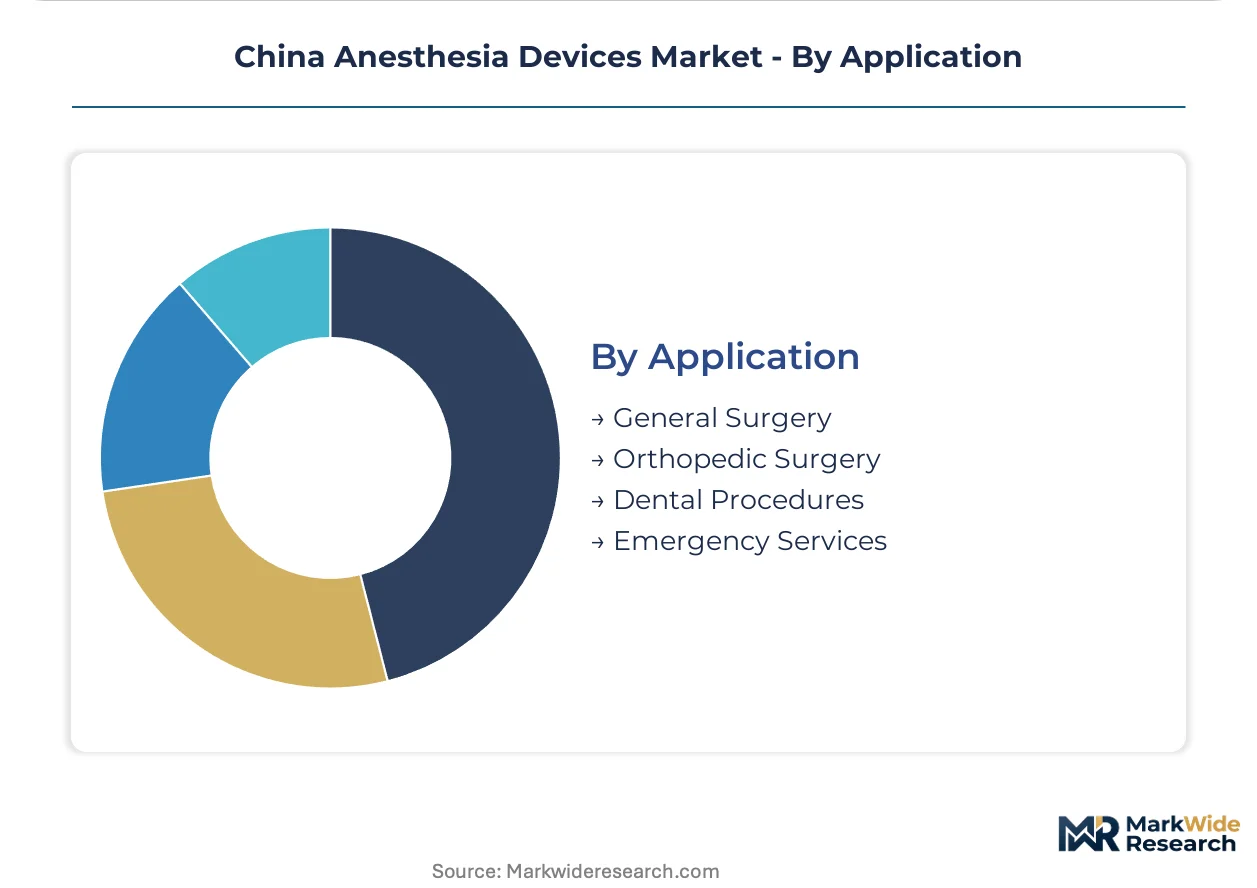
Application:
Procedure complexity and reimbursement rates determine anesthesia workstation specification requirements across surgical service lines.
- General Surgery:Abdominal and thoracic procedures requiring controlled ventilation and multi-agent anesthetic delivery. Jiangsu provincial health commissions bundle anesthesia workstations into single-tender lots favoring full-suite vendors.
- Orthopedic Surgery:Joint replacement and trauma procedures with extended anesthetic durations. Tier-three hospitals in Zhejiang are expanding surgical capacity for aging population demand.
- Dental Procedures:Outpatient extraction and implant surgery using inhalational sedation.
- Emergency Services:Rapid-sequence induction capabilities for trauma and acute intervention.
General surgery consumes the most capital equipment; orthopedic surgery is climbing the fastest as joint replacement volumes rise in East China.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
East China's municipal hospital clusters command 35-40% price premiums over Central China procurement tenders for equivalent anesthesia workstation specifications. Jiangsu and Zhejiang health commissions bundle multi-device contracts that favor vendors with full-suite manufacturing capabilities.
Yangtze River Delta
Tier-three hospitals in Shanghai and Jiangsu are replacing legacy anesthesia machines with intelligent delivery systems as surgical volumes climb. NMPA's updated medical device classification rules have compressed registration timelines for domestic infusion pumps from 18-24 months to 8-12 months. Suzhou and Hangzhou manufacturing clusters are exploiting this regulatory tailwind to displace imported mid-tier products in municipal tenders.
Pearl River Delta
Shenzhen-based domestic manufacturers concentrate production of patient monitors and electromechanical infusion pumps for nationwide distribution. Provincial centralized procurement programs in Guangdong are collapsing margins for standard pump variants by 40-60 percent. The Dongguan-Shenzhen corridor hosts assembly operations for anesthesia monitoring systems serving South China hospital networks.
Beijing-Tianjin-Hebei
Academic medical centers in Beijing deploy closed-loop anesthesia systems at replacement cycle points as clinical evidence accumulates. NMPA registration delays for domestic alternatives constrain provincial hospital access to automated control platforms. Tianjin port logistics facilitate German-engineered vaporizer imports for top-tier institutions requiring precision components.
Sichuan-Chongqing
Western China anesthesia device penetration rates trail East China levels by 30-40 percent, creating whitespace for mid-tier system vendors. Biomedical engineer vacancy rates of 40-60 percent in tier-three hospitals constrain utilization of advanced workstation features. Chengdu municipal health commissions are expanding surgical capacity with cost-optimized conventional machine procurement.
Shandong Peninsula
Qingdao and Jinan hospital clusters are upgrading anesthesia monitoring infrastructure under provincial operating-room digitization mandates. GB 9706 series electromagnetic compatibility testing requirements add 8-14 months to product launch timelines for domestic innovators. Shandong procurement officers prioritize total cost of ownership over discrete equipment performance specifications in bundled tenders.
China Anesthesia Devices Market Competitive Environment
Concentration sits with multinational medical technology conglomerates and scaled domestic manufacturers competing across tiered hospital procurement segments. The vendor base separates into three strategic archetypes: German-engineered premium platforms commanding academic medical center premiums, Chinese mid-tier specialists dominating provincial municipal tenders, and diversified global health technology portfolios leveraging service contract lock-in. Competitive dynamics center on NMPA registration velocity for domestic alternatives and long-term aftermarket maintenance contract capture.
Among German-engineered platform providers, Draegerwerk AG exemplifies premium-tier positioning through closed-loop anesthesia systems. Mindray Medical International Limited occupies the scaled domestic manufacturer archetype with in-house production advantages. GE Healthcare anchors the diversified global portfolio segment via installed-base upgrade cycles and service contract structures. These three company types represent the competitive vectors reshaping hospital procurement outcomes across East China's municipal clusters.
| Leading Market Players |
|---|
| B. Braun Melsungen AG |
| Beijing Aeonmed Co Ltd |
| Draegerwerk AG |
| Fisher & Paykel Healthcare |
| GE Healthcare |
| Medtronic PLC |
| Mindray Medical International Limited |
| Koninklijke Philips N.V. |
| Smiths Medical |
| Others |
Value Chain & Pricing Dynamics
Long-term service contracts with embedded equipment replacement clauses lock in supply access for tier-three hospitals while insulating NMPA-registered domestic manufacturers from spot-market volatility in precision vaporizer sourcing. These structures bundle anesthesia workstation procurement with multi-year maintenance agreements, converting capital expenditure into predictable operational budgets that favor vendors with captive manufacturing capabilities.
Pricing Analysis
Configured-to-order pricing for closed-loop anesthesia systems commands substantial premiums over standard workstation configurations in Beijing and Shanghai academic medical centers. Three-tier pricing structure across premium, standard, and economy levels stratifies by NMPA registration tier and after-sales service bundling, with German-engineered platforms capturing the premium band. Cost compression in standard infusion pumps is intensifying because provincial centralized procurement programs in Jiangsu and Anhui collapse margins through volume-based tender aggregation. Municipal hospital procurement officers exhibit highest price sensitivity, while academic medical centers prioritize clinical performance specifications over unit economics.
Supply Chain Analysis
Germany and Japan anchor precision vaporizer manufacturing for inhalation anesthesia machines, while China concentrates patient monitor and electromechanical infusion pump assembly. Domestic production draws from imported high-accuracy flow sensors, specialized polymer tubing, and precision-machined metal components. Single-source vulnerability in German vaporizer supply exposes tier-three hospital procurement timelines to logistics disruptions at Tianjin port. Distribution runs through provincial health commission centralized tender platforms that consolidate multi-device contracts favoring full-suite domestic manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market rewards regulatory entrenchment as a defensive moat, where NMPA registration velocity and installed-base service lock-in create switching costs that protect incumbent positions from displacement.
For Market Incumbents: Compound defensive positioning through backward integration into precision vaporizer component manufacturing to reduce import dependency exposure. Expand capacity in Suzhou and Hangzhou manufacturing clusters to exploit compressed NMPA registration timelines for Class II reclassified devices. Prioritize software subscription revenue capture through wireless monitoring integration with hospital information systems. For New Entrants and Emerging Players: Lead with mid-tier anesthesia workstation offerings targeting Sichuan-Chongqing and Hubei-Henan provinces where penetration rates trail East China levels by substantial margins. Central China municipal hospitals present the most penetrable geography due to biomedical engineer scarcity constraining utilization of premium closed-loop features. Pursue go-to-market partnerships with provincial distributor networks that maintain relationships with tier-two hospital procurement committees. For Investors and Strategic Acquirers: Capital is best deployed toward domestic manufacturers with NMPA Class III registration capabilities for closed-loop systems and established service infrastructure in East China municipal clusters. Long-term viability over the projection horizon hinges on regulatory entrenchment depth and software-enabled recurring revenue attachment rates. Monitor provincial health commission tender aggregation intensity as the critical inflection signal for margin compression trajectory.| Strategic Initiative | Industry Significance |
|---|---|
| NMPA Class III Registration Acceleration | Compressed timelines for closed-loop systems unlock premium hospital access before multinational incumbents expand service coverage. |
| Wireless Monitoring Platform Integration | Software subscription revenue from HIS-integrated gas analysis creates recurring income streams beyond equipment replacement cycles. |
| Provincial Health Commission Partnership | Direct relationships with Jiangsu and Zhejiang tender committees secure placement in bundled multi-device procurement lots. |
| Precision Component Backward Integration | In-house vaporizer manufacturing reduces currency exposure and logistics vulnerability to German and Japanese supply disruptions. |
| Biomedical Engineer Training Program | Workforce development partnerships with western province hospitals expand addressable market for advanced workstation feature utilization. |
Study Parameters
Cross-validation between hospital procurement database analysis and NMPA registration filing review anchors the qualitative findings on competitive positioning and market access dynamics. Primary interviews with biomedical engineers, hospital purchasing committee members, anesthesia department heads, and GPO contracts managers combined with secondary validation from provincial health commission tender announcements, GB standards documentation, and customs import records. Bottom-up equipment shipment estimates and top-down healthcare capital expenditure allocations were triangulated to establish market sizing boundaries.
Sensitivity analysis across vaporizer import cost scenarios and provincial procurement aggregation intensity informs the projection framework. Segmentation dimensions modeled include device type, end-user facility tier, technology tier, and application urgency across the analysis window. CAGRs were derived from replacement cycle analysis, surgical volume growth trajectories, and NMPA registration velocity differentials between domestic and imported equipment categories. Forecast inputs incorporate dual carbon mandate compliance requirements and electromagnetic compatibility testing timeline assumptions under updated GB 9706 series standards.
The analysis sits within stated boundaries; outcomes outside sustained provincial centralized procurement expansion or NMPA classification rule stability would require recalibration. Forecasts reflect documented assumptions regarding hospital capital budget allocation patterns and domestic manufacturing scale-up trajectories. Specific risk factors include biomedical engineer vacancy persistence in western provinces and proprietary HIS protocol fragmentation blocking seamless EMR integration. Recalibration cycles align with material shifts in provincial tender aggregation policies and NMPA registration timeline announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Intravenous Infusion Pump Market
Medical Devices
Single Lead ECG Equipment Market
Medical Devices
X-Ray Positioning Devices Market
Medical Devices
Veterinary Procedure Lights Market
Medical Devices
Global Hernia Repair Devices Market
Medical Devices
Germany Artificial Organs and Bionics Market
Medical Devices
Global Intraoral Cameras Market
Medical Devices
Global Motion Preservation Devices Market
Medical Devices
US Intrauterine Devices Market
Medical Devices
Intelligent Prosthetics Market
Medical Devices
Electric Massage Equipment Market
Medical Devices
Global Smart Implants Market
Medical Devices
Middle East and Africa Non-Surgical Procedures Market
Medical Devices
Artificial Urinary Sphincters Market
Medical Devices
Subcutaneous Implantable Defibrillator System Market
Medical Devices
Pressotherapy Systems Market