
 Europe Breast Implant Market | 2026-2036
Europe Breast Implant Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Breast Implant Market Insights
Silicone gel formulations is decoupling from older saline-based cost structures across European manufacturing. GC Aesthetics leverages vertically integrated production facilities in Ireland to control regional distribution costs. Polytech Health & Aesthetics GmbH anchors its competitive position through specialized silicone surface texturing technologies. Establishment Labs Holdings Inc. differentiates via proprietary silicone shell designs that address emerging safety protocols.
Breast implants are medical prostheses composed of an elastomer silicone shell filled with either viscous silicone gel or sterile saline solution, designed for surgical insertion to augment or reconstruct mammary tissue. Silicone gel-filled devices dominate European value pools due to superior tactile properties and longer commercial track records, while structured and composite variants occupy emerging niches for revision-specific applications. Reconstruction applications sustain premium pricing through reimbursement-linked procurement channels, whereas aesthetic procedures compete on surgeon preference and device longevity metrics. Clinics and hospitals represent the primary end-user channel, with ambulatory surgery centers capturing faster volume growth across France, Spain, and Italy.
The EU Medical Device Regulation and notified body frameworks under BSI Group and TÜV SÜD are elevating clinical data requirements for silicone implant approvals, extending product development timelines and consolidating manufacturer compliance investments. EMA-aligned vigilance reporting and France's ANSM post-market surveillance mandates are reshaping liability structures and warranty terms across the value chain. Stakeholders must monitor evolving notified body capacity constraints and pre-market clinical study cost trajectories to calibrate European market entry and portfolio prioritization decisions.
Market Dynamics
The EU Medical Device Regulation (MDR) is compressing product development timelines and consolidating compliance investments among silicone breast implant manufacturers. This regulatory pressure is reshaping competitive positioning by favoring firms with captive clinical data generation capabilities and notified body relationships.
Growth Catalysts
- MDR Clinical Evidence Requirements:Stricter pre-market study mandates under BSI Group and TÜV SÜD oversight are filtering out marginal competitors and concentrating market share among established manufacturers with dedicated regulatory affairs infrastructure.
- Metropolitan Surgical Hub Expansion:Aesthetic clinics in Berlin, Paris, and Madrid are scaling procedure volumes through centralized high-throughput facilities that optimize implant inventory turnover and surgeon utilization rates.
- Silicone Gel Formulation Advances:Fifth-generation cohesive gel technologies with enhanced shape retention properties are capturing preference among reconstructive surgeons seeking durable aesthetic outcomes for post-mastectomy patients.
Market Restraints
- Notified Body Capacity Bottlenecks:Limited MDR-designated certification bodies are extending approval timelines to 18-24 months, freezing new entrant pipelines and elevating working capital requirements for pending applications.
- Medical-Grade Silicone Feedstock Concentration:European polymer supply chains depend on a narrow base of specialty chemical producers in Germany and Belgium, creating input cost volatility exposure for shell and gel manufacturers.
- ANSM Post-Market Surveillance Mandates:France's national health safety agency requires enhanced implant registration and longitudinal outcome tracking, adding administrative burden and warranty liability complexity across the value chain.
Strategic Opportunities
- Spain and Italy Ambulatory Surgery Center Penetration:Underdeveloped same-day discharge infrastructure in Mediterranean markets presents whitespace for outpatient-focused implant distribution models with simplified logistics and lower facility overhead.
- Structured Surface Texture Differentiation:Micro-polyurethane and nano-textured shell technologies that reduce capsular contracture rates offer premium positioning opportunities within revision surgery segments.
- EMA-Aligned Vigilance Reporting Integration:Early adoption of centralized European adverse event databases enables manufacturers to convert compliance cost into competitive intelligence and product improvement feedback loops.
Industry Challenges
- Biocompatibility Testing Talent Scarcity:Qualified toxicologists and materials scientists capable of designing MDR-compliant biological evaluation plans command premium compensation and limited availability across the continent.
- Legacy ERP-to-UDI System Integration:Medical device unique device identification requirements are forcing costly middleware development to bridge decades-old manufacturing execution systems with new traceability platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Breast Implant Market |
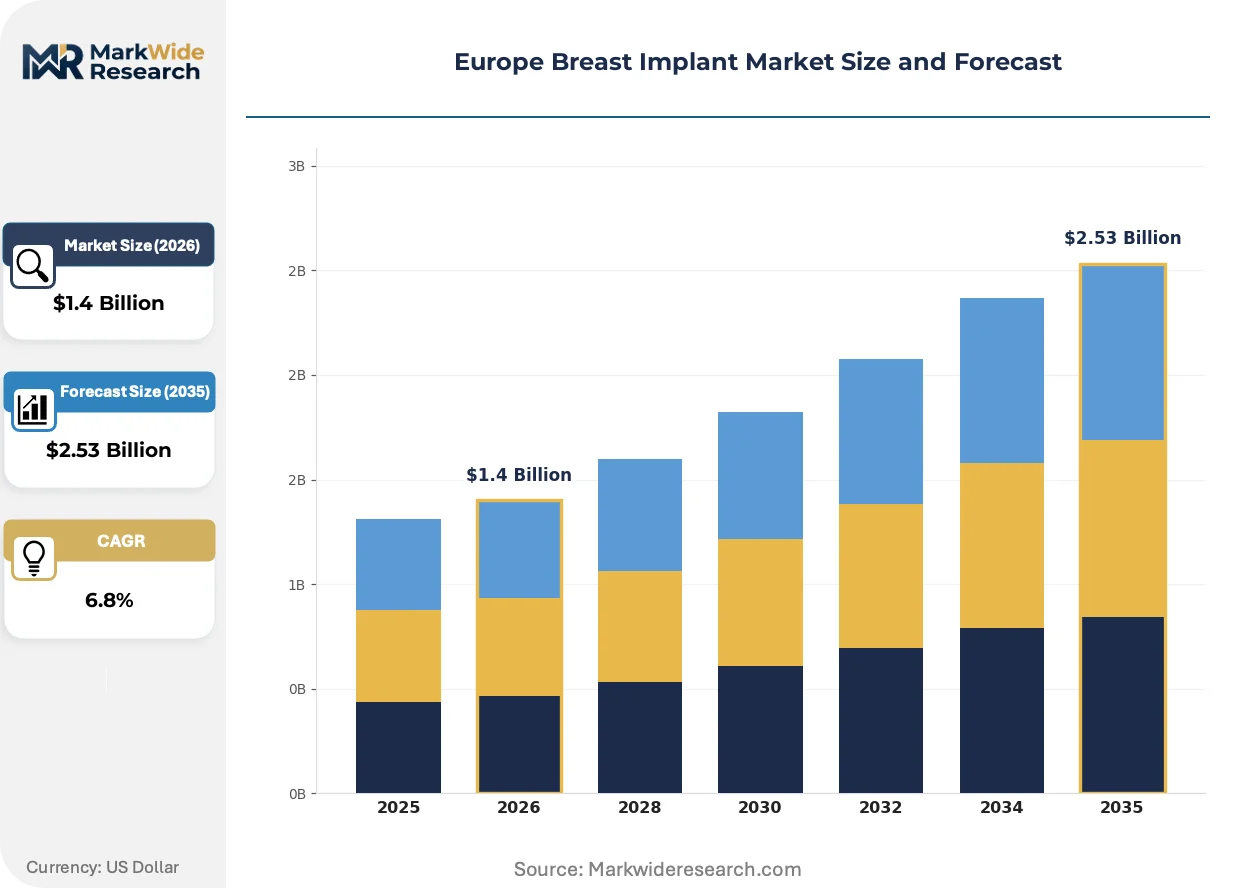
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.53 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Silicone Gel, Saline, Structured, Composite End User: Clinics, Hospitals, Ambulatory Surgery Centers, Medical Spas Application: Reconstruction, Aesthetic, Corrective, Therapeutic Material: Silicone, Polyurethane, Rubber, PMMA |
| Companies Covered | AbbVie Inc. (Allergan PLC), GC Aesthetics, Groupe Sebbin SAS, Laboratories Arion, Johnson & Johnson (Mentor Worldwide LLC), Establishment Labs Holdings Inc., Polytech Health & Aesthetics GmbH, Sientra Inc., EuropeSilicone Laboratoire, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Breast Implant Market Trends and Innovations
Silicone surface engineering and digital surgical planning tools are converging to reshape implant selection workflows and long-term outcome predictability. These developments are compressing the traditional information asymmetry between manufacturers and surgical end-users.
Highly cohesive anatomical silicone gel implants with form-stable properties are overtaking round devices in reconstructive applications across German university hospitals. Breast reconstruction surgeons in Munich and Hamburg academic medical centers are adopting these devices at accelerating rates for immediate post-mastectomy procedures. This technology shift is enabling outcome standardization and reducing revision surgery incidence, compressing total lifetime cost metrics that influence procurement committee decisions.
France's ANSM has implemented mandatory implant passports and enhanced traceability requirements that exceed baseline MDR obligations. This regulatory layering is forcing manufacturers to maintain parallel compliance systems and country-specific documentation workflows. Reconstruction device portfolios face the heaviest documentation burden, as these products require linkage to oncology treatment records and long-term follow-up protocols.
Direct-to-surgeon digital platforms are fragmenting traditional distributor relationships by enabling implant manufacturers to capture preference data and influence device selection earlier in the patient journey. Specialized breast surgery centers in London, Amsterdam, and Stockholm are piloting these channels for aesthetic procedure planning. This behavioral shift is most visible in private-pay segments where surgeon discretion over device choice remains unconstrained by institutional procurement frameworks.
Europe Breast Implant Market Segmentation
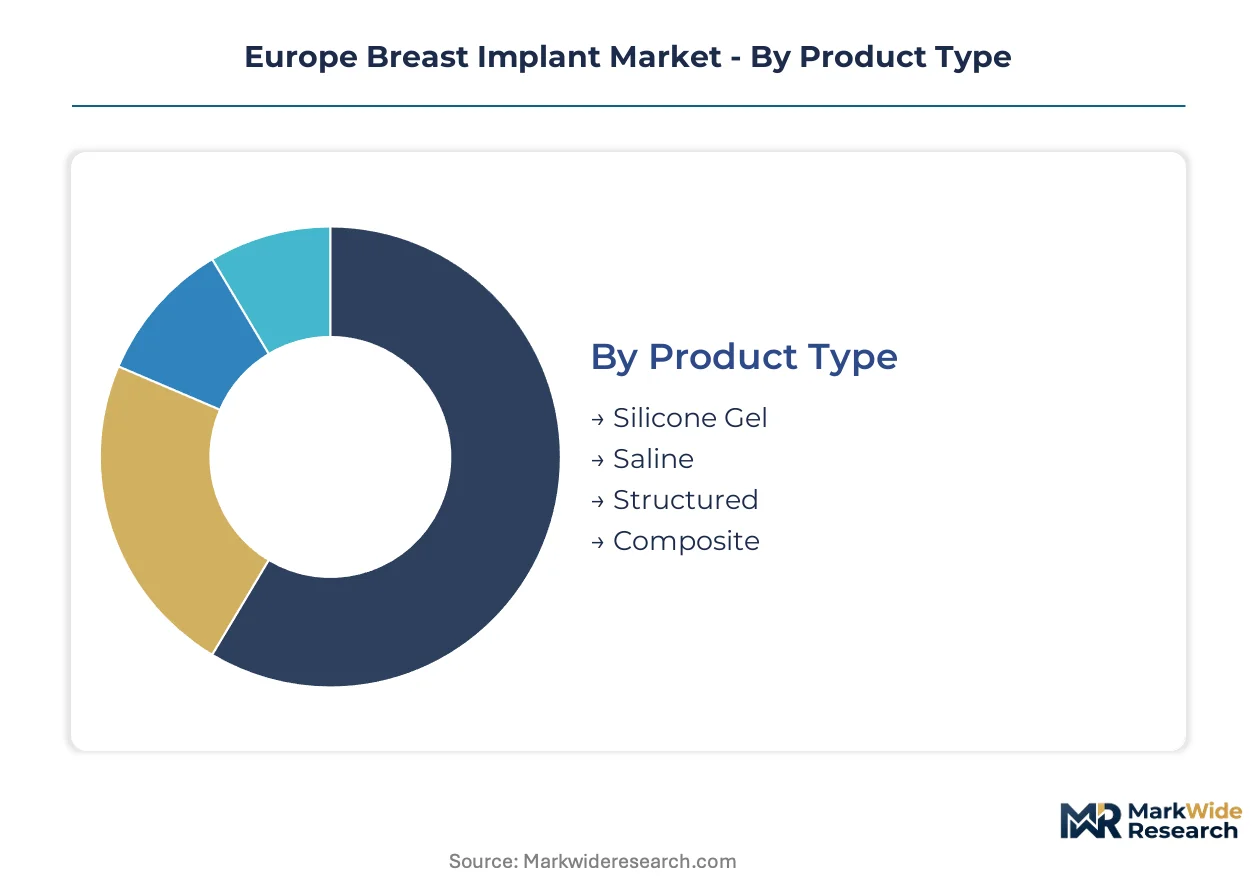
Implant manufacturers navigate divergent approval pathways across Europe depending on segment-specific risk classifications. Product formulation, end-user setting, and intended application each trigger distinct clinical evidence requirements under MDR and notified body frameworks.
Product Type:
Silicone gel formulations demand the most extensive pre-market clinical dossiers under BSI Group and TÜV SÜD review, while saline devices face streamlined biological evaluation requirements.
- Silicone Gel:Fifth-generation cohesive formulations with enhanced shape retention properties dominate procurement at German university hospitals. Demand concentrates in reconstructive applications across Munich and Hamburg academic medical centers where surgeons prioritize tactile outcomes and device longevity metrics.
- Saline:Sterile saline-filled shells with adjustable post-operative volume capabilities retain cost-sensitive positioning in Southern European aesthetic markets. Spanish and Italian clinics favor these devices for price-conscious patient segments where regulatory documentation burdens remain lighter.
- Structured:Multi-layer shell architectures with internal baffling systems address specific revision surgery indications.
- Composite:Hybrid material constructions combining gel and alternative fillers occupy emerging niche applications.
Leading the category by volume: Silicone Gel. Growing fastest: Structured.
End User:
Facility type determines procurement channel structure, with hospital systems leveraging centralized tender processes while independent clinics operate through direct manufacturer relationships.
- Clinics:Dedicated aesthetic surgery centers in Berlin, Paris, and Madrid drive high-throughput implant consumption through concentrated surgeon utilization. These facilities optimize inventory turnover via direct-to-manufacturer ordering platforms that bypass traditional distributor markups.
- Hospitals:German and French public hospital systems anchor reconstructive device procurement through reimbursement-linked frameworks. Procurement committees at these institutions prioritize total lifetime cost metrics and long-term outcome data over upfront device pricing.
- Ambulatory Surgery Centers:Same-day discharge facilities in France, Spain, and Italy capture accelerating volume growth through streamlined logistics.
- Medical Spas:Wellness-oriented facilities with limited surgical infrastructure represent a peripheral channel for consultation and referral services.
Clinics command the largest revenue share. Ambulatory Surgery Centers are expanding most quickly.
Application:
Reconstructive indications sustain premium pricing through oncology-linked reimbursement channels, while aesthetic applications compete on surgeon preference and device differentiation.
- Reconstruction:Post-mastectomy implant procedures require linkage to oncology treatment records and extended follow-up protocols under ANSM mandates. French and German hospital systems prioritize form-stable anatomical devices for immediate reconstruction workflows.
- Aesthetic:Elective augmentation procedures in private-pay segments allow unconstrained surgeon discretion over device selection. London, Amsterdam, and Stockholm surgical centers pilot digital planning platforms that influence implant choice earlier in patient consultations.
- Corrective:Revision surgeries addressing capsular contracture or device malposition command specialized surface texture technologies.
- Therapeutic:Gender-affirming and congenital anomaly applications represent regulated but lower-volume indications.
Reconstruction leads by value. Aesthetic shows the steepest expansion trajectory.
Material:
Shell and filler material selection directly impacts biocompatibility testing scope and notified body evaluation timelines under MDR biological evaluation plans.
- Silicone:Medical-grade elastomer formulations from German and Belgian specialty chemical producers constitute the dominant shell and gel substrate. Supply concentration creates input cost volatility exposure for manufacturers dependent on narrow polymer feedstock bases.
- Polyurethane:Micro-polyurethane surface coatings reduce capsular contracture incidence in revision applications. These textured surfaces command premium positioning within specialized surgical segments.
- Rubber:Alternative elastomer formulations occupy limited legacy device categories.
- PMMA:Polymethyl methacrylate microsphere composites serve specific structural reinforcement applications.
Silicone dominates by installed base. Polyurethane coatings are gaining share fastest in revision segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for breast implants concentrates in Western European metropolitan surgical hubs where aesthetic clinic networks and academic medical centers drive procedure volumes. Germany, France, and the United Kingdom anchor procurement activity through distinct reimbursement and regulatory frameworks. Southern European markets exhibit faster ambulatory surgery center penetration despite lower absolute volumes.
Germany
Reconstructive applications at Munich and Hamburg university hospitals sustain premium device procurement through oncology-linked reimbursement channels. The Federal Institute for Drugs and Medical Devices (BfArM) enforces MDR-aligned vigilance reporting that extends product development timelines for silicone gel formulations. Baden-Württemberg and Bavaria host specialized manufacturing facilities serving regional distribution networks.
France
ANSM post-market surveillance mandates require enhanced implant registration and longitudinal outcome tracking that exceeds baseline EU requirements. Paris-based aesthetic surgery centers drive high-throughput consumption through centralized facilities optimizing surgeon utilization rates. Île-de-France concentrates procurement committee decision-making for public hospital reconstructive device selection.
United Kingdom
London surgical centers pilot direct-to-surgeon digital platforms that fragment traditional distributor relationships in private-pay aesthetic segments. The Medicines and Healthcare products Regulatory Agency (MHRA) maintains post-Brexit alignment with MDR clinical evidence standards for silicone implant approvals. Southeast England clusters academic medical centers adopting form-stable anatomical devices for immediate reconstruction workflows.
Italy
Milan and Rome ambulatory surgery centers capture accelerating volume growth through streamlined same-day discharge infrastructure. The Italian Medicines Agency (AIFA) oversees notified body coordination for silicone gel device approvals under consolidated EU frameworks. Northern Italy exhibits concentrated demand for cost-sensitive saline devices in aesthetic applications.
Spain
Barcelona and Madrid clinics expand implant procedure volumes through high-throughput facilities bypassing traditional distributor markups. The Spanish Agency for Medicines and Health Products (AEMPS) implements MDR-compliant biological evaluation requirements for surface-textured devices. Mediterranean markets present whitespace for outpatient-focused distribution models with simplified logistics.
Europe Breast Implant Market Competitive Landscape
Regulatory compliance investments dominate the current landscape as MDR-designated notified body capacity constraints extend approval timelines to 18-24 months. Market structure consolidates around established manufacturers with dedicated regulatory affairs infrastructure and captive clinical data generation capabilities. Three archetypes define competitive positioning: vertically integrated silicone producers controlling regional distribution costs, specialized surface technology developers commanding revision surgery premiums, and diversified medical device conglomerates leveraging procurement committee relationships. Capacity expansion and strategic partnerships represent the dominant competitive moves as firms navigate biocompatibility testing talent scarcity.
Among Ireland-based manufacturers, GC Aesthetics exemplifies vertically integrated production strategies. Polytech Health & Aesthetics GmbH represents German specialized surface texturing capabilities. Establishment Labs Holdings Inc. anchors the proprietary design archetype addressing emerging safety protocols. Johnson & Johnson and AbbVie Inc. occupy positions within diversified medical device portfolios serving hospital procurement channels. These named entities illustrate how regulatory compliance infrastructure and geographic positioning determine competitive viability under tightened MDR frameworks.
| Leading Market Players |
|---|
| AbbVie Inc. (Allergan PLC) |
| GC Aesthetics |
| Groupe Sebbin SAS |
| Laboratories Arion |
| Johnson & Johnson (Mentor Worldwide LLC) |
| Establishment Labs Holdings Inc. |
| Polytech Health & Aesthetics GmbH |
| Sientra Inc. |
| EuropeSilicone Laboratoire |
| Others |
Pricing and Supply Chain Analysis
Family-owned German and Belgian specialty chemical producers anchor medical-grade silicone feedstock supply, translating concentrated upstream ownership into asymmetric pricing power over shell and gel manufacturers. This ownership pattern compresses margin flexibility for implant producers while reinforcing procurement discipline among notified body-certified manufacturers.
Pricing Analysis
Volume concentration in reconstructive applications at German university hospitals sustains premium pricing for fifth-generation cohesive gel devices, while aesthetic segments in Southern Europe compete on surgeon preference and device longevity metrics. Price differentiation rests on MDR certification tier and surface texturing technology, with micro-polyurethane coatings commanding premiums in revision surgery. Cost compression in saline device tiers is intensifying because Spanish and Italian clinics prioritize cost-sensitive patient segments. Ambulatory surgery centers exhibit highest price sensitivity due to streamlined logistics overhead, whereas hospital procurement committees prioritize total lifetime cost metrics over upfront device pricing.
Supply Chain Analysis
Dual-sourcing requirements from BSI Group and TÜV SÜD notified bodies mandate multi-supplier qualification for silicone polymer feedstock, forcing manufacturers to maintain parallel vendor relationships despite geographic concentration. Supply concentrates in Germany, Belgium, and Ireland for medical-grade elastomer formulations, with shell fabrication drawing from specialized surface texturing facilities. Single-source vulnerability persists for fifth-generation cohesive gel precursors. Distribution runs through direct-to-manufacturer platforms for high-throughput Berlin and Paris clinics, while hospital systems leverage centralized tender processes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe breast implant market is transitioning from round to form-stable anatomical silicone gel technologies, with Munich and Hamburg academic medical centers accelerating adoption for immediate post-mastectomy reconstruction workflows.
For Market Incumbents: Extend captive clinical data generation capabilities to compress MDR approval timelines below the 18-24 month notified body bottleneck. Consolidate regulatory affairs infrastructure across German and French jurisdictions to offset biocompatibility testing talent scarcity. Prioritize backward integration into medical-grade silicone polymer supply to reduce feedstock cost volatility exposure from Belgian and German specialty chemical producers. For New Entrants and Emerging Players: Direct-to-surgeon digital platforms offer lower-friction entry into private-pay aesthetic segments in London, Amsterdam, and Stockholm where procurement committee constraints are absent. Target Spain and Italy ambulatory surgery center whitespace with simplified logistics models and saline device portfolios that face lighter biological evaluation requirements. Pursue surface texture differentiation through micro-polyurethane or nano-textured technologies for revision surgery niches. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap specialists with captive notified body relationships in Ireland and Germany during MDR transition capacity constraints. Five-to-ten year viability hinges on clinical data asset accumulation and EMA-aligned vigilance reporting infrastructure. Watch notified body designation expansion by BSI Group and TÜV SÜD as inflection indicator for new entrant pipeline thaw.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway Acceleration | MDR-designated notified body relationships compress approval timelines for silicone gel formulations under BSI Group oversight. |
| Backward Integration into Silicone Feedstock | Captive polymer supply from German and Belgian producers reduces input cost volatility for shell and gel manufacturing. |
| Hospital System Partnership | Procurement committee relationships at Munich and Hamburg university hospitals secure reconstructive device volume commitments. |
| Software Companion Development | Digital surgical planning tools influence implant selection earlier in patient consultations at London and Stockholm centers. |
| Reimbursement Strategy | Oncology-linked frameworks in France and Germany sustain premium pricing for post-mastectomy reconstruction applications. |
Research Methodology
Document review covered EMA vigilance databases, ANSM implant registration records, and notified body designation lists, complemented by interviews with reconstructive surgeons, hospital procurement managers, biomedical engineers, and regulatory affairs directors at silicone implant manufacturers. Secondary validation drew from BSI Group certification directories, TÜV SÜD technical documentation, and EU MDR implementation guidance. Bottom-up procedure volume estimates from German, French, and UK hospital systems were triangulated against top-down manufacturer shipment data.
Historical reconstruction and aesthetic procedure trends were cross-referenced against surgeon panel input regarding fifth-generation cohesive gel adoption rates. The analytical framework modeled volume and value across product type, end-user facility tier, application indication, and surface material technology throughout the forecast period. CAGRs were derived from fitted trend extrapolation adjusted for MDR implementation phase-in effects and notified body capacity constraints.
Inputs from hospital procurement databases and GPO contracts were available through the study window; gaps in longitudinal ANSM outcome tracking data introduce uncertainty bands around revision surgery incidence assumptions. Forecasts reflect documented assumptions regarding MDR compliance timeline normalization and cohesive gel formulation adoption curves. Deviation in notified body designation expansion or silicone polymer supply disruption would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Medical Bionic Implants and Exoskeletons Market
Medical Devices
Balloon Valvuloplasty Device Market
Medical Devices
Brachytherapy Market
Medical Devices
South Korea ECG Market
Medical Devices
Nasal Implant Market
Medical Devices
Global Automated External Defibrillators Market
Medical Devices
Global Surgical Robotics Market
Medical Devices
Ultrasonic Diathermy Market
Medical Devices
Global Pregnancy Detection Kits Market
Medical Devices
Spectacle Lens Market
Medical Devices
Drug Delivery Solutions Market
Medical Devices
Global Ligation Devices Market
Medical Devices
Neuro Navigation System Market
Medical Devices
Disposable Needle Guides Market
Medical Devices
North America Biopsy Devices Market
Medical Devices
Breast Biopsy Localization Wire Market