
 Attack Helicopter Market | 2026-2036
Attack Helicopter Market Size, Share, and Industry Trends Forecast 2026-2036
Attack Helicopter Market Analysis
Capability gaps in stealth integration and digital avionics is bifurcating the competitive landscape. Boeing leverages its integrated defense systems portfolio to sustain long-term service contracts with NATO-aligned operators. Russian Helicopters anchors regional supply through Rostec's consolidated industrial base. Leonardo specializes in navalized attack variants, occupying niche maritime strike segments where platform corrosion resistance and folding rotor systems differentiate offerings.
An attack helicopter constitutes a rotary-wing combat aircraft engineered for armed assault, typically integrating 20-30mm chain guns, anti-tank guided missiles, and helmet-mounted display systems with thermal imaging sensors. These platforms deliver close air support, armored vehicle interdiction, and armed reconnaissance in contested airspace below fixed-wing operating ceilings. Multirole attack configurations now lead procurement volumes as militaries prioritize fleet commonality over single-mission gunship architectures. Advanced avionics segments attract disproportionate R&D allocation because sensor fusion and manned-unmanned teaming interfaces determine operational effectiveness against layered air defenses. Heavy attack variants retain concentrated margin pools despite lower unit volumes, since armor protection, redundant flight systems, and maximum gross weights above ten metric tons command premium pricing from wealthier defense budgets.
The US FAA coordinates civil airworthiness standards for dual-use rotary platforms, while military certification falls under Pentagon-directed MIL-STD-810 environmental testing protocols. European operators navigate EASA military oversight alongside national defense procurement regulations that mandate offset agreements and technology transfer. India's Ministry of Defence enforces indigenous content thresholds through the Defence Acquisition Procedure, compelling foreign OEMs to partner with Hindustan Aeronautics Limited for domestic assembly. Stakeholders must weigh sovereign content requirements against proprietary technology protection when structuring joint ventures for emerging fleet replacement cycles.
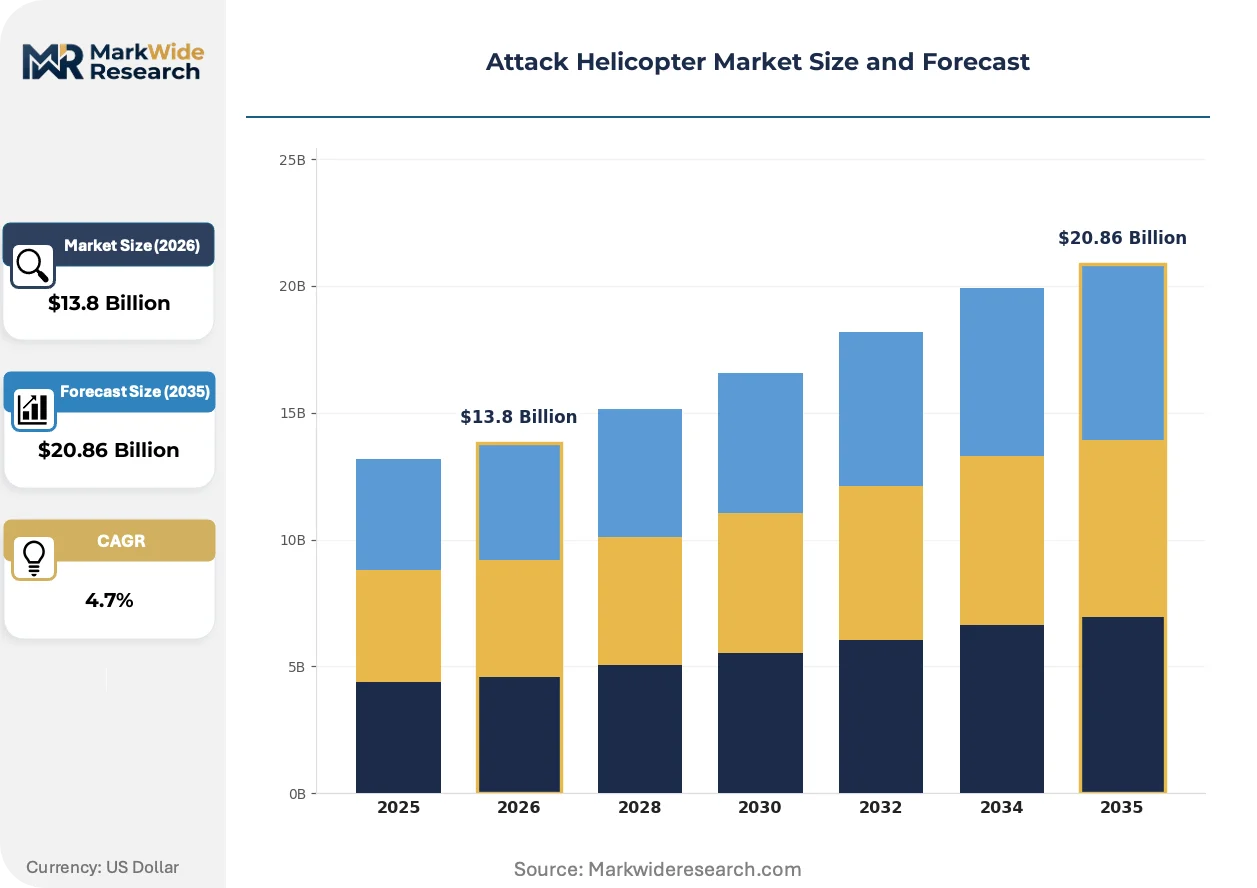
Market Dynamics
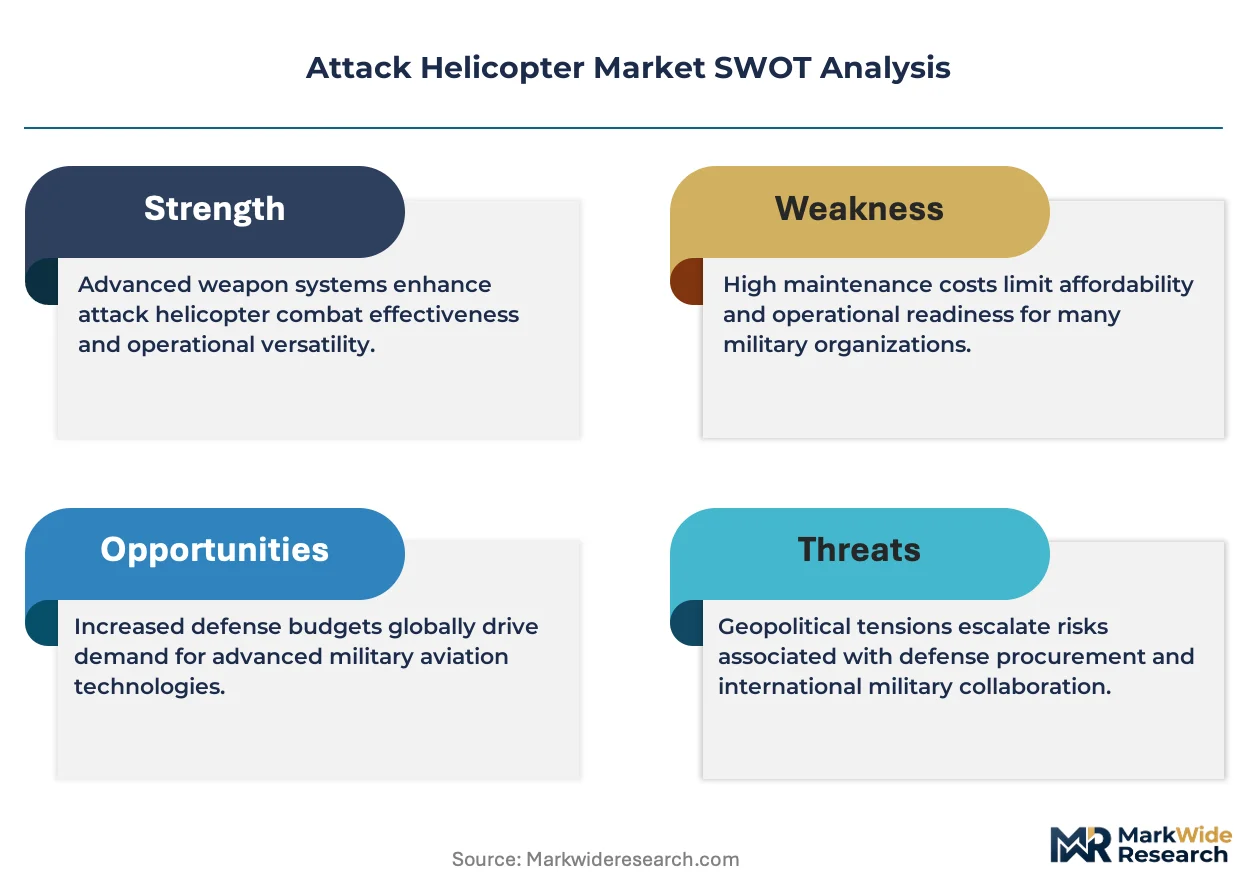
Stealth integration and digital avionics upgrades are bifurcating procurement criteria, splitting operators between legacy fleet life-extension programs and clean-sheet next-generation acquisitions that demand sensor fusion and manned-unmanned teaming interfaces.
Growth Catalysts
- India's Defence Acquisition Procedure:Indigenous content thresholds compel foreign OEMs to partner with Hindustan Aeronautics Limited for domestic assembly, accelerating localized production capacity.
- Layered air defense proliferation:Militaries across contested regions prioritize advanced avionics segments where sensor fusion determines operational effectiveness below fixed-wing operating ceilings.
- Navalized attack variants:Maritime strike segments reward platform corrosion resistance and folding rotor systems, opening fleet modernization pathways for coastal defense forces.
Market Restraints
- Titanium and composite input volatility:Armor protection and redundant flight systems in heavy attack variants concentrate exposure to aerospace-grade material price swings.
- Rostec's consolidated industrial base:Russian Helicopters anchors regional supply through state-controlled vertical integration, limiting alternative sourcing for NATO-aligned operators.
- MIL-STD-810 environmental testing protocols:Pentagon-directed certification timelines extend development cycles for new platform entries, compressing competitive windows.
Strategic Opportunities
- Multirole attack configurations:Fleet commonality priorities over single-mission gunship architectures create volume advantages for platforms integrating 20-30mm chain guns with anti-tank guided missiles.
- Helmet-mounted display convergence:Thermal imaging sensor integration with pilot interface systems opens upgrade revenue streams for existing medium-lift fleets.
- EASA military oversight alignment:European operators navigating dual certification pathways create demand for platforms satisfying both civil airworthiness and defense procurement regulations.
Industry Challenges
- Sensor fusion engineering scarcity:Manned-unmanned teaming interface development requires specialized avionics talent pools concentrated among defense primes with captive R&D facilities.
- Legacy platform integration friction:Digital avionics retrofits onto airframes designed for analog architectures demand bespoke engineering that erodes margin on upgrade contracts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Attack Helicopter Market |
| Market Size in 2026 | $13.8 Billion |
| Market Size in 2035 | $20.86 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Light Attack, Medium Attack, Heavy Attack, Multirole Attack Technology: Gunship, Rotary-Wing, Advanced Avionics, Stealth Design End User: Military, Law Enforcement, Private Security, Government Application: Combat Operations, Reconnaissance, Search and Rescue, Close Air Support |
| Companies Covered | Bell Textron Inc., Russian Helicopters (Rostec), The Boeing Company, MD Helicopters Inc., Hindustan Aeronautics Limited, Lockheed Martin Corporation, Leonardo S.p.A., Turkish Aerospace Industries, Airbus Helicopters, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Attack Helicopter Market Emerging Trajectories
Active electronically scanned array radar integration and low-observable airframe treatments are compressing the performance gap between attack helicopters and fixed-wing close air support platforms, reshaping mission allocation across combined arms formations.
Fly-by-wire flight control architectures with triple redundancy are displacing mechanical linkages in new platform designs. Heavy attack variant programs in wealthier defense budgets mandate these systems for survivability against electromagnetic interference. This shift is displacing legacy hydromechanical suppliers from prime contractor tiers while concentrating avionics integration roles among firms with proprietary control law software.
The EU Green Deal's defense sector emissions reporting requirements are pressuring European operators to document fuel consumption and lifecycle carbon footprints for rotary platforms. EASA military oversight divisions are developing certification pathways for sustainable aviation fuel compatibility in turbine engines. Navalized attack variants with extended maritime endurance requirements face the steepest compliance timelines due to salt-corrosion interaction with alternative fuel chemistries.
After-sales service unbundling is fragmenting traditional through-life support contracts. NATO-aligned operators now separate airframe maintenance from avionics refresh and weapons integration, enabling competitive tendering for each workstream. This pattern concentrates most visibly in Asia-Pacific fleet modernization programs where defense offset policies mandate local maintenance infrastructure development alongside platform delivery.
Attack Helicopter Market Segmentation
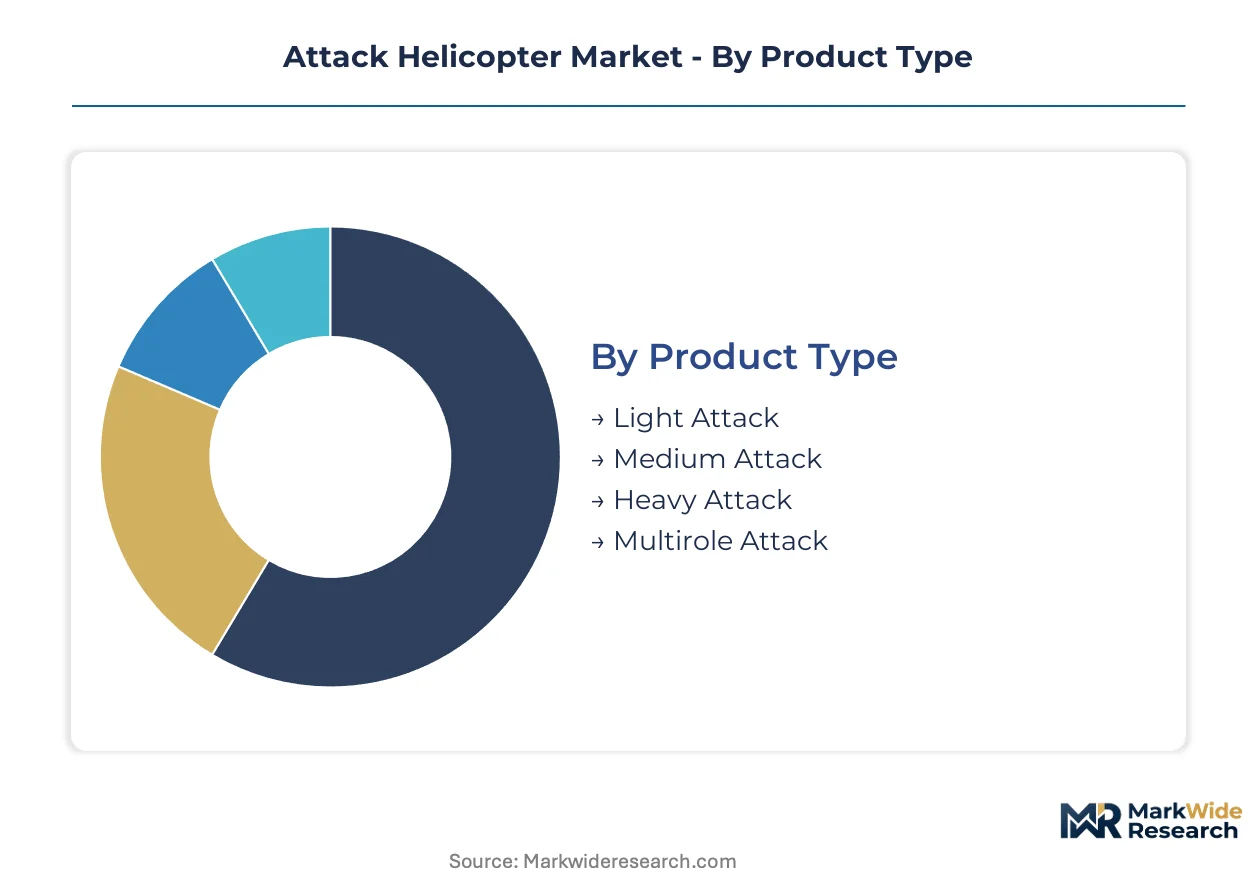
Attack helicopter procurement splits along capability tiers and operational envelopes, with platform weight class and mission architecture determining certification pathways and sovereign content requirements. Segment boundaries are hardening as defense offset policies and indigenous production mandates reshape supplier relationships across major fleet replacement programs.
Product Type:
FAA and EASA military oversight divisions apply divergent airworthiness standards across weight classes, with heavy variants triggering extended environmental testing protocols under MIL-STD-810 guidelines.
- Light Attack:Platforms under six metric tons gross weight prioritize maneuverability in urban close air support and counter-insurgency roles. India's Hindustan Aeronautics Limited concentrates domestic assembly capacity here under Defence Acquisition Procedure offset thresholds, though armor protection trade-offs limit penetration against layered air defenses.
- Heavy Attack:Maximum gross weights exceeding ten metric tons integrate redundant flight systems and titanium-composite armor packages. Wealthier NATO-aligned budgets concentrate demand for these variants where survivability against electromagnetic interference commands premium pricing through triple-redundant fly-by-wire architectures.
- Medium Attack:Five-to-eight ton platforms balance payload flexibility with forward basing requirements.
- Multirole Attack:Configurations integrating 20-30mm chain guns with anti-tank guided missiles now lead procurement volumes as fleet commonality displaces single-mission gunship architectures.
Heavy Attack handles the majority of throughput; Multirole Attack is the fastest mover on share.
Technology:
Cost tier differentiation separates legacy mechanical systems from digitally integrated architectures, with sensor fusion capabilities determining operational effectiveness premiums.
- Advanced Avionics:Helmet-mounted display convergence with thermal imaging sensors and manned-unmanned teaming interfaces attracts disproportionate R&D allocation. Layered air defense proliferation across contested Asia-Pacific regions prioritizes these segments where pilot situational awareness determines mission survivability below fixed-wing operating ceilings.
- Stealth Design:Low-observable airframe treatments and active electronically scanned array radar integration compress the performance gap with fixed-wing close air support. Navalized variants with folding rotor systems and corrosion-resistant coatings command specialized maritime strike premiums from coastal defense forces.
- Gunship:Analog-era architectures with mechanical flight controls dominate legacy fleet life-extension programs.
- Rotary-Wing:Baseline turboshaft propulsion configurations without digital integration serve training and secondary transport roles.
Advanced Avionics captures the steepest margin expansion; Stealth Design is climbing the fastest on procurement priority lists.
End User:
Customer type determines funding stability and through-life support contracting structures, with sovereign defense budgets offering multi-decade revenue visibility against commercial security operators.
- Military:National defense procurement regulations across India, the United States, and European Union member states mandate indigenous content thresholds and technology transfer agreements. Asia-Pacific fleet modernization programs drive the dominant share of attack helicopter acquisition volume through structured offset policies requiring local maintenance infrastructure.
- Law Enforcement:Border patrol and counter-narcotics configurations prioritize sensor persistence over armor protection, with FAA civil airworthiness standards applying to dual-use rotary platforms.
- Government:Non-military state agencies with disaster response mandates operate medium-lift fleets for search and rescue coordination.
- Private Security:Contracted airborne security services face restricted access to weapons-integrated platforms under export control regimes.
Military absorbs the dominant procurement volume; Law Enforcement is expanding most quickly as border security budgets harden.
Application:
Operational mission profiles dictate platform configuration trade-offs between armor, endurance, and sensor payload, with combined arms doctrine reshaping mission allocation across rotary and fixed-wing assets.
- Close Air Support:Armored vehicle interdiction below fixed-wing operating ceilings demands integrated anti-tank guided missile systems and 20-30mm chain gun stabilization. Contested airspace operations in Asia-Pacific and Eastern European theaters concentrate procurement for these missions where stealth integration and digital avionics determine effectiveness against mobile air defense networks.
- Reconnaissance:Armed scouting roles prioritize sensor fusion and manned-unmanned teaming interfaces for target designation without direct engagement. Extended maritime endurance requirements for navalized variants face EU Green Deal emissions compliance timelines due to salt-corrosion interaction with sustainable aviation fuel chemistries.
- Combat Operations:High-intensity combined arms missions require full armor protection and redundant flight systems.
- Search and Rescue:Combat search and rescue configurations balance defensive armament with hoist capacity and medical evacuation fit-outs.
Close Air Support maintains the largest mission allocation; Reconnaissance is gaining share fastest as sensor-centric warfare doctrines mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium pricing for heavy attack variants concentrates in NATO-aligned European defense budgets, while India's indigenous production mandates under Defence Acquisition Procedure compress import-dependent cost structures across Asia-Pacific fleet modernization programs.
United States
Pentagon-directed MIL-STD-810 certification timelines and triple-redundant fly-by-wire mandates drive procurement for heavy attack configurations. FAA coordinates civil airworthiness standards for dual-use rotary platforms alongside military oversight. The Boeing Company and Bell Textron anchor domestic manufacturing clusters in Texas and Pennsylvania, sustaining long-term service contracts through integrated defense systems portfolios.
India
Defence Acquisition Procedure indigenous content thresholds compel foreign OEMs to partner with Hindustan Aeronautics Limited for domestic assembly. Ministry of Defence offset policies mandate local maintenance infrastructure development alongside platform delivery. Hindustan Aeronautics Limited expands production capacity at Bangalore and Hyderabad facilities under structured technology transfer agreements with international primes.
Germany
EASA military oversight divisions navigate dual certification pathways alongside national defense procurement regulations requiring offset agreements. EU Green Deal emissions reporting requirements pressure documentation of fuel consumption and lifecycle carbon footprints for rotary platforms. Airbus Helicopters maintains engineering and final assembly operations at Donauwörth, specializing in navalized attack variants with corrosion-resistant coatings.
United Kingdom
Ministry of Defence fleet commonality priorities favor multirole attack configurations integrating sensor fusion capabilities. National procurement regulations mandate sovereign content thresholds for through-life support contracting structures. Leonardo's Yeovil facility concentrates on maritime strike segments where folding rotor systems differentiate navalized offerings for coastal defense forces.
Turkey
Domestic defense industrial base expansion drives indigenous platform development under national offset frameworks. Turkish Aerospace Industries anchors regional supply for medium-attack variants with advanced avionics integration. Ankara-based engineering clusters focus on helmet-mounted display convergence and thermal imaging sensor systems for pilot situational awareness enhancements.
Attack Helicopter Market Vendor Landscape
Concentration sits with integrated defense primes possessing captive R&D facilities for sensor fusion engineering. The vendor base structures across three tiers: legacy airframe manufacturers with established through-life support networks, avionics specialists controlling proprietary control law software, and state-controlled vertical integrators anchoring regional supply. Tier boundaries harden as defense offset policies and indigenous production mandates reshape supplier relationships. Competitive moves center on strategic partnerships for technology transfer compliance and geographic expansion into fleet replacement cycles across Asia-Pacific markets.
Within the integrated defense prime tier, The Boeing Company and Lockheed Martin Corporation exemplify portfolio breadth spanning airframe production through long-term service contracting. Leonardo S.p.A. occupies a specialized position in navalized attack variants where platform corrosion resistance and folding rotor systems command maritime strike premiums. Hindustan Aeronautics Limited represents the state-backed indigenous production archetype, leveraging Defence Acquisition Procedure mandates to capture domestic assembly volume under technology transfer frameworks. Russian Helicopters sits within the consolidated state-controlled vertical integration model, limiting alternative sourcing pathways for NATO-aligned operators through Rostec's captive industrial base.
| Leading Market Players |
|---|
| Bell Textron Inc. |
| Russian Helicopters (Rostec) |
| The Boeing Company |
| MD Helicopters Inc. |
| Hindustan Aeronautics Limited |
| Lockheed Martin Corporation |
| Leonardo S.p.A. |
| Turkish Aerospace Industries |
| Airbus Helicopters |
| Others |
Supply Flow & Price Mechanics
Long-term service contracts with NATO-aligned operators lock in both titanium-composite armor supply access and price visibility across heavy attack variant programs, while India's Defence Acquisition Procedure offsets compress import-dependent cost structures through Hindustan Aeronautics Limited domestic assembly partnerships.
Pricing Analysis
Configured-to-order pricing for heavy attack variants with triple-redundant fly-by-wire architectures commands substantial premiums over standard multirole configurations, with differentiation driven by MIL-STD-810 certification grade and sovereign content thresholds under national offset policies. Cost compression in light attack segments intensifies because Hindustan Aeronautics Limited localized production eliminates import duties and foreign exchange exposure. Military end users in Asia-Pacific demonstrate highest price sensitivity due to budget constraints, while NATO-aligned operators in Germany and the United Kingdom absorb premium pricing for survivability-enhanced heavy variants.
Supply Chain Analysis
Port congestion along Asia-Pacific trade lanes elevates inbound logistics costs for aerospace-grade titanium and carbon-fiber prepregs destined for Indian and Turkish assembly facilities. Supply concentrates in the United States for advanced avionics and sensor fusion systems, Russia for Rostec-consolidated helicopter subsystems, and Italy for navalized corrosion-resistant coatings. Production draws from titanium ore processed in China and Australia, composite resins manufactured in Japan, and precision-forged rotor hubs from German engineering clusters. Single-source vulnerability around active electronically scanned array radar modules from captive defense prime R&D facilities poses structural risk. Distribution runs through government-to-government foreign military sale channels and offset-mandated joint venture structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized engineering talent for manned-unmanned teaming interface development represents the critical capability gap, with sensor fusion expertise concentrated among integrated defense primes possessing captive R&D facilities and proprietary control law software.
For Market Incumbents: Consolidate control over avionics integration tiers by acquiring specialist firms with proprietary helmet-mounted display convergence technology, while expanding Bangalore and Hyderabad maintenance infrastructure partnerships to satisfy India's Defence Acquisition Procedure offset mandates. Emerging indigenous production mandates across Asia-Pacific fleet modernization programs threaten traditional export-dependent revenue streams. Backward integration into titanium-composite armor supply chains reduces exposure to aerospace-grade material price volatility. For New Entrants and Emerging Players: EASA military oversight fast-track certification for navalized attack variants with folding rotor systems opens white-space access in European coastal defense segments underserved by established primes. Law enforcement border patrol configurations present the most penetrable end-use category given lower armor protection requirements and FAA civil airworthiness pathways. Target sensor persistence upgrades for existing medium-lift fleets through competitive tendering for avionics refresh workstreams unbundled from airframe maintenance contracts. For Investors and Strategic Acquirers: Avionics specialists controlling proprietary control law software and sensor fusion engineering talent represent the priority acquisition archetype, with long-term viability hinging on through-life support contract visibility across multi-decade military procurement cycles. Platform standardization trends toward multirole attack configurations favor firms with modular weapons integration capabilities. Watch for EU Green Deal sustainable aviation fuel certification timelines as inflection indicator for navalized variant program viability, given salt-corrosion interaction with alternative fuel chemistries.| Strategic Initiative | Industry Significance |
|---|---|
| Technology Transfer Partnership | Hindustan Aeronautics Limited domestic assembly capacity expands under Defence Acquisition Procedure indigenous content thresholds. |
| Sensor Fusion R&D Investment | Manned-unmanned teaming interface development determines operational effectiveness against layered Asia-Pacific air defenses. |
| Navalized Variant Certification | EASA military oversight pathways for corrosion-resistant coatings address EU Green Deal emissions compliance timelines. |
| After-Sales Service Unbundling | Separate competitive tendering for avionics refresh concentrates upgrade revenue streams among specialized integrators. |
| Backward Integration into Armor Supply | In-house titanium-composite production mitigates price volatility exposure for heavy attack variant programs. |
Methodological Framework
Operator-level perspectives from attack helicopter program managers, military procurement officers, avionics integration engineers, and aftermarket service directors anchored the qualitative base, supplemented by secondary validation from Pentagon MIL-STD-810 certification records, EASA military oversight division filings, India's Defence Acquisition Procedure offset documentation, and customs trade data for aerospace-grade titanium and composite inputs. Bottom-up platform delivery tallies across Hindustan Aeronautics Limited, Boeing, and Leonardo production facilities triangulated against top-down defense budget appropriations from NATO-aligned and Asia-Pacific ministries.
Sensitivity analysis across the projection horizon tested forecast robustness against alternative scenarios for indigenous production mandate acceleration and sustainable aviation fuel certification delays. Segmentation dimensions modeled include platform weight class, technology tier, end-user type, and application mission profile alongside regional regulatory cluster differentiation. CAGRs derived from exponential smoothing of historical delivery volumes adjusted for fleet replacement cycle timing and offset policy implementation schedules. Industry-specific inputs incorporated fly-by-wire adoption rates and helmet-mounted display convergence penetration curves.
Decision-makers should treat outputs as directional under sustained defense budget growth and stable aerospace material supply assumptions; material deviation would warrant model refresh. Specific risk factors include abrupt export control regime tightening, Rostec supply disruption contagion effects, and EU Green Deal compliance timeline acceleration. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft
Military Trainer Aircraft Market
Aircraft
Aircraft Galley Systems Market
Aircraft
Freighter Aircraft Market
Aircraft
Aircraft Cables Market
Aircraft
Aircraft Mounts Market
Aircraft
Global Business Aircraft Market
Aircraft
Europe Commercial Aircraft Market
Aircraft
Aircraft Galley Equipment Market
Aircraft
Air Deflector Market
Aircraft
Global Aircraft Design and Engineering Market
Aircraft
Air Starter Market
Aircraft
United States Aerospace and Defense Market
Aircraft
Commercial Aircraft Market
Aircraft
Aircraft Lavatory System Market
Aircraft
Asia-Pacific Business Jet Market
Aircraft
Aircraft Windshield Wiper and Washer System Market