
 Air Deflector Market | 2026-2036
Air Deflector Market Size, Share, and Industry Trends Forecast 2026-2036
Air Deflector Market Intelligence
The push for greater fuel economy, codified in regulations like the US EPA's standards for heavy-duty vehicles, is restructuring demand for aerodynamic components. This shift benefits large-scale suppliers such as Magna International Inc., which leverages its deep OEM relationships and manufacturing scale. Plastic Omnium specializes in lightweight composite materials for front and rear deflectors. In the aftermarket, Lund International differentiates through its extensive distribution network and brand recognition among vehicle enthusiasts.
An air deflector is an aerodynamic component, typically molded from polycarbonate or acrylic, designed to redirect airflow around a vehicle. Its primary purpose is to reduce aerodynamic drag and wind noise, thereby improving fuel efficiency and vehicle stability. While acrylic remains a common material choice for its clarity, polycarbonate offers superior impact resistance. The passenger vehicle application represents a mature market, whereas the commercial transport segment shows significant growth potential driven by operational cost savings.
Compliance with regional standards is critical for market access, governed by bodies like the US NHTSA and regulations such as the EU's CE marking framework. China's GB standards also dictate material and performance requirements for automotive components sold within its borders. The key decision for manufacturers is balancing investment between supplying OEMs with integrated designs and serving the high-volume aftermarket with universal and vehicle-specific products.
Market Dynamics
The central dynamic in the air deflector market is the bifurcation of demand between OEM-integrated systems for new commercial vehicles and universal-fit products for the aftermarket, a split driven by global fuel efficiency and emissions regulations.
Growth Catalysts
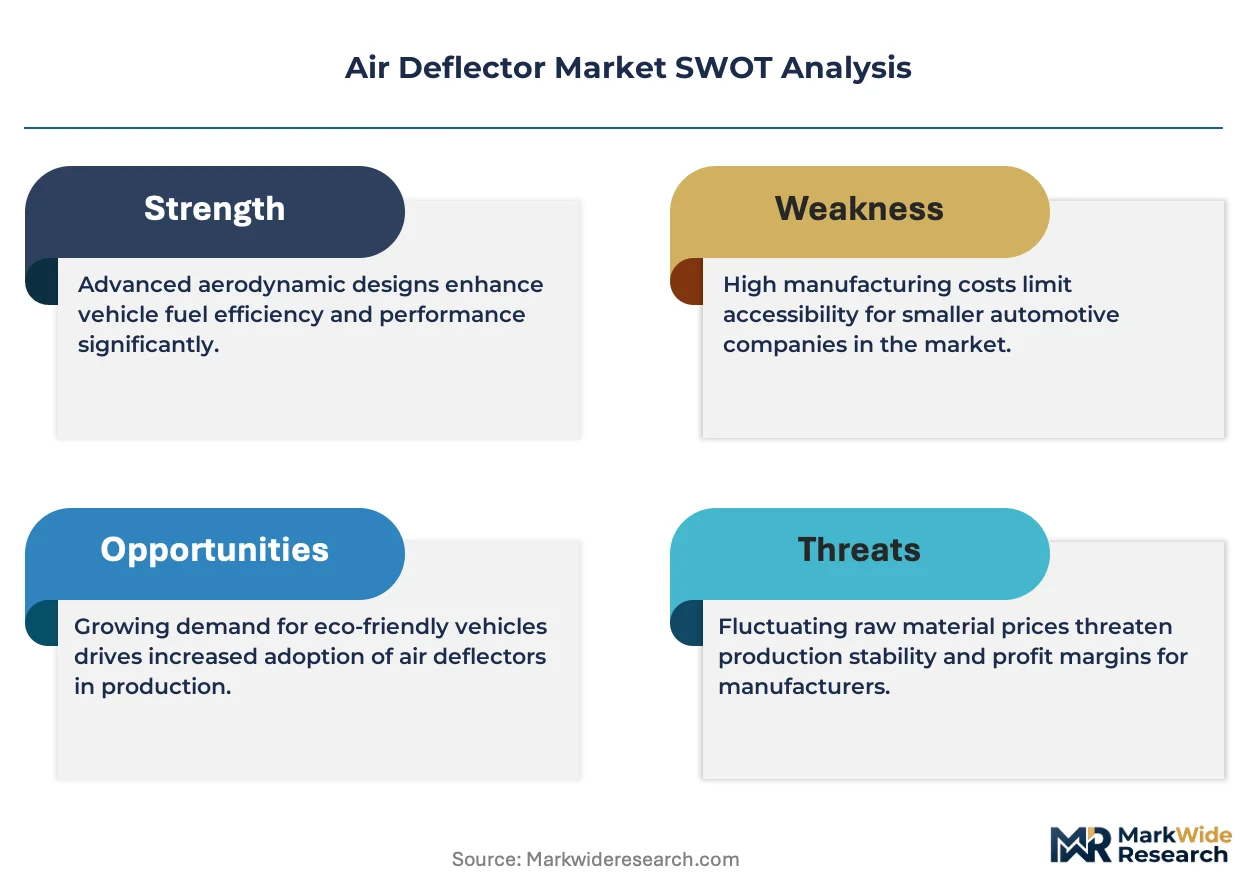
- Emissions Regulations:The EU Green Deal and comparable standards from the US EPA mandate reductions in CO2 emissions from heavy-duty vehicles, compelling fleet operators to adopt aerodynamic components to improve fuel economy and ensure compliance.
- Operational Cost Savings:The commercial transport sector, particularly in logistics-heavy economies like Germany, utilizes air deflectors to reduce fuel consumption, which represents a significant portion of total operating costs for long-haul freight carriers.
- Material Advancement:The development of high-impact, lightweight polycarbonate and composite materials enables the production of more durable and effective deflectors, improving performance and extending product lifespan compared to traditional acrylics.
Market Restraints
- Raw Material Price Volatility:The market's profitability is sensitive to fluctuations in the price of petroleum-derived raw materials, specifically polycarbonate and acrylic resins, which are primary inputs for manufacturing and subject to global supply chain disruptions.
- OEM Design Integration:Vehicle manufacturers are increasingly incorporating aerodynamic features directly into the body design of new models, which can reduce the addressable market for separate, bolt-on aftermarket air deflector products, particularly for passenger cars.
- Substitution by Active Systems:The emergence of active aerodynamic systems, such as automatically adjusting spoilers and grille shutters, presents a long-term substitution threat to static, passive air deflectors in high-performance and premium vehicle segments.
Strategic Opportunities
- Active Aerodynamic Systems:Developing smart deflectors with sensors and actuators that adjust automatically based on vehicle speed and wind conditions offers a path to higher-value products for both premium passenger vehicles and next-generation commercial trucks.
- Light Commercial Vehicle (LCV) Fleets:Targeting the underpenetrated LCV segment in emerging markets across Southeast Asia and Latin America with cost-effective, vehicle-specific deflectors can open new volume opportunities outside the saturated heavy-duty truck market.
- Recycled and Bio-based Polymers:Innovating with recycled polycarbonate or developing bio-based polymer alternatives aligns with automotive OEM sustainability goals and can create a competitive advantage under circular economy regulations like those proposed in the EU.
Industry Challenges
- Regulatory Fragmentation:Manufacturers face complexity and higher testing costs in adhering to disparate regional safety and material standards, such as the US NHTSA's requirements, Europe's CE marking, and China's GB standards for automotive parts.
- ADAS Sensor Interference:Integrating front-end deflectors without interfering with the functionality of critical Advanced Driver-Assistance Systems (ADAS) sensors, such as radar and lidar units, requires significant R&D investment and sophisticated testing protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Air Deflector Market |
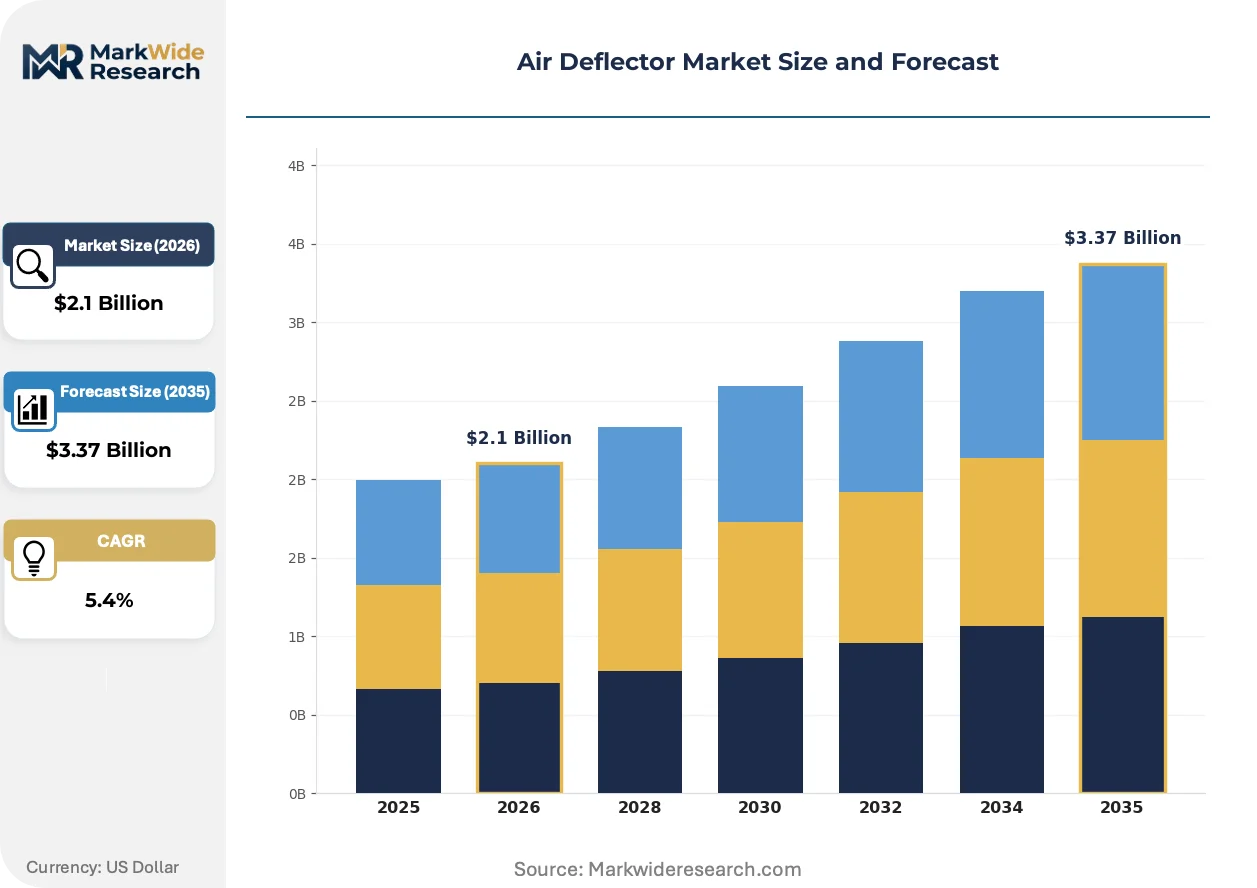
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.37 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Front Air Deflector, Rear Air Deflector, Side Air Deflector, Roof Air Deflector, Universal Air Deflector Material: Acrylic, Polycarbonate, ABS Plastic, Aluminum, Fiberglass Application: Passenger Vehicle, Commercial Transport, Off-Road Vehicles, Agricultural Equipment, Marine Craft End User: Vehicle Manufacturers, Aftermarket Suppliers, Fleet Operators, Specialty Vehicle Builders, Automotive Dealers |
| Companies Covered | Piedmont Plastics, Climair UK Ltd, Lund International, EGR, Stampede Automotive Accessories, AVS (Auto Ventshade), Magna International Inc., Plastic Omnium, WeatherTech, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Air Deflector Market Strategic Shifts & Innovations
Component evolution is defined by the integration of electronics and new materials, shifting air deflectors from passive, static parts to intelligent components within a vehicle's broader energy management system. This transformation is driven by regulatory pressures and fleet operator demands.
Active aerodynamics introduces sensor-driven, adjustable deflectors that optimize airflow in real-time. Premium passenger vehicles and advanced commercial trucks are the primary adopters of this technology. This innovation is decentralizing aerodynamic control from a fixed vehicle shape to a dynamic system that responds to changing driving conditions, maximizing efficiency across a wider operational range.
Regulatory mandates like the US EPA's greenhouse gas emissions standards for heavy-duty vehicles are a powerful design influence. This framework compels truck and engine manufacturers to adopt a suite of fuel-saving technologies, including advanced aerodynamics. The Class 8 truck segment is most affected, with suppliers now engineering deflectors as part of a holistic, certified aerodynamic package.
Fleet procurement behavior is shifting from purchasing individual components to specifying fully integrated aerodynamic kits for new vehicle orders. This trend disrupts the traditional aftermarket parts channel for single-item sales, favoring suppliers who can offer a complete system. This shift is most prominent among large long-haul trucking fleets in North America and Europe seeking guaranteed fuel-efficiency gains.
Air Deflector Market Segmentation
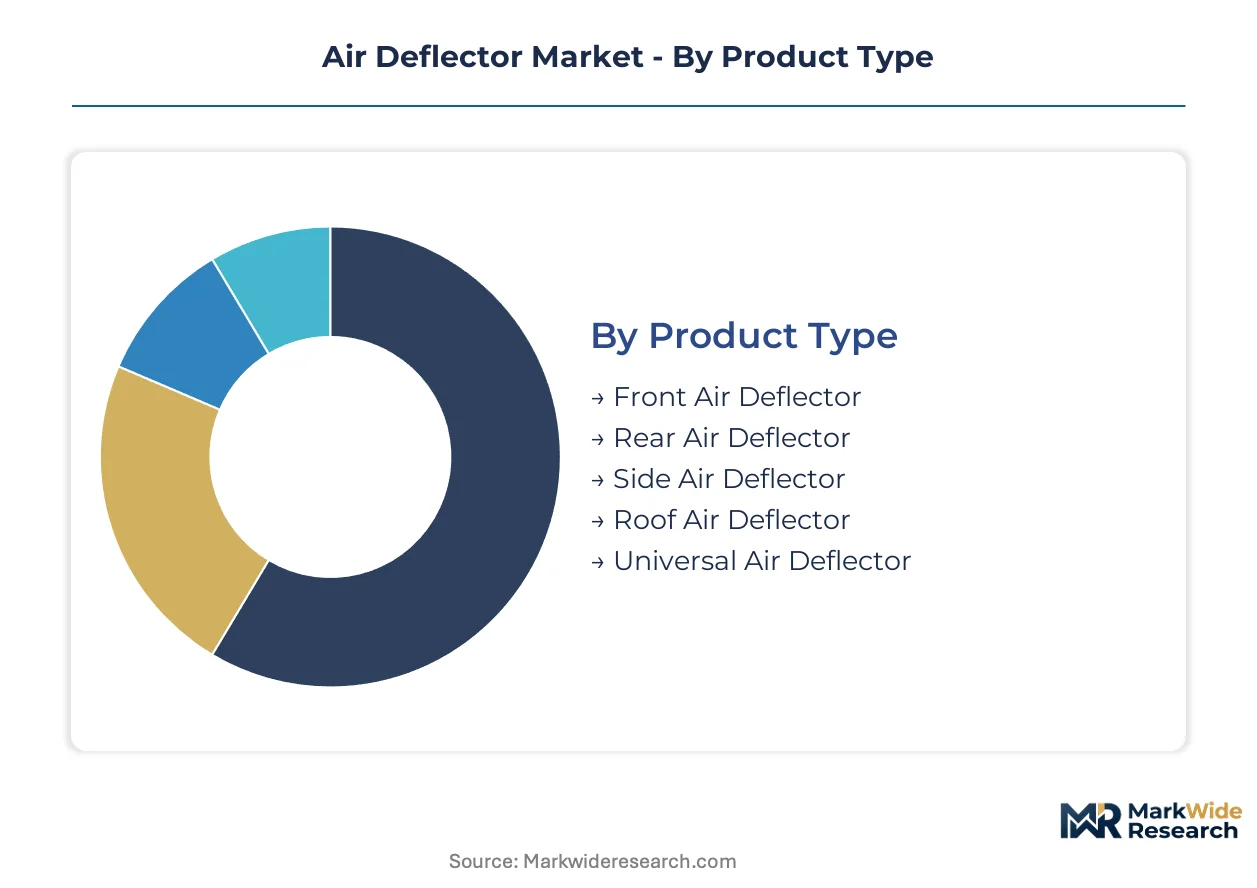
The air deflector market segments based on product design, material composition, vehicle application, and end-user type, reflecting the diverse requirements across commercial and passenger vehicle ecosystems. Understanding these distinctions helps manufacturers align product development with specific operational needs and regulatory mandates.
Product Type:
The customization-vs-standardization spectrum significantly influences product type offerings, ranging from vehicle-specific components to widely adaptable solutions.
- Front Air Deflector:These components are typically mounted on the hood or roofline to redirect airflow over the windshield, reducing drag and insect accumulation. Demand concentrates in the heavy-duty commercial transport sector in North America due to stringent fuel efficiency regulations from the US EPA.
- Universal Air Deflector:Designed for broad compatibility across various vehicle models, these deflectors are popular in the aftermarket for their ease of installation and cost-effectiveness. The market for these products thrives in regions with diverse vehicle fleets and a strong DIY culture, such as Germany.
- Rear Air Deflector:Positioned at the back of a vehicle, these deflectors manage turbulent air behind trailers or cargo areas, improving stability and fuel economy. Fleet operators in Europe increasingly adopt these for long-haul freight vehicles to comply with EU Green Deal targets.
- Side Air Deflector:These deflectors attach to side windows or cab extensions, minimizing wind noise and improving cabin comfort, particularly in commercial vans.
- Roof Air Deflector:Primarily used on commercial trucks and SUVs, roof deflectors optimize airflow over roof-mounted cargo or trailers, enhancing aerodynamic performance.
Most installed capacity flows through Front Air Deflector. Expansion is steepest in Universal Air Deflector.
Material:
Material properties and cost-effectiveness define the segmentation within air deflector manufacturing, balancing durability, weight, and production expense.
- Polycarbonate:Valued for its high impact resistance and optical clarity, polycarbonate is increasingly used in premium and commercial vehicle deflectors where durability is paramount. This material gains traction in Germany and other European markets due to requirements for robust components in heavy-duty applications.
- Acrylic:A traditional choice, acrylic offers good optical clarity and UV resistance at a lower cost, making it prevalent in the passenger vehicle aftermarket. Its widespread use continues across various vehicle types in the US and China, driven by affordability.
- ABS Plastic:Known for its strength and rigidity, ABS plastic provides a cost-effective solution for non-transparent deflector applications, offering a balance of performance and price.
- Aluminum:Primarily used for heavy-duty commercial applications, aluminum offers superior strength and rigidity for larger, structural deflector components.
- Fiberglass:This composite material provides high strength-to-weight ratios, finding application in custom or high-performance deflector designs where weight reduction is critical.
Polycarbonate is seeing rapid adoption, while Acrylic maintains its market presence.
Application:
Operational demands and regulatory compliance are key differentiators across vehicle applications, influencing deflector design and adoption rates.
- Commercial Transport:This segment encompasses heavy-duty trucks, buses, and vans, where air deflectors are critical for fuel efficiency and emissions compliance. Fleet operators in North America and Europe prioritize aerodynamic solutions to reduce operational costs and meet regulatory standards.
- Passenger Vehicle:A mature market, passenger vehicle applications include deflectors for cars, SUVs, and light trucks, primarily focused on comfort, aesthetics, and minor fuel savings. This segment holds significant volume in China and the US.
- Off-Road Vehicles:Deflectors for off-road vehicles protect against debris and manage airflow in challenging environments, enhancing driver visibility and vehicle integrity.
- Agricultural Equipment:Specialized deflectors on tractors and harvesting machinery reduce dust accumulation and improve operator comfort during extensive field work.
- Marine Craft:Air deflectors on boats and yachts redirect spray and wind, enhancing comfort and visibility for passengers and crew.
Commercial transport applications are driving the most significant volume gains.
End User:
Procurement strategies and value chain positioning define the end-user landscape, ranging from direct integration by vehicle manufacturers to aftermarket distribution channels.
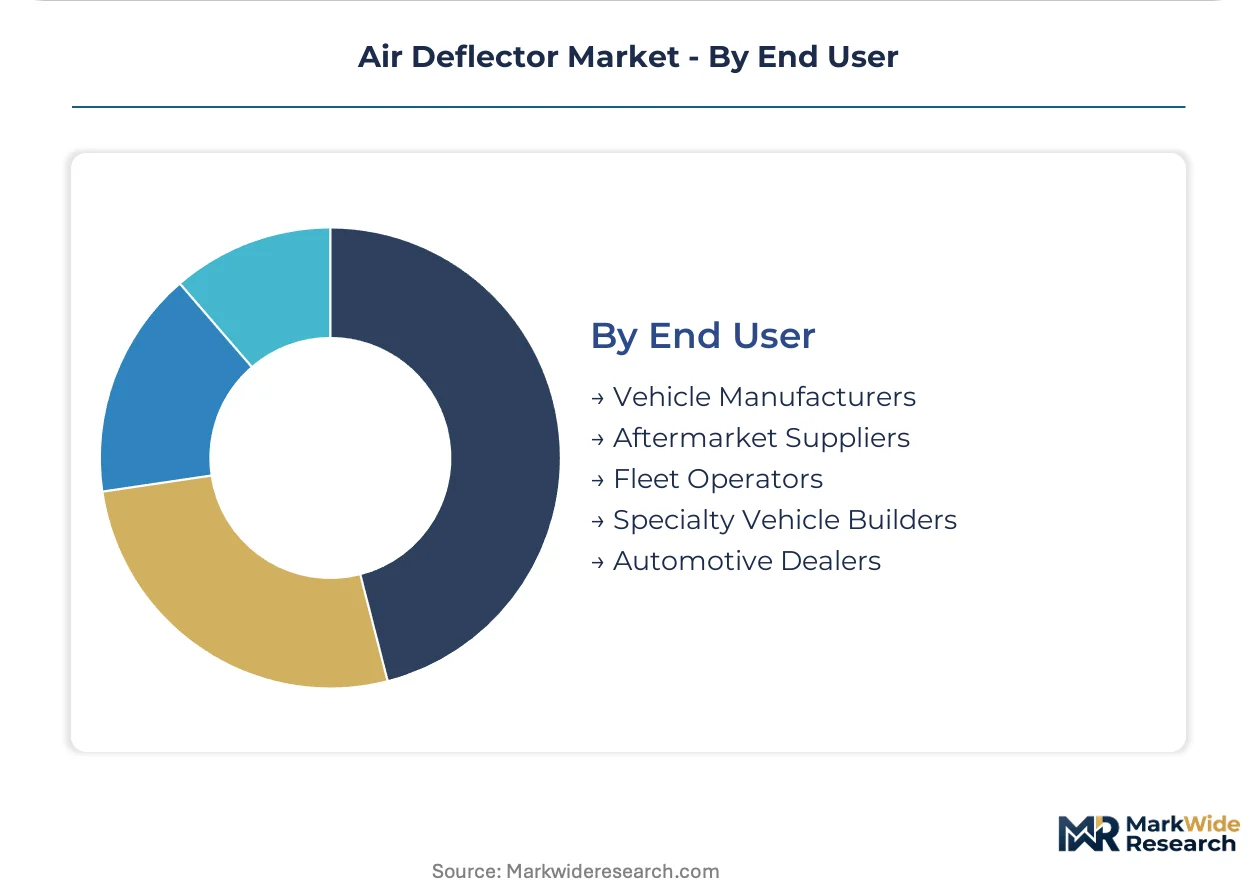
- Vehicle Manufacturers:OEMs integrate air deflectors directly into new vehicle designs, ensuring seamless aesthetic and aerodynamic performance, particularly for new models in Germany and Japan.
- Aftermarket Suppliers:These entities provide deflectors for existing vehicles, offering a wide range of universal and vehicle-specific products through retail and online channels. Aftermarket sales are strong in the US and across Europe.
- Fleet Operators:Large commercial fleets purchase deflectors for their vehicle entire fleets to standardize fuel efficiency improvements and ensure compliance with emission regulations.
- Specialty Vehicle Builders:Manufacturers of custom or niche vehicles, such as recreational vehicles or emergency vehicles, integrate specialized air deflector solutions.
- Automotive Dealers:Dealerships offer air deflectors as optional accessories or replacement parts, catering to individual customer preferences and maintenance needs.
Demand from vehicle manufacturers dictates product design, while aftermarket suppliers cater to replacement and upgrade needs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
A concentration of automotive engineering talent across key global regions drives innovation in air deflector design and deployment. These geographic hubs demonstrate unique demand patterns influenced by regulatory frameworks and operational priorities.
United States
Demand for air deflectors in the United States stems from stringent fuel efficiency requirements for heavy-duty trucks. The US EPA's greenhouse gas emissions standards compel fleet operators to adopt advanced aerodynamic solutions. Automotive manufacturing centers in Michigan, particularly around Detroit, integrate these components into new vehicle platforms.
Germany
Germany's extensive logistics and freight forwarding industry generates significant demand for commercial transport air deflectors. The EU Green Deal's emissions targets accelerate the integration of aerodynamic components for heavy-duty vehicles. Major automotive component suppliers in regions like Bavaria drive innovation in durable polycarbonate deflector solutions.
China
China's vast passenger vehicle market and expanding commercial transport sector contribute to growing demand for air deflectors. Compliance with China's GB standards dictates material and performance requirements for automotive components. The Yangtze River Delta region, a major automotive production hub, sees high adoption across various vehicle types.
India
Emerging markets like India present opportunities in the underpenetrated light commercial vehicle (LCV) segment for cost-effective air deflectors. Local emissions norms encourage fleet operators to seek fuel-saving technologies. Chennai's automotive manufacturing cluster is a focal point for developing and producing vehicle-specific aerodynamic solutions.
Brazil
Brazil's commercial vehicle sector and agricultural equipment industry drive demand for robust air deflectors. National vehicle standards promote the use of components that enhance vehicle stability and fuel economy. The industrial belt around São Paulo is a key area for automotive component manufacturing and distribution in Latin America.
Air Deflector Market Key Industry Players
Capital-heavy producers compete with asset-light designers across the air deflector market. The competitive structure features a tiered landscape, ranging from large-scale OEM suppliers to specialized aftermarket providers. Strategic archetypes include integrated system providers, material innovation specialists, and widespread distribution network operators. Companies pursue portfolio diversification and geographic expansion to secure market share.
On the premium-tier vector, Magna International Inc. leverages its deep OEM relationships and manufacturing scale for integrated designs. Plastic Omnium, a European-based company, exemplifies specialization in lightweight composite materials for advanced deflector solutions, particularly for front and rear applications. Lund International, operating primarily in the aftermarket, anchors its position through an extensive distribution network and brand recognition among vehicle enthusiasts seeking universal and vehicle-specific products.
| Leading Market Players |
|---|
| Piedmont Plastics |
| Climair UK Ltd |
| Lund International |
| EGR |
| Stampede Automotive Accessories |
| AVS (Auto Ventshade) |
| Magna International Inc. |
| Plastic Omnium |
| WeatherTech |
| Others |
Cost & Logistics Intelligence
Specialized manufacturing expertise in automotive component hubs like the Yangtze River Delta creates labor-cost differentials, influencing pricing tiers between premium OEM-integrated designs and cost-effective aftermarket solutions.
Pricing Analysis
A tiered pricing structure across premium, standard, and economy levels defines the air deflector market. Price differentiation stems from material composition, such as polycarbonate for durability, and the level of OEM integration for custom designs. Pricing pressure stems from raw material price volatility, particularly for petroleum-derived polycarbonate and acrylic resins. Aftermarket consumers exhibit higher price sensitivity for universal products, while commercial fleet operators prioritize long-term value and fuel efficiency.
Supply Chain Analysis
Logistics and freight costs significantly influence the delivered price of air deflectors, particularly for large commercial vehicle components. Geographic supply concentration for manufacturing centers on China and Germany, with key raw material dependencies on polycarbonate and acrylic resins. Single-source vulnerability for specialized composite materials poses a structural supply chain risk. Distribution runs through direct channels for vehicle manufacturers and extensive aftermarket networks for universal-fit products.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The air deflector market offers a clear margin-expansion story, driven by the premiumization of active aerodynamic systems and the shift towards high-performance, lightweight composite materials.
For Market Incumbents:To counter the threat of active aerodynamic system substitution, established incumbents should deepen R&D investment in sensor-integrated, adjustable deflector technologies. Consolidating OEM relationships ensures early integration into new vehicle platforms, particularly for heavy-duty commercial trucks. Expanding manufacturing capabilities for advanced composites, like those used by Plastic Omnium, provides a competitive advantage. This strategy defends market share against emerging high-tech solutions.
For New Entrants and Emerging Players:A significant price-point gap exists between premium OEM-integrated solutions and basic aftermarket offerings, creating an entry opportunity. New entrants should target underpenetrated Light Commercial Vehicle (LCV) fleets in emerging markets like Southeast Asia and Latin America. Offering cost-effective, vehicle-specific deflectors made from recycled or bio-based polymers aligns with sustainability goals. This approach leverages a high-volume segment with lower initial R&D barriers.
For Investors and Strategic Acquirers:Large automotive component manufacturers are the most active acquirers in this space, seeking to expand their aerodynamic portfolio. The market offers long-term viability, driven by global fuel efficiency regulations and material advancements. Acquisition targets include specialized firms in lightweight composite materials or developers of active aerodynamic systems. The signal to watch is increased investment in companies offering ADAS-compatible front-end deflector solutions.
| Strategic Initiative | Industry Significance |
|---|---|
| R&D in Active Aerodynamics | Optimizes real-time efficiency for commercial fleets, responding dynamically to driving conditions. |
| Bio-based Polymer Development | Aligns with OEM sustainability mandates, reducing environmental impact for new vehicle platforms. |
| LCV Market Penetration | Captures new volume opportunities in underpenetrated segments, especially in emerging economies. |
| OEM Partnership Deepening | Secures integrated design wins for next-generation heavy-duty trucks, ensuring platform compatibility. |
| Aftermarket Distribution Expansion | Reaches diverse vehicle fleets with universal and vehicle-specific products through retail channels. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window to build a comprehensive market view. Primary research involved discussions with automotive OEM engineers, commercial fleet procurement managers, aftermarket distributors, and material science R&D leads. Secondary data was sourced from US EPA reports, EU Green Deal documents, China GB standards, and global automotive production databases. This combined approach enabled robust bottom-up and top-down market size validation.
Segment-weighting across product type, material composition, vehicle application, end-user type, and regional regulatory compliance formed the basis of the forecast framework. Compound Annual Growth Rates (CAGRs) were derived from analyzing historical market trends and projected impacts of global emissions regulations over the projection horizon. Key inputs included anticipated changes in fuel efficiency mandates and long-term raw material cost forecasts. The model integrated these factors to project market expansion.
Caveats apply where geopolitical events impacting raw material supply chains or rapid shifts in regulatory enforcement could materially shift the outlook. Forecasts reflect assumptions documented through extensive research and industry consultation. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft
UK Military Aviation Market
Aircraft
Civil Helicopter Market
Aircraft
Global Helicopter Market
Aircraft
Asia-Pacific Commercial Aircraft Market
Aircraft
Commercial Turboprop Aircrafts Market
Aircraft
Air Starter Market
Aircraft
Online in-Flight Shopping Market
Aircraft
Two-Seater Ultralight Helicopters Market
Aircraft
Aircraft Leasing and Rental Market
Aircraft
Fighter Aircraft Market
Aircraft
Reusable Launch Vehicles Market
Aircraft
Commercial Helicopter Market
Aircraft
Asia-Pacific Turboprop Aircraft Market
Aircraft
Commercial Aircraft Lavatory System Market
Aircraft
Helicopter Flight Management System Market
Aircraft
Tanker Aircraft Market