
 Freighter Aircraft Market | 2026-2036
Freighter Aircraft Market Size, Share, and Industry Trends Forecast 2026-2036
Freighter Aircraft Market Analysis
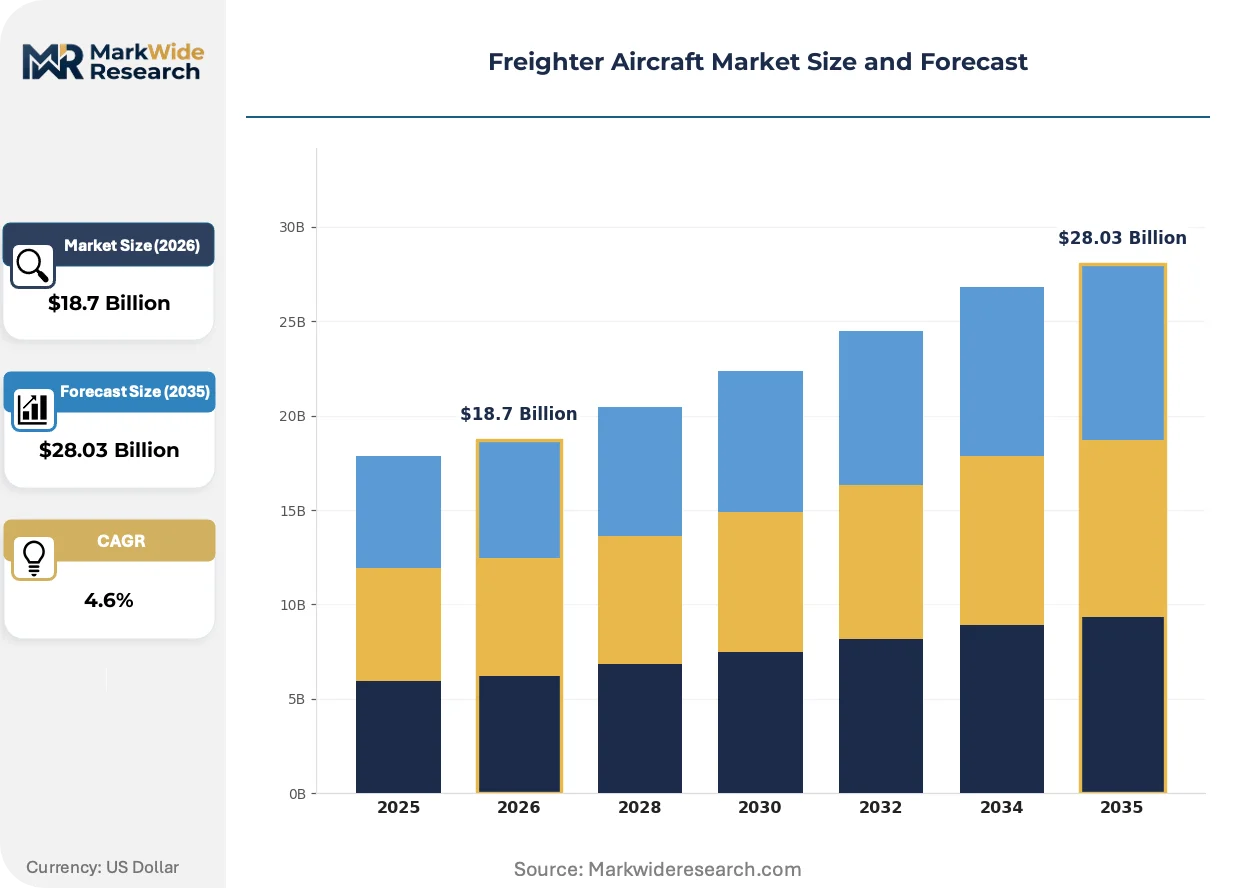
Freighter lifecycle management services is expanding the addressable revenue per airframe beyond the initial sale. Boeing leverages its integrated conversion line in Wichita to control the passenger-to-freighter modification pipeline. Airbus competes through its A350F clean-sheet design, targeting express carriers seeking fuel efficiency. Atlas Air sustains its position as the largest ACMI operator, anchoring demand for leased widebody capacity across trans-Pacific lanes.
Freighter aircraft are fixed-wing cargo airplanes engineered for dedicated goods transport, typically featuring reinforced floors, wide cargo doors, and payload ratings from ten tons to over one hundred tons for intercontinental routes. Their primary commercial purpose is to move time-sensitive, high-value, or temperature-controlled shipments that surface transport cannot accommodate within required delivery windows. Dedicated freighters occupy the premium tier of the aircraft type segment, commanding higher lease rates due to factory-built structural integrity, while converted freighters attract budget-constrained operators entering regional e-commerce fulfillment. The over thirty tons payload capacity bracket leads in dollar terms, as long-haul widebodies generate disproportionate revenue per available ton-kilometer on Asia-Europe and trans-Pacific corridors.
The FAA mandates Stage 5 noise compliance and progressive emission reductions under its ongoing environmental standards framework, pushing operators toward newer-generation freighters or expensive re-engining programs. EASA's REACH-aligned material restrictions and its evolving sustainable aviation fuel blending mandates reshape MRO supply chains and new aircraft specification sheets across European-registered cargo fleets. ICAO's carbon offsetting and reduction scheme for international aviation progressively tightens operating economics for older, less efficient freighter platforms. Stakeholders must monitor regulatory threshold dates and conversion cost curves to time fleet renewal decisions against residual value trajectories.
Market Dynamics
The freighter aircraft market is fundamentally reshaped by regulatory-driven fleet turnover, as FAA Stage 5 noise mandates and ICAO carbon offset schemes force operators to retire aging widebodies and accelerate capital deployment toward next-generation platforms.
Growth Catalysts
- E-commerce fulfillment networks:Express carriers in the United States are expanding dedicated freighter orders to capture surging parcel volumes on trans-Pacific and intra-Asian lanes.
- REACH-aligned material mandates:EASA's evolving restrictions on hazardous substances in MRO supply chains are accelerating specification upgrades for European-registered cargo fleets.
- Passenger-to-freighter conversion pipelines:Narrowbody feedstock availability from retiring 737-800 and A321ceo fleets is expanding the addressable pool for regional cargo operators.
Market Restraints
- Aerospace-grade aluminum-titanium supply:Concentration of specialty metal processing in a limited supplier base creates input cost volatility for airframe manufacturers.
- Engine OEM lead times:Extended delivery schedules for high-bypass turbofans constrain production ramp rates for new widebody freighter programs.
- SAF blending infrastructure gaps:Patchy sustainable aviation fuel distribution networks at secondary cargo hubs limit operational compliance pathways for ICAO CORSIA obligations.
Strategic Opportunities
- Indian subcontinent express corridors:Underdeveloped domestic air cargo infrastructure creates white space for dedicated narrowbody freighter services linking Delhi, Mumbai, and Bangalore manufacturing clusters.
- Blockchain-IoT convergence:Real-time cargo condition monitoring combined with immutable chain-of-custody records opens premium pricing tiers for pharmaceutical and perishable verticals.
- EU Green Deal aviation incentives:Member state subsidies for zero-emission ground handling and SAF uptake reduce total cost of ownership for next-generation freighter deployments.
Industry Challenges
- Airframe engineering talent scarcity:Retiring workforce demographics in structural analysis and fatigue testing functions constrain conversion line throughput at modification centers.
- Supplemental type certification timelines:FAA and EASA validation procedures for passenger-to-freighter modifications extend program schedules by 18-24 months.
- Legacy avionics integration friction:Retrofitting digital flight data recorders and satellite communications suites onto 1990s-era platforms demands scarce systems integration expertise.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Freighter Aircraft Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $28.03 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Aircraft Type: Dedicated Freighter, Converted Freighter, Cargo Lifter, Hybrid Freighter Payload Capacity: Up to 10 Tons, 10-20 Tons, 20-30 Tons, Over 30 Tons End User: Logistics Companies, E-commerce Retailers, Airlines, Military Operating Environment: Domestic, International, Regional, All-Cargo |
| Companies Covered | FedEx Express, Qantas Freight, Boeing, Korean Air Cargo, Cathay Pacific Cargo, Airbus, UPS Airlines, Atlas Air, Emirates SkyCargo, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Freighter Aircraft Market Emerging Trajectories
Digital thread technologies and sustainable propulsion architectures are compressing development cycles and redefining competitive differentiation in freighter platform economics. These shifts are redrawing supplier hierarchies and operator procurement criteria.
Advanced composite wing structures are consolidating manufacturing footprints across the freighter supply base. Boeing and Airbus have both migrated to automated fiber placement for wing boxes and control surfaces, reducing part count and assembly labor. Tier-one aerostructures suppliers in Japan and Italy are capturing expanded work share as metallic fabrication recedes. This consolidation is compressing the viable supplier base to firms with billion-dollar autoclave investments.
ICAO's Carbon Offsetting and Reduction Scheme for International Aviation tightens operating economics for pre-2020 freighter vintages. Operators face escalating offset purchase obligations or accelerated retirement decisions. Long-haul widebody segments on Asia-Europe corridors bear the highest compliance cost exposure, driving preference for factory-built A350F and 777-8F platforms with 20% fuel burn advantages over converted alternatives.
Express carriers are unbundling maintenance contracts from dry lease agreements, creating standalone MRO procurement competitions. Amazon Air and regional European integrators now separately tender engine overhaul and line maintenance, pressuring OEM bundled-service margins. This disintermediation is most visible in United States hub operations, where specialized engine shops in Texas and Georgia capture work previously captive to lessors.
Freighter Aircraft Market Segmentation
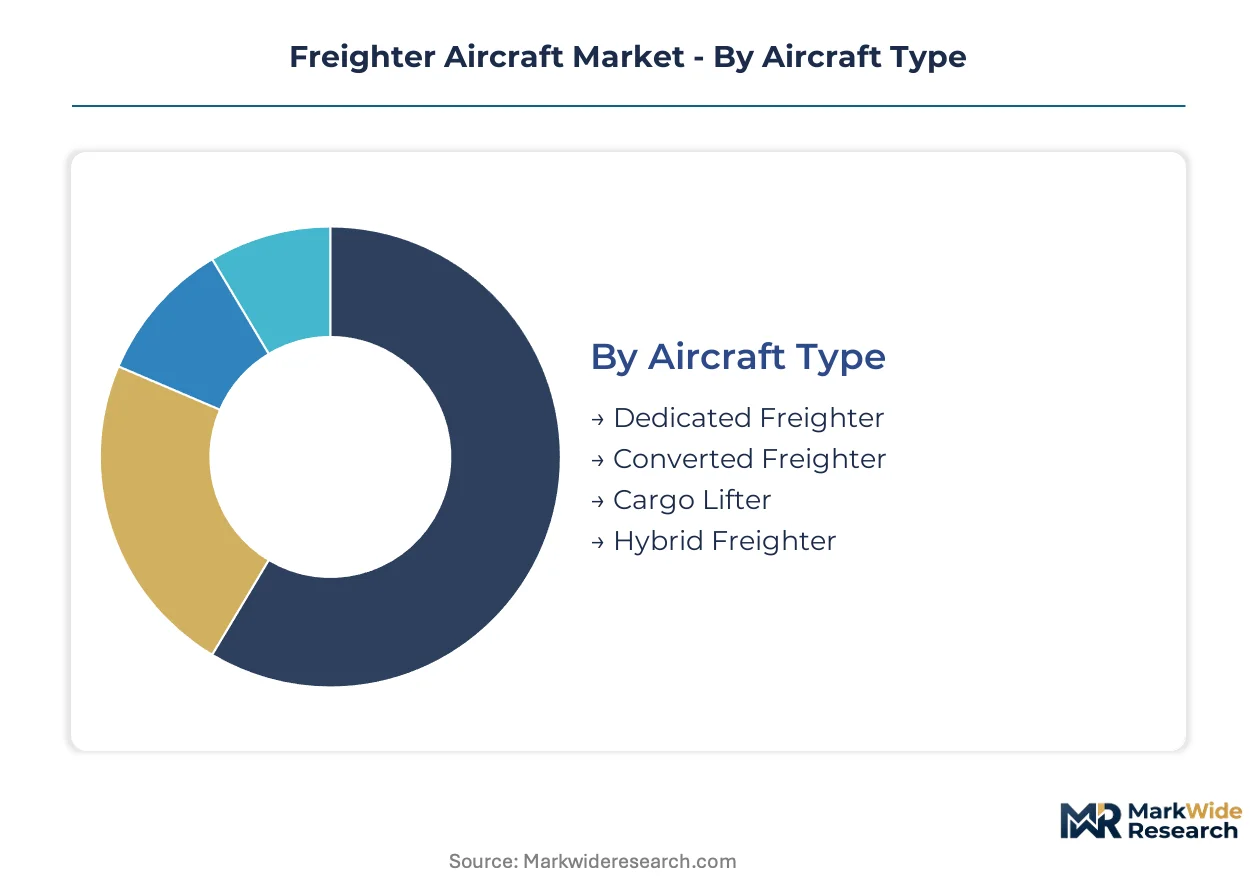
Freighter aircraft segmentation reveals how payload economics, conversion pathways, and end-use specialization fragment procurement patterns. Operators select platforms based on route density, cargo commodity mix, and regulatory compliance horizons rather than generic capacity metrics.
Aircraft Type:
Structural engineering approaches define competitive positioning across the freighter fleet, separating factory-optimized designs from modification-based alternatives.
- Dedicated Freighter:Factory-built cargo aircraft feature reinforced floors, integrated loading systems, and fatigue-rated structures for high-cycle operations. Express carriers in the United States favor these platforms for Memphis and Louisville hub networks, accepting premium lease rates for structural integrity and dispatch reliability.
- Converted Freighter:Passenger-to-freighter modifications of retiring narrowbodies extend airframe utility through supplemental type certification. Regional operators in India and Southeast Asia deploy converted 737-800s for e-commerce feeder routes, capitalizing on feedstock availability and lower capital deployment.
- Cargo Lifter:Specialized heavy-lift platforms transport outsized industrial equipment and project cargo. Energy sector demand in the North Sea and Gulf of Mexico drives intermittent charter requirements for these low-volume, high-rate assets.
- Hybrid Freighter:Quick-change configurations alternate between passenger and cargo missions. Leisure carriers in Mediterranean markets utilize these assets for seasonal freight surges, optimizing utilization across summer tourism and winter cargo peaks.
Mature deployment sits with Dedicated Freighter platforms. Newer deployment is concentrated in Converted Freighter programs.
Payload Capacity:
Weight-class stratification determines route economics, with threshold effects at structural loading limits and airport infrastructure constraints.
- Over 30 Tons:Widebody platforms dominate intercontinental lanes with unit economics scaling across Asia-Europe and trans-Pacific corridors. These assets command disproportionate revenue per available ton-kilometer due to fuel efficiency and belly-hold substitution effects.
- 20-30 Tons:Mid-size widebodies serve secondary long-haul markets with thinner cargo density. African and Latin American trunk routes favor this bracket for balanced payload-range performance.
- 10-20 Tons:Narrowbody platforms penetrate regional express networks with higher frequency and airport accessibility. European integrators deploy these assets for next-day delivery commitments across continental hub-and-spoke systems.
- Up to 10 Tons:Turboprop and small jet freighters access constrained airfields for time-critical shipments. Remote mining and offshore logistics in Australia and Canada sustain demand for this capacity tier.
Volume concentration favors Over 30 Tons for trunk routes. Fastest expansion is occurring in 10-20 Tons for intra-regional e-commerce fulfillment.
End User:
Procurement authority and operational control separate vertically integrated networks from outsourced capacity arrangements.
- Logistics Companies:Third-party freight forwarders and integrators operate dedicated fleets or contracted capacity. DHL and FedEx procurement patterns in Germany and the United States drive specification requirements for cross-dock compatibility and ground handling automation.
- E-commerce Retailers:Amazon, Alibaba, and regional platforms are building captive air networks. These operators prioritize narrowbody feedstock with quick-turn capabilities for sortation hub integration.
- Airlines:Combination carriers deploy freighters alongside passenger widebodies for belly cargo optimization. Lufthansa and Korean Air maintain factory-built freighter subfleets for pharmaceutical and perishable verticals.
- Military:Defense logistics commands operate strategic airlift for expeditionary deployment. NATO and national procurement in France, the United Kingdom, and the United States sustains demand for outsized cargo platforms.
Established fleet ownership rests with Logistics Companies. Emerging procurement authority is shifting toward E-commerce Retailers.
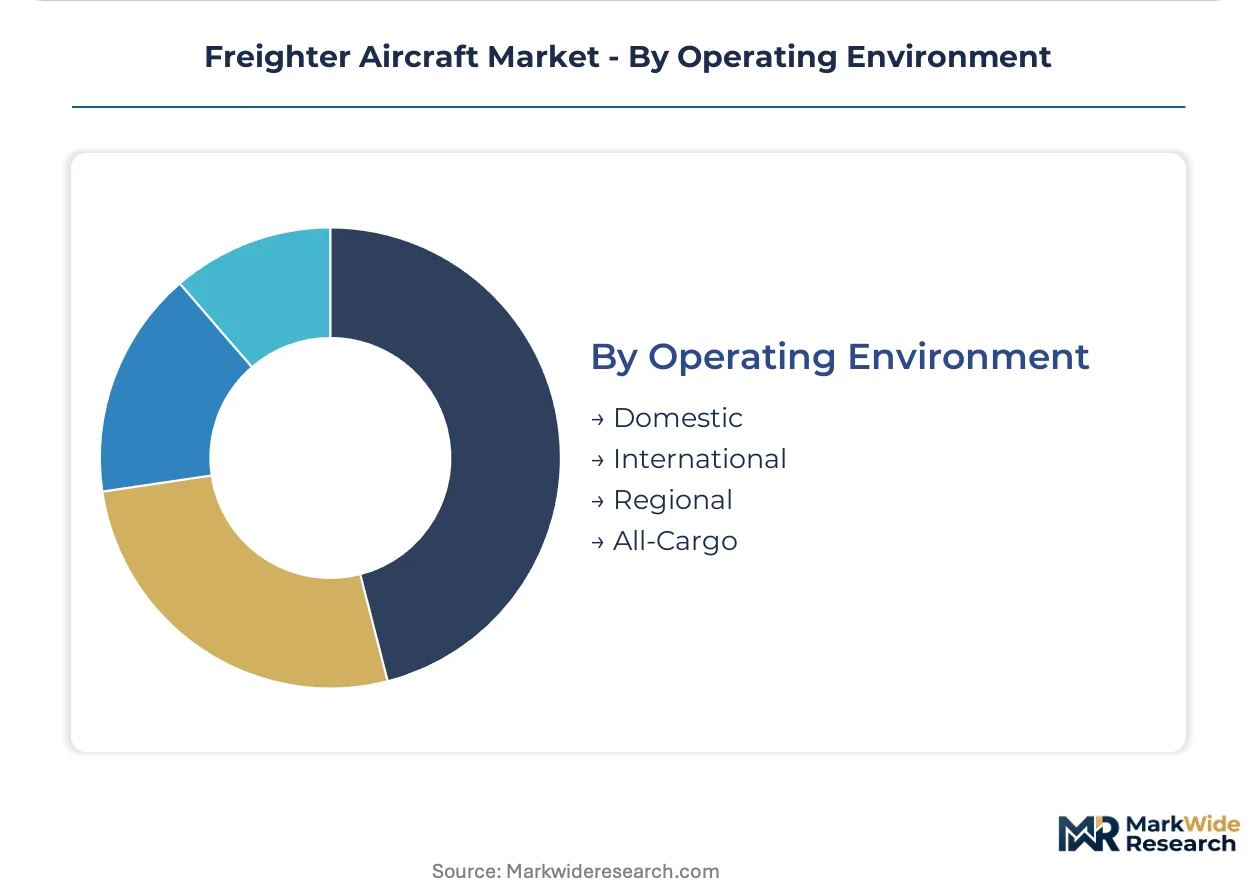
Operating Environment:
Regulatory jurisdiction and route authorization shape aircraft specification, with distinct certification requirements for cross-border operations.
- International:ICAO Annex 6 compliance and bilateral traffic rights govern scheduled cargo services. These operations require extended-range equipment, satellite communications, and crew rest provisions for transoceanic sectors.
- Domestic:National aviation authority oversight applies to internal cargo networks. Chinese domestic express carriers operate under CAAC regulations with simplified equipment standards for mainland trunk routes.
- Regional:Cross-border services within economic blades operate under harmonized standards. EU Open Skies agreements enable seamless narrowbody freighter deployment across member states.
- All-Cargo:Dedicated cargo airlines without passenger operations face distinct slot allocation and noise quota regimes. These carriers optimize for nighttime curfew windows at Frankfurt, Amsterdam, and Tokyo Narita.
Regulatory complexity peaks in International operations. Operational flexibility is expanding fastest in Regional configurations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Freighter aircraft production concentrates in France and the United States where final assembly lines dominate, while consumption spreads across express carrier hubs in Memphis, Louisville, and Leipzig that drive fleet renewal cycles.
United States
Integrator networks at Memphis and Louisville anchor narrowbody and widebody procurement as FedEx and UPS expand dedicated freighter orders. FAA Stage 5 noise mandates accelerate retirement of aging MD-11 and 767-300F platforms. Wichita, Kansas hosts Boeing's integrated conversion line controlling passenger-to-freighter modification throughput for North American operators.
Germany
DHL Express drives specification requirements for cross-dock compatibility and ground handling automation across European trunk routes. EASA REACH-aligned material restrictions reshape MRO supply chains for German-registered cargo fleets. Leipzig-Halle Airport serves as the primary Central European air cargo hub where next-generation freighter deployments concentrate.
China
Domestic express carriers under CAAC oversight operate simplified equipment standards for mainland trunk routes linking manufacturing clusters. The country's national aviation regulator enforces progressive emission standards aligned with ICAO CORSIA frameworks. Yangtze River Delta logistics corridors generate concentrated demand for 737-800 converted freighters serving e-commerce fulfillment networks.
United Arab Emirates
Dubai International and Al Maktoum International anchor trans-Asia-Europe cargo flows with 24-hour operational windows exempt from noise curfews. The country's civil aviation authority mandates satellite communications and extended-range equipment for international scheduled services. Jebel Ali free trade zone concentration supports dedicated freighter deployment for pharmaceutical and perishable verticals.
Japan
Narita and Kansai airports enforce strict nighttime curfew windows that optimize all-cargo airline scheduling for premium express services. METI industrial policy supports SAF blending infrastructure development at secondary cargo hubs. Tokyo-Osaka manufacturing belt generates time-critical shipment demand for narrowbody freighter penetration of regional airports.
Freighter Aircraft Market Vendor Landscape
Top-tier vendors anchor factory-built freighter manufacturing, while conversion specialists and express carriers occupy distinct competitive tiers. The market structures around three player categories: airframe OEMs with integrated production lines, ACMI operators leasing widebody capacity, and integrators operating captive fleets. Strategic moves concentrate on conversion line expansion and unbundled MRO procurement competitions that pressure OEM bundled-service margins.
Among North American-based operators, FedEx Express and UPS Airlines exemplify the integrator archetype with dedicated freighter subfleets optimized for hub-and-spoke networks. Boeing occupies a position representing factory-built and conversion line dominance through its Wichita facility. Airbus anchors the European competitive vector with clean-sheet freighter designs targeting fuel efficiency requirements.
| Leading Market Players |
|---|
| FedEx Express |
| Qantas Freight |
| Boeing |
| Korean Air Cargo |
| Cathay Pacific Cargo |
| Airbus |
| UPS Airlines |
| Atlas Air |
| Emirates SkyCargo |
| Others |
Supply Flow & Price Mechanics
Integrator procurement concentration at Memphis and Louisville hub networks anchors contract-based long-term offtake pricing for factory-built freighters, while conversion specialists compete on capital efficiency for regional e-commerce operators. This buyer archetype fragmentation splits the market between premium structural integrity leases and feedstock-driven modification economics.
Pricing Analysis
Margin tightening in the converted freighter tier traces to narrowing feedstock availability windows as 737-800 and A321ceo retirement curves flatten. Three-tier pricing structure across factory-new, OEM-converted, and third-party modification levels differentiates on certification pedigree and residual value guarantees, with FAA Stage 5 compliance timelines accelerating price erosion for pre-2020 vintages. Express carriers show lowest price sensitivity for dedicated factory-built platforms, while emerging Asian operators prioritize capital deployment efficiency in the conversion market.
Supply Chain Analysis
Airframe qualification gating through FAA supplemental type certification and EASA validation procedures constrains modification center throughput, extending program timelines and compressing viable supplier bases. Aerospace-grade aluminum-titanium supply draws from concentrated specialty metal processing in the United States, Japan, and Italy, with automated fiber placement equipment for composite wing structures feeding from billion-dollar autoclave investments at tier-one aerostructures suppliers. Single-source vulnerability sits with high-bypass turbofan engine OEM lead times, while distribution runs through lessor-integrator direct channels and ACMI operator intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Freighter platform economics are converging on vertical-integration races, with airframe OEMs capturing conversion line capacity and express carriers unbundling MRO procurement to pressure bundled-service margins.
For Market Incumbents: Lock in conversion line capacity at Wichita and other modification centers to control passenger-to-freighter feedstock pipelines against emerging Asian competitors. Secure long-term engine overhaul contracts with Texas and Georgia specialized shops before express carriers complete MRO unbundling transitions, preserving attach rate economics against disintermediation threats. For New Entrants and Emerging Players: Digital freight forwarding platforms offer the most penetrable route for regional narrowbody deployment, targeting Indian subcontinent express corridors linking Delhi, Mumbai, and Bangalore manufacturing clusters. White space exists in blockchain-IoT cargo condition monitoring for pharmaceutical verticals, with premium pricing tiers available for immutable chain-of-custody solutions. For Investors and Strategic Acquirers: Distressed-cycle entries favor ACMI operators with trans-Pacific lane exposure and long-term e-commerce retailer contracts, particularly those with 777-300ER converted freighter deployments. Monitor ICAO CORSIA offset obligation curves as the inflection signal for accelerated retirement decisions among pre-2020 widebody vintages.| Strategic Initiative | Industry Significance |
|---|---|
| Passenger-to-Freighter Conversion Line Expansion | Boeing's Wichita facility controls North American modification throughput for 737-800 feedstock. |
| SAF Blending Infrastructure Partnership | EU Green Deal subsidies reduce total cost of ownership for next-generation freighter deployments at Leipzig-Halle. |
| Unbundled MRO Procurement Competition | Amazon Air's separate engine overhaul tenders pressure OEM bundled-service margins across United States hubs. |
| Blockchain-IoT Cargo Monitoring Integration | Real-time condition tracking opens premium pricing tiers for pharmaceutical and perishable verticals. |
| Regional Express Corridor Development | Underdeveloped Indian domestic air cargo infrastructure creates white space for dedicated narrowbody services. |
Methodological Framework
Multi-period observation of freighter delivery backlogs, conversion line throughput rates, and e-commerce air cargo volume indices anchored the trend analysis, supplemented by interviews with fleet planning executives at express carriers, modification center program managers, and ACMI contract specialists. Secondary validation drew from FAA supplemental type certification filings, EASA REACH-aligned material restriction updates, ICAO CORSIA framework documents, and customs trade data for aerospace-grade aluminum-titanium flows. Bottom-up airframe deployment tracking and top-down market sizing triangulated volume estimates across the analysis window.
Segment-weighting approaches applied payload capacity brackets, aircraft type classifications, and end-user procurement authority dimensions throughout the modeling period. CAGRs derived from regression analysis against e-commerce penetration curves and regulatory compliance threshold dates, with fuel efficiency improvements and SAF blending infrastructure development as freighter-specific forecast inputs.
The model holds under stable regulatory phase-in schedules and continued e-commerce volume expansion; deviation in engine OEM production ramp rates or aluminum-titanium supply disruptions would shift fleet renewal timing assumptions. Stakeholders should weight these assumptions against their own operating context and residual value trajectories.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft
Global Commercial Aircraft Windows and Windshields Market
Aircraft
Turboprop Aircraft Market
Aircraft
Asia-Pacific Light and Very Light Jets Market
Aircraft
Aircraft Galley Equipment Market
Aircraft
Aircraft Galley Systems Market
Aircraft
Global Aircraft Electric Brake Control System Market
Aircraft
Asia-Pacific Aircraft Windshield Wiper and Washer System Market
Aircraft
Flap Track Fairing Drag Reduction Upgrade Kits Market
Aircraft
Water Bomber Market
Aircraft
Cargo Compartment Latches Market
Aircraft
Sailplane Market
Aircraft
Winglets Market
Aircraft
Aircraft Ailerons Market
Aircraft
Commercial Aircraft Market
Aircraft
Aircraft Aerostructures Market
Aircraft
Manned Evtol Crafts Market