
 Aircraft Galley Systems Market | 2026-2036
Aircraft Galley Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Aircraft Galley Systems Market Outlook
Buyer concentration among full-service carriers is expanding as legacy airlines consolidate fleet renewal schedules around single-aisle platforms. Collins Aerospace leverages its RTX parent company's avionics integration capabilities to bundle galley systems with cabin management electronics. Safran SA anchors its position through vertical control of refrigeration compressor technology. Diehl Stiftung & Co. KG competes on modularity, offering line-fit configurations that reduce final assembly labor at airframe plants.
Aircraft galley systems comprise modular food preparation, storage, and distribution assemblies engineered from lightweight aluminum alloys and fire-resistant thermoplastic composites, typically rated for 16g crash loads and smoke-toxicity thresholds per FAR 25.853. These systems serve the essential commercial purpose of enabling efficient meal service workflows while minimizing weight penalties and maximizing cabin floor space utilization. Electric galley inserts now dominate new installations, displacing gas-powered alternatives as airlines prioritize emission reduction and simplified maintenance protocols. Retrofit activity represents the fastest-growing installation channel, driven by aging wide-body fleets requiring galley modernization to match passenger experience standards on newer aircraft.
FAA Part 25 airworthiness standards and EASA CS-25 certification frameworks govern flammability, electrical safety, and structural integrity requirements for galley systems installed on transport-category aircraft. The EU Green Deal's aviation decarbonization targets are accelerating induction technology adoption by restricting gas-based galley equipment on European-registered fleets. Stakeholders must monitor evolving electrical load standards as next-generation narrow-bodies introduce higher-capacity galley configurations to support premium cabin densification strategies.
Market Dynamics
The narrow-body fleet densification wave is compressing galley footprints while expanding functional requirements, forcing suppliers to engineer higher-capacity inserts within shrinking spatial envelopes certified to 16g crash standards.
Growth Catalysts
- FAA Part 25.853 smoke-toxicity mandates:Fire-resistant thermoplastic composites are displacing legacy aluminum in new line-fit installations as carriers accelerate fleet renewal schedules.
- Electric galley inserts:Induction technology is displacing gas-powered equipment across European-registered fleets under EU Green Deal aviation decarbonization targets.
- Retrofit channel expansion:Aging wide-body fleets in the United States are driving procurement of modular modernization kits to match passenger experience standards on newer aircraft.
Market Restraints
- Aluminum alloy price volatility:Lightweight structural material costs fluctuate with energy-intensive smelting economics, compressing margin buffers for tier-two fabricators.
- Refrigeration compressor supply concentration:Vertical control of critical cooling subsystems by a limited supplier base creates procurement bottlenecks during airframe production ramps.
- Electrical load ceiling constraints:Next-generation narrow-body power distribution architectures impose hard limits on simultaneous galley insert operation during peak service windows.
Strategic Opportunities
- Premium cabin densification:Airlines are reconfiguring forward galleys to accommodate lie-flat seating expansions, creating demand for ultra-compact food preparation modules.
- Line-fit modularity:Configurations that reduce final assembly labor at airframe plants are capturing preference from Boeing and Airbus procurement teams.
- EASA CS-25 electrical safety evolution:Anticipated amendments to arc-fault protection standards will open retrofit windows for early-generation electric galley fleets.
Industry Challenges
- Multiphysics simulation talent scarcity:Crash-load modeling combined with thermal-electrical analysis requires specialized aerospace engineering competencies concentrated at tier-one suppliers.
- Certification timeline compression:FAA and EASA concurrent validation protocols for novel composite formulations extend development cycles beyond airline fleet planning horizons.
- Legacy fleet integration friction:New-generation inserts face mechanical and electrical interface mismatches with 1990s-era wide-body galley monuments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aircraft Galley Systems Market |
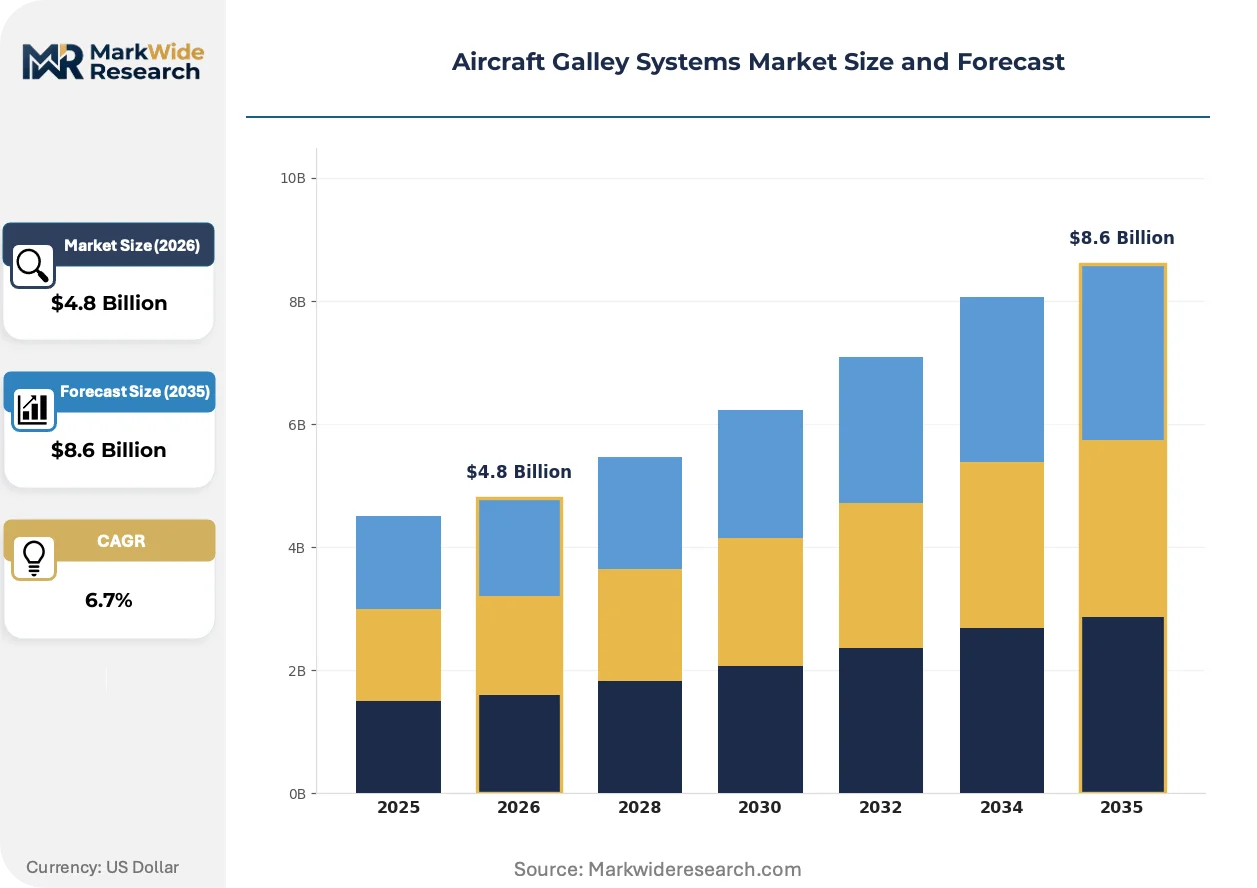
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Galley Inserts, Meal Distribution Systems, Refrigeration Units, Beverage Makers End User: Commercial Airlines, Cargo Airlines, Private Jets, Government Aircraft Technology: Electric, Gas, Induction, Hybrid Installation Type: Line Fit, Retrofit, Modular, Integrated |
| Companies Covered | Collins Aerospace (RTX Corporation), Safran SA, JAMCO Corporation, Diehl Stiftung & Co. KG, Bucher Leichtbau AG, Aerolux Ltd., AIM Altitude, AVIC Cabin Systems Limited, Korita Aviation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aircraft Galley Systems Market Strategic Shifts
Galley system engineering is pivoting from passive meal storage toward active thermal management and intelligent power allocation, reshaping supplier capabilities and buyer evaluation criteria.
Induction-based food warming technology is overtaking convection and steam-based alternatives in new installations. Full-service carriers adopting premium cabin densification strategies specify these units for their reduced thermal mass and precise temperature control. The shift is compressing demand for gas infrastructure routing and associated maintenance protocols across narrow-body production lines.
EU Green Deal aviation decarbonization targets are accelerating regulatory pressure on gas-powered galley equipment. EASA is developing amended certification pathways that favor all-electric configurations for European-registered fleets. Airlines operating mixed-registry portfolios are standardizing on electric inserts to simplify fleet management and avoid operational restrictions.
Buyer concentration among consolidated legacy carriers is compressing procurement cycles and elevating technical dialogue to executive levels. Long-term cabin configuration agreements now bundle galley systems with avionics and in-flight entertainment packages. This pattern is most visible in United States-based fleet renewal programs, where Boeing production recovery has synchronized multiple airline procurement timelines.
Aircraft Galley Systems Market Segmentation
Galley system procurement splits sharply between airframe-integrated line-fit programs and aftermarket retrofit cycles, with technology choices increasingly constrained by electrical load architectures and decarbonization mandates. Understanding these segment boundaries clarifies where supplier R&D investments concentrate versus where price competition dominates.
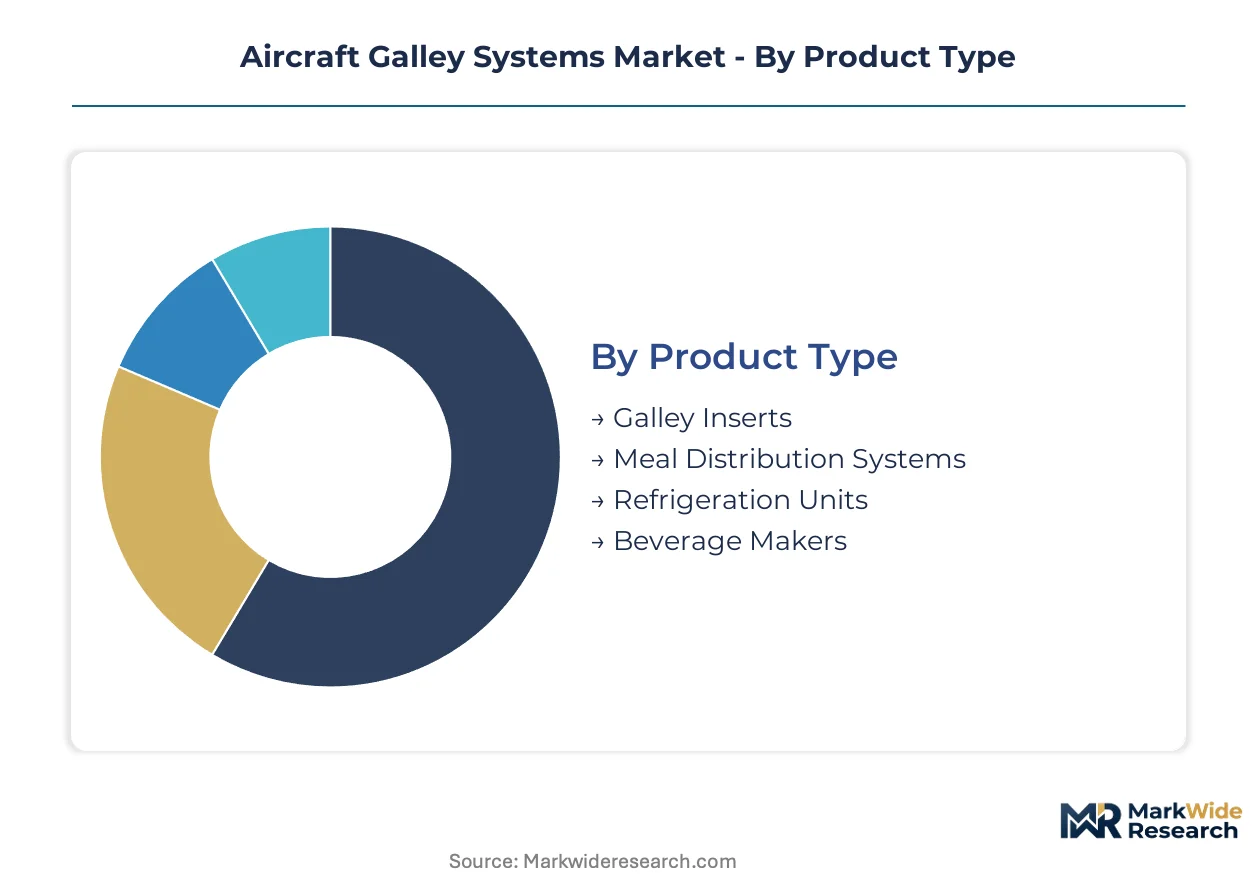
Product Type:
Customization intensity varies from standardized refrigeration compressors to bespoke meal distribution configurations tailored to individual airline service protocols.
- Galley Inserts:Modular food warming, cooling, and preparation units engineered from fire-resistant thermoplastic composites meeting FAR 25.853 smoke-toxicity thresholds. Demand clusters in narrow-body line-fit programs at Boeing's Renton facility as airlines densify single-aisle cabins. FAA electrical load management standards are forcing suppliers to redesign insert power profiles for simultaneous peak operation.
- Refrigeration Units:Vapor-compression cooling systems with hermetic compressors, typically specified for 16g crash load certification and extended mean-time-between-failures. Procurement concentrates among United States-based full-service carriers retrofitting aging wide-body fleets to match passenger experience standards on newer aircraft. Vertical control of compressor technology by Safran SA creates supply bottlenecks during production ramps.
- Meal Distribution Systems:Trolley-based cart systems and automated dispensing mechanisms for efficient cabin service workflows.
- Beverage Makers:Coffee and tea brewing equipment optimized for altitude pressure compensation and rapid cycle times.
Most installed capacity flows through Galley Inserts. Expansion is steepest in Refrigeration Units.
End User:
Customer procurement sophistication ranges from standardized government specifications to highly customized private jet interiors demanding bespoke material finishes.
- Commercial Airlines:Full-service and low-cost carriers operating scheduled passenger services on transport-category aircraft. Fleet renewal programs at United States legacy carriers are synchronizing galley procurement timelines with Boeing production recovery. Long-term cabin configuration agreements now bundle galley systems with avionics and in-flight entertainment packages.
- Private Jets:Business aviation operators specifying ultra-compact, premium-finish galley modules for cabin density optimization. Demand concentrates in completions centers across Wichita, Kansas and Savannah, Georgia where Gulfstream and Textron Aviation facilities drive regional supplier clustering. Custom wood veneer and stone countertop integrations extend delivery timelines.
- Cargo Airlines:Freighter operators requiring minimal crew meal facilities on long-haul routes.
- Government Aircraft:Military and head-of-state transport programs with hardened security and communication integration requirements.
Commercial Airlines absorb the dominant share of production volume. Private Jets are climbing the fastest as fractional ownership expands.
Technology:
Regulatory pressure is compressing the viable technology set, with gas systems facing operational restrictions under EU Green Deal aviation decarbonization targets.
- Electric:Resistive heating and compressor-based cooling systems drawing from aircraft electrical buses, now standard for new installations. EASA is developing amended certification pathways favoring all-electric configurations for European-registered fleets. Airlines operating mixed-registry portfolios are standardizing on electric inserts to simplify fleet management.
- Induction:Electromagnetic heating technology eliminating thermal mass and enabling precise temperature control for premium cabin service. Full-service carriers adopting lie-flat seating expansions specify these units for reduced galley footprints. The shift is compressing demand for gas infrastructure routing across narrow-body production lines.
- Gas:Propane-based heating systems facing phase-out pressure from EU Green Deal aviation decarbonization targets.
- Hybrid:Dual-mode systems combining electric and gas capabilities for operational flexibility across registry jurisdictions.
Electric systems command the largest installed base. Induction is gaining share fastest as premium cabin densification accelerates.
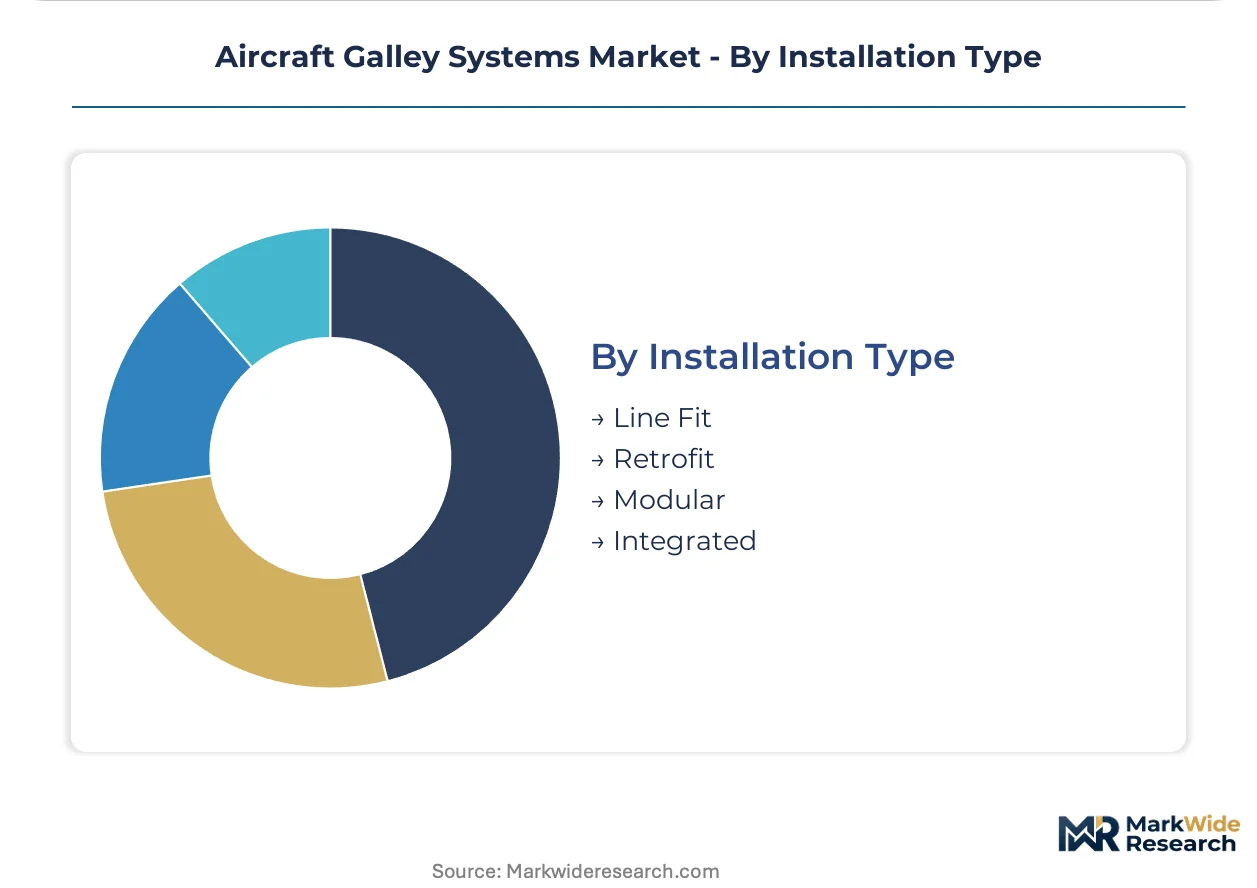
Installation Type:
Channel economics diverge sharply between airframe-integrated programs with multi-year lead times and aftermarket retrofit windows driven by maintenance cycle triggers.
- Retrofit:Modular modernization kits installed during heavy maintenance checks to upgrade aging fleet interiors. Aging wide-body fleets in the United States are driving sustained procurement as carriers match passenger experience standards on newer aircraft. Collins Aerospace leverages RTX avionics integration capabilities to bundle retrofit galley systems with cabin management electronics.
- Line Fit:Factory-integrated installations at final assembly lines reducing airline induction labor and certification burden. Diehl Stiftung & Co. KG competes on modularity, offering configurations that reduce final assembly labor at Boeing and Airbus plants. Procurement teams at both airframe manufacturers are capturing preference for standardized modular interfaces.
- Modular:Pre-certified subassemblies enabling rapid configuration changes across mixed fleet types.
- Integrated:Fully customized galley monuments engineered for specific airframe structural envelopes.
Line Fit absorbs the majority of new production value. Retrofit is expanding most quickly as wide-body fleet age profiles peak.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Aerospace engineering talent clusters in Seattle, Toulouse, and Hamburg anchor galley system procurement decisions. These workforce concentrations synchronize with airframe final assembly locations. Regulatory divergence between FAA Part 25 and EASA CS-25 frameworks shapes regional supplier qualification requirements.
United States
Boeing's production recovery at Renton and Everett drives narrow-body galley procurement synchronization. FAA Part 25.853 smoke-toxicity mandates accelerate fire-resistant thermoplastic adoption in new installations. Seattle-Tacoma-Bellevue metro anchors tier-one supplier engineering offices serving airline retrofit programs.
France
Airbus final assembly in Toulouse-Blagnac concentrates line-fit demand for integrated galley monuments. EASA CS-25 electrical safety evolution favors all-electric configurations under EU Green Deal aviation targets. Safran SA's vertical control of refrigeration compressor technology creates supply bottlenecks during A320 production ramps.
Germany
Diehl Stiftung & Co. KG's modularity-focused engineering in Laupheim reduces final assembly labor at Airbus Hamburg. German carriers retrofit aging wide-body fleets to match passenger experience standards. Bavaria's aerospace supplier cluster specializes in 16g crash-load certified structural components.
United Kingdom
AIM Altitude and Aerolux Ltd. anchor galley fabrication in Southern England's aerospace corridor. UK CAA alignment with EASA certification pathways simplifies European-registered fleet standardization. London Gatwick and Heathrow base carriers drive premium cabin densification procurement for lie-flat seating expansions.
Japan
JAMCO Corporation's engineering concentration in Tokyo-Yokohama serves Boeing and Airbus Asian operator retrofit demand. METI industrial policy supports lightweight composite development for next-generation narrow-body configurations. Nagoya's aerospace manufacturing cluster supplies fire-resistant thermoplastic subassemblies to tier-one integrators.
Aircraft Galley Systems Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across the galley systems value chain. Tier-one integrators bundle avionics integration with cabin management electronics to capture long-term airline contracts. Three archetypes dominate: aerospace conglomerates leveraging parent-company avionics capabilities, family-owned German fabricators competing on modularity, and Asian specialists in lightweight structural components. Competitive moves concentrate on strategic partnerships with airframe OEMs and backward integration into critical cooling subsystems.
Among aerospace conglomerates, Collins Aerospace represents the avionics-bundling archetype through its RTX parent-company integration capabilities. Safran SA anchors the vertical-control position through captive refrigeration compressor technology. Diehl Stiftung & Co. KG exemplifies the family-owned modular specialist competing on final-assembly labor reduction at Boeing and Airbus plants.
| Leading Market Players |
|---|
| Collins Aerospace (RTX Corporation) |
| Safran SA |
| JAMCO Corporation |
| Diehl Stiftung & Co. KG |
| Bucher Leichtbau AG |
| Aerolux Ltd. |
| AIM Altitude |
| AVIC Cabin Systems Limited |
| Korita Aviation |
| Others |
Value Chain & Pricing Dynamics
EU Green Deal aviation decarbonization targets gate qualified supply and premium-tier pricing access by mandating all-electric galley configurations for European-registered fleets, forcing suppliers to absorb certification costs or cede market position. Buyers operating mixed-registry portfolios now demand standardized electric inserts, compressing margins for fabricators unable to scale fire-resistant thermoplastic production.
Pricing Analysis
Bundled avionics-galley packages command premium positioning against unbundled component procurement, with Collins Aerospace leveraging RTX integration capabilities to capture long-term airline contracts. Price differentiation hinges on FAR 25.853 certification tier and customization depth for premium cabin densification. Cost compression in standard narrow-body line-fit configurations is intensifying because aluminum alloy price volatility erodes tier-two fabricator margins. Low-cost carriers exhibit highest price sensitivity, while full-service legacy airlines prioritize total cost of ownership over unit acquisition cost.
Supply Chain Analysis
Single-source vulnerability sits with Safran SA's captive refrigeration compressor technology, which creates procurement bottlenecks during Airbus and Boeing production ramps. Supply concentrates in the United States, France, and Germany, drawing from lightweight aluminum alloy and fire-resistant thermoplastic composite inputs. Tariff exposure on energy-intensive smelting feedstocks amplifies raw material cost volatility. Distribution runs through airframe OEM procurement teams at final assembly lines, with aftermarket retrofit channels serving aging wide-body fleet operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a regulatory compounder, with FAA Part 25.853 smoke-toxicity mandates and EASA CS-25 electrical safety evolution continuously resetting compliance baselines and procurement cycles.
For Market Incumbents: Deepen backward integration into fire-resistant thermoplastic composite formulation to defend against emerging Asian specialists in lightweight structural components. Lock in multi-year cabin configuration agreements with Boeing and Airbus procurement teams before arc-fault protection standard amendments open retrofit windows for second-tier competitors. Captive control of cooling subsystem technology remains the critical margin defense lever. For New Entrants and Emerging Players: Maintenance-repair-overhaul facilities represent the most penetrable channel partner type for modular retrofit kit penetration, as aging wide-body fleets in the United States require galley modernization outside OEM line-fit programs. Target private jet completions centers in Wichita and Savannah with ultra-compact premium-finish modules. A technical co-development alliance with a tier-one airframe supplier accelerates qualification timelines faster than standalone certification investment. For Investors and Strategic Acquirers: Roll-up economics work for family-owned German fabricators because modularity-focused engineering capabilities reduce final assembly labor at Boeing and Airbus plants, creating sticky supplier relationships. Platform consolidation across Bavaria's aerospace supplier cluster offers five-to-ten year viability exposure to narrow-body fleet densification tailwinds. Watch EASA CS-25 amendment publication timing as the inflection signal for early-generation electric galley fleet retrofit demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Thermoplastic Composites | Captive fire-resistant material supply locks in FAR 25.853 compliance margin against volatile aluminum alloy pricing. |
| Multi-Year Cabin Configuration Bundling | Long-term avionics-galley-IFE packages with United States legacy carriers synchronize procurement with Boeing production recovery. |
| Induction Technology Platform Standardization | All-electric insert portfolios align with EU Green Deal decarbonization targets and eliminate gas infrastructure maintenance. |
| Retrofit Channel Partnership Expansion | Modular modernization kit alliances with MRO facilities capture aging wide-body fleet upgrade cycles. |
| Geographic Engineering Talent Clustering | Seattle-Tacoma-Bellevue metro offices anchor tier-one supplier positioning for airline retrofit program capture. |
Study Parameters
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combining structured interviews with airline procurement executives, airframe OEM platform engineers, MRO facility operations managers, and galley system R&D directors. Secondary validation draws from FAA airworthiness directive filings, EASA certification pathway publications, SEC 10-K aerospace segment disclosures, and customs trade data on aluminum alloy and thermoplastic composite imports. Bottom-up segment sizing triangulates against top-down airframe production forecasts and fleet age profile analysis.
Rate-of-change decomposition separates volume growth from value mix shift across the projection horizon, modeling galley inserts, refrigeration units, meal distribution systems, and beverage makers by installation type, technology architecture, and end-user segment. CAGRs derive from airframe delivery schedules, fleet retirement patterns, and regulatory mandate implementation timelines. Induction technology penetration curves and electric galley insert power profile evolution serve as industry-specific forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to aluminum alloy price volatility, EASA electrical safety amendment timing, and Boeing production rate stability. Forecasts reflect documented assumptions on fleet renewal synchronization and decarbonization mandate enforcement intensity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft
Europe Aircraft Engines Market
Aircraft
Aircraft Pushback Tugs Market
Aircraft
Aircraft Strut Market
Aircraft
Aircraft Band Clamps Market
Aircraft
Global Commercial Aircraft Disassembly Market
Aircraft
Regional Jet Market
Aircraft
Online in-Flight Shopping Market
Aircraft
Europe Turboprop Aircraft Market
Aircraft
Aircraft Container & Pallet Loader Market
Aircraft
Commercial Aircraft Overhead Stowage Bins Market
Aircraft
Fiber-Optic Strain Sensing Systems for Composite Wing Structures Market
Aircraft
Asia-Pacific Aircraft Windshield Wiper and Washer System Market
Aircraft
North America Commercial Aircraft Market
Aircraft
Special Mission Aircraft Market
Aircraft
Water Bomber Market
Aircraft
Global Helicopter Market