
 North Korea Nuclear Bombs and Missiles Market | 2026-2036
North Korea Nuclear Bombs and Missiles Market Size, Share, and Industry Trends Forecast 2026-2036
North Korea Nuclear Bombs and Missiles Market Insights
State deterrence procurement is shifting toward dual-capable delivery systems across East Asian strategic theaters. April 25th Factory leverages its ordnance manufacturing heritage to dominate ground-based launcher production. Second Academy of Natural Sciences sustains advanced propulsion research that anchors the country's long-range ballistic program. Sanjon Machine Factory competes through precision machining capabilities that extend into guidance system components.
North Korea nuclear bombs and missiles encompass fission-based and thermonuclear warheads paired with ballistic and cruise delivery vehicles, typically utilizing highly enriched uranium or plutonium cores with solid or liquid propellant propulsion achieving ranges from hundreds to intercontinental distances. These systems serve primarily to project strategic deterrence and coercive diplomatic leverage against regional adversaries and alliance networks. Intercontinental ballistic missiles command the largest resource allocation within weapon type categories as testing frequency validates engineering maturity. Mobile transporter erector launchers within delivery systems attract accelerated investment because survivable basing modes complicate adversary targeting calculus. Tactical nuclear devices represent the fastest-expanding operational status segment as doctrine evolves toward limited escalation scenarios.
The country's national defense procurement framework restricts foreign technology transfer while mandating indigenized supply chains across critical subsystems. The central strategic weapons authority enforces development timelines that compress testing cycles despite material sanctions from multilateral export control regimes. Stakeholders must monitor submarine-launched vehicle test cadence as the decisive indicator of second-strike credibility investments.
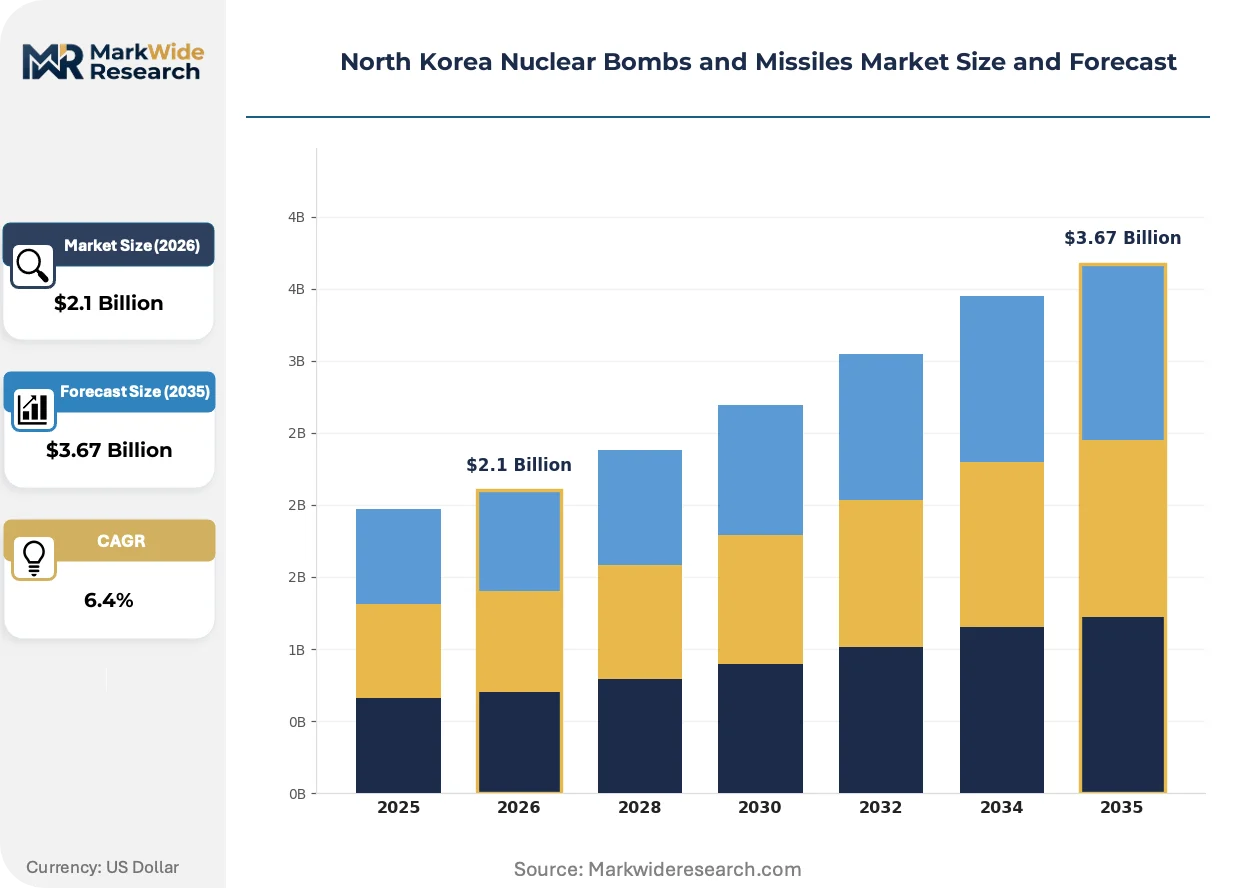
Market Dynamics
Submarine-launched ballistic missile maturation is electrifying procurement priorities as survivable second-strike capabilities displace fixed-site deterrence postures. The Second Academy of Natural Sciences compresses development cycles through indigenized solid propellant research.
Growth Catalysts
- Second-Strike Doctrine Evolution:Mobile transporter erector launchers attract resource reallocation as survivable basing modes complicate adversary targeting calculus. Tactical nuclear devices expand operational status as limited escalation scenarios reshape force deployment.
- Indigenized Supply Chain Mandates:The central strategic weapons authority enforces compressed testing timelines despite multilateral export control sanctions. Critical subsystem production localizes at April 25th Factory and Sanjon Machine Factory.
- Solid Propellant Advancement:Advanced propulsion research at Second Academy of Natural Sciences anchors long-range ballistic program viability. Liquid propellant systems face displacement as solid fuel reliability improves.
Market Restraints
- Material Sanctions Regime:Multilateral export controls restrict precision machining equipment and specialty alloy access. Sanjon Machine Factory confronts component sourcing bottlenecks for guidance system fabrication.
- Testing Frequency Constraints:Flight test cadence limitations compress validation windows for intercontinental ballistic missile engineering maturity. Range instrumentation gaps obscure telemetry analysis.
- Warhead Miniaturization Thresholds:Thermonuclear device yield-to-weight optimization encounters physics constraints. Fission-based tactical devices face payload integration limits on cruise delivery vehicles.
Strategic Opportunities
- Submarine Platform Integration:Sinpo-class ballistic missile submarine construction creates new delivery vehicle deployment architecture. Second-strike credibility investments concentrate at the country's eastern naval facilities.
- Guidance System Localization:Precision machining capabilities at Sanjon Machine Factory extend into inertial navigation component production. Import substitution reduces foreign technology dependency.
- Tactical Doctrine Expansion:Limited escalation scenarios drive demand for short-range ballistic systems with reduced-yield warheads. Regional force deployment patterns favor mobile launcher proliferation.
Industry Challenges
- Specialized Workforce Scarcity:Advanced propulsion engineering and nuclear materials science expertise concentrates within Second Academy of Natural Sciences. Knowledge transfer constraints limit production scaling.
- Quality Assurance Complexity:Solid propellant grain manufacturing demands environmental control infrastructure. Batch consistency verification extends component qualification timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North Korea Nuclear Bombs and Missiles Market |
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.67 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Weapon Type: Intercontinental Ballistic Missiles, Short-Range Ballistic Missiles, Cruise Missiles, Nuclear Warheads, Tactical Nuclear Devices Delivery System: Land-Based Launchers, Submarine-Launched Vehicles, Airborne Platforms, Mobile Transporter Erector Launchers, Fixed Silos Operational Status: Active Deployment, Testing Phase, Development Stage, Decommissioned Facilities Strategic Purpose: Deterrence, Strategic Threat Projection, Tactical Battlefield Use, Political Leverage |
| Companies Covered | April 25th Factory, Sanjon Machine Factory, Second Academy of Natural Sciences, Chahung Machine Factory, Pukchang Machine Factory, National Aerospace Development Administration, Ryongsong Machine Complex, Kangdong General Tractor Plant, Korean Central News Agency Munitions Factories, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North Korea Nuclear Bombs and Missiles Market Trends and Innovations
Propulsion system electrification and guidance miniaturization are compressing development-to-deployment cycles. State procurement prioritizes survivable basing modes over fixed infrastructure.
Solid propellant motor production is electrifying ballistic missile reliability as liquid fuel handling constraints compress launch readiness timelines. Second Academy of Natural Sciences adopts continuous casting techniques for propellant grain fabrication. Mobile launcher units receive priority allocation as survivability requirements disperse basing geography.
The country's national defense procurement framework restricts foreign technology transfer while mandating indigenized supply chains across critical subsystems. Central strategic weapons authority enforcement compresses testing cycles despite multilateral export control material sanctions. Submarine-launched vehicle programs attract accelerated resource allocation as second-strike credibility investments.
Regional military procurement patterns concentrate demand within tactical nuclear devices as limited escalation doctrines reshape force deployment. Mobile transporter erector launchers displace fixed-site silos in procurement priority. The country's eastern coastal facilities anchor submarine platform construction as survivable basing modes complicate adversary targeting calculus.
North Korea Nuclear Bombs and Missiles Market Segmentation
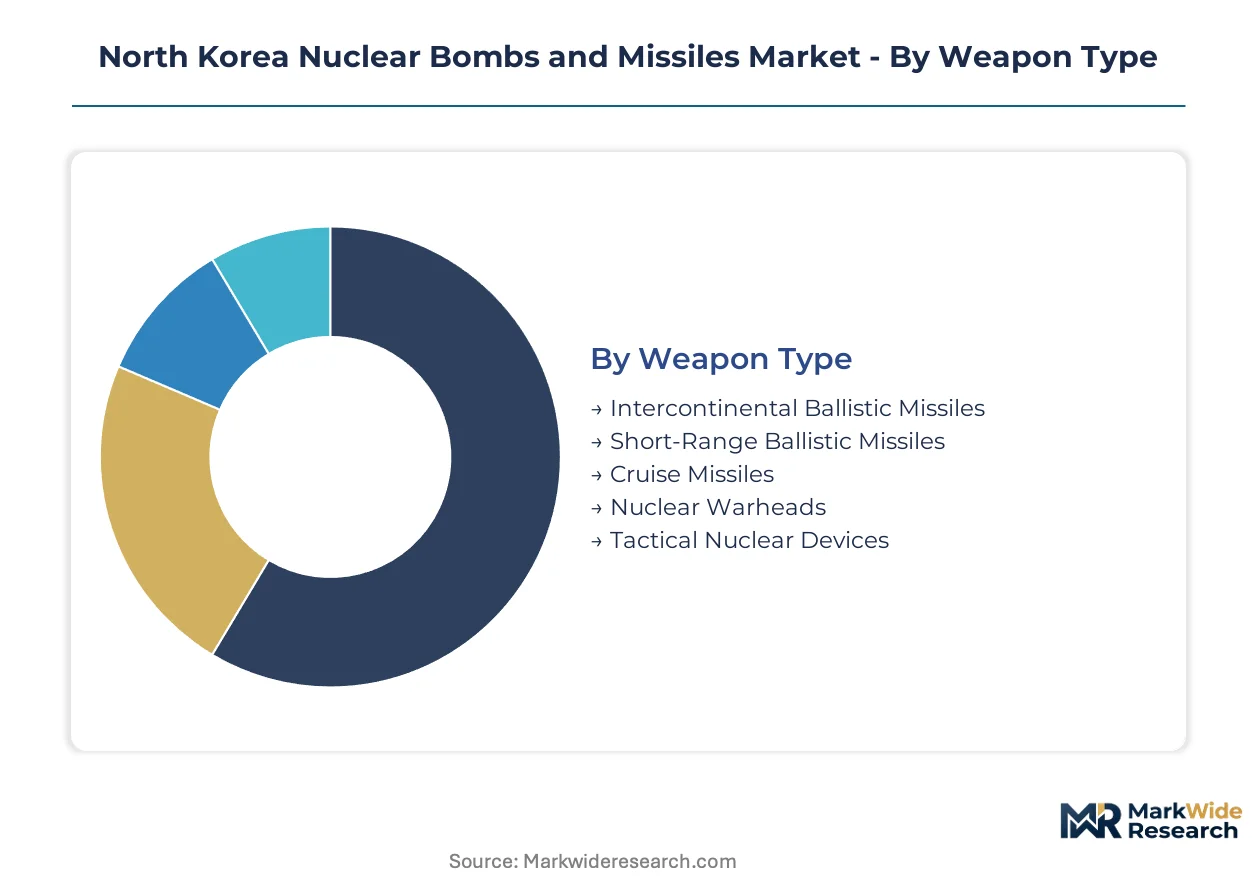
Segmentation reveals how procurement resources fragment across delivery architectures and operational readiness tiers. Weapon type distribution reflects doctrinal priorities, while delivery system choices expose survivability investments against adversary counterforce targeting.
Weapon Type:
Standalone strategic systems operate independently of conventional force integration, whereas tactical variants embed within combined arms structures.
- Intercontinental Ballistic Missiles:Liquid and solid propellant systems achieve ranges exceeding 10,000 kilometers with multiple independently targetable reentry vehicles. Resource concentration at the Second Academy of Natural Sciences reflects prioritization of continental-range deterrence against alliance networks.
- Tactical Nuclear Devices:Reduced-yield warheads with sub-kiloton to low-kiloton outputs integrate with short-range delivery systems. Limited escalation scenarios at regional flashpoints drive procurement acceleration as doctrine evolves toward warfighting applications.
- Short-Range Ballistic Missiles:Solid propellant systems under 1,000 kilometers range dominate theater strike planning.
- Cruise Missiles:Air-breathing propulsion with terrain-following guidance extends conventional-nuclear dual-use options.
- Nuclear Warheads:Fission and thermonuclear designs utilizing highly enriched uranium or plutonium cores anchor payload inventories.
Intercontinental Ballistic Missiles leads volumes today; Tactical Nuclear Devices is gaining share fastest.
Delivery System:
Cost tier stratification separates survivable mobile basing from fixed infrastructure requiring hardened construction.
- Mobile Transporter Erector Launchers:Wheeled and tracked vehicles disperse launch units across road and off-road networks. April 25th Factory production lines prioritize these systems as counterforce resistance becomes paramount.
- Submarine-Launched Vehicles:Solid propellant missiles deploy from Sinpo-class ballistic missile submarines. Eastern naval facilities concentrate investment as second-strike credibility displaces first-use postures.
- Land-Based Launchers:Fixed and mobile ground systems comprise the legacy deployment architecture.
- Airborne Platforms:Modified transport aircraft deliver gravity bombs with limited penetration capability.
- Fixed Silos:Hardened underground launch facilities confront precision strike vulnerability.
Mobile Transporter Erector Launchers commands the largest procurement allocation; Submarine-Launched Vehicles shows the steepest expansion trajectory.
Operational Status:
Volume distribution across maturity stages indicates pipeline depth versus fielded capability ratios.
- Active Deployment:Fielded systems with established command-and-control protocols maintain alert status. Central strategic weapons authority enforcement compresses deployment timelines despite multilateral sanctions.
- Testing Phase:Flight validation programs at domestic ranges verify engineering parameters before operational certification. Range instrumentation gaps constrain telemetry analysis.
- Development Stage:Pre-prototype research at Second Academy of Natural Sciences advances propulsion and guidance subsystems.
- Decommissioned Facilities:Retired systems and mothballed production infrastructure retain reactivation potential.
Active Deployment dominates current force structure; Testing Phase is expanding most quickly as validation cycles accelerate.
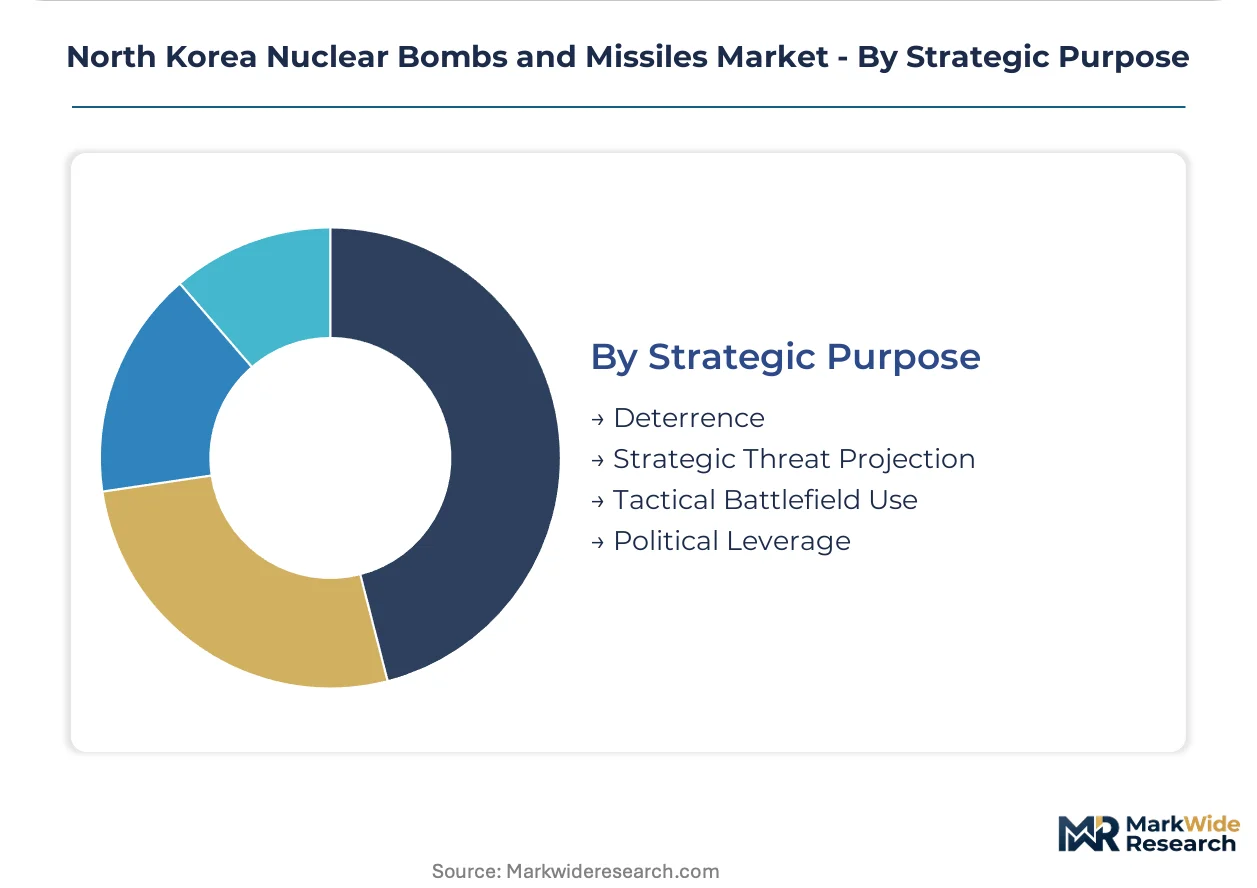
Strategic Purpose:
Application segmentation distinguishes existential deterrence from coercive diplomacy and warfighting integration.
- Deterrence:Strategic posture designed to prevent adversary aggression through assured retaliation. Second-strike capability investments at submarine facilities anchor credibility.
- Tactical Battlefield Use:Theater-level employment against military targets within regional conflict scenarios. Force deployment patterns favor mobile launcher proliferation near armistice lines.
- Strategic Threat Projection:Long-range strike capability against distant adversary homelands.
- Political Leverage:Latent capability deployment for diplomatic coercion and negotiation positioning.
Deterrence retains the dominant doctrinal position; Tactical Battlefield Use is climbing the fastest as limited war concepts mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage around sanctions enforcement gaps channels component sourcing toward jurisdictions with weaker export control implementation. Production activity clusters in areas where dual-use technology monitoring remains fragmented.
China
Machine tool and precision component demand flows through Dandong and Shenyang industrial corridors near the Korean border. The country's export control enforcement under MIIT regulations shows variable implementation across provincial jurisdictions. Liaoning Province machine shops serve as intermediary fabrication nodes for specialty alloy components.
Russia
Propulsion system research collaboration and materials science exchange accelerates through Far Eastern Federal District technical institutes. Rosatom oversight mechanisms do not extend to certain dual-use academic partnerships. Vladivostok and Khabarovsk technical universities host visiting research programs with limited scrutiny.
Iran
Ballistic missile engineering knowledge transfer and solid propellant manufacturing techniques circulate through defense research establishments. The country's nuclear regulatory authority under AEOI maintains separation between declared civilian and suspected military applications. Isfahan and Tehran research complexes facilitate technical documentation exchange through academic channels.
Pakistan
Uranium enrichment methodology and warhead miniaturization expertise concentrates at Khan Research Laboratories and related facilities. The Pakistan Atomic Energy Commission regulatory framework does not fully account for cross-border technical consultation. Kahuta and Rawalpindi defense industrial zones maintain historical knowledge-sharing relationships.
Myanmar
Submarine construction technical assistance and naval architecture consultation emerges through military-to-military cooperation frameworks. The country's defense procurement oversight lacks transparency mechanisms for foreign advisory contracts. Yangon and Thilawa port facilities receive unexplained technical delegations with marine engineering specialization.
North Korea Nuclear Bombs and Missiles Market Competitive Landscape
Vertical integration into critical subsystem production dominates the current landscape as sanctions exposure forces captive supply chain development. The vendor base concentrates within state-directed industrial groupings rather than independent private entities. Three archetypes prevail: weapons research institutes with integrated manufacturing, machine complexes with precision fabrication specialization, and component factories with single-product focus. Strategic moves center on backward integration into specialty materials and geographic dispersion of production nodes.
Within the research-institute archetype, the Second Academy of Natural Sciences occupies the central position anchoring propulsion and guidance development. Among machine-complex fabricators, April 25th Factory and Sanjon Machine Factory exemplify the precision-manufacturing tier with heritage ordnance production capabilities. These named entities represent the dominant institutional forms rather than competing commercial enterprises.
| Leading Market Players |
|---|
| April 25th Factory |
| Sanjon Machine Factory |
| Second Academy of Natural Sciences |
| Chahung Machine Factory |
| Pukchang Machine Factory |
| National Aerospace Development Administration |
| Ryongsong Machine Complex |
| Kangdong General Tractor Plant |
| Korean Central News Agency Munitions Factories |
| Others |
Pricing and Supply Chain Analysis
Solid propellant motor production transitions at Second Academy of Natural Sciences simultaneously compress unit production costs and concentrate upstream chemical precursor sourcing within domestic supply nodes. This manufacturing shift redirects procurement power toward captive specialty alloy foundries while marginalizing liquid fuel system suppliers.
Pricing Analysis
Direct-to-OEM channels handling strategic weapons procurement operate without intermediary margin layers, compressing cost pass-through to central procurement authorities. Three-tier pricing structure across intercontinental systems, tactical devices, and cruise delivery vehicles reflects yield-to-weight optimization thresholds and guidance system complexity. Pricing pressure stems from multilateral export control enforcement tightening specialty machining equipment access. State procurement offices exhibit lowest price sensitivity given mission-critical specifications, while technical institute research contracts face budget constraint scrutiny.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale demand from central strategic weapons authority procurement mandates. Geographic supply concentration centers on domestic machine complexes in Pyongyang and Hamhung industrial corridors, with secondary component sourcing through Dandong and Shenyang border corridors. Raw material dependencies include high-strength specialty alloys, precision ball bearings, and solid propellant precursor chemicals. Single-source vulnerability pervades guidance system inertial navigation component fabrication. Distribution runs through state-directed logistics networks bypassing commercial freight channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as procurement specifications harden around survivable basing modes and second-strike credibility investments displace first-use postures.
For Market Incumbents: Deepen backward integration into specialty alloy foundry operations at Ryongsong Machine Complex to offset Sanjon Machine Factory sourcing bottlenecks. Expand solid propellant grain manufacturing capacity at Second Academy of Natural Sciences before liquid system suppliers consolidate. Counter emerging submarine platform integration demands through preemptive eastern naval facility infrastructure lock-in. For New Entrants and Emerging Players: Precision miniaturization of inertial navigation components offers entry path into guidance system subcontracting tiers. Target tactical nuclear device warhead integration services as doctrine evolution accelerates demand for reduced-yield payload specialists. Pursue technical advisory contracts through Myanmar and Iran military-to-military frameworks as alternative market development channels. For Investors and Strategic Acquirers: Valuations sit cheapest among machine-complex fabricators with dormant precision machining capacity suitable for propulsion component reactivation. Long-term viability hinges on sustained second-strike doctrine commitment across successive leadership transitions. Acquisition target archetype: single-product component factories with transferable specialty alloy expertise. Monitor submarine-launched vehicle test cadence as decisive inflection indicator for resource reallocation credibility.| Strategic Initiative | Industry Significance |
|---|---|
| Solid Propellant Manufacturing Scale-Up | Second Academy of Natural Sciences compression of development cycles displaces liquid fuel system incumbents. |
| Submarine Platform Integration | Sinpo-class ballistic missile submarine construction anchors second-strike credibility investments at eastern naval facilities. |
| Guidance System Localization | Sanjon Machine Factory extension into inertial navigation production reduces foreign technology dependency exposure. |
| Specialty Alloy Backward Integration | Ryongsong Machine Complex foundry investments counter multilateral export control machining equipment restrictions. |
| Tactical Doctrine Expansion | Limited escalation scenario procurement acceleration reshapes force deployment patterns near regional armistice lines. |
Research Methodology
Multiple input streams — defense procurement documentation, technical institute research disclosures, and sanctions enforcement monitoring — were reconciled through systematic cross-validation. Primary interviews engaged strategic weapons program administrators, machine complex production directors, and export control compliance specialists across East Asian jurisdictions. Secondary sources included multilateral sanctions committee reports, customs trade data, and technical documentation from academic exchange programs. Bottom-up segment sizing and top-down macro constraint triangulation anchored volume estimates.
Historical testing frequency patterns were cross-referenced against panel input from propulsion engineering specialists to derive trajectory assumptions across the projection horizon. Segmentation dimensions modeled encompass weapon type, delivery system architecture, operational readiness tier, and strategic purpose application. CAGRs were derived from trend extrapolation of procurement resource allocation patterns validated against doctrinal evolution indicators. Forecast inputs incorporated solid propellant reliability advancement curves and submarine platform construction timelines.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to leadership transition dynamics and alliance network deterrence posture recalibration. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Weapons and Ammunition
Asia-Pacific Ammunition Market
Weapons and Ammunition
Torpedo Market
Weapons and Ammunition
Weapon Night Sight Market
Weapons and Ammunition
Programmable Ammunition Market
Weapons and Ammunition
NATO Ammunition Market
Weapons and Ammunition
Riflescope Market
Weapons and Ammunition
Weapons Carriage and Release System Market
Weapons and Ammunition
France Nuclear Bombs and Missiles Market
Weapons and Ammunition
Ballistic Protection Market
Weapons and Ammunition
High Power Microwave Directed Energy Weapons Market
Weapons and Ammunition
Cruise Missile Market
Weapons and Ammunition
Manned Anti-Tank Guided Missile System Market
Weapons and Ammunition
Precision Guided Munition Market
Weapons and Ammunition
Recoilless Rifle Market
Weapons and Ammunition
Airsoft Guns Market
Weapons and Ammunition
Missile Seekers Market