
 Global Aircraft Design and Engineering Market | 2026-2036
Global Aircraft Design and Engineering Market Size, Share, and Industry Trends Forecast 2026-2036
Global Aircraft Design and Engineering Market Foresight
China's COMAC production ramp-up is reshaping competitive dynamics in commercial airframe engineering. Boeing leverages its vertically integrated design-test-certification pipeline to sustain program execution speed. Airbus anchors European engineering capacity through its Toulouse and Hamburg development centers. Lockheed Martin dominates military platform design with classified program specialization.
Aircraft design and engineering encompasses the multidisciplinary process of conceiving, analyzing, and validating airborne vehicle configurations from conceptual layouts through production-ready technical datasets, incorporating computational fluid dynamics validation, composite laminate optimization, and systems-level integration testing to achieve certifiable flight performance. The engineering discipline dimension shows structural engineering and avionics commanding the deepest margin pools due to certification complexity and intellectual property intensity, while systems engineering grows fastest as electrified propulsion architectures demand integrated thermal-electric-mechanical control frameworks. Service offerings cluster heavily in simulation and testing, where digital twin fidelity requirements are elevating vendor technical barriers.
The FAA, EASA, and CAAC collectively govern market access through divergent certification timelines and airworthiness interpretation standards, with each regulator's evolving stance on autonomous flight and sustainable aviation fuels directly redirecting R&D allocation across engineering teams. ISO 9100 quality management and AS9100D aerospace-specific standards further constrain supplier qualification, compressing the addressable vendor base for prime contractors. Stakeholders must monitor which regulatory jurisdiction achieves streamlined electric aircraft certification first, as that geography will attract disproportionate design engineering investment and talent migration.
Market Dynamics
Electrified propulsion architectures are forcing a fundamental reconfiguration of aircraft design workflows, collapsing the traditional separation between airframe, powertrain, and thermal engineering disciplines into unified development sprints.
Growth Catalysts
- FAA Airworthiness Pathways:The FAA's streamlined certification routes for electric propulsion systems compress design-to-flight timelines, accelerating capital deployment into novel airframe configurations.
- Defense Procurement Surge:Pentagon demand for next-generation aerodynamic platforms sustains multi-year engineering contracts with embedded technology refresh clauses.
- Composite Laminate Optimization:Automated fiber placement and out-of-autoclave curing processes reduce airframe weight fractions while maintaining damage tolerance thresholds.
Market Restraints
- Titanium Supply Concentration:Russian and Chinese dominance in sponge production creates input cost volatility for structural components requiring high strength-to-weight ratios.
- Certification Divergence:Misaligned timelines between FAA, EASA, and CAAC force parallel qualification campaigns, duplicating validation expenditures.
- Legacy Fleet Substitution Limits:Existing turbine-powered aircraft retain operational economics that delay replacement cycles for electric alternatives.
Strategic Opportunities
- Urban Air Mobility Infrastructure:Vertiport network planning in the United Arab Emirates creates demand for integrated vehicle-ground system engineering.
- EU Green Deal Alignment:Sustainable aviation fuel mandates and carbon border adjustments redirect R&D budgets toward lifecycle-optimized airframe designs.
- Digital Twin Convergence:Fusion of computational fluid dynamics with real-time sensor feedback enables predictive maintenance contracts that capture aftermarket value.
Industry Challenges
- Multiphysics Simulation Talent Scarcity:Shortage of engineers fluent in coupled thermal-electric-mechanical modeling constrains program staffing for electrified platforms.
- Type Certificate Timeline Compression:Compressed FAA validation schedules strain test article production capacity and flight envelope expansion protocols.
- IP Fragmentation Across Tier N:Distributed patent holdings in battery management and motor control complicate technology licensing for integrated propulsion systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Aircraft Design and Engineering Market |
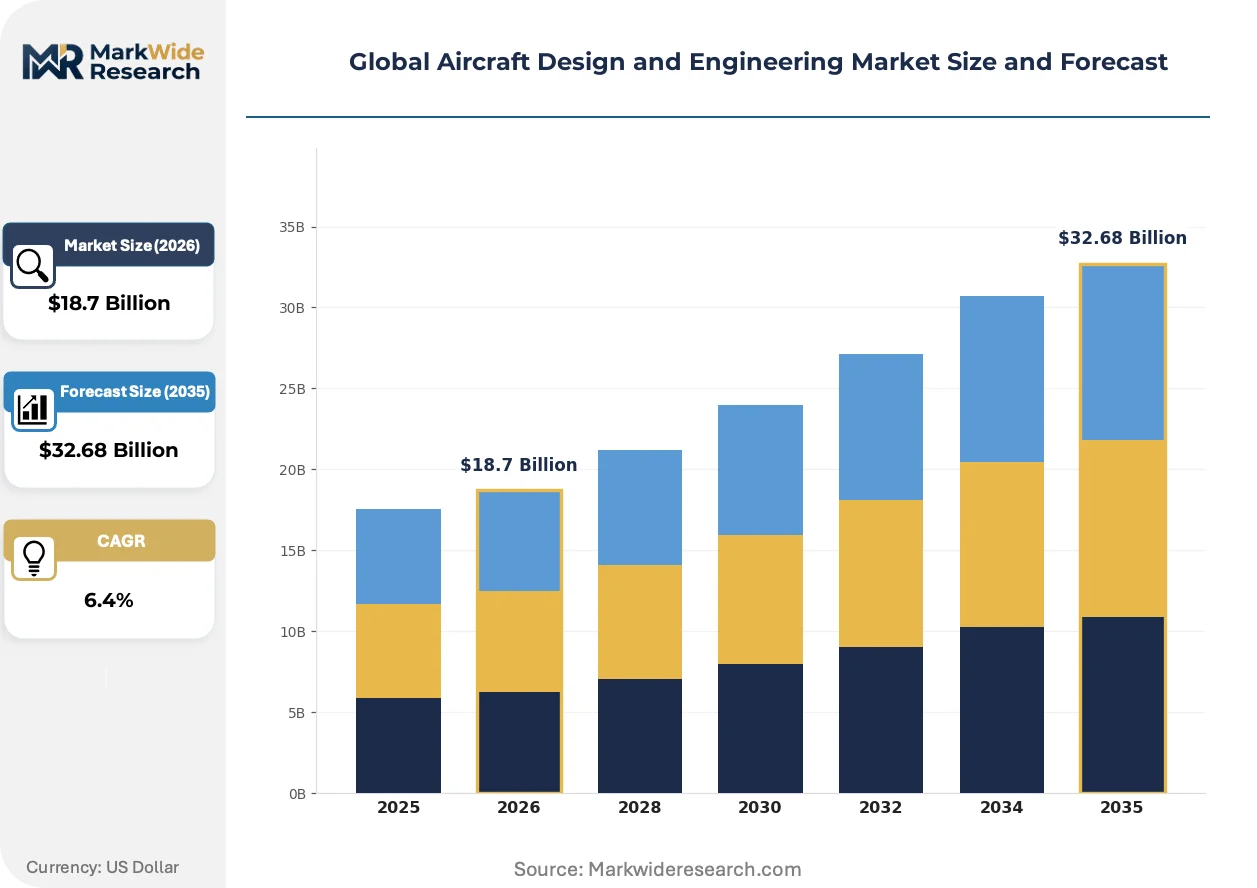
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $32.68 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Design Type: Conceptual, Preliminary, Detailed, System Integration Engineering Discipline: Aerodynamics, Avionics, Structural, Propulsion, Systems Engineering End User: Airframe Manufacturers, Defense Contractors, Space Agencies, Airline Companies Service Offering: CAD Modeling, Simulation & Testing, Prototyping, Certification Support, Project Management |
| Companies Covered | Northrop Grumman, General Dynamics, Boeing, Embraer, Dassault Aviation, Airbus, BAE Systems, COMAC, Lockheed Martin, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Aircraft Design and Engineering Market Shifts & Advancements
Computational methods and regulatory frameworks are converging to redefine how aircraft configurations progress from concept to certifiable design, with digital validation replacing physical prototyping at unprecedented scale.
Digital thread architectures are hybridizing legacy CAD-CAE workflows into continuous model-based engineering environments. Tier 1 suppliers and primes now mandate native geometry sharing across aerostructures, propulsion, and avionics teams. This convergence collapses interface control document cycles and enables real-time interference detection before hardware commitment.
EASA's evolving stance on autonomous flight certification is redirecting European engineering resources toward fault-tolerant control law development. The regulator's condition-specific airworthiness criteria for reduced-crew operations force redesign of cockpit human-machine interfaces. German and French development centers now anchor continental capability for self-certifying flight control software.
Airline technical procurement teams are consolidating vendor relationships around full-lifecycle engineering partners rather than discrete design contracts. Long-term service agreements now bundle initial airframe development with continued airworthiness management and modification engineering. This pattern concentrates most visibly among low-cost carriers operating narrowbody fleets in Southeast Asia.
Global Aircraft Design and Engineering Market Segmentation
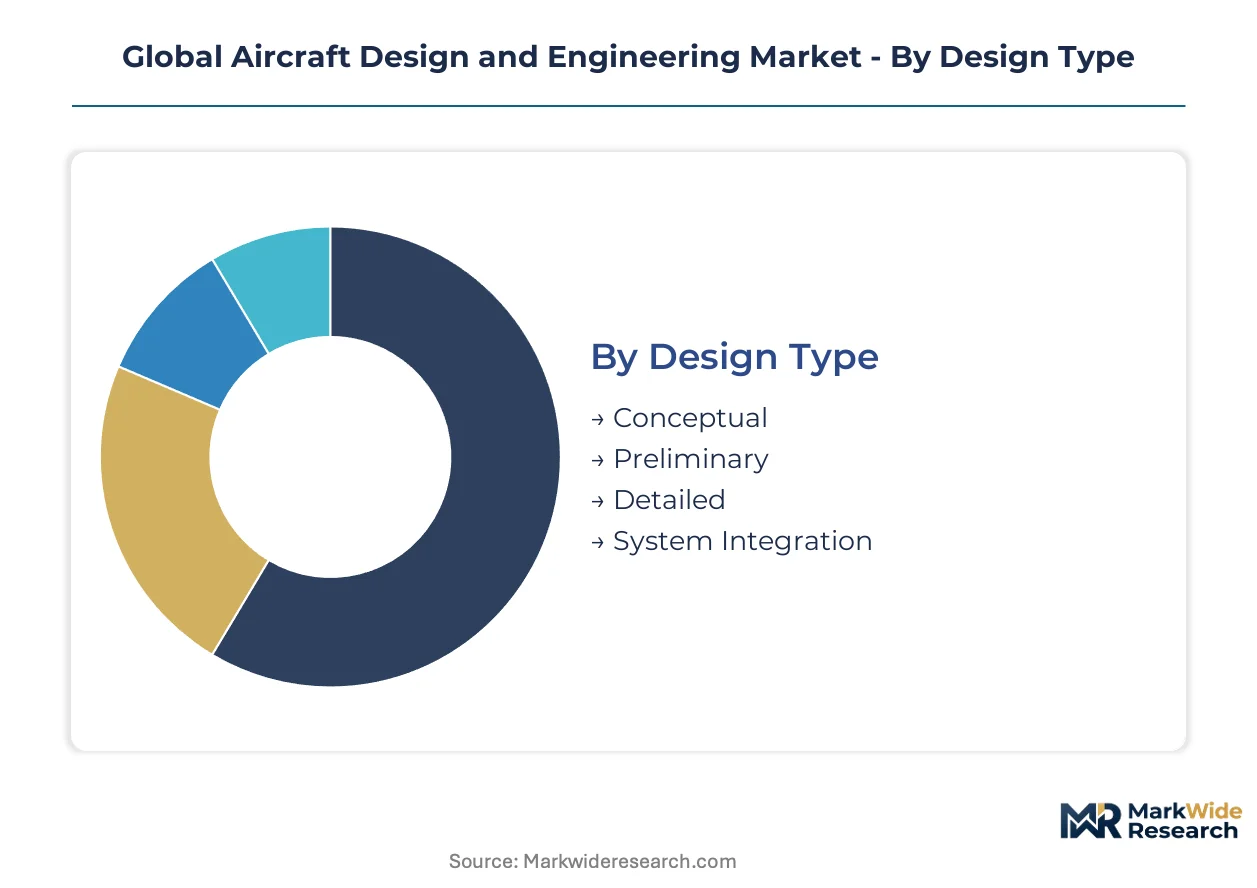
Aircraft design and engineering services fragment across multiple dimensions, with contract duration and technical specialization determining vendor selection criteria. Design type governs project phasing and cash flow timing, while engineering discipline alignment dictates which firms qualify for prime contractor relationships.
Design Type:
Conceptual phases turn over fastest with 6-18 month cycles, while system integration stretches across multi-year development programs. Preliminary and detailed design occupy intermediate positions with 2-4 year typical durations.
- Detailed:Production-ready technical datasets specifying material callouts, manufacturing tolerances, and assembly sequences. Defense contractors in the United States concentrate procurement here, driven by Pentagon multi-year engineering contracts with embedded technology refresh clauses.
- System Integration:Validation of interoperable avionics, propulsion, and flight control architectures against certifiable performance thresholds. Airbus anchors European demand through its Toulouse and Hamburg development centers, constrained by EASA's evolving autonomous flight certification timelines.
- Conceptual:Mission requirement translation into initial configuration layouts and performance estimates.
- Preliminary:Sizing trades and configuration refinement before commitment to detailed design.
Detailed design dominates installed base. System integration is where expansion concentrates.
Engineering Discipline:
Cost tier stratification separates high-margin certification-intensive specialties from commoditized analysis services. Structural engineering and avionics command premium pricing due to intellectual property intensity.
- Structural:Composite laminate optimization, damage tolerance analysis, and fatigue life prediction for certifiable airframes. Boeing leverages vertically integrated design-test-certification pipelines here, sustaining program execution speed through captive structural analysis capacity.
- Systems Engineering:Integrated thermal-electric-mechanical control frameworks for electrified propulsion architectures. Engineering teams in Germany and France concentrate development resources, redirected by EASA condition-specific airworthiness criteria for reduced-crew operations.
- Aerodynamics:Computational fluid dynamics validation and wind tunnel correlation for drag and stability characteristics.
- Avionics:Flight control software, navigation systems, and cockpit human-machine interface development.
- Propulsion:Turbine, electric motor, and hybrid powertrain integration with airframe thermal management.
Structural engineering captures deepest margin pools. Systems engineering is climbing the fastest as electrified platforms proliferate.
End User:
Application focus determines technical specification stringency, with defense and space programs imposing classified handling requirements that filter the addressable vendor base.
- Defense Contractors:Classified aerodynamic platform development with embedded counter-stealth and survivability specifications. Lockheed Martin dominates procurement here through specialized program execution capabilities, sustained by Pentagon demand for next-generation platforms.
- Airframe Manufacturers:Commercial transport and business jet configuration development from concept through type certificate. China's COMAC production ramp-up is reshaping competitive dynamics, with engineering demand concentrating around Shanghai and Xi'an aerospace clusters.
- Airline Companies:Continued airworthiness management, modification engineering, and fleet standardization programs.
- Space Agencies:Reusable launch vehicle and orbital platform design with extreme environment survivability requirements.
Defense contractors anchor high-value program flow. Airframe manufacturers represent the steepest expansion trajectory as commercial production rates recover.
Service Offering:
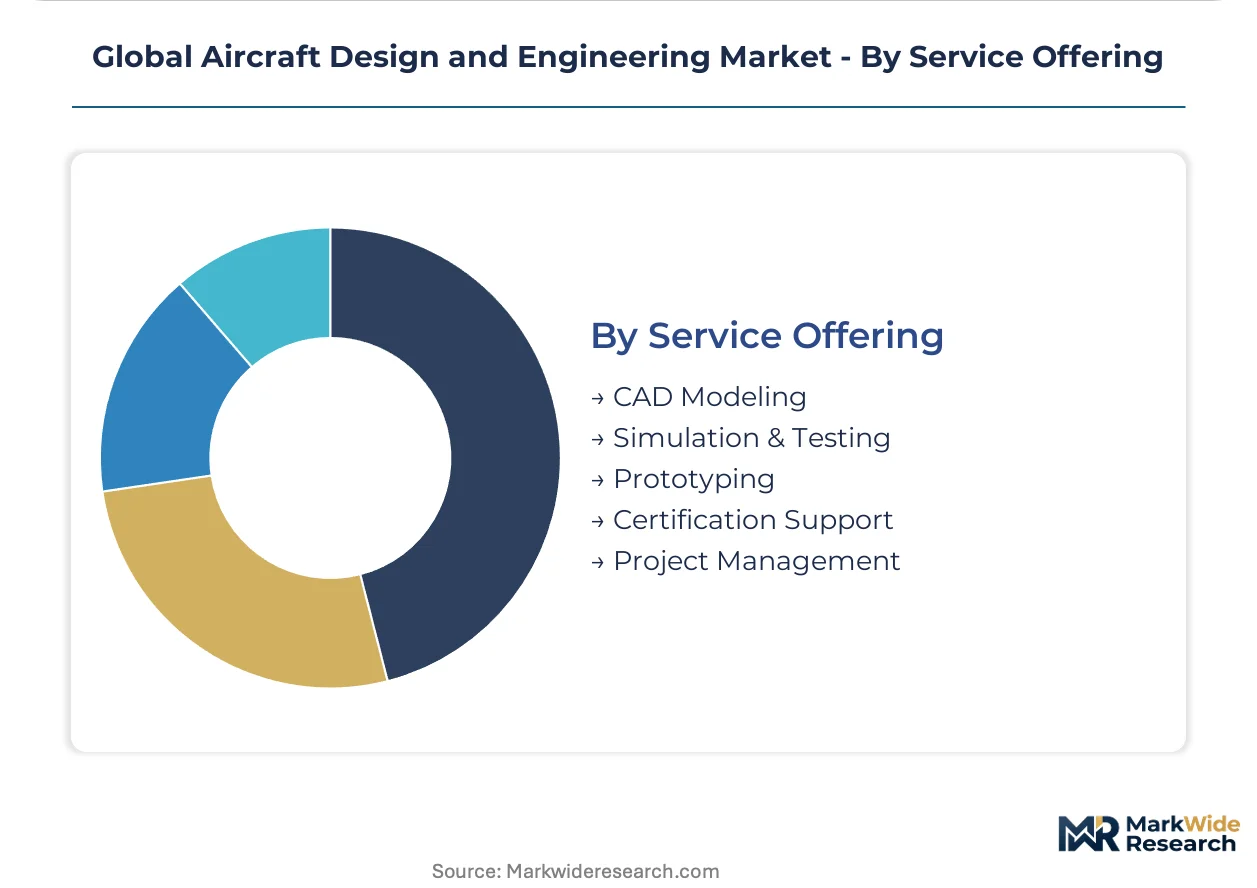
Customer type splits between discrete project contracts and long-term lifecycle partnerships, with full-service bundling gaining share among low-cost carriers.
- Simulation & Testing:Digital twin implementation, computational fluid dynamics validation, and hardware-in-the-loop verification. Tier 1 suppliers and primes now mandate native geometry sharing across aerostructures, propulsion, and avionics teams, elevating vendor technical barriers.
- Certification Support:FAA, EASA, and CAAC airworthiness documentation, flight test planning, and regulatory liaison. Engineering teams face compressed FAA validation schedules that strain test article production capacity and flight envelope expansion protocols.
- CAD Modeling:Parametric geometry development and model-based engineering environment maintenance.
- Prototyping:Physical test article fabrication for structural, systems, and full-vehicle validation campaigns.
- Project Management:Integrated master scheduling, risk quantification, and supplier coordination across distributed engineering teams.
Simulation and testing commands premium positioning. Certification support is gaining share fastest as regulatory divergence forces parallel qualification campaigns.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The FAA anchors the dominant geography through streamlined certification pathways for electric propulsion systems, while EASA and CAAC compete for regulatory leadership in autonomous flight and sustainable aviation standards.
United States
Pentagon procurement of next-generation aerodynamic platforms sustains multi-year engineering contracts with embedded technology refresh clauses. The FAA's updated airworthiness certification pathways compress design-to-flight timelines for novel configurations. Engineering demand concentrates around Seattle and Wichita aerospace clusters, where defense contractors and commercial primes maintain vertically integrated design-test-certification pipelines.
China
COMAC's production ramp-up for commercial airframes is reshaping competitive dynamics in airframe engineering services. The Civil Aviation Administration of China maintains divergent timelines from Western regulators, forcing parallel qualification campaigns for export-bound platforms. Shanghai and Xi'an aerospace clusters anchor engineering capacity expansion, with state-directed investment accelerating development center construction.
Germany
EASA's evolving stance on autonomous flight certification redirects engineering resources toward fault-tolerant control law development. The EU Green Deal's sustainable aviation fuel mandates and carbon border adjustments redirect R&D budgets toward lifecycle-optimized airframe designs. Hamburg and Munich development centers anchor continental capability for self-certifying flight control software and electrified propulsion integration.
France
Airbus anchors European engineering capacity through Toulouse development centers focused on system integration and reduced-crew operations. EASA condition-specific airworthiness criteria force redesign of cockpit human-machine interfaces for autonomous flight. The Toulouse aerospace cluster concentrates avionics and flight control engineering talent, with German-French collaboration defining continental standards.
United Arab Emirates
Vertiport network planning for urban air mobility creates demand for integrated vehicle-ground system engineering. The country's national aviation regulator aligns with emerging global standards for electric vertical take-off and landing certification. Dubai and Abu Dhabi development zones attract engineering investment for advanced air mobility infrastructure, with sovereign wealth deployment accelerating test facility construction.
Global Aircraft Design and Engineering Market Competitive Landscape
Vertically integrated primes and specialized defense contractors split the market between multi-year platform programs and discrete engineering services. The vendor base concentrates around captive design-test-certification pipelines and classified program execution capabilities. Three archetypes dominate: defense-focused classified specialists, commercial airframe integrators, and emerging national champions with state backing. Competitive moves center on strategic partnerships for electrified propulsion architectures and geographic expansion into urban air mobility hubs.
Among defense-focused classified specialists, Northrop Grumman and Lockheed Martin occupy positions sustained by Pentagon demand for survivable aerodynamic platforms. Boeing exemplifies the vertically integrated commercial prime archetype, anchoring high-volume narrowbody and widebody development through captive structural analysis capacity. COMAC represents the emerging national champion model, with state-directed investment enabling production ramp-up that reshapes competitive dynamics in commercial airframe engineering.
| Leading Market Players |
|---|
| Northrop Grumman |
| General Dynamics |
| Boeing |
| Embraer |
| Dassault Aviation |
| Airbus |
| BAE Systems |
| COMAC |
| Lockheed Martin |
| Others |
Supply & Pricing Matrix
Russian and Chinese dominance in titanium sponge production concentrates upstream supply for structural airframe components, anchoring margin pools in detailed design and system integration services where certification complexity creates pricing power. Defense contractors absorb input cost volatility through multi-year contracts with embedded technology refresh clauses, while commercial primes face compressed margins on electric propulsion programs.
Pricing Analysis
United States-based engineering services command 40-60% premiums over Chinese and Indian competitors due to FAA certification credibility and proximity to Seattle and Wichita aerospace clusters. Pricing stratifies across defense-classified, commercial-transport, and emerging-air-mobility tiers, with certification grade and intellectual property intensity as primary differentiation drivers. Cost compression in commercial-transport engineering intensifies as COMAC's production ramp-up introduces state-subsidized competition. Low-cost carriers operating narrowbody fleets exhibit highest price sensitivity, while Pentagon procurement teams prioritize technical performance over unit cost.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities have become standard for Tier 2 and Tier 3 aerostructures suppliers, with primes leveraging balance-sheet strength to capture working-capital advantages. Manufacturing concentration spans the United States, Germany, and China, with composite preform production drawing from Japanese carbon fiber and European resin systems. Titanium sponge, rare-earth magnets for electric motors, and advanced avionics semiconductors represent critical input dependencies. Single-source vulnerability in high-strength alloy supply creates exposure to geopolitical disruption. Distribution runs through vertically integrated prime contractor design-test-certification pipelines rather than open vendor markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Aircraft design and engineering operates as a regulatory-moat business where FAA, EASA, and CAAC certification entrenchment creates switching costs that protect incumbent positions across multi-year development cycles.
For Market Incumbents: Pre-empt emerging national champions by accelerating electrified propulsion certification investments before EASA streamlines autonomous flight pathways. Lock in exclusive system integration partnerships with urban air mobility infrastructure developers in the United Arab Emirates. Capture battery management and motor control IP through targeted technology licensing to counter IP fragmentation across Tier N suppliers.
For New Entrants and Emerging Players: Pursue white-space opportunities in urban air mobility ground infrastructure engineering where regulatory frameworks remain unsettled and incumbent presence is thin. Target continued airworthiness management contracts with Southeast Asian low-cost carriers consolidating vendor relationships around full-lifecycle partners. Establish credibility through EASA condition-specific airworthiness criteria specialization for reduced-crew operations.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed aerostructures specialists holding captive positions in Boeing and Airbus supply chains but lacking electrified platform capabilities. Long-term viability hinges on 5-10 year regulatory alignment between FAA and EASA on electric aircraft certification. Watch for talent migration signals toward whichever geography achieves streamlined electric propulsion validation first.
| Strategic Initiative | Industry Significance |
|---|---|
| Digital Twin Convergence | Fusion of CFD with real-time sensor feedback enables predictive maintenance contracts capturing aftermarket value from airline operators. |
| EU Green Deal Alignment | Sustainable aviation fuel mandates redirect R&D budgets toward lifecycle-optimized airframe designs meeting carbon border adjustments. |
| Vertiport Infrastructure Partnership | Integrated vehicle-ground system engineering in Dubai and Abu Dhabi attracts sovereign wealth deployment accelerating test facility construction. |
| Autonomous Flight Certification | EASA condition-specific airworthiness criteria force redesign of cockpit HMI for reduced-crew operations anchoring German-French capability. |
| Composite Laminate Optimization | Automated fiber placement and out-of-autoclave curing reduce weight fractions while maintaining damage tolerance thresholds for defense platforms. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with aircraft program managers, certification engineering directors, Tier 1 supplier procurement leads, and airline technical fleet planners; and secondary validation against FAA type certificate databases, EASA airworthiness directives, customs trade flows for titanium and carbon fiber, and SEC filings from publicly traded primes. Bottom-up project pipeline enumeration was cross-checked against top-down market sizing from defense procurement disclosures and commercial aircraft delivery forecasts.
Forecast inputs span design type, engineering discipline, end-user application, and service offering dimensions across the projection horizon. CAGRs were derived from regression analysis of historical program cycle times, certification timeline compression rates, and electrified platform adoption curves. Modeled variables include Pentagon R&D budget trajectories, EASA autonomous flight rulemaking velocity, and COMAC production ramp-up schedules.
Sensitivities concentrate around regulatory timeline divergence between FAA and EASA, titanium supply disruption scenarios, and electric aircraft certification pathway acceleration. Forecasts reflect documented assumptions about continued defense procurement growth and commercial aviation recovery patterns. Macroeconomic contraction, geopolitical trade restriction expansion, or breakthrough battery energy density improvement would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft
Aircraft Sequencing System Market
Aircraft
Global Helicopter Market
Aircraft
Utility Aircraft Market
Aircraft
Europe Light and Very Light Jets Market
Aircraft
General Aviation Market
Aircraft
Europe Fighter Aircraft Market
Aircraft
Japan Aviation Market
Aircraft
Military Helicopters Market
Aircraft
Middle-East and Africa Business Jet Market
Aircraft
Asia-Pacific Heavy-Lift Helicopter Market
Aircraft
Ultra-Light Aircraft Market
Aircraft
Global Aircraft Electric Brake Control System Market
Aircraft
Global LW Sport Aircraft Market
Aircraft
Military Rotorcraft Market
Aircraft
Aircraft Ailerons Market
Aircraft
GCC General Aviation Market