
 Vehicle Mounted Anti-Tank Missile System Market | 2026-2036
Vehicle Mounted Anti-Tank Missile System Market Size, Share, and Industry Trends Forecast 2026-2036
Vehicle Mounted Anti-Tank Missile System Market Analysis
Multi-source component sourcing is pivoting toward captive production of seeker arrays and propulsion systems among prime contractors. Raytheon Company leverages in-house electro-optical manufacturing to reduce dependency on foreign sensor suppliers. Lockheed Martin Corporation sustains vertical integration through controlled production of laser designation modules. Rafael Advanced Defense Systems anchors its competitive stance with specialized thermal imaging expertise developed for desert and urban combat environments.
A vehicle mounted anti-tank missile system integrates a tube-launched precision munition with a stabilized launch platform, typically housing missiles with tandem warheads capable of defeating explosive reactive armor at ranges exceeding four kilometers. The primary purpose is to provide mechanized units with standoff engagement capability against main battle tanks and fortified positions without exposing crews to direct fire. Fire-and-forget technology leads product type demand as forces prioritize shoot-and-scoot survivability over manual guidance. Military forces dominate end user procurement, though defense contractors absorb growing share through government-funded development programs. Electro-optical guidance occupies the largest technology margin pool due to component complexity and ITAR-controlled export restrictions.
The US State Department's Directorate of Defense Trade Controls shapes market access through International Traffic in Arms Regulations, while NATO's STANAG 4579 establishes interoperability standards for vehicle-integrated missile electronics. The EU Green Deal's defense industrial provisions, channeled through the European Defence Fund, redirect procurement toward European-sourced propulsion and guidance systems. Stakeholders must monitor evolving ITAR exemption negotiations and the European Commission's proposed ammunition production acceleration framework to anticipate supply chain reconfiguration and qualification pathway changes.
Market Dynamics
Fire-and-forget guidance architectures are compressing development cycles and forcing legacy command-line-of-sight suppliers into rapid capability reinvestment or exit. This technological displacement concentrates procurement leverage among prime contractors with captive electro-optical manufacturing.
Growth Catalysts
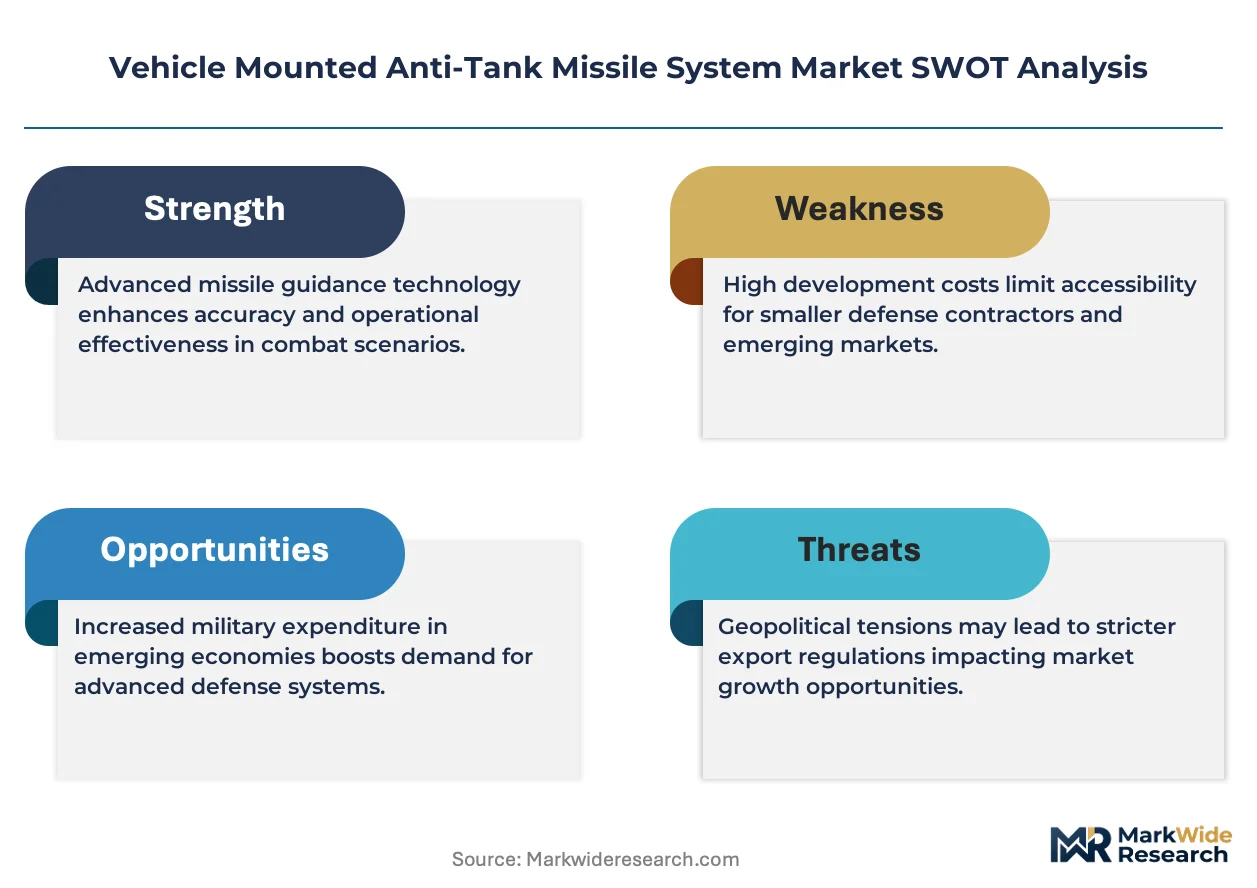
- STANAG 4579 Interoperability Mandate:NATO standardization for vehicle-integrated missile electronics creates cross-border procurement pools and reduces qualification costs for compliant systems across Poland, Turkey, and Baltic states.
- Explosive Reactive Armor Proliferation:Main battle tank upgrades with tandem-charge defeat mechanisms drive demand for missiles with dual-warhead configurations and extended standoff ranges exceeding four kilometers.
- Mechanized Infantry Modernization:United States Army programs to replace Bradley Fighting Vehicle platforms accelerate vehicle-mounted precision strike integration timelines and volume commitments.
Market Restraints
- ITAR-Controlled Component Access:United States State Department export licensing creates 12-18 month procurement delays for electro-optical seekers and laser designation modules, constraining non-NATO ally acquisition pathways.
- Seeker Array Supply Concentration:German and Israeli thermal imaging foundries control 70% of qualified uncooled infrared detector supply for fire-and-forget systems, creating single-source vulnerability.
- Tungsten Heavy Alloy Price Volatility:Penetrator warhead material costs fluctuate with Chinese rare earth processing quotas, squeezing margin structures on fixed-price development contracts.
Strategic Opportunities
- Ukraine Defense Industrial Base Reconstruction:Post-conflict vehicle-mounted system co-production agreements offer qualified NATO suppliers localized assembly footholds and reduced ITAR friction for Eastern European sales.
- European Defence Fund Ammunition Acceleration:EU Green Deal defense industrial provisions redirect procurement toward European-sourced propulsion and guidance systems, creating preference margins for qualified continental suppliers.
- Urban Combat Target Recognition:Machine learning-enabled thermal signature discrimination for cluttered environments opens differentiation space against legacy electro-optical systems optimized for open terrain engagement.
Industry Challenges
- Guidance Algorithm Talent Scarcity:Fire-and-forget seeker software development requires specialized expertise in real-time target tracking and countermeasure rejection, with limited qualified personnel pools in defense sectors.
- Legacy Platform Integration Complexity:Retrofitting stabilized launch platforms onto existing mechanized vehicle architectures demands structural modification and power system upgrades that extend fielding timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vehicle Mounted Anti-Tank Missile System Market |
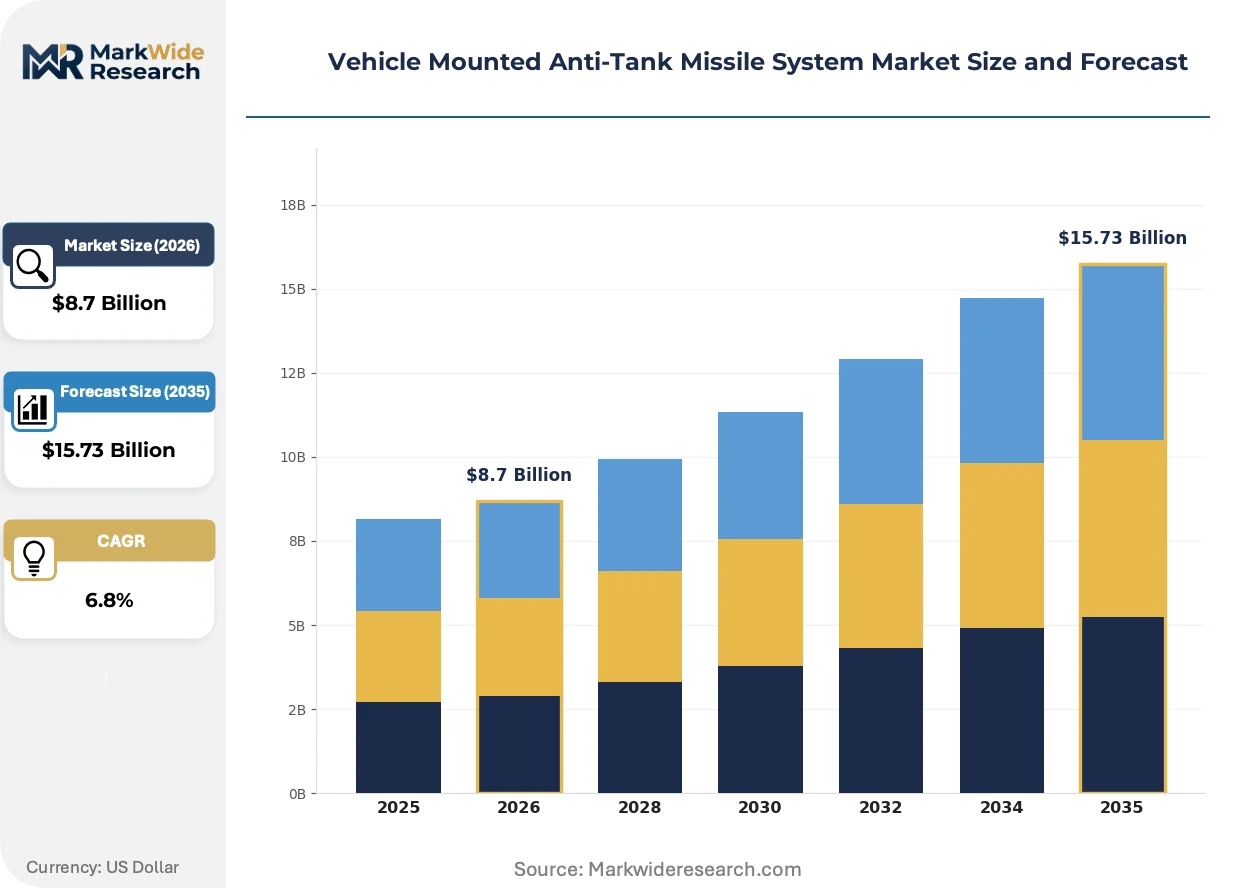
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Guided Missiles, Fire-and-Forget, Semi-Active Homing, Top Attack End User: Military Forces, Defense Contractors, Government Agencies, Security Organizations Deployment: On-Ground, Mobile Platforms, Fixed Installations, Coastal Defense Technology: Electro-Optical, Radar Guidance, Thermal Imaging, Laser Designation |
| Companies Covered | Raytheon Company, Lockheed Martin Corporation, General Dynamics Corporation, MBDA, Rafael Advanced Defense Systems, Elbit Systems Ltd, SAAB AB, Thales Group, BAE Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vehicle Mounted Anti-Tank Missile System Market Emerging Trajectories
Active seeker technology and artificial intelligence-enabled target recognition are compressing engagement timelines while regulatory frameworks reconfigure supplier qualification pathways across NATO and partner nations.
Imaging infrared seekers with on-board processing for automatic target detection and tracking are expanding into mechanized infantry platforms previously limited to laser-guided or wire-command systems. Polish and Turkish land forces are accelerating adoption of fire-and-forget configurations for shoot-and-scoot survivability. This capability expansion is compressing manual guidance system market share and forcing legacy suppliers toward seeker technology partnerships or exit.
EU Green Deal defense industrial provisions channeled through the European Defence Fund are redirecting vehicle-mounted missile procurement toward European-sourced propulsion and guidance components. The framework mandates supply chain documentation and sustainability criteria that disqualify certain non-European subsystems from funded programs. Prime contractors with continental manufacturing footprints are capturing preference margins in German, French, and Italian modernization competitions.
Bundled system procurement combining vehicle platforms, missiles, and training packages is displacing discrete component purchasing across NATO mechanized forces. Defense ministries in the United States and Poland are consolidating vendor relationships to reduce integration risk and accelerate fielding timelines. This concentration pattern is most visible in multi-year indefinite delivery contracts that lock in prime contractor positions across platform lifecycles.
Vehicle Mounted Anti-Tank Missile System Market Segmentation
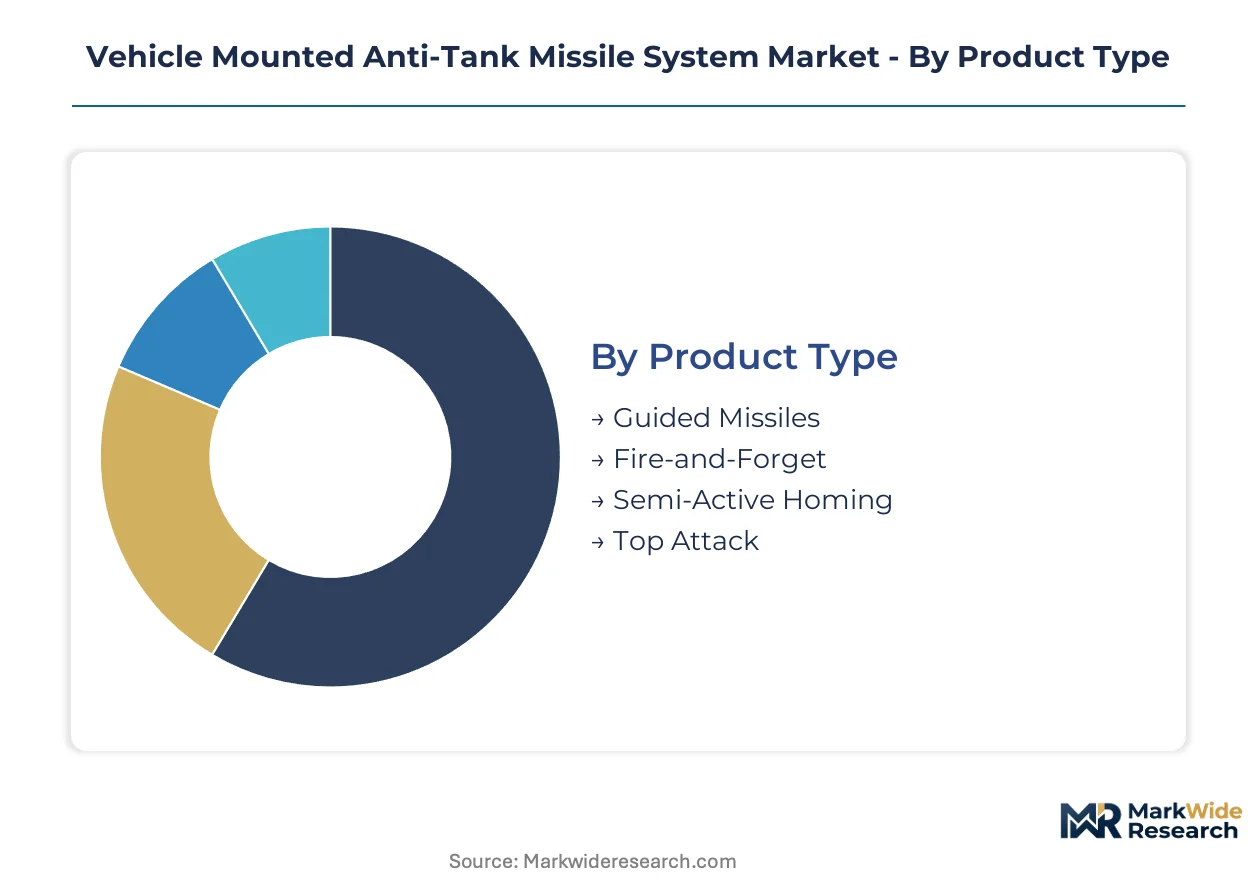
Platform modernization cycles and guidance technology transitions reshape procurement patterns across vehicle-mounted precision strike systems. Segment boundaries reflect divergent upgrade priorities between mechanized forces pursuing fire-and-forget capability and legacy operators extending command-line-of-sight inventories.
Product Type:
Replacement timelines for aging tube-launched systems concentrate demand around guidance architectures that reduce crew exposure time.
- Fire-and-Forget:Imaging infrared seekers with on-board automatic target detection eliminate operator guidance after launch. Polish and Turkish mechanized units prioritize these configurations for shoot-and-scoot survivability against counter-battery fire.
- Guided Missiles:Wire-command and laser-designated architectures persist in budget-constrained modernization programs where platform integration costs dominate acquisition decisions. These systems retain relevance in forces prioritizing ammunition commonality over seeker sophistication.
- Semi-Active Homing:External laser illumination requirements limit deployment flexibility but reduce unit cost for forces with established designator networks.
- Top Attack:Trajectory profiles optimized for roof-armor penetration address main battle tank upgrades with enhanced frontal protection packages.
Fire-and-forget sits at the top of the volume ranking, with top attack climbing the fastest as reactive armor proliferation drives seeker trajectory diversification.
End User:
Funding authority and fielding timeline urgency separate procurement behavior across institutional buyer categories.
- Military Forces:Mechanized infantry and cavalry units drive platform-integrated system acquisition through multi-year modernization appropriations. United States Army Bradley replacement programs anchor volume commitments with bundled vehicle-missile procurement.
- Defense Contractors:Government-funded development programs absorb engineering services and low-rate initial production for next-generation seeker technologies. These engagements concentrate in electro-optical subsystem qualification and algorithm development.
- Government Agencies:Border security and coastal defense organizations procure simplified configurations with reduced electronic counter-countermeasure suites.
- Security Organizations:Paramilitary and internal security forces acquire limited quantities for specialized anti-vehicle roles outside conventional warfare scenarios.
Military forces command the dominant procurement share, while defense contractors expand fastest through development program absorption.
Deployment:
Mobility requirements and engagement geometry dictate platform selection across contested operational environments.
- Mobile Platforms:Stabilized launch systems integrated onto armored fighting vehicles provide mechanized units with on-the-move engagement capability. These configurations demand structural modification and power system upgrades that extend fielding timelines.
- On-Ground:Tripod-mounted and vehicle-dismounted systems retain relevance for light infantry formations and rapid deployment scenarios where platform weight constraints prohibit permanent integration.
- Fixed Installations:Defensive emplacements protecting critical infrastructure employ hardened launch positions with pre-registered firing sectors.
- Coastal Defense:Maritime adaptations address fast attack craft and amphibious landing craft threats through modified seeker algorithms for sea-surface clutter rejection.
Mobile platforms generate the highest unit volumes, with on-ground configurations gaining share fastest among expeditionary force structures.
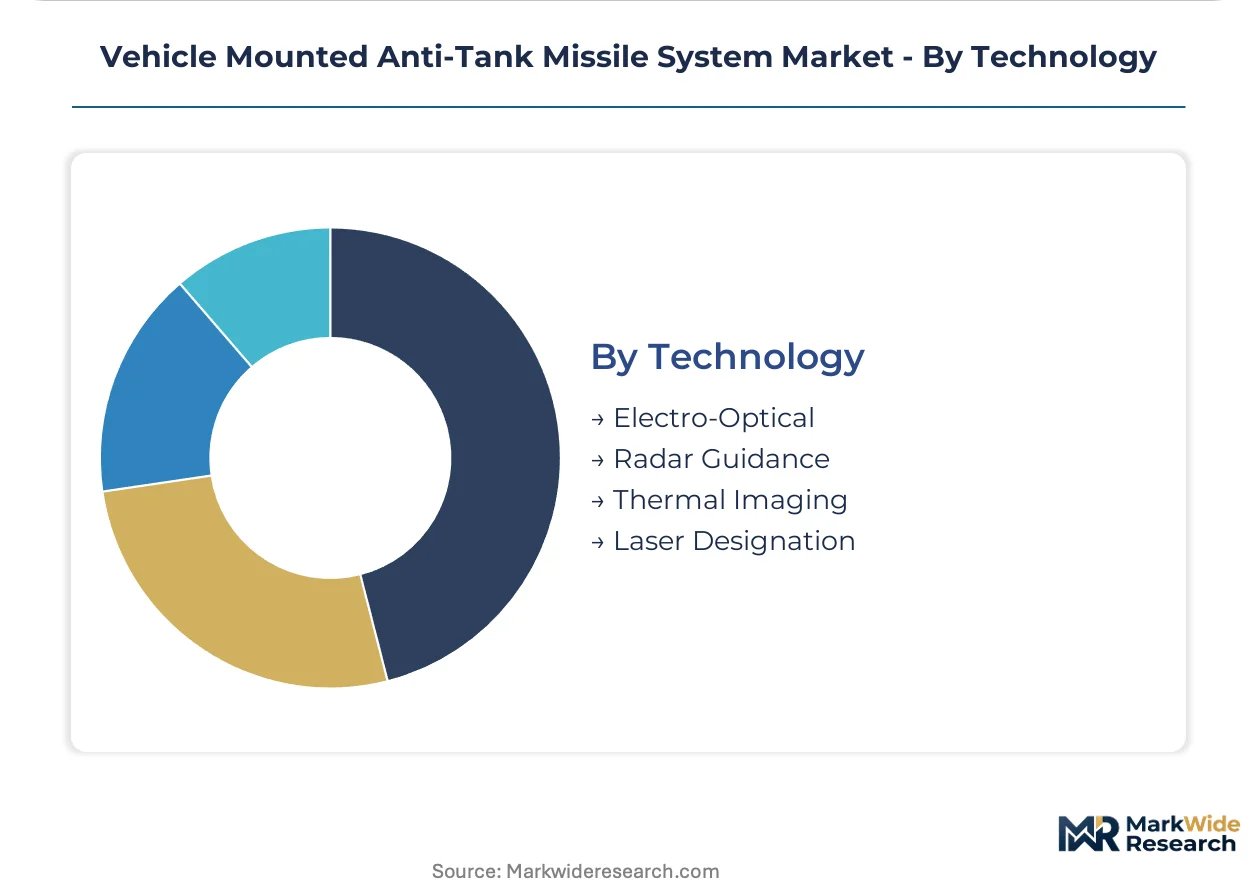
Technology:
Component complexity and export control classification create margin stratification across guidance architectures.
- Electro-Optical:Charge-coupled device and complementary metal-oxide semiconductor imagers with digital signal processing dominate fire-and-forget system architectures. ITAR-controlled export restrictions concentrate qualified supplier pools among captive prime contractor manufacturing.
- Thermal Imaging:Uncooled infrared detector arrays enable passive target acquisition in degraded visibility conditions. German and Israeli foundries control qualified supply for NATO-compliant systems.
- Laser Designation:Semi-active homing dependence on external illumination limits operational flexibility but reduces seeker unit cost.
- Radar Guidance:Millimeter-wave seekers penetrate obscurants and electronic countermeasures but impose power and aperture constraints on compact missile designs.
Electro-optical technology leads absolute volume, with thermal imaging expanding most quickly as uncooled detector costs decline.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Tucson, Arizona anchors precision strike manufacturing through Raytheon's electro-optical foundry, while mechanized modernization programs across NATO member states concentrate demand in specific national procurement pipelines.
United States
Army Bradley Fighting Vehicle replacement programs drive bundled vehicle-missile procurement through multi-year indefinite delivery contracts. The State Department's ITAR licensing framework creates 12-18 month approval timelines for electro-optical seeker exports. Tucson, Arizona and Dallas-Fort Worth, Texas host concentrated electro-optical manufacturing for fire-and-forget seeker arrays.
Poland
Mechanized infantry modernization prioritizes shoot-and-scoot survivability against counter-battery threats along eastern flank deployments. NATO's STANAG 4579 interoperability mandate reduces qualification costs for vehicle-integrated missile electronics. Warsaw and Poznań defense industrial clusters absorb co-production agreements for localized assembly footholds.
Turkey
Land forces accelerate fire-and-forget adoption for mechanized platforms operating in contested border regions. National procurement frameworks emphasize indigenous propulsion and guidance system development. Ankara's defense technology corridor hosts specialized thermal imaging expertise adapted for desert and urban combat environments.
Germany
Rheinmetall and MBDA integration partnerships address Leopard platform precision strike upgrades with extended standoff requirements. EU Green Deal defense industrial provisions redirect ammunition procurement toward European-sourced subsystems. Bavaria and Baden-Württemberg thermal imaging foundries control qualified uncooled infrared detector supply for NATO-compliant systems.
Israel
Rafael and Elbit anchor competitive positioning through captive electro-optical manufacturing and specialized desert warfare seeker algorithms. Ministry of Defense funding sustains vertical integration in laser designation module production. Haifa and Beersheba defense clusters develop machine learning-enabled target recognition for cluttered urban environments.
Vehicle Mounted Anti-Tank Missile System Market Vendor Landscape
Global majors compete with regional champions across guidance technology architectures and platform integration capabilities. The supplier base concentrates among prime contractors with captive electro-optical manufacturing and ITAR-compliant export licensing. Three archetypes dominate: vertically integrated system houses controlling seeker-to-launcher production, specialized seeker technology developers licensing subsystems, and platform integrators bundling vehicle-missile packages. Competitive moves center on backward integration into thermal imaging foundries and strategic partnerships for STANAG 4579 qualification pathways.
Among US-based system houses, Raytheon Company and Lockheed Martin Corporation exemplify the vertically integrated archetype through in-house electro-optical and laser designation manufacturing. Rafael Advanced Defense Systems occupies a specialist position within Israeli defense clusters, while MBDA represents European consortium structures spanning French, German, and Italian industrial participation.
| Leading Market Players |
|---|
| Raytheon Company |
| Lockheed Martin Corporation |
| General Dynamics Corporation |
| MBDA |
| Rafael Advanced Defense Systems |
| Elbit Systems Ltd |
| SAAB AB |
| Thales Group |
| BAE Systems |
| Others |
Supply Flow & Price Mechanics
EU Green Deal defense industrial provisions gate qualified supply and premium-tier pricing access for vehicle-mounted anti-tank missile systems, channeling procurement toward European-sourced propulsion and guidance components while imposing sustainability documentation requirements that disqualify non-compliant subsystems from funded programs. This regulatory filtration concentrates pricing power among prime contractors with continental manufacturing footprints and captive electro-optical production.
Pricing Analysis
Input-cost pass-through from tungsten heavy alloy penetrator materials and uncooled infrared detector arrays shapes contract structures across fixed-price development agreements. Three-tier pricing structure across ITAR-restricted, NATO-compliant, and export-limited configurations separates prime contractor bundled systems from subsystem licensing arrangements. Cost compression in seeker array procurement is intensifying because German and Israeli foundry supply concentration limits qualified alternatives. Government procurement offices exhibit highest price sensitivity through multi-year indefinite delivery negotiations, while defense contractors absorb engineering premiums for algorithm development programs.
Supply Chain Analysis
Specialized freight and customs handling for ITAR-controlled electro-optical components extends logistics timelines and inflates landed costs for cross-border subsystem transfers. Manufacturing concentrates in the United States, Germany, and Israel for qualified seeker arrays, laser designation modules, and thermal imaging detectors. Production draws from Chinese-processed rare earth elements for tungsten heavy alloy warheads, German uncooled infrared foundries for fire-and-forget seekers, and Israeli thermal imaging expertise for desert-optimized systems. Single-source vulnerability in uncooled detector supply creates structural risk for NATO-compliant system qualification. Distribution runs through prime contractor captive channels and government-facilitated foreign military sales pathways.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as mechanized forces prioritize fire-and-forget shoot-and-scoot survivability over legacy command-line-of-sight architectures, compressing procurement toward premium guidance specifications with embedded automatic target recognition.
For Market Incumbents: Acquire thermal imaging foundry capacity to secure qualified uncooled infrared detector supply against German and Israeli supply concentration. Backward integration into laser designation module production reduces ITAR licensing friction for export configurations. Capacity addition in Poland and Turkey through co-production agreements defends market position against indigenous development programs in NATO eastern flank states. For New Entrants and Emerging Players: STANAG 4579 interoperability mandates in NATO member states open a window for subsystem qualification partnerships with established prime contractors. White-space targets concentrate in machine learning-enabled target recognition for cluttered urban environments and reduced electronic counter-countermeasure suites for border security agencies. Go-to-market positioning through European Defence Fund ammunition acceleration pathways captures preference margins in continental procurement competitions. For Investors and Strategic Acquirers: Roll-up economics work for specialized seeker technology developers because fire-and-forget algorithm talent scarcity limits organic capability replication. Long-term viability centers on five-to-ten year platform modernization cycles with bundled vehicle-missile procurement consolidation. Acquisition targets should demonstrate STANAG 4579 qualification progress and captive electro-optical manufacturing. Watch for ITAR exemption negotiation outcomes as inflection indicators for Eastern European market access expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Thermal Imaging Foundries | Secures uncooled infrared detector supply against German-Israeli concentration for NATO-compliant fire-and-forget systems. |
| STANAG 4579 Qualification Partnership | Unlocks cross-border procurement pools across Poland, Turkey, and Baltic states through standardized vehicle-integrated electronics. |
| Machine Learning Target Recognition Development | Differentiates electro-optical seekers for cluttered urban environments against legacy open-terrain optimized architectures. |
| European Defence Fund Ammunition Acceleration Alignment | Captures preference margins in German, French, and Italian modernization through EU-sourced propulsion and guidance compliance. |
| Ukraine Defense Industrial Base Co-Production | Establishes localized assembly footholds with reduced ITAR friction for post-conflict Eastern European vehicle-mounted system sales. |
Methodological Framework
Coverage spans the United States, Poland, Turkey, Germany, and Israel, with primary inputs from each market through structured interviews with program executive officers at mechanized infantry modernization commands, electro-optical subsystem procurement leads at prime contractors, thermal imaging foundry operations directors, and defense ministry acquisition specialists. Secondary validation draws from NATO STANAG documentation, US State Department ITAR licensing records, European Defence Fund program announcements, and customs trade data for tungsten heavy alloy and rare earth element flows. Bottom-up platform procurement forecasts triangulate against top-down defense budget appropriation analysis.
Granularity-level modeling disaggregates volume and value across fire-and-forget, guided missile, semi-active homing, and top attack product types; military forces, defense contractors, government agencies, and security organizations end users; mobile platform, on-ground, fixed installation, and coastal defense deployments; and electro-optical, thermal imaging, laser designation, and radar guidance technologies. CAGRs derive from fitted growth curves against historical procurement patterns and announced modernization program timelines. Industry-specific inputs include Bradley Fighting Vehicle replacement schedule acceleration and Leopard platform precision strike upgrade commitments.
Revisions become necessary when ITAR exemption negotiations materially alter Eastern European export pathways, when tungsten heavy alloy price volatility disrupts fixed-price contract structures, or when STANAG 4579 interoperability mandates expand to additional NATO member states. Forecasts reflect documented assumptions about mechanized infantry modernization urgency and fire-and-forget technology displacement timelines. Stakeholders should weight assumptions against their own operating context and program risk tolerance.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Weapons and Ammunition
Global Ammunition Market
Weapons and Ammunition
Smart Bombs Market
Weapons and Ammunition
Military Fire Control Systems Market
Weapons and Ammunition
Surface to Air Missiles Market
Weapons and Ammunition
Turret System Market
Weapons and Ammunition
Weapons and Ammunition Market
Weapons and Ammunition
North Korea Nuclear Bombs and Missiles Market
Weapons and Ammunition
Light Weapons Market
Weapons and Ammunition
Particle Beam Directed Energy Weapon Market
Weapons and Ammunition
Manned Anti-Tank Guided Missile System Market
Weapons and Ammunition
Asia-Pacific Ammunition Market
Weapons and Ammunition
NATO Ammunition Market
Weapons and Ammunition
Ammunition Storage Market
Weapons and Ammunition
Weapon Mounts Market
Weapons and Ammunition
Military Airborne Laser Market
Weapons and Ammunition
Global Rockets and Missiles Market