
 Aircraft Galley Equipment Market | 2026-2036
Aircraft Galley Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Aircraft Galley Equipment Market Analysis
The aircraft galley equipment sector is recalibrating around a widening gap between premium long-haul configurations and commodity short-haul specifications. Safran SA leverages its integrated cabin systems portfolio to dominate high-complexity galley architectures for twin-aisle platforms. Diehl Stiftung & Co. KG anchors European supply through its specialization in lightweight refrigeration units certified under EASA CS-25 standards.
Aircraft galley equipment encompasses the modular food preparation, storage, and beverage service systems installed within commercial and business aircraft cabins, typically constructed from aerospace-grade aluminum alloys or carbon-fiber-reinforced composites to meet strict flammability and smoke-toxicity requirements under FAR 25.853. The equipment serves the essential function of enabling in-flight meal service while minimizing weight penalty and maximizing volumetric efficiency in constrained cabin envelopes. Ovens and refrigerators capture the largest share of product-type value, driven by mandatory hot-meal capability on routes exceeding five hours. Composite materials represent the fastest-growing material segment as airlines pursue fuel-burn reductions through gram-level weight savings in cabin interiors.
FAA airworthiness directives and EASA certification specifications govern flammability, electrical safety, and crashworthiness of galley installations, creating compliance barriers that favor established suppliers with sustained type-certificate relationships. The EU Green Deal's evolving cabin sustainability requirements and emerging EPA guidance on aircraft interior material recycling are reshaping supplier R&D priorities toward circular design principles. Stakeholders must monitor how impending changes to CS-25 galley load-attainment criteria will alter competitive positioning between integrated system providers and component specialists.
Market Dynamics
The aircraft galley equipment sector is recalibrating around FAA and EASA weight-reduction mandates that compel airlines to strip kilograms from cabin interiors. Composite material substitution is absorbing engineering resources as gram-level savings translate directly into fuel-burn reductions over aircraft lifecycles.
Growth Catalysts
- Narrow-body fleet expansion:Low-cost carriers in Southeast Asia and Latin America are retrofitting galleys to support buy-on-board meal programs, driving linefit and retrofit demand simultaneously.
- EASA CS-25 Amendment 25:Updated galley load-attainment criteria are forcing redesign cycles that favor suppliers with established type-certificate relationships, consolidating procurement toward certified incumbents.
- Carbon-fiber-reinforced thermoplastics:These materials now penetrate oven housings and trolley structures, enabling 15-20% weight reductions against aluminum benchmarks while meeting FAR 25.853 flammability thresholds.
Market Restraints
- Aerospace-grade resin supply concentration:Prepreg manufacturing for composite galley components clusters in Japan and Germany, exposing buyers to geopolitical logistics disruptions and extended lead times.
- Certification cost escalation:FAA airworthiness directives governing electrical safety and crashworthiness require sustained engineering investment that excludes emerging suppliers without type-certificate histories.
- Refrigerant phase-down constraints:The EU F-Gas Regulation restricts high-GWP coolants in galley refrigeration units, forcing costly redesign of thermal management systems for European-registered aircraft.
Strategic Opportunities
- India domestic aviation surge:IndiGo and Air India narrow-body order backlogs exceed 1,000 aircraft, creating concentrated demand for lightweight galley configurations optimized for 90-minute sector economics.
- Circular design principles:The EU Green Deal's evolving cabin sustainability requirements reward suppliers developing modular, disassemblable trolley systems with documented end-of-life material recovery pathways.
- Electrification-thermal convergence:Integration of induction heating and solid-state refrigeration eliminates traditional oven-refrigerator thermal segregation, enabling volumetric efficiency gains in constrained single-aisle envelopes.
Industry Challenges
- Composite repair technician scarcity:Airlines and MRO providers lack personnel certified to repair carbon-fiber galley components to OEM structural integrity standards, extending AOG durations.
- Legacy 28VDC power architecture incompatibility:Next-generation galley equipment designed for 270VDC more-electric aircraft faces retrofit complexity on older Boeing 737NG and Airbus A320ceo fleets.
- IP fragmentation across trolley interface standards:Proprietary rail and latch mechanisms lock airlines into single-supplier ecosystems, complicating multi-source procurement strategies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aircraft Galley Equipment Market |
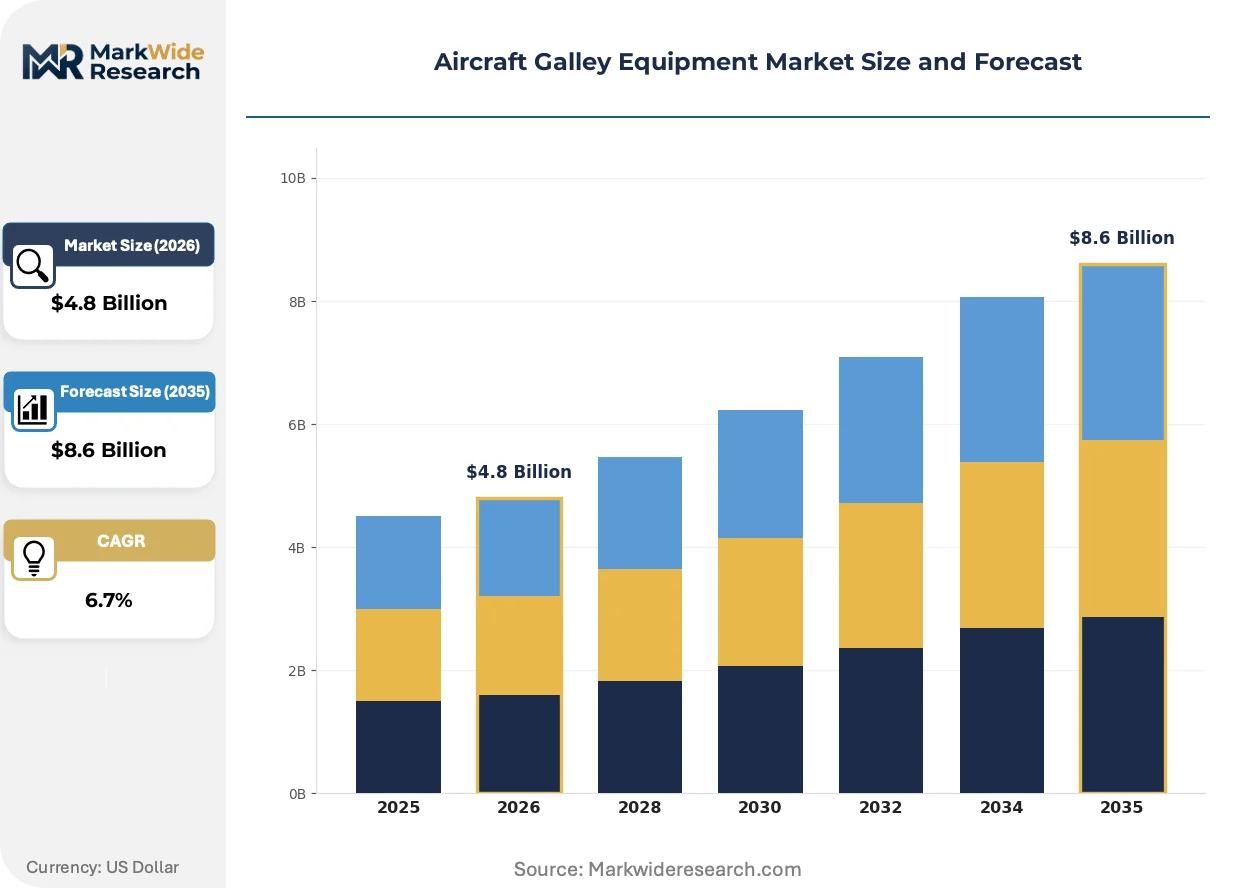
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ovens, Coffee Makers, Refrigerators, Drink Dispensers End User: Commercial Airlines, Charter Services, Cargo Airlines, Business Jets Material: Aluminum, Stainless Steel, Plastic, Composite Materials Installation Type: Linefit, Retrofit, Modular, Custom Installations |
| Companies Covered | Safran SA, Collins Aerospace, JAMCO Corporation, Diehl Stiftung & Co. KG, Bucher Leichtbau AG, AVIC Cabin Systems Limited, AIM Altitude, EFW GmbH, Aerolux, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aircraft Galley Equipment Market Emerging Trajectories
Galley engineering is converging on electrification and modularity as airlines prioritize fuel efficiency and cabin reconfigurability. Three developments are compressing traditional equipment categories and reshaping supplier competitive boundaries.
Thermoplastic composite oven housings are absorbing development investment from major galley suppliers. These structures replace aluminum assemblies in premium long-haul configurations where weight reduction justifies unit cost premiums. Full-service carriers operating Boeing 787 and Airbus A350 fleets are specifying thermoplastic ovens for new deliveries, compressing the addressable market for legacy metal fabricators.
The EU Green Deal's cabin sustainability requirements are mandating material transparency and end-of-life accountability for galley equipment installed in European-registered aircraft. Suppliers must now document recycled content percentages and establish take-back programs for trolleys and containers. Narrow-body operators with high aircraft rotation rates between EU and non-EU registries face compliance complexity that favors integrated system providers with established circular logistics infrastructure.
Airline procurement departments are consolidating galley specification authority at fleet-planning level rather than deferring to individual route managers. This centralization compresses supplier negotiation cycles and privileges long-term framework agreements with integrated cabin system providers. The shift is most visible at US network carriers where procurement teams now bundle galley, seat, and lavatory awards to maximize volume leverage and simplify linefit coordination with airframers.
Aircraft Galley Equipment Market Segmentation
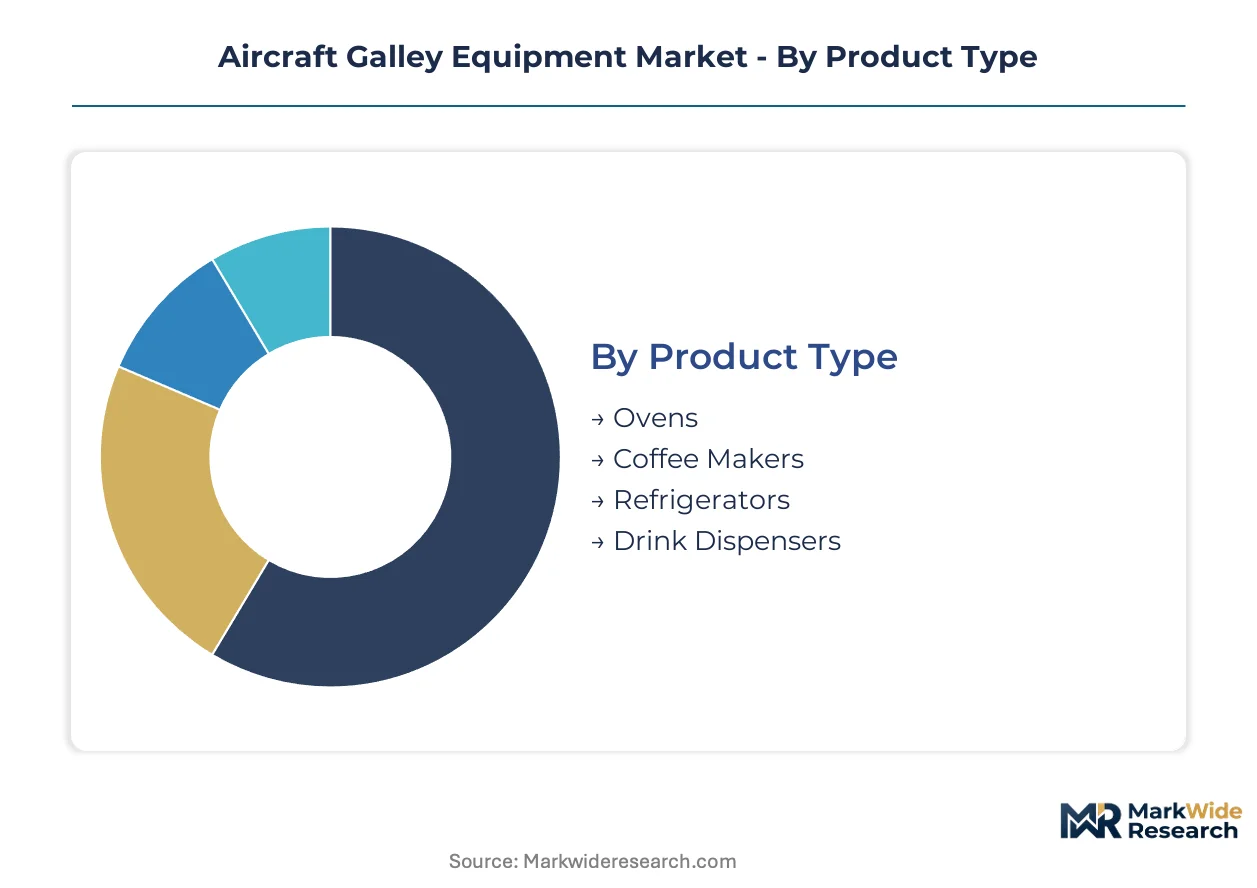
Galley equipment procurement fragments across four distinct taxonomies that reshape supplier competitive boundaries. Product type determines engineering resource allocation, while material selection governs compliance with FAA and EASA weight-reduction mandates. Installation type and end-user category further stratify pricing power and contract duration across the value chain.
Product Type:
Supply concentration in oven and refrigerator manufacturing dominates procurement negotiations, with tier-one suppliers capturing long-term fleet contracts through integrated thermal system architectures.
- Ovens:Forced-air and convection configurations built from aerospace-grade aluminum or thermoplastic composite housings serve hot-meal service requirements on routes exceeding five hours. Full-service carriers operating Boeing 787 and Airbus A350 platforms specify these units for new deliveries, compressing addressable market access for legacy metal fabricators.
- Refrigerators:Lightweight vapor-compression and emerging solid-state thermal management units certified under EASA CS-25 standards anchor European supply chains. Diehl Stiftung's specialization in this segment reflects certification barriers that favor incumbents with sustained type-certificate relationships.
- Coffee Makers:Compact 28VDC and 270VDC electrical brewing systems integrate into narrow-body galley envelopes for buy-on-board programs.
- Drink Dispensers:Chilled beverage units with modular cartridge interfaces support rapid reconfiguration between short-haul and medium-haul service profiles.
Ovens absorb the bulk of installed capacity; refrigerators are expanding most quickly as composite material substitution accelerates.
End User:
Cost tier differentiation separates premium long-haul specifications from commodity short-haul configurations, with procurement authority consolidating at fleet-planning level rather than route-manager discretion.
- Commercial Airlines:Network carriers and low-cost operators drive linefit demand through Boeing and Airbus delivery backlogs, while retrofit programs modernize legacy narrow-body fleets for buy-on-board economics. US network carriers now bundle galley awards with seat and lavatory contracts to maximize volume leverage.
- Business Jets:Ultra-long-range platforms including Gulfstream G700 and Bombardier Global 7500 demand compact, multi-function galley modules with premium finish specifications. Completion centers in Wichita and Savannah concentrate customization demand for VIP cabin configurations.
- Charter Services:Flexible galley specifications accommodate rapid aircraft rotation between executive and tour-operator roles.
- Cargo Airlines:Minimal galley requirements on freighter conversions limit addressable market scope to pilot meal service units.
Commercial airlines absorb the bulk of installed capacity; business jets are climbing the fastest as ultra-long-range deliveries accelerate.
Material:
Volume distribution across material categories reflects gram-level weight savings translating directly into fuel-burn reductions over aircraft lifecycles.
- Composite Materials:Carbon-fiber-reinforced thermoplastics now penetrate oven housings and trolley structures, enabling substantial weight reduction against aluminum benchmarks while meeting FAR 25.853 flammability thresholds. Full-service carriers specify these for premium twin-aisle deliveries.
- Aluminum:Aerospace-grade alloys remain dominant in retrofit markets and cost-sensitive narrow-body programs where unit economics resist composite premiums.
- Stainless Steel:Corrosion-resistant grades persist in high-cycle trolley and container applications requiring impact durability.
- Plastic:Injection-molded thermoplastics serve non-structural trim and latch components with lower certification burden.
Aluminum retains the bulk of installed capacity; composite materials are gaining share fastest as EASA and FAA mandates harden.
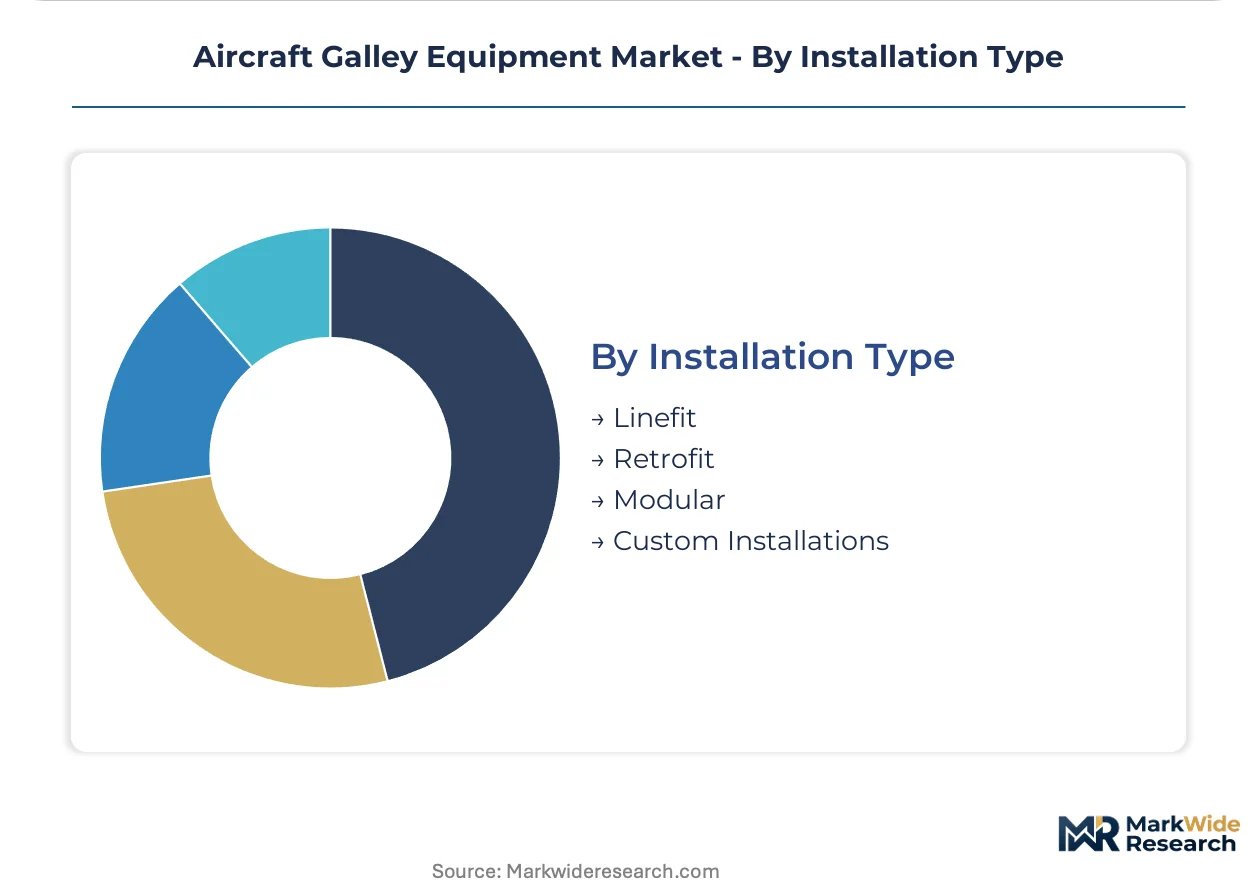
Installation Type:
Customer type stratification separates original equipment procurement from aftermarket retrofit, with contract duration and margin structure diverging accordingly.
- Linefit:Factory-integrated galley systems specified during airframe assembly command premium pricing and long-term supplier relationships. Boeing's delivery backlog in the United States drives concentrated demand for linefit equipment procurement coordinated through airframer integration teams.
- Retrofit:Post-delivery modification programs address aging narrow-body fleets, with low-cost carriers in Southeast Asia and Latin America driving simultaneous linefit and retrofit demand for buy-on-board meal programs.
- Modular:Standardized rail-mounted units enable rapid cabin reconfiguration between high-density and premium layouts.
- Custom Installations:Bespoke galley architectures for VIP and head-of-state aircraft require extended engineering cycles.
Linefit absorbs the bulk of installed capacity; retrofit is expanding most quickly as fleet modernization cycles compress.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Wichita anchors North American galley equipment activity through its concentration of business jet completion centers and Boeing supplier integration teams. The metropolitan corridor channels specification authority for premium cabin configurations while coordinating linefit procurement with Seattle and Charleston assembly lines.
United States
Boeing's delivery backlog in Washington and South Carolina drives concentrated linefit equipment procurement through airframer integration teams. FAA weight-reduction mandates under Part 25 airworthiness directives compel gram-level optimization in cabin interiors. The Pacific Northwest aerospace cluster in Everett coordinates galley specification authority with Wichita completion centers for mixed fleet deployments.
Germany
Diehl Stiftung's specialization in EASA CS-25 certified refrigeration units anchors European supply chain concentration in Hamburg and Laupheim. The EU F-Gas Regulation restricts high-GWP coolants in galley thermal management systems, forcing redesign cycles for European-registered aircraft. Bavaria's aerospace engineering corridor clusters composite material R&D for lightweight trolley structures.
France
Safran SA leverages integrated cabin systems portfolios from Paris-region headquarters to dominate high-complexity galley architectures for twin-aisle platforms. EASA CS-25 Amendment 25 load-attainment criteria favor established type-certificate relationships, consolidating procurement toward certified incumbents. Toulouse aerospace suppliers coordinate galley linefit integration with Airbus final assembly lines.
China
AVIC Cabin Systems represents state-backed vertical integration into commercial aircraft interior supply chains from Xi'an and Shanghai facilities. China's dual carbon goals accelerate composite material substitution in cabin equipment specifications for C919 and ARJ21 programs. The Yangtze River Delta aerospace cluster concentrates MRO retrofit demand for narrow-body fleet modernization.
India
IndiGo and Air India narrow-body order backlogs exceeding 1,000 aircraft create concentrated demand for lightweight galley configurations optimized for 90-minute sector economics. BIS certification requirements for imported aircraft equipment create compliance barriers favoring suppliers with established Indian technical representation. Karnataka's aerospace manufacturing corridor in Bangalore hosts subsystem integration facilities serving domestic carrier procurement teams.
Aircraft Galley Equipment Market Vendor Landscape
Premium-margin players sit above commodity-margin players across certification depth and type-certificate relationship longevity. The vendor base stratifies between integrated cabin system providers with sustained airframer partnerships and component specialists serving retrofit aftermarket demand. Three archetypes dominate: aerospace conglomerates with multi-system portfolios, family-owned engineering specialists with EASA/FAA certification depth, and state-backed national champions serving domestic aircraft programs. Consolidation pressure manifests through framework agreement bundling and long-term fleet procurement centralization at airline headquarters.
Within the integrated systems tier, Safran SA and Collins Aerospace exemplify aerospace conglomerates leveraging multi-cabin-system portfolios to capture bundled procurement awards. Diehl Stiftung & Co. KG represents the family-owned specialist archetype with concentrated certification expertise in thermal management systems. AVIC Cabin Systems Limited anchors the state-backed tier, channeling domestic aircraft program requirements through vertically integrated supply structures. Bucher Leichtbau AG and JAMCO Corporation occupy positions between these archetypes, with geographic naming conventions suggesting Swiss and Japanese operational bases respectively. EFW GmbH's German corporate suffix indicates European engineering heritage within the competitive set.
| Leading Market Players |
|---|
| Safran SA |
| Collins Aerospace |
| JAMCO Corporation |
| Diehl Stiftung & Co. KG |
| Bucher Leichtbau AG |
| AVIC Cabin Systems Limited |
| AIM Altitude |
| EFW GmbH |
| Aerolux |
| Others |
Supply Flow & Price Mechanics
Certification-grade bifurcation between FAA/EASA type-certificate holders and uncertified aspirants concentrates pricing power in established incumbents while fragmenting supply chain access for emerging suppliers. This tier divergence manifests in long-term framework agreements commanding premium valuations for certified thermal systems, whereas commodity retrofit orders face margin compression from aluminum-intensive specifications.
Pricing Analysis
Value-based pricing anchored to fuel-burn savings per kilogram removed from cabin interiors governs composite galley component transactions. Three-tier pricing structure across premium thermoplastic, standard aluminum, and economy-grade stainless steel configurations reflects certification depth and airframer relationship longevity. Cost compression in narrow-body retrofit tiers is intensifying because low-cost carriers bundle galley awards with seat and lavatory contracts. Full-service carriers operating twin-aisle platforms exhibit lowest price sensitivity; Southeast Asian low-cost operators demonstrate highest.
Supply Chain Analysis
Domestic-content mandates in India's BIS certification requirements and China's C919 program localization targets are reshaping sourcing patterns toward regional subsystem integration. Prepreg manufacturing for composite components concentrates in Japan and Germany; aerospace-grade aluminum extrusion feeds from United States and French mills. Supply chain risk centers on single-source vulnerability for carbon-fiber-reinforced thermoplastic resins. Distribution runs through airframer integration teams at Boeing's Everett and Airbus's Toulouse final assembly lines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Composite material certification capacity constraints prop pricing power for incumbent thermal system suppliers, creating a supply-constrained market structure favoring established type-certificate holders.
For Market Incumbents: Anchor certification depth against emerging composite specialists by accelerating EASA CS-25 Amendment 25 compliance investments before redesign cycles consolidate procurement. Defend position through backward integration into aerospace-grade resin supply chains, mitigating Japan-Germany prepreg concentration risk. Prioritize long-term framework agreements with US network carriers bundling galley, seat, and lavatory awards. For New Entrants and Emerging Players: EASA F-Gas Regulation refrigerant phase-down in Europe opens a window for solid-state thermal management specialists to capture retrofit demand from legacy vapor-compression units. Target India's narrow-body fleet expansion for lightweight galley configurations optimized for 90-minute sector economics. Pursue BIS certification partnerships with Karnataka aerospace manufacturing corridors as primary go-to-market pathway. For Investors and Strategic Acquirers: Re-rating potential sits with family-owned EASA/FAA certification specialists given EU Green Deal circular design requirements favoring modular, disassemblable trolley systems. Long-term viability over a decade horizon rests on type-certificate relationship longevity and airframer integration depth. Watch for CS-25 load-attainment criteria enforcement as inflection signal consolidating procurement toward certified incumbents.| Strategic Initiative | Industry Significance |
|---|---|
| Composite Material Certification Investment | EASA CS-25 Amendment 25 compliance secures type-certificate relationships with Boeing and Airbus integration teams. |
| Backward Integration into Resin Supply | Captive aerospace-grade prepreg production mitigates Japan-Germany supply concentration and lead time volatility. |
| Circular Design Platform Development | EU Green Deal take-back program documentation enables European-registered aircraft fleet compliance and premium positioning. |
| India Localization Partnership | BIS certification through Karnataka aerospace corridors unlocks IndiGo and Air India narrow-body order backlogs. |
| Solid-State Thermal System Launch | Induction heating and solid-state refrigeration integration addresses EU F-Gas Regulation phase-down constraints. |
Methodological Framework
Independent corroboration across airframer integration teams, airline fleet planning executives, and MRO procurement directors underwrites the qualitative findings in this study. Primary interviews with galley equipment program managers, EASA certification engineers, and composite material R&D leads combined with secondary validation from FAA airworthiness directives, EASA CS-25 amendment documentation, and airframer supplier portal disclosures. Bottom-up segmentation modeling and top-down market sizing triangulate volume estimates across the analysis window.
Comparable-period anchoring to historical delivery backlogs and retrofit cycle timing informed the projection horizon segmentation. Product type, material category, installation mode, and end-user tier dimensions structured the analytical framework. CAGRs derived from fleet delivery schedules, composite substitution curves, and regulatory compliance timelines. Forecast inputs incorporated Boeing and Airbus narrow-body production rates, EU F-Gas Regulation phase-down milestones, and India domestic aviation growth trajectories.
The model assumes a particular technology adoption path; alternative pathways for solid-state refrigeration and induction heating thermal convergence would alter the outlook. Forecasts reflect assumptions regarding EASA CS-25 Amendment 25 enforcement timing, composite material cost parity achievement, and airline procurement centralization trajectories. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft
Latin America Commercial Aircraft Market
Aircraft
Commercial Aerospace Market
Aircraft
US Aviation Market
Aircraft
UK Aviation Market
Aircraft
Aircraft Window Frame Market
Aircraft
Attack Helicopter Market
Aircraft
Fixed Wing Aircraft Rivets Market
Aircraft
Water Bomber Market
Aircraft
Amphibious Aircraft Market
Aircraft
Glider Aircraft Market
Aircraft
Global Aircraft Electric Brake Control System Market
Aircraft
Aircraft Cables Market
Aircraft
Commercial Helicopter Market
Aircraft
Aircraft Leasing Market
Aircraft
Sailplane Market
Aircraft
Aircraft Inspection Covers Market