
 Asia-Pacific Business Jet Market | 2026-2036
Asia-Pacific Business Jet Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Business Jet Market Outlook
CAAC type certification timelines for imported business aircraft is collapsing from twenty-four months to under fourteen months. Gulfstream Aerospace leverages its Savannah-based completion center to sustain premium cabin customization lead times for Chinese buyers. Bombardier Aviation anchors its Asia-Pacific service footprint through Singapore's Seletar maintenance hub. Honda Aircraft Company differentiates via its HA-420 HondaJet's over-the-wing engine mount configuration, competing for short-runway access across Indonesia's archipelago.
A business jet denotes a fixed-wing aircraft purpose-built or retrofitted for private and corporate air transport, typically featuring pressurized cabins, turbofan propulsion, and range capabilities from 1,500 to 7,500 nautical miles depending on segment class. These aircraft serve time-sensitive executive mobility, medical evacuation, and specialized cargo roles where scheduled airline networks prove inadequate. Light Jets occupy the highest transaction frequency in pre-owned markets across the Asia-Pacific, while Ultra-long-range Jets capture disproportionate value pools on direct Sydney-to-London and Shanghai-to-New York routings. Charter Services within the End User dimension are outpacing private ownership growth as fractional and on-demand models reduce capital commitment barriers for Southeast Asian family offices.
Civil Aviation Administration of China certification requirements shape aircraft import eligibility and cabin modification standards for mainland operators. Australia's Civil Aviation Safety Authority mandates enhanced vision system compliance for remote-area medical evacuation contracts, directing technology procurement patterns. Japan's MLIT noise abatement protocols around Tokyo Haneda and Osaka Itami constrain night-slot business jet movements, altering fleet deployment economics. Stakeholders must weigh CAAC's accelerating certification pace against Australia's evolving sustainable aviation fuel mandates when positioning next-generation aircraft introductions.
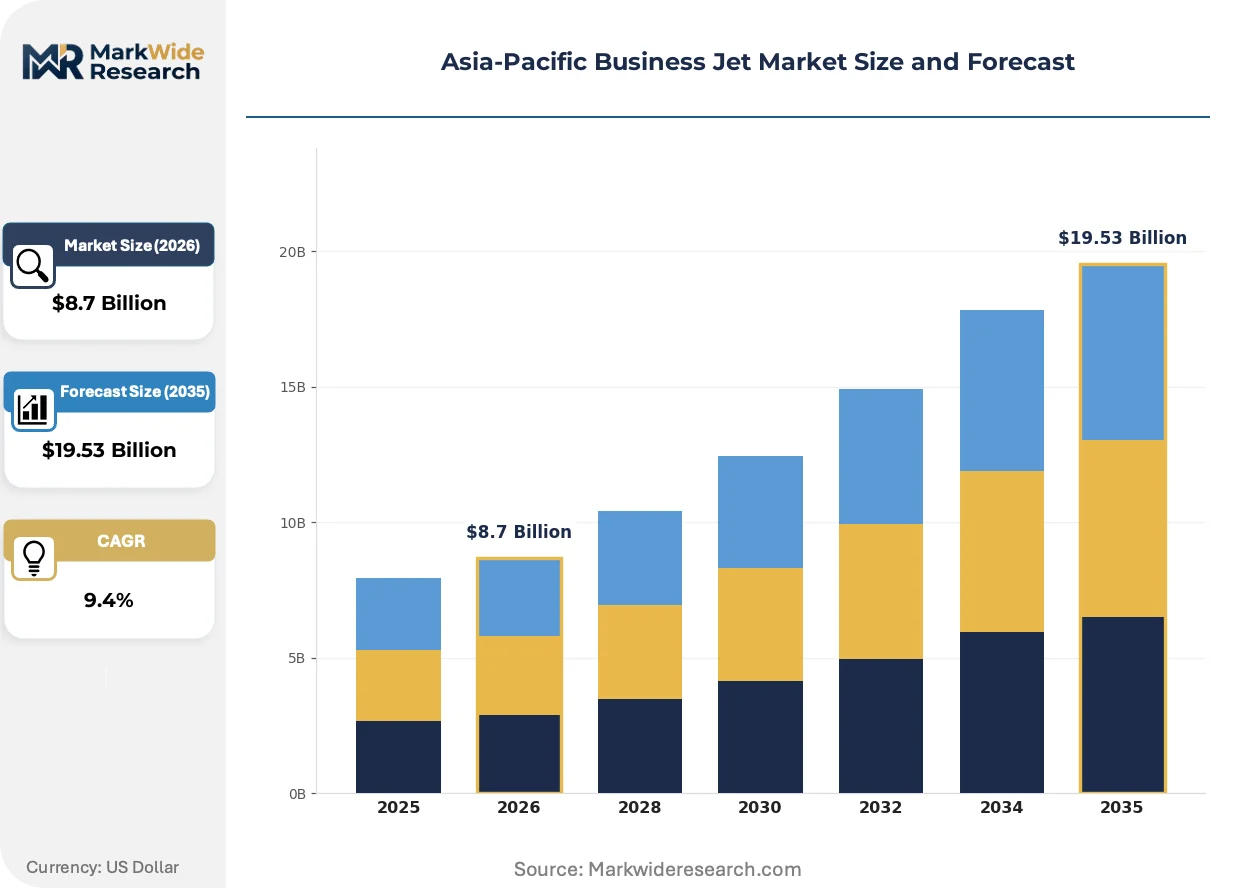
Market Dynamics
China's dual carbon goals are compressing fleet renewal timelines across the region, pressuring operators toward sustainable aviation fuel adoption and next-generation propulsion architectures before asset depreciation cycles complete.
Growth Catalysts
- CAAC Certification Acceleration:China's Civil Aviation Administration has collapsed type certification timelines from twenty-four months to under fourteen months, unlocking faster fleet modernization for mainland operators.
- Fractional Ownership Models:Southeast Asian family offices are reducing capital commitment barriers through on-demand charter structures, expanding addressable demand beyond traditional full-ownership segments.
- Remote Medical Evacuation Contracts:Australia's Civil Aviation Safety Authority mandates enhanced vision system compliance for outback medical services, directing technology procurement toward capable light jet platforms.
Market Restraints
- Sustainable Aviation Fuel Supply Concentration:SAF production capacity remains concentrated in Singapore and select Australian refineries, creating geographic dependency for dual carbon compliance.
- Import Duty Regimes:Indonesia's customs frameworks impose substantial landed cost penalties on completed aircraft, distorting direct ownership economics versus offshore charter arrangements.
- Runway Infrastructure Limitations:Short-field performance requirements across Indonesia's archipelago restrict eligible aircraft types to specific wing-mounted engine configurations.
Strategic Opportunities
- Philippines Charter Liberalization:Regulatory reforms opening secondary airport slots to private aviation are creating first-mover advantages for fleet operators targeting Manila-Cebu-Davao triangle connectivity.
- Electrification Pathways:Hybrid-electric propulsion development programs in Japan and South Korea are converging with battery energy density improvements to enable sub-500 nautical mile regional routes.
- Maintenance Hub Consolidation:Singapore's Seletar aerospace cluster offers regulatory harmonization across ASEAN markets, reducing multi-jurisdiction compliance overhead for regional fleet managers.
Industry Challenges
- Certification Coordination Complexity:Operators must reconcile CAAC's accelerating approval pace with Australia's evolving sustainable aviation fuel mandates when positioning next-generation aircraft introductions.
- Pilot Training Pipeline Constraints:Type rating capacity for advanced avionics suites lags fleet expansion rates across Southeast Asian training centers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Business Jet Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Light Jets, Mid-size Jets, Large Jets, Ultra-long-range Jets End User: Private Owners, Corporations, Charter Services, Government Agencies Application: Executive Travel, Medical Evacuations, Cargo Transport, Tourism Technology: Fly-by-wire, Avionics Systems, Turbofan Engines, Enhanced Vision Systems |
| Companies Covered | Textron Aviation, Honda Aircraft Company, Gulfstream Aerospace, Boeing Business Jets, Airbus Corporate Jets, Bombardier Aviation, Embraer Executive Jets, Pilatus Aircraft, Dassault Aviation, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Business Jet Market Strategic Shifts
Propulsion architecture choices and certification pathway strategies are actively fragmenting competitive positioning, with sustainability mandates and operational flexibility requirements pulling fleet planning in divergent directions.
Over-the-wing engine mount configurations are bifurcating short-runway access capabilities from traditional rear-fuselage designs. Indonesian charter operators are adopting these platforms at accelerated rates for archipelago connectivity. The technology is bifurcating market segmentation between terrain-limited island networks and major hub-to-hub trunk routes.
Japan's MLIT noise abatement protocols around Tokyo Haneda and Osaka Itami constrain night-slot business jet movements. These restrictions alter fleet deployment economics toward day-optimized routing and alternative base positioning. Ultra-long-range segments respond through Narita and Kansai International secondary hub strategies.
Charter service procurement now dominates Southeast Asian family office mobility decisions, displacing traditional whole-aircraft ownership as the default capital deployment model. On-demand platforms capture transaction frequency previously reserved for pre-owned light jet acquisitions. This behavioral shift concentrates most visibly across Singapore, Jakarta, and Bangkok metropolitan corridors.
Asia-Pacific Business Jet Market Segmentation
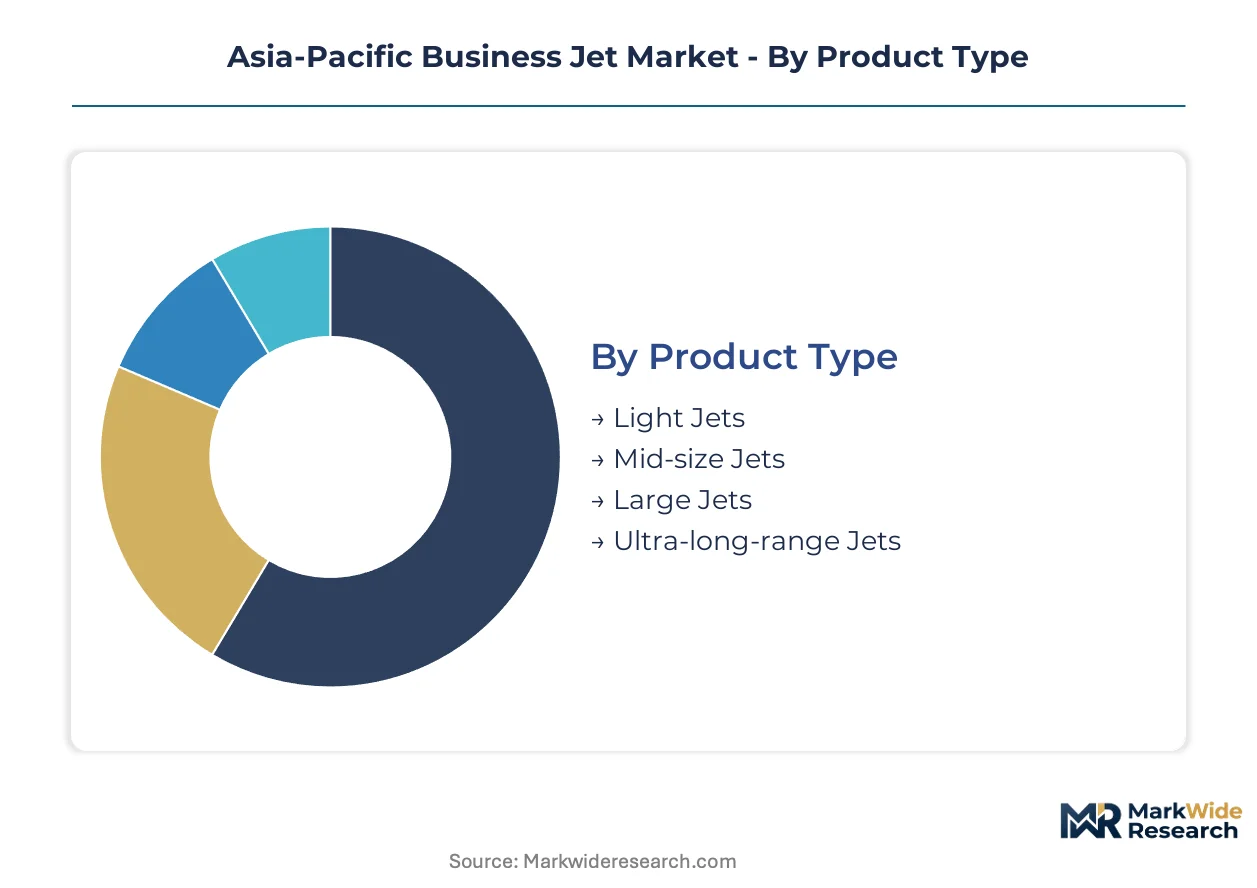
Segmentation across product type, end user, application, and technology reveals divergent margin architectures across the Asia-Pacific business jet market. Fleet planners configure procurement strategies around certification timelines, runway constraints, and carbon compliance obligations that vary sharply by segment.
Product Type:
Margin pools concentrate in ultra-long-range platforms serving trans-Pacific trunk routes, while transaction velocity drives profitability in the pre-owned light jet channel across Southeast Asian secondary markets.
- Light Jets:These aircraft typically accommodate 6-8 passengers with ranges below 2,400 nautical miles and short-field performance enabling archipelago operations. Demand concentrates across Indonesia's island networks where charter operators prioritize runway flexibility over cabin scale, with CAAC certification acceleration now permitting faster fleet turnover for Chinese import buyers.
- Ultra-long-range Jets:Capable of 6,000+ nautical mile nonstop sectors with full passenger loads and premium cabin configurations. Australia's mining corridor executive shuttles and Sydney-London direct routings anchor demand, though dual carbon goals pressure operators toward SAF-compatible next-generation powerplants before depreciation cycles complete.
- Mid-size Jets:Balance transcontinental range with moderate acquisition costs for corporate flight departments.
- Large Jets:Deliver intercontinental capability with stand-up cabins for 12-16 passengers in full-service configurations.
Light Jets hold installed capacity across Southeast Asian charter fleets. Ultra-long-range Jets are rotating up the share rankings as Chinese and Australian operators prioritize direct connectivity over hub transfers.
End User:
Capital deployment patterns bifurcate between asset-light charter access and balance-sheet ownership, with family office behavior shifting decisively toward on-demand structures.
- Charter Services:Fleet operators aggregate demand across fragmented user bases through fractional and ad-hoc access models. Southeast Asian family offices in Singapore, Jakarta, and Bangkok corridors are displacing whole-aircraft ownership with this capital-efficient alternative, compressing pre-owned light jet transaction timelines.
- Private Owners:Individual or family-controlled aircraft with dedicated flight crews and hangar infrastructure. China's high-net-worth demographic sustains this segment despite tightening import documentation requirements, with Gulfstream and Bombardier completion centers capturing customization premiums.
- Corporations:Flight departments serving executive mobility and client entertainment mandates.
- Government Agencies:State-operated fleets for official transport and specialized mission profiles.
Private Owners hold installed capacity across Greater China's premium completion market. Charter Services are expanding most quickly as fractional platforms capture transaction frequency previously reserved for outright acquisition.
Application:
Operational specialization determines equipment specifications, with medical evacuation contracts imposing avionics mandates that reshape technology procurement patterns.
- Medical Evacuations:Dedicated air ambulance configurations with stretcher systems, medical oxygen, and enhanced vision system compliance for remote-area operations. Australia's Civil Aviation Safety Authority mandates EVS capability for outback contracts, directing fleet investment toward capable light and mid-size platforms.
- Executive Travel:Time-sensitive point-to-point mobility for corporate leadership and high-net-worth individuals. China's dual carbon goals accelerate fleet renewal timelines here, pressuring operators toward SAF adoption before asset depreciation cycles complete.
- Cargo Transport:Specialized freight configurations for time-critical logistics and humanitarian relief.
- Tourism:Luxury experiential travel and destination access for ultra-premium hospitality segments.
Executive Travel holds installed capacity across the region's corporate flight departments. Medical Evacuations are climbing the fastest as Australia's remote-area healthcare infrastructure expands.
Technology:
Propulsion and avionics choices fragment competitive positioning, with sustainability mandates and certification pathway strategies pulling fleet planning in divergent directions.
- Turbofan Engines:Core propulsion systems delivering thrust-to-weight ratios and fuel efficiency for business jet performance envelopes. Pratt & Whitney Canada and Honeywell variants dominate the Asia-Pacific installed base, with next-generation architectures addressing dual carbon compliance pressures.
- Enhanced Vision Systems:Sensor fusion technologies combining infrared imaging with synthetic terrain displays for low-visibility operations. Australia's CASA mandates drive adoption across medical evacuation fleets, while Indonesia's terrain-challenged archipelago routes reward EVS-equipped platforms.
- Fly-by-wire:Digital flight control systems replacing mechanical linkages for precision handling.
- Avionics Systems:Integrated cockpit suites encompassing navigation, communication, and flight management.
Turbofan Engines hold installed capacity across the regional fleet. Enhanced Vision Systems are gaining share fastest as regulatory mandates expand beyond Australian medical contracts into general operational requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dual carbon mandates and certification acceleration are redrawing fleet deployment patterns across the region. China's collapsing CAAC timelines and Australia's SAF mandates create divergent compliance calendars. Southeast Asian charter liberalization opens secondary airport access.
China
Mainland operators drive ultra-long-range jet procurement for direct Shanghai-New York and Beijing-London trunk routes. CAAC type certification compression from twenty-four to fourteen months unlocks faster fleet modernization. Completion centers in Tianjin and Savannah-based Gulfstream facilities capture customization premiums for high-net-worth buyers.
Australia
Mining corridor executive shuttles anchor light and mid-size jet demand across Western Australia and Queensland. CASA mandates enhanced vision system compliance for remote-area medical evacuation contracts, directing technology procurement. Perth and Brisbane maintenance clusters expand to support outback operational requirements.
Indonesia
Archipelago connectivity requirements favor short-field performance aircraft with over-the-wing engine configurations. Customs duty regimes impose substantial landed cost penalties on completed imports, distorting ownership economics toward offshore charter structures. Jakarta and Bali charter operators aggregate fragmented demand across the island network.
Japan
MLIT noise abatement protocols constrain night-slot movements around Tokyo Haneda and Osaka Itami, altering fleet deployment toward day-optimized routing. Hybrid-electric propulsion development programs in Nagoya and Seoul converge with battery density improvements. Narita and Kansai International serve as secondary hubs for ultra-long-range segments.
Singapore
Seletar aerospace cluster offers regulatory harmonization across ASEAN markets, reducing multi-jurisdiction compliance overhead. SAF production concentration in Singaporean refineries creates geographic dependency for regional dual carbon compliance. Fractional ownership platforms headquartered here capture Southeast Asian family office capital deployment.
Asia-Pacific Business Jet Market Competitive Environment
Player mix skews toward integrated airframe-completion-service conglomerates with captive aftermarket networks. Market structure concentrates around three strategic archetypes: Savannah-based ultra-long-range specialists, Montreal/Toronto-centered diversified portfolios, and São Paulo-linked regional jet platforms. Competitive moves center on certification pathway acceleration and Singapore hub consolidation for ASEAN coverage.
Within the diversified-portfolio tier, Bombardier Aviation anchors aftermarket positioning through Seletar maintenance infrastructure. Gulfstream Aerospace exemplifies the premium-completion archetype via Savannah customization lead times for Chinese buyers. Honda Aircraft Company occupies the short-field specialization vector, competing for Indonesian archipelago access. These three represent distinct competitive positioning rather than overlapping segment contestation.
| Leading Market Players |
|---|
| Textron Aviation |
| Honda Aircraft Company |
| Gulfstream Aerospace |
| Boeing Business Jets |
| Airbus Corporate Jets |
| Bombardier Aviation |
| Embraer Executive Jets |
| Pilatus Aircraft |
| Dassault Aviation |
| Others |
Value Chain & Pricing Dynamics
Fourteen-month CAAC certification timelines now compress inventory cycles for Chinese import buyers, concentrating pricing power among Savannah and Tianjin completion centers while fragmenting negotiation leverage across Southeast Asian charter operators lacking direct manufacturer relationships.
Pricing Analysis
Certification tier—CAAC-approved versus pending-import status—creates the primary spread between premium and standard transaction bands. Ultra-long-range platforms command project-based pricing with after-sales service bundling, while light jets trade on per-unit transactional terms with volume-scale discounts for fleet operators. Cost compression in the pre-owned channel intensifies as fractional ownership models displace whole-aircraft demand, making charter services the most price-sensitive buyer archetype and private owners in Greater China the least.
Supply Chain Analysis
Port congestion along Singapore-Jakarta trade lanes elevates inbound logistics costs for Indonesian charter operators sourcing completion services offshore. Manufacturing concentrates in the United States, Canada, and Brazil for airframe assembly, while Japan and South Korea anchor avionics and hybrid-electric propulsion development. Supply chain risk rests on single-source vulnerability for Pratt & Whitney Canada and Honeywell engine variants. Distribution runs through Singapore's Seletar cluster for ASEAN regulatory harmonization.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits at a platform-economics inflection where fractional ownership platforms in Singapore are converging with on-demand charter interoperability, compressing traditional asset-heavy models into liquidity-driven access networks.
For Market Incumbents: Secure CAAC certification pathway acceleration through Tianjin completion center expansion, defending against emerging entrant charter platforms capturing Southeast Asian family office capital. Deepen backward integration into Savannah-based cabin customization to sustain premium pricing power as dual carbon mandates pressure fleet renewal economics. For New Entrants and Emerging Players: Differentiate on short-field performance specialization for Indonesia's archipelago connectivity, where terrain-limited island networks remain underpenetrated by rear-fuselage designs. Target Philippines charter liberalization through Manila-Cebu-Davao triangle fleet positioning, leveraging regulatory reform windows before incumbent operators consolidate secondary airport slots. For Investors and Strategic Acquirers: Long-term, this sits as a infrastructure-capture play because maintenance hub consolidation in Singapore offers regulatory arbitrage across fragmented ASEAN compliance regimes. Acquisition targets center on Seletar-anchored service providers with multi-jurisdiction approvals. The signal to watch is CAAC-SAF mandate synchronization timing as a fleet replacement acceleration trigger.| Strategic Initiative | Industry Significance |
|---|---|
| CAAC Certification Acceleration | Compresses fourteen-month approval timelines, unlocking faster mainland China fleet modernization for Savannah completion centers. |
| Singapore Hub Consolidation | Seletar aerospace cluster reduces multi-jurisdiction compliance overhead for ASEAN charter fleet managers. |
| Short-Field Platform Specialization | HondaJet's over-the-wing configuration captures Indonesian archipelago routes with terrain-limited runway access. |
| SAF Supply Agreement | Singapore refinery concentration creates geographic dependency for regional dual carbon compliance. |
| Fractional Ownership Platform Launch | On-demand models displace whole-aircraft ownership among Bangkok and Jakarta family offices. |
Study Parameters
Operator-level perspectives from charter fleet managers, CAAC certification specialists, Singapore-based maintenance directors, and Australian mining corridor flight departments anchored the qualitative base. Secondary validation drew from CAAC type certification filings, CASA medical evacuation contract specifications, MLIT noise abatement protocols, and customs documentation from Indonesian Directorate General of Customs and Excise. Bottom-up transaction analysis triangulated with top-down fleet registry modeling.
Sensitivity analysis tested volume and value outputs across product type, end user archetype, application specialization, and technology adoption segments over the projection horizon. CAGRs derived from fleet replacement cycle compression, CAAC timeline acceleration, and SAF mandate phase-in assumptions. Industry-specific inputs incorporated dual carbon compliance calendars and archipelago runway infrastructure constraints.
The analysis sits within stated boundaries; outcomes outside CAAC-SAF synchronization, Philippines regulatory reform durability, or Indonesia customs regime stability would require recalibration. Forecasts reflect documented assumptions regarding certification pathway evolution and sustainable aviation fuel production scaling. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft
Onboard Oxygen Generating System (OBOGS) Market
Aircraft
General Aviation Market
Aircraft
Airship Market
Aircraft
Aircraft Cargo Systems Market
Aircraft
Aircraft Cables Market
Aircraft
Aircraft Cargo Winches Market
Aircraft
North America General Aviation Market
Aircraft
Asia-Pacific Commercial Aircraft Market
Aircraft
Aircraft Anchoring System Market
Aircraft
Commercial Aircraft Market
Aircraft
Aircraft Windshield Wiper and Washer System Market
Aircraft
Wing Inspection and Taxi Lighting Upgrade Kits Market
Aircraft
Flap Track Fairing Drag Reduction Upgrade Kits Market
Aircraft
US Military Aviation Market
Aircraft
Manned Evtol Crafts Market
Aircraft
Australia Aviation Market