
 Helicopter Simulator Market | 2026-2036
Helicopter Simulator Market Size, Share, and Industry Trends Forecast 2026-2036
Helicopter Simulator Market Intelligence
The push for Level D certification for full flight simulators is reorganizing pilot training priorities and investment cycles. CAE Inc. leverages its extensive network of global training centers to offer certified simulation services for a wide range of helicopter models. L3Harris Technologies Inc. specializes in high-fidelity military training systems for complex mission rehearsals. Thales Group differentiates through its advanced visual systems and integrated instructor operating stations.
A helicopter simulator is a ground-based system that replicates the flight characteristics and cockpit environment of a specific rotary-wing aircraft. These systems incorporate high-resolution visual displays and six-degrees-of-freedom motion platforms to create an immersive training experience for pilots. Full Flight Simulators continue to command the highest value, driven by regulatory requirements for commercial pilot training. However, lower-cost Virtual Reality Trainers gain traction for procedural tasks, particularly in military training and emergency response training applications.
Regulatory bodies such as the US Federal Aviation Administration (FAA) and European aviation safety authorities mandate specific levels of simulator fidelity for pilot certification. Compliance with these stringent standards, which govern motion, visual, and control loading systems, dictates market access and product design. For manufacturers, the key decision revolves around balancing the high cost of developing certified systems against the expanding opportunities in non-certified, procedure-focused training devices for new markets.
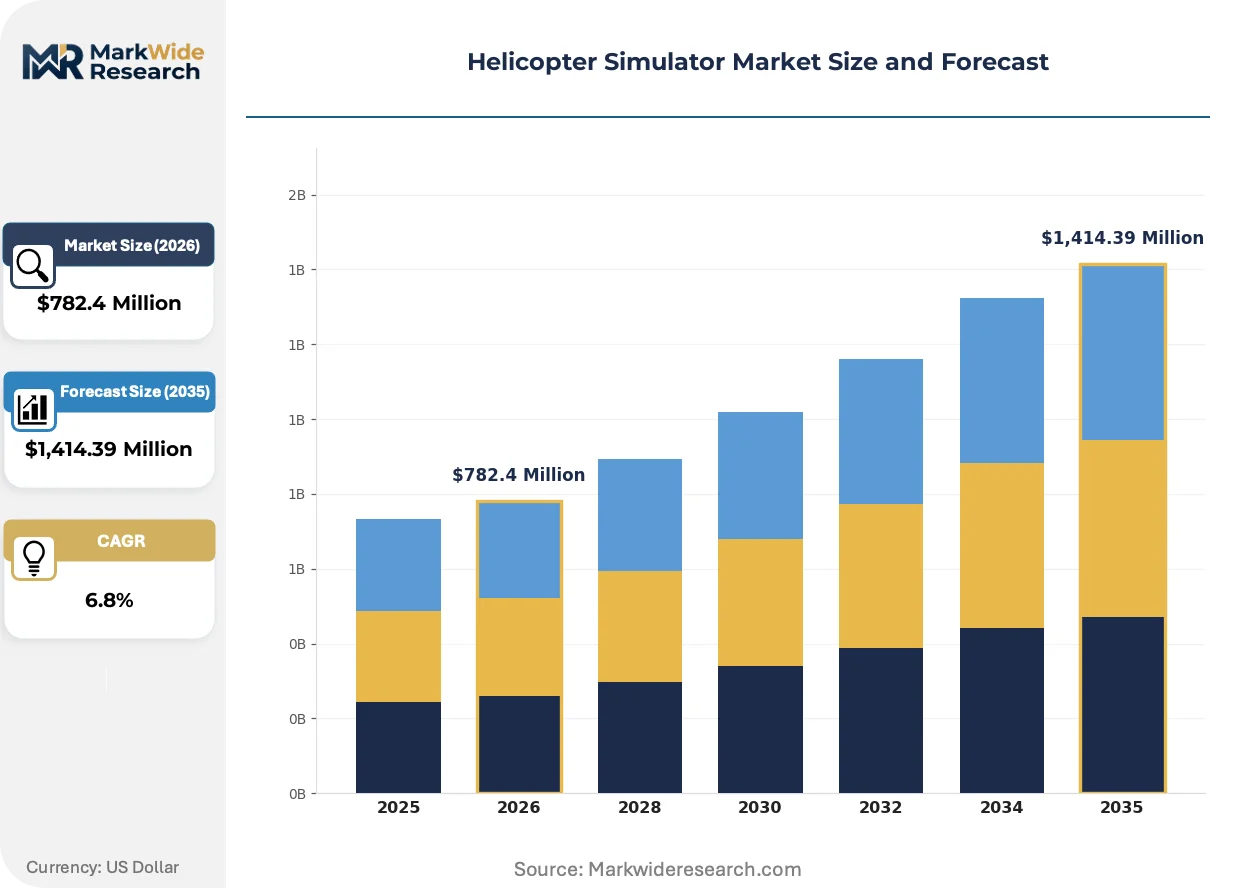
Market Dynamics
The helicopter simulator market is shaped by the fundamental tension between regulatory mandates demanding higher fidelity and operational pressures for more cost-effective training solutions. This dynamic forces a clear split between high-investment Level D full flight simulators and accessible, task-focused virtual reality systems.
Growth Catalysts
- Emergency Service Demand:Growing requirements from law enforcement, air ambulance, and search-and-rescue operators for realistic training that simulates high-stakes crisis scenarios are expanding the user base beyond traditional military and commercial pilots.
- Virtual Reality Integration:The adoption of lower-cost VR-based trainers for procedural and cockpit familiarization tasks allows flight schools and smaller operators to enhance training programs without the expense of full flight simulator time.
- Regulatory Mandates:Stringent certification standards from aviation authorities like the US FAA and EASA, which require simulator-based training hours for pilot currency and type ratings, provide a consistent demand floor for certified devices.
Market Restraints
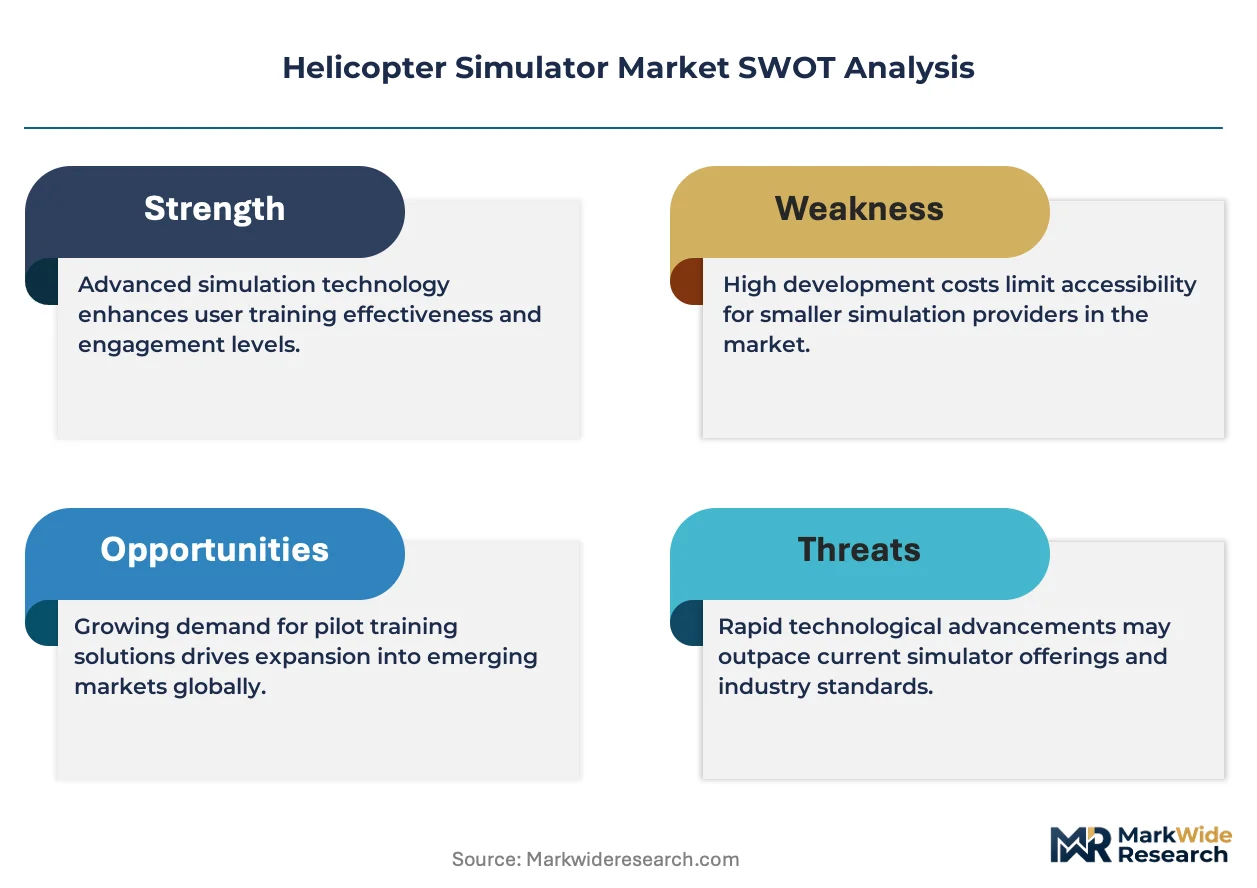
- High Development Costs:The significant research, development, and engineering investment required to create a high-fidelity simulator, particularly one meeting Level D certification, presents a major barrier to entry for new manufacturers.
- Complex Supply Chains:Reliance on a limited number of suppliers for critical components, such as six-degrees-of-freedom motion platforms and specialized control loading systems, creates potential bottlenecks and cost volatility.
- Long Certification Cycles:The extensive and time-consuming process of achieving certification from bodies like the FAA or EASA for new simulator models can delay market entry and return on investment for manufacturers.
Strategic Opportunities
- Maintenance Crew Training:There is a significant opportunity to develop and market specialized simulators and virtual trainers designed specifically for helicopter maintenance technicians, an underserved segment compared to pilots. -
- AI-Driven Scenario Generation:Integrating artificial intelligence to create dynamic, unpredictable training scenarios for emergency response and military mission rehearsal can provide a distinct competitive advantage over static, pre-programmed events. -
- Emerging Market Expansion:Targeting aviation authorities and operators in developing regions, such as parts of Latin America and Southeast Asia, with cost-effective, non-certified procedural trainers presents a key growth vector.
Industry Challenges
- Specialized Talent Scarcity:A shortage of qualified engineers and software developers with expertise in aerodynamics, avionics, and simulation software presents a persistent challenge to product development and innovation.
- Legacy System Integration:Operators face significant technical hurdles and costs when attempting to integrate new-generation simulators with older, existing IT infrastructure and training management systems at their facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Helicopter Simulator Market |
| Market Size in 2026 | $782.4 Million |
| Market Size in 2035 | $1,414.39 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Full Flight Simulator, Fixed Base Simulator, Part Task Trainer, Virtual Reality Trainer Technology: Visual Systems, Motion Systems, Control Loading, Instructor Operating Station, Scenario Generation Application: Military Training, Commercial Pilot Training, Emergency Response Training, Search and Rescue Preparation End User: Defense Organizations, Flight Schools, Emergency Service Providers, Research Institutions |
| Companies Covered | L3Harris Technologies Inc., Airbus SE, CAE Inc., Rheinmetall AG, Textron Inc., FlightSafety International, Raytheon Technologies Corporation, Indra Sistemas SA, Thales Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Helicopter Simulator Market Strategic Shifts & Innovations
The market's evolution is defined by a dual pursuit of hyper-realistic immersion in high-end systems and cost-effective modularity in procedural trainers. This creates distinct development paths for simulators geared toward certification versus those focused on skill acquisition.
Virtual Reality (VR) and Augmented Reality (AR) trainers provide a cost-effective medium for procedural, spatial, and muscle-memory training. Military and emergency service operators are adopting these systems to supplement traditional simulator time for tasks like cockpit familiarization. For certain training modules, this technology is supplanting the need for exclusive reliance on more expensive full flight simulators, thereby optimizing training budgets.
Regulatory pressure from bodies like the FAA and EASA to enhance simulator fidelity for creditable training hours continues to intensify. This directly influences manufacturer design priorities, forcing investment in advanced visual and motion-cueing systems to meet or exceed Level D standards. Commercial training organizations are most affected, often leading them to partner with or outsource to large, specialized training centers.
A clear behavioral shift is occurring as operators increasingly favor training-as-a-service models over direct capital purchases of simulators. This model allows helicopter fleet operators to avoid large upfront investments and technology obsolescence risk, paying instead for guaranteed access to certified simulator hours. The trend is most visible in North America and Europe, where a dense network of third-party training providers exists.
Helicopter Simulator Market Segmentation
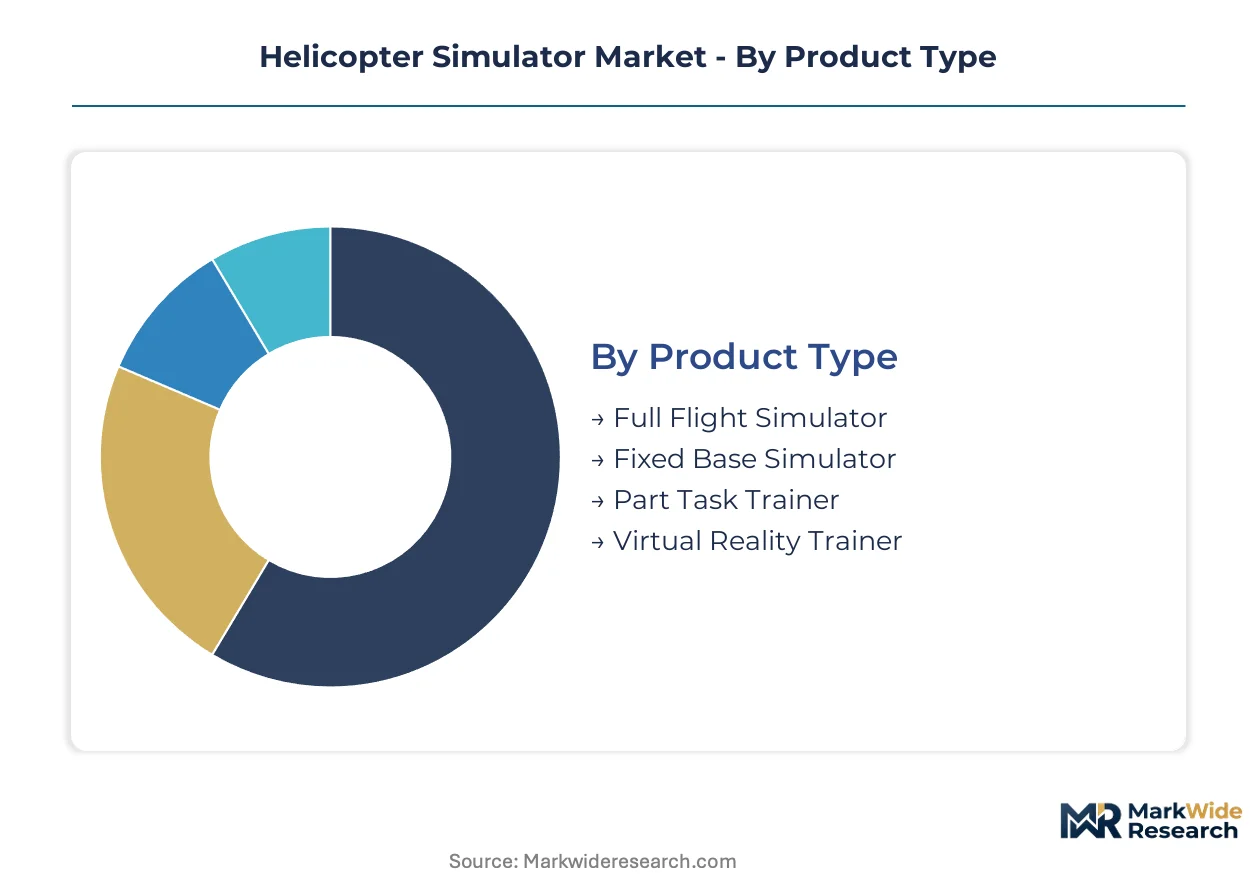
The helicopter simulator market segmentation reveals distinct value propositions and demand drivers across product types, underlying technologies, diverse applications, and varied end-user groups. Understanding these divisions is crucial for manufacturers to tailor solutions that meet specific operational demands and regulatory compliance. This analysis highlights the areas of concentrated investment and emerging opportunities.
Product Type:
Regulatory mandates from bodies like the US Federal Aviation Administration (FAA) and European aviation safety authorities significantly influence the development and deployment of helicopter simulator product types.
- Full Flight Simulator:These ground-based systems replicate the flight characteristics and cockpit environment of specific rotary-wing aircraft with high fidelity. Regulatory requirements for commercial pilot training and type ratings drive consistent demand for these certified devices in North America and Europe.
- Virtual Reality Trainer:These lower-cost, immersive systems utilize VR technology for procedural, spatial, and muscle-memory training. Military training organizations and emergency service providers are increasingly adopting these trainers to supplement traditional simulator time for cockpit familiarization tasks.
- Fixed Base Simulator:These systems offer a realistic cockpit environment without the full motion platform, providing cost-effective solutions for instrument flight rules (IFR) training.
- Part Task Trainer:Focused on specific skills or procedures, these trainers allow pilots to practice individual tasks like engine start-up or emergency procedures without full system engagement.
Established volume favors Full Flight Simulators; emerging adoption favors Virtual Reality Trainers.
Technology:
The cost structure of helicopter simulator technology components varies significantly, impacting overall system affordability and capability for different training requirements.
- Visual Systems:These advanced projection or display systems create highly realistic external environments, crucial for immersive training and meeting Level D certification standards. Investment in high-resolution visual systems is particularly strong for military mission rehearsal and complex commercial pilot training.
- Motion Systems:Utilizing six-degrees-of-freedom platforms, these systems provide physical cues replicating aircraft movement, G-forces, and turbulence. Manufacturers focus on reducing latency and increasing realism in motion systems to enhance pilot immersion and critical decision-making under stress.
- Control Loading:This technology provides realistic resistance and feedback in flight controls, accurately simulating aerodynamic forces and aircraft handling characteristics.
- Instructor Operating Station:This dedicated interface allows instructors to monitor, control, and introduce malfunctions into the simulation, facilitating effective training management.
- Scenario Generation:These software tools enable the creation of dynamic, unpredictable training scenarios, particularly valuable for emergency response and military mission rehearsals.
Technology advancements in Visual Systems boost realism, while Scenario Generation components enhance training efficiency.
Application:
Different customer types within the market prioritize specific applications for helicopter simulation, reflecting varied operational requirements and training objectives.
- Military Training:This application focuses on tactical operations, mission rehearsal, and advanced combat scenarios, often requiring high-fidelity systems and specialized visual databases. Procurement for military training applications remains robust across the United States and parts of the Middle East.
- Emergency Response Training:This segment demands realistic simulation of high-stakes crisis scenarios, including air ambulance operations, law enforcement pursuits, and search-and-rescue missions. Emergency service providers seek systems that can accurately replicate challenging environmental conditions and complex decision-making under pressure.
- Commercial Pilot Training:This application primarily addresses pilot certification, type ratings, and recurrent training for civil aviation operators.
- Search and Rescue Preparation:Simulators for this application focus on specific procedures, coordination, and environmental challenges encountered during search and rescue missions.
The demand for Military Training applications remains consistently high, with Emergency Response Training applications expanding most quickly.
End User:
End-user segments contribute varying volumes of procurement to the helicopter simulator market, influenced by budget cycles and operational scale.
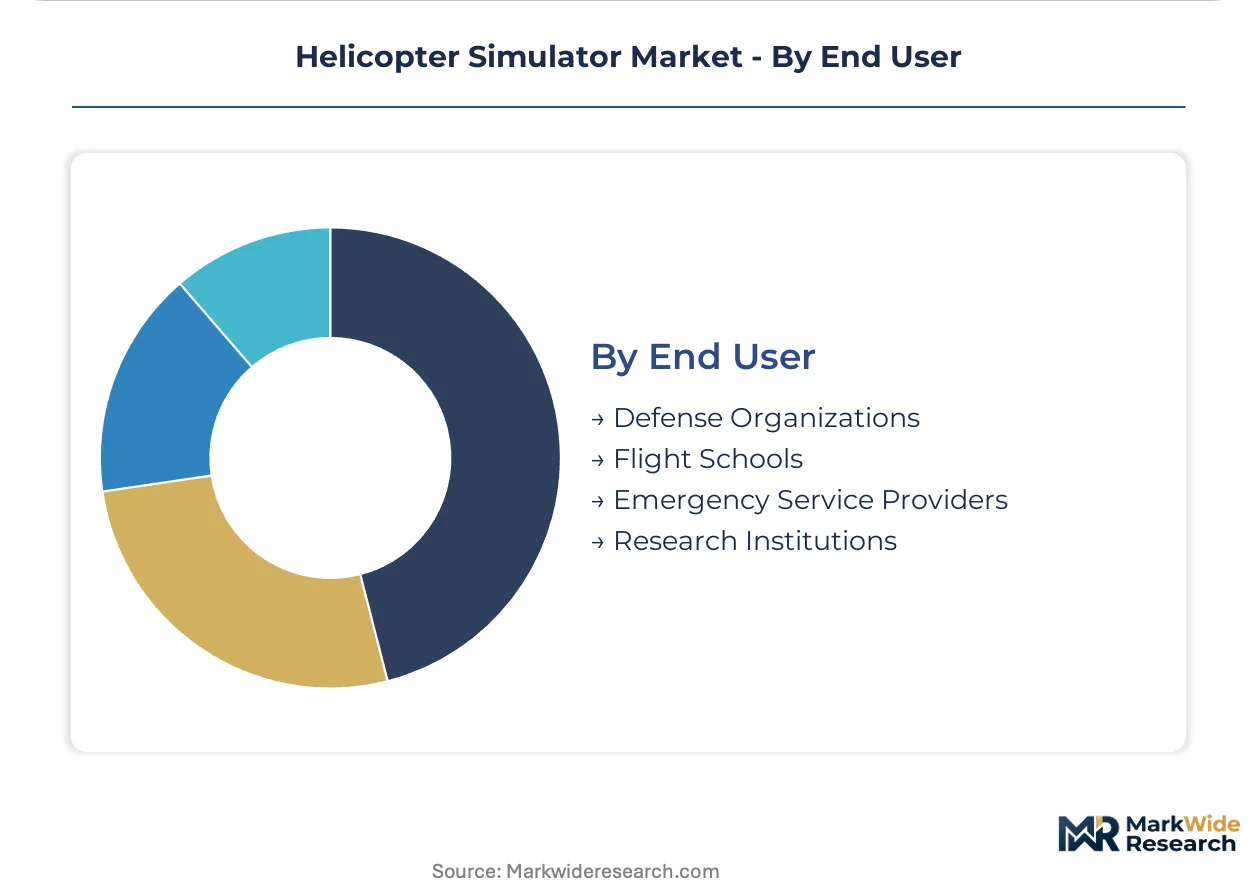
- Defense Organizations:These entities, including national air forces and army aviation, procure simulators for pilot training, mission rehearsal, and tactical development. Defense organizations typically invest in high-fidelity, complex systems that can integrate with broader military training ecosystems.
- Flight Schools:These institutions utilize simulators for initial pilot training, instrument ratings, and recurrent pilot checks, often seeking cost-effective solutions that meet regulatory certification standards. Flight schools in North America and Europe are increasingly adopting training-as-a-service models.
- Emergency Service Providers:This group includes air ambulance services, law enforcement aviation units, and coast guard operations, requiring realistic training for crisis management.
- Research Institutions:These organizations use simulators for human factors studies, aircraft design evaluation, and advanced aerospace research.
Procurement from Defense Organizations users provides market stability, while Research Institutions users seek solutions for specialized requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global helicopter simulator market exhibits varied trade dynamics, with nations acting as significant exporters of advanced training systems while others heavily import these specialized devices. Demand drivers span military, commercial, and emergency service sectors. Regulatory bodies across continents dictate fidelity and certification requirements.
United States
Military training and commercial pilot certification drive demand for helicopter simulators in the United States. The US Federal Aviation Administration (FAA) sets stringent standards for Level D simulators. Florida's Space Coast, alongside Texas's aerospace hubs, sees significant simulator research, development, and procurement.
France
Military mission rehearsal and commercial pilot training fuel simulator demand in France. European aviation safety authorities (EASA) mandates influence pilot certification requirements. Toulouse, a major aerospace center, drives simulator development and integration for European operators.
Germany
Defense organizations and flight schools are primary end-users for helicopter simulators in Germany. EASA regulations influence simulator design and deployment for both military and civil applications. The Munich region, with its strong engineering base, supports advanced simulator technology development and manufacturing.
United Arab Emirates
Military procurement and emergency service training drive simulator demand in the United Arab Emirates. Local civil aviation authorities adopt international standards for pilot training programs. Dubai and Abu Dhabi are central to Middle Eastern military and commercial aviation training investments.
Canada
Global training centers and commercial pilot programs sustain simulator demand in Canada. Transport Canada regulations align with international aviation safety standards for simulator use. Montreal, a key aerospace cluster, hosts major simulator manufacturers and training providers.
Helicopter Simulator Market Key Industry Players
Listed leaders compete with private specialists across the full spectrum of simulator fidelity, from Level D full flight systems to accessible virtual reality trainers. The market structure features a mix of large, diversified aerospace and defense contractors alongside highly specialized simulation technology providers. Strategic archetypes include integrated training solution providers, high-fidelity military system developers, and advanced visual system innovators. Companies actively pursue portfolio diversification and strategic partnerships to expand their global footprint and capture new market segments.
Specialists in comprehensive training solutions include CAE Inc., which exemplifies a global provider leveraging extensive training networks across various helicopter models. L3Harris Technologies Inc. represents a key developer of high-fidelity military training systems for complex mission rehearsals, often integrating specialized hardware for defense applications. Thales Group occupies a position as an innovator in advanced visual systems and integrated instructor operating stations, differentiating its offerings through technological superiority and integrated software platforms. These companies anchor different segments of the market, from commercial pilot certification to advanced military tactical training.
| Leading Market Players |
|---|
| L3Harris Technologies Inc. |
| Airbus SE |
| CAE Inc. |
| Rheinmetall AG |
| Textron Inc. |
| FlightSafety International |
| Raytheon Technologies Corporation |
| Indra Sistemas SA |
| Thales Group |
Cost & Logistics Intelligence
Virtual Reality trainer component substitution for traditional Full Flight Simulator modules reshapes both global supply chain geography and overall market pricing economics. This shift allows more accessible training solutions to emerge.
Pricing Analysis
Industrial OEM buyers anchor project-based pricing structures for high-fidelity helicopter simulators. Price differentiation stems from Level D certification and advanced visual systems, which command a premium. Pricing softness arises from the integration of lower-cost Virtual Reality trainers, driven by budget-conscious flight schools. Defense organizations exhibit the least price sensitivity, prioritizing mission-critical fidelity over cost.
Supply Chain Analysis
Reliance on specialized motion platform manufacturers in Germany underpins the high-fidelity simulator supply chain. Key components like six-degrees-of-freedom platforms and advanced visual displays draw from specialized suppliers in Germany, Canada, and the United States. Single-source vulnerability for these critical components represents a structural risk. Distribution runs through direct sales channels to defense organizations and large training centers, with channel partners serving smaller flight schools.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The helicopter simulator market requires a substitution defense strategy, as lower-cost Virtual Reality trainers increasingly threaten the dominance of traditional Full Flight Simulators for procedural tasks. Incumbents must navigate this technological shift.
For Market Incumbents: Fortify existing Level D certification advantages through continuous research and development in visual and motion cueing systems. Expand global training center networks, leveraging a training-as-a-service model to counter the threat of VR trainers displacing basic procedural training. Invest in integrating AI-driven scenario generation to maintain a lead in complex mission rehearsal capabilities. This strategy defends against erosion from lower-cost alternatives.
For New Entrants and Emerging Players: Anchor in underserved segments like maintenance crew training and emerging markets for procedural trainers. Target aviation authorities and operators in regions such as Latin America and Southeast Asia with cost-effective, non-certified VR solutions. Focus on specialized applications that traditional Full Flight Simulators do not adequately address. A go-to-market strategy emphasizing rapid deployment and task-specific modularity will gain traction.
For Investors and Strategic Acquirers: Capital is best deployed toward integrated training solution providers with strong global networks and diversified offerings. Long-term viability depends on adapting to the shift from capital expenditure to training-as-a-service models. Acquire specialized software developers in AI-driven scenario generation or advanced visual systems to future-proof portfolios. Watch for regulatory bodies, like the FAA, expanding creditable hours for advanced VR-based training.
| Strategic Initiative | Industry Significance |
|---|---|
| AI-Driven Scenario Generation | Enhances realism and unpredictability for military and emergency response mission rehearsals. |
| Strategic Partnership: VR Hardware Integration | Lowers cost and increases accessibility for procedural training, expanding market reach. |
| Geographic Expansion: Emerging Market Entry | Captures new demand from developing regions seeking cost-effective training solutions. |
| Capacity Expansion: Global Training Centers | Meets demand for certified simulator hours via training-as-a-service models in North America and Europe. |
| R&D Investment: Advanced Visual Systems | Maintains Level D certification compliance and enhances immersion for high-fidelity pilot training. |
Research Approach
Findings reconcile primary fieldwork against secondary review of FAA publications, EASA mandates, aerospace industry reports, and defense procurement databases. This involved extensive interviews with pilot training directors, defense procurement officers, simulator engineers, and aviation safety regulators. The analysis utilized both bottom-up aggregation of segment data and top-down market sizing for robust triangulation.
Product type, technology, application, end-user, and geographic region constituted the segmentation dimensions modeled across the analysis window. The analytical framework integrated historical data trends with projected demand drivers to derive compound annual growth rates. Key forecast inputs included pilot training hours, defense spending allocations, and Virtual Reality technology adoption rates.
Material uncertainties — such as geopolitical instability, rapid technological obsolescence, and shifts in aviation safety regulations — sit outside the modeled envelope. Forecasts reflect assumptions regarding current market dynamics and regulatory frameworks. Practitioners should keep alternative scenarios live as defense budgets and VR integration rates evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Simulation and Training
Drone Simulator Market
Simulation and Training
Civil Aviation Simulator Market
Simulation and Training
GNSS Simulators Market
Simulation and Training
Live Laser-Based Training and Simulation Platforms Market
Simulation and Training
Military Training Aircraft Market
Simulation and Training
Simulators Market
Simulation and Training
Military Vehicles and Aircraft Simulations Market
Simulation and Training
Europe Ship Bridge Simulators Market
Simulation and Training
Middle East Civil Aviation Flight Training and Simulation Market
Simulation and Training
Global Healthcare Games and Simulation Market
Simulation and Training
Middle East and Africa Ship Bridge Simulators Market
Simulation and Training
Police and Military Simulation Training Market
Simulation and Training
Military Simulation Software Market
Simulation and Training
Global Military Airborne Simulation and Training Market
Simulation and Training
Military Simulation Virtual Training Market
Simulation and Training
Military Aerospace Simulation and Training Market