
 Commercial Aircraft Market | 2026-2036
Commercial Aircraft Market Size, Share, and Industry Trends Forecast 2026-2036
Commercial Aircraft Market Analysis
EU Green Deal aviation mandates is realigning the cost-of-entry calculus for new airframe programs, forcing OEMs to front-load R&D spending on sustainable propulsion architectures. Airbus SE anchors European wide-body development through its A350 platform while sustaining composite manufacturing scale in Toulouse and Hamburg. Boeing Co. navigigates FAA certification timelines for its next narrow-body iteration, while COMAC positions its C919 as a state-backed alternative within China's domestic market.
Commercial aircraft are fixed-wing, powered vehicles designed for transporting passengers or cargo at altitudes exceeding 30,000 feet, with airframes typically combining aluminum alloys, carbon-fiber composites, and titanium in monocoque or semi-monocoque structural configurations. Narrow-body configurations dominate current delivery backlogs due to route fragmentation and hub bypass economics, while wide-body programs face extended replacement cycles as airlines prioritize capital discipline. Composite material penetration continues rising in wing and fuselage applications, though aluminum retains cost advantages in single-aisle programs where production rates exceed sixty units monthly.
FAA Part 25 airworthiness standards, EASA CS-25 certification requirements, and ICAO carbon offsetting rules collectively shape product development timelines, fleet retirement decisions, and market access conditions for non-compliant manufacturers. The EPA's emerging aircraft greenhouse gas standards will further constrain engine architecture choices for US-registered fleets. Stakeholders must monitor which regulatory jurisdiction achieves first-mover status on hydrogen propulsion certification, as this determination will cascade through global supply chain investment priorities.
Market Dynamics
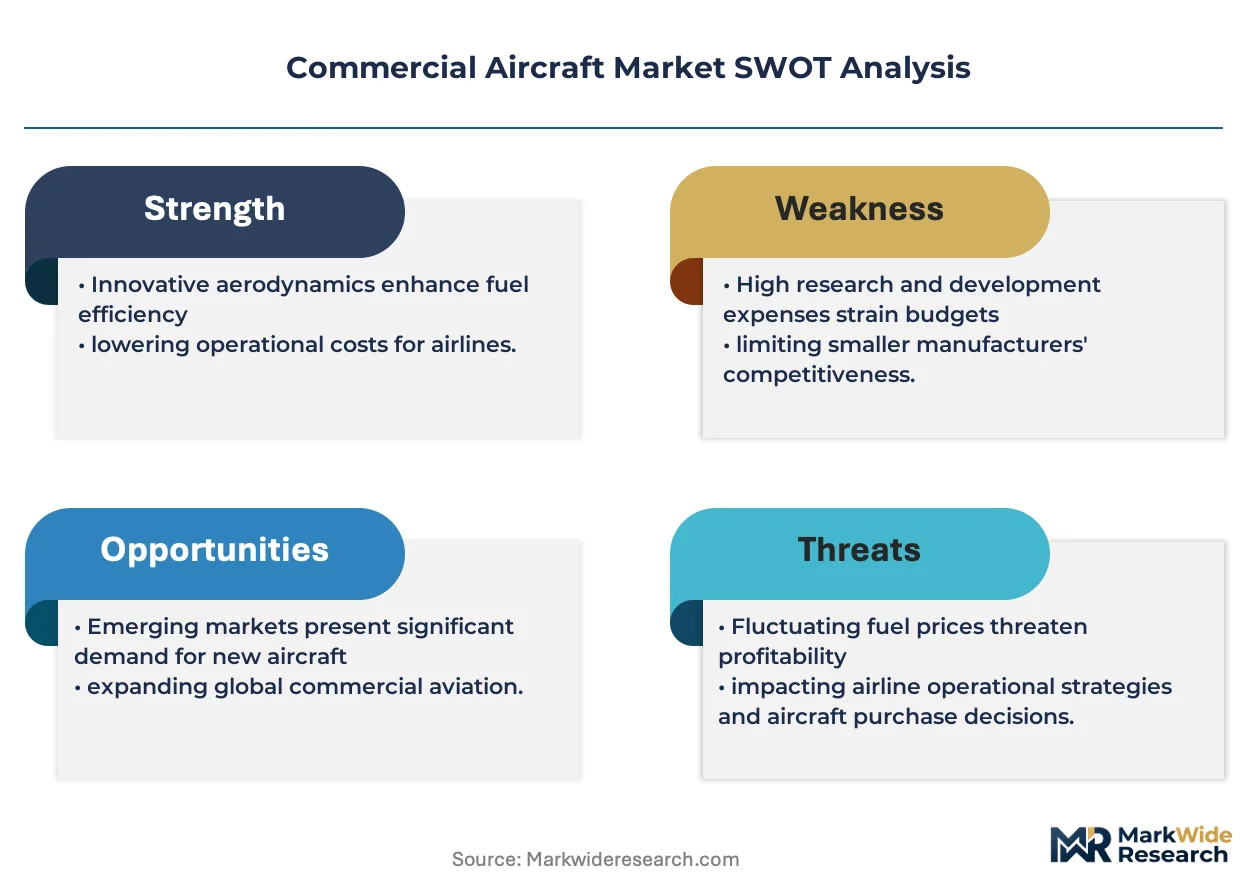
Post-pandemic fleet renewal cycles are colliding with FAA and EASA emissions mandates, forcing airlines to accelerate narrow-body replacements while OEMs absorb certification delays for sustainable propulsion architectures.
Growth Catalysts
- EU Green Deal aviation mandates:Binding carbon reduction targets are compelling European carriers to prioritize next-generation fuel-efficient aircraft in procurement decisions.
- Composite manufacturing scale:Automated fiber placement and resin transfer molding are cutting wing production costs, enabling higher-rate single-aisle output.
- Southeast Asia low-cost carrier expansion:VietJet, AirAsia, and Lion Air are placing multi-hundred-unit orders as passenger volumes exceed pre-pandemic levels.
Market Restraints
- Titanium supply concentration:Russian and Chinese dominance in sponge and mill products exposes Western OEMs to geopolitical supply disruptions.
- FAA Part 25 certification timelines:Extended review periods for novel propulsion systems are stretching program development cycles and freezing R&D budgets.
- Aluminum-lithium substitution ceiling:Mature alloy performance limits further weight reduction in single-aisle fuselage applications.
Strategic Opportunities
- India domestic aviation liberalization:UDAN regional connectivity schemes are stimulating demand for sub-150-seat aircraft from IndiGo and Akasa Air.
- Hydrogen propulsion certification first-mover advantage:EASA's exploratory rulemaking on cryogenic storage systems offers European OEMs regulatory arbitrage.
- Airframe MRO unbundling:Airlines are separating heavy maintenance from OEM service contracts, opening independent shop capacity.
Industry Challenges
- Aerospace composites technician shortage:Bonded repair certification programs are not producing qualified personnel at rates matching fleet growth.
- Engine-airframe integration complexity:Open-rotor and hybrid-electric architectures demand new collaborative development protocols between propulsion and airframe engineering teams.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Commercial Aircraft Market |
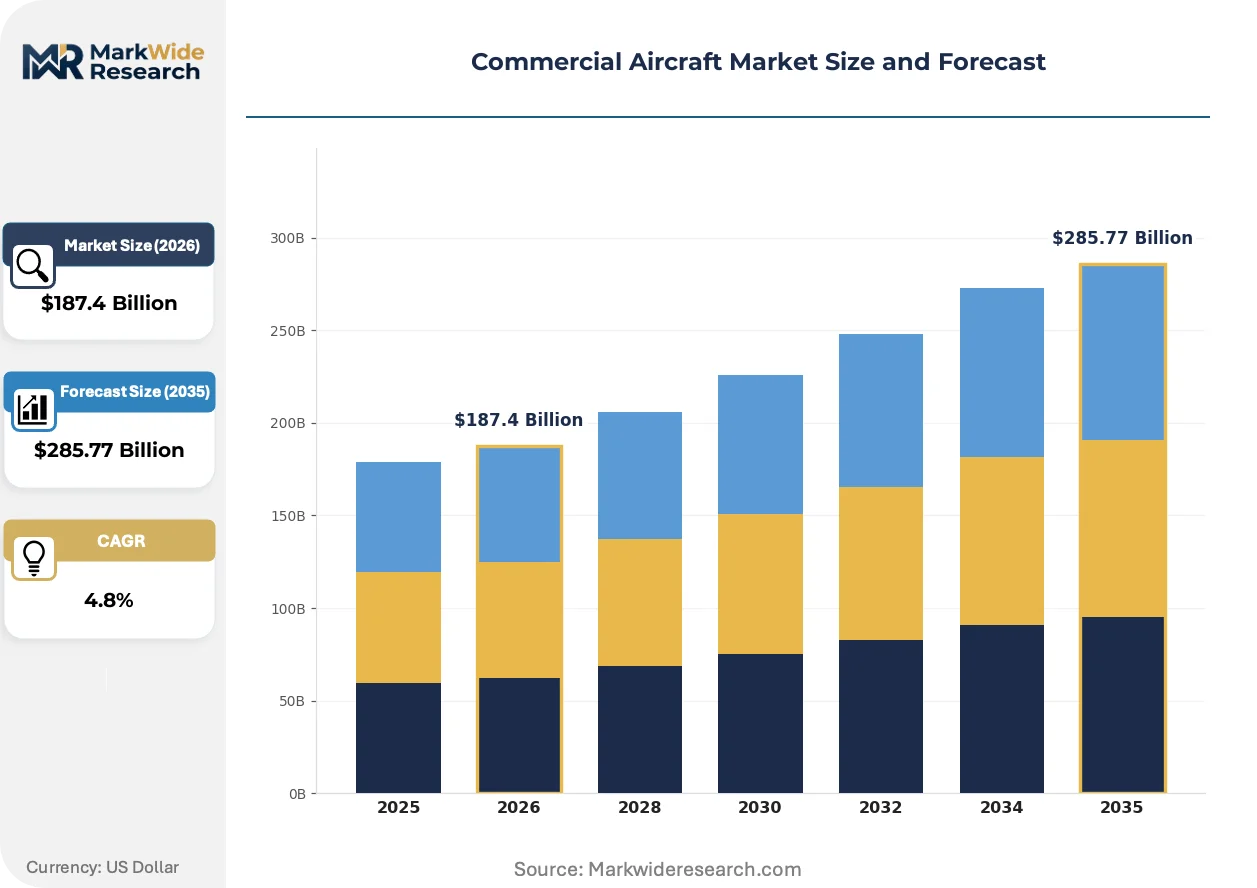
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $285.77 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Aircraft Type: Narrow-Body, Wide-Body, Regional, Cargo End User: Airlines, Leasing Companies, Government, Charter Operators Configuration: Single-Aisle, Twin-Aisle, All-Economy, Business-Class Material: Aluminum, Composite, Steel, Titanium |
| Companies Covered | The Boeing Co., Airbus SE, Embraer SA, Textron Aviation, Inc., Mitsubishi Aircraft Corporation, Bombardier, United Aircraft Corporation, ATR, COMAC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Commercial Aircraft Market Emerging Trajectories
Propulsion electrification and airframe digitization are converging to redefine performance benchmarks, while regulatory jurisdictions compete to set certification precedents for alternative fuels.
Thermoplastic composites are overtaking thermoset prepregs in wing and empennage applications. Airbus and tier-one suppliers are qualifying welded joints and automated assembly for A350 follow-on programs. This material transition is overtaking traditional autoclave curing, compressing cycle times and enabling out-of-autoclave manufacturing at lower energy intensity.
ICAO's Carbon Offsetting and Reduction Scheme for International Aviation is tightening emissions baselines for post-2028 deliveries. Airlines operating US-registered fleets face overlapping EPA aircraft greenhouse gas standards that constrain engine architecture choices. Wide-body programs serving transpacific routes are most affected, with carriers deferring retirement of younger four-engine aircraft to avoid premature capital deployment.
Power-by-the-hour contracts are fragmenting as lessors and institutional investors acquire direct exposure to residual value risk. Middle Eastern and Chinese leasing companies are displacing traditional bank-affiliated lessors in sale-leaseback transactions for narrow-body deliveries. This shift concentrates most visibly in Singapore and Dublin, where aviation finance clusters are expanding technical asset management capabilities.
Commercial Aircraft Market Segmentation
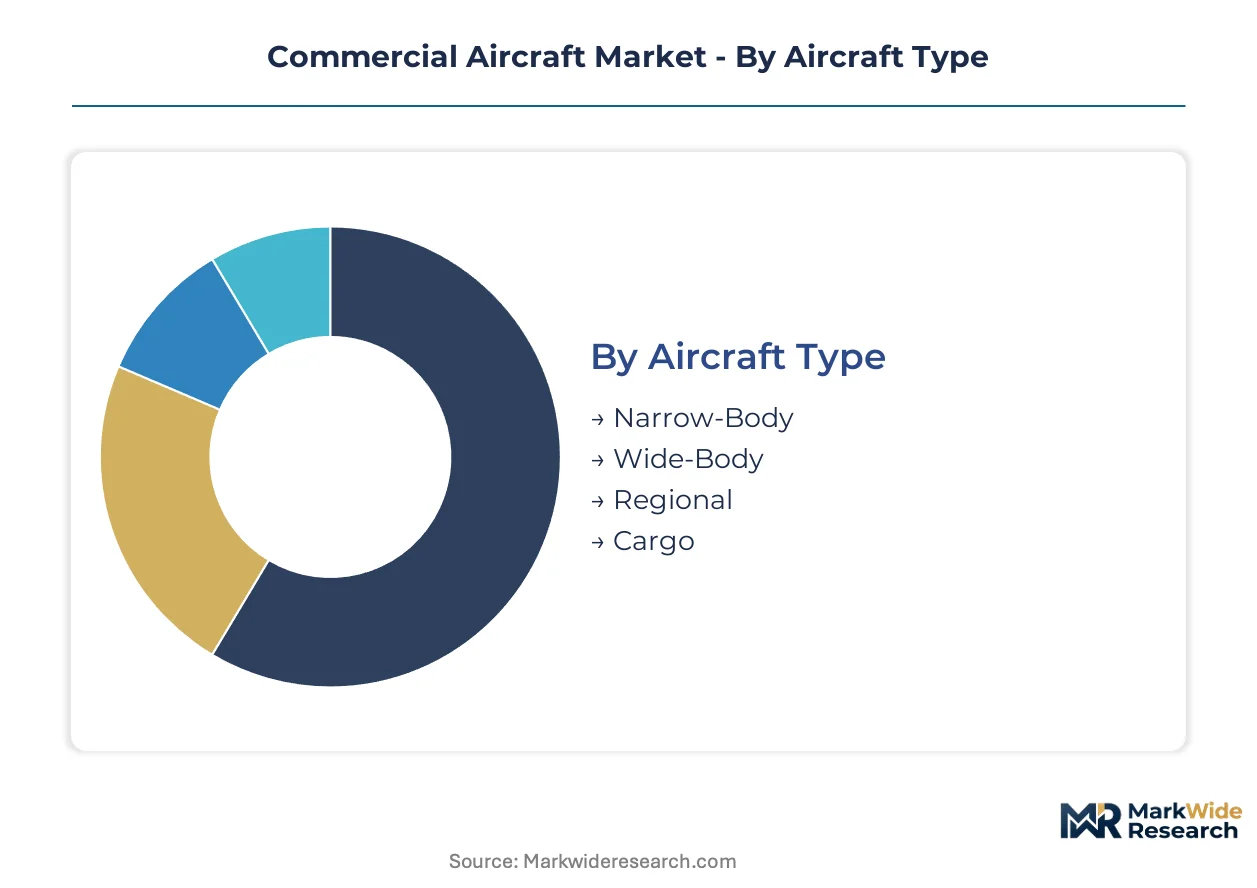
Commercial aircraft procurement patterns fragment sharply across operational missions, financing structures, and regulatory exposure profiles. Understanding these fault lines reveals where OEMs concentrate engineering resources and where aftermarket services extract margin.
Aircraft Type:
Supply concentration in final assembly tilts heavily toward narrow-body platforms where production rates exceed sixty units monthly at Toulouse and Renton facilities.
- Narrow-Body:Single-aisle configurations with 100-240 seat capacity dominate delivery backlogs. Route fragmentation and hub-bypass economics drive fleet renewal at VietJet, IndiGo, and Southwest Airlines as fuel efficiency mandates tighten.
- Wide-Body:Twin-aisle aircraft serving transpacific and long-haul trunk routes face extended replacement cycles. Airlines defer retirement of younger four-engine units to avoid premature capital deployment under overlapping EPA and ICAO emissions baselines.
- Regional:Sub-100-seat turboprops and regional jets serve thin routes under India's UDAN connectivity schemes and European public service obligations.
- Cargo:Dedicated freighter conversions and factory-built cargo variants capture e-commerce-driven belly-hold substitution demand at integrators and express carriers.
Today's leader: Narrow-Body. Tomorrow's challenger: Cargo.
End User:
Financing structure determines procurement velocity and specification flexibility across customer categories.
- Airlines:Network carriers and low-cost operators drive specification standardization. Southeast Asian LCCs place multi-hundred-unit orders with concentrated delivery slots to capture post-pandemic passenger volume recovery.
- Leasing Companies:Dublin and Singapore-based lessors acquire direct residual value exposure, displacing bank-affiliated players in sale-leaseback transactions for narrow-body deliveries.
- Government:State-owned carriers and military transport derivatives prioritize domestic industrial participation over pure cost optimization.
- Charter Operators:Ad-hoc capacity providers and VIP configuration specialists demand flexible cabin reconfiguration and extended maintenance intervals.
Airlines set specification standards. Lessors are climbing the fastest in transaction volume.
Configuration:
Passenger experience differentiation and turnaround efficiency create divergent engineering priorities.
- Single-Aisle:One central aisle maximizes seat density for LCC economics. Airbus A320neo and Boeing 737 MAX families anchor this segment with engine-airframe integration optimized for short-haul cycles.
- Twin-Aisle:Two aisles enable passenger boarding efficiency and galley/service cart mobility on routes exceeding eight hours. Premium cabin configurations concentrate revenue in forward compartments.
- All-Economy:Maximum density layouts at 28-29 inch pitch dominate ultra-low-cost carrier specifications and ACMI wet-lease deployments.
- Business-Class:Lie-flat seats and direct aisle access configurations command yield premiums on corporate-heavy routes and flag carrier long-haul services.
Single-Aisle captures volume. Business-Class captures yield expansion.
Material:
Weight-performance tradeoffs and supply security shape material selection across airframe programs.
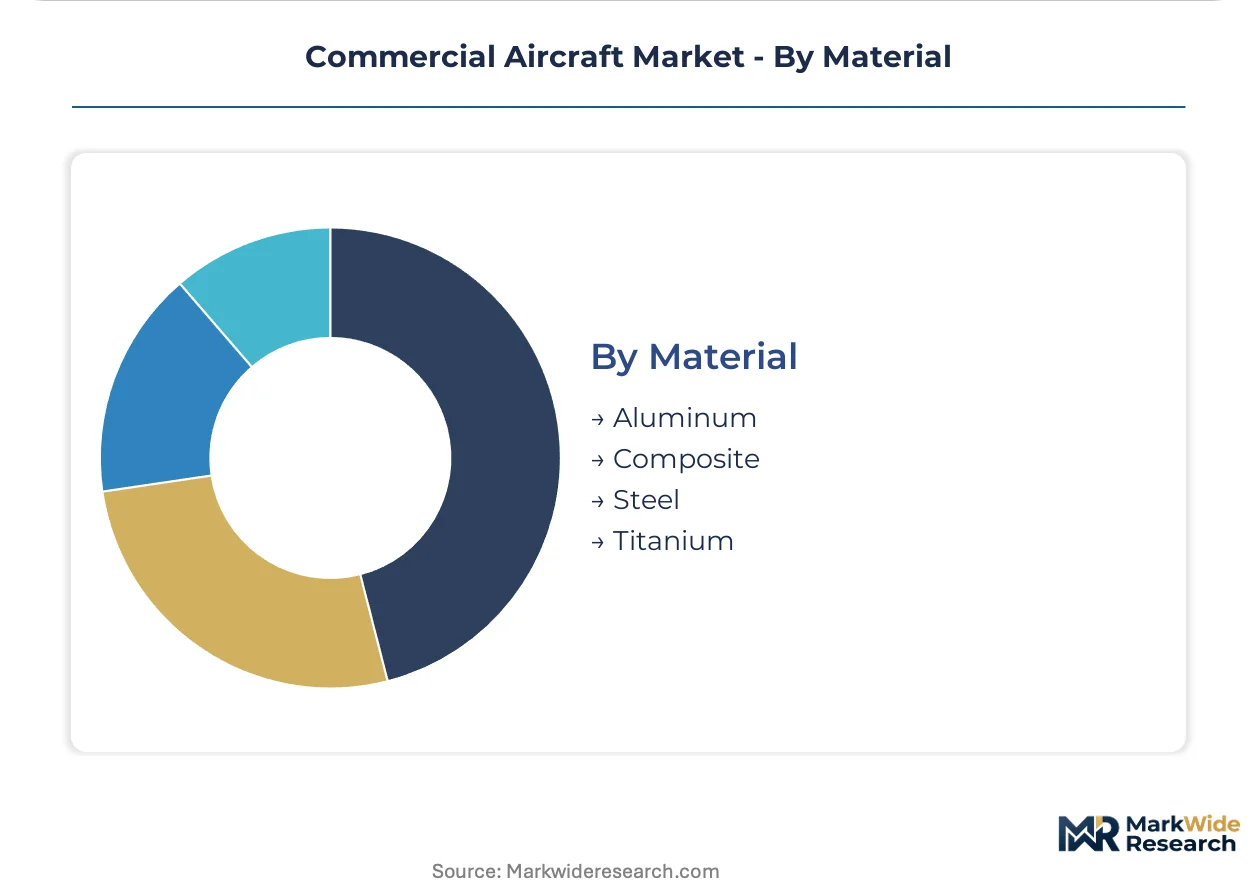
- Aluminum:Aluminum-lithium alloys retain cost advantages in single-aisle fuselage applications where mature alloy performance limits further weight reduction but production scale dominates economics.
- Composite:Carbon-fiber reinforced polymers penetrate wing and empennage applications as automated fiber placement cuts production costs. Thermoplastic composites overtake thermoset prepregs in next-generation programs.
- Steel:High-strength alloys concentrate in landing gear, engine mounts, and control surface actuation where fatigue resistance and impact tolerance outweigh weight penalties.
- Titanium:Russian and Chinese dominance in sponge and mill products exposes Western OEMs to geopolitical supply disruptions despite superior strength-to-weight ratios in engine and fastener applications.
Composite is gaining share fastest. Titanium supply concentration poses structural vulnerability.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Commercial aviation traces its industrial origins to the United States, where Boeing pioneered jetliner manufacturing in Seattle during the 1950s, establishing the template for integrated airframe-engine production that persists today.
United States
Boeing's 737 and 787 programs anchor final assembly in Renton, Washington, and North Charleston, South Carolina. FAA Part 25 certification timelines constrain development cycles for sustainable propulsion architectures. Wichita, Kansas hosts a dense cluster of aerostructures suppliers and business jet manufacturers including Textron Aviation.
France
Airbus SE operates its primary wide-body assembly in Toulouse and narrow-body production in Hamburg, Germany. EU Green Deal aviation mandates bind European carriers to carbon reduction targets that prioritize fuel-efficient fleet renewal. The Toulouse-Blagnac aerocluster concentrates composite manufacturing expertise and engine integration capabilities.
China
COMAC scales C919 production in Shanghai to capture domestic airline procurement previously directed at Western OEMs. The country's national aviation regulator certifies indigenous designs while airlines diversify supplier relationships beyond Boeing and Airbus. The Yangtze River Delta hosts expanding aerostructures and avionics supplier networks.
Brazil
Embraer SA dominates regional jet and executive aircraft segments from its São José dos Campos headquarters. ANAC, the national civil aviation agency, coordinates certification reciprocity with FAA and EASA for export market access. The São Paulo state aerospace cluster integrates composite component fabrication with final assembly operations.
Canada
Bombardier concentrated business aviation expertise in Montreal after divesting commercial aircraft programs. Transport Canada certification standards align with FAA harmonization agreements for North American market access. The Greater Montreal aerospace cluster maintains specialized capabilities in composite wing manufacturing and avionics integration.
Commercial Aircraft Market Vendor Landscape
The competitive structure tilts toward duopoly concentration at the wide-body and narrow-body tier, with regional and business aviation segments showing more fragmented participation. Two dominant strategic archetypes define the field: integrated airframe-engine OEMs controlling certification and final assembly, and tier-one aerostructures suppliers capturing subsystem value. Competitive moves center on geographic diversification of final assembly and vertical integration into composite materials production.
Among integrated OEMs, The Boeing Co. and Airbus SE occupy positions as the twin anchors of large commercial aircraft supply, while COMAC represents the state-backed challenger archetype targeting domestic market substitution. Embraer SA and Bombardier exemplify specialization strategies focused on regional connectivity and business aviation segments where production flexibility outweighs scale economics.
| Leading Market Players |
|---|
| The Boeing Co. |
| Airbus SE |
| Embraer SA |
| Textron Aviation, Inc. |
| Mitsubishi Aircraft Corporation |
| Bombardier |
| United Aircraft Corporation |
| ATR |
| COMAC |
| Others |
Supply Flow & Price Mechanics
Thermoplastic composite manufacturing transitions are simultaneously compressing wing production cycle times and concentrating tier-one supplier leverage in Toulouse and Hamburg aeroclusters. This dual effect reshapes how OEMs negotiate long-term offtake agreements and how airlines structure acquisition financing.
Pricing Analysis
Power-by-the-hour contracts versus unbundled heavy maintenance arrangements now define procurement economics across fleet categories. Three-tier pricing structure across premium, standard, and economy levels reflects engine thrust ratings, cabin configuration density, and residual value guarantees from Dublin and Singapore lessors. Pricing pressure stems from Southeast Asian LCC bulk orders compressing margins on single-aisle programs. Ultra-low-cost carriers exhibit highest price sensitivity, while flag carriers prioritizing brand differentiation show lowest.
Supply Chain Analysis
Domestic content mandates in China's C919 program and India's UDAN procurement requirements are forcing Western OEMs to localize aerostructures sourcing. Titanium sponge and mill products draw from Russian and Chinese suppliers, carbon-fiber prepregs feed from Japanese and US producers, and aluminum-lithium alloys rest on European and North American mills. Single-source vulnerability in titanium exposes final assembly schedules to geopolitical disruption. Distribution runs through airframe MRO networks that airlines are unbundling from OEM service contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Commercial aircraft procurement operates as a geographic-arbitrage play where EASA's exploratory hydrogen certification rulemaking offers European OEMs regulatory cost advantages unavailable to FAA-governed competitors.
For Market Incumbents: Deepen composite materials production in Toulouse and Hamburg to defend against COMAC's domestic-content advantages in Shanghai. Secure captive titanium supply through long-term offtake agreements with Australian and Japanese sponge producers to mitigate Russian supply disruption risk. Accelerate thermoplastic welding qualifications to compress A350 follow-on program cycle times.
For New Entrants and Emerging Players: Capture India's UDAN regional connectivity demand by positioning sub-150-seat platforms for IndiGo and Akasa Air procurement cycles. Target the freighter conversion segment where e-commerce belly-hold substitution creates white-space demand independent of passenger traffic recovery. Pursue EASA certification reciprocity pathways as the fastest regulatory entry mechanism.
For Investors and Strategic Acquirers: Valuations sit cheapest among independent aerostructures suppliers lacking composite manufacturing scale. Long-term viability hinges on 5-10 year fleet renewal cycles intersecting with emissions mandates. Watch EASA hydrogen propulsion certification timelines as the inflection signal for supply chain investment priority shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| Thermoplastic Composite Qualification | Airbus and tier-one suppliers are validating welded joints for A350 follow-on programs. |
| Domestic Content Localization | COMAC's C919 scaling forces Western OEMs to establish Shanghai aerostructures partnerships. |
| Hydrogen Storage Certification | EASA exploratory rulemaking on cryogenic systems offers European OEMs regulatory arbitrage. |
| Titanium Supply Diversification | Western OEMs are securing Australian and Japanese sponge to reduce Russian exposure. |
| Airframe MRO Unbundling | Airlines separating heavy maintenance from OEM contracts opens independent shop capacity. |
Methodological Framework
Multiple input streams — OEM program management interviews, airline fleet planning director discussions, and lessor technical asset manager consultations — were reconciled against FAA certification filings, EASA design approval databases, and ICAO emissions registry data. Secondary validation drew from customs trade records, aerostructures supplier SEC disclosures, and regional aviation authority production statistics. Bottom-up delivery backlog analysis and top-down fleet projection models were cross-referenced to establish market sizing.
Historical delivery patterns were cross-referenced against panel input from procurement executives at VietJet, IndiGo, and AirAsia. Segmentation dimensions modeled include aircraft type, end-user financing structure, configuration density, and material composition across the projection horizon. CAGRs were derived from production rate assumptions at Toulouse, Renton, and Shanghai facilities intersecting with regulatory mandate compliance timelines. Forecast inputs incorporated composite manufacturing scale economics and titanium supply concentration risk factors.
Geopolitical supply disruption, regulatory certification delays, and alternative propulsion technology readiness are the dominant revision risks to modeled outputs. Forecasts reflect documented assumptions regarding fleet retirement schedules and emissions baseline compliance. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft
Global Commercial Aircraft Seat Actuation Market
Aircraft
North America Turboprop Aircraft Market
Aircraft
Europe Freighter Aircraft Market
Aircraft
Global Ultralight and Light Aircraft Market
Aircraft
Middle-East and Africa Turboprop Aircraft Market
Aircraft
LAMEA Aircraft Band Clamps Market
Aircraft
Anti Rolling Gyro (ARG) Market
Aircraft
Commercial Aircraft Aerostructures Market
Aircraft
Global Aircraft Transparencies Market
Aircraft
America Freighter Aircraft Market
Aircraft
Turboprop Aircraft Market
Aircraft
Airplane Landing Gear Market
Aircraft
Latin America Business Jet Market
Aircraft
Global LW Sport Aircraft Market
Aircraft
Europe Business Jet Market
Aircraft
Commercial Aircraft Fadec Market