
 Air Starter Market | 2026-2036
Air Starter Market Size, Share, and Industry Trends Forecast 2026-2036
Air Starter Market Intelligence
The shift toward specialized third-party maintenance and repair organizations is rewriting traditional distribution models, bypassing original equipment manufacturer channels. Ingersoll Rand leverages its extensive service network to capture this aftermarket segment. Caterpillar sustains its market position through integrated equipment and service packages for its heavy machinery. Honeywell International Inc. specializes in high-reliability starters for auxiliary power units and specific industrial applications, differentiating on performance criteria.
An air starter is a pneumatic device that converts compressed air energy into mechanical motion to crank large diesel or gas engines. These systems operate at high pressures, typically between 90 and 150 PSI, delivering significant torque to overcome engine inertia. Pneumatic product types remain the dominant category due to their reliability in hazardous environments, while turbine technology sees uptake for its high power-to-weight ratio. Within applications, marine engines and power generation represent the largest segments, driven by uptime requirements in critical infrastructure.
Compliance with ISO 9001 quality management standards is a baseline for market entry and global trade. In the United States, OSHA regulations govern the safe use of pneumatic equipment in industrial settings, while CE marking is mandatory for products sold in the European Union. The key decision for manufacturers will be balancing investment in legacy pneumatic systems against developing next-generation hybrid or electric starter solutions to meet evolving efficiency demands.
Market Dynamics
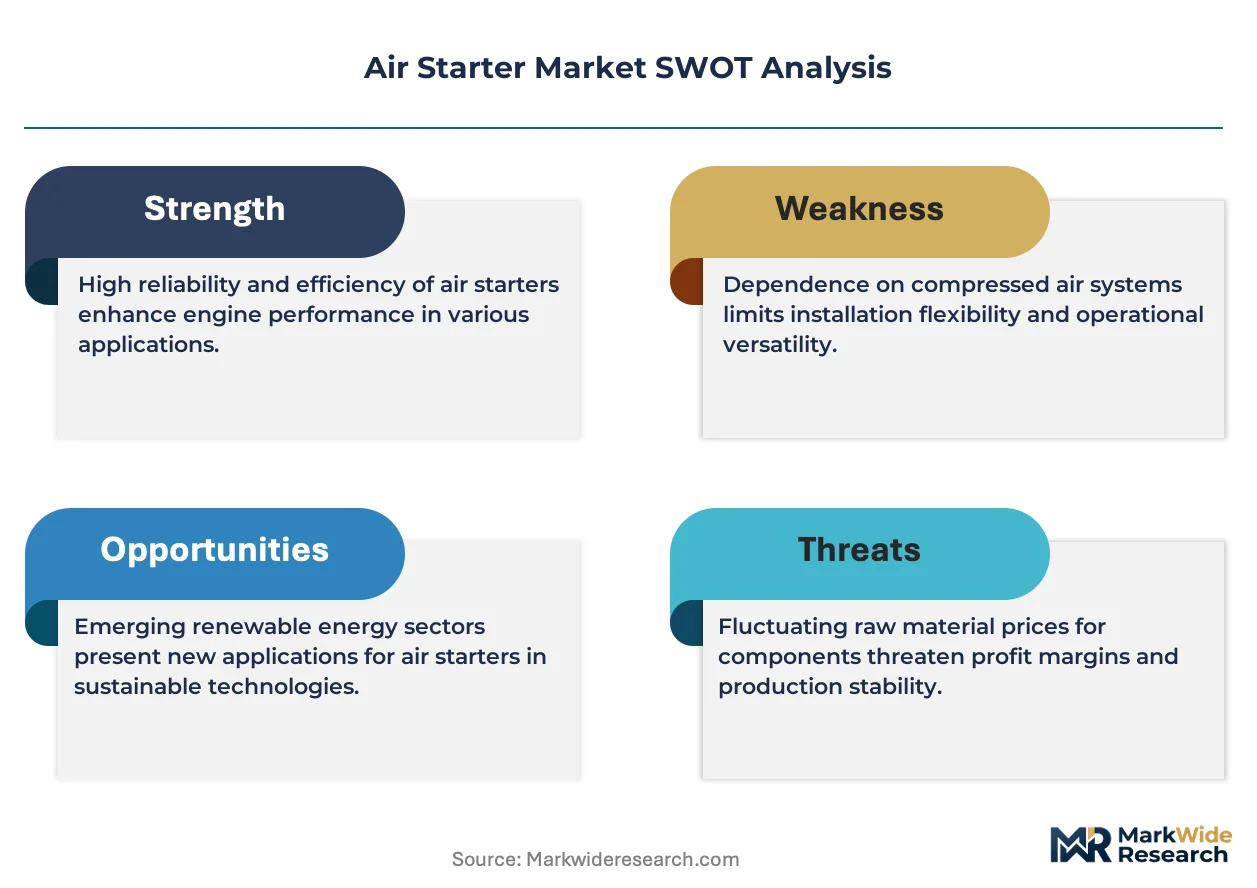
The central force shaping the air starter market is the tension between stringent environmental mandates demanding greater engine efficiency and the unyielding requirement for high-torque, reliable starting solutions in critical infrastructure sectors like power generation and marine transport.
Growth Catalysts
- Stricter Emission Frameworks:Regulations under the EU Green Deal and similar international maritime standards are compelling engine manufacturers to adopt more efficient auxiliary components, including modern turbine air starters, to reduce overall fuel consumption and emissions.
- Infrastructure Development in Asia:Major public and private investments in port facilities, power plants, and mining operations in countries such as Indonesia are creating sustained demand for reliable engine starting systems for heavy machinery and vessels.
- Inherent Safety in Hazardous Environments:The non-sparking nature of pneumatic systems continues to drive their adoption in oil and gas exploration, chemical plants, and underground mining, where the risk of igniting flammable atmospheres precludes the use of electric starters.
Market Restraints
- High Initial System Cost:The significant capital investment required for a complete compressed air system, including compressors, storage tanks, and high-pressure lines, acts as a barrier for smaller operators when compared to self-contained electric starting systems.
- Rise of Electric and Hybrid Alternatives:Advances in battery technology and high-power electric motors present a viable substitution threat, particularly for medium-duty diesel engines where the extreme torque of an air starter is not a strict requirement.
- Maintenance and Air Quality Sensitivity:System performance is highly dependent on a clean, dry supply of compressed air, requiring diligent maintenance of filters and dryers to prevent internal corrosion and component failure, which adds to operational complexity.
Strategic Opportunities
- Fleet Modernization and Retrofitting:A significant opportunity exists in upgrading older marine vessels and locomotives with newer, more efficient air starter models to meet contemporary emissions regulations and improve fuel economy without complete engine replacement.
- Hybrid Starter System Development:Combining the high torque of pneumatic starters with the precise control of electric systems offers a path to new product categories that provide both power and efficiency for next-generation large-bore engines.
- Expansion into Data Center Backup Power:The global build-out of data centers creates a new application segment for high-reliability air starters for emergency diesel generators, where instant and dependable starting is non-negotiable.
Industry Challenges
- Pneumatic Systems Skill Gap:A diminishing pool of technicians with specialized expertise in diagnosing and repairing high-pressure pneumatic systems poses an operational challenge, especially as the aftermarket shifts toward independent service organizations.
- Navigating Fragmented Certifications:Manufacturers face increased compliance costs and longer lead times to secure necessary approvals, such as CE marking for the European market and adherence to OSHA standards for industrial use in the United States.
- Legacy System Integration:Ensuring backward compatibility of new, technologically advanced air starters with a wide array of older engine models and existing, on-site compressed air infrastructures presents a considerable engineering challenge.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Air Starter Market |
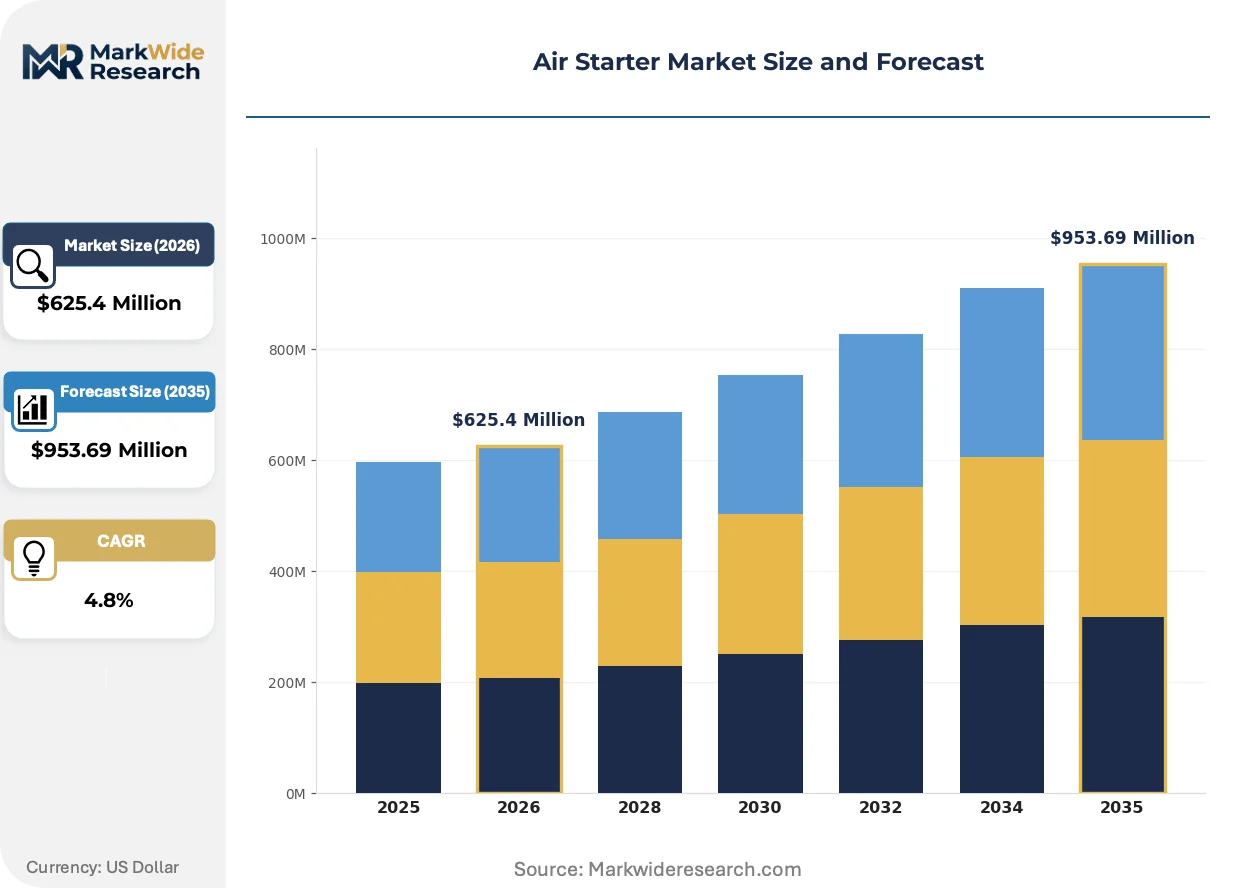
| Market Size in 2026 | $625.4 Million |
| Market Size in 2035 | $953.69 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pneumatic, Electric, Hydraulic, Hybrid, Spring-Loaded Technology: Direct Drive, Geared Drive, Rotary Vane, Turbine, Diaphragm Application: Marine Engines, Construction Equipment, Power Generation, Locomotive Engines, Agricultural Machinery End User: Engine Manufacturers, Equipment Rental Firms, Power Plant Operators, Railway Companies, Farming Cooperatives |
| Companies Covered | Honeywell International Inc., Gali, Ingersoll Rand, Industrial Power Units, Maradyne, Caterpillar, TDI, Dusterloh Fluidtechnik, Rheinmetall, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Air Starter Market Strategic Shifts & Innovations
A convergence of digital monitoring technologies and evolving service models is reshaping the lifecycle management of air starter systems. This shift prioritizes predictive maintenance and operational uptime over traditional component sales, altering the competitive landscape for both OEMs and aftermarket suppliers.
Onboard diagnostics and sensor integration are becoming standard features in modern air starters. These systems monitor operational parameters like pressure, cycle count, and pinion engagement speed, providing real-time data on starter health. End-users in the marine and power generation sectors are the primary adopters, seeking to preempt failures in critical equipment. This technology is digitizing the maintenance workflow, enabling a shift from fixed-schedule overhauls to condition-based servicing that maximizes asset life.
The European Union’s Green Deal framework is accelerating the enforcement of emission limits for non-road mobile machinery, directly impacting engine system design. This policy forces equipment manufacturers to account for the energy consumption of all auxiliary components, including starters. The marine and off-highway vehicle segments are most affected, responding by specifying lighter, more efficient turbine-type air starters to contribute to overall fuel economy and compliance goals.
A behavioral shift among end-users sees them increasingly sourcing starters and service from independent MRO specialists rather than exclusively through engine OEMs. This unbundling of component procurement from the primary equipment purchase disrupts traditional, closed-loop distribution channels. The trend is most visible in the North American oil and gas sector and Southeast Asian maritime hubs, where uptime and specialized service expertise are primary decision drivers.
Air Starter Market Segmentation
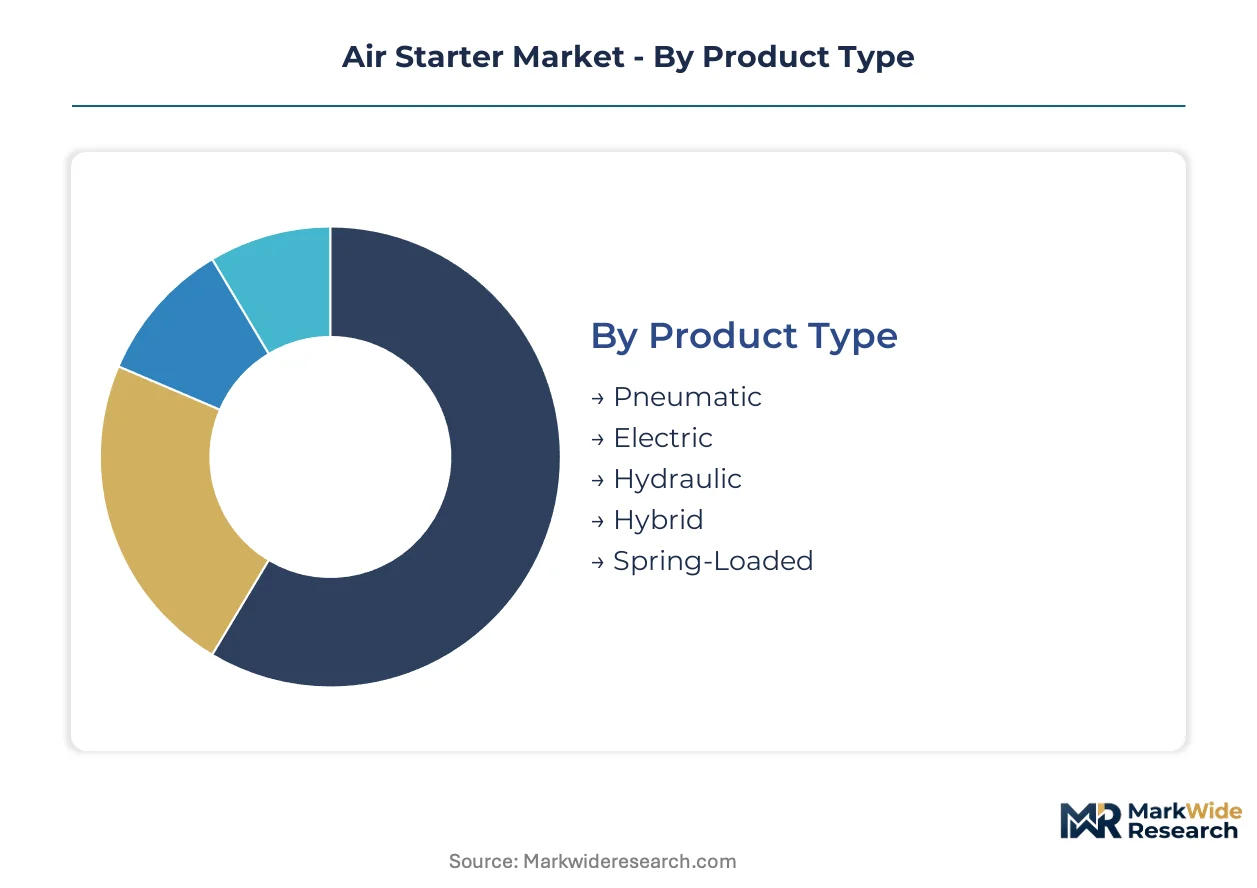
Understanding the air starter market through its core segments reveals how different product types and technologies address specific operational demands. This segmentation provides clarity on where innovation is most impactful and where established solutions maintain their dominance across various end-use sectors.
Product Type:
The product type segmentation highlights the varying operational lifecycles, with some pneumatic systems offering decades of reliable service while hybrid solutions represent faster turnover for next-generation engines.
- Pneumatic:These devices convert compressed air energy into mechanical motion, operating at high pressures to deliver significant torque for large engines. Demand concentrates in hazardous environments like oil and gas exploration, where the non-sparking nature prevents ignition of flammable atmospheres.
- Hybrid:Combining the high torque of pneumatic starters with the precise control of electric systems, hybrid solutions offer both power and efficiency. This technology is gaining traction for next-generation large-bore engines, particularly where evolving efficiency demands require optimized starting.
- Electric:Utilizing battery power to crank engines, electric starters are common for medium-duty diesel applications where the extreme torque of an air starter is not strictly necessary.
- Hydraulic:Hydraulic starters deliver high power density through pressurized fluid, finding use in heavy-duty industrial applications requiring robust and reliable starting.
- Spring-Loaded:These manual backup systems are typically used for smaller engines or in remote locations where external power sources are unavailable.
Pneumatic solutions anchor the volume base while Hybrid technology gains share at the steepest rate.
Technology:
Technology differentiation within air starters dictates their suitability for specific applications, influencing performance characteristics and operational longevity across diverse industrial settings.
- Turbine:These starters feature a high power-to-weight ratio and efficient operation, making them suitable for applications in marine engines and power generation. The technology helps meet stringent emission limits for non-road mobile machinery.
- Rotary Vane:Known for their robust design and reliability in demanding conditions, rotary vane starters are widely adopted in the oil and gas sector and mining operations. Their inherent durability ensures consistent performance in harsh environments.
- Direct Drive:Direct drive starters offer a simple design and cost-effective solution, primarily serving smaller engine applications where high torque requirements are less critical.
- Geared Drive:Incorporating gearing to increase torque output, geared drive starters are preferred for larger industrial engines needing substantial cranking power.
- Diaphragm:Diaphragm starters operate effectively at lower pressures, finding specialized applications in certain small engine categories where their unique characteristics are beneficial.
Turbine technology demonstrates the most rapid expansion, driven by efficiency mandates, while Rotary Vane designs maintain consistent demand in critical sectors.
Application:
The application segments illustrate where the highest demand for air starters originates, highlighting critical infrastructure sectors that prioritize uptime and reliability above all else.
- Marine Engines:Air starters are essential for large vessels, ensuring critical uptime and compliance with international maritime standards. The global shipping industry consistently drives significant demand for these robust starting systems.
- Power Generation:This segment includes standby and primary power systems for facilities like data centers, where instant and dependable starting of emergency diesel generators is non-negotiable. Power plant operators rely on air starters for critical infrastructure.
- Construction Equipment:Heavy machinery used in large-scale infrastructure development projects, particularly in countries like Indonesia, relies on air starters for consistent operation.
- Locomotive Engines:Rail transport systems utilize air starters for their large diesel engines, supporting fleet modernization efforts and ensuring reliable service.
- Agricultural Machinery:Large farm equipment and machinery in the agricultural sector depend on air starters for dependable operation, especially in remote environments.
Marine Engines and Power Generation applications represent the largest and most stable segments, while Construction Equipment shows substantial growth linked to global infrastructure investments.
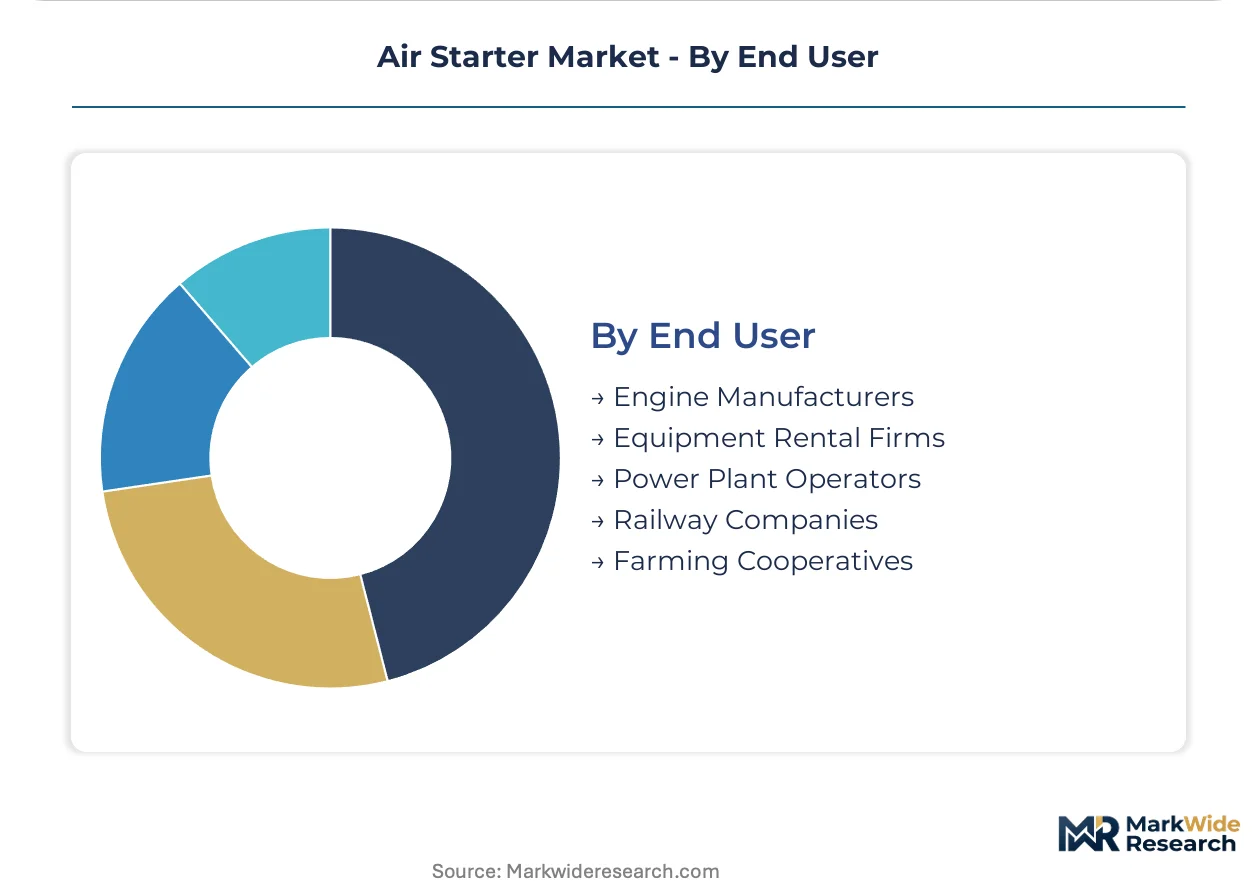
End User:
The end-user classification reveals the diverse customer base for air starters, ranging from original equipment integration to specialized aftermarket service providers.
- Engine Manufacturers:These entities integrate air starters into new engine designs, ensuring compatibility and compliance with efficiency mandates. They often influence component selection for auxiliary equipment.
- Power Plant Operators:Responsible for critical infrastructure, these operators prioritize high-reliability air starters for emergency diesel generators and primary power systems. Their procurement decisions emphasize dependability and regulatory adherence.
- Equipment Rental Firms:Managing diverse fleets of machinery, these firms require robust and easily maintainable air starters to ensure operational flexibility for their customers.
- Railway Companies:Operating extensive locomotive fleets, railway companies procure air starters for scheduled maintenance and new installations, focusing on safety regulations and long-term durability.
- Farming Cooperatives:These organizations purchase air starters for agricultural machinery, balancing seasonal demand with the need for reliable starting in remote field operations.
Engine Manufacturers set the initial market baseline, while Power Plant Operators drive demand for high-reliability, long-lifecycle solutions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The enforcement of stringent environmental mandates, such as the EU Green Deal, significantly influences the Air Starter Market. These global frameworks compel engine manufacturers to integrate more efficient auxiliary components, including modern turbine air starters. Compliance requirements shape product development and market demand across diverse industrial applications.
United States
Demand for air starters in the United States stems from its robust oil and gas sector and extensive power generation infrastructure. OSHA regulations strictly govern the safe use of pneumatic equipment within industrial settings, ensuring compliance. The Gulf Coast region, with its numerous offshore platforms and refineries, drives substantial requirements for non-sparking pneumatic systems.
Germany
European Union directives, including the EU Green Deal, drive the adoption of efficient air starters for non-road mobile machinery. CE marking is mandatory for all products sold in the European Union, influencing design and manufacturing processes. Industrial clusters in Bavaria, particularly around automotive and machinery manufacturing, integrate advanced air starter systems into heavy equipment.
Indonesia
Significant infrastructure development projects and maritime expansion in Indonesia create sustained demand for reliable engine starting systems. The country's national port development programs require robust air starters for new vessels and port machinery. Major investments in Jakarta's infrastructure and resource extraction sites across Kalimantan necessitate durable pneumatic solutions.
China
China's vast manufacturing base and expanding power generation capacity fuel considerable demand for industrial air starters. The country's dual carbon goals encourage the adoption of more efficient engine auxiliary components. Large industrial zones in the Yangtze River Delta, supporting heavy machinery and marine engine production, constitute a significant market.
India
Infrastructure modernization and growth in the marine sector are primary demand drivers for air starters in India. The Ministry of Shipping's Sagarmala program promotes port-led development, increasing the need for dependable starting solutions. Major shipbuilding facilities in Mumbai and Visakhapatnam consistently procure high-torque air starters for marine engines.
Air Starter Market Key Industry Players
On the supply side, the industry is characterized by a blend of large, diversified industrial players and specialized pneumatic equipment manufacturers. Several strategic archetypes emerge, including integrated equipment providers, pure-play air starter specialists, and aftermarket service network operators. Competitive positioning hinges on leveraging extensive service capabilities, offering comprehensive equipment and service packages, and pursuing product innovation for enhanced efficiency. This dynamic landscape also sees players focusing on regional market penetration and technology licensing.
At the enterprise-level end of the spectrum, companies such as Ingersoll Rand exemplify broad industrial reach, leveraging extensive service networks to capture significant aftermarket segments. Caterpillar, a major equipment manufacturer, sustains its market position by offering integrated equipment and service packages for its heavy machinery. Honeywell International Inc. occupies a specialized niche, focusing on high-reliability starters for auxiliary power units and specific industrial applications; its differentiation centers on meeting stringent performance criteria for critical systems.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| Gali |
| Ingersoll Rand |
| Industrial Power Units |
| Maradyne |
| Caterpillar |
| TDI |
| Dusterloh Fluidtechnik |
| Rheinmetall |
| Others |
Cost & Logistics Intelligence
China's vast manufacturing base for engine components heavily influences air starter production costs, impacting downstream pricing for both original equipment manufacturers and aftermarket suppliers. This concentration determines where value accrues across the air starter market.
Pricing Analysis
Volume-based discounts characterize air starter pricing across different customer segments, reflecting the scale of procurement. Pricing stratifies across premium, standard, and economy tiers, driven by factors such as ISO 9001 certification, brand reputation, and the extent of after-sales service bundles. Pricing pressure stems from the increasing viability of electric and hybrid alternatives, especially for medium-duty applications. Equipment rental firms exhibit the highest price sensitivity, whereas power plant operators prioritize reliability and performance over cost, demonstrating lower price sensitivity.
Supply Chain Analysis
Extended payment terms are common within the air starter supply chain, reflecting the capital-intensive nature of component manufacturing. Geographic supply concentration for specialized parts is evident in countries like China for general components and Germany for precision engineering, with final assembly often occurring in the United States. The market relies on specific inputs such as high-pressure valves, robust pneumatic motors, and specialized castings. A structural risk exists in potential single-source vulnerability for highly specialized components. Distribution runs through both traditional OEM channels and a rapidly expanding network of specialized third-party maintenance and repair organizations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The air starter market is approaching a platform-economics inflection, driven by the integration of onboard diagnostics and sensor data into broader engine management ecosystems. This interoperability shifts value from hardware to predictive maintenance services.
For Market Incumbents:Insulate existing market share by accelerating research and development into next-generation hybrid starter solutions. This move counters the threat from purely electric alternatives and positions firms for evolving efficiency mandates. Expand and deepen service network capabilities to capture the growing aftermarket segment, which is increasingly bypassing traditional OEM channels. Invest in advanced material science to reduce weight and improve durability of core pneumatic components.
For New Entrants and Emerging Players:Underpenetration in specialized MRO services within Southeast Asian maritime hubs offers a clear entry point for new market participants. Target the data center backup power segment, which demands ultra-high reliability and instant starting capabilities. A focused go-to-market angle involves offering specialized service contracts with guaranteed uptime metrics, leveraging advanced diagnostic tools for predictive maintenance in critical infrastructure applications.
For Investors and Strategic Acquirers:Secondary-cycle assets sit with pure-play air starter specialists and established MRO providers, offering stable cash flows from critical infrastructure. The long-term viability of the air starter market is secured by the unyielding demand for high-torque starting solutions in marine and power generation. Acquisition targets should include firms with strong intellectual property in turbine technology or extensive certified service networks. The signal to watch is increased adoption rates of hybrid starter systems in new large-bore engine designs.
| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Starter System Development | Addresses evolving efficiency demands for next-generation large-bore engines. |
| Aftermarket Service Network Expansion | Captures market share from engine OEMs through specialized MRO expertise. |
| Digital Monitoring Integration | Improves operational uptime for marine and power generation critical equipment. |
| Regional Manufacturing Localization | Mitigates supply chain risks from concentrated component sourcing in Asia. |
| Compliance Certification Investment | Ensures market access in regulated regions like the European Union and United States. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted through primary interviews to gather qualitative insights into air starter market dynamics. Stakeholders included maintenance directors from power plants, engine manufacturers' procurement teams, and marine vessel operators. This primary data was validated against secondary sources such as ISO standards, OSHA regulations, EU Green Deal policy documents, and national infrastructure project databases, ensuring robust bottom-up and top-down triangulation.
Quantitative models were calibrated using a blend of historical performance data and projected market shifts across the analysis window. The analytical framework incorporated segmentation dimensions such as product type, technology, application, end user, and regional regulatory compliance. Compound annual growth rates were derived from historical trends and projected market shifts, factoring in industry-specific inputs like engine production forecasts and infrastructure development spending.
The forecast holds incumbent behavior within observed patterns; aggressive moves by hybrid starter innovators or major engine OEMs would shift outcomes. Forecasts reflect assumptions regarding regulatory stability and technological progression. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft
Aircraft Cargo Winches Market
Aircraft
Autonomous Aircraft Propulsion Systems Market
Aircraft
North America Aviation Market
Aircraft
US Aviation Market
Aircraft
Airplane Landing Gear Market
Aircraft
Fixed Wing Turbine Aircraft Market
Aircraft
Global LW Sport Aircraft Market
Aircraft
Evtol (Electric Vertical Takeoff and Landing) Airplane Market
Aircraft
Europe Aircraft Manufacturing Market
Aircraft
Commercial Aircraft Lighting Market
Aircraft
Airplane Brackets Market
Aircraft
America Freighter Aircraft Market
Aircraft
Sailplane Market
Aircraft
Europe Attack Helicopter Market
Aircraft
Evtol Aircraft Market
Aircraft
Asia-Pacific Attack Helicopter Market