
 Military Trainer Aircraft Market | 2026-2036
Military Trainer Aircraft Market Size, Share, and Industry Trends Forecast 2026-2036
Military Trainer Aircraft Market Outlook
Carbon fiber reinforced polymer is consolidating its position in airframe structures, displacing conventional aluminum alloys in next-generation trainer designs to reduce weight and extend airframe life. Leonardo S.p.A. leverages integrated aerostructures capabilities across its Italian manufacturing base to control composite fabrication costs. Korea Aerospace Industries Ltd. anchors its T-50 family with domestic supply chain density that sustains competitive export pricing. BAE Systems plc navigates UK defense procurement cycles while extending Hawk platform relevance through avionics refresh programs.
Military trainer aircraft are fixed-wing platforms designed for pilot instruction, typically featuring dual cockpits with instructor override controls, ejection seats rated for zero-zero conditions, and thrust-to-weight ratios between 0.3 and 0.6 to simulate fighter handling characteristics. Jet trainer configurations lead procurement volumes among air forces transitioning pilots to supersonic combat aircraft, while advanced trainer variants with fly-by-wire systems capture expanding margin pools as operators demand fighter-congruent handling. Digital cockpit technology segments are gaining fastest as glass-panel avionics replace analog instrumentation across refurbishment programs and new-build contracts.
The US Federal Aviation Administration coordinates military airworthiness certification with the Air Force and Navy through the MIL-HDBK-516 framework, while the EU AI Act and CE marking requirements increasingly govern embedded simulation software exports from European suppliers. India's Directorate General of Aeronautical Quality Assurance enforces indigenous content mandates that shape vendor selection for the country's HTT-40 and intermediate jet trainer competitions. Stakeholders must monitor how evolving sovereign content rules and software export controls will determine platform eligibility in the largest replacement cycles.
Market Dynamics
Fourth- and fifth-generation fighter inductions across Southeast Asian and Middle Eastern air forces are compressing training pipelines and forcing procurement cycles toward platforms with fighter-congruent handling characteristics. Synthetic training environments are displacing live-flight hours in early-stage instruction, altering fleet sizing calculations and platform longevity requirements.
Growth Catalysts
- Fleet Modernization Mandates:Air forces in India, Saudi Arabia, and Poland are replacing Soviet-era trainers with advanced jet platforms capable of supersonic transition training. These programs create immediate procurement volume.
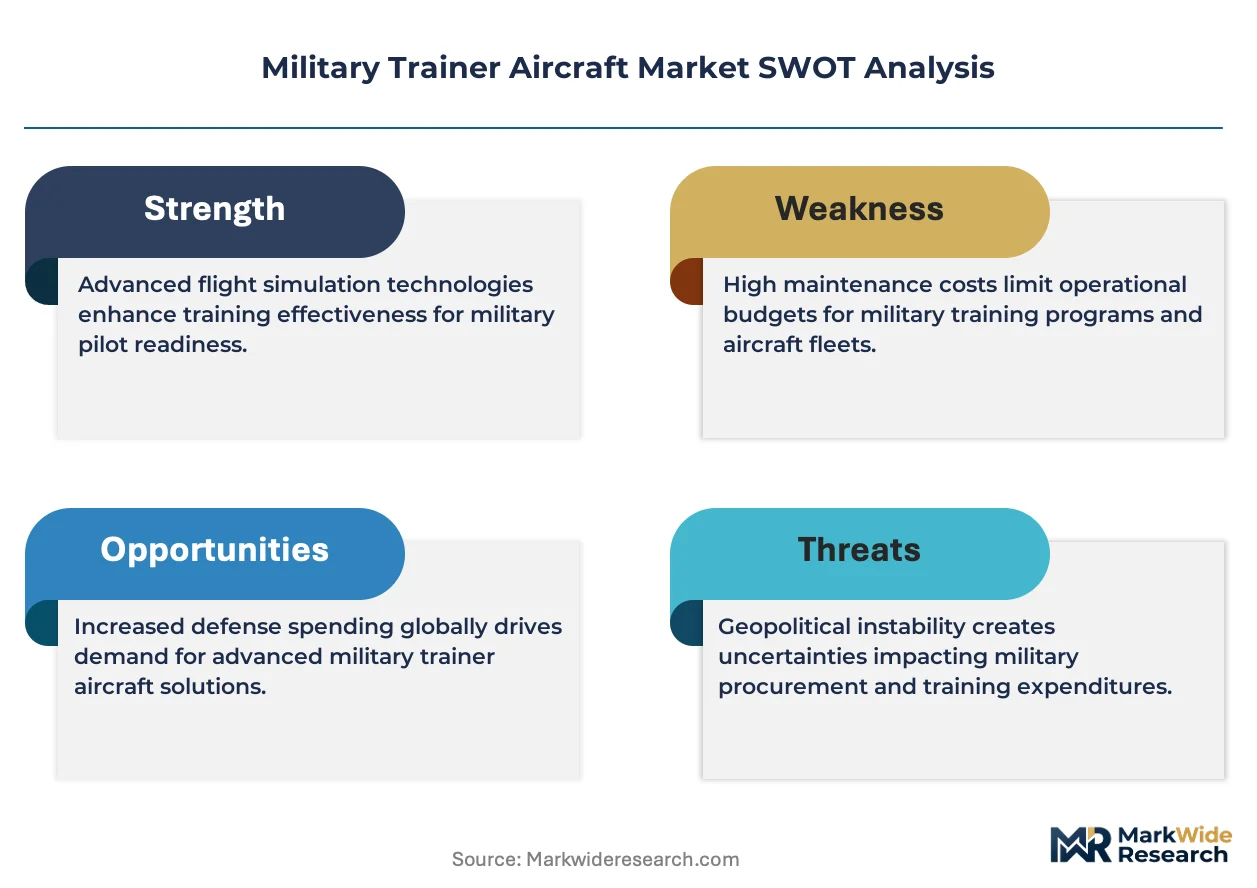
- MIL-HDBK-516 Framework:The US FAA coordination with military airworthiness authorities streamlines certification pathways for platforms seeking export eligibility. This reduces time-to-contract for qualifying suppliers.
- Carbon Fiber Reinforced Polymer Adoption:Composite airframe structures extend service life while reducing weight, enabling higher G-force training profiles that simulate modern fighter envelopes.
Market Restraints
- Titanium and Nickel Alloy Volatility:Engine hot-section components depend on aerospace-grade superalloys concentrated in limited supplier bases. Price swings compress margins on fixed-price trainer contracts.
- Indigenous Content Mandates:India's DGAA enforcement of local sourcing thresholds disqualifies fully foreign-built platforms from HTT-40 and intermediate jet trainer competitions. This fragments addressable market segments.
- Software Export Control Friction:The EU AI Act and CE marking requirements for embedded simulation systems create compliance overhead for European suppliers exporting to non-European operators.
Strategic Opportunities
- Polish Training Infrastructure Gap:Warsaw's accelerated F-35 delivery schedule has outpaced compatible trainer procurement, creating near-term demand for advanced platforms with integrated sensor simulation.
- Convergence of AR and Live-Flight Training:Augmented reality helmet displays overlaid on actual cockpit environments bridge the fidelity gap between synthetic and airborne instruction. Early adopters in Gulf Cooperation Council states are funding development.
- Performance-Based Logistics Contracts:Availability-guaranteed service models replace traditional spares procurement, opening recurring revenue streams for platform OEMs with established regional depot networks.
Industry Challenges
- Zero-Zero Ejection Seat Certification Bottlenecks:Martin-Baker and Saab dominate qualified seat supply, creating single-source dependencies that extend integration timelines for new trainer programs.
- Fly-by-Wire Control Law Harmonization:Matching handling qualities across multiple fighter types requires proprietary flight control software licensing from combat aircraft OEMs, complicating multi-role trainer development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Military Trainer Aircraft Market |
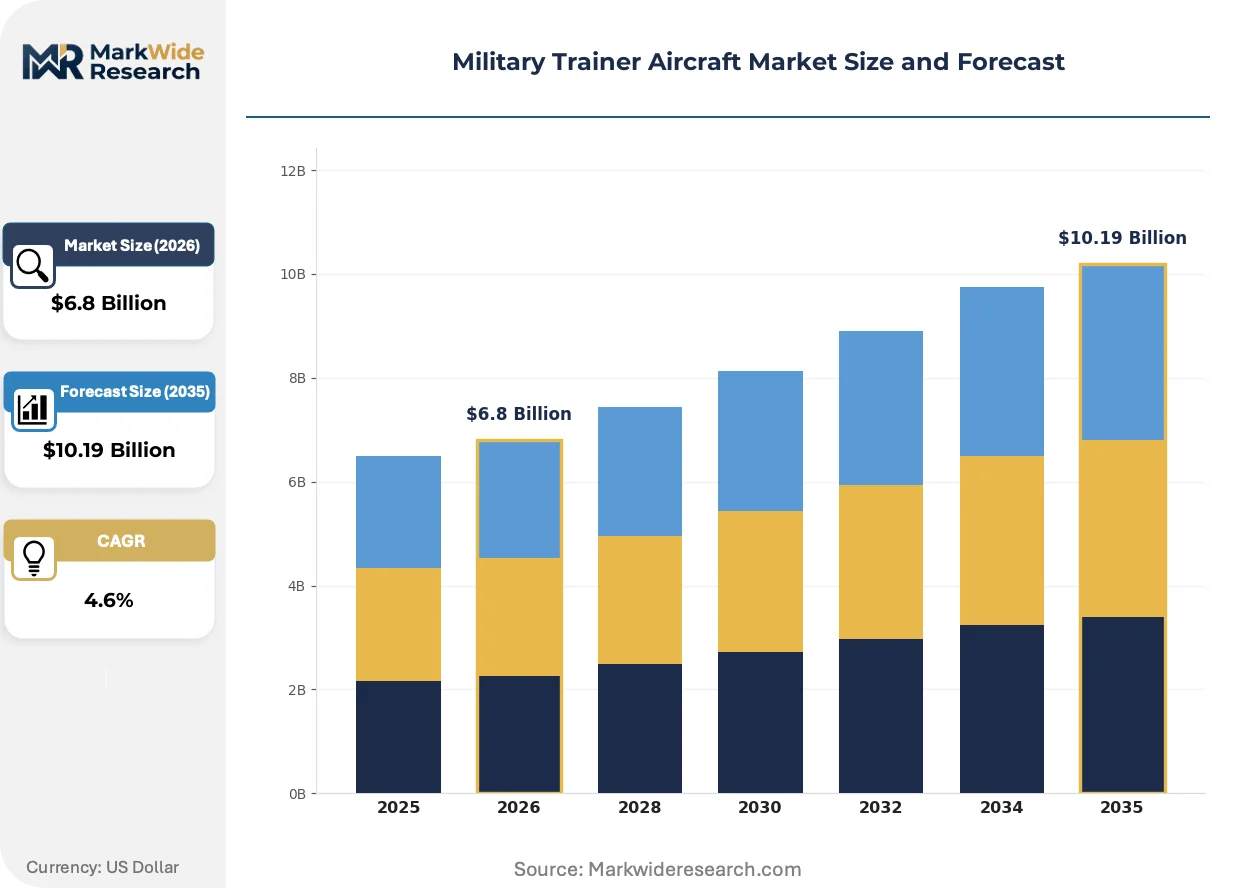
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.19 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Aircraft Type: Jet Trainer, Propeller Trainer, Advanced Trainer, Basic Trainer End User: Air Force, Navy, Private Operator, Defense Contractor Technology: Digital Cockpit, Fly-by-Wire, Avionics Suite, Simulation Capabilities Usage Type: Initial Training, Advanced Training, Instrument Rating, Combat Readiness |
| Companies Covered | The Boeing Company, Leonardo S.p.A., Textron Inc., Korea Aerospace Industries Ltd., Pilatus Aircraft Ltd., Airbus SE, Lockheed Martin Corporation, BAE Systems plc, Embraer S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Military Trainer Aircraft Market Strategic Shifts
Digital cockpit architectures are rendering analog instrumentation obsolete across both new-build and refurbishment programs, while sovereign data requirements are fragmenting simulation software supply chains. Platform economics increasingly favor airframes designed for 15,000+ hour service lives.
Glass-panel avionics suites with reconfigurable multi-function displays are modularizing cockpit configurations to accommodate diverse fighter type transitions. Air forces in the Middle East are specifying open-architecture standards that permit rapid software updates without hardware replacement. This modularity is compressing obsolescence cycles and extending platform relevance across multiple fighter generations.
The EU AI Act's risk classification framework for embedded training software is forcing European suppliers to segregate simulation code bases between domestic and export variants. India's DGAA is mirroring this fragmentation through data localization requirements for networked training systems. Advanced trainer segments with integrated sensor simulation are absorbing the highest compliance costs and passing these through to contract pricing.
Air forces are unbundling after-sales support from initial platform acquisition, awarding multi-year availability contracts to third-party integrators or in-house maintenance units. Saudi Arabia's Technical and Vocational Training Corporation is building indigenous MRO capacity for its T-50 fleet, displacing OEM service revenue. This behavioral shift concentrates supplier margins on initial delivery and technology refresh programs rather than through-life support.
Military Trainer Aircraft Market Segmentation
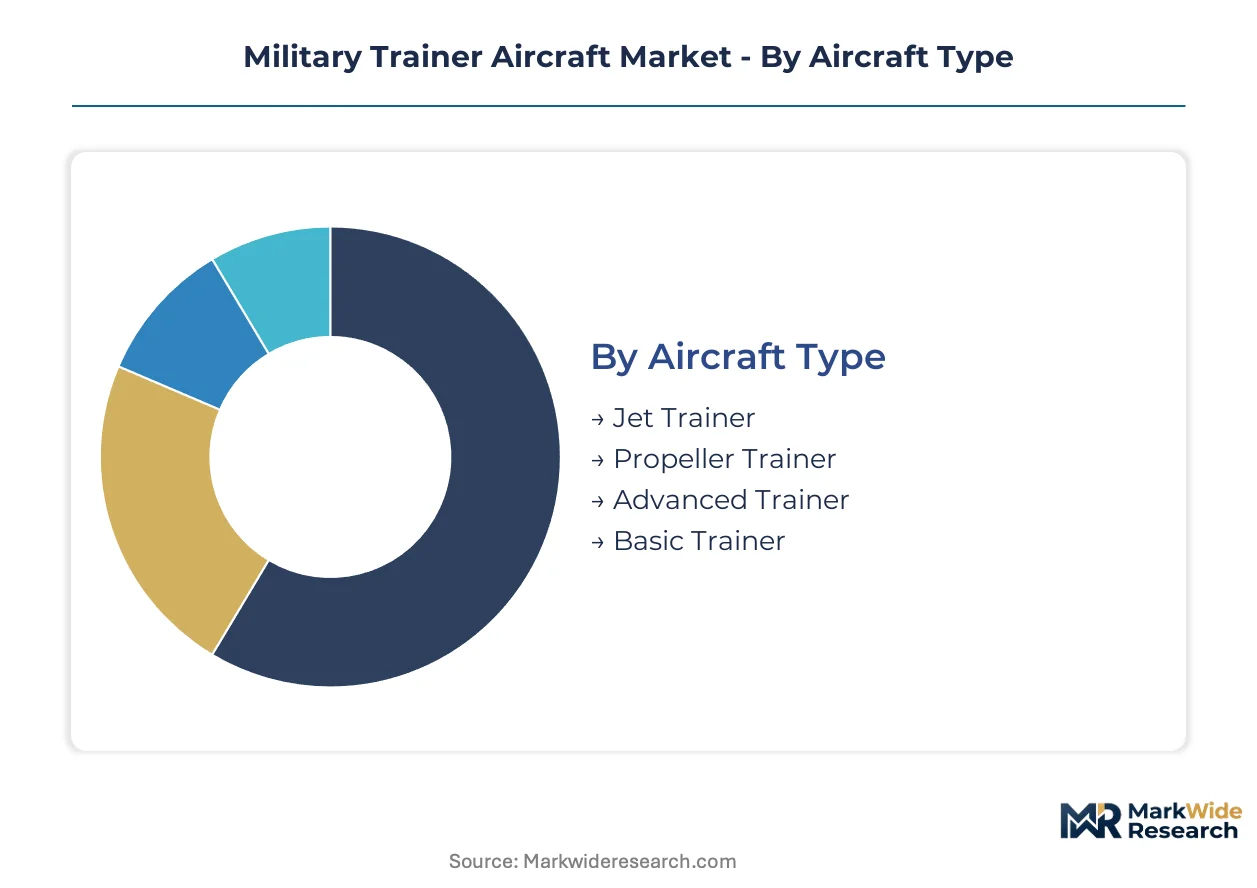
Segmentation in military trainer aircraft procurement reveals how air forces balance acquisition cost against fidelity to combat aircraft handling. Platform selection cascades through training pipelines, with each segment commanding distinct certification requirements and supplier qualification thresholds.
Aircraft Type:
Standalone platforms dominate fleet procurement volumes, while embedded subsystems in advanced variants capture expanding margin pools through integrated sensor simulation.
- Jet Trainer:Supersonic-capable airframes with afterburning turbofans replicate fourth- and fifth-generation fighter thrust-to-weight ratios. Demand concentrates in Saudi Arabia and Poland as F-35 inductions outpace compatible trainer availability.
- Advanced Trainer:Fly-by-wire control surfaces and integrated radar simulators enable fighter-congruent handling without supersonic speed. India's HTT-40 replacement cycle and intermediate jet trainer competitions are driving procurement volume here.
- Propeller Trainer:Turboprop powerplants deliver cost-efficient ab initio instruction with stall characteristics matching early-stage syllabus requirements.
- Basic Trainer:Fixed-gear, non-aerobatic platforms focus on primary flight instruction and instrument familiarization before jet transition.
Jet trainers lead volumes today; advanced trainers are gaining share fastest as synthetic environments compress live-flight hour requirements.
End User:
Customer procurement authority determines contract structure, with sovereign air forces favoring offset-backed acquisition and private operators prioritizing hourly operating economics.
- Air Force:National service branches specify zero-zero ejection seats and MIL-HDBK-516 certification as baseline requirements. India's Directorate General of Aeronautical Quality Assurance enforces indigenous content thresholds that reshape vendor eligibility for these contracts.
- Navy:Carrier-capable variants demand strengthened landing gear, arresting hook provisions, and corrosion-resistant coatings for maritime environments. Procurement concentrates in nations with CATOBAR or STOBAR carrier operations.
- Private Operator:Civilian training academies and defense contractors acquire surplus military platforms or purpose-built commercial derivatives with reduced avionics suites.
- Defense Contractor:Platform OEMs and systems integrators maintain captive fleets for test pilot instruction and customer demonstration.
Air force procurement dominates contract value; navy segments are expanding most quickly with Asian carrier program acceleration.
Technology:
Technology segmentation tracks how avionics architecture determines platform longevity and upgrade pathway cost.
- Digital Cockpit:Glass-panel multi-function displays with reconfigurable symbology replace analog instruments across refurbishment programs. Gulf Cooperation Council air forces are mandating open-architecture standards that permit software updates without hardware replacement.
- Fly-by-Wire:Digital flight control systems enable programmable handling qualities that simulate multiple fighter types from a single airframe. Control law licensing from combat aircraft OEMs creates proprietary barriers for multi-role trainer developers.
- Avionics Suite:Integrated communication, navigation, and identification systems replicate combat aircraft cockpit workload for pilot familiarization.
- Simulation Capabilities:Embedded virtual radar, electronic warfare, and weapon system emulators compress transition time to operational fighters.
Digital cockpit installations anchor replacement demand; fly-by-wire systems show the steepest expansion trajectory as synthetic training fidelity requirements intensify.
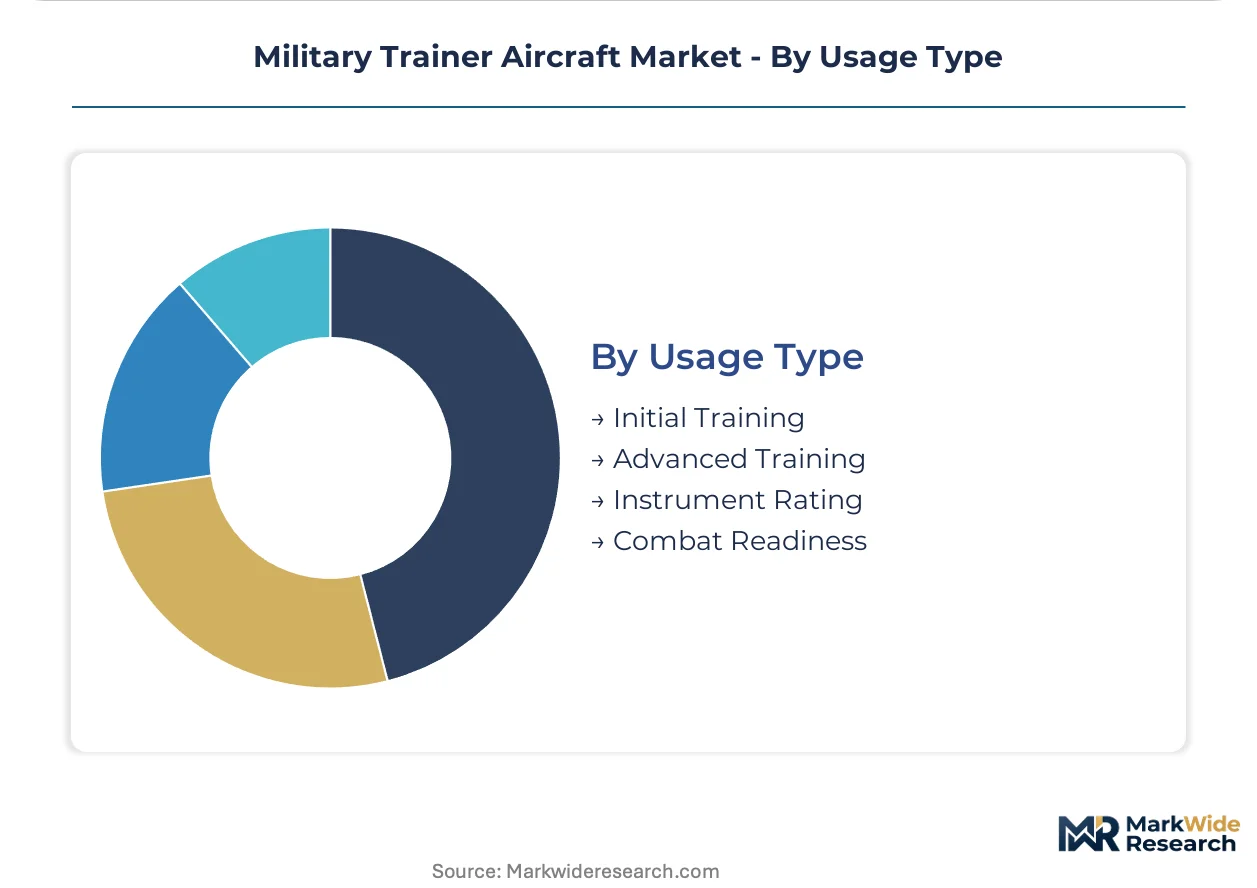
Usage Type:
Usage segmentation aligns platform capability against syllabus progression, with each stage demanding graduated handling complexity and risk exposure.
- Initial Training:Ab initio instruction focuses on basic attitude flying, navigation, and emergency procedures in forgiving aircraft with docile stall characteristics.
- Advanced Training:Complex aerobatics, formation flying, and instrument procedures prepare pilots for fighter transition. Poland's accelerated F-35 delivery schedule has compressed training pipelines here.
- Instrument Rating:Dedicated platforms emphasize all-weather capability and precision approach procedures with minimal aerobatic performance.
- Combat Readiness:Lead-in fighter training with sensor simulation, tactical datalinks, and weapon delivery profiles completes pre-operational qualification.
Advanced training absorbs the largest procurement volume; combat readiness segments are climbing the fastest with fifth-generation fleet inductions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Italian aerostructures manufacturing around Leonardo's integrated facilities exemplifies how regional industrial clustering shapes platform economics and export competitiveness in advanced trainer production.
United States
The US Air Force and Navy coordinate trainer procurement through the MIL-HDBK-516 airworthiness framework, streamlining certification for platforms seeking NATO interoperability. FAA-military coordination reduces export approval timelines. Textron's Wichita operations and Boeing's St. Louis facilities anchor domestic advanced jet trainer development for allied nations.
India
Indian Air Force expansion of fourth-generation fighter fleets compresses training pipeline capacity, driving HTT-40 and intermediate jet trainer competitions. DGAA indigenous content mandates disqualify fully foreign-built platforms from major tenders. Bengaluru's aerospace cluster hosts Hindustan Aeronautics Limited integration facilities for domestically designed basic trainers.
Saudi Arabia
Royal Saudi Air Force T-50 fleet inductions and F-15SA pilot training requirements concentrate demand for lead-in fighter platforms with integrated sensor simulation. Technical and Vocational Training Corporation programs build indigenous MRO capacity. Riyadh-based maintenance infrastructure development displaces traditional OEM service revenue models.
Poland
Accelerated F-35A delivery schedules have outpaced compatible advanced trainer availability, creating immediate procurement pressure for supersonic-capable platforms. Warsaw's defense modernization programs prioritize NATO-standard certification compatibility. Mielec's aviation manufacturing base supports offset negotiations for foreign platform selection.
South Korea
Korea Aerospace Industries leverages domestic supply chain density to sustain competitive T-50 family export pricing across Southeast Asian markets. Republic of Korea Air Force pilot training expansion supports regional fleet modernization trends. Sacheon's integrated production facilities demonstrate how captive aerostructures capabilities control composite fabrication costs.
Military Trainer Aircraft Market Competitive Environment
Technology licensing dominates the current landscape as platform developers seek fly-by-wire control law agreements from combat aircraft OEMs. The vendor base concentrates around integrated aerostructures manufacturers and systems integrators with captive composite capabilities. Two strategic archetypes prevail: full-spectrum developers controlling airframe-to-avionics integration, and subsystem specialists supplying ejection seats or simulation packages. M&A activity and strategic partnerships represent the dominant competitive vectors as firms address sovereign content requirements.
Within the full-spectrum developer tier, Leonardo S.p.A. and Korea Aerospace Industries Ltd. exemplify vertically integrated manufacturers with domestic supply chain control, while BAE Systems plc occupies a position bridging platform sustainment and avionics refresh capabilities. These three anchors demonstrate how geographic industrial clustering—Italian composite fabrication, Korean cost-competitive production, and UK defense procurement navigation—shapes competitive positioning without requiring identical strategic approaches.
| Leading Market Players |
|---|
| The Boeing Company |
| Leonardo S.p.A. |
| Textron Inc. |
| Korea Aerospace Industries Ltd. |
| Pilatus Aircraft Ltd. |
| Airbus SE |
| Lockheed Martin Corporation |
| BAE Systems plc |
| Embraer S.A. |
| Others |
Value Chain & Pricing Dynamics
Certification-grade bifurcation between MIL-HDBK-516 qualified platforms and non-certified alternatives manifests in pricing power concentration among NATO-aligned suppliers and supply chain clustering around FAA-coordinated airworthiness hubs. This divergence rewards integrated manufacturers with captive composite capabilities while squeezing margins for subsystem-dependent assemblers facing titanium alloy volatility.
Pricing Analysis
Input-cost pass-through from aerospace-grade superalloy volatility governs contract structures, with titanium and nickel alloy price swings compressing fixed-price trainer margins. Three-tier pricing structure across advanced jet, intermediate, and basic trainer levels reflects certification burden and fly-by-wire integration depth. Pricing pressure stems from indigenous content mandates in India's DGAA-regulated competitions, which disqualify fully foreign-built platforms. Air force procurement shows lowest price sensitivity given operational requirements, while private training academies prioritize hourly operating economics.
Supply Chain Analysis
Warehouse-distribution layer concentration in Italian aerostructures clusters, Korean integrated production facilities, and UK defense procurement corridors shapes regional fulfillment patterns. Carbon fiber reinforced polymer fabrication draws from Japanese precursor suppliers and Italian autoclave capacity, while zero-zero ejection seat supply rests on Martin-Baker and Saab dual-source dependencies. Single-source vulnerability in qualified seat certification creates integration bottlenecks. Distribution runs through government-to-government offset frameworks rather than commercial channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunity concentrates in composite airframe platforms and performance-based logistics contracts, with carbon fiber adoption reducing unit production costs while extending service life premiums.
For Market Incumbents: To counter sovereign content fragmentation, deepen backward integration into aerostructures manufacturing and establish regional depot networks for availability-guaranteed service models. Lock in fly-by-wire control law licensing from combat aircraft OEMs before multi-role trainer competitions accelerate. For New Entrants and Emerging Players: Regional MRO integrators represent the most penetrable channel partner type for aftermarket service unbundling. Target Poland's F-35 trainer gap and India's HTT-40 replacement cycle through offset-backed joint ventures with local aerospace clusters. Lead with augmented reality helmet display development funded by Gulf Cooperation Council states. For Investors and Strategic Acquirers: Consolidation pressure builds where simulation software compliance costs fragment European supplier code bases between domestic and export variants. Long-term viability favors full-spectrum developers with captive composite capabilities over subsystem assemblers. Watch for EU AI Act enforcement intensity as inflection indicator for embedded training software margin compression.| Strategic Initiative | Industry Significance |
|---|---|
| Control Law Licensing Agreement | Proprietary flight control software from combat aircraft OEMs enables multi-role trainer development. |
| Regional Depot Network Expansion | Saudi Arabia's TVTC MRO capacity building demonstrates displacement of traditional OEM service revenue. |
| Composite Fabrication Scale-Up | Leonardo's Italian integrated aerostructures capabilities demonstrate cost control through captive supply. |
| Open-Architecture Avionics Investment | Gulf Cooperation Council mandates for software-updatable glass panels extend platform relevance cycles. |
| Synthetic Training Environment Development | AR helmet displays overlaid on live cockpits bridge fidelity gaps for early-stage instruction compression. |
Study Parameters
Coverage spans United States, India, Saudi Arabia, Poland, and South Korea, with primary inputs from each market's defense procurement ecosystem. Primary interviews with air force acquisition officers, platform OEM program managers, DGAA certification leads, and MRO facility directors combined with secondary validation from MIL-HDBK-516 documentation, FAA coordination protocols, EU AI Act regulatory filings, and customs trade data. Bottom-up fleet replacement pipeline analysis triangulated against top-down defense budget allocation patterns.
Rate-of-change decomposition across the analysis window separates volume drivers from value migration patterns. Segmentation dimensions modeled include aircraft type, end user authority, technology architecture, and usage stage progression. CAGRs derived from fleet induction schedules, training pipeline compression ratios, and platform service life assumptions. Industry-specific inputs incorporated synthetic training hour substitution rates and sovereign content threshold enforcement intensity.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to titanium alloy price volatility, ejection seat certification bottlenecks, and software export control friction. Forecasts reflect documented assumptions regarding F-35 delivery schedules, HTT-40 competition timelines, and EU AI Act implementation pacing. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft
Tanker Aircraft Market
Aircraft
Airplane Brackets Market
Aircraft
Aircraft Cargo Container Market
Aircraft
Aircraft Wheels Market
Aircraft
Freighter Aircraft Market
Aircraft
Electric Aircraft Market
Aircraft
Aircraft Cables Market
Aircraft
Global Aircraft Towbars Market
Aircraft
Aircraft Inspection Covers Market
Aircraft
Europe General Aviation Market
Aircraft
General Aviation Market
Aircraft
Sailplane Market
Aircraft
Light and Very Light Jets Market
Aircraft
Two-Seater Ultralight Helicopters Market
Aircraft
Attack Helicopter Market
Aircraft
Aircraft Ailerons Market