
 Fast Attack Craft (FAC) Market | 2026-2036
Fast Attack Craft (FAC) Market Size, Share, and Industry Trends Forecast 2026-2036
Fast Attack Craft (FAC) Market Analysis
Export credit financing and sovereign leasing arrangements are reshaping how smaller navies acquire Fast Attack Craft capability without full capital outlay. Damen Shipyards Group leverages its standardized product lines to compete across multiple tiers of buyer sophistication. BAE Systems plc anchors its position through integrated combat system packages that extend beyond hull fabrication. Garden Reach Shipbuilders & Engineers Ltd. specializes in cost-optimized designs that occupy the mid-market segment for developing naval forces.
Fast Attack Craft are high-speed naval vessels typically displacing under 500 tons, engineered for surface strike, interdiction, and littoral dominance through combinations of anti-ship missiles, gun armament, and advanced sensor suites. Missile boats dominate procurement volumes while swarm boat configurations represent the fastest-growing technology segment as distributed maritime operations gain doctrinal traction. Trimaran and hydrofoil hull forms command premium positioning within the technology dimension due to reduced radar cross-section and enhanced seakeeping.
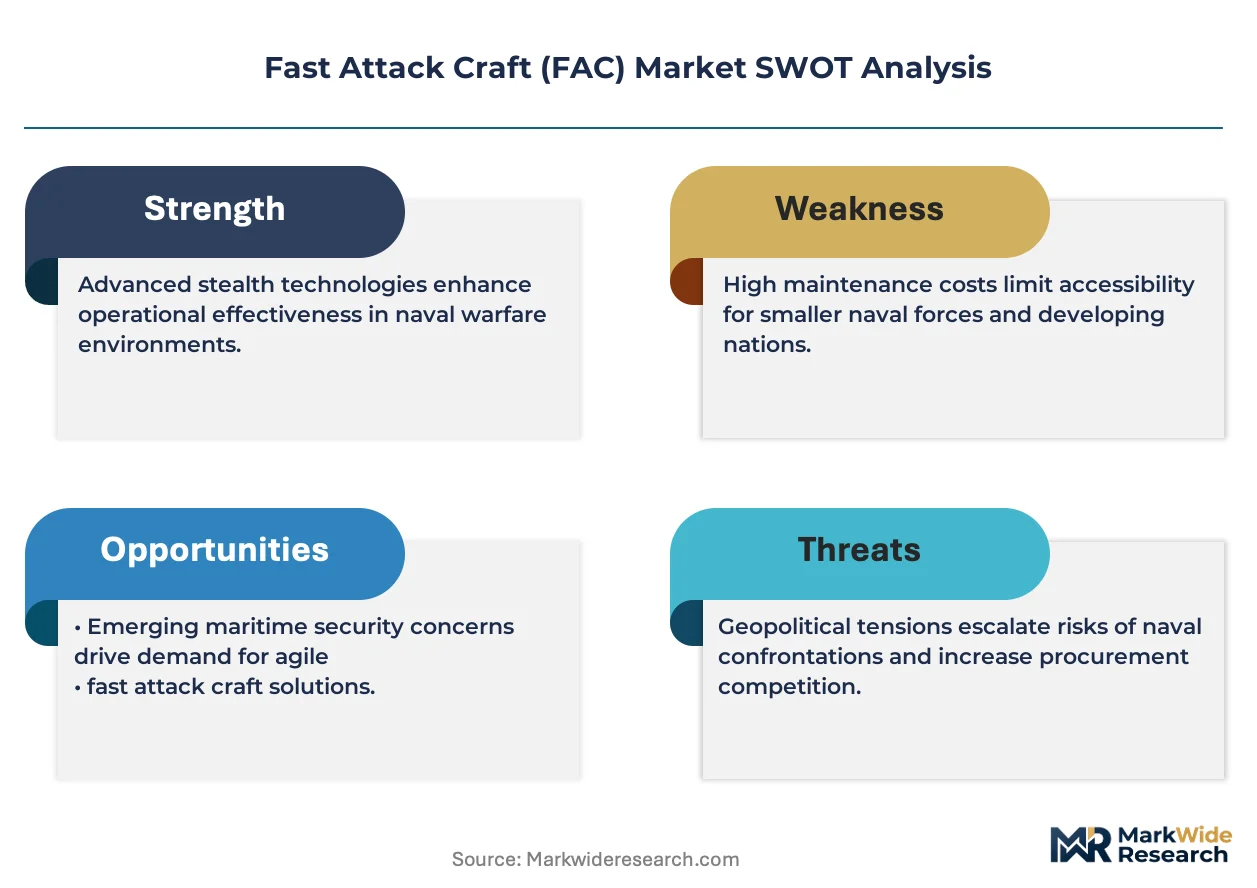
Naval procurement authorities in buyer nations increasingly mandate NATO STANAG interoperability standards, while the International Maritime Organization's safety conventions constrain hull construction and crew accommodation specifications. Export licensing regimes administered by supplier-country defense trade controls further segment market access based on end-user certification and regional stability assessments. Stakeholders must monitor evolving autonomous payload integration standards that will determine which platform architectures remain upgradeable against unmanned swarm threats.
Market Dynamics
Composite hull fabrication and integrated combat management architectures are compressing platform refresh cycles while elevating performance thresholds for littoral dominance missions.
Growth Catalysts
- Naval Modernization Mandates:Southeast Asian archipelagic states are expanding brown-water fleets through sovereign leasing arrangements that bypass full capital outlay requirements.
- STANAG Interoperability Standards:NATO procurement specifications are mandating common datalink protocols and sensor fusion architectures across allied fast patrol platforms.
- Swarm Boat Configurations:Distributed maritime operations doctrine is accelerating demand for trimaran and hydrofoil hull forms with reduced radar cross-section profiles.
Market Restraints
- Advanced Composite Input Costs:Carbon-fiber and aramid hull materials face price volatility tied to aerospace sector demand competition and energy-intensive curing processes.
- Export Licensing Friction:Supplier-country defense trade controls segment market access based on end-user certification and regional stability assessments, constraining deal velocity.
- Crew Accommodation Standards:International Maritime Organization safety conventions impose minimum hull volume and habitability specifications that compromise stealth-optimized designs.
Strategic Opportunities
- Autonomous Payload Integration:Unmanned surface vehicle docking standards will determine which platform architectures remain upgradeable against emerging swarm threats.
- Mid-Market Cost Optimization:Developing naval forces in the Indian Ocean rim present unmet demand for missile-armed patrol craft below premium NATO-tier pricing.
- Combat System Unbundling:Modular sensor and weapon packages allow hull fabricators to compete separately from integrated combat management providers.
Industry Challenges
- Marine Systems Engineering Talent:Naval architects with combined expertise in high-speed hydrodynamics and signature reduction are concentrated among a handful of defense primes.
- Legacy Platform Integration:Brown-water fleets operating mixed-generation craft face interoperability gaps between analog gunnery systems and digital fire-control networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fast Attack Craft (FAC) Market |
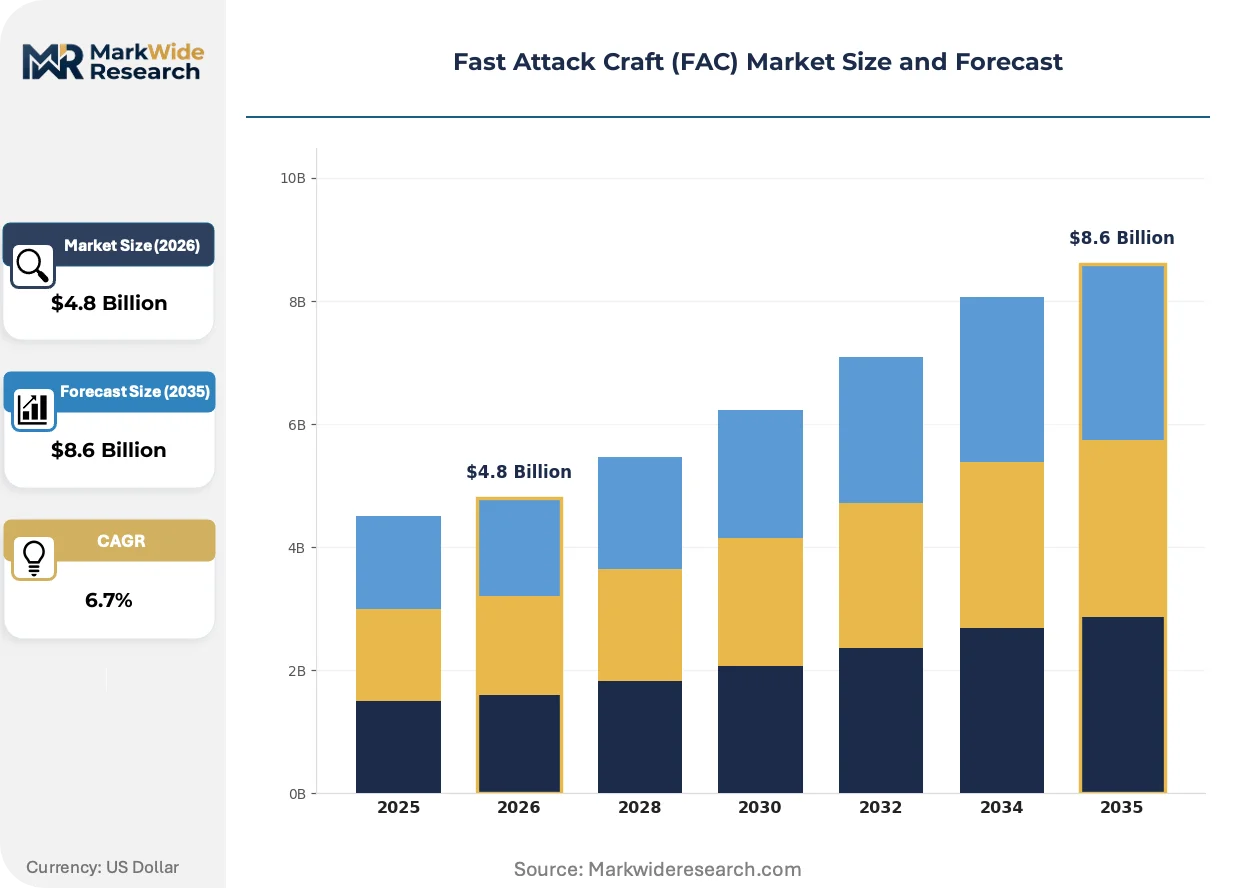
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Missile Boats, Patrol Vessels, Armed Yachts, Swarm Boats Technology: Stealth, Hydrofoils, Trimaran, Monohull End User: Navies, Coast Guards, Private Security, Training Organizations Deployment: Inshore, Offshore, Coastal, Riverine |
| Companies Covered | CMN Group, Garden Reach Shipbuilders & Engineers Ltd., BAE Systems plc, Fincantieri S.p.A., Damen Shipyards Group, Lürssen Werft GmbH & Co. KG, China Shipbuilding & Offshore International Co. Ltd., Israel Shipyards Ltd., Navantia S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fast Attack Craft (FAC) Market Emerging Trajectories
Propulsion electrification and additive manufacturing are rewriting platform design constraints while export credit structures reshape capital deployment patterns for naval procurement.
Integrated electric propulsion architectures with lithium-ion energy storage are rendering obsolete mechanical drivetrain configurations in new-build fast attack craft. Southeast Asian navies are specifying hybrid-electric systems for extended loiter endurance during maritime interdiction missions. The shift is compressing platform development timelines as hull designers optimize around distributed power rather than centralized engine rooms.
REACH chemical substance restrictions are constraining anti-fouling coating formulations and hull treatment processes for European-built patrol craft. Shipyards serving NATO export markets are reformulating surface preparation protocols to eliminate restricted biocides while maintaining drag reduction performance. German and Dutch builders are certifying alternative copper-free treatments ahead of anticipated regulatory tightening.
Leasing-with-purchase-option structures are displacing traditional capital acquisition for missile boat procurement among fiscally constrained navies. Defense export credit agencies in France, Italy, and South Korea are structuring sovereign-backed facilities that transfer operational risk to supplier nations. Indonesian and Philippine fleet expansion programs exemplify this shift away from outright purchase toward operational service contracts with embedded technology refresh clauses.
Fast Attack Craft (FAC) Market Segmentation
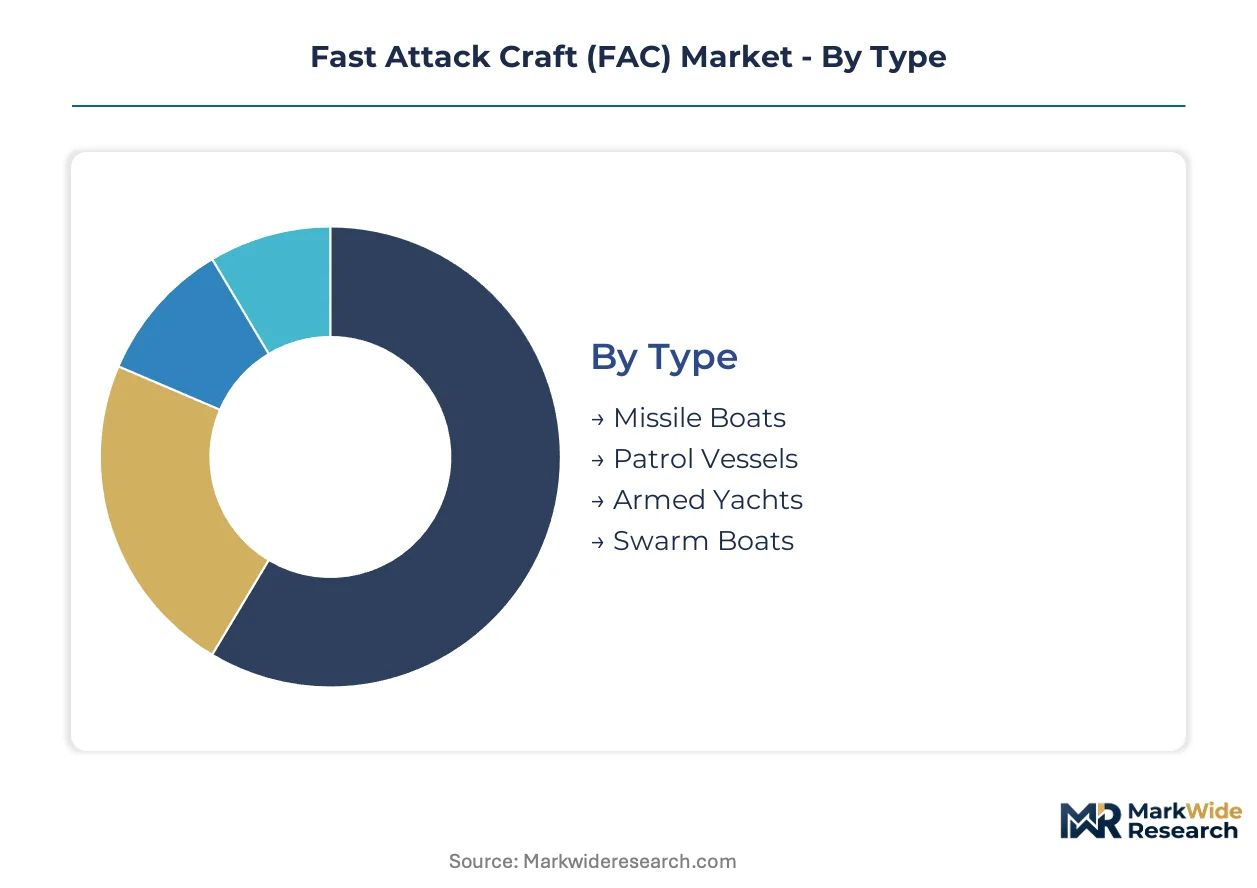
Fast Attack Craft procurement divides across mission profiles, hull architectures, and operational authorities. Platform specifications diverge sharply between missile-strike missions requiring speed and endurance patrols demanding crew habitability. Understanding these fault lines clarifies where composite materials, electrified propulsion, and autonomous payloads concentrate investment.
Type:
Platform categories span the full spectrum from high-endurance patrol missions to saturation strike configurations.
- Missile Boats:Displacing 200-500 tons with dedicated anti-ship missile launchers and integrated fire-control radars. Procurement concentrates in Indonesian and Philippine fleet modernization programs where sovereign leasing structures bypass capital constraints.
- Swarm Boats:Distributed maritime operations doctrine favors trimaran and hydrofoil hull forms with reduced radar cross-section. Southeast Asian archipelagic navies specify these for area-denial scenarios against larger surface combatants.
- Patrol Vessels:Gun-armed platforms optimized for maritime interdiction and constabulary duties with extended loiter endurance.
- Armed Yachts:Converted commercial hulls serving private security contractors and coast guard auxiliaries in low-threat environments.
Established volume favors Missile Boats; emerging adoption favors Swarm Boats.
Technology:
Hull form selection trades signature management against construction cost and seakeeping in littoral conditions.
- Stealth:Radar-absorbing superstructures and angled hull geometries reduce cross-section for missile boats operating within hostile air-defense envelopes. NATO STANAG interoperability mandates are standardizing signature specifications across allied procurement.
- Monohull:Conventional steel and aluminum construction dominates cost-optimized builds for developing naval forces. Indian Ocean rim navies specify these for brown-water patrol where speed requirements remain modest.
- Hydrofoils:Lift-assisted hulls achieve 50+ knot sprint speeds for rapid intercept missions with reduced drag at cruise.
- Trimaran:Triple-hull configurations deliver stable weapons platforms with expansive deck area for sensor integration.
Procurement concentration sits with Monohull for volume; technology differentiation concentrates in Stealth configurations.
End User:
Operational authority determines armament ceilings, rules of engagement, and interoperability requirements.
- Navies:Full-spectrum combatants with integrated combat management systems and NATO datalink compatibility. Brown-water fleet expansion across Southeast Asian states is accelerating missile boat procurement through export credit facilities.
- Coast Guards:Law enforcement platforms with reduced armament but enhanced boarding and inspection capabilities. Philippine and Indonesian maritime security agencies are separating constabulary missions from naval strike roles.
- Private Security:Armed escort vessels protecting commercial traffic in piracy-affected corridors with rules-of-fire constraints.
- Training Organizations:Simplified hulls for crew certification and tactical development without full combat system suites.
Navies command procurement value; Coast Guards are expanding fleet share fastest.
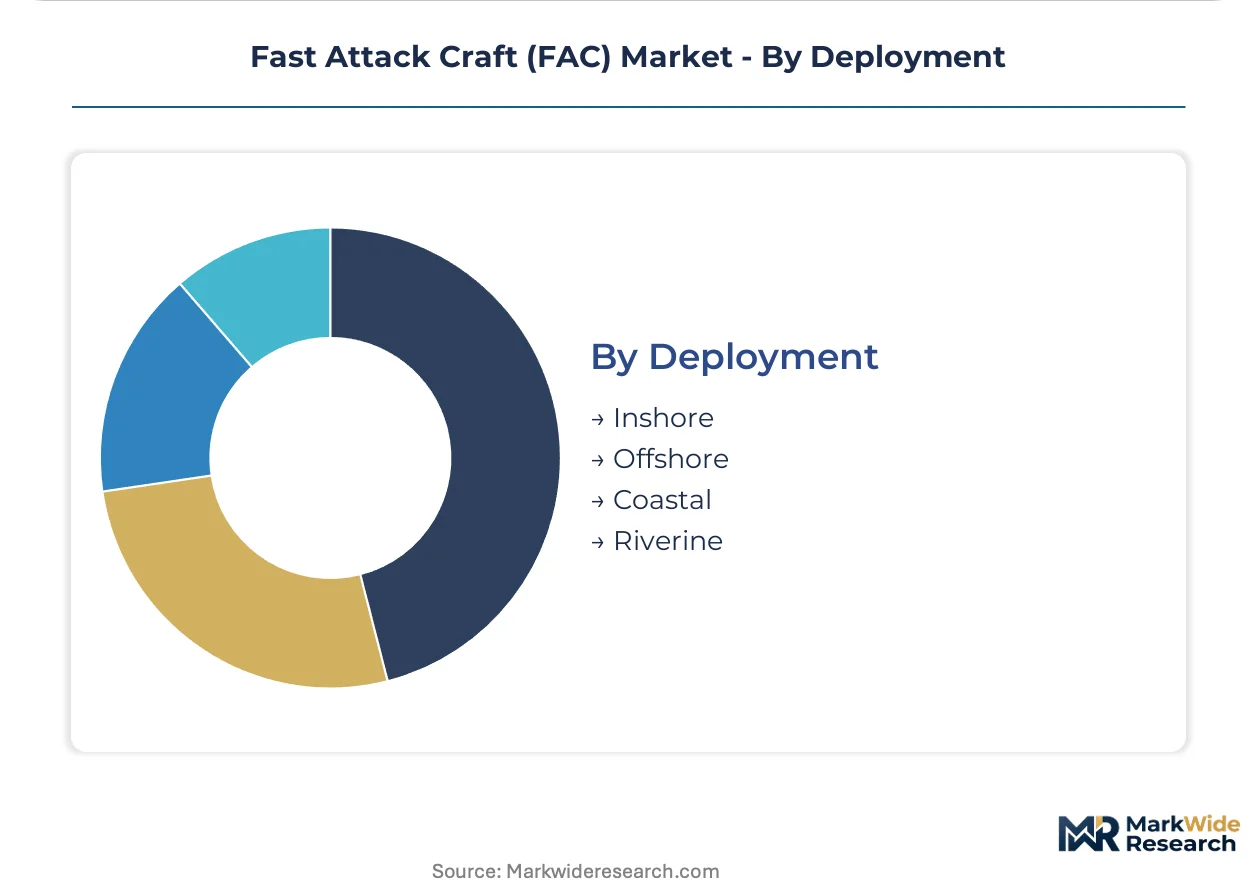
Deployment:
Operating environment dictates hull strength, draft requirements, and sensor performance against clutter.
- Coastal:Medium-draft platforms balancing blue-water seakeeping with littoral maneuverability. Archipelagic navies prioritize these for exclusive economic zone enforcement across dispersed island chains.
- Riverine:Shallow-draft patrol craft with reduced signatures for inland waterway operations. Mekong Delta and similar environments specify air-cushion or flat-bottom configurations.
- Inshore:High-speed interceptors for harbor defense and maritime policing within territorial waters.
- Offshore:Extended-range platforms with replenishment capability for operations beyond immediate coastal support.
Coastal deployment anchors procurement volume; Riverine configurations are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export credit facilities and sovereign leasing arrangements are redistributing Fast Attack Craft procurement across littoral states, with supplier nations securing long-term operational contracts that transfer financing risk from buyer to builder.
Indonesia
Archipelagic fleet modernization drives missile boat procurement through defense export credit agencies in France and Italy. The country's national defense procurement authority structures operational service contracts with embedded technology refresh clauses. Surabaya's naval shipyard cluster hosts joint production arrangements with European builders for composite hull fabrication.
Philippines
Maritime security agencies are separating constabulary missions from naval strike roles, accelerating patrol vessel acquisition. The Department of National Defense mandates NATO STANAG interoperability standards for new fast attack platforms. Subic Bay Freeport Zone serves as the primary hub for hull assembly and combat system integration with South Korean partners.
South Korea
Domestic shipbuilders leverage sovereign-backed financing facilities to capture Southeast Asian export markets. The Defense Acquisition Program Administration coordinates export credit terms with state development banks. Busan-Ulsan shipbuilding corridor concentrates production of stealth-optimized trimaran hull forms for regional clients.
Germany
Precision engineering standards and REACH chemical compliance requirements shape patrol craft specifications for NATO export markets. The Federal Office of Bundeswehr Equipment, Information Technology and In-Service Support administers technology transfer protocols for composite hull materials. Hamburg-Bremen shipbuilding cluster specializes in integrated combat management system packaging for allied navies.
Israel
Advanced sensor fusion architectures and signature reduction expertise position domestic builders in premium-tier procurement competitions. The Ministry of Defense's export licensing division segments market access based on end-user certification and regional stability assessments. Haifa's naval engineering complex concentrates development of swarm boat configurations for littoral dominance missions.
Fast Attack Craft (FAC) Market Vendor Landscape
On the supply side, the industry is tiered across integrated combat system providers, hull fabricators, and modular payload specialists. Consolidation pressures favor builders with captive financing arrangements and standardized product platforms. Three archetypes dominate: European primes bundling combat management with hull delivery, Asian yards competing on cost-optimized production cycles, and Israeli specialists anchoring premium sensor integration tiers. Competitive moves center on export credit structuring and sovereign leasing partnerships that transfer operational risk.
Among European-integrated primes, BAE Systems plc and Damen Shipyards Group exemplify divergent approaches to platform delivery. BAE Systems anchors the combat-system-centric archetype through integrated fire-control and sensor fusion packaging. Damen represents the standardized product-line model with configurable hull architectures across multiple buyer sophistication tiers. Garden Reach Shipbuilders & Engineers Ltd. occupies the mid-market cost-optimization segment, serving developing naval forces with designs below NATO-tier pricing thresholds.
| Leading Market Players |
|---|
| CMN Group |
| Garden Reach Shipbuilders & Engineers Ltd. |
| BAE Systems plc |
| Fincantieri S.p.A. |
| Damen Shipyards Group |
| Lürssen Werft GmbH & Co. KG |
| China Shipbuilding & Offshore International Co. Ltd. |
| Israel Shipyards Ltd. |
| Navantia S.A. |
| Others |
Supply Flow & Price Mechanics
Export licensing friction determines both pricing tier spreads and supply chain shape across Fast Attack Craft procurement, as supplier-country defense trade controls segment market access based on end-user certification and regional stability assessments. This regulatory chokepoint compresses margins for builders serving restricted markets while elevating premiums for NATO-interoperable platforms.
Pricing Analysis
Naval procurement authorities anchor pricing stratification across premium, standard, and economy tiers. Premium NATO-tier platforms command substantial markups for STANAG-compliant combat management systems and composite hull certification. Cost compression in the economy tier intensifies because Indian Ocean rim navies prioritize hull fabrication over integrated sensor packages. Coast guard buyers exhibit highest price sensitivity, while sovereign leasing arrangements reduce capital outlay sensitivity for naval strike procurement.
Supply Chain Analysis
Extended payment terms through export credit agencies in France, Italy, and South Korea reshape working capital requirements for hull fabricators. Supply concentrates in Germany, the Netherlands, and South Korea for precision-engineered combat system integration. Carbon-fiber and aramid composite inputs draw from aerospace sector suppliers, creating single-source vulnerability during demand surges. Distribution runs through sovereign-backed operational service contracts with embedded technology refresh clauses rather than outright purchase.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across buyer sophistication tiers creates niche opportunities as archipelagic navies separate constabulary missions from naval strike roles. This demand-side specialization rewards builders with configurable product architectures.
For Market Incumbents: Pre-empt autonomous payload integration standards by embedding unmanned surface vehicle docking capability in new hull designs. Secure backward integration into lithium-ion energy storage systems to capture electrification value. Counter emerging Asian cost-optimized entrants through captive financing arrangements that transfer operational risk.
For New Entrants and Emerging Players: Philippine coast guard modernization represents underpenetrated white-space with separated procurement authority from naval strike programs. Indonesian maritime security agencies offer second entry point through joint production arrangements at Surabaya shipyard cluster. Pursue modular combat system packaging to compete separately from integrated European primes.
For Investors and Strategic Acquirers: REACH chemical substance restrictions reshape the acquisition landscape by favoring builders with certified copper-free hull treatments ahead of regulatory tightening. Five-to-ten year viability hinges on upgradeable platform architectures against swarm threats. Target mid-market hull fabricators with standardized product lines serving developing naval forces. Monitor autonomous payload integration standards as inflection indicator for platform obsolescence risk.
| Strategic Initiative | Industry Significance |
|---|---|
| Export Credit Facility Structuring | Sovereign-backed financing transfers operational risk from Indonesian and Philippine buyers to European and South Korean suppliers. |
| Composite Hull Certification Investment | REACH-compliant carbon-fiber curing processes secure access to NATO export markets against regulatory tightening. |
| Modular Combat System Unbundling | Separate sensor and weapon packaging allows Garden Reach Shipbuilders to compete below premium-tier pricing. |
| Autonomous Payload Integration | Unmanned surface vehicle docking standards determine which Damen and Israel Shipyards platforms remain upgradeable. |
| Joint Production Arrangement | Surabaya and Subic Bay assembly hubs localize hull fabrication for archipelagic navies with technology transfer clauses. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted across naval procurement authorities, shipyard program managers, defense export credit agency underwriters, and combat system integration engineers. Secondary validation drew from NATO STANAG documentation, International Maritime Organization safety convention filings, customs trade data for hull material imports, and SEC disclosures from listed defense primes. Bottom-up platform delivery forecasts triangulated against top-down naval modernization budget allocations.
Calibration across the analysis window employed segmented modeling by hull architecture, mission profile, and operational authority. CAGRs derived from procurement pipeline visibility and sovereign leasing adoption curves. Forecast inputs included electrified propulsion penetration rates and autonomous payload integration timelines specific to littoral dominance doctrine evolution.
Macroeconomic conditions sit as an overlay; deviation in sovereign debt servicing capacity and defense budget prioritization would shift the trajectory. Forecasts reflect documented assumptions regarding export licensing regime stability and composite material cost trajectories. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Naval Warfare
Naval Gas Turbine Market
Naval Warfare
Aircraft Carrier Market
Naval Warfare
Maritime Patrol Naval Vessels (OPV) Market
Naval Warfare
Naval Combat Vessels Market
Naval Warfare
Naval Vessel Defense Systems Market
Naval Warfare
Combat Management System Market
Naval Warfare
Europe Naval Vessels Market
Naval Warfare
Amphibious Landing Craft Market
Naval Warfare
Sea Based C4ISR Market
Naval Warfare
Sea-Based Remote Weapon Systems Market
Naval Warfare
Aircraft Carrier Ship Market
Naval Warfare
Naval Vessels Market
Naval Warfare
Anti-Ship Missile Defense System Market
Naval Warfare
Bow and Stern Thrusters Market
Naval Warfare
Anti-Submarine Warfare Market
Naval Warfare
Naval Radar Systems Market