
 Military Multirole Aircraft Market | 2026-2036
Military Multirole Aircraft Market Size, Share, and Industry Trends Forecast 2026-2036
Military Multirole Aircraft Market Outlook
The EU Green Deal's defense adaptation framework is decoupling carbon-intensive manufacturing from next-generation aircraft sourcing criteria. Lockheed Martin leverages its integrated digital thread architecture to sustain production velocity on the F-35 program across three service variants. Boeing anchors its multirole portfolio through the F/A-18 Super Hornet and emerging NGAD concepts, while Dassault Aviation differentiates via the Rafale's combat-proven versatility and full sovereign supply chain.
Military multirole aircraft are fixed-wing platforms engineered to execute fighter, strike, reconnaissance, and electronic warfare missions from a single airframe, typically incorporating thrust-vectoring or supercruise-capable propulsion exceeding Mach 1.5 without afterburner. Their primary purpose is to reduce fleet complexity while maximizing sortie-generation rates across contested airspace scenarios. Fighter jets occupy the dominant revenue position given their centrality to air superiority doctrines and nuclear delivery roles. Stealth technology segments attract disproportionate R&D allocation as radar-cross-section reduction becomes mandatory for penetration missions against integrated air defense networks. Transport missions represent a stable, mature application category with replacement-driven procurement rather than expansionary demand.
The US Department of Defense mandates MIL-STD-810 environmental testing and ITAR-controlled technology transfer protocols, constraining supplier bases and international co-development arrangements. EASA's military certification liaison and NATO's STANAG interoperability standards shape European procurement, while China's GB standards and MIIT directives govern indigenous platform development. Stakeholders must monitor how AUKUS technology-sharing frameworks and emerging JADC2 network requirements reshape platform specifications before committing to long-cycle development programs.
Market Dynamics
The obsolescence of fourth-generation fighter fleets across NATO member states is forcing accelerated multirole procurement cycles, with air forces prioritizing platforms capable of penetrating integrated air defense networks while reducing logistical tail complexity.
Growth Catalysts
- ITAR Technology Transfer Liberalization:The US State Department's revised Category VIII export controls are enabling faster international co-production arrangements for sensitive avionics and propulsion systems.
- JADC2 Network Mandates:The US Department of Defense's Joint All-Domain Command and Control architecture requires multirole platforms with open systems architectures and modular mission computers.
- Carbon-Neutral Base Operations:The EU Green Deal's defense adaptation framework is creating procurement preference for aircraft with sustainable aviation fuel compatibility and reduced lifecycle emissions profiles.
Market Restraints
- Titanium and Nickel Superalloy Concentration:Russian and Chinese dominance in sponge titanium and vacuum arc remelting capacity creates input cost volatility and supply security risks for airframe and engine manufacturers.
- ITAR Compliance Burden:US International Traffic in Arms Regulations impose multi-year licensing timelines and facility security requirements that constrain supplier base expansion and international joint ventures.
- Stealth Coating Technical Limitations:Current radar-absorbent materials require climate-controlled hangar infrastructure and frequent maintenance, limiting forward basing options in austere environments.
Strategic Opportunities
- AUKUS Technology-Sharing Framework:The trilateral security pact between Australia, the United Kingdom, and the United States is opening collaborative development pathways for next-generation electronic warfare and hypersonic integration.
- Unmanned-Teaming Convergence:Manned-unmanned teaming architectures combining F-35 sensor fusion with loyal wingman drones are creating new platform ecosystem revenue streams beyond airframe sales.
- Digital Thread Manufacturing:Model-based enterprise approaches integrating design, production, and sustainment data are compressing development timelines and enabling continuous capability insertion.
Industry Challenges
- Clearance-Held Engineering Talent Scarcity:The specialized workforce holding security clearances for classified avionics and low-observable technology work is aging, with insufficient pipeline replacement from STEM programs.
- MIL-STD-810H Certification Timelines:Environmental qualification testing for extreme temperature, vibration, and electromagnetic interference conditions extends development programs by 18-24 months.
- Legacy System Architecture Integration:Fourth-generation command and control networks lack bandwidth and protocol compatibility with fifth-generation sensor fusion systems, forcing expensive gateway development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Military Multirole Aircraft Market |
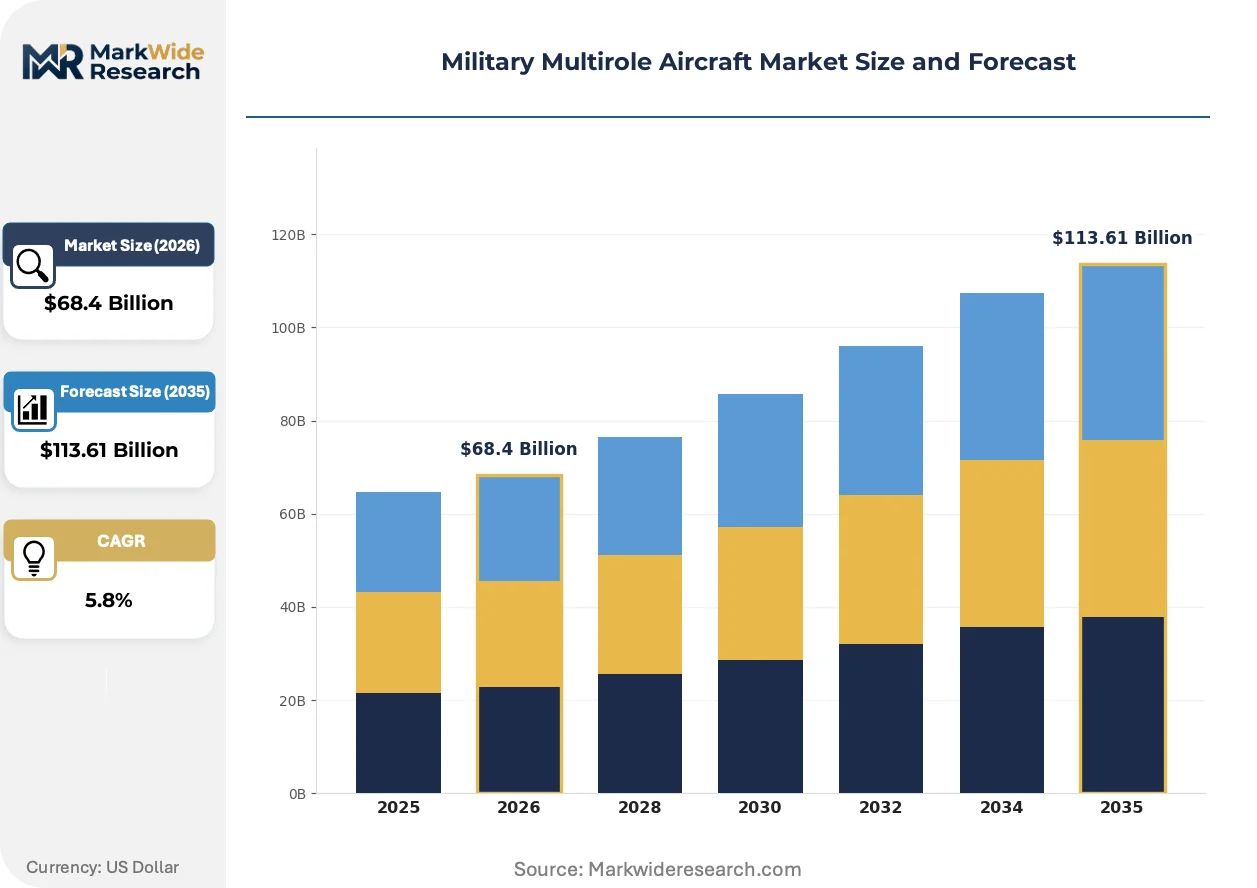
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $113.61 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fighter Jets, Transport Aircraft, Surveillance Aircraft, Cargo Planes Technology: Stealth Technology, Avionics Systems, Radar Systems, Engine Technology Application: Combat Operations, Reconnaissance, Transport Missions, Humanitarian Assistance End User: Air Forces, Defense Agencies, Government Entities, Private Contractors |
| Companies Covered | Lockheed Martin Corporation, The Boeing Company, Dassault Aviation, Saab AB, Eurofighter Jagdflugzeug GmbH, Airbus SE, Leonardo SpA, United Aircraft Corporation, Sukhoi JSC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Military Multirole Aircraft Market Strategic Shifts
Adaptive cycle propulsion and open mission systems architectures are compressing the traditional 20-year platform development cycle, enabling incremental capability upgrades without full airframe redesign.
Variable-cycle engines integrating adaptive fan technology and third-stream cooling are overtaking fixed-geometry turbofans in next-generation fighter propulsion competitions. The US Air Force's Adaptive Engine Transition Program is driving adoption timelines, with full-scale demonstrations scheduled for mid-decade integration. This propulsion shift is enabling supercruise without afterburner across broader flight envelopes while reducing thermal signature.
The EU Green Deal's defense adaptation framework is mandating lifecycle carbon accounting in military procurement evaluations, with EASA developing military certification liaison procedures for sustainable aviation fuel blends. European air forces are responding by inserting fuel efficiency and emissions criteria into technical requirement documents alongside traditional performance metrics.
Air forces are consolidating fleet diversity through multirole platform standardization, replacing specialized strike, reconnaissance, and electronic warfare aircraft with common airframe configurations. The Royal Australian Air Force exemplifies this shift, retiring F/A-18 Hornets and EA-18G Growlers in favor of expanded F-35A procurement with reconfigurable mission systems. This concentration pattern is visible across NATO members prioritizing interoperability over service-specific platform preferences.
Military Multirole Aircraft Market Segmentation
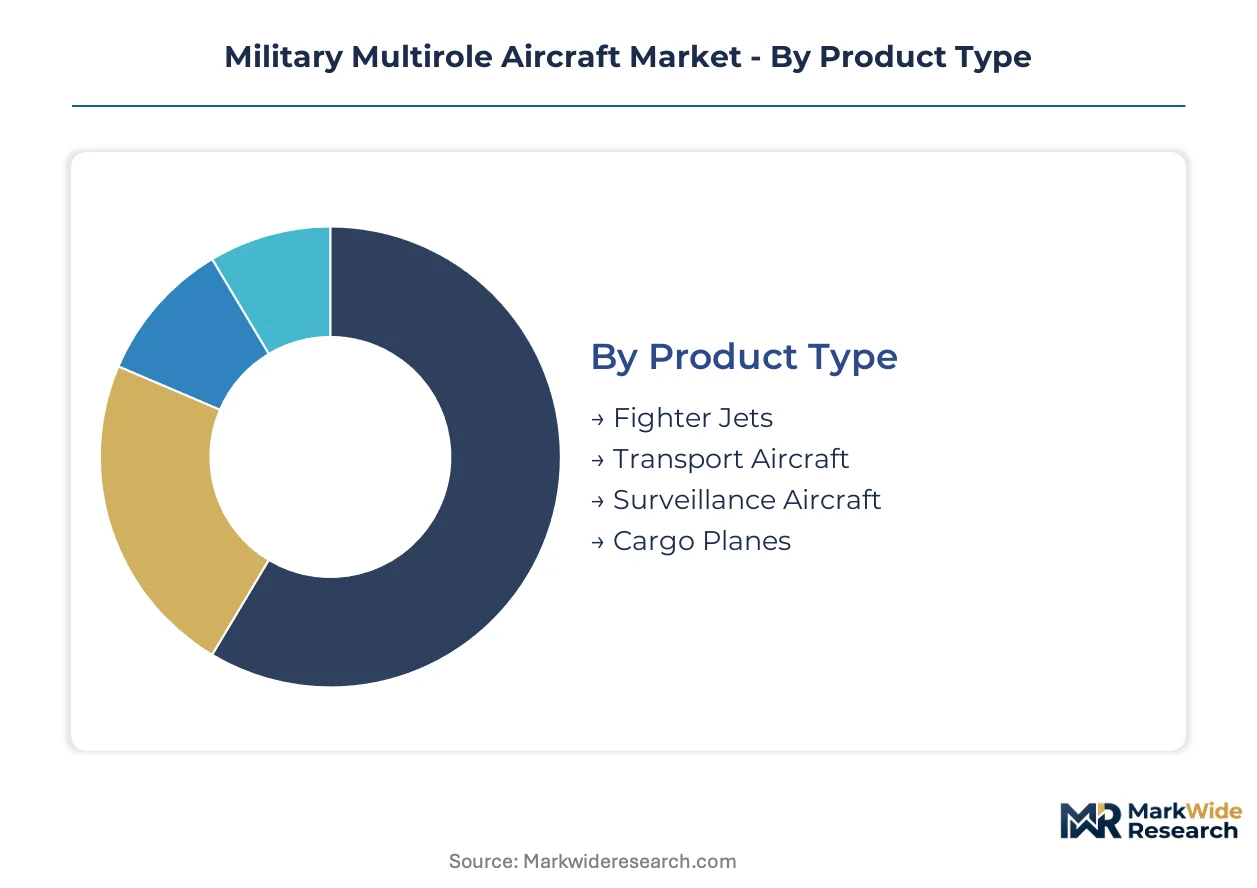
Multirole aircraft procurement patterns diverge sharply across operational mandates, with combat-focused air forces prioritizing sensor fusion and low-observable platforms while transport-heavy operators emphasize payload flexibility and austere-field compatibility. Understanding these segment boundaries clarifies where technology investments concentrate versus where replacement cycles drive volume.
Product Type:
Buyers in this category separate according to mission-criticality thresholds and fleet standardization imperatives.
- Fighter Jets:Thrust-vectoring or supercruise-capable airframes engineered for air superiority, strike, and electronic warfare from common configurations. The United States Air Force anchors procurement volume through F-35A standardization across tactical fighter wings, constrained by titanium supply security risks from Russian sponge titanium dominance.
- Transport Aircraft:Fixed-wing platforms optimized for strategic airlift, tactical resupply, and personnel movement across contested logistics networks. NATO's Defense Investment Pledge accelerates replacement timelines for aging C-130 fleets in Germany, Italy, and Poland, though procurement tilts toward multirole fighters in overall defense budgets.
- Surveillance Aircraft:Sensor-dense platforms integrating synthetic aperture radar and signals intelligence packages for persistent area monitoring.
- Cargo Planes:Heavy-lift configurations emphasizing palletized cargo capacity and rapid reconfiguration for medical evacuation roles.
Volume sits with Fighter Jets; growth tilts toward Surveillance Aircraft.
Technology:
Cost tier differentiation separates prime contractors from subsystem specialists, with sovereign capability requirements reshaping sourcing patterns.
- Stealth Technology:Radar-absorbent materials and geometric shaping reducing cross-section signatures below detection thresholds for integrated air defense penetration. The US Department of Defense mandates MIL-STD-810 environmental testing for coating durability, though climate-controlled hangar requirements limit forward basing flexibility in Pacific theater operations.
- Avionics Systems:Modular mission computers and open systems architectures enabling JADC2 network interoperability and continuous software refresh cycles. European air forces under EASA military certification liaison procedures prioritize sustainable aviation fuel compatibility alongside traditional performance metrics.
- Radar Systems:Active electronically scanned arrays providing multi-target tracking and electronic attack capabilities.
- Engine Technology:Adaptive cycle propulsion integrating third-stream cooling for supercruise without afterburner.
Revenue concentrates in Avionics Systems; capability gaps are widening fastest in Stealth Technology.
Application:
Operational tempo and rules-of-engagement stringency determine platform configuration priorities across mission sets.
- Combat Operations:Kinetic strike and air-to-air engagement missions requiring low-observable penetration and networked sensor fusion. The Royal Australian Air Force exemplifies concentration strategy, retiring specialized strike and electronic warfare airframes for expanded F-35A procurement with reconfigurable mission systems.
- Reconnaissance:Intelligence collection missions emphasizing standoff persistence and multi-spectral sensor integration. China's GB standards and MIIT directives govern indigenous platform development for intelligence-surveillance-reconnaissance roles, constraining foreign subsystem integration.
- Transport Missions:Strategic and tactical logistics movement with replacement-driven rather than expansionary demand profiles.
- Humanitarian Assistance:Disaster response and medical evacuation configurations prioritizing rapid deployment and interoperability with civilian air traffic management.
Procurement velocity runs highest for Combat Operations; mission expansion is broadening fastest in Humanitarian Assistance.
End User:
Budget cycle predictability and clearance infrastructure separate institutional buyers from emergent contracting channels.
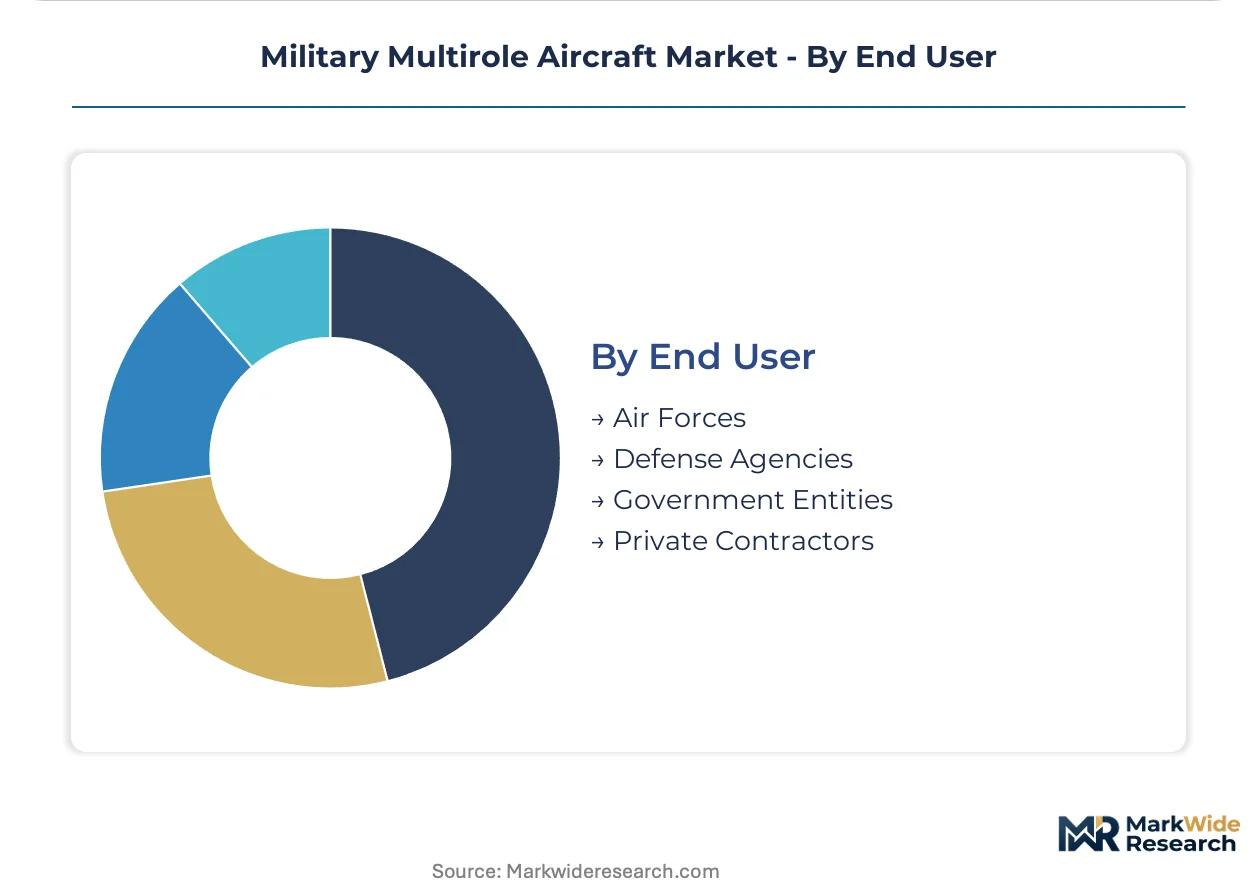
- Air Forces:Service branches with established flight operations, maintenance depots, and pilot training pipelines representing the core procurement channel. Congressional defense appropriations in the United States continue prioritizing fifth-generation fighter production and next-generation adaptive engine programs through formal acquisition frameworks.
- Defense Agencies:Cross-service organizations with specialized mission requirements including intelligence community air support and test range operations. ITAR-controlled technology transfer protocols constrain supplier bases and international co-development arrangements for sensitive avionics integration.
- Government Entities:Non-military state actors including coast guards and border security services with patrol and interdiction mandates.
- Private Contractors:Commercial entities providing adversary air training, test pilot services, and logistics support under government contract.
Contract flow concentrates with Air Forces; access expansion is proceeding fastest through Private Contractors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentration sits with established aerospace clusters in the United States and Western Europe, while procurement demand spreads across NATO members and Indo-Pacific partners confronting fleet obsolescence cycles. Consumption patterns diverge between mature air forces prioritizing fifth-generation replacement and emergent operators seeking versatile fourth-generation platforms.
United States
Congressional defense appropriations prioritize F-35A production across tactical fighter wings and adaptive engine development through the Air Force's next-generation propulsion program. The Department of Defense mandates MIL-STD-810 environmental testing and ITAR-controlled technology transfer protocols that constrain supplier bases. Fort Worth, Texas anchors final assembly operations for the F-35 Lightning II program, sustaining production velocity through Lockheed Martin's integrated digital thread architecture.
United Kingdom
The Royal Air Force accelerates Typhoon fleet modernization and F-35B integration while pursuing sixth-generation fighter concepts under the Global Combat Air Programme. AUKUS technology-sharing frameworks with Australia and the United States reshape electronic warfare and hypersonic integration pathways. BAE Systems facilities in Lancashire and Warton concentrate design engineering for combat air systems, supporting sovereign capability retention alongside transatlantic partnerships.
Germany
Luftwaffe procurement focuses on F-35A acquisition to replace Tornado IDS nuclear delivery roles and Eurofighter Typhoon expansion for air policing missions. NATO's Defense Investment Pledge accelerates modernization timelines, with EASA military certification liaison procedures governing airworthiness standards. Airbus Defence and Space operations in Manching and Bremen anchor European fighter development, integrating German industrial participation into multinational programs.
France
The Armée de l'Air et de l'Espace pursues Rafale F4 standard upgrades and FCAS sixth-generation development with Germany and Spain, emphasizing full sovereign supply chain control. Dassault Aviation leverages combat-proven versatility and independent export licensing authority. Saint-Cloud and Mérignac cluster design and final assembly operations, sustaining vertical integration from airframe fabrication through mission system integration without US technology dependencies.
Australia
The Royal Australian Air Force consolidates fleet diversity through F-35A standardization, retiring F/A-18 Hornets and EA-18G Growlers in favor of reconfigurable multirole configurations. AUKUS submarine and technology-sharing commitments extend to collaborative electronic warfare development. RAAF Base Williamtown in New South Wales hosts regional F-35 sustainment infrastructure, supporting interoperability with US and UK operational concepts across Indo-Pacific theaters.
Military Multirole Aircraft Market Competitive Environment
The competitive structure tilts toward prime contractor consolidation around integrated platform developers with sovereign supply chain control. Three to five major airframe manufacturers dominate program awards, with tiered specialization among engine producers and avionics subsystem suppliers. Strategic archetypes separate full-spectrum platform integrators from national champions with protected domestic markets and emerging state-affiliated challengers. Competitive moves concentrate on transnational joint ventures for risk-sharing and digital thread manufacturing investments for sustainment revenue capture.
Among US-based prime contractors, Lockheed Martin Corporation and The Boeing Company exemplify the full-spectrum integrator archetype, spanning fighter, surveillance, and strategic airlift categories. Dassault Aviation occupies a distinct position as a European national champion with demonstrated export success outside NATO frameworks. These three anchors illustrate how market position derives from program execution scale, sovereign technology access, and long-cycle government relationship depth rather than commercial pricing flexibility.
| Leading Market Players |
|---|
| Lockheed Martin Corporation |
| The Boeing Company |
| Dassault Aviation |
| Saab AB |
| Eurofighter Jagdflugzeug GmbH |
| Airbus SE |
| Leonardo SpA |
| United Aircraft Corporation |
| Sukhoi JSC |
| Others |
Value Chain & Pricing Dynamics
Sovereign-backed defense primes with captive aerospace clusters command pricing power through ITAR-controlled technology access, while procurement officers face cost-down mandates from congressional appropriations committees. This ownership pattern concentrates supply discipline in Fort Worth and Saint-Cloud, with pricing leverage flowing to airframe integrators holding security-cleared engineering workforces.
Pricing Analysis
Margin tightening in fifth-generation fighter contracts reflects titanium sponge cost volatility from Russian supply dominance and adaptive engine R&D amortization. Three-tier pricing structure across stealth-enabled, avionics-integrated, and legacy-sustainment configurations separates NATO members from export-restricted partners. Pricing pressure stems from congressional scrutiny on F-35 unit cost reduction targets. Defense agencies show highest price sensitivity; sovereign air forces with nuclear delivery mandates absorb premium tiers.
Supply Chain Analysis
Freight costs for vacuum arc remelted superalloys and radar-absorbent material precursors escalate due to climate-controlled transport requirements and ITAR facility security protocols. Supply concentrates in the United States, Russia, and China for sponge titanium; Germany and Japan for nickel superalloy forging. Raw material dependencies span titanium sponge, carbon fiber composites, and gallium nitride substrates. Single-source vulnerability in Russian titanium feedstock threatens airframe cost stability. Distribution runs through prime contractor final assembly lines with government-furnished equipment integration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around platforms with JADC2 interoperability and sovereign supply chain control, with ITAR compliance burdens forcing subscale avionics suppliers toward acquisition or exit.
For Market Incumbents: Extend digital thread manufacturing investments to compress sustainment revenue capture timelines, while deepening backward integration into titanium sponge alternatives to offset Russian supply risk. Lockheed Martin's integrated production architecture demonstrates how model-based enterprise approaches defend against Boeing's NGAD concept positioning. For New Entrants and Emerging Players: The EU Green Deal's defense adaptation framework in Europe opens a window for sustainable aviation fuel compatibility specialists and lifecycle carbon accounting software providers. Target surveillance aircraft retrofit markets in Poland and Italy where NATO's Defense Investment Pledge accelerates C-130 replacement timelines without F-35 budget allocation. Partner with Airbus Defence and Space for subsystem integration credibility. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-tier avionics houses with EASA military certification liaison experience and cleared engineering talent pipelines in the United Kingdom. Long-term viability hinges on AUKUS technology-sharing framework participation extending beyond submarine propulsion into electronic warfare domains. Monitor JADC2 architecture mandate acceleration as inflection signal for open systems architecture valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Adaptive Engine Transition Program Participation | Pratt and Whitney and General Electric compete for Air Force propulsion modernization, with winner-take-all implications for next-decade fighter engine revenue. |
| AUKUS Electronic Warfare Collaboration | BAE Systems and Australian industry partners gain preferential access to US classified spectrum warfare architectures under trilateral security commitments. |
| Digital Thread Manufacturing Investment | Lockheed Martin's Fort Worth facility demonstrates continuous capability insertion without airframe redesign, compressing F-35 upgrade cycles. |
| Sustainable Aviation Fuel Certification | EASA military certification liaison procedures enable European air forces to insert emissions criteria alongside MIL-STD-810 performance requirements. |
| ITAR Technology Transfer Liberalization | US State Department Category VIII revisions enable faster international co-production for sensitive avionics, expanding addressable markets for cleared suppliers. |
Study Parameters
Document review covered Department of Defense budget justification materials, NATO STANAG interoperability standards, and congressional appropriations committee records, complemented by interviews with program executive officers at US Air Force Life Cycle Management Center, procurement directors at Luftwaffe and Armée de l'Air, and supply chain managers at Lockheed Martin and BAE Systems. Secondary validation drew from FAA military certification liaison procedures, EASA environmental compliance frameworks, and customs data on titanium sponge trade flows. Bottom-up platform delivery forecasts triangulated against top-down defense expenditure projections.
Output modeling spanned unit delivery volumes and program value across the projection horizon, with segmentation by fighter jet, transport aircraft, and surveillance aircraft categories alongside stealth technology, avionics systems, and engine technology tiers. CAGRs derived from historical procurement cycle analysis and obsolescence-driven replacement scheduling. Forecast inputs included congressional defense appropriations trajectory, NATO's Defense Investment Pledge compliance timelines, and adaptive engine demonstration milestones.
The model assumes a particular technology adoption path; alternative pathways for variable-cycle propulsion or loyal wingman unmanned teaming would alter the outlook. Forecasts reflect assumptions on ITAR licensing velocity, titanium supply diversification success, and JADC2 architecture deployment pace. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft
Water Bomber Market
Aircraft
Aircraft Mounts Market
Aircraft
Flap Track Fairing Drag Reduction Upgrade Kits Market
Aircraft
Winglets Market
Aircraft
Asia-Pacific General Aviation Market
Aircraft
Asia-Pacific Aircraft Windshield Wiper and Washer System Market
Aircraft
Aircraft Cargo Container Market
Aircraft
Vietnam Business Jets and Helicopters Market
Aircraft
Commercial Aircraft Aerostructures Market
Aircraft
Aircraft Ailerons Market
Aircraft
Global Aircraft De-Icing Market
Aircraft
Middle-East and Africa Freighter Aircraft Market
Aircraft
Commercial Aircraft in-Seat Power System Market
Aircraft
Global Aircraft Towbars Market
Aircraft
Light and Very Light Jets Market
Aircraft
Aircraft Cargo Winches Market