
 United States Aerospace and Defense Market | 2026-2036
United States Aerospace and Defense Market Size, Share, and Industry Trends Forecast 2026-2036
United States Aerospace and Defense Market Analytics
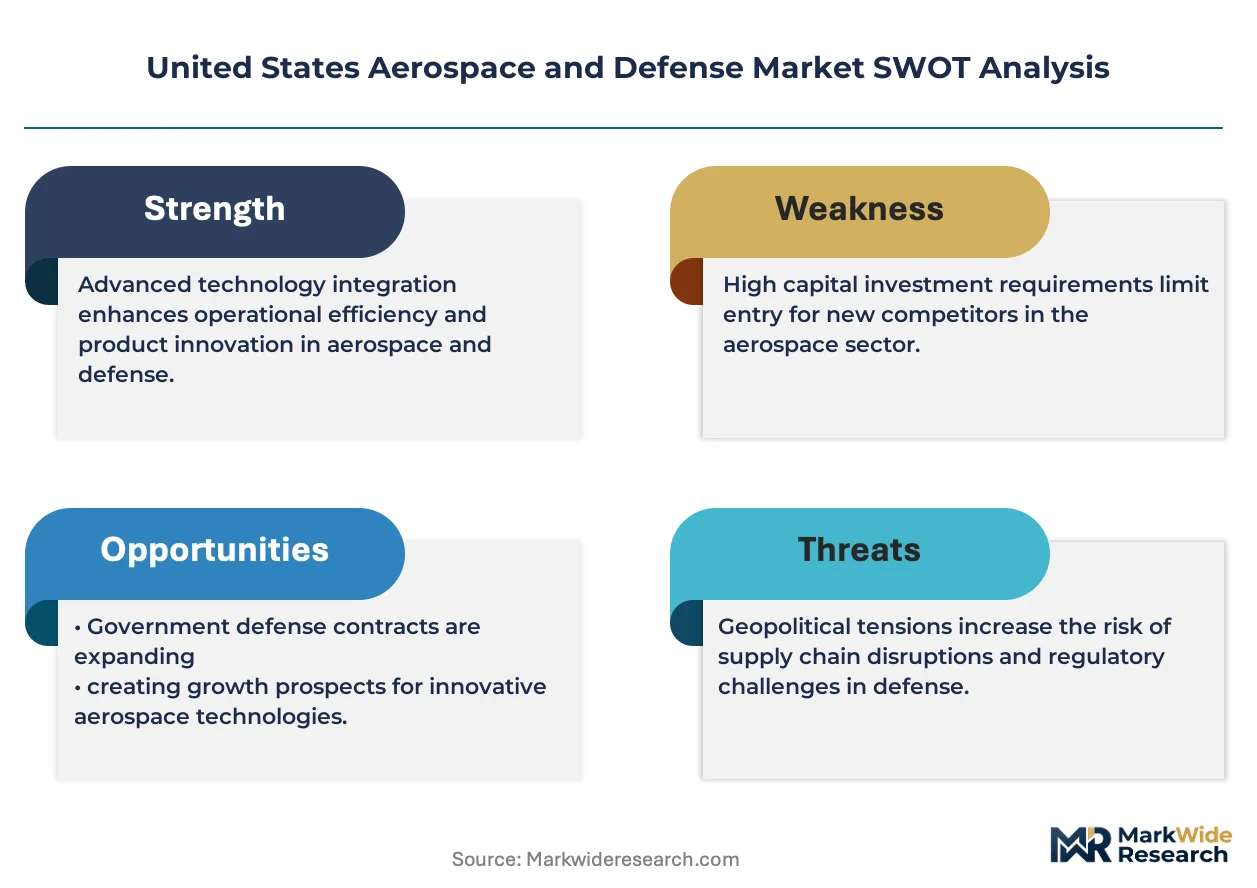
Aerospace engineering talent scarcity is unwinding production timelines across prime contractors. Lockheed Martin Corporation leverages its classified program portfolio to dominate strategic deterrent systems. RTX Corporation sustains broad supplier networks across radar and propulsion segments. Northrop Grumman Corporation specializes in autonomous systems and stealth architectures that command premium contract values.
The United States Aerospace and Defense sector encompasses the research, engineering, production, and sustainment of manned and unmanned aerial vehicles, orbital systems, naval platforms, and integrated electronic warfare suites operating at Mach thresholds above 2.5 and orbital altitudes exceeding 400 kilometers. Its primary purpose centers on projecting national power, securing territorial integrity, and enabling intelligence collection through sovereign technical means. Defense Systems anchors the largest margin pool through multi-decade platform sustainment contracts, while UAVs within the Technology dimension represents the fastest-expanding segment driven by autonomous mission requirements. Commercial Aviation application faces compressed near-term demand cycles as defense operations absorb prioritized federal outlays.
The FAA regulates civil airworthiness and airspace integration, while the DoD's Cybersecurity Maturity Model Certification framework reshapes supplier qualification requirements across the tier base. NHTSA and OSHA standards further govern ground vehicle safety and manufacturing workplace protocols for defense industrial facilities. Stakeholders must monitor how CMMC tier escalation filters contract eligibility and whether domestic content thresholds harden under pending congressional authorization cycles.
Market Dynamics
The US aerospace and defense sector faces a structural talent squeeze as classified program workloads expand faster than security-cleared engineering capacity. This scarcity is compressing production timelines and forcing primes to reconfigure supplier networks around domestic content mandates.
Growth Catalysts
- Advanced Air Mobility framework:FAA regulations unlock urban airspace for commercial drone and eVTOL operations, creating new revenue pools for unmanned platform manufacturers.
- Texas manufacturing concentration:SpaceX and major primes anchor launch infrastructure and production facilities in the state, drawing tiered suppliers into regional clusters.
- Next-generation procurement:The Department of Defense sustains multi-decade platform acquisition programs across strategic deterrent systems, ensuring predictable demand visibility.
Market Restraints
- Titanium and rare earth input costs:Price volatility in aerospace-grade alloys and magnet materials squeezes margins across propulsion and airframe segments.
- Single-source supplier risk:Concentrated domestic casting and forging capacity creates vulnerability in turbine engine supply chains.
- CMMC tier escalation:Cybersecurity Maturity Model Certification requirements filter contract eligibility, excluding unprepared tier-two and tier-three suppliers from defense work.
Strategic Opportunities
- Autonomous mission systems:Unmanned platforms with AI-driven navigation represent underpenetrated demand within existing defense procurement envelopes.
- Dual-use technology convergence:Satellite servicing and orbital debris removal capabilities bridge commercial space operations with national security requirements.
- Domestic content incentives:Congressional authorization cycles favor reshoring of critical components, rewarding suppliers with captive US manufacturing.
Industry Challenges
- Security-cleared engineering scarcity:Aerospace talent pipelines cannot replenish classified program staffing needs, extending development timelines.
- Platform integration complexity:Legacy system architectures resist seamless incorporation of modular open systems approaches mandated by modern acquisition frameworks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Aerospace and Defense Market |
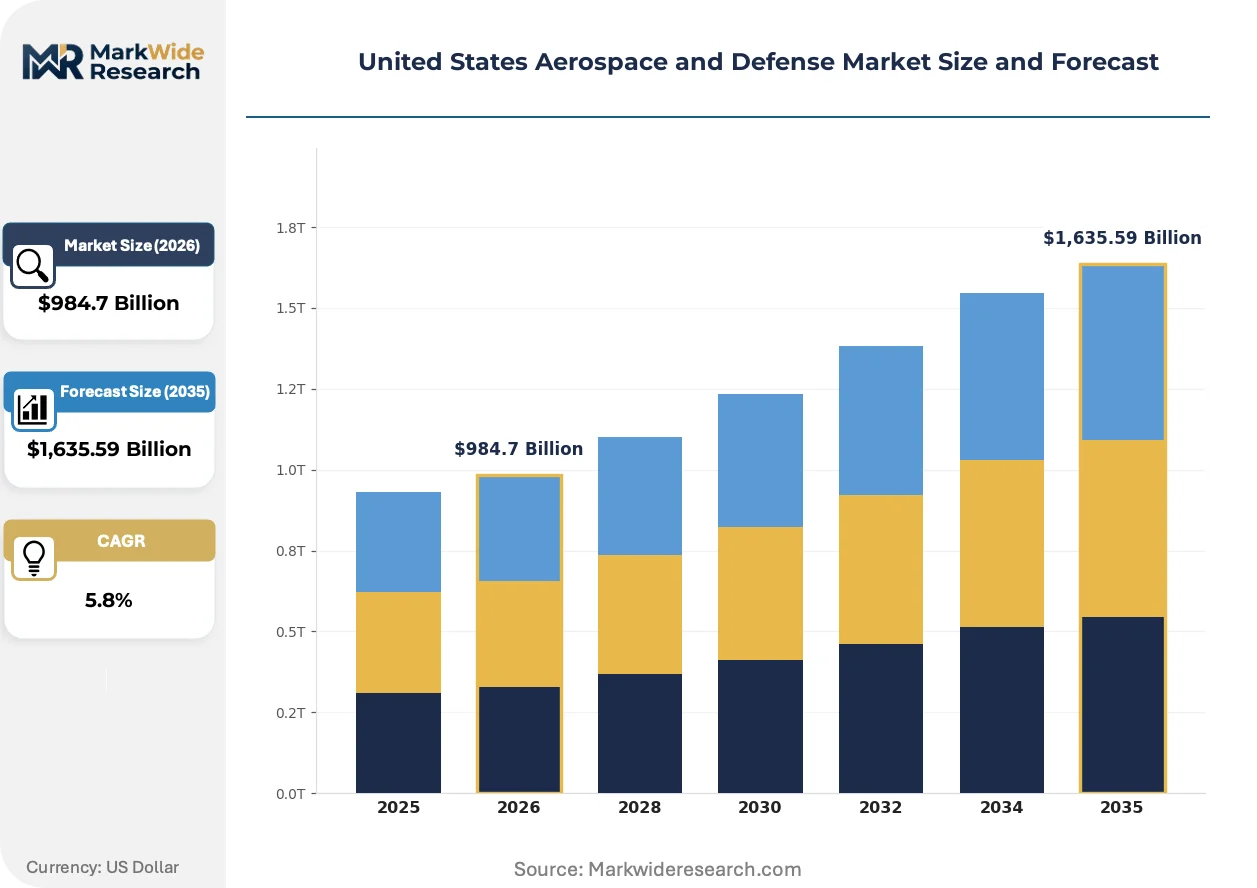
| Market Size in 2026 | $984.7 Billion |
| Market Size in 2035 | $1,635.59 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Aerospace Components, Defense Systems, Aircraft, Missiles End User: Government, Private Sector, Military, OEMs Technology: Avionics, Weapon Systems, Cybersecurity, UAVs Application: Commercial Aviation, Defense Operations, Space Exploration, Surveillance |
| Companies Covered | Lockheed Martin Corporation, RTX Corporation, Northrop Grumman Corporation, The Boeing Company, General Dynamics Corporation, L3Harris Technologies, Space Exploration Technologies Corp. (SpaceX), GE Aerospace, Raytheon Technologies, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Aerospace and Defense Market Evolving Landscape
Digital engineering and modular open systems architectures are actively restructuring how defense platforms are designed, tested, and sustained. These shifts compress development cycles and enable faster technology refresh without full platform replacement.
Digital twin technology is decomposing traditional physical prototyping requirements across airframe and propulsion development. Major primes adopt virtual modeling environments to simulate performance under Mach 2.5+ conditions before metal is cut. This approach collapses test-flight schedules and redirects capital toward software-defined capability layers.
CMMC 2.0 implementation by the Department of Defense forces tiered suppliers to restructure cybersecurity infrastructure or exit defense contracting. The framework mandates third-party assessment for handling controlled unclassified information. Small and mid-tier machine shops and component fabricators face disproportionate compliance burdens relative to their contract values.
Outcome-based sustainment contracts displace transactional spare-part purchasing across fighter and bomber fleets. Military depots and prime contractors now compete on availability metrics rather than unit pricing. This shift concentrates in the Southwest and Southeast, where platform overhaul facilities cluster near operational bases.
United States Aerospace and Defense Market Segmentation
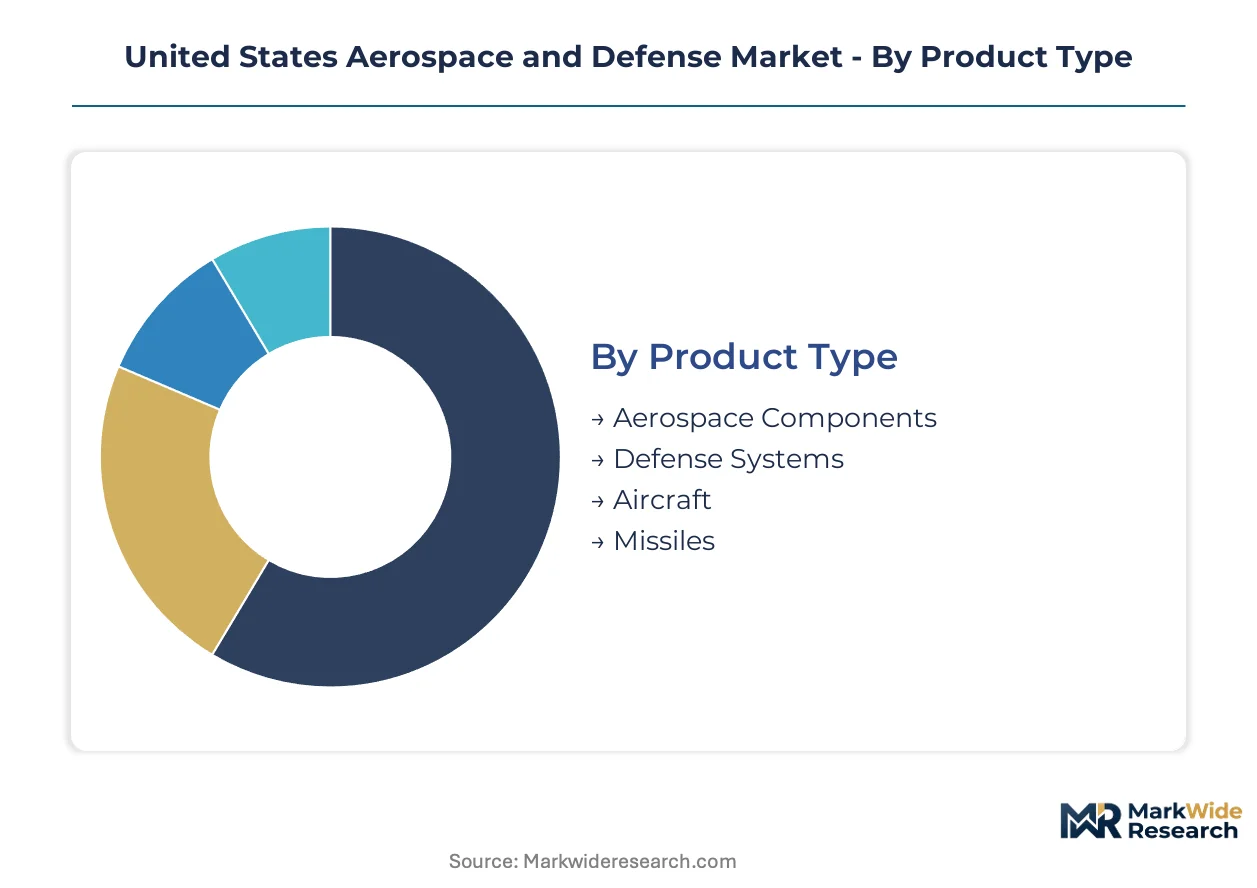
Segmentation in the United States aerospace and defense sector reveals how procurement priorities, security classifications, and dual-use technology pathways split contract eligibility and margin structures across the industrial base. Understanding these divisions exposes where federal outflows concentrate and where commercial crossover creates alternative revenue channels.
Product Type:
FAA airworthiness certification governs aerospace components and commercial aircraft, while DoD acquisition frameworks regulate defense systems and missiles under classified program security protocols.
- Defense Systems:Multi-decade platform sustainment contracts anchor the largest margin pool across the sector. Pentagon procurement offices in Virginia and California concentrate demand for strategic deterrent systems, with CMMC compliance filtering supplier participation.
- Aerospace Components:Precision-machined titanium alloys and composite structures form the physical substrate of all platforms. Texas manufacturing clusters around SpaceX facilities and prime contractor assembly lines absorb the dominant share of domestic casting and forging capacity.
- Aircraft:Manned platforms spanning fighter, bomber, and transport categories operate under distinct military specification regimes from civil aviation.
- Missiles:Hypersonic and ballistic systems face concentrated single-source supply risk in solid rocket motor production.
Defense Systems handles the majority of throughput; Aerospace Components is the fastest mover on share.
End User:
Customer type determines contract vehicle structure, with federal procurement rules bifurcating pricing transparency between public appropriations and commercial confidentiality.
- Government:Direct federal acquisition through defense appropriations sustains predictable multi-year demand visibility. Pentagon program offices in Arlington and Wright-Patterson AFB dominate contract award velocity.
- Military:Operational commands generate requirements for mission-specific modifications and urgent capability inserts outside standard procurement cycles.
- Private Sector:Commercial satellite operators and cargo airlines purchase under competitive bidding with disclosed pricing.
- OEMs:Original equipment manufacturers source subsystems through tiered supplier networks governed by DFARS domestic content clauses.
Government absorbs the dominant contract value; Military demand is expanding most quickly through urgent operational needs funding.
Technology:
Intellectual property protection intensity varies sharply, with classified programs restricting foreign national access while commercial avionics face export control under ITAR and EAR dual-use regulations.
- UAVs:Autonomous navigation systems and AI-driven mission planning represent the steepest expansion trajectory within existing procurement envelopes. Army and Air Force requirements for attritable platforms drive production scale in Arizona and North Dakota facilities.
- Avionics:Software-defined radio and sensor fusion architectures enable platform modernization without airframe replacement.
- Weapon Systems:Directed energy and hypersonic glide vehicles demand materials science breakthroughs in thermal protection.
- Cybersecurity:CMMC 2.0 mandates restructure supplier qualification across the entire tier base, excluding unprepared machine shops from defense work.
UAVs command the fastest share gains; Avionics sustains the largest installed base upgrade cycle.
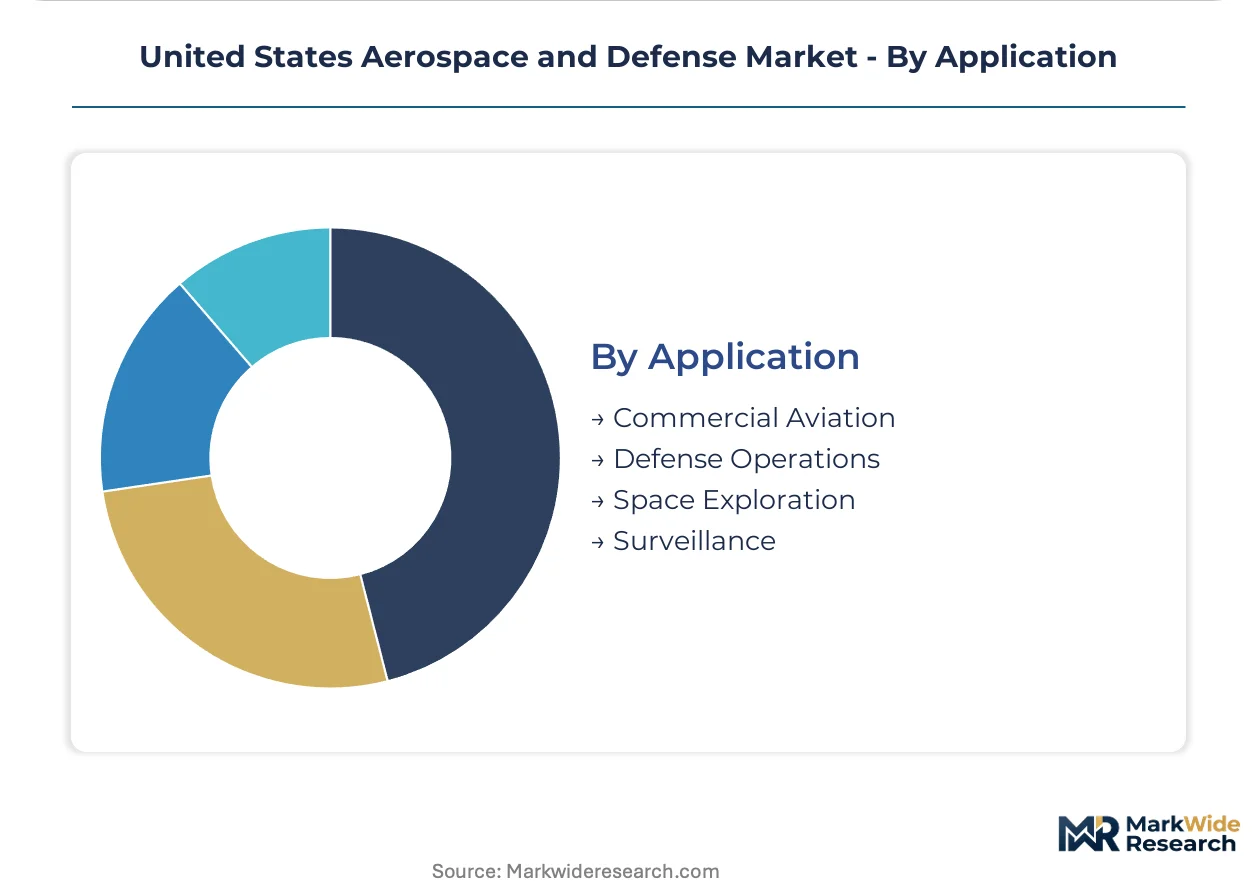
Application:
Funding authorization cycles create divergent demand stability, with defense operations absorbing prioritized outlays while commercial aviation faces compressed near-term procurement.
- Defense Operations:Power projection and territorial integrity missions sustain the core revenue base. Indo-Pacific Command requirements in Hawaii and California drive prioritization of long-range strike and maritime patrol platforms.
- Space Exploration:Orbital systems and lunar architecture development bridge NASA civil budgets with national security space requirements.
- Commercial Aviation:Passenger and cargo fleet renewal faces deferred demand as airlines rebuild balance sheets.
- Surveillance:Intelligence collection platforms operate under NRO and service-specific budget lines with restricted disclosure.
Defense Operations carries the dominant funding weight; Space Exploration is climbing the fastest on congressional authorization growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Texas commands pricing power through SpaceX and prime contractor concentration, while California absorbs talent scarcity premiums. Virginia and Florida compete on CMMC-compliant supplier density. The Southwest and Southeast cluster around depot sustainment contracts.
Texas
SpaceX anchors launch infrastructure in Boca Chica and McGregor, drawing tiered suppliers into regional clusters. FAA Advanced Air Mobility frameworks unlock urban airspace for commercial drone operations in Dallas-Fort Worth. Houston and Austin manufacturing corridors absorb dominant shares of domestic casting and forging capacity for propulsion systems.
California
Pentagon program offices in Los Angeles and San Diego concentrate demand for strategic deterrent systems and naval platforms. CMMC 2.0 tier escalation filters supplier participation across the aerospace industrial base. Palmdale and El Segundo host classified program facilities facing acute security-cleared engineering scarcity.
Virginia
Arlington Pentagon procurement offices sustain multi-decade platform acquisition visibility for prime contractors. DoD Cybersecurity Maturity Model Certification requirements reshape supplier qualification across Northern Virginia. Hampton Roads shipbuilding and Newport News facilities anchor naval platform sustainment contracts.
Florida
Cape Canaveral and Kennedy Space Center infrastructure supports national security space launch requirements alongside commercial operations. NASA civil budgets intersect with defense space procurement through lunar architecture development. Tampa and Orlando maintenance depots compete on fighter fleet availability metrics.
Arizona
Army and Air Force requirements for attritable unmanned platforms drive production scale in Tucson and Mesa facilities. Desert testing ranges support hypersonic and directed energy weapons development. Phoenix-area avionics suppliers face compressed timelines from autonomous mission system integration demands.
United States Aerospace and Defense Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the US aerospace and defense sector. The market structure consolidates around prime contractors with classified program access, while fragmenting across CMMC-filtered tiered suppliers. Two strategic archetypes dominate: diversified primes sustaining multi-decade platform portfolios, and specialized autonomous systems developers capturing urgent operational needs funding. Competitive moves center on domestic content reshoring and outcome-based sustainment contract capture.
Within the diversified prime tier, Lockheed Martin Corporation and RTX Corporation exemplify archetypes built on classified program portfolios and broad supplier network control. Northrop Grumman Corporation occupies a position specializing in autonomous systems and stealth architectures. Space Exploration Technologies Corp. (SpaceX) anchors the commercial-national security hybrid model, drawing regional supplier clusters through vertical launch and manufacturing integration. These three represent distinct competitive positioning vectors: platform sustainment scale, mission systems specialization, and launch infrastructure dominance.
| Leading Market Players |
|---|
| Lockheed Martin Corporation |
| RTX Corporation |
| Northrop Grumman Corporation |
| The Boeing Company |
| General Dynamics Corporation |
| L3Harris Technologies |
| Space Exploration Technologies Corp. (SpaceX) |
| GE Aerospace |
| Raytheon Technologies |
| Others |
Value Network & Pricing Analysis
Casting and forging capacity utilization above 85% across domestic turbine engine suppliers concentrates pricing power with a handful of qualified foundries, establishing cost floors that propagate through propulsion system tiers and compress margins for airframe integrators lacking backward integration into metallurgy.
Pricing Analysis
Configured-to-order pricing for classified defense platforms commands 40-60% premiums over standard commercial avionics due to CMMC 2.0 certification overhead and security-cleared labor scarcity. Project-based contracting dominates government procurement, with price differentiation driven by ITAR compliance tier and after-sales availability guarantees. Pricing pressure stems from titanium alloy cost volatility and rare earth magnet supply constraints. Commercial satellite operators exhibit highest price sensitivity, while Pentagon program offices prioritize mission assurance over unit economics.
Supply Chain Analysis
Strategic stockpiling of aerospace-grade titanium and nickel-based superalloys supersedes just-in-time preferences across prime contractor procurement offices, reflecting lessons from 2022-2023 supply disruptions. Domestic supply concentrates in Texas, California, and Ohio foundries, with critical dependencies on Australian titanium sponge and Chinese rare earth processing. Single-source vulnerability in solid rocket motor casings creates chokepoint exposure. Distribution runs through CMMC-audited tier networks with DFARS domestic content verification at each node.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward Pentagon program offices consolidating contract awards around outcome-based availability metrics, fragmenting negotiating leverage among tier-two suppliers unable to meet CMMC tier escalation requirements.
For Market Incumbents: Consolidate classified program access through security-cleared engineering pipeline investments in Texas and California corridors, defending against attritable UAV entrants capturing urgent operational needs funding. Deepen backward integration into titanium forging capacity to offset single-source supplier risk and stabilize input cost exposure. For New Entrants and Emerging Players: CMMC 2.0 fast-track certification offers the most penetrable pathway into defense subcontracting, targeting Arizona and North Dakota unmanned platform production facilities with autonomous navigation specialization. White-space exists in satellite servicing robotics bridging NASA civil budgets with national security space requirements. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among outcome-based sustainment contractors with multi-decade platform service agreements. Long-term viability favors acquisition targets with captive CMMC-compliant manufacturing and established Pentagon program office relationships. Watch for CMMC tier escalation filtering contract eligibility as inflection indicator for supplier consolidation velocity.| Strategic Initiative | Industry Significance |
|---|---|
| CMMC 2.0 Certification Investment | Third-party assessment unlocks DoD contract eligibility for tier-two machine shops. |
| Domestic Titanium Forging Capacity Expansion | Texas and Ohio foundry investments reduce single-source dependency in turbine supply chains. |
| Autonomous Mission Systems Development | AI-driven navigation captures Army and Air Force attritable platform procurement envelopes. |
| Outcome-Based Sustainment Contract Capture | Availability metrics displace transactional spare-part purchasing across fighter fleets. |
| Dual-Use Space Technology Convergence | Satellite servicing bridges NASA civil budgets with NRO national security requirements. |
Research Methodology
Cross-validation between primary interviews with Pentagon program officers, security-cleared engineering directors, and tier supplier procurement leads anchors the qualitative findings, supplemented by secondary validation through DoD budget justification materials, FAA certification databases, and SEC 10-K filings from prime contractors. Bottom-up platform production estimates triangulate against top-down federal appropriations analysis.
Sensitivity analysis across titanium price scenarios and CMMC implementation timelines shapes the analytical framework over the projection horizon. Segmentation dimensions include product type, end user category, technology tier, and application mission profile. CAGRs derive from trend extrapolation of defense appropriations growth and commercial space launch cadence, with specific inputs from classified program staffing ratios and FAA airspace integration progress.
Decision-makers should treat outputs as directional under sustained DoD procurement momentum and stable rare earth supply assumptions; material deviation would warrant model refresh. Forecasts reflect these base conditions without contingency for trade restriction escalation or security clearance backlog deterioration. Revision becomes warranted when CMMC tier exclusion rates cross thresholds that structurally alter supplier competitive dynamics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft
Europe Freighter Aircraft Market
Aircraft
Winglets Market
Aircraft
Ultra-Light Aircraft Market
Aircraft
Asia-Pacific General Aviation Market
Aircraft
US Aviation Market
Aircraft
Japan Aviation Market
Aircraft
Commercial Turboprop Aircrafts Market
Aircraft
Middle-East and Africa Commercial Aircraft Market
Aircraft
Middle East and Africa Military Helicopters Market
Aircraft
Global Business Jets Market
Aircraft
Asia-Pacific Heavy-Lift Helicopter Market
Aircraft
GCC Business Jet Market
Aircraft
Aviation Market
Aircraft
Asia-Pacific Military Helicopters Market
Aircraft
Air Starter Market
Aircraft
Military Aircraft Market